
 Large Volume Nebulizers Market | 2026-2036
Large Volume Nebulizers Market Size, Share, and Industry Trends Forecast 2026-2036
Large Volume Nebulizers Market Foresight
Preventive maintenance and calibration service contracts is broadening what hospitals and homecare providers purchase alongside hardware. PARI GmbH leverages its German engineering heritage to sustain premium positioning in pneumatic and mesh technology segments. Vyaire Medical anchors North American distribution through deep clinical channel relationships and acute-care contract structures. GaleMed Corporation specializes in compact, transport-oriented designs that compete for emergency services and ambulance fleet procurement.
Large volume nebulizers are medical devices that convert liquid medication into aerosol droplets between one and five microns for deep lung deposition, typically operating with compressed gas or piezoelectric vibration at frequencies exceeding 100 kHz to deliver bronchodilators, corticosteroids, and antibiotics to patients with obstructive or infectious respiratory conditions. Pneumatic jet technology still dominates hospital procurement due to lower per-unit cost and compatibility with existing compressed air infrastructure, though vibrating mesh systems are capturing margin pools in homecare settings where silent operation and reduced treatment time command price premiums. Tabletop nebulizers retain volume leadership in clinics and emergency services, while portable and handheld configurations are expanding fastest among COPD patients managing disease progression outside clinical facilities.
The FDA's 510(k) clearance framework and ISO 18562 biocompatibility testing requirements for breathing gas pathways shape product development timelines and market access costs for manufacturers targeting the United States. Europe's MDR and REACH substance restrictions add compliance layers that favor established players with dedicated regulatory affairs capacity over smaller entrants. Stakeholders must monitor how CMS reimbursement coding for home nebulizer therapy evolves relative to alternative delivery modalities such as soft-mist inhalers and dry powder devices.
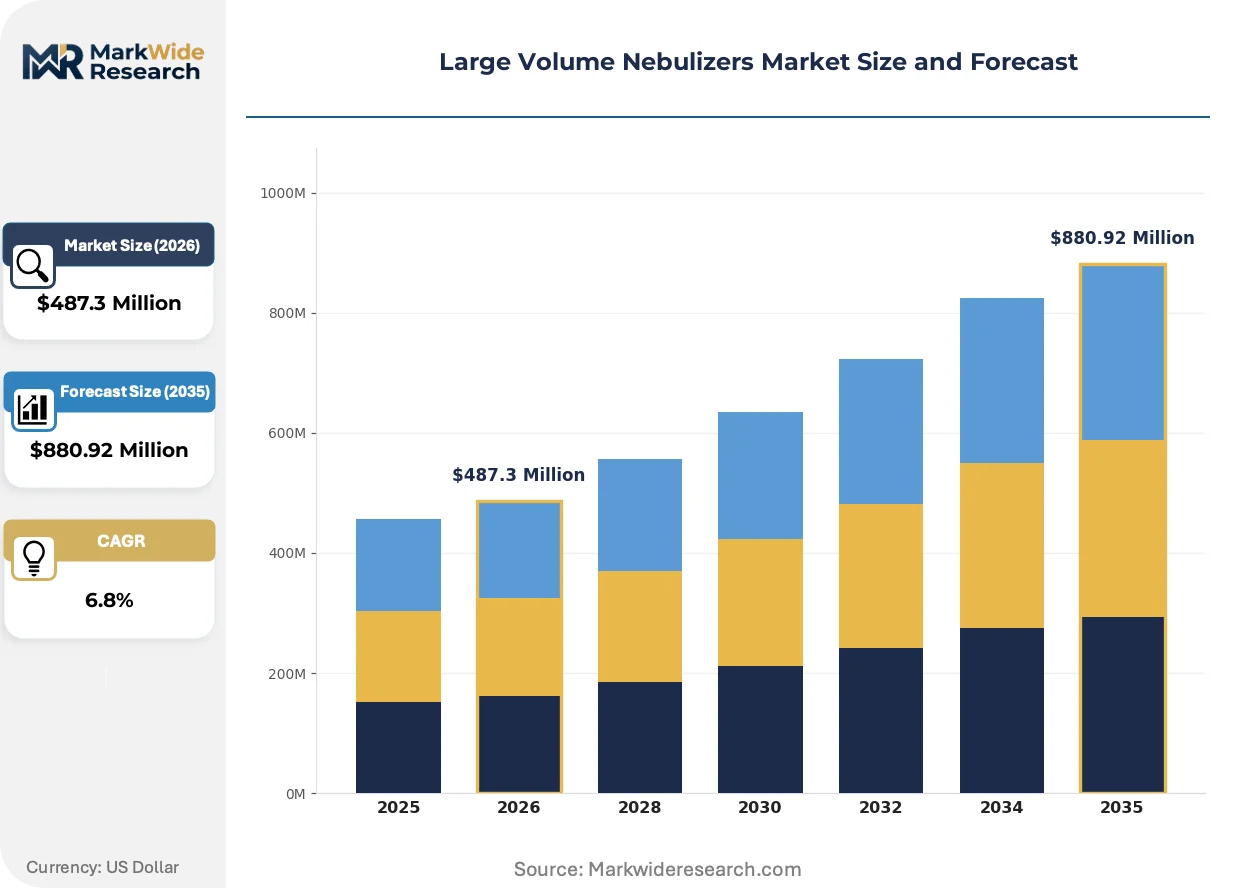
Market Dynamics
The Large Volume Nebulizers Market is restructuring around compressed treatment times and silent operation as vibrating mesh systems capture preference in homecare settings where patient compliance hinges on convenience and discretion.
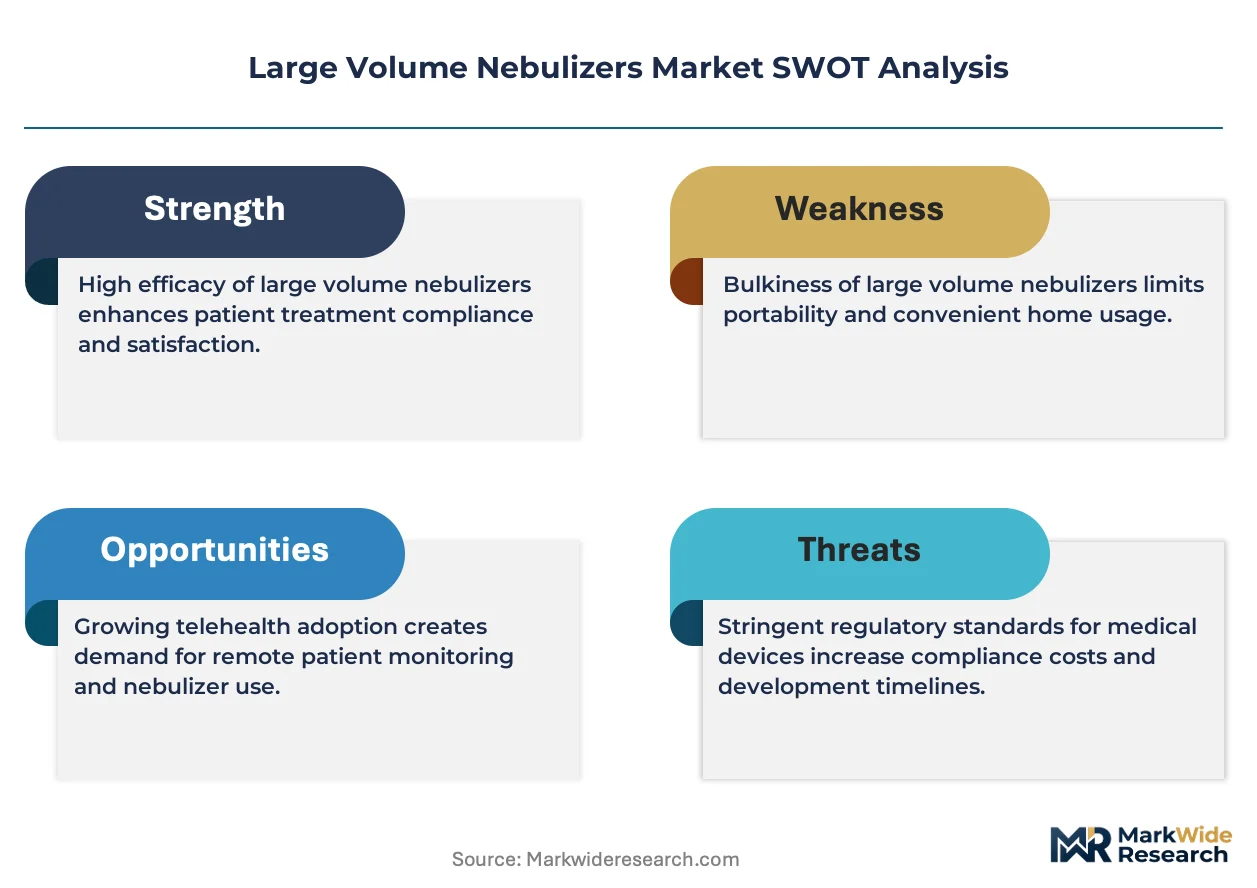
Growth Catalysts
- Aging demographics in the United States:Chronic obstructive pulmonary disease prevalence among Americans over 65 sustains institutional procurement volumes and homecare device replacement cycles.
- ISO 18562 biocompatibility testing:Standardized breathing gas pathway requirements accelerate regulatory clearance timelines for manufacturers with pre-validated materials libraries.
- Piezoelectric vibration at 100+ kHz:Mesh nebulization technology reduces medication waste and treatment duration, commanding price premiums in direct-to-patient channels.
Market Restraints
- Pneumatic jet infrastructure lock-in:Hospital compressed air systems and existing capital equipment create switching costs that delay mesh technology penetration in acute care.
- Reimbursement compression:CMS coding for home nebulizer therapy faces downward pressure as soft-mist inhalers and dry powder devices gain formulary inclusion.
- REACH substance restrictions:European chemicals regulation limits polymer and coating options for breathing gas pathways, extending reformulation cycles for device manufacturers.
Strategic Opportunities
- Preventive maintenance contracts:Service bundling with hardware sales creates recurring revenue streams as hospitals outsource calibration and replacement scheduling.
- Portable configurations for COPD patients:Handheld device demand expands among disease-managed populations seeking therapy outside clinical facilities.
- Emergency services procurement:Compact transport-oriented designs compete for ambulance fleet standardization contracts in municipal healthcare systems.
Industry Challenges
- FDA 510(k) documentation burden:Predicate device identification and substantial equivalence demonstrations consume 12-18 month development timelines for novel mesh geometries.
- Legacy pneumatic compatibility:Integration with existing hospital air supply infrastructure requires adapter engineering that fragments product SKUs and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large Volume Nebulizers Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tabletop Nebulizers, Portable Nebulizers, Ultrasonic Nebulizers, Mesh Nebulizers End User: Hospitals, Clinics, Homecare Settings, Emergency Services Technology: Pneumatic, Ultrasonic, Vibrating Mesh, Jet Application: Respiratory Disorders, Cystic Fibrosis, COPD, Anesthesia |
| Companies Covered | Teleflex Incorporated, PARI GmbH, Tri-Anim Health Services, Inc., Vyaire Medical, Sarnova, Inc., Winnomed, GaleMed Corporation, Vadi Medical Technology Co., Ltd., GF Health Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large Volume Nebulizers Market Shifts & Advancements
Vibrating mesh nebulization is compressing treatment windows and enabling discrete therapy administration outside institutional settings. Device manufacturers are racing to optimize piezoelectric transducer efficiency while navigating divergent regulatory pathways across major markets.
Mesh-based aerosol generation is overtaking pneumatic jet systems in homecare channels where silent operation and medication conservation determine purchase decisions. COPD patients managing disease progression outside hospitals adopt handheld configurations that reduce therapy time from fifteen minutes to under five. This shift is compressing margins for legacy compressor-based product lines while rewarding manufacturers with proprietary piezoelectric architectures.
Europe's MDR implementation is extending clinical evaluation requirements for nebulizer devices with patient-contact components. Breathing gas pathway biocompatibility documentation now demands toxicological risk assessments that add six to nine months to conformity assessment procedures. German and French notified bodies are prioritizing submissions from manufacturers with established ISO 13485 quality management systems, creating clearance backlogs for smaller entrants.
Homecare providers are unbundling device procurement from maintenance and calibration services, creating discrete purchasing decisions for hardware and aftermarket support. Durable medical equipment suppliers now compete on service response times and loaner device availability rather than unit price alone. This pattern is most visible in United States Medicare competitive bidding regions where total cost of ownership calculations determine contract awards.
Large Volume Nebulizers Market Segmentation
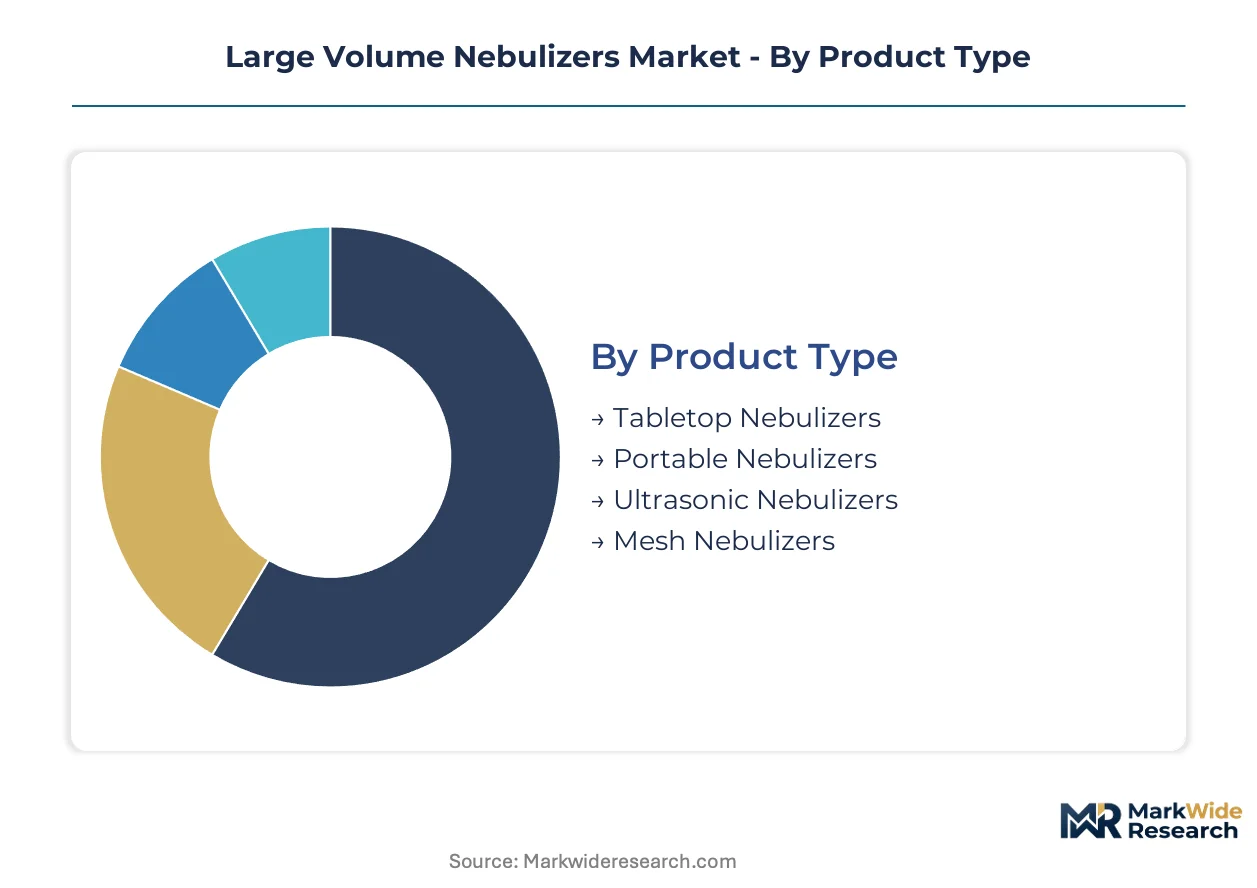
Large volume nebulizers fragment across four critical axes that determine reimbursement pathways, regulatory classification, and procurement behavior. Technology differentiation and end-use environment shape margin structures and competitive positioning for manufacturers.
Product Type:
Device form factor dictates power requirements, medication capacity, and mobility constraints that segment addressable markets.
- Tabletop Nebulizers:Stationary units with compressor-driven pneumatic systems deliver continuous aerosol flow for extended therapy sessions. Hospitals in the United States deploy these for inpatient bronchodilator administration where electrical outlets and compressed air infrastructure are ubiquitous.
- Portable Nebulizers:Battery-operated and handheld configurations enable COPD patients to administer therapy during travel or workplace activity. Homecare demand concentrates among Medicare beneficiaries seeking to maintain pulmonary function outside clinical supervision.
- Ultrasonic Nebulizers:Piezoelectric crystal vibration at 1-2 MHz generates aerosol without compressor noise. These units serve pediatric and noise-sensitive environments where treatment compliance depends on reduced acoustic disturbance.
- Mesh Nebulizers:Micro-perforated membranes driven by high-frequency vibration produce respirable particles with minimal medication residue. German engineering clusters dominate proprietary mesh geometry patents for premium homecare positioning.
Tabletop nebulizers lead on scale; mesh nebulizers lead on momentum.
End User:
Procurement authority and reimbursement mechanisms create distinct purchasing dynamics across care settings.
- Hospitals:Acute-care facilities prioritize pneumatic jet compatibility with existing compressed air infrastructure and bulk medication vial formats. Group purchasing organizations negotiate multi-year contracts based on total cost of ownership metrics.
- Clinics:Outpatient respiratory therapy centers balance device durability against patient throughput requirements. These settings favor tabletop units with rapid medication chamber exchange for sequential patient treatments.
- Homecare Settings:Medicare competitive bidding regions drive durable medical equipment suppliers toward portable and mesh configurations that reduce service call frequency. Patient self-administration demands intuitive interfaces and minimal cleaning protocols.
- Emergency Services:Ambulance fleets and first responder units require compact, battery-redundant designs that withstand vibration and temperature extremes. Municipal procurement contracts emphasize device reliability under field conditions.
Hospitals anchor volume procurement; homecare settings expand most quickly.
Technology:
Aerosol generation mechanisms determine particle size distribution, medication waste rates, and regulatory testing requirements.
- Pneumatic:Compressed gas-driven Venturi systems remain the cost baseline for institutional procurement. Jet nebulizers dominate where capital equipment amortization and supply chain standardization outweigh performance advantages.
- Ultrasonic:High-frequency piezoelectric transducers generate aerosol through liquid surface disruption. Thermal effects limit heat-sensitive medication compatibility, constraining application scope for protein-based therapies.
- Vibrating Mesh:Aperture plate oscillation at 100+ kHz produces consistent particle sizes with minimal residual volume. FDA 510(k) clearance timelines favor manufacturers with pre-validated biocompatibility documentation under ISO 18562.
- Jet:Continuous-flow compressed air systems with baffles control droplet size through aerodynamic shear. These systems face displacement pressure from mesh alternatives in premium segments.
Pneumatic technology retains installed base dominance; vibrating mesh gains share fastest.
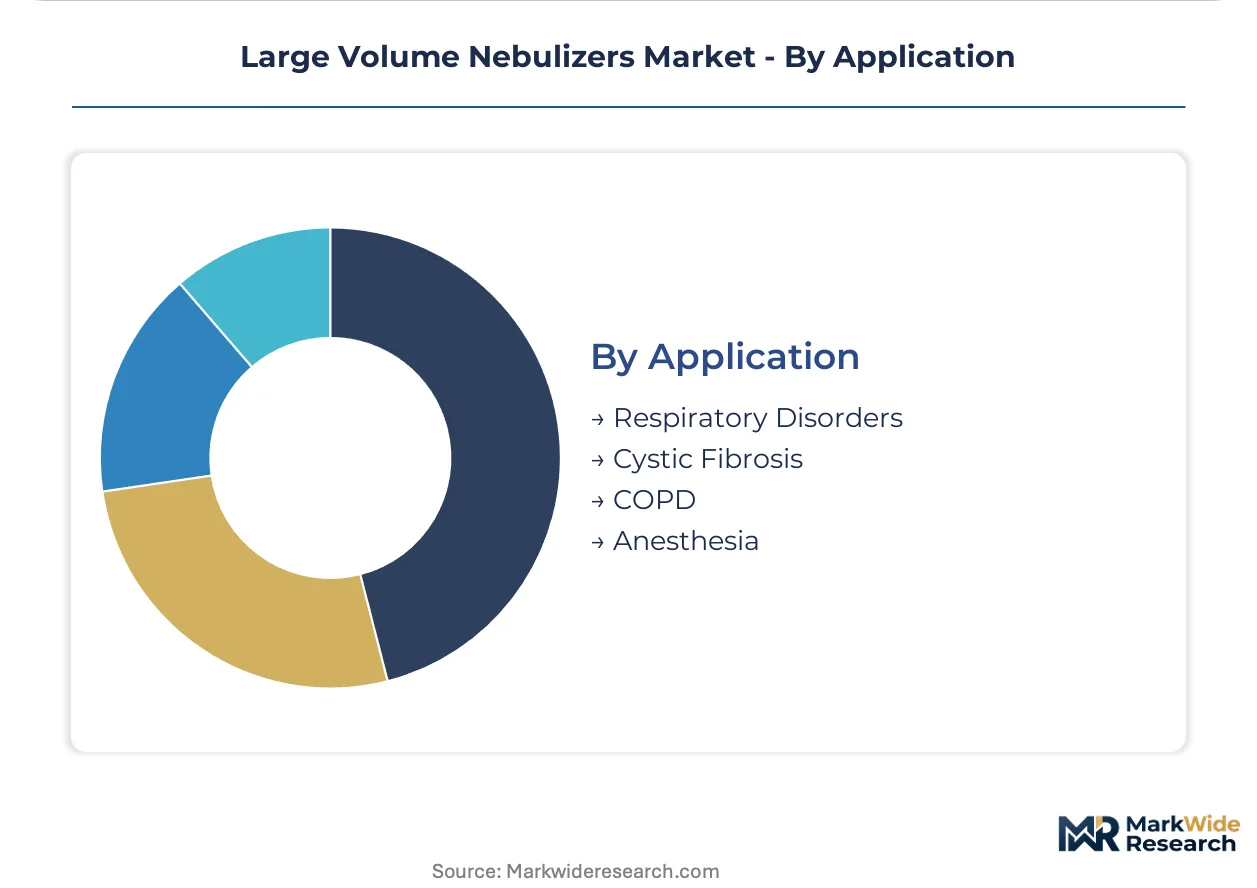
Application:
Therapeutic indication determines dosing frequency, medication viscosity, and patient population characteristics.
- Respiratory Disorders:Asthma and acute bronchospasm management drives high-frequency nebulizer utilization across all care settings. Bronchodilator delivery protocols standardize around specific particle size ranges for lower airway deposition.
- Cystic Fibrosis:Mucolytic and antibiotic aerosol therapy requires devices capable of handling viscous formulations without clogging. Specialized nebulizer designs accommodate tobramycin and dornase alfa with validated cleaning protocols.
- COPD:Chronic obstructive pulmonary disease patients generate recurring device demand through progressive disease management. Long-acting bronchodilator and corticosteroid combination therapies favor efficient medication delivery systems.
- Anesthesia:Perioperative bronchodilator premedication and airway management utilize nebulizers in surgical preparation sequences. Operating room integration demands rapid treatment completion and minimal equipment footprint.
Respiratory disorders command the largest patient population; COPD demonstrates the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision engineering clusters command premium mesh technology positioning, while the United States sustains volume procurement through Medicare infrastructure and aging demographics. Japan's compact device innovation competes for portable segment share against Chinese manufacturing scale.
United States
COPD prevalence among Americans over 65 drives institutional procurement and homecare replacement cycles. FDA 510(k) clearance pathways and ISO 18562 biocompatibility requirements shape product development timelines for market access. Minnesota and Massachusetts host medical device clusters where pneumatic and mesh technology R&D concentrates.
Germany
Engineering heritage sustains premium positioning in pneumatic and vibrating mesh segments for export markets. EU MDR and REACH substance restrictions extend conformity assessment timelines, favoring established regulatory affairs capacity. Stuttgart and Munich anchor precision manufacturing clusters for aperture plate geometries and piezoelectric transducer optimization.
Japan
Aging population density and compact living spaces accelerate demand for silent, handheld nebulizer configurations. PMDA regulatory frameworks align with international standards while maintaining distinct documentation requirements for breathing gas pathways. Osaka and Tokyo metropolitan areas concentrate device miniaturization expertise and patient-centered design capabilities.
China
Domestic manufacturing scale and respiratory disease burden expand both production capacity and local consumption. NMPA device classification rules and GB standards for medical electrical equipment govern market entry for indigenous and imported products. Shenzhen and Shanghai clusters integrate component sourcing with finished device assembly for cost-optimized pneumatic systems.
United Kingdom
NHS procurement frameworks and homecare service outsourcing reshape purchasing patterns toward total cost of ownership metrics. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR while streamlining certain conformity routes. London and Cambridge medical technology corridors concentrate distribution logistics and clinical validation partnerships.
Large Volume Nebulizers Market Competitive Landscape
Top-tier vendors anchor premium mesh technology positioning, while mid-scale specialists compete on pneumatic system cost optimization and regional distribution density. The vendor base stratifies across German engineering heritage, North American acute-care contract structures, and East Asian manufacturing scale. Three archetypes dominate: precision technology licensors, acute-care channel integrators, and compact transport specialists. Consolidation pressure manifests through strategic partnerships for regulatory clearance acceleration and geographic expansion into Medicare competitive bidding regions.
Within the precision technology tier, PARI GmbH represents German engineering-based premium positioning, while Vyaire Medical anchors North American acute-care channel relationships. GaleMed Corporation exemplifies the compact transport specialist archetype targeting emergency services procurement. These three occupy distinct competitive vectors—technology licensing, institutional contract structures, and field-durability design—rather than direct segment overlap.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| PARI GmbH |
| Tri-Anim Health Services, Inc. |
| Vyaire Medical |
| Sarnova, Inc. |
| Winnomed |
| GaleMed Corporation |
| Vadi Medical Technology Co., Ltd. |
| GF Health Products, Inc. |
| Others |
Supply & Pricing Matrix
Medicare competitive bidding consolidation in the United States is compressing margins for durable medical equipment suppliers and forcing manufacturers to reconfigure component sourcing toward lower-cost production clusters. This demand-side pressure propagates backward through supply chains, fragmenting pricing power across pneumatic legacy systems and vibrating mesh premium tiers.
Pricing Analysis
Capacity additions in China and Mexico are reshaping price floors for pneumatic nebulizer assemblies, eroding the cost advantage of legacy compressor-based systems. Three-tier pricing structure across premium, standard, and economy levels separates ISO 18562-validated mesh devices from basic jet nebulizers and unbranded imports. Pricing pressure stems from soft-mist inhaler formulary inclusion displacing home nebulizer reimbursement codes. Hospital group purchasing organizations demonstrate lowest price sensitivity; Medicare homecare suppliers face acute margin compression.
Supply Chain Analysis
Trans-Pacific freight rate volatility and port congestion at Los Angeles-Long Beach are elevating landed costs for piezoelectric transducers sourced from Japanese component houses. Manufacturing concentrates in China, Germany, and the United States, with Shenzhen clusters feeding cost-optimized pneumatic systems and Stuttgart engineering centers anchoring precision mesh fabrication. Supply chains draw from specialty polymers, piezoelectric ceramics, and medical-grade silicones. Single-source vulnerability concentrates in aperture plate micro-machining equipment. Distribution runs through hospital group purchasing organizations, durable medical equipment suppliers, and emergency services fleet contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Large Volume Nebulizers Market functions as a stable compounder anchored by irreversible demographic shifts in chronic respiratory disease prevalence among aging populations.
For Market Incumbents: Extend service contract bundling beyond hardware sales to capture recurring revenue streams as hospitals outsource preventive maintenance. Deepen backward integration into piezoelectric transducer production to defend margin position against Chinese component cost erosion. Prioritize FDA 510(k) clearance acceleration for next-generation mesh geometries before reimbursement compression intensifies. For New Entrants and Emerging Players: Ambulance fleet procurement managers represent an underserved buyer archetype with concentrated municipal contract value and limited incumbent loyalty. Compact transport-oriented designs with battery-redundant architectures penetrate emergency services faster than saturated homecare channels. Target direct municipal healthcare system relationships rather than distributor intermediaries to compress sales cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with precision mesh technology licensors holding proprietary aperture plate patents and established ISO 13485 quality systems. Long-term viability over a decade-long horizon favors manufacturers with regulatory affairs capacity spanning FDA, EU MDR, and Japan PMDA pathways. Monitor CMS reimbursement coding revisions for home nebulizer therapy as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Compresses market access timelines for mesh nebulizers targeting Medicare homecare channels. |
| EU MDR Conformity Pathway Investment | Extends clinical evaluation capacity for breathing gas pathway biocompatibility documentation. |
| Hospital System Partnership | Locks in multi-year group purchasing organization contracts with total cost of ownership metrics. |
| Software Companion Development | Enables connected nebulizer platforms for remote patient monitoring and adherence tracking. |
| Reimbursement Strategy Alignment | Positions devices within favorable CMS coding categories against soft-mist inhaler displacement. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with biomedical engineers, hospital purchasing committee members, durable medical equipment procurement directors, and group purchasing organization contract managers. Secondary validation draws from FDA 510(k) clearance databases, EU MDR notified body submissions, CMS Medicare competitive bidding records, and hospital procurement transaction logs. Bottom-up unit demand estimates triangulate against top-down market value reconstructions.
Rate-of-change decomposition separates volume growth from price trajectory across the projection horizon. Segmentation dimensions modeled include technology type, end-use environment, patient population severity, and regional regulatory cluster. CAGRs derive from fitted trend extrapolation adjusted for patent expiry impacts, reimbursement regime shifts, and technology substitution elasticities. Forecast inputs incorporate COPD prevalence projections, Medicare beneficiary growth, and pneumatic-to-mesh technology transition rates.
Underlying measurement precision varies by segment; vibrating mesh technology and homecare settings carry tighter precision than legacy pneumatic systems in institutional markets. Forecasts reflect documented assumptions regarding regulatory clearance timelines, reimbursement stability, and competitive entry patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
China Intrauterine Devices Market
Medical Devices
Enteral Stents Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
Pipetting Systems Market
Medical Devices
Actigraphy Sensors and Polysomnography Devices Market
Medical Devices
Cervical Spine System Market
Medical Devices
Wheelchair and Components Market
Medical Devices
At-Home Vaginal Ph Test Kit Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
Neurotechnology Market
Medical Devices
Next Generation Infusion Pump Market
Medical Devices
Nano Healthcare Technology Market
Medical Devices
Global Ureteral Stent Market
Medical Devices
Urolithiasis Management Devices Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
Global Neurovascular Guidewires Market