
 Middle East and Africa C-Arms Market | 2026-2036
Middle East and Africa C-Arms Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa C-Arms Market Foresight
Flat-panel detector technology is recalibrating product economics across the Middle East and Africa C-Arms landscape by displacing legacy image intensifier systems. Siemens Healthineers leverages its installed base in Gulf Cooperation Council tertiary centers to sustain service revenue streams. GE Healthcare anchors its regional position through localized refurbishment hubs in South Africa. Koninklijke Philips NV competes on digital integration, positioning its systems for hybrid operating room workflows.
A C-arm denotes a fluoroscopic imaging device with a C-shaped gantry that houses an X-ray source and detector array, typically operating at 50-120 kVp with real-time image acquisition rates exceeding 30 frames per second for intraoperative guidance. The apparatus enables dynamic visualization during orthopedic fixation, cardiac catheterization, and pain management interventions without repositioning the patient. Mobile C-Arms dominate current procurement cycles across the region's surgical centers, while Digital technology segments command premium placement in hospital capital budgets. Fixed C-Arms retain entrenched positions in dedicated cardiac catheterization laboratories, though Hybrid C-Arms represent the fastest-growing configuration as facilities consolidate interventional and surgical capabilities.
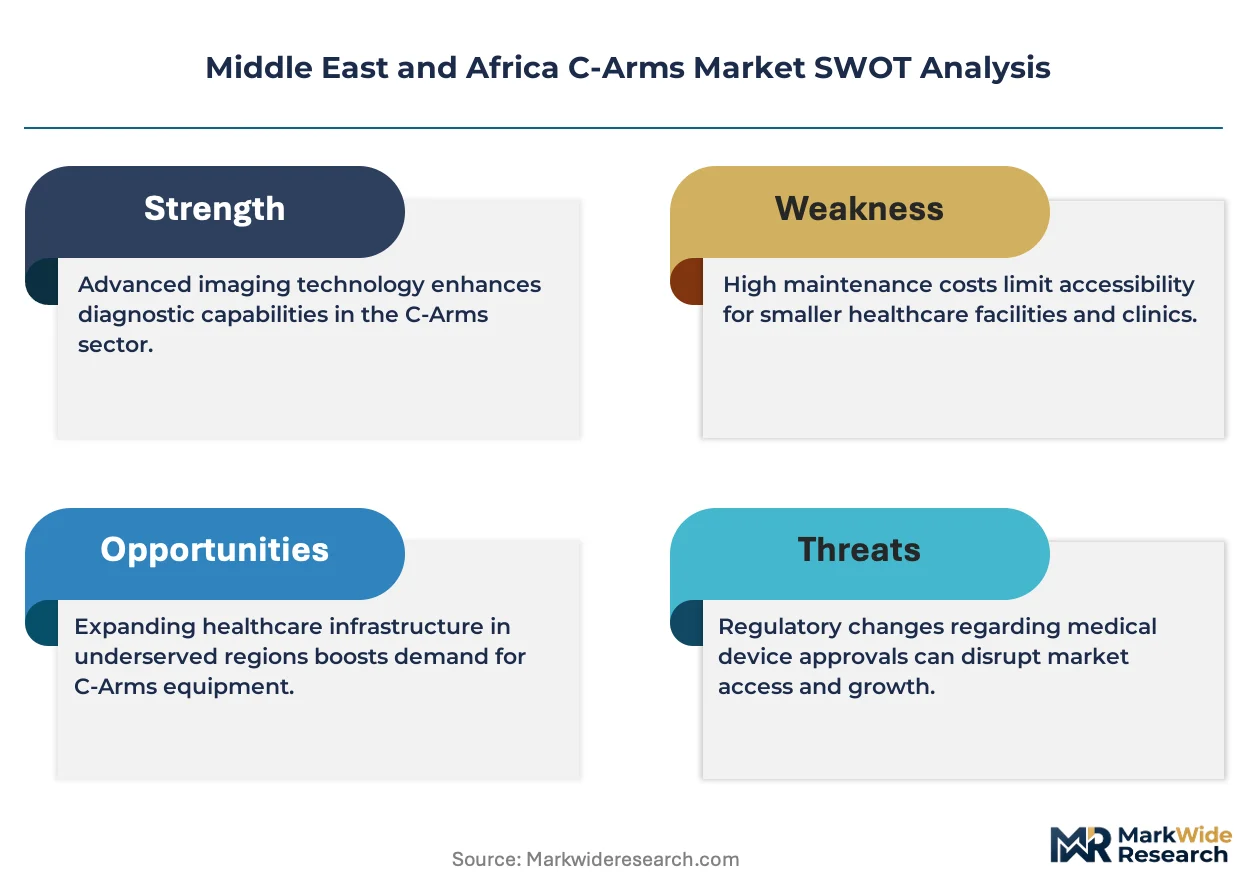
South Africa's SAHPRA, Saudi Arabia's SFDA, and the UAE's MOHAP collectively enforce medical device quality management system requirements that shape product registration timelines and aftermarket service obligations. CE marking alignment under the EU MDR transitional provisions continues to influence vendor qualification for North African markets tethered to European supply chains. Stakeholders must monitor harmonization gaps between Gulf standardization initiatives and sub-Saharan national regulatory frameworks to anticipate compliance cost escalations.
Market Dynamics
Flat-panel detector technology is compressing replacement cycles across surgical centers while Gulf privatization mandates accelerate capital deployment timelines.
Growth Catalysts
- Saudi Healthcare Privatization:The National Transformation Program mandates private sector participation targets that channel investment into diagnostic imaging infrastructure.
- Hybrid OR Construction:Tertiary hospitals in the UAE and Qatar are consolidating interventional cardiology and surgical capabilities into single-suite configurations.
- SFDA Streamlined Pathways:Saudi Arabia's medical device registration reforms have reduced technical documentation review periods for CE-marked systems.
Market Restraints
- Import Duty Structure:Egyptian customs tariffs on imaging equipment exceed regional averages, inflating landed costs for private hospital groups.
- Generator Component Concentration:X-ray tube and high-voltage generator supply chains concentrate among three European and Japanese manufacturers.
- Grid Infrastructure Deficits:Voltage instability in Nigerian and Kenyan secondary cities degrades image quality and accelerates detector calibration drift.
Strategic Opportunities
- Moroccan Diagnostic Network Expansion:The Ministry of Health's regional hospital modernization program targets 40 new surgical suites with fluoroscopic capability.
- Refurbishment Channel Formalization:Certified pre-owned C-Arm programs address budget constraints among Egyptian and Algerian private clinic chains.
- AI-Assisted Fluoroscopy Integration:Dose-reduction algorithms and anatomical recognition software are converging with detector hardware.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Field service technician pipelines remain underdeveloped across sub-Saharan markets, extending mean time to repair.
- Multi-Jurisdictional Registration Burden:Divergent technical file requirements between SAHPRA, SFDA, and MOHAP force redundant conformity assessments.
- PACS Integration Complexity:Legacy hospital information systems in South African public sectors resist seamless DICOM connectivity with mobile C-Arm units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa C-Arms Market |
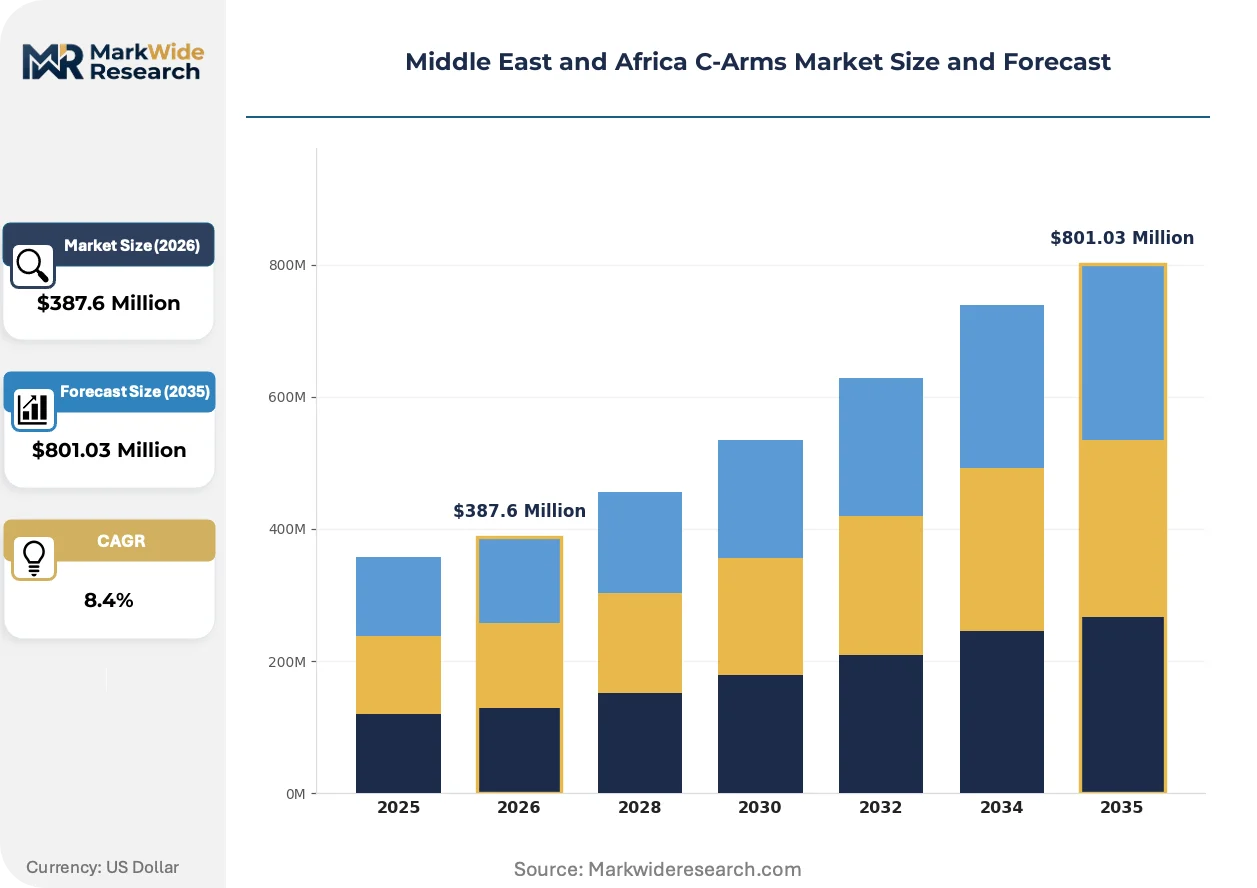
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $801.03 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed C-Arms, Mobile C-Arms, Mini C-Arms, Hybrid C-Arms End User: Hospitals, Surgical Centers, Diagnostic Imaging Centers, Research Institutions Technology: Direct Radiography, Computed Radiography, Analog, Digital Application: Orthopedics, Pain Management, Cardiovascular Procedures, Neurology |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips NV, Hologic Corporation, Canon Medical Systems Corporation, Ziehm Imaging GmbH, Orth Oscan Inc., BMI Biomedical International, Shimadzu Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa C-Arms Market Shifts & Advancements
Detector technology maturation and regulatory harmonization pressures are compressing product lifecycles while reshaping vendor-service relationships across the region.
CMOS flat-panel detectors are unifying image acquisition and processing functions previously handled by separate image intensifier and camera chain assemblies. Saudi Arabian orthopedic centers are adopting these systems at replacement rates exceeding historical intensifier upgrade cycles. This unification is collapsing the price premium between mobile and fixed configurations.
EU MDR transitional provisions are extending CE certificate validity timelines for legacy devices, creating temporary registration windows for North African distributors. SAHPRA has aligned quality management system audits with MDR Article 120 documentation standards. South African importers are leveraging this convergence to accelerate dual-market registrations.
Equipment-as-service models are displacing outright purchase contracts among Gulf private hospital operators. Leasing structures bundle preventive maintenance and software updates into per-procedure fee arrangements. This shift concentrates most visibly in Dubai's healthcare free zones.
Middle East and Africa C-Arms Market Segmentation
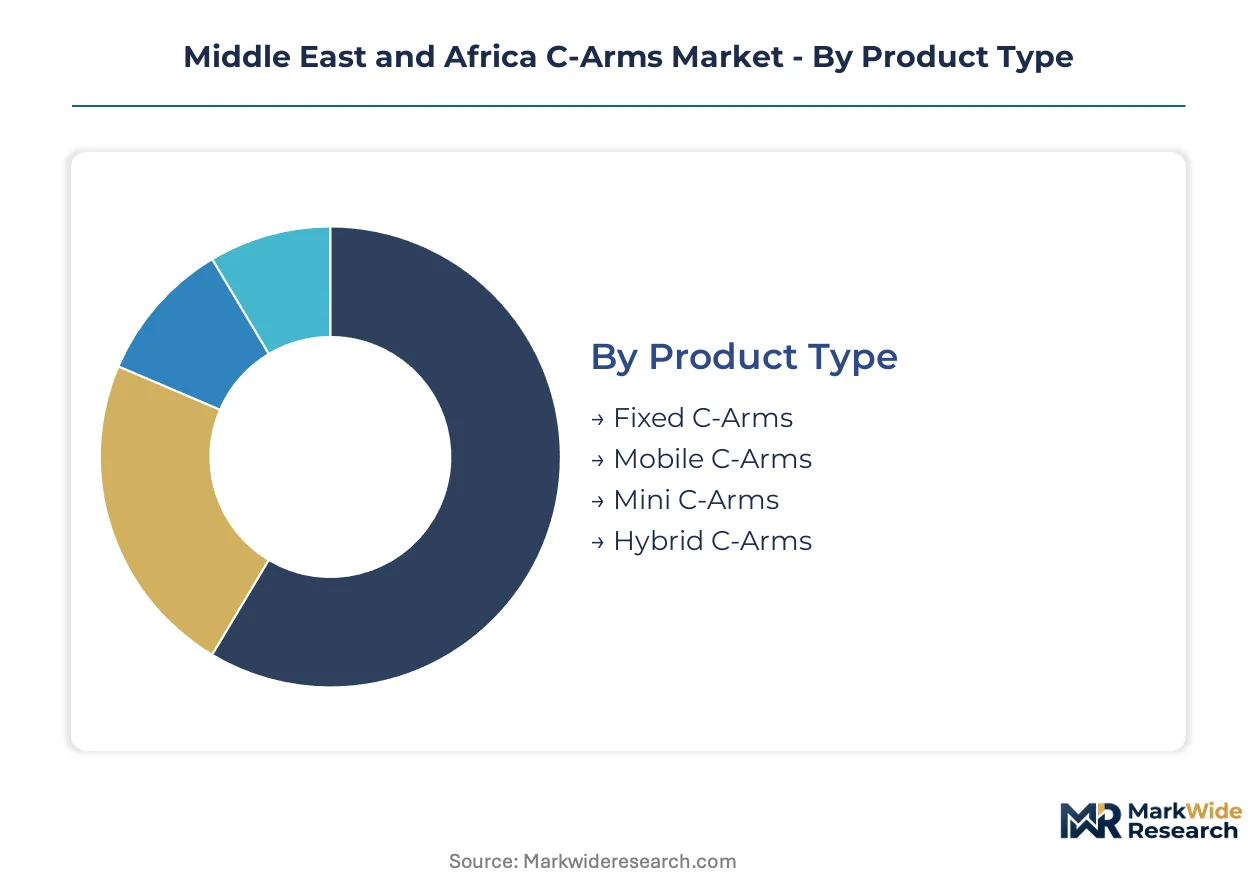
C-Arms procurement patterns across the Middle East and Africa diverge sharply by facility infrastructure, with tertiary hospitals prioritizing fixed installations while private surgical networks favor mobile configurations for capital flexibility.
Product Type:
Customization intensity varies from standardized mobile units to highly configured hybrid suites requiring architectural integration.
- Mobile C-Arms:Wheeled fluoroscopy systems with battery-backed power supplies enable rapid repositioning between operating theaters. Procurement concentrates among Saudi private hospital groups responding to National Transformation Program privatization timelines. These systems dominate replacement cycles across Egyptian and Algerian secondary cities where grid instability demands generator-independent operation.
- Hybrid C-Arms:Dual-purpose configurations merge surgical table integration with interventional catheterization capability. Demand clusters in Dubai and Abu Dhabi healthcare free zones where facilities consolidate cardiac and orthopedic service lines into single-suite footprints. Leasing structures bundle these systems into per-procedure fee arrangements.
- Fixed C-Arms:Ceiling-mounted or floor-fixed gantries with dedicated generator rooms serve dedicated catheterization laboratories.
- Mini C-Arms:Compact extremity-focused systems with reduced field-of-view target outpatient orthopedic clinics.
Leading the category by volume: Mobile C-Arms. Growing fastest: Hybrid C-Arms.
End User:
Capital deployment capacity separates high-volume purchasers from price-sensitive adopters across this category.
- Hospitals:Tertiary medical centers with dedicated biomedical engineering departments absorb full-service contracts and preventive maintenance schedules. Saudi Arabia's healthcare privatization corridors channel the largest capital allocations, with SFDA-streamlined registration pathways accelerating procurement timelines for CE-marked systems.
- Surgical Centers:Ambulatory facilities with focused procedure mixes prioritize mobile C-Arms for multi-specialty utilization. South African private clinic chains leverage GE Healthcare's Johannesburg refurbishment hub to access certified pre-owned inventory.
- Diagnostic Imaging Centers:Standalone radiology providers serving referral networks.
- Research Institutions:Academic medical centers with protocol development requirements.
Revenue concentration sits with hospitals. Expanding most quickly: surgical centers.
Technology:
Detector architecture determines image acquisition economics and regulatory compliance burden.
- Digital:CMOS flat-panel detectors unify acquisition and processing functions previously requiring separate image intensifier chains. Saudi orthopedic centers adopt these at replacement rates exceeding historical intensifier upgrade cycles. This unification collapses price premiums between mobile and fixed configurations.
- Direct Radiography:Amorphous selenium or cesium iodide panels convert X-ray photons directly to electrical signals.
- Computed Radiography:Photostimulable phosphor plates require separate scanning stations.
- Analog:Image intensifier and camera chain assemblies retain entrenched positions in budget-constrained Nigerian and Kenyan secondary cities.
Digital technology commands premium placement in hospital capital budgets. Analog systems face accelerating displacement.
Application:
Procedure reimbursement rates and clinical workflow complexity shape technology requirements.
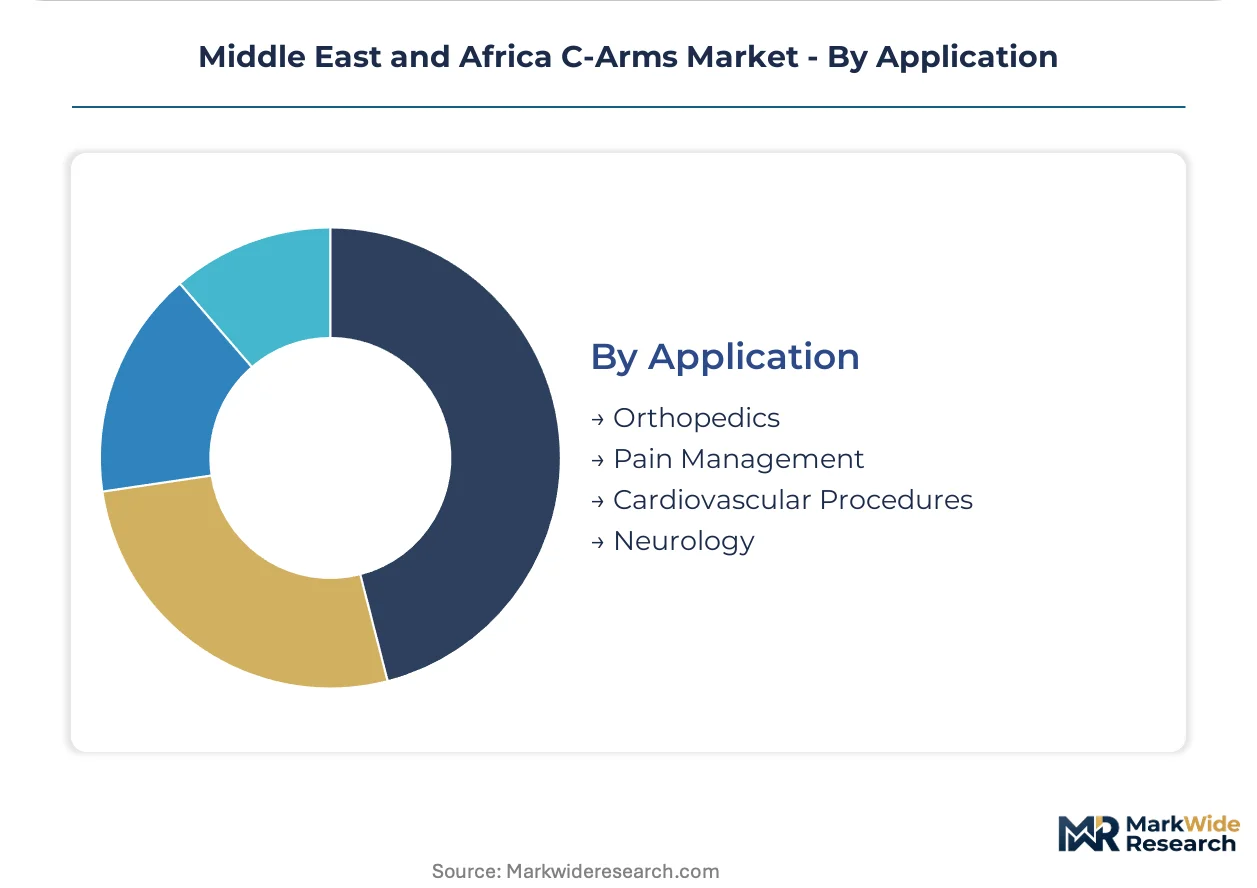
- Orthopedics:Trauma fixation, arthroscopy, and spine procedures demand high-resolution bony detail at low dose. South African tertiary hospitals anchor regional demand, with SAHPRA quality management system audits aligning with EU MDR documentation standards to accelerate dual-market registrations.
- Cardiovascular Procedures:Percutaneous coronary intervention and electrophysiology mapping require real-time roadmap imaging. UAE and Qatar hybrid OR construction drives configuration complexity.
- Pain Management:Epidural and facet joint injections utilize C-Arm guidance for needle placement.
- Neurology:Cerebral angiography and shunt placement procedures.
Orthopedics generates the highest procedure volume. Cardiovascular applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai Healthcare City and Abu Dhabi's KIZAD free zones concentrate C-Arms distribution infrastructure for Gulf markets. South Africa's Western Cape manufacturing incentives anchor refurbishment operations serving sub-Saharan demand corridors.
Saudi Arabia
The National Transformation Program channels private capital into diagnostic imaging infrastructure across Riyadh and Jeddah medical cities. SFDA streamlined registration pathways reduce technical documentation review periods for CE-marked systems. Eastern Province tertiary hospitals anchor hybrid OR construction consolidating cardiac catheterization with surgical capabilities.
United Arab Emirates
Dubai's healthcare free zones deploy equipment-as-service leasing models bundling preventive maintenance into per-procedure fees. MOHAP enforces quality management system requirements shaping product registration timelines and aftermarket obligations. Abu Dhabi hybrid operating room construction drives demand for dual-purpose interventional-surgical configurations.
South Africa
SAHPRA tightened medical device registration pathways while aligning quality management audits with EU MDR Article 120 documentation standards. Johannesburg refurbishment hubs serve private clinic chains accessing certified pre-owned inventory. Western Cape biomedical engineering programs address field service technician scarcity extending mean time to repair.
Egypt
Customs tariffs on imaging equipment exceed regional averages, inflating landed costs for Cairo and Alexandria private hospital groups. The country's national medical device regulator maintains divergent technical file requirements from Gulf standardization initiatives. Nile Delta secondary cities retain entrenched analog image intensifier systems where grid instability demands generator-independent mobile configurations.
Morocco
The Ministry of Health's regional hospital modernization program targets surgical suites with fluoroscopic capability in Casablanca and Rabat medical districts. CE marking alignment under transitional provisions influences vendor qualification through European supply chain tethering. Marrakech and Fez private clinic networks concentrate orthopedic procedure volume driving mobile C-Arms procurement.
Middle East and Africa C-Arms Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-system vendors commanding premium placement in tertiary hospital capital budgets while refurbishment operators capture price-sensitive private clinic demand. The vendor base concentrates around imaging conglomerates with installed base leverage, mid-scale European specialists with detector technology differentiation, and regional service integrators with localized aftermarket presence. Three archetypes dominate: Gulf-installed-base incumbents sustaining service revenue streams, refurbishment hub operators with South African logistics advantages, and digital integration specialists positioning for hybrid OR workflows. Competitive moves center on equipment-as-service model proliferation and AI-assisted fluoroscopy integration bundling dose-reduction algorithms with detector hardware.
Within the imaging conglomerate tier, GE Healthcare, Siemens Healthineers, and Koninklijke Philips NV occupy positions shaped by installed base scale and regional service infrastructure density. GE Healthcare exemplifies the refurbishment hub archetype through its Johannesburg-based operations serving sub-Saharan clinic chains with certified pre-owned inventory. Siemens Healthineers represents Gulf-installed-base leverage sustaining service revenue streams across tertiary centers in Saudi Arabia and the UAE. Koninklijke Philips NV sits within the digital integration specialist category, with positioning converging on hybrid operating room workflows and AI-assisted fluoroscopy bundling.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips NV |
| Hologic Corporation |
| Canon Medical Systems Corporation |
| Ziehm Imaging GmbH |
| Orth Oscan Inc. |
| BMI Biomedical International |
| Shimadzu Corporation |
| Others |
Supply & Pricing Matrix
Saudi private hospital groups consolidating procurement under National Transformation Program mandates anchor equipment-as-service leasing structures across Gulf markets. This buyer concentration compresses upfront capital outlays while bundling preventive maintenance into per-procedure fee arrangements, reshaping vendor cash flow patterns and aftermarket revenue recognition.
Pricing Analysis
Premium pricing attaches to systems with sub-90-day delivery windows serving Dubai healthcare free zone construction timelines, while spot inventory from Johannesburg refurbishment hubs commands 15-25% discounts. Three-tier pricing structure across premium hybrid configurations, standard mobile units, and economy analog intensifier systems stratifies by detector architecture and software integration depth. Cost compression in the analog tier intensifies as Moroccan and Egyptian clinics accelerate digital migration. Surgical centers in Algeria and Kenya exhibit highest price sensitivity, deferring replacement cycles until refurbishment inventory surfaces.
Supply Chain Analysis
CE marking alignment under EU MDR transitional provisions gates vendor qualification for North African distribution channels tethered to European supply chains. X-ray tube and high-voltage generator production concentrates in Germany, Japan, and the Netherlands, while CMOS flat-panel detector fabrication rests on South Korean and Taiwanese semiconductor foundries. Single-source vulnerability in generator component supply chains exposes procurement timelines to 6-9 month order backlogs. Distribution runs through Dubai Healthcare City and Abu Dhabi KIZAD free zones serving Gulf markets, with Johannesburg refurbishment hubs feeding sub-Saharan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flat-panel detector technology is displacing legacy image intensifier systems across the Middle East and Africa C-Arms landscape, compressing replacement cycles and recalibrating vendor-service relationships. This transition phase rewards players with detector manufacturing partnerships and hybrid OR integration capabilities.
For Market Incumbents: Deepen service infrastructure density in Saudi tertiary corridors to defend against equipment-as-service model proliferation by regional integrators. Anchor refurbishment certification programs in South Africa to capture price-sensitive demand from Nigerian and Kenyan clinic chains facing currency volatility. Prioritize AI-assisted fluoroscopy R&D partnerships to differentiate hybrid OR offerings in UAE and Qatar construction pipelines. For New Entrants and Emerging Players: Enter via certified pre-owned channel formalization targeting Egyptian and Algerian private clinic networks constrained by customs tariff inflation on new equipment. The Moroccan Ministry of Health regional hospital modernization program offers the most penetrable white-space for mobile C-Arms deployment. Pursue distributor partnerships with European OEMs seeking CE-marked system placement in North African markets. For Investors and Strategic Acquirers: The window for entry favors refurbishment hub operators with Johannesburg logistics advantages and SAHPRA registration expertise. Long-term viability hinges on exposure to Saudi healthcare privatization corridors and hybrid OR construction trajectories. Monitor SFDA registration pathway efficiency as the inflection signal for Gulf market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid OR Construction Partnership | Dual-purpose configurations consolidate cardiac and orthopedic service lines in Dubai and Abu Dhabi free zones. |
| Refurbishment Hub Certification | Johannesburg-based operations capture price-sensitive demand from sub-Saharan clinic chains. |
| AI-Assisted Fluoroscopy Integration | Dose-reduction algorithms bundled with detector hardware differentiate premium system positioning. |
| Equipment-as-Service Model Deployment | Per-procedure fee arrangements displace outright purchase contracts among Gulf private operators. |
| Dual-Market Registration Alignment | EU MDR Article 120 documentation standards accelerate SAHPRA and SFDA pathway convergence. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contracts, and SFDA registration filings underwrites the qualitative findings in this study. Primary interviews with biomedical engineering directors, hospital purchasing committee members, and GPO contracts managers combined with secondary validation from customs/trade data, CE marking documentation, and equipment leasing disclosure records. Bottom-up demand modeling triangulates against top-down market sizing across the analysis window.
Rate-of-change decomposition separates volume expansion from price-mix effects across product type, technology architecture, end-user facility tier, and application segment dimensions. CAGRs derive from procedure volume trajectories, replacement cycle compression, and capital deployment patterns modeled throughout the forecast period. Industry-specific inputs include SFDA registration pathway efficiency indices and hybrid OR construction pipeline tracking.
Forecast precision tightens around the base case; tail outcomes carry wider variance under grid infrastructure deficit scenarios in Nigerian and Kenyan secondary cities. Forecasts reflect assumptions documented in segmentation and regional outlook sections. A model refresh is warranted upon material change in Saudi healthcare privatization participation targets or EU MDR transitional provision extensions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Disposable Lancets Market
Medical Devices
Medical Polyimide Tubing Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Membrane Oxygenators Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
Hearing Aids Market
Medical Devices
Cranial Implants Treatment Market
Medical Devices
Sweden Ophthalmic Devices Market
Medical Devices
Global Disposable Medical Sensors Market
Medical Devices
Urinary Incontinence Devices Market
Medical Devices
Alexandrite Gemstone Lasers Market
Medical Devices
Surgical Smart Glasses Market
Medical Devices
Intrapartum Monitors Market
Medical Devices
Internal Trauma Fixation Device Market
Medical Devices
Saudi Arabia Anesthesia Devices Market
Medical Devices
Global Medical Laser Systems Market