
 Cryoprecipitated Antihemophilic Factor Market | 2026-2036
Cryoprecipitated Antihemophilic Factor Market Size, Share, and Industry Trends Forecast 2026-2036
Cryoprecipitated Antihemophilic Factor Market Analytics
Recombinant factor concentrates is rebalancing procurement economics away from traditional plasma-derived cryoprecipitate across major health systems. Baxter International Inc leverages its integrated plasma collection network to sustain cryoprecipitate supply stability in North American hospital chains. CSL Behring anchors its position through vertical control of fractionation capacity across Australian and US facilities. Grifols dominates European plasma sourcing, competing on volume scale against recombinant alternatives.
Cryoprecipitated antihemophilic factor is a cold-insoluble plasma protein concentrate containing fibrinogen, factor VIII, von Willebrand factor, and factor XIII, prepared by thawing fresh frozen plasma at one to six degrees Celsius and recovering the precipitate for intravenous administration in bleeding disorders. The product type dimension shows cryoprecipitate retaining relevance in trauma care and massive transfusion protocols where rapid fibrinogen replacement takes priority over recombinant precision. End user concentration favors hospitals and hematology clinics, with blood banks serving as critical intermediaries in emergency distribution networks.
FDA plasma collection standards and EMA blood product guidelines govern manufacturing consistency, viral safety, and lot release criteria that determine market access for both domestic and imported cryoprecipitate. The EU F-Gas Regulation and US EPA cold-chain requirements shape storage infrastructure investment, directly affecting distribution economics for temperature-sensitive biologics. Stakeholders must weigh plasma supply sustainability against recombinant substitution curves when committing to long-term hemophilia therapy contracts.
Market Dynamics
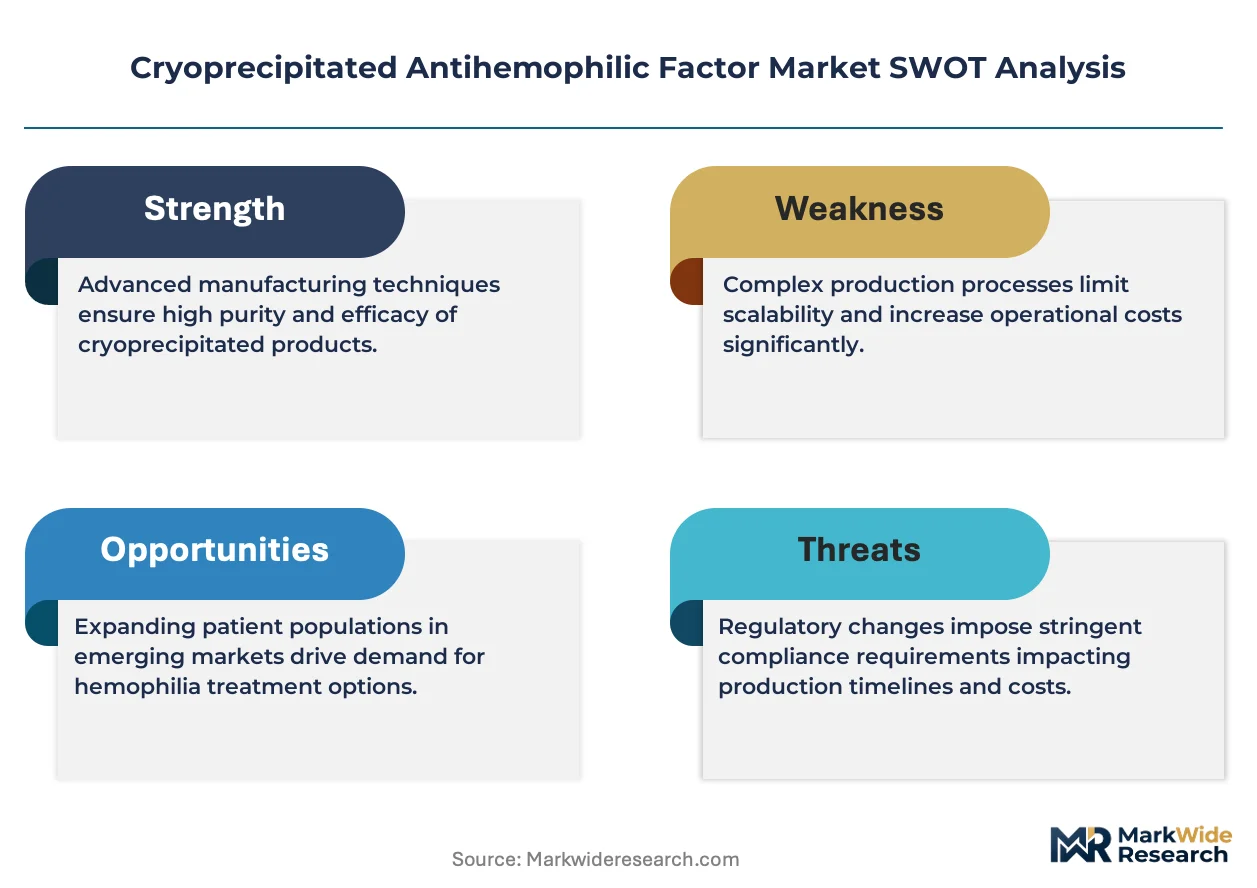
Recombinant factor VIII concentrates are systematically displacing plasma-derived cryoprecipitate across major hemophilia treatment centers, forcing blood product suppliers to defend volume through trauma and surgical niches where rapid fibrinogen replacement retains clinical priority.
Growth Catalysts
- von Willebrand disease protocols:Hemophilia treatment centers in the United States are expanding cryoprecipitate utilization for acquired and congenital von Willebrand disease where desmopressin fails. This indication preserves hospital formulary placement against recombinant competition.
- FDA plasma collection standards:Stringent viral safety and lot release criteria under FDA guidance sustain physician confidence in plasma-derived products for emergency settings. Regulatory clarity accelerates hospital procurement committee approvals.
- Massive transfusion protocols:Trauma centers and surgical suites maintain cryoprecipitate stockpiles for rapid fibrinogen correction during hemorrhage. This clinical workflow creates durable demand independent of hemophilia prophylaxis trends.
Market Restraints
- Plasma supply concentration:United States plasma collection networks dominate global source material, exposing non-US manufacturers to import dependency and geopolitical supply risk.
- Recombinant substitution:Extended half-life recombinant factor VIII and emicizumab prophylaxis reduce bleeding episodes, compressing routine cryoprecipitate utilization in hemophilia A.
- Cold-chain infrastructure costs:EPA refrigeration requirements and EU F-Gas Regulation compliance impose capital intensity on storage and distribution networks, elevating per-unit logistics expense.
Strategic Opportunities
- Rural hospital networks:Underserved regions in India and Southeast Asia lack recombinant cold-chain infrastructure, preserving cryoprecipitate relevance where plasma fractionation capacity exists.
- Fibrin sealant convergence:Combination of cryoprecipitate-derived fibrinogen with thrombin in surgical hemostasis opens tissue adhesive applications beyond intravenous replacement.
- Emergency blood bank channels:Direct-to-hospital distribution partnerships bypass traditional wholesaler markups, capturing margin in time-critical transfusion scenarios.
Industry Challenges
- Fractionation specialist scarcity:Plasma protein purification expertise concentrates at legacy CSL Behring and Grifols facilities, constraining new entrant technical staffing.
- Viral validation timelines:Nucleic acid testing and pathogen inactivation protocol certification under EMA blood product guidelines extend lot release cycles, compressing inventory turns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryoprecipitated Antihemophilic Factor Market |
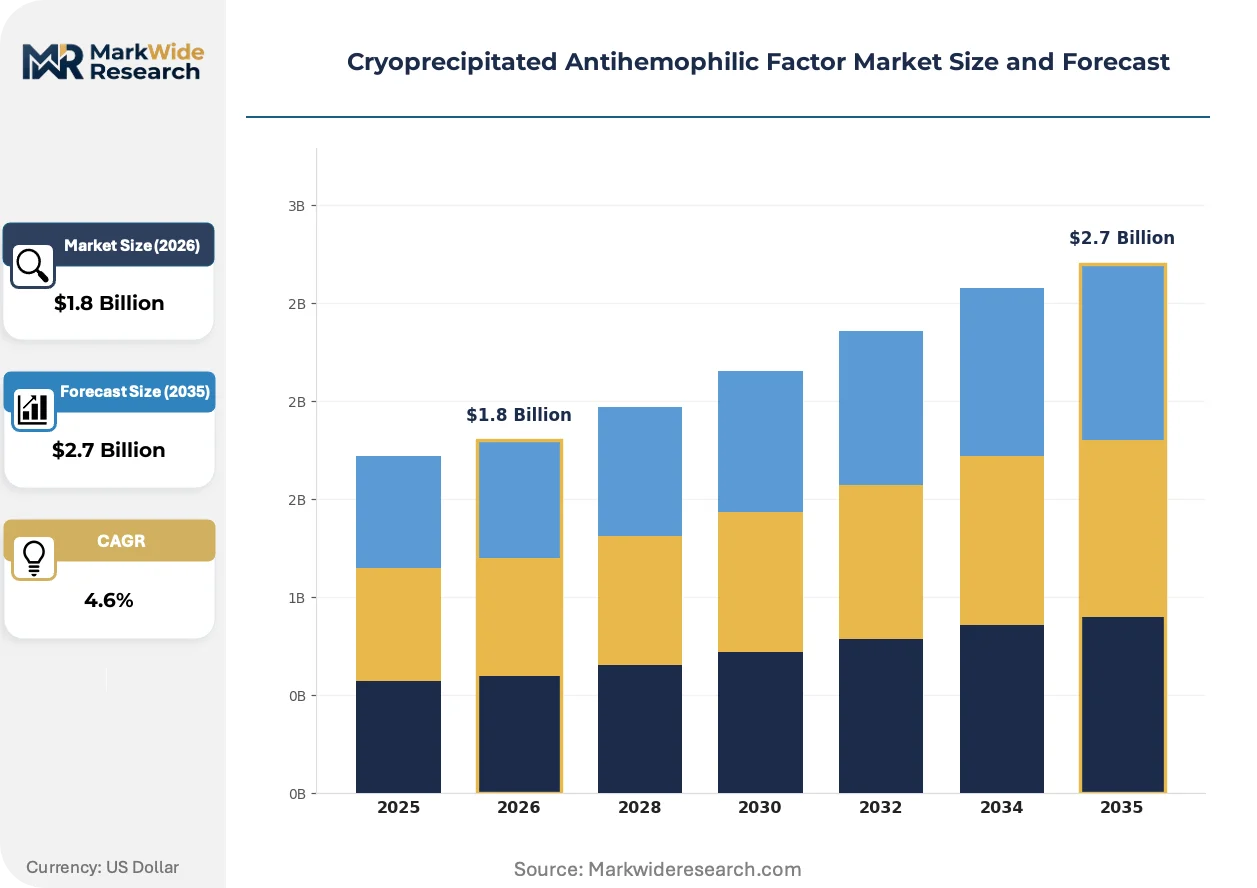
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pooled Plasma, Recombinant Factor, Fresh Frozen Plasma, Cryoprecipitate End User: Hospitals, Blood Banks, Hematology Clinics, Specialty Clinics Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral Application: Coagulation Disorders, Surgical Procedures, Trauma Care, Hemorrhagic Conditions |
| Companies Covered | Baxter International Inc, CSL Behring, Grifols, Bayer AG, Pfizer, Inc., Takeda Pharmaceutical Co. Ltd., Bio Products Laboratory Ltd., Novo Nordisk A/S, Biogen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryoprecipitated Antihemophilic Factor Market Evolving Landscape
Pathogen reduction technologies and automated thawing systems are redefining cryoprecipitate handling standards, while procurement patterns tilt toward consolidated blood bank networks that favor suppliers with integrated plasma collection.
Solvent-detergent treatment and riboflavin-based pathogen inactivation are modularizing viral safety architecture in cryoprecipitate manufacturing. Blood banks in Germany and Australia are adopting these platforms to reduce transfusion-transmitted infection risk. The technology is modularizing regulatory compliance costs, enabling smaller fractionators to meet FDA and EMA safety benchmarks without captive plasma collection infrastructure.
EMA blood product guidelines and FDA guidance on post-collection pathogen reduction are tightening manufacturing consistency requirements across European and North American facilities. Industrial consequence includes accelerated consolidation of contract fractionation services toward vertically integrated plasma collectors. Hospital blood banks in France and Italy are responding by qualifying fewer suppliers with demonstrated viral safety validation.
Consolidated procurement through regional blood center networks is compressing vendor diversity in the United States. Independent hospitals are ceding purchasing authority to entities like Blood Centers of America and America's Blood Centers, which negotiate volume contracts with CSL Behring and Grifols. This concentration is most visible in the Midwest and Southeast, where rural hospital participation in shared services organizations exceeds sixty percent of transfusion volume.
Cryoprecipitated Antihemophilic Factor Market Segmentation
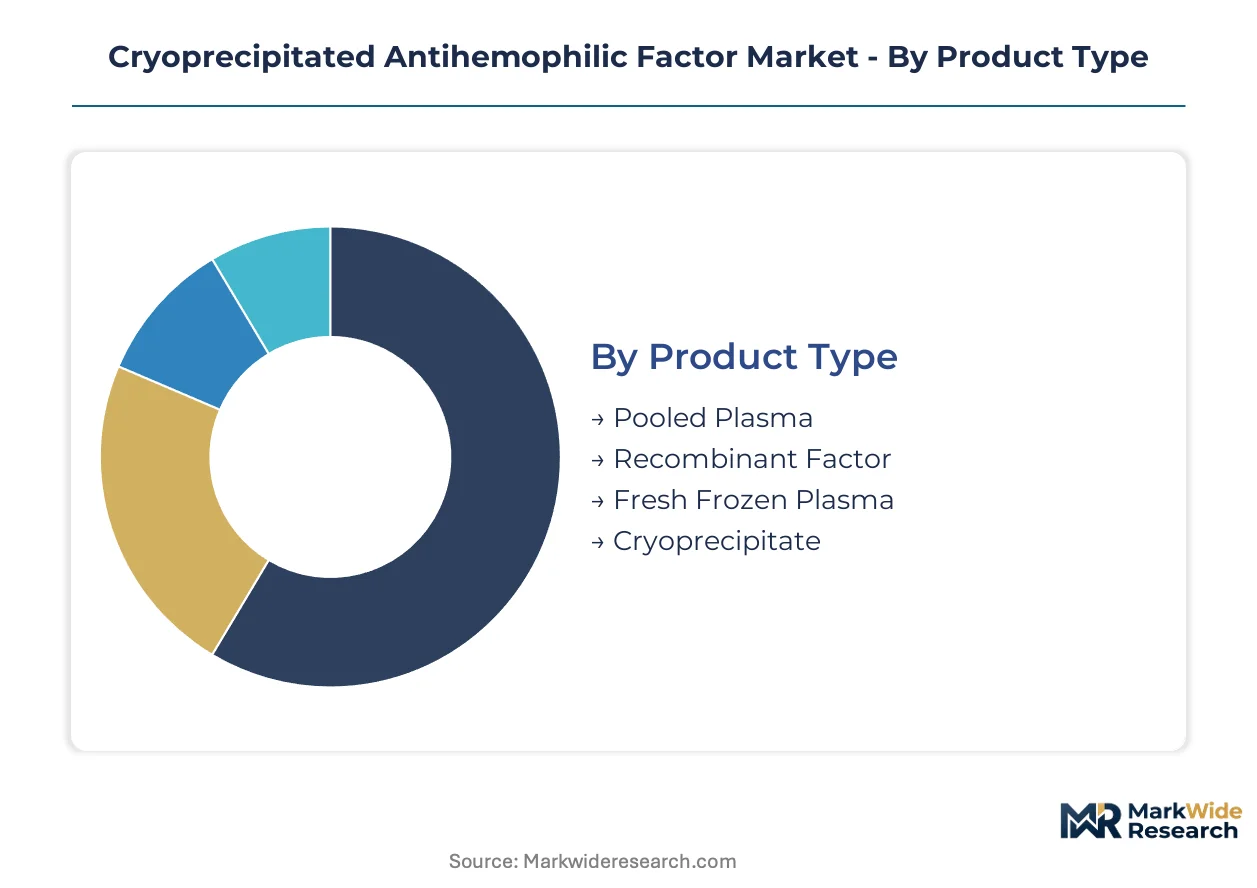
Segmentation in the cryoprecipitated antihemophilic factor market reveals distinct procurement patterns across product formulations and clinical settings. Hospital formulary decisions and blood bank inventory policies create divergent demand profiles that suppliers must navigate through differentiated service models.
Product Type:
Cryoprecipitate functions as a standalone fibrinogen concentrate in trauma protocols, while recombinant alternatives embed into chronic hemophilia management systems.
- Pooled Plasma:Multiple donor units combined for fractionation yield consistent factor VIII concentrations across production lots. Demand concentrates in European hospital networks where EMA blood product guidelines favor centralized fractionation over single-donor sourcing.
- Recombinant Factor:Cell-culture derived proteins eliminate plasma collection dependency entirely. Baxter International and CSL Behring drive fastest expansion in US hemophilia treatment centers where extended half-life formulations displace plasma-derived prophylaxis.
- Fresh Frozen Plasma:Unfractionated source material requiring thawing before transfusion retains utility in rural facilities lacking cold-chain capacity for processed concentrates.
- Cryoprecipitate:Cold-precipitated fibrinogen-rich concentrate serves massive transfusion protocols and von Willebrand disease rescue therapy.
Volume placements concentrate in Cryoprecipitate; the faster expansion belongs to Recombinant Factor.
End User:
Procurement authority varies sharply across customer types, with consolidated blood banks wielding greater negotiating leverage than independent specialty clinics.
- Hospitals:Level I trauma centers and academic medical centers maintain 24-hour cryoprecipitate stockpiles for emergency fibrinogen replacement. Massive transfusion protocol activation drives consistent utilization independent of hemophilia caseload.
- Blood Banks:Regional collection centers like Blood Centers of America aggregate demand across multiple hospital systems. Centralized inventory management reduces per-unit logistics costs through pooled cold-chain infrastructure.
- Hematology Clinics:Dedicated coagulation disorder centers prioritize recombinant concentrates for routine prophylaxis.
- Specialty Clinics:Surgical and obstetric practices stock limited cryoprecipitate for perioperative bleeding management.
Procurement volume tilts toward Blood Banks; margin capture favors Hospitals through emergency markup structures.
Delivery Mode:
Route selection reflects the tension between rapid therapeutic effect and patient convenience in chronic versus acute care settings.
- Intravenous:Direct vascular administration achieves immediate factor VIII peak levels essential for hemorrhage control. Trauma centers and operating suites depend exclusively on this route for fibrinogen replacement.
- Subcutaneous:Recombinant emicizumab prophylaxis enables home administration, reducing clinic visit burden for hemophilia A patients. This delivery mode climbs fastest in pediatric and adolescent populations.
- Intramuscular:Limited applicability for cryoprecipitate due to fibrinogen precipitation risks; occasional use in desmopressin adjunct therapy.
- Oral:Not viable for cryoprecipitate or factor concentrates due to protein degradation in gastrointestinal tract; included for completeness in delivery taxonomy.
Clinical reliance centers on Intravenous administration; Subcutaneous delivery gains share fastest through recombinant prophylaxis expansion.
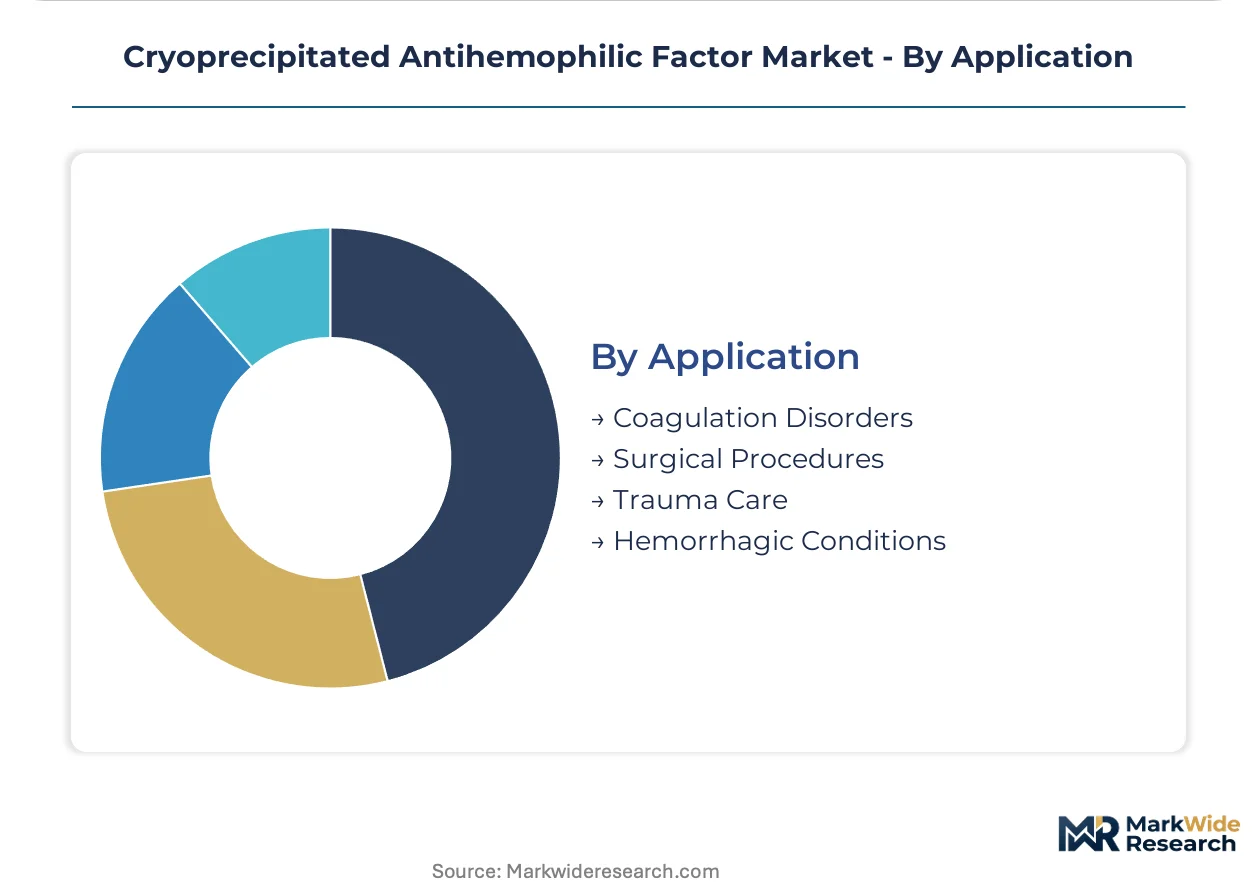
Application:
Disease-specific utilization patterns separate emergency replacement therapy from scheduled prophylactic administration.
- Coagulation Disorders:Hemophilia A and von Willebrand disease management consumes the majority of factor VIII concentrates. US patient registries track utilization patterns that inform national procurement forecasts.
- Surgical Procedures:Cardiac and orthopedic surgery protocols incorporate fibrinogen replacement for acquired coagulopathy. European surgical societies publish guidelines that preserve cryoprecipitate formulary placement.
- Trauma Care:Emergency department activation of massive transfusion protocols drives immediate cryoprecipitate consumption. This application segment shows steepest volume growth in US Level I trauma centers.
- Hemorrhagic Conditions:Obstetric hemorrhage and gastrointestinal bleeding represent secondary indications with sporadic demand.
Procurement scale favors Coagulation Disorders; Trauma Care demonstrates the most rapid volume acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hemophilia treatment centers drive the majority of cryoprecipitate procurement volume through patient registry tracking systems. Germany and Australia maintain significant fractionation capacity through vertically integrated plasma collectors. Japan and India represent contrasting demand profiles where recombinant penetration diverges sharply.
United States
Level I trauma centers and academic medical centers in Houston, Chicago, and Los Angeles maintain 24-hour cryoprecipitate stockpiles for massive transfusion protocols. FDA plasma collection standards and viral safety guidance sustain physician confidence in emergency settings. Blood Centers of America aggregates procurement across Midwest and Southeast rural hospital networks exceeding sixty percent of transfusion volume.
Germany
Solvent-detergent pathogen reduction technologies are modularizing manufacturing compliance for smaller fractionators in Frankfurt-Rhine-Main industrial clusters. EMA blood product guidelines and EU F-Gas Regulation shape cold-chain infrastructure investment decisions. Hospital blood banks in Bavaria and North Rhine-Westphalia are qualifying fewer suppliers with demonstrated viral safety validation.
Australia
Vertical control of fractionation capacity across Melbourne and Sydney facilities anchors regional supply stability for von Willebrand disease protocols. TGA alignment with FDA guidance accelerates post-collection pathogen reduction adoption. Blood service networks in New South Wales and Victoria are consolidating procurement toward integrated plasma collectors with captive collection infrastructure.
Japan
Extended half-life recombinant factor VIII and emicizumab prophylaxis are compressing routine cryoprecipitate utilization in Tokyo and Osaka hemophilia treatment centers. PMDA regulatory frameworks favor precision therapeutics over plasma-derived alternatives in chronic management. Osaka-based pharmaceutical clusters concentrate recombinant manufacturing investment away from fractionation-dependent supply models.
India
Rural hospital networks in Maharashtra and Karnataka lack recombinant cold-chain infrastructure, preserving cryoprecipitate relevance where plasma fractionation capacity exists. CDSCO oversight of blood product manufacturing consistency determines import access for domestic hospital formulary placement. Mumbai and Hyderabad medical centers balance cost constraints against viral safety requirements in procurement committee decisions.
Cryoprecipitated Antihemophilic Factor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated plasma collectors defending trauma and surgical niches against recombinant displacement. Three to four legacy fractionators concentrate technical expertise and regulatory validation capacity. Strategic moves center on backward integration into plasma collection networks and geographic expansion through regional blood bank partnerships.
Among integrated plasma collectors, Baxter International Inc, CSL Behring, and Grifols occupy positions exemplifying scale-driven supply stability archetypes. Baxter represents North American hospital chain consolidation through integrated collection networks. CSL Behring anchors Australian and US fractionation capacity. Grifols exemplifies European plasma sourcing dominance competing on volume scale against recombinant alternatives.
| Leading Market Players |
|---|
| Baxter International Inc |
| CSL Behring |
| Grifols |
| Bayer AG |
| Pfizer, Inc. |
| Takeda Pharmaceutical Co. Ltd. |
| Bio Products Laboratory Ltd. |
| Novo Nordisk A/S |
| Biogen |
| Others |
Value Network & Pricing Analysis
Plasma fractionation specialists concentrated in Melbourne and Frankfurt-Rhine-Main industrial clusters command wage premiums that translate directly into tiered pricing spreads between premium pathogen-reduced cryoprecipitate and standard cold-precipitated units. Labor-cost differentials between these specialized European and Australian facilities versus emerging-market contract manufacturers create the primary wedge separating premium-grade fibrinogen concentrates from economy-tier hospital formulary alternatives.
Pricing Analysis
Volume procurement through Blood Centers of America and consolidated European blood bank networks captures standard-tier margins, while emergency hospital markups in Level I trauma centers defend premium pricing for immediate fibrinogen replacement. Pricing stratifies across premium, standard, and economy tiers based on pathogen reduction certification grade and viral safety validation depth. Cost compression in the standard tier is intensifying because automated thawing systems and modular pathogen inactivation platforms reduce per-unit manufacturing overhead. Rural hospital networks in India and Southeast Asia exhibit highest price sensitivity due to limited reimbursement coverage, whereas academic medical centers in Houston and Chicago demonstrate lowest sensitivity given massive transfusion protocol activation requirements.
Supply Chain Analysis
FDA lot release certification and EMA blood product guideline compliance gate market access for fractionators lacking demonstrated viral safety validation, concentrating qualified supply among legacy CSL Behring, Grifols, and Baxter facilities in the United States, Germany, and Australia. Plasma collection networks in the United States, Austria, and the Czech Republic feed these fractionation hubs with source material subject to nucleic acid testing standards. Single-source vulnerability runs through the concentrated US plasma collection infrastructure that dominates global source material. Distribution runs through regional blood center networks that aggregate hospital demand and pool cold-chain logistics investment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where captive control over plasma collection infrastructure determines supply stability and pricing power across trauma and surgical niches. Players are pursuing backward integration into source plasma networks as the decisive upstream lever.
For Market Incumbents: Anchor trauma center formulary placement through 24-hour stockpile guarantees and massive transfusion protocol integration, while securing captive plasma collection capacity in United States and Austrian donor networks to defend against recombinant substitution. Recombinant factor VIII and emicizumab prophylaxis compression in hemophilia A represents the primary threat requiring defensive positioning in fibrinogen-focused surgical applications. For New Entrants and Emerging Players: Rural hospital networks in Maharashtra and Karnataka lacking recombinant cold-chain infrastructure present the most penetrable buyer archetype for economy-tier cryoprecipitate sourcing. Pathogen reduction technology licensing from German solvent-detergent platform providers offers the fastest regulatory qualification pathway without captive fractionation investment. For Investors and Strategic Acquirers: The window for entry favors contract fractionation specialists with demonstrated EMA and FDA viral safety validation but limited captive plasma collection. Long-term viability rests on securing integrated source material access before regional blood bank procurement consolidation completes. Monitor emicizumab prophylaxis penetration rates in pediatric hemophilia A populations as the signal indicating recombinant displacement acceleration versus cryoprecipitate resilience in emergency settings.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | Captive donor base in United States and Austria insulates against import dependency and geopolitical supply disruption. |
| Pathogen Reduction Technology Licensing | German solvent-detergent and riboflavin platforms enable smaller fractionators to meet FDA viral safety benchmarks. |
| Regional Blood Bank Partnership Consolidation | Direct contracts with Blood Centers of America bypass wholesaler markups in time-critical transfusion scenarios. |
| Fibrin Sealant Product Line Extension | Combination of cryoprecipitate-derived fibrinogen with thrombin opens surgical tissue adhesive applications. |
| Automated Thawing System Deployment | Australian and German hospital blood banks reduce per-unit handling labor and cold-chain compliance costs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plasma center operations directors, blood bank procurement managers, hospital transfusion service chiefs, and EMA regulatory affairs specialists. FDA guidance documents, EMA blood product guidelines, TGA submissions, and hospital formulary databases provided validation benchmarks. Bottom-up cryoprecipitate utilization tracking across United States patient registries combined with top-down plasma collection volume analysis from national blood service reports.
Data-stream reconciliation across product type, end user, delivery mode, and application dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segmented volume modeling against plasma supply sustainability assumptions and recombinant substitution curves. Modeled inputs included massive transfusion protocol activation frequencies in Level I trauma centers, von Willebrand disease rescue therapy incidence, and rural hospital cold-chain infrastructure penetration rates.
Revisions become necessary when recombinant factor VIII half-life extension accelerates beyond modeled substitution curves, or when FDA plasma collection standards tighten donor eligibility criteria. Forecasts reflect documented assumptions regarding viral safety validation timelines and regional blood bank procurement consolidation velocity. A model refresh is warranted upon material change in emicizumab prophylaxis reimbursement coverage or EU F-Gas Regulation cold-chain compliance cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Calcium Channel Blocker Market
Pharmaceuticals
US Generic Injectables Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Recombinant Plasma Protein Therapeutics Market
Pharmaceuticals
Sporanox Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Antibodies Market
Pharmaceuticals
Czech Republic Pharmaceutical Market
Pharmaceuticals
Ginkgo Leaf Extract and Dipyridamole Injection Market
Pharmaceuticals
Targeted Therapeutics Market
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Global Female Contraceptive Market
Pharmaceuticals
Non-Steroidal Anti-Inflammatory API Market
Pharmaceuticals
Asia Pacific Multiple Sclerosis Drugs Market
Pharmaceuticals
Male Hypogonadism Market
Pharmaceuticals
US Over the Counter Drugs Market
Pharmaceuticals
Migraine Nasal Spray Market
Pharmaceuticals
Anticancer Drugs Market