
 Acellular Dermal Matrix Market | 2026-2036
Acellular Dermal Matrix Market Size, Share, and Industry Trends Forecast 2026-2036
Acellular Dermal Matrix Market Insights
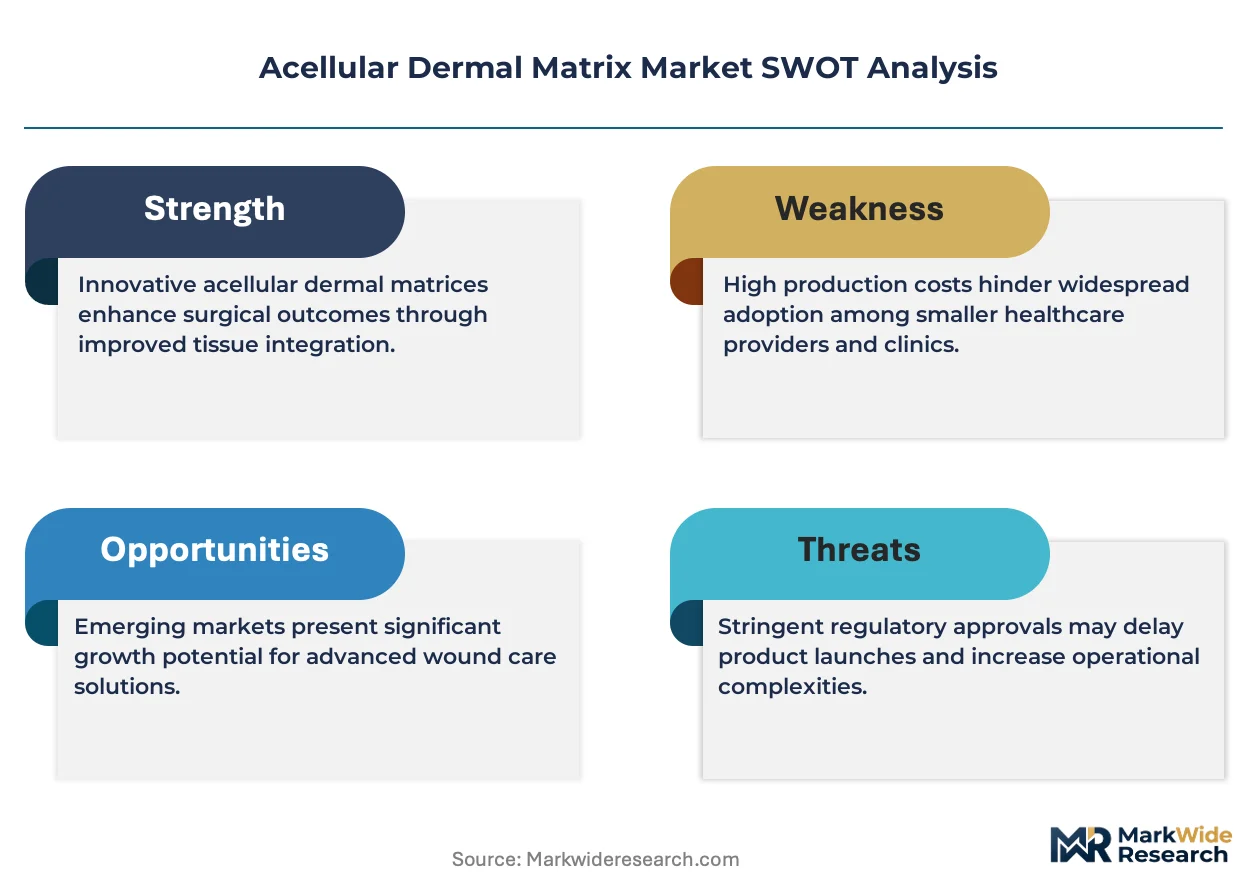
Decellularization technology is fragmenting into multiple proprietary platforms that reshape how manufacturers process donor tissue and synthetic scaffolds. Integra LifeSciences Corporation leverages its MatriStem portfolio to anchor positions in surgical reconstruction and wound healing segments. AbbVie Inc. sustains competitive presence through Alloderm's established brand strength in plastic and reconstructive surgery applications. Johnson & Johnson competes across burn treatment and hernia repair channels with SurgiMend and similar biologic mesh offerings.
An acellular dermal matrix comprises human, porcine, or bovine dermis stripped of cellular components via chemical, enzymatic, or physical decellularization, leaving an intact collagen-elastin scaffold that supports host cell infiltration and vascularization. The material serves primarily as a biologic implant for soft tissue reinforcement, wound coverage, and dermal regeneration in procedures ranging from breast reconstruction to diabetic ulcer management. Human-derived ADM products occupy mature, premium-priced positions in complex reconstructive cases where immunogenicity concerns constrain synthetic alternatives. Synthetic and polymer-based segments are capturing faster growth in ambulatory surgical settings where off-the-shelf availability and reduced disease transmission risk appeal to cost-conscious buyers. Collagen-based formulations concentrate margin pools among specialized manufacturers with vertically controlled tissue procurement networks.
FDA 510(k) clearance requirements and the agency's evolving guidance on human cells, tissues, and cellular and tissue-based products (HCT/Ps) shape product development timelines and clinical evidence standards for market access. EMA's Medical Device Regulation (MDR) and ISO 13485 quality management frameworks impose additional compliance burdens on manufacturers seeking European commercialization. Health Canada and Australia's TGA maintain parallel but distinct biologic device classification systems that fragment regulatory strategy for multinational suppliers. Stakeholders must monitor how CMS and private payer coverage determinations for bioengineered skin substitutes evolve alongside comparative effectiveness data requirements.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships for ADM grafts around suppliers with vertically controlled tissue networks, compressing contract cycles and forcing mid-tier manufacturers to demonstrate superior clinical evidence or exit the reconstructive surgery supply chain.
Growth Catalysts
- Medicare reimbursement expansion:CMS coverage determinations for bioengineered skin substitutes in diabetic ulcer management are pulling ADM products into outpatient wound care centers across the United States.
- Decellularization platform maturation:Enzymatic processing methods are reducing immunogenicity profiles in porcine-derived matrices, opening adoption in pediatric burn reconstruction previously restricted to human allografts.
- Breast reconstruction volume:Post-mastectomy implant-based procedures using ADM for tissue support are concentrating demand in academic medical center oncology units with integrated plastic surgery departments.
Market Restraints
- Donor tissue scarcity:Human-derived ADM production depends on finite cadaveric skin supply from US tissue banks, creating batch-to-batch availability constraints.
- EMA MDR compliance costs:European Medical Device Regulation technical documentation requirements for biologic implants are extending time-to-market by 18-24 months for non-CE-marked manufacturers.
- Synthetic mesh substitution:Polypropylene and polyester alternatives in hernia repair are capturing price-sensitive cases where biologic integration speed is clinically non-critical.
Strategic Opportunities
- Ambulatory surgery center penetration:Same-day hernia and breast reconstruction protocols in US outpatient facilities are creating demand for off-the-shelf ADM formats with simplified hydration requirements.
- Japan PMDA pathway:Accelerated review tracks for regenerative medicine products are enabling first-mover positioning in Asia-Pacific's highest-value reconstructive surgery market.
- 3D bioprinting convergence:Integration of patient-specific digital imaging with collagen scaffold deposition is enabling custom ADM geometries for complex facial trauma reconstruction.
Industry Challenges
- Decellularization technician shortage:Specialized biochemistry expertise for tissue processing is concentrating among a limited pool of US-based manufacturing facilities.
- FDA 510(k) clinical data requirements:Evolving standards for human cells and tissue-based products are forcing manufacturers to fund prospective trials for clearance renewals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acellular Dermal Matrix Market |
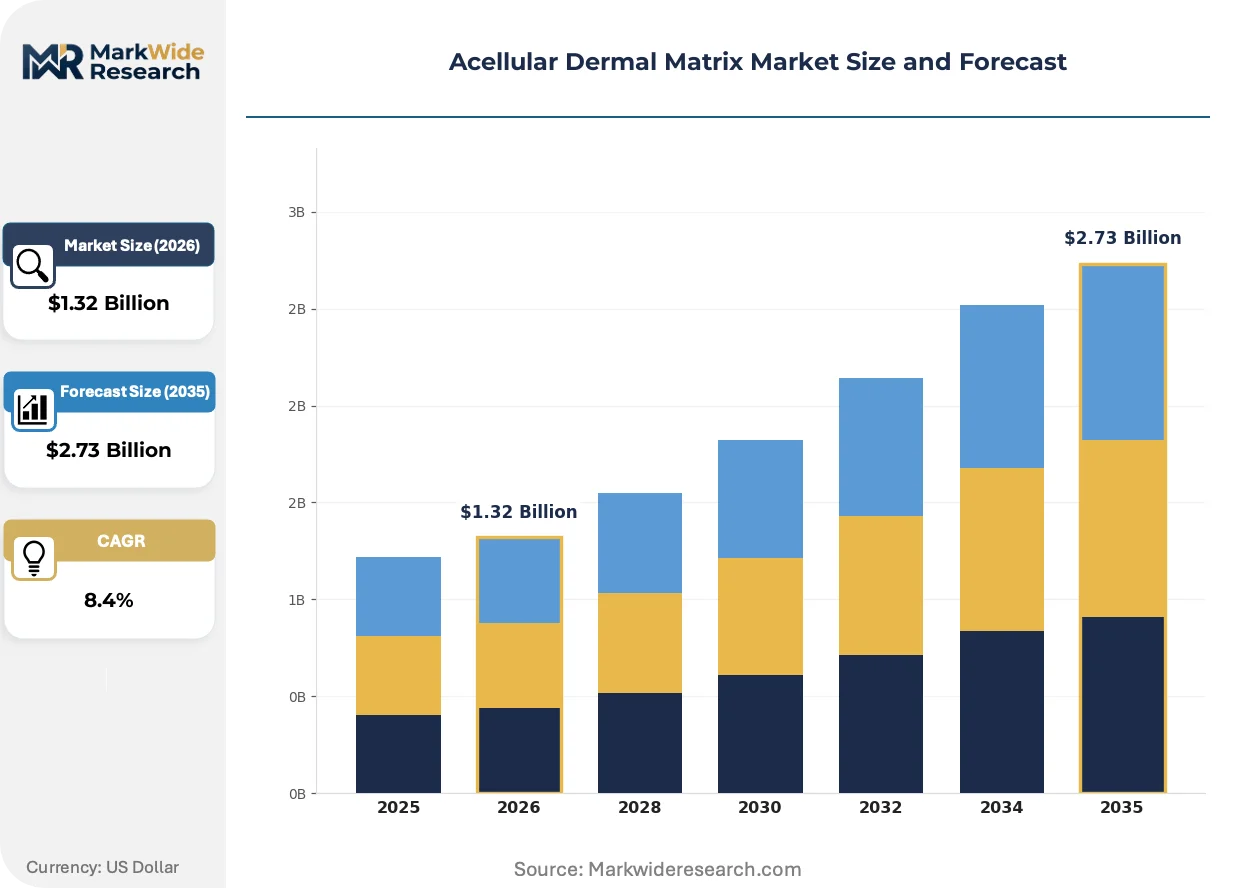
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.73 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Human-Derived, Synthetic, Collagen-Based, Polymer-Based End User: Hospitals, Ambulatory Surgical Centers, Clinical Laboratories, Healthcare Facilities Application: Burn Treatment, Surgical Reconstruction, Wound Healing, Cosmetic Procedures Distribution Channel: Online Retail, Direct Sales, Medical Supply Distributors, Wholesalers |
| Companies Covered | Integra LifeSciences Corporation, AbbVie Inc., Johnson & Johnson, Smith & Nephew Plc., Zimmer Biomet Holdings, Organogenesis Holdings Inc., Tissue Regenix, LifeNet Health, AlloSource, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acellular Dermal Matrix Market Trends and Innovations
Processing technology and procurement models are diverging simultaneously, with automation in tissue decellularization colliding against hospital buying committees demanding outcome guarantees rather than unit pricing.
Lyophilized ADM formats are migrating from academic burn centers into community hospital wound clinics. Off-the-shelf shelf stability eliminates frozen storage infrastructure, enabling adoption by facilities without specialized tissue banking capabilities. This migration is compressing the addressable market for traditional cryopreserved products to complex reconstructive cases requiring maximal scaffold integrity.
EMA's Medical Device Regulation is tightening clinical evidence standards for biologic mesh classifications. Manufacturers must now submit post-market surveillance data for hernia repair indications, raising documentation burdens. European distributors are responding by consolidating supplier portfolios around firms with dedicated regulatory affairs teams in Brussels.
Hospital value analysis committees are unbundling ADM procurement from surgical kit contracts. Separate line-item negotiation for biologic implants is displacing bundled pricing in US health systems above 500 beds. This behavioral shift concentrates purchasing power among supply chain executives and compresses vendor margins in the Southeast and Midwest hospital networks.
Acellular Dermal Matrix Market Segmentation
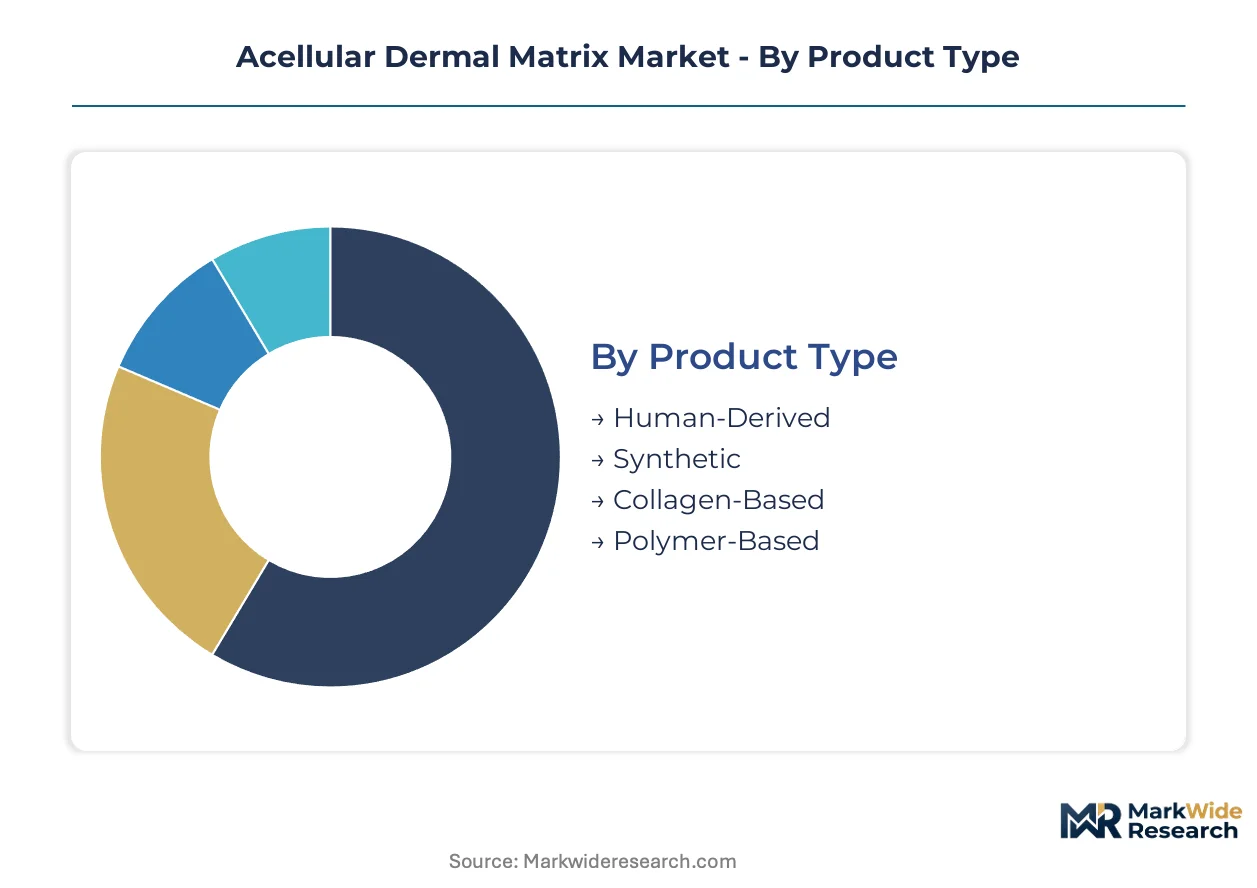
ADM market segmentation reveals how processing methods, clinical settings, and procurement channels fragment commercial opportunity. Manufacturers must align product formats with specific reimbursement pathways and facility infrastructure capabilities.
Product Type:
Mature allograft technologies coexist with emerging synthetic platforms, creating a bifurcated supply landscape where biological fidelity competes against manufacturing scalability.
- Human-Derived:Cadaveric dermis processed through proprietary decellularization protocols retains native collagen architecture and elastin networks. Academic medical centers in the United States prioritize these matrices for complex breast reconstruction and pediatric burn cases where immunogenicity tolerance is narrowest.
- Synthetic:Polymer scaffolds manufactured from biodegradable polyesters offer batch-to-batch consistency and eliminate infectious disease transmission risks. Ambulatory surgical centers are standardizing these products for hernia repair protocols where rapid deployment outweighs integration speed requirements.
- Collagen-Based:Purified bovine or porcine collagen matrices processed through enzymatic extraction serve mid-tier reconstructive applications.
- Polymer-Based:Engineered synthetic matrices with tunable degradation profiles target cost-sensitive wound care segments.
Human-Derived retains volume leadership; Synthetic holds the steepest expansion curve.
End User:
Facility infrastructure and reimbursement sophistication determine product format selection across the care continuum.
- Hospitals:Integrated health systems with dedicated tissue banks manage cryopreserved allografts for complex reconstructive surgery. Medicare reimbursement for bioengineered skin substitutes in burn units and oncology departments sustains premium product utilization at these facilities.
- Ambulatory Surgical Centers:Same-day discharge protocols favor lyophilized ADM formats with room-temperature stability and simplified hydration workflows. CMS facility fee structures for outpatient hernia and breast reconstruction are accelerating product adoption in this channel.
- Clinical Laboratories:Specialized reference labs process ADM biopsies for integration assessment and vascularization monitoring.
- Healthcare Facilities:Skilled nursing facilities and long-term acute care hospitals deploy ADM for chronic wound management.
Hospitals command the largest revenue share; Ambulatory Surgical Centers are climbing the fastest.
Application:
Clinical indication drives scaffold specification, with load-bearing requirements and vascularization timelines dictating material selection.
- Burn Treatment:Full-thickness thermal injuries require immediate temporary wound coverage with matrices that support autologous cell migration. Shriners Hospitals for Children and regional burn centers in the United States specify human-derived ADM for pediatric cases where donor site morbidity must be minimized.
- Surgical Reconstruction:Post-mastectomy implant-based breast reconstruction consumes substantial ADM volume for tissue expander support and pocket reinforcement. Plastic surgery departments at MD Anderson Cancer Center and similar institutions standardize ADM use in oncoplastic protocols.
- Wound Healing:Diabetic foot ulcers and venous leg ulcers represent addressable volume for bioengineered skin substitutes.
- Cosmetic Procedures:Aesthetic surgery applications including rhinoplasty and facial rejuvenation utilize smaller-format ADM sheets.
Surgical Reconstruction retains volume leadership; Burn Treatment holds the steepest expansion curve.
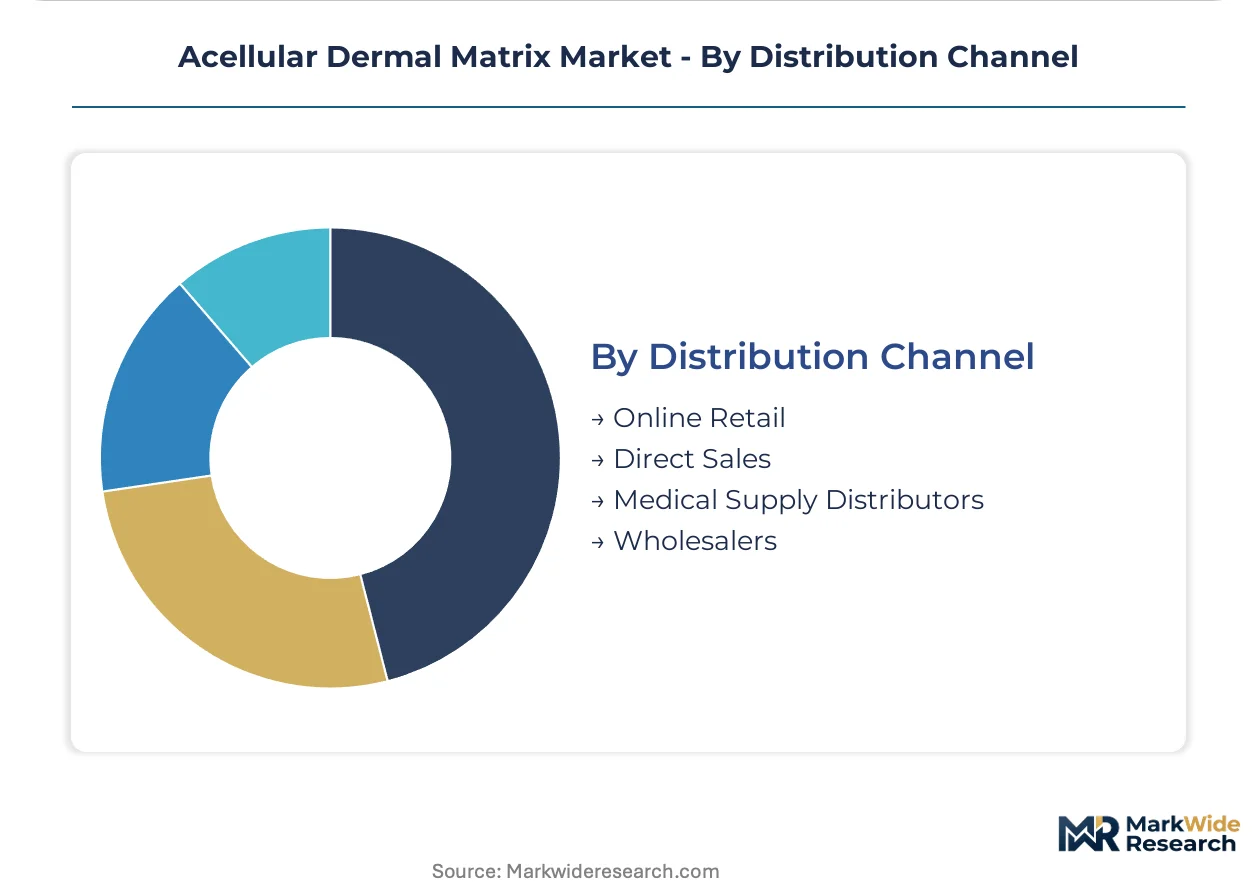
Distribution Channel:
Procurement centralization is reshaping how ADM products reach clinical end-users, with health system consolidation favoring direct manufacturer relationships over traditional distribution.
- Direct Sales:Manufacturer field representatives negotiate directly with hospital value analysis committees and supply chain executives. Premier and Vizient group purchasing organizations are consolidating ADM contracts around suppliers with dedicated clinical support teams.
- Medical Supply Distributors:Cardinal Health and McKesson maintain regional inventory positions for same-day delivery to surgical suites. These distributors handle logistics for mid-tier hospitals without specialized tissue banking infrastructure.
- Online Retail:E-commerce platforms serve outpatient wound care clinics and smaller practices with low-volume ADM requirements.
- Wholesalers:Regional medical product wholesalers stock standard ADM formats for emergency procurement scenarios.
Direct Sales retains volume leadership; Online Retail holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States concentrate purchasing power for acellular dermal matrix products, while ambulatory surgical centers in Germany and Japan accelerate adoption of lyophilized formats for same-day procedures.
United States
Medicare reimbursement policies for bioengineered skin substitutes drive clinical adoption at academic medical centers and burn units. FDA 510(k) clearance pathways streamline market entry for human-derived tissue products. The Texas Medical Center in Houston anchors complex reconstructive surgery volume, with MD Anderson Cancer Center standardizing ADM use in post-mastectomy protocols.
Germany
EMA Medical Device Regulation compliance costs extend time-to-market for biologic mesh manufacturers seeking CE marking. German hospital networks consolidate vendor relationships around suppliers with dedicated regulatory affairs teams in Brussels. The Rhine-Ruhr metropolitan region concentrates procurement decision-making for ADM grafts across integrated health systems.
Japan
PMDA accelerated review tracks for regenerative medicine products enable first-mover positioning in Asia-Pacific's highest-value reconstructive surgery market. METI industrial policy supports domestic tissue engineering capabilities. Tokyo's Keiyō Industrial Zone hosts specialized biochemistry facilities for enzymatic decellularization processing.
United Kingdom
NHS England coverage determinations for complex wound management pull ADM products into regional burn centers and plastic surgery departments. MHRA post-Brexit regulatory autonomy creates parallel but distinct biologic device classification requirements. The Oxford-Cambridge arc concentrates research activity in collagen scaffold engineering and 3D bioprinting convergence.
Australia
TGA biologic device frameworks maintain distinct classification systems that fragment regulatory strategy for multinational suppliers. Private health insurance reimbursement for breast reconstruction sustains premium product utilization. Melbourne's Parkville biomedical precinct anchors clinical trial activity for porcine-derived matrix immunogenicity assessment.
Acellular Dermal Matrix Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hospital procurement and ambulatory surgical center segments. The vendor base concentrates among diversified medical technology conglomerates with established tissue banking networks and mid-tier manufacturers with proprietary decellularization platforms. Three strategic archetypes dominate: vertically integrated tissue processors, synthetic scaffold specialists, and regional distributors with clinical support capabilities. M&A activity targets specialized biochemistry expertise, while capacity expansion focuses on lyophilized production lines for outpatient formats.
Within the diversified medical technology tier, Integra LifeSciences Corporation and Johnson & Johnson occupy positions spanning surgical reconstruction and wound healing segments. AbbVie Inc. exemplifies brand-driven positioning in plastic and reconstructive surgery applications through established allograft portfolios. Smith & Nephew Plc. and Zimmer Biomet Holdings represent orthopedic and trauma-focused competitors with biologic mesh offerings. Organogenesis Holdings Inc., LifeNet Health, and AlloSource anchor the specialized tissue processor archetype with vertically controlled donor networks. Tissue Regenix and AlloSource exemplify mid-tier manufacturers competing on clinical evidence generation for specific indications.
| Leading Market Players |
|---|
| Integra LifeSciences Corporation |
| AbbVie Inc. |
| Johnson & Johnson |
| Smith & Nephew Plc. |
| Zimmer Biomet Holdings |
| Organogenesis Holdings Inc. |
| Tissue Regenix |
| LifeNet Health |
| AlloSource |
| Others |
Pricing and Supply Chain Analysis
Memphis-based cold-chain logistics corridors connecting US tissue banks to academic medical centers impose freight premiums that compound donor scarcity costs, concentrating pricing power among manufacturers with captive procurement networks while forcing smaller suppliers toward synthetic scaffold alternatives.
Pricing Analysis
Cost-plus contracts indexed to cadaveric tissue recovery fees dominate human-derived ADM procurement, with hospital GPOs negotiating three-tier pricing structures across premium cryopreserved, standard lyophilized, and economy synthetic formats. Price differentiation hinges on FDA 510(k) clearance tier and vertical integration depth in tissue banking. Pricing pressure stems from Medicare reimbursement compression for outpatient wound care, squeezing mid-tier suppliers. Ambulatory surgical centers exhibit highest price sensitivity; academic burn units demonstrate lowest sensitivity due to clinical outcome guarantees.
Supply Chain Analysis
US Commerce Department export controls on decellularization enzyme technologies limit processing equipment flows to unlicensed foreign facilities, tethering advanced ADM production to domestic manufacturing clusters. Supply concentrates in the United States, Germany, and Japan. Raw material dependencies include cadaveric dermis, porcine collagen, and recombinant growth factors. Single-source vulnerability characterizes enzymatic reagent supply. Distribution runs through manufacturer field representatives negotiating directly with hospital value analysis committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ADM procurement is shifting toward service-attach models where clinical support teams and reimbursement navigation services expand faster than graft unit sales, rewarding vendors who bundle outcome guarantees with hardware supply.
For Market Incumbents: Harden regulatory moats by accelerating FDA 510(k) renewal investments ahead of evolving HCT/P guidance, while deepening backward integration into tissue banking to defend against synthetic substitution in hernia repair. Consolidate vendor relationships with Premier and Vizient GPOs before mid-tier competitors generate comparable clinical evidence.
For New Entrants and Emerging Players: Lyophilized ADM formats for Japanese ambulatory surgical centers represent the most penetrable entry point, given PMDA accelerated review tracks and METI industrial policy support. Target US outpatient wound care clinics underserved by cryopreserved product logistics. Lead with simplified hydration workflows and room-temperature stability claims.
For Investors and Strategic Acquirers: Specialized biochemistry facilities with proprietary enzymatic decellularization platforms command scarcity premiums in a market where technician expertise concentrates among limited US manufacturing sites. Long-term viability rests on convergence with 3D bioprinting capabilities and regenerative medicine reimbursement expansion. Monitor CMS coverage determinations for diabetic ulcer management as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Streamlined HCT/P clearance reduces time-to-market for human-derived matrices against synthetic competitors. |
| CE Marking Under MDR | EMA technical documentation requirements extend European commercialization timelines for biologic mesh manufacturers. |
| Hospital System Partnership | Direct contracts with MD Anderson and Texas Medical Center anchor volume in post-mastectomy reconstruction. |
| Software Companion Development | Digital imaging integration enables patient-specific ADM geometries for complex facial trauma applications. |
| Reimbursement Strategy | CMS coverage expansion for bioengineered skin substitutes pulls ADM into outpatient wound care centers. |
Research Methodology
A standing panel of hospital procurement executives, plastic surgery department heads, tissue bank operations managers, and biomedical engineers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital GPO contract repositories, and EMA MDR technical documentation. Bottom-up graft volume modeling triangulated against top-down market sizing from manufacturer revenue disclosures.
Scenario-bracketing anchored projections across conservative, baseline, and expansion cases throughout the forecast period. Segmentation dimensions modeled include product type, end-user facility tier, clinical application, and regional regulatory cluster. CAGRs derived from graft unit trajectory analysis and average selling price evolution. Industry-specific inputs incorporated Medicare reimbursement rate assumptions and PMDA review timeline probabilities.
Practitioners should monitor FDA guidance evolution on HCT/P clinical data requirements and CMS national coverage determinations for early signals of forecast revision. Forecasts reflect assumptions around tissue bank supply stability and enzymatic processing cost curves. Material shifts in cadaveric donor availability or EMA MDR enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neuro Medical Devices Market
Medical Devices
Global Radiofrequency Ablation Devices Market
Medical Devices
Global Occlusion Devices Market
Medical Devices
Global Hysteroscope Market
Medical Devices
Colposcopes Market
Medical Devices
Infusion Management Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
Radial Head Resection Implant Market
Medical Devices
Europe Foot Orthotic Insoles Market
Medical Devices
Global Ureteral Stent Market
Medical Devices
PPG Biosensors Market
Medical Devices
Creatinine Meter Market
Medical Devices
Global Live Cell Encapsulation Market
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
US Electrosurgical Generators Market
Medical Devices
Laparoscopic Electrodes Market