
 Asia-Pacific Single-Use Medical Device Reprocessing Market | 2026-2036
Asia-Pacific Single-Use Medical Device Reprocessing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Single-Use Medical Device Reprocessing Market Outlook
India's sterilization infrastructure build-out is narrowing the gap between fragmented local reprocessors and accredited centralized facilities. Stryker Corporation sustains technology leadership through proprietary cleaning validation systems for complex catheter geometries. Johnson & Johnson leverages its hospital supply relationships to position reprocessing services within bundled procurement contracts. Medline Industries competes on manufacturing scale, operating regional sterilization hubs that reduce turnaround times for high-volume surgical drapes and infusion sets.
Single-use medical device reprocessing encompasses the collection, cleaning, functional testing, sterilization, and redistribution of devices originally labeled for one-time use, with validated processes typically achieving sterility assurance levels of 10^-6 through ethylene oxide or radiation modalities. The practice primarily reduces per-procedure supply costs while diverting polymer waste from incineration streams. Catheters and electrosurgical devices command the deepest reprocessing penetration due to their higher original equipment costs and established validation protocols, whereas surgical drapes see thinner margins concentrated in high-throughput central sterile supply departments. Hospitals remain the dominant end-user channel, though ambulatory surgical centers represent the fastest-expanding segment as outpatient procedure volumes shift away from inpatient settings across the region.
India's CDSCO, Australia's TGA, and South Korea's MFDS each enforce distinct sterility validation and labeling requirements that fragment compliance costs across national boundaries. India's PLI scheme for domestic medical device manufacturing indirectly pressures reprocessors to demonstrate equivalent quality outcomes against newly subsidized domestic production. Stakeholders must monitor divergence between national reprocessing approval pathways and harmonized ISO 13485 quality management expectations, as regulatory misalignment threatens to trap capital in country-specific compliance infrastructure without transferable scale.
Market Dynamics
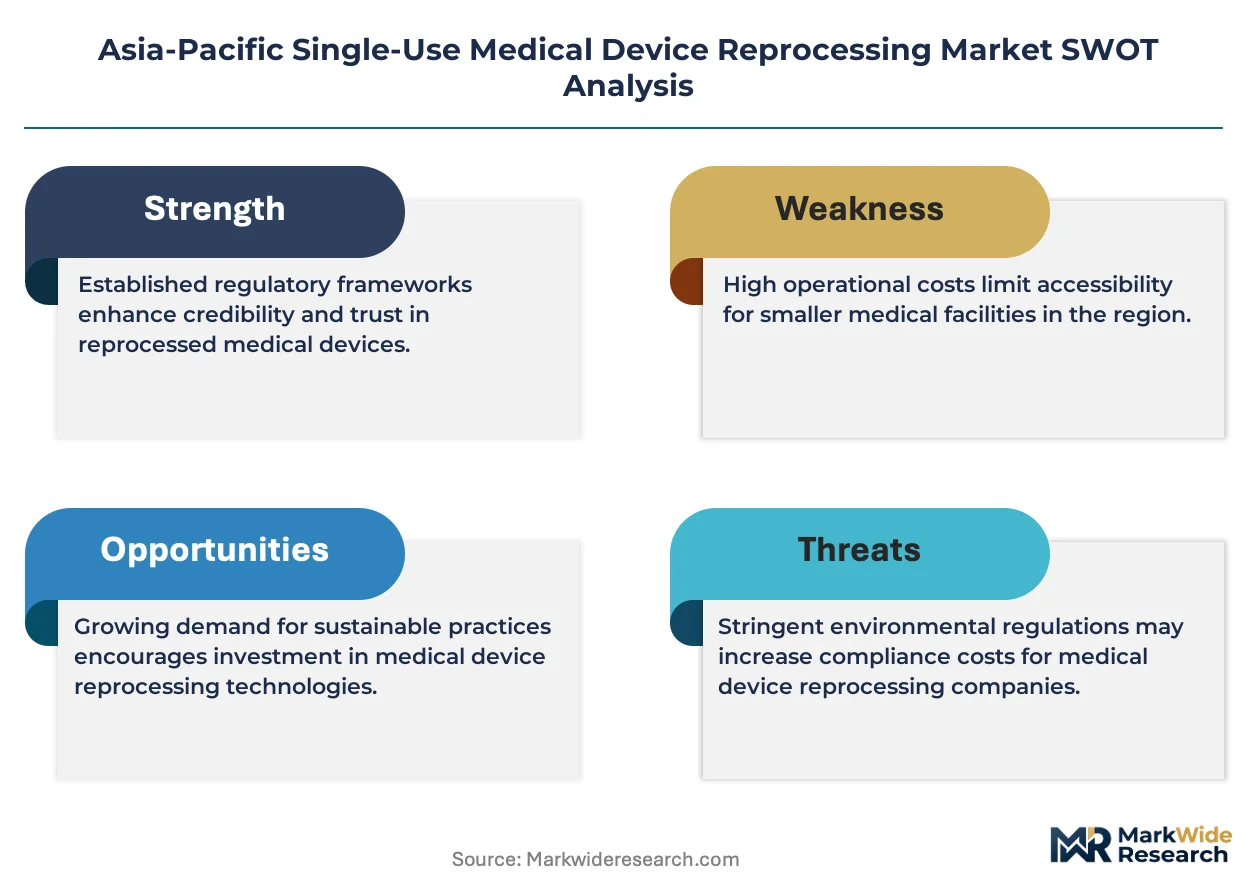
Hospital procurement departments across Southeast Asia are consolidating vendor relationships to reduce per-procedure supply expenditures, compressing margins for reprocessors that lack validated sterilization infrastructure or CDSCO-equivalent accreditation pathways.
Growth Catalysts
- CDSCO quality guidelines:India's tightened sterility validation requirements push tier-1 hospitals toward accredited third-party processors, filtering out informal local operators and concentrating volume with validated facilities.
- Public health network mandates:Australia's state-level cost-containment directives in Victoria and New South Wales embed reprocessing quotas within hospital procurement frameworks, institutionalizing demand for catheter and electrosurgical device reprocessing.
- Ethylene oxide sterilization:Regional hub operators are deploying automated EtO systems with parametric release capabilities, reducing turnaround cycles and enabling same-day redistribution for high-throughput surgical drapes.
Market Restraints
- Polymer feedstock volatility:Fluctuating virgin polymer prices from Southeast Asian petrochemical suppliers compress reprocessing margins when original equipment manufacturers slash single-use device prices.
- Regulatory fragmentation:Divergent sterility assurance documentation requirements between India's CDSCO, Australia's TGA, and South Korea's MFDS trap compliance capital in non-transferable national infrastructure.
- Gamma irradiation capacity concentration:Sterilization cobalt-60 supply chains concentrate through two regional contract irradiators, creating single-point vulnerability for radiation-dependent reprocessors.
Strategic Opportunities
- Ambulatory surgical centers:Outpatient procedure volume migration in Thailand and Malaysia creates unmet demand for rapid-turnaround reprocessing services outside hospital central sterile supply departments.
- PLI scheme quality equivalence:India's production-linked incentive subsidies for domestic device manufacturing create opening for reprocessors to demonstrate ISO 13485 outcomes against subsidized virgin equipment.
- RFID-tracked device lifecycle management:Convergence of sterilization validation protocols with wireless inventory tracking enables outcome-based service contracts linking reprocessor fees to functional device performance metrics.
Industry Challenges
- Bioburden assessment expertise:Facilities struggle to recruit microbiologists capable of validating cleaning efficacy for complex catheter lumens against ISO 17664 standards.
- Legacy sterilizer integration:Retrofitting existing ethylene oxide chambers with parametric release monitoring systems demands capital outlays that mid-scale reprocessors cannot amortize across thin-margin drape volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Single-Use Medical Device Reprocessing Market |
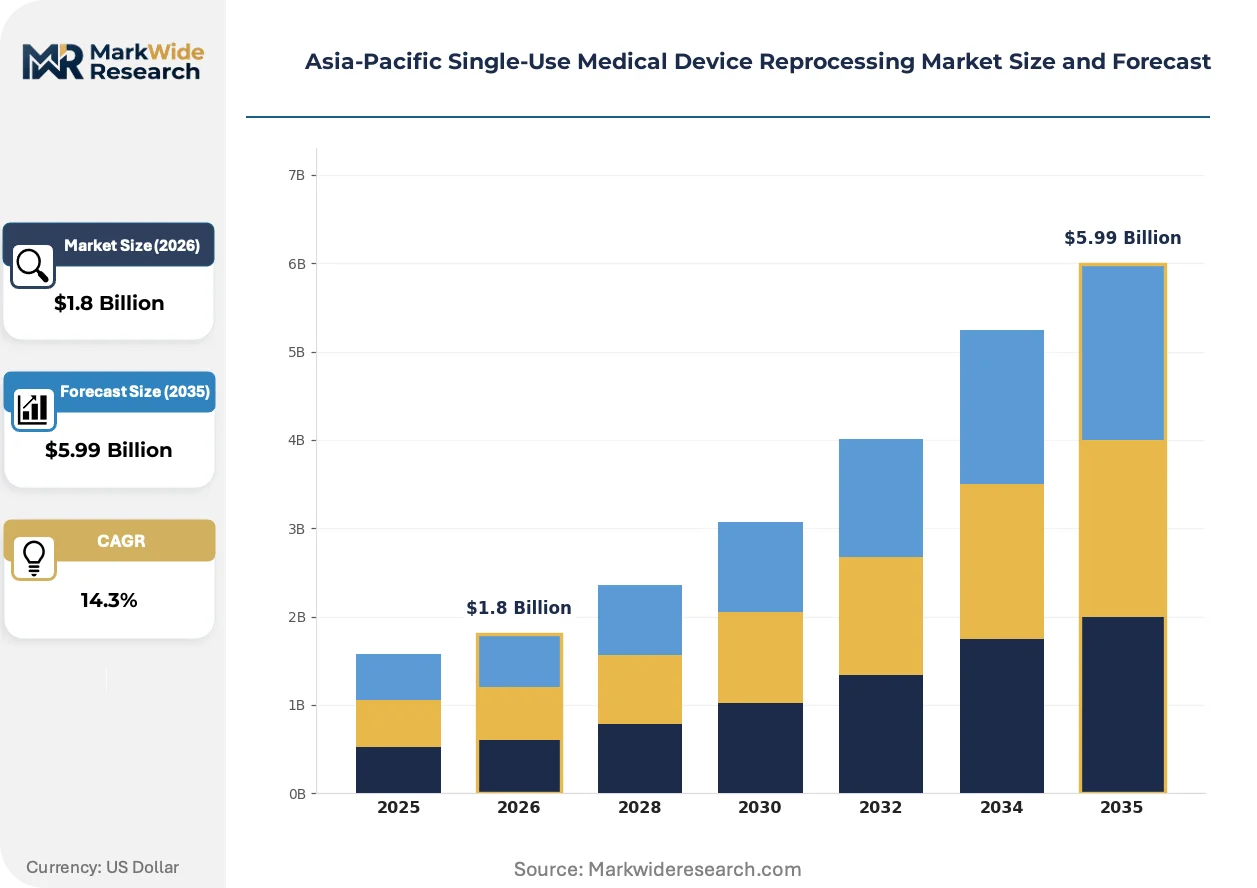
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.99 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Surgical Drapes, Infusion Sets, Electrosurgical Devices End User: Hospitals, Ambulatory Surgical Centers, Home Care, Clinics Technology: Ethylene Oxide Sterilization, Steam Sterilization, Radiation Sterilization, Plasma Sterilization Application: Cardiovascular, Orthopedic, General Surgery, Neurology |
| Companies Covered | Medline Industries, Stryker Corporation, Johnson & Johnson, NEScientific, ReNu Medical, Sterilmed, Arjo, Soma Technology, Centurion Medical Products Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Single-Use Medical Device Reprocessing Market Strategic Shifts
Reprocessing technology is migrating toward automated cleaning validation systems that reduce human intervention in bioburden assessment, while regulatory convergence pressures and ambulatory demand expansion reshape competitive requirements across the Asia-Pacific region.
Automated luminal cleaning systems utilizing pressure-pulse fluid dynamics and fluorescence-based residue detection are migrating from research hospital pilot programs to commercial third-party reprocessing facilities. Australian public health networks and Indian tier-1 hospital clusters are adopting these systems fastest, driven by CDSCO documentation requirements for catheter reprocessing. The technology is migrating from manual brush-and-flush protocols toward closed-loop validated cycles that compress labor costs while tightening sterility assurance documentation.
Australia's TGA is harmonizing its reprocessing guidance with ISO 14155 clinical investigation standards, requiring third-party processors to submit device-specific validation data rather than generic sterilization certificates. This regulatory tightening elevates compliance costs for smaller regional operators while creating competitive moats for facilities with in-house microbiology laboratories. Catheter reprocessing segments face the steepest documentation burden, with TGA auditors demanding functional testing records for each device lot rather than sampling-based release.
Hospital supply chain managers are unbundling reprocessing services from bundled procurement contracts with original equipment manufacturers, negotiating direct relationships with specialized third-party sterilization providers. This disintermediation is most visible in India's Maharashtra and Karnataka state hospital networks, where procurement officers cite PLI-subsidized domestic device pricing as leverage to extract volume discounts from reprocessors. The shift compresses margins for reprocessors dependent on manufacturer-channel referrals while rewarding direct-sales capabilities and rapid-turnaround logistics infrastructure.
Asia-Pacific Single-Use Medical Device Reprocessing Market Segmentation
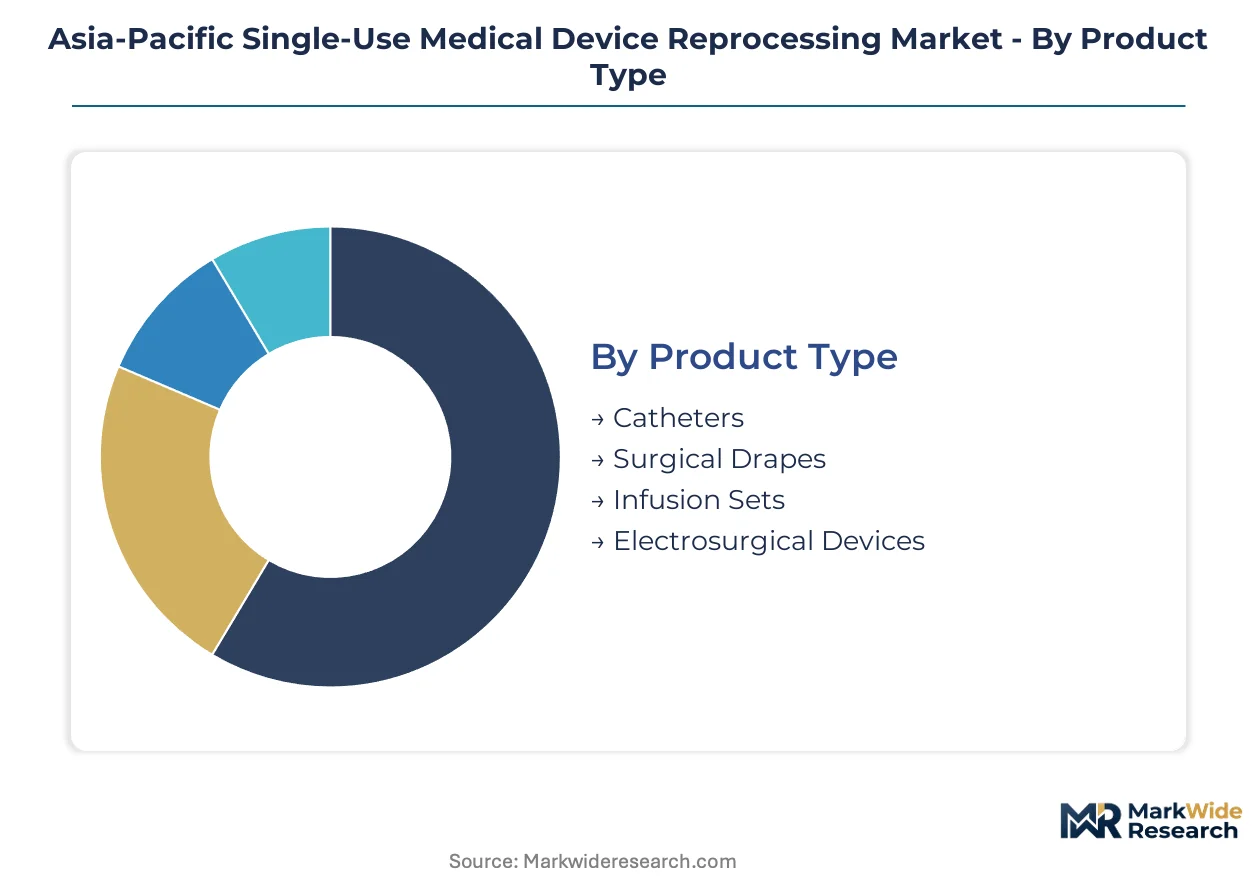
Segmentation in Asia-Pacific single-use medical device reprocessing reveals distinct service intensity requirements across product categories. Catheter geometries demand validated luminal cleaning protocols with documented bioburden assessment, while surgical drapes prioritize throughput velocity over technical complexity. Understanding these divergent service models enables processors to allocate sterilization capacity and technical labor appropriately.
Product Type:
After-sales service intensity varies dramatically across device categories, with complex geometries requiring sustained technical support and simpler items demanding logistics excellence.
- Catheters:Multi-lumen designs with tortuous pathways require automated pressure-pulse cleaning systems and fluorescence-based residue detection. Demand concentrates in India's tier-1 cardiac catheterization labs and Australian public hospital interventional suites, where CDSCO and TGA documentation requirements for functional testing drive preference toward accredited third-party processors with in-house microbiology capabilities.
- Electrosurgical Devices:Handpieces and electrodes with insulated components need dielectric testing post-sterilization to ensure patient safety. Australian state health networks in Victoria and New South Wales embed these devices within mandated reprocessing quotas, institutionalizing volume flows toward centralized sterilization hubs with rapid-turnaround logistics.
- Surgical Drapes:High-throughput polymer barriers with minimal functional complexity.
- Infusion Sets:Tubing assemblies requiring validated sealing integrity checks.
Catheters hold the largest share; momentum sits with electrosurgical devices as Australian procurement mandates deepen penetration.
End User:
Customer type determines service configuration, with inpatient facilities requiring integrated supply chain solutions and outpatient settings prioritizing rapid turnaround.
- Hospitals:Central sterile supply departments with established ethylene oxide infrastructure anchor regional reprocessing volume. Maharashtra and Karnataka state networks in India leverage PLI-subsidized domestic device pricing as negotiation leverage against reprocessor margins, while maintaining demand concentration through accreditation requirements.
- Ambulatory Surgical Centers:Thailand and Malaysia outpatient facilities lack captive sterilization capacity, creating demand for third-party collection-and-redistribution services with same-day turnaround. These centers represent the steepest expansion trajectory as procedure volumes migrate from inpatient settings.
- Clinics:Lower-volume settings with intermittent sterilization needs.
- Home Care:Minimal reprocessing penetration due to regulatory complexity and infection control liability.
Hospitals dominate current volume; ambulatory surgical centers are climbing the fastest as regional outpatient infrastructure expands.
Technology:
Sterilization modality selection hinges on material compatibility, throughput requirements, and national regulatory documentation standards.
- Ethylene Oxide Sterilization:Automated EtO systems with parametric release capabilities enable same-day redistribution for high-throughput surgical drapes. Southeast Asian hub operators deploy these systems to compress turnaround cycles and capture ambulatory surgical center demand.
- Radiation Sterilization:Gamma irradiation dependent on concentrated cobalt-60 supply chains through two regional contract irradiators, creating single-point vulnerability for radiation-dependent reprocessors serving catheter and electrosurgical device segments.
- Steam Sterilization:Limited applicability for heat-sensitive polymers.
- Plasma Sterilization:Emerging adoption for temperature-sensitive device categories.
Ethylene oxide sterilization commands the largest installed base; plasma sterilization is gaining share fastest as material diversity expands.
Application:
Clinical application dictates device complexity, usage volume, and reimbursement environment shaping reprocessing economics.
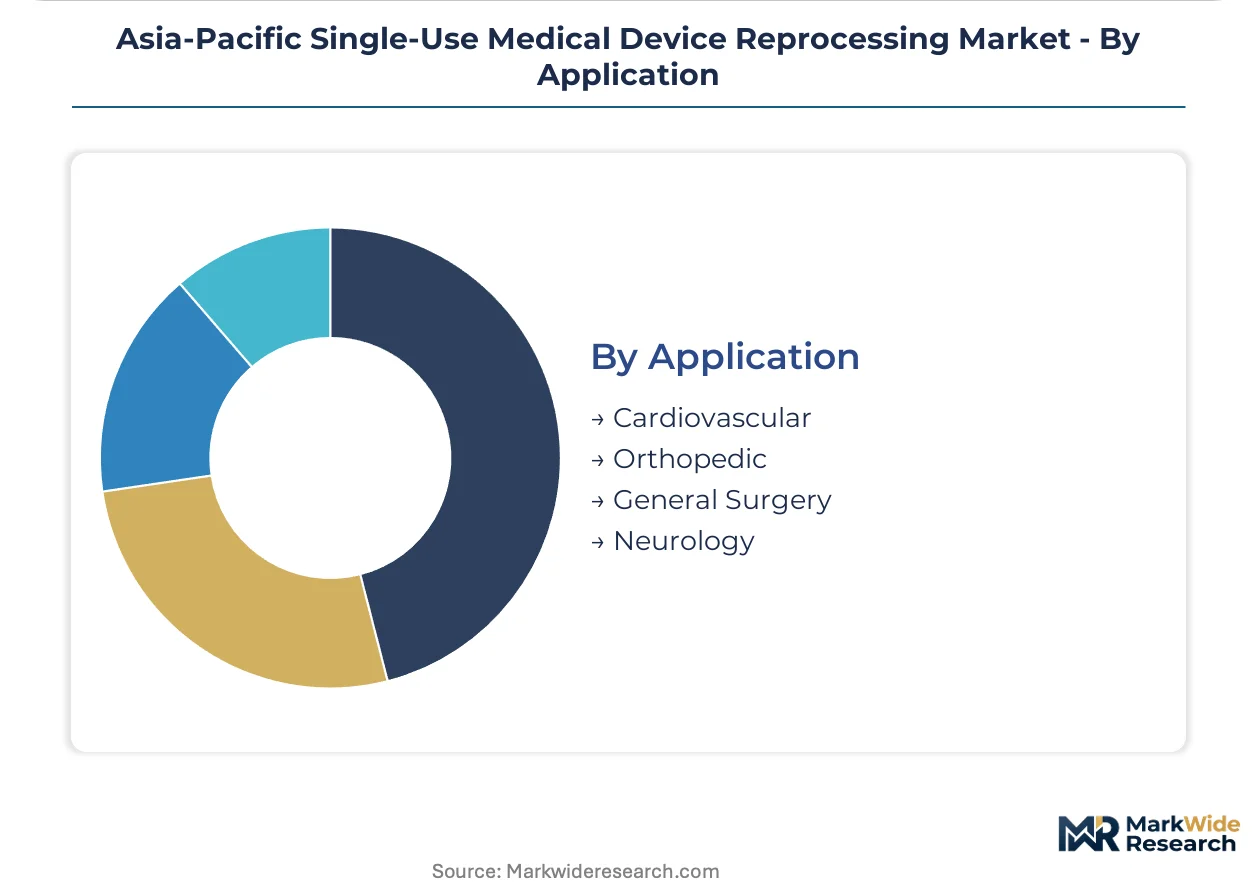
- Cardiovascular:Diagnostic and interventional catheters with highest original equipment costs generate strongest reprocessing economics. Indian cardiac centers and Australian interventional suites drive demand for validated luminal cleaning with documented sterility assurance.
- General Surgery:Electrosurgical devices and drapes with standardized geometries enable economies of scale in high-throughput sterilization operations.
- Orthopedic:Reprocessing penetration limited by device complexity and liability concerns.
- Neurology:Specialized devices with constrained validation protocols.
Cardiovascular applications hold the largest share; general surgery maintains steady expansion through standardized device flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO quality guidelines anchor India as the regulatory fulcrum for Asia-Pacific reprocessing standards. Hospital procurement departments across Southeast Asia and Oceania navigate divergent national accreditation pathways while scaling validated sterilization infrastructure.
India
Tier-1 cardiac catheterization labs in Maharashtra and Karnataka drive catheter reprocessing volume. CDSCO tightened sterility validation requirements, filtering informal operators toward accredited third-party processors. Mumbai and Bangalore hospital clusters concentrate demand for documented luminal cleaning protocols.
Australia
Victoria and New South Wales state health networks embed reprocessing quotas within procurement frameworks. TGA harmonization with ISO 14155 standards elevates documentation burdens for device-specific validation data. Sydney and Melbourne public hospital systems institutionalize electrosurgical device reprocessing through centralized sterilization hubs.
Thailand
Ambulatory surgical centers in Bangkok and surrounding provinces generate rapid-turnaround reprocessing demand. The national pharmaceutical regulator enforces sterility assurance documentation aligned with ASEAN harmonization initiatives. Private hospital chains in the capital region outsource collection-and-redistribution services lacking captive EtO capacity.
South Korea
MFDS maintains distinct sterility validation requirements that fragment compliance costs across national boundaries. Seoul Capital Area hospital networks balance cost-containment mandates against domestic device manufacturer relationships. Gyeonggi Province medical device clusters face regulatory misalignment pressures when scaling across Asia-Pacific markets.
Malaysia
Outpatient procedure migration in Selangor and Kuala Lumpur creates unmet demand for third-party reprocessing. The national medical device authority applies convergence pressures toward ISO 13485 quality management expectations. Private healthcare operators in the Klang Valley negotiate direct sterilization contracts outside traditional manufacturer channels.
Asia-Pacific Single-Use Medical Device Reprocessing Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated competitive structure across Asia-Pacific reprocessing. Automated cleaning validation systems and in-house microbiology laboratories define the premium tier, while regional sterilization hubs compete on throughput velocity and logistics reach. Strategic archetypes include technology specialists with proprietary catheter geometries, diversified hospital supply conglomerates leveraging bundled procurement relationships, and contract sterilization operators optimizing EtO turnaround cycles. Dominant competitive moves encompass geographic hub expansion to capture ambulatory surgical center demand and backward integration into collection logistics networks.
Among North American-based multinationals, Stryker Corporation and Johnson & Johnson occupy positions exemplifying divergent strategic archetypes. Stryker represents the technology-specialist tier through proprietary cleaning validation capabilities for complex device geometries. Johnson & Johnson exemplifies supply-chain leverage, embedding reprocessing services within broader hospital procurement relationships. Medline Industries anchors the scale-driven contract sterilization segment, operating regional hub infrastructure that compresses turnaround times for high-throughput device categories.
| Leading Market Players |
|---|
| Medline Industries |
| Stryker Corporation |
| Johnson & Johnson |
| NEScientific |
| ReNu Medical |
| Sterilmed |
| Arjo |
| Soma Technology |
| Centurion Medical Products Corporation |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on cobalt-60 irradiation capacity through two regional contract sterilizers determines both pricing tier spreads and supply chain shape across Asia-Pacific reprocessing markets. CDSCO documentation requirements for catheter validation create premium pricing tiers for accredited facilities, while informal operators compete on thin-margin drape volumes without transferable compliance infrastructure.
Pricing Analysis
Geographic price spreads between India's tier-1 cardiac centers and Thailand's ambulatory surgical centers exceed two-fold for equivalent catheter reprocessing services. Three-tier pricing structure across ISO 13485-accredited premium facilities, CDSCO-registered standard operators, and unaccredited economy reprocessors reflects certification grade and microbiology capability differentiation. Cost compression in the economy tier intensifies because Maharashtra and Karnataka state hospital networks leverage PLI-subsidized domestic device pricing as negotiation leverage. Ambulatory surgical centers in Bangkok and Kuala Lumpur exhibit highest price sensitivity due to absence of captive sterilization infrastructure and rapid-turnaround requirements.
Supply Chain Analysis
Tariff exposure between Australian TGA-registered facilities and ASEAN harmonization initiatives fragments compliance capital across non-transferable national infrastructure. Sterilization capacity concentrates in India, Australia, and Thailand, with ethylene oxide feedstock and cobalt-60 isotope supply drawing from concentrated petrochemical and nuclear processing hubs. Single-source vulnerability in gamma irradiation creates chokepoint risk for radiation-dependent catheter reprocessors. Distribution runs through hospital central sterile supply departments in tier-1 clusters and third-party collection-and-redistribution networks for ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific single-use medical device reprocessing market rewards facilities with validated luminal cleaning protocols and in-house microbiology laboratories, while penalizing operators lacking CDSCO-equivalent accreditation pathways. Microbiologist recruitment gaps and automated cleaning validation system deployment costs erect capability barriers that concentrate margin capture with technology-intensive processors.
For Market Incumbents: Insulate catheter reprocessing margins by deploying proprietary fluorescence-based residue detection systems and securing exclusive GPO contracts with Maharashtra and Karnataka state hospital networks. Retrofit existing ethylene oxide chambers with parametric release monitoring to defend against rapid-turnaround competitors in the surgical drape segment. CDSCO's tightened documentation requirements threaten informal operators; accelerate accreditation pathway investments to capture filtering volume. For New Entrants and Emerging Players: Establish a beachhead in Thailand's ambulatory surgical center segment by constructing regional EtO hubs with same-day redistribution logistics outside Bangkok's hospital cluster. Target electrosurgical device reprocessing in Malaysian private healthcare networks where procurement officers negotiate direct sterilization contracts outside traditional manufacturer channels. A collection-and-redistribution service model with RFID-tracked device lifecycle management offers the cleanest go-to-market angle. For Investors and Strategic Acquirers: The market sits at a regulatory consolidation phase that favors accredited third-party processors with transferable ISO 13485 infrastructure across national boundaries. Long-term viability centers on facilities demonstrating quality equivalence against PLI-subsidized domestic device manufacturing through documented sterility assurance outcomes. Acquisition targets should display automated cleaning validation capabilities and established relationships with tier-1 cardiac catheterization labs. Watch TGA harmonization with ISO 14155 standards as the signal indicating accelerated documentation burden elevation and competitive moat deepening.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Cleaning Validation Deployment | Fluorescence-based residue detection systems compress labor costs while tightening CDSCO documentation compliance. |
| Parametric Release EtO Retrofit | Same-day redistribution capability captures ambulatory surgical center demand in Thailand and Malaysia. |
| RFID-Tracked Lifecycle Management | Wireless inventory convergence enables outcome-based service contracts linking fees to functional device performance. |
| ISO 13485 Multi-Country Accreditation | Transferable quality infrastructure defends against regulatory fragmentation between CDSCO, TGA, and MFDS requirements. |
| Backward Integration into Collection Logistics | Captive redistribution networks reduce dependency on hospital central sterile supply department referrals. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and third-party reprocessing facility operators; and secondary validation through CDSCO regulatory filings, TGA guidance documents, hospital procurement databases, and GPO contract disclosure records. Bottom-up segmentation modeling triangulated against top-down market sizing from sterilization capacity utilization rates and device reprocessing penetration benchmarks.
Forecast inputs considered validated reprocessing volume by product category, accreditation pathway adoption curves, and ambulatory surgical center infrastructure expansion across the projection horizon. Segmentation dimensions modeled encompass device complexity tier, sterilization modality, end-user facility type, and national regulatory cluster. CAGRs derived from sterilization throughput growth rates, hospital procurement budget allocation shifts, and outpatient procedure volume migration patterns.
Stress conditions across cobalt-60 supply disruption, PLI subsidy expansion, and TGA-ISO 14155 harmonization acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding CDSCO enforcement consistency and ASEAN regulatory convergence momentum. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Lacrimal Dilator Market
Medical Devices
Global Medical Grade Coating Market
Medical Devices
Dermal Allograft Market
Medical Devices
Biliary Catheters Market
Medical Devices
Needle-Free IV Connectors Market
Medical Devices
Sialendoscopes Market
Medical Devices
Distal Embolic Filters Market
Medical Devices
Interlaminar Device Market
Medical Devices
Syringeless Injector Market
Medical Devices
Drug Device Combination Products Market
Medical Devices
Global Plastic Surgery Devices Market
Medical Devices
Kidney Stone Management Devices Market
Medical Devices
Artificial Cartilage Implant Market
Medical Devices
Chile Ultrasound Devices Market
Medical Devices
Middle Ear Implants Market
Medical Devices
Single Lead ECG Equipment Market