
 Global Extracorporeal CO2 Removal Devices Market | 2026-2036
Global Extracorporeal CO2 Removal Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Extracorporeal CO2 Removal Devices Market Foresight
High-flow venovenous configurations with integrated anticoagulation management is rotating toward the premium specification tier across procurement committees. Medtronic leverages its end-to-end critical care portfolio to sustain bundled contract positioning in North American academic medical centers. Getinge AB anchors European demand through its direct service infrastructure and long-term equipment leasing programs. Xenios AG differentiates via modular platform designs that occupy the mid-tier replacement cycle across German and Austrian hospitals.
Extracorporeal CO2 removal devices are blood-gas exchange systems that extract carbon dioxide directly from circulating blood through semipermeable membrane lungs, typically operating at blood flow rates between 0.4 and 1.5 liters per minute depending on cannulation strategy and patient metabolic load. These systems serve primarily as lung-protective adjuncts in patients with refractory hypercapnia or severe acidosis who cannot tolerate conventional mechanical ventilation pressures. The venovenous device category leads current revenue contribution due to its broader indication range and lower hemorrhagic complication profile relative to arteriovenous approaches. Sorbent-based regeneration technology represents the fastest-expanding segment as it enables prolonged circuit life without continuous fresh gas supply, concentrating margin pools with manufacturers controlling proprietary binding chemistries. Membrane lung technology remains the mature workhorse segment where hollow fiber geometries dominate manufacturing scale and procurement standardization.
The FDA maintains premarket notification requirements for extracorporeal circuits under 21 CFR 870.4, while the EU MDR demands renewed clinical evaluation for membrane lung devices previously cleared under the Medical Device Directive. Japan's PMDA imposes additional biocompatibility testing protocols that extend registration timelines for non-domestic manufacturers. Stakeholders must monitor evolving reimbursement thresholds for prolonged extracorporeal respiratory support as hospital payment systems recalibrate toward bundled episode economics.
Market Dynamics
The EU MDR's tightened clinical evidence requirements for membrane lung technologies are forcing manufacturers to rebuild regulatory dossiers, reshaping competitive positioning and procurement timelines across academic medical centers.
Growth Catalysts
- Acute Respiratory Distress Syndrome protocols:Critical care units in Germany, the United States, and Japan are expanding installed bases as lung-protective ventilation strategies become standard of care for refractory hypercapnia management.
- Sorbent-based regeneration chemistry:Proprietary binding technologies enabling prolonged circuit life without continuous fresh gas supply are concentrating margin pools with manufacturers controlling these material innovations.
- Japan PMDA biocompatibility pathways:Extended registration timelines for non-domestic manufacturers create first-mover advantages for firms completing early compliance investment.
Market Restraints
- Hollow fiber membrane supply concentration:Manufacturing scale for semipermeable membrane lungs clusters with specialized polymer processors, creating input bottlenecks during demand surges.
- Arteriovenous hemorrhagic complication profile:Higher bleeding risk relative to venovenous configurations limits addressable patient populations and narrows reimbursement eligibility.
- 21 CFR 870.4 premarket notification:FDA circuit classification requirements impose documentation burdens that extend commercialization timelines for novel cannulation strategies.
Strategic Opportunities
- Austrian mid-tier hospital replacement cycles:Modular platform designs are capturing share among facilities upgrading from first-generation systems without full academic medical center capital budgets.
- Bundled episode economics:Hospital payment system recalibration toward procedural packaging creates incentives for prolonged extracorporeal respiratory support integration.
- Integrated anticoagulation management:Convergence of regional citrate protocols with high-flow venovenous configurations is opening premium specification tier positioning.
Industry Challenges
- Perfusionist and ECMO specialist training pipelines:Specialized workforce scarcity constrains safe scaling of procedural volumes across community hospital settings.
- EU MDR clinical evaluation renewal:Previously MDD-cleared membrane lung devices face retrospective evidence generation costs and notified body capacity constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Extracorporeal CO2 Removal Devices Market |
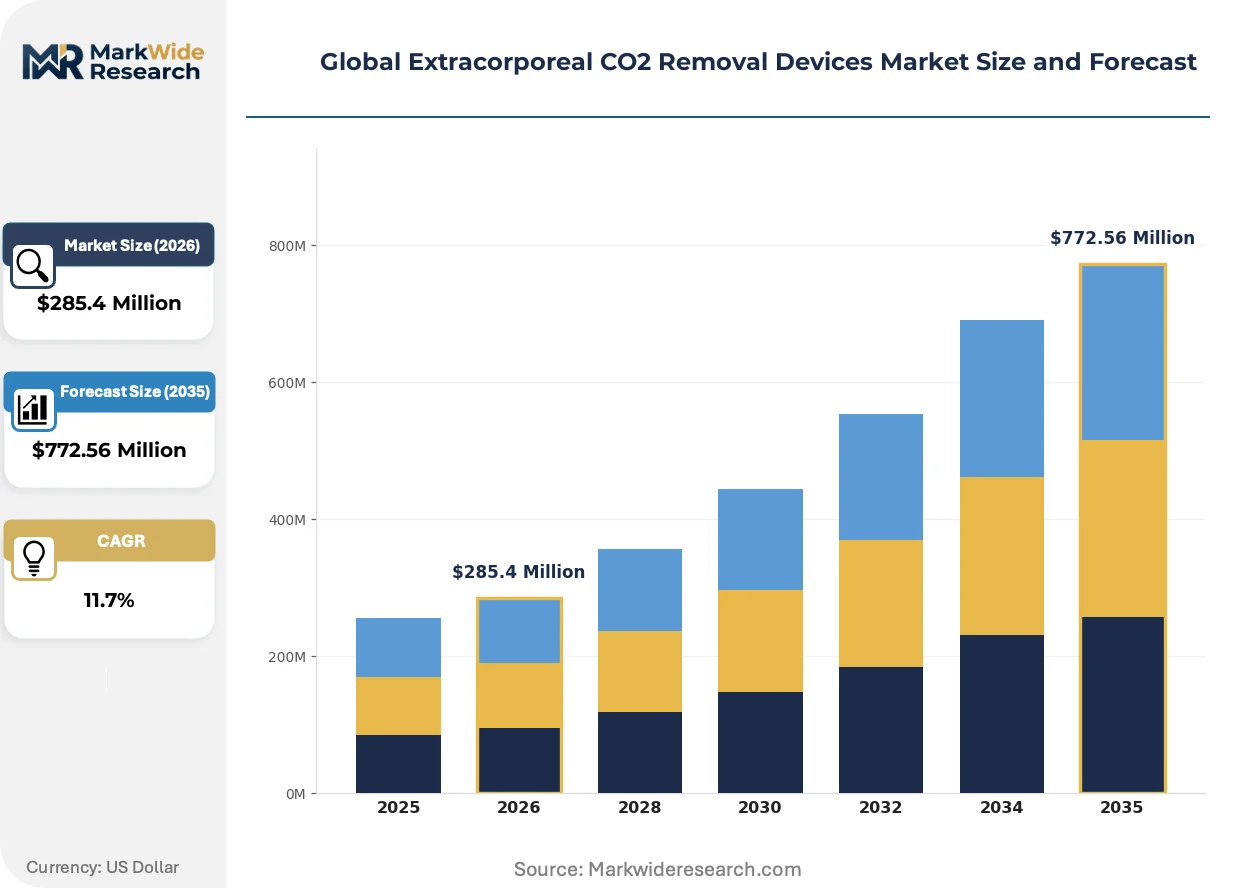
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $772.56 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Venovenous, Arteriovenous, Hybrid, Portable Systems, Implantable Devices Technology: Membrane Lung, Hollow Fiber, Microfluidic, Sorbent-Based, Enzymatic Application: Chronic Respiratory Failure, Acute Respiratory Distress Syndrome, Chronic Obstructive Pulmonary Disease, Pulmonary Hypertension, Pediatric Respiratory Support End User: Academic Medical Centers, Specialty Clinics, Critical Care Units, Research Laboratories, Home Care Providers |
| Companies Covered | Medtronic, Getinge AB, Xenios AG, ALung Technologies, ESTOR S.P.A., Medica S.P.A., Edwards Lifesciences, Fresenius Medical Care, LivaNova PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Extracorporeal CO2 Removal Devices Market Shifts & Advancements
Active miniaturization of blood-gas exchange surfaces and algorithm-driven anticoagulation protocols are compressing the gap between acute and prolonged support modalities.
Sorbent-based CO2 regeneration systems are displacing conventional sweep-gas dependent circuits in German and Austrian academic centers. These platforms eliminate continuous fresh gas supply requirements, reducing operational complexity for extended therapy. Intensive care procurement committees are accelerating evaluation timelines for these configurations, compressing replacement cycles for hollow fiber-dependent legacy installations.
The EU MDR framework demands renewed clinical evaluation for membrane lung devices previously cleared under the Medical Device Directive. Manufacturers must generate post-market clinical follow-up data and update technical documentation to maintain CE marking. German notified bodies are experiencing capacity constraints, extending certification timelines for mid-tier competitors without established MDR transition experience.
Hospital procurement committees are unbundling after-sales service from capital equipment contracts in North American academic medical centers. Third-party clinical engineering firms are capturing maintenance revenue previously retained by original equipment manufacturers. This pattern is most visible in the United States, where group purchasing organizations are standardizing service-level specifications across multi-hospital systems.
Global Extracorporeal CO2 Removal Devices Market Segmentation
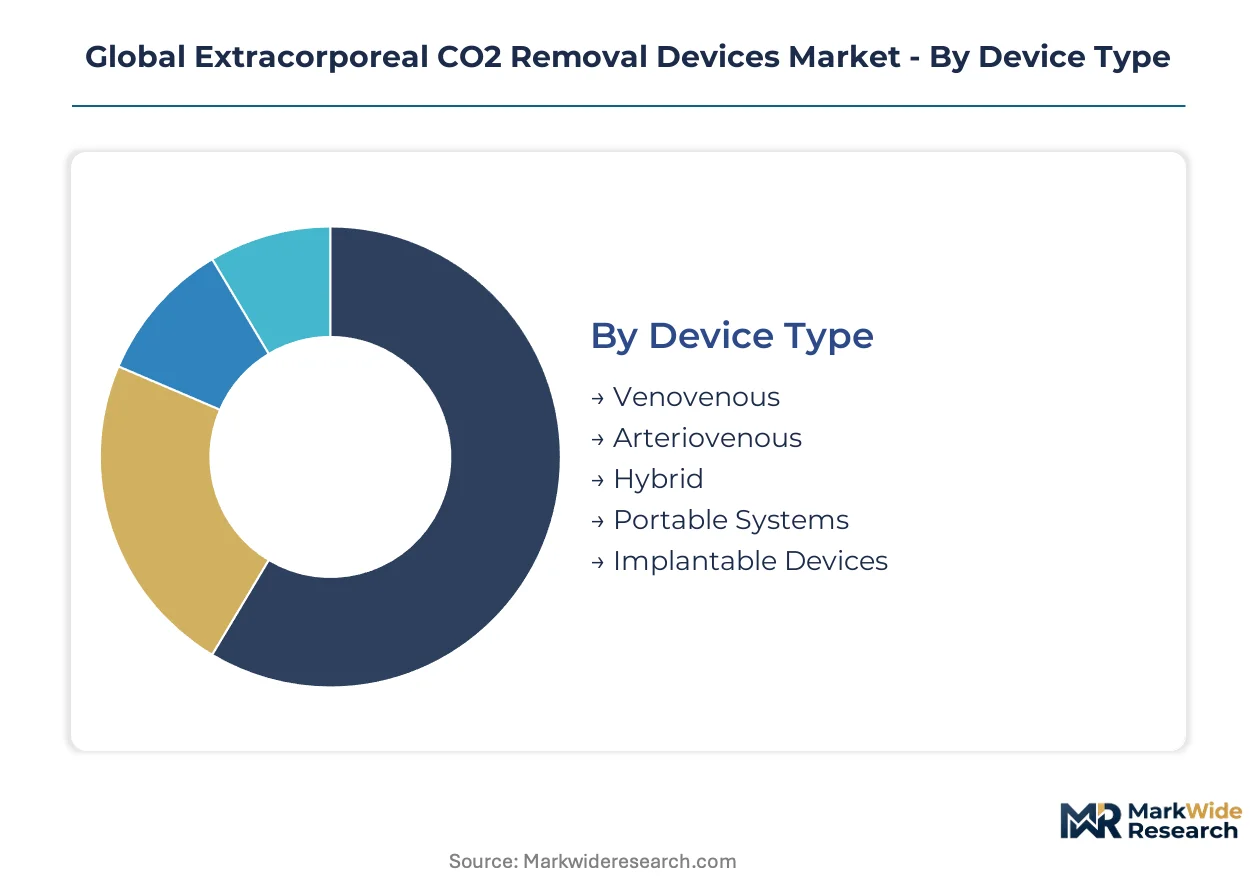
Segmentation in extracorporeal CO2 removal devices reveals distinct procurement patterns across clinical settings and technology tiers. Device configuration and cannulation strategy determine reimbursement pathways, while end-user concentration shapes regional demand distribution.
Device Type:
Venovenous systems dominate domestic hospital procurement in Germany and the United States, while portable configurations increasingly serve export markets targeting community hospital expansion.
- Venovenous:Blood is withdrawn and returned through central venous access, typically via femoral-jugular or dual-lumen jugular cannulation. German academic medical centers in Berlin and Munich operate the highest procedural volumes, driven by lung-protective ventilation protocols for acute respiratory distress syndrome.
- Arteriovenous:Relies on the patient's native cardiac output to drive blood through the membrane lung without a mechanical pump. Demand concentrates in Japanese tertiary centers where perfusionist staffing constraints limit pump-driven alternatives, though hemorrhagic complications narrow eligible patient populations.
- Hybrid:Combines venovenous cannulation with arteriovenous backup capabilities for hemodynamic instability.
- Portable Systems:Battery-powered units enabling inter-hospital transport and step-down unit deployment.
- Implantable Devices:Long-term implantable CO2 removal systems for bridge-to-transplant candidates.
Venovenous holds the largest share; momentum sits with portable systems.
Technology:
Cost tiers separate membrane lung commoditization from sorbent-based premium positioning, with hollow fiber occupying the mid-market replacement cycle.
- Sorbent-Based:Proprietary binding chemistries regenerate the dialysate without continuous sweep gas, enabling circuit life extension beyond 72 hours. Austrian hospitals in Vienna and Graz are accelerating procurement evaluations, compressing replacement cycles for gas-dependent legacy systems.
- Membrane Lung:Hollow fiber bundles with polymethylpentene or polypropylene exchange surfaces remain the procurement standard across North American academic medical centers. Bundled contract pricing with service integration sustains manufacturer margin pools despite polymer input cost volatility.
- Hollow Fiber:Standard geometry for semipermeable exchange surfaces with established manufacturing scale.
- Microfluidic:Silicon or polymer microchannel arrays enabling active miniaturization of blood-gas interfaces.
- Enzymatic:Carbonic anhydrase-immobilized surfaces accelerating CO2 hydration kinetics.
Membrane lung maintains installed base dominance; sorbent-based configurations are climbing the fastest.
Application:
Volume concentration in acute respiratory distress syndrome contrasts with emerging pediatric and chronic respiratory failure segments requiring specialized cannulation protocols.
- Acute Respiratory Distress Syndrome:Refractory hypercapnia management in patients failing conventional mechanical ventilation. United States critical care units in Boston, Houston, and Seattle operate the highest device utilization rates, tied to ECMO specialist training program density.
- Chronic Respiratory Failure:Bridge-to-transplant or destination therapy for irreversible lung disease. German lung transplant centers in Hanover and Essen are expanding chronic support programs, though reimbursement thresholds for prolonged extracorporeal therapy remain under negotiation with statutory insurers.
- Chronic Obstructive Pulmonary Disease:Exacerbation management with hypercapnic respiratory failure.
- Pulmonary Hypertension:Right ventricular failure with concomitant CO2 retention.
- Pediatric Respiratory Support:Specialized low-flow circuits for neonatal and pediatric metabolic requirements.
Acute respiratory distress syndrome captures procedural volume; pediatric respiratory support is gaining share fastest.
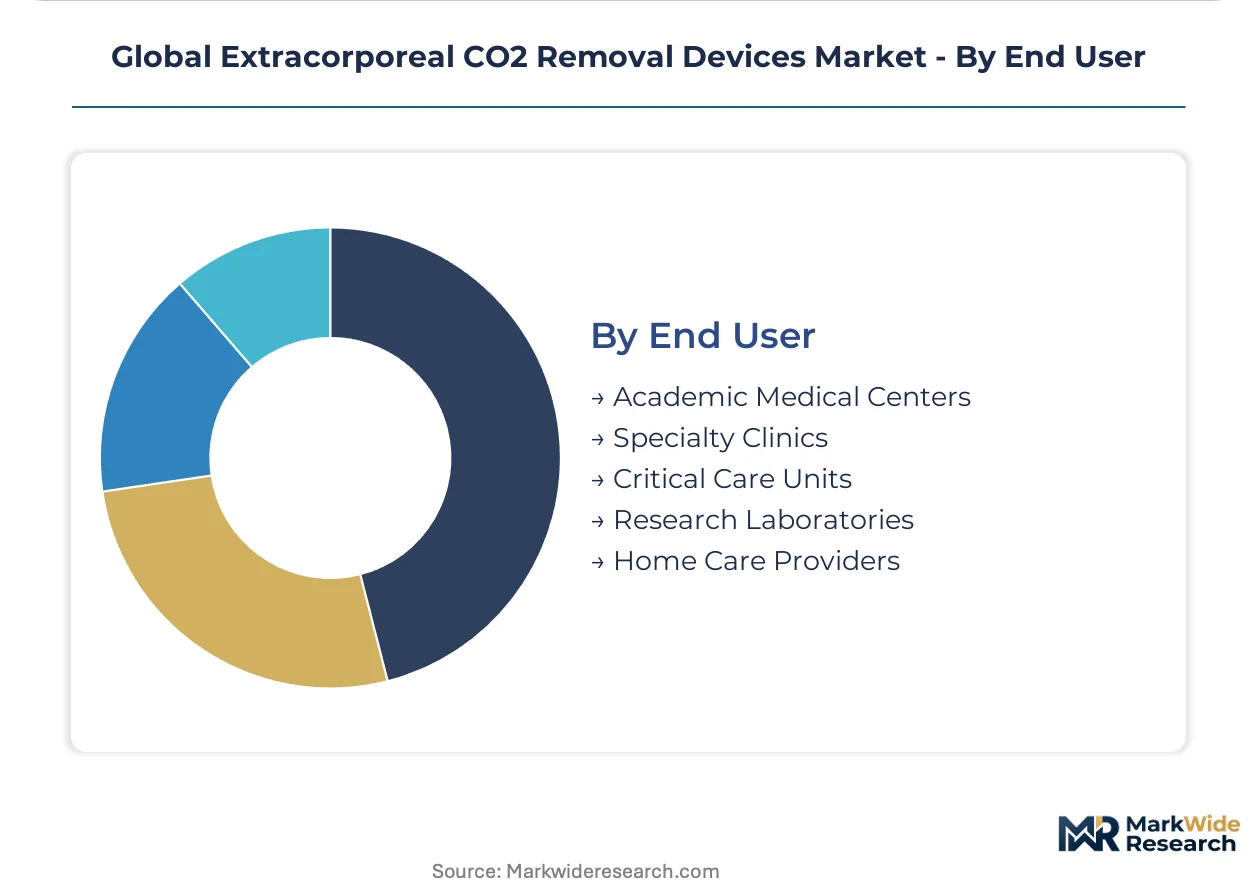
End User:
Customer type stratification separates academic medical center capital budgets from specialty clinic leasing arrangements and emerging home care reimbursement experiments.
- Academic Medical Centers:Full-service critical care departments with ECMO specialist staffing and perfusionist coverage. Japanese centers at Keio University and Osaka University anchor Asia-Pacific procedural volume, supported by PMDA early-compliance pathways for biocompatibility documentation.
- Critical Care Units:Hospital-based intensive care with extracorporeal respiratory support capability. United States community hospitals in Florida and Texas are expanding installed bases through group purchasing organization standardization, though perfusionist training pipelines constrain safe scaling.
- Specialty Clinics:Pulmonary or cardiothoracic focused outpatient facilities.
- Research Laboratories:Preclinical and clinical trial sites for device validation.
- Home Care Providers:Emerging reimbursement experiments for chronic outpatient support.
Academic medical centers hold the largest share; critical care units are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export membrane lung systems to academic medical centers in Japan and the United States, establishing the primary trade corridor for high-flow venovenous configurations.
United States
Academic medical centers in Boston, Houston, and Seattle operate the highest procedural volumes for acute respiratory distress syndrome management. The FDA maintains premarket notification requirements under 21 CFR 870.4 for extracorporeal circuits, extending commercialization timelines for novel cannulation strategies. ECMO specialist training programs at Massachusetts General and Baylor St. Luke's anchor regional utilization clusters.
Germany
Lung-protective ventilation protocols drive installed base expansion across Berlin and Munich critical care units. The EU MDR framework demands renewed clinical evaluation for membrane lung devices previously cleared under the Medical Device Directive, reshaping procurement timelines. German notified bodies face capacity constraints, extending certification timelines for mid-tier competitors.
Japan
Tertiary centers at Keio University and Osaka University anchor Asia-Pacific procedural volume for pump-driven alternatives. Japan's PMDA imposes additional biocompatibility testing protocols that extend registration timelines for non-domestic manufacturers. Perfusionist staffing constraints concentrate demand in metropolitan academic centers with established ECMO specialist coverage.
Austria
Vienna and Graz hospitals accelerate procurement evaluations for sorbent-based regeneration systems, compressing replacement cycles for gas-dependent legacy installations. EU MDR compliance costs disproportionately impact mid-tier facilities upgrading from first-generation systems without full academic medical center capital budgets. Modular platform designs capture share among regional hospitals seeking technology refresh without bundled service contracts.
United Kingdom
Specialized commissioning frameworks for prolonged extracorporeal respiratory support concentrate evaluation authority within NHS England specialized services teams. MHRA post-Brexit regulatory divergence from EU MDR timelines creates parallel compliance pathways for membrane lung manufacturers. London teaching hospitals at Guy's and St Thomas' and Imperial College Healthcare anchor national referral networks for refractory hypercapnia cases.
Global Extracorporeal CO2 Removal Devices Market Competitive Landscape
Listed leaders compete with private specialists across regulatory dossier capabilities and service infrastructure depth. The vendor base clusters around three tiers: diversified critical care conglomerates with bundled contract positioning, European mid-cap specialists with modular platform architectures, and emerging technology developers targeting sorbent-based regeneration chemistry. Strategic archetypes include end-to-end portfolio bundlers, regional direct-service anchors, and component-focused innovators. Competitive moves concentrate on M&A for regulatory dossier consolidation and long-term equipment leasing program expansion.
Among diversified critical care conglomerates, Medtronic and Getinge AB exemplify contrasting geographic anchoring strategies, with the former sustaining North American academic medical center positioning and the latter dominating European direct service infrastructure. Xenios AG occupies the mid-tier modular platform segment across German-speaking hospital systems. These three entities collectively illustrate how regulatory transition costs and service unbundling trends are reshaping procurement committee evaluation criteria.
| Leading Market Players |
|---|
| Medtronic |
| Getinge AB |
| Xenios AG |
| ALung Technologies |
| ESTOR S.P.A. |
| Medica S.P.A. |
| Edwards Lifesciences |
| Fresenius Medical Care |
| LivaNova PLC |
| Others |
Supply & Pricing Matrix
Hollow fiber membrane manufacturing scale in Germany and Japan creates dual-anchor supply concentration that elevates price floors for mid-tier competitors lacking captive polymer processing capacity. Sorbent-based regeneration chemistry introduces premium-tier pricing stratification as proprietary binding technologies command margin premiums over commodity hollow fiber bundles.
Pricing Analysis
Prior-generation hollow fiber membrane systems trade at standard-tier price points, current-generation sorbent-based configurations occupy premium positioning, and next-generation microfluidic platforms remain pre-commercial with value-based pilot pricing. Three-tier pricing structure across premium, standard, and economy levels separates integrated anticoagulation systems from basic venovenous circuits from arteriovenous alternatives. Cost compression in the standard tier intensifies because third-party clinical engineering firms unbundle after-sales service from capital equipment contracts. Community hospitals in the United States exhibit highest price sensitivity due to GPO-driven standardization, while Japanese academic medical centers show lowest sensitivity tied to PMDA compliance investment amortization.
Supply Chain Analysis
Inventory buffers for polymethylpentene and polypropylene hollow fiber bundles extend lead times during demand surges in Germany, Japan, and the United States. Raw material dependencies center on specialized polymer processors for semipermeable membranes, proprietary sorbent chemistries for regeneration systems, and precision pump components for integrated flow control. Single-source vulnerability concentrates in German notified body capacity for EU MDR certification, creating bottleneck risk for mid-tier manufacturers. Distribution runs through direct service infrastructure for academic medical center contracts and third-party clinical engineering networks for community hospital installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward group purchasing organizations in North America and specialized commissioning frameworks in the United Kingdom, consolidating procurement authority away from individual hospital committees.
For Market Incumbents: Consolidate regulatory dossier capabilities by acquiring mid-tier competitors with established EU MDR transition experience, addressing notified body capacity constraints that threaten certification timelines. Deepen backward integration into hollow fiber polymer processing to defend margin position against input cost volatility from specialized German and Japanese suppliers. For New Entrants and Emerging Players: Lead with sorbent-based regeneration platforms targeting Austrian mid-tier hospitals undergoing replacement cycles without full academic medical center capital budgets. The most penetrable segment sits with community critical care units in Florida and Texas expanding installed bases through GPO standardization, accessible via modular platform designs with unbundled service options. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component-focused innovators controlling proprietary binding chemistries over diversified critical care conglomerates facing service unbundling pressure. Long-term viability hinges on 5-10 year regulatory transition completion and reimbursement threshold negotiation outcomes for prolonged extracorporeal support. The signal to watch is German statutory insurer coverage decisions for chronic respiratory failure applications.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evaluation Completion | CE marking renewal for membrane lung devices previously cleared under MDD preserves German and Austrian market access. |
| Sorbent Chemistry Patent Portfolio Expansion | Proprietary binding technology control concentrates margin pools with circuit life extension beyond 72 hours. |
| Academic Medical Center Bundled Contracts | End-to-end critical care portfolio positioning sustains procurement committee influence in Boston and Houston. |
| Perfusionist Training Program Partnerships | ECMO specialist pipeline development enables safe scaling of procedural volumes across community hospital settings. |
| Third-Party Service Infrastructure Acquisition | Clinical engineering firm integration recaptures maintenance revenue from unbundled North American contracts. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with critical care physicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up and top-down triangulation cross-checked installed base estimates against procedural volume data from academic medical centers in Germany, the United States, and Japan.
Across the projection horizon, the analytical framework modeled device configuration, cannulation strategy, technology tier, application indication, and end-user concentration dimensions. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion patterns, incorporating sorbent-based technology adoption curves and EU MDR transition timeline assumptions.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement support for prolonged extracorporeal respiratory support or notified body capacity normalization would require recalibration. Forecasts reflect documented assumptions regarding lung-protective ventilation protocol adoption and perfusionist training pipeline expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
High Flow Ventilators Market
Medical Devices
Europe Intraocular Lens Market
Medical Devices
Airway Clearance Devices System Market
Medical Devices
Medical Tricorder Market
Medical Devices
North America Intraocular Lens Market
Medical Devices
Ankle Mobile Bearing System Market
Medical Devices
Global Pacemakers Market
Medical Devices
Peripheral Micro Catheters Market
Medical Devices
Ultrasonic Nebulizers Market
Medical Devices
Medical Polyetheretherketone Market
Medical Devices
Argentina Aesthetic Devices Market
Medical Devices
Anti-Snore Device Market
Medical Devices
South Korea Massage Equipment Market
Medical Devices
Global Radial Artery Compression Devices Market
Medical Devices
3D Printed Implants Market
Medical Devices
Ambulatory X-Ray Devices Market