
 Medical Device Tester Market | 2026-2036
Medical Device Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Device Tester Market Outlook
EU MDR is shifting the cost-of-entry calculus for device manufacturers seeking CE marking, compelling expanded electrical safety and biocompatibility testing before market authorization. SGS SA leverages its pan-European notified body network to capture recurring conformity assessment revenue. TÜV SÜD anchors its position through deep specialization in active implantable device testing. Eurofins Scientific competes by extending analytical chemistry capabilities into extractables and leachables validation.
Medical device testers are precision instruments designed to verify electrical safety, performance accuracy, and electromagnetic compatibility of diagnostic and therapeutic equipment, typically operating within calibrated tolerance bands of ±1% or tighter to ensure patient safety. Their primary commercial purpose is to provide documented evidence of regulatory compliance for manufacturers and healthcare facilities. The electrocardiogram tester segment dominates installed base volumes due to the ubiquity of ECG machines across care settings, while infusion pump testers command premium pricing driven by the critical nature of dose-delivery accuracy. Automatic testing technology leads growth trajectories as hospitals seek to reduce human error in routine preventive maintenance schedules.
FDA enforces premarket notification requirements under 21 CFR Part 820, while the EU MDR and ISO 13485 framework mandate sustained post-market surveillance testing throughout device lifecycles. These overlapping compliance obligations create durable demand for both initial validation equipment and ongoing service contracts. Stakeholders must monitor evolving harmonization gaps between FDA and EU MDR test protocols when configuring multi-jurisdictional product portfolios.
Market Dynamics
Hospitals are consolidating in-house biomedical engineering departments to reduce third-party service dependency, while FDA's updated Quality System Regulation forces manufacturers to expand pre-market verification capabilities. This dual pressure on both user and supplier sides is restructuring equipment procurement cycles and service contract structures.
Growth Catalysts
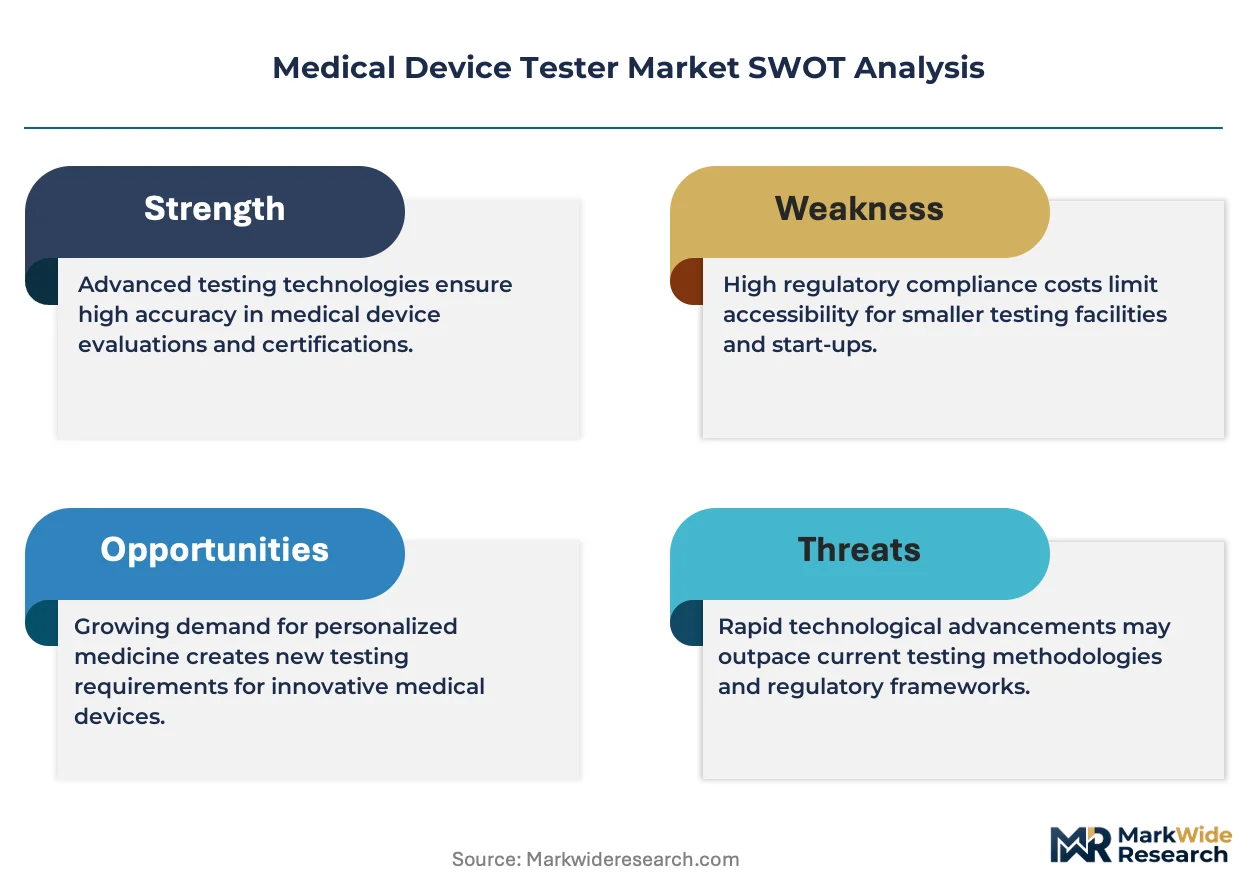
- EU MDR compliance deadlines:The Medical Device Regulation mandates expanded electrical safety and biocompatibility testing before CE marking authorization, compelling manufacturers to invest in verification equipment.
- Active implantable specialization:Cardiac pacemakers and neurostimulators require precision testing protocols that drive recurring demand for high-accuracy validation systems.
- Hospital consolidation:Health system mergers in Germany and the United States are centralizing biomedical engineering functions and standardizing tester fleets across multi-site networks.
Market Restraints
- Calibration gas supply concentration:Specialty gas blends for anesthesia tester calibration depend on a limited supplier base concentrated in industrial chemical clusters.
- ISO 17025 accreditation timelines:Third-party testing laboratories face 12-18 month certification delays that bottleneck market entry for new service providers.
- Refurbished equipment substitution:Secondary markets for recertified infusion pump testers capture budget-constrained buyers in outpatient surgery centers.
Strategic Opportunities
- Point-of-care device expansion:Home dialysis and portable diagnostic equipment create demand for compact, field-deployable testers outside hospital settings.
- Software-as-a-Service test automation:Cloud-based preventive maintenance platforms enable remote calibration tracking and reduce on-site engineering headcount.
- India's CDSCO manufacturing incentives:Production-linked incentive schemes for medical device manufacturing are attracting test equipment suppliers to establish local calibration facilities.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized technicians capable of servicing multi-modality testers command premium wages and extend recruitment cycles.
- Legacy equipment integration:New automatic testing systems must interface with 20-year-old infusion pumps and defibrillators through proprietary communication protocols.
- FDA 21 CFR Part 11 validation:Electronic records compliance for automated testers requires extensive documentation that extends product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Device Tester Market |
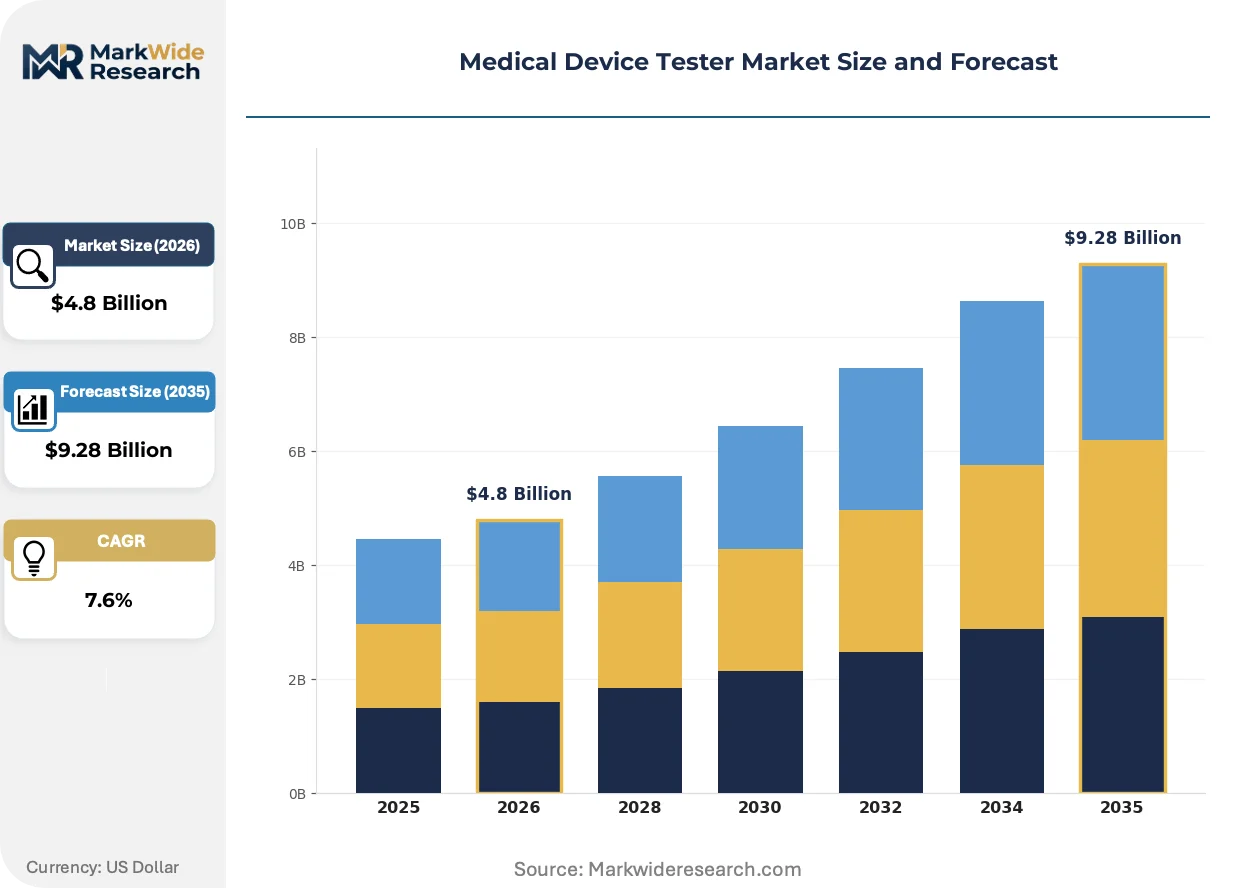
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrocardiogram, Infusion Pump Tester, Blood Glucose Meter, Defibrillator Tester Technology: Digital, Analog, Automatic, Manual End User: Hospitals, Clinics, Laboratories, Quality Assurance Departments Service Type: Calibration, Repair, Maintenance, Testing |
| Companies Covered | SGS SA, Laboratory Corporation of America Holdings, TÜV SÜD, Charles River Laboratories, Eurofins Scientific, Intertek Group Plc, Element Minnetonka, Nelson Laboratories, Pace Analytical Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Device Tester Market Strategic Shifts
Artificial intelligence is penetrating preventive maintenance workflows, while regulatory harmonization efforts between FDA and EU MDR are compressing test protocol development cycles. Equipment manufacturers are responding with modular platforms that adapt to evolving compliance requirements.
Machine learning algorithms embedded in electrocardiogram testers are rewriting how predictive maintenance schedules are generated. Large hospital systems in the United States are deploying these systems to anticipate component degradation before failure. The technology is compressing service contract pricing by reducing unplanned downtime incidents.
EU MDR's Unique Device Identification requirements are mandating traceable test records across device lifecycles. Manufacturers must now link every verification event to specific unit serial numbers. Active implantable device producers face the steepest compliance burden as they reconfigure quality management systems.
After-sales service unbundling is fragmenting traditional equipment-plus-service bundles. German hospital procurement departments are separately negotiating calibration contracts and software subscriptions. This shift is most pronounced in university medical centers with dedicated biomedical engineering research functions.
Medical Device Tester Market Segmentation
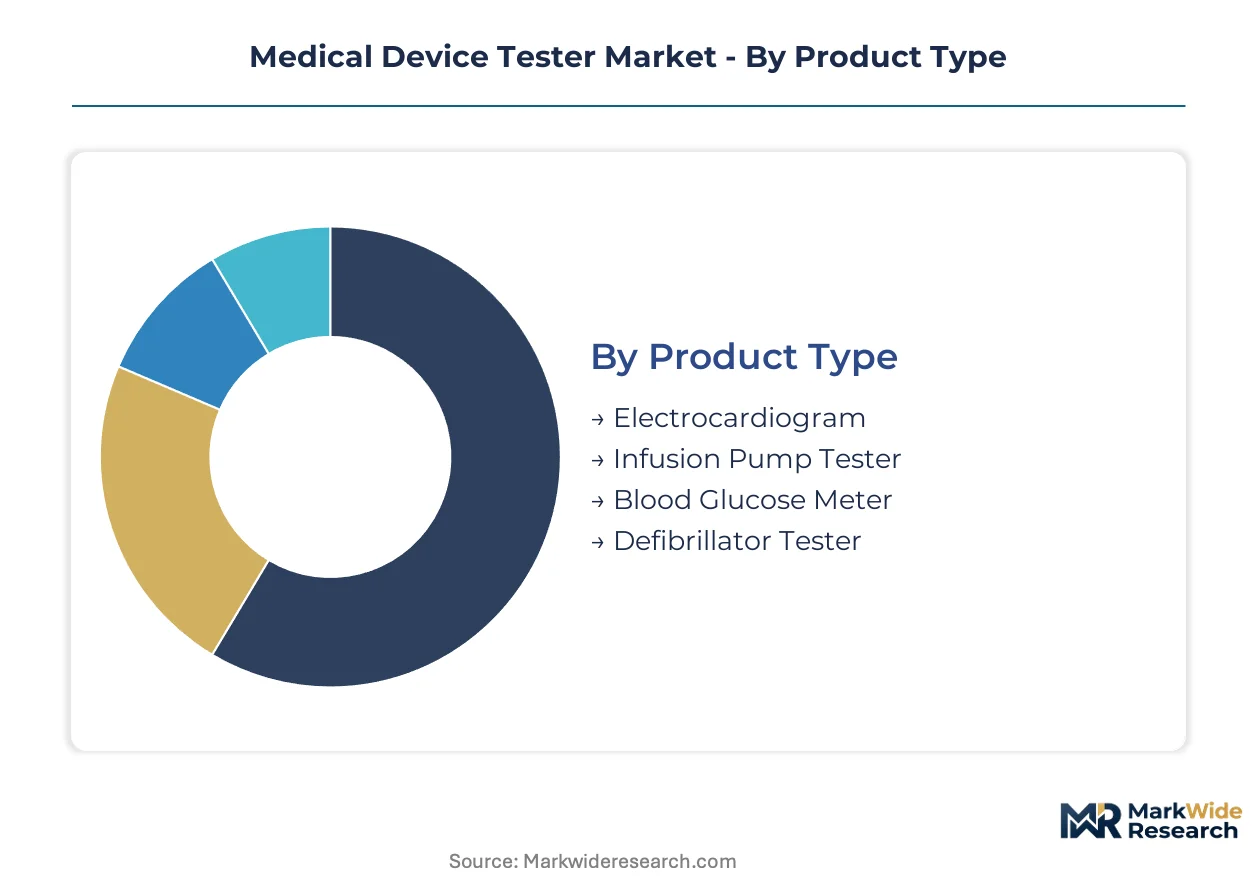
Medical device tester segmentation reflects divergent technical requirements across regulatory environments and care settings. Equipment specifications vary sharply between high-accuracy active implantable validation and routine preventive maintenance workflows.
Product Type:
Customization demands intensify with device complexity, from standardized ECG verification to bespoke infusion pump protocols requiring ±1% dose accuracy guarantees.
- Electrocardiogram:Twelve-lead signal simulation and waveform analysis capabilities dominate hospital biomedical engineering departments. Demand concentrates in German university medical centers upgrading legacy fleets to meet EU MDR traceability mandates.
- Infusion Pump Tester:Precision flow-rate validation systems measure volumetric and syringe pump performance across calibrated pressure ranges. Critical care units in United States health systems drive procurement for multi-channel testers supporting simultaneous device verification.
- Blood Glucose Meter:Electrochemical sensor calibration units verify hematocrit interference compensation and strip lot consistency.
- Defibrillator Tester:Energy discharge measurement systems assess biphasic waveform delivery and charge cycle integrity.
Leading the category by volume: Electrocardiogram. Expanding most quickly: Infusion Pump Tester.
Technology:
Cost tier separation runs from premium automatic platforms to economy manual units, with digital architectures commanding service contract premiums.
- Digital:Microprocessor-controlled measurement engines with embedded calibration algorithms and USB data export. German TÜV SÜD certification networks specify digital traceability for active implantable device testing.
- Automatic:Programmable test sequences execute standardized preventive maintenance protocols without technician intervention. United States hospital consolidation drives demand for fleet-wide automation reducing per-device labor hours.
- Analog:Discrete component measurement circuits for legacy device compatibility and electromagnetic isolation.
- Manual:Hand-operated verification tools for field service applications and low-throughput outpatient settings.
Highest margin concentration: Automatic. Steepest volume decline: Manual.
End User:
Application intensity varies from 24/7 clinical engineering operations to intermittent laboratory validation cycles.
- Hospitals:Centralized biomedical engineering departments manage multi-modality tester fleets across cardiac catheterization labs, operating suites, and emergency departments. In-house capability expansion in United States health systems reduces third-party service dependency.
- Quality Assurance Departments:Pre-market verification laboratories execute design validation protocols for FDA 510(k) submissions. EU MDR technical documentation requirements expand testing scope for CE marking applicants.
- Clinics:Limited-service verification for point-of-care diagnostics and basic physiological monitors.
- Laboratories:Analytical chemistry integration for extractables and leachables testing under ISO 17025 frameworks.
Dominant procurement volume: Hospitals. Fastest contract expansion: Quality Assurance Departments.
Service Type:
Customer type stratification separates capital equipment buyers from recurring revenue service subscribers.
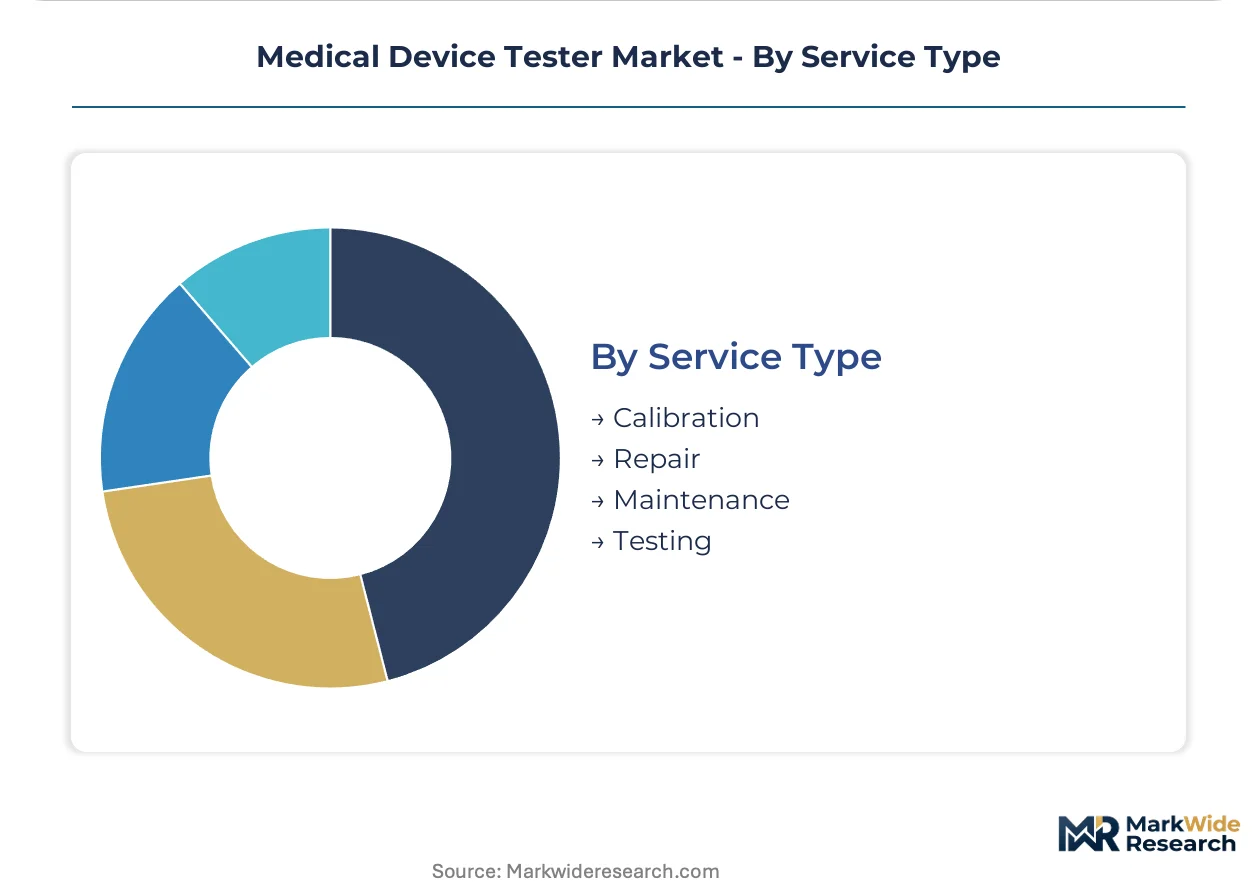
- Calibration:Traceable reference standard comparison against national metrology institute specifications. German notified bodies mandate documented calibration intervals for electrical safety testers under MDR surveillance requirements.
- Maintenance:Preventive service schedules aligned with manufacturer risk management files and FDA 21 CFR Part 820 quality system regulation. United States hospital networks standardize maintenance intervals across merged facility portfolios.
- Testing:One-time or periodic verification events for regulatory submission support or incident investigation.
- Repair:Component-level refurbishment and firmware updates extending equipment service life.
Recurring revenue anchor: Calibration. Fastest attach rate growth: Maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's CDSCO production-linked incentive zones concentrate new manufacturing capacity near Delhi-NCR and Gujarat. Special economic zones in South Korea and Germany anchor precision equipment clusters serving notified body networks.
United States
FDA 21 CFR Part 820 enforcement drives hospital biomedical engineering consolidation across multi-site health systems. The updated Quality System Regulation compels manufacturers to expand pre-market verification laboratories. Minneapolis-St. Paul hosts dense clusters of active implantable device specialists serving cardiac rhythm management firms.
Germany
TÜV SÜD and other notified bodies maintain certification networks that concentrate testing demand in Bavaria and Baden-Württemberg. EU MDR traceability mandates force manufacturers to reconfigure quality management systems for electrical safety documentation. Munich anchors the highest density of active implantable device testing facilities in Europe.
India
CDSCO production-linked incentives attract test equipment suppliers to establish local calibration facilities near Ahmedabad and Hyderabad. Manufacturing scale-up for export-oriented device production creates demand for ISO 17025-accredited verification laboratories. Karnataka's medical device park near Bengaluru clusters analytical chemistry capabilities for extractables testing.
China
NMPA regulatory harmonization efforts with ISO 13485 frameworks expand pre-market testing requirements for domestic manufacturers. Yangtze River Delta medical device production zones drive procurement of automated preventive maintenance systems. Shanghai's biomedical engineering talent concentration supports multi-modality tester service networks.
South Korea
MFDS post-market surveillance mandates sustain recurring demand for calibration services throughout device lifecycles. Seoul Capital Area hospital consolidation centralizes biomedical engineering functions across merged facility portfolios. Gyeonggi Province clusters precision measurement equipment suppliers serving diagnostic imaging manufacturers.
Medical Device Tester Market Competitive Environment
German specialists anchor the premium certification tier; United States-based service networks hold scale advantages in hospital contracting. The vendor base separates into three strata: pan-European notified bodies with dense accreditation networks, regional testing laboratories with ISO 17025 specialization, and equipment manufacturers bundling hardware with service contracts. Dominant competitive moves include geographic expansion of calibration networks and unbundling of after-sales service from capital equipment sales.
Within the notified body tier, SGS SA and TÜV SÜD exemplify pan-European certification specialists leveraging dense accreditation networks. Eurofins Scientific occupies a position bridging analytical chemistry capabilities into extractables and leachables validation. These three entities represent distinct archetypes: SGS SA exemplifies multi-sector conformity assessment scale, TÜV SÜD anchors active implantable device specialization, and Eurofins Scientific extends laboratory analytical services into device testing workflows.
| Leading Market Players |
|---|
| SGS SA |
| Laboratory Corporation of America Holdings |
| TÜV SÜD |
| Charles River Laboratories |
| Eurofins Scientific |
| Intertek Group Plc |
| Element Minnetonka |
| Nelson Laboratories |
| Pace Analytical Services |
| Others |
Value Chain & Pricing Dynamics
Specialty gas blend indices for anesthesia tester calibration cascade through three distinct pricing tiers, compressing margins for mid-range equipment while insulating premium automatic platforms. German notified body certification requirements tether pricing power to traceability documentation, forcing secondary market recertified units to absorb steeper discounts.
Pricing Analysis
Lead-time premiums of 30-60 days for ISO 17025-accredited calibration services command 15-25% markups over standard scheduling, while spot inventory of manual testers clears at distressed levels. Three-tier pricing structure across premium automatic, standard digital, and economy analog levels separates buyers by compliance urgency. Price differentiation hinges on FDA 21 CFR Part 11 validation documentation and bundled after-sales service contracts. Pricing pressure stems from refurbished equipment substitution in outpatient surgery centers. Budget-constrained clinics exhibit highest price sensitivity; active implantable device manufacturers show least sensitivity due to liability exposure.
Supply Chain Analysis
Regional distribution centers in Munich, Minneapolis-St. Paul, and Seoul Capital Area anchor hub-and-spoke patterns for precision measurement equipment. Manufacturing concentrates in Germany, the United States, and South Korea. Component sourcing draws from Taiwan for microprocessor-controlled measurement engines, Japan for precision flow sensors, and domestic chemical clusters for specialty calibration gases. Single-source vulnerability in ISO 17025-accredited reference standard supply creates bottleneck risk. Distribution runs through authorized service networks with direct hospital contracting in consolidated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 17025 accreditation capacity constraints prop pricing premiums by extending third-party laboratory certification timelines to 12-18 months.
For Market Incumbents: Acquire distressed calibration laboratory assets in Germany and the United States to preempt capacity bottlenecks. Consolidate regional service networks to defend against unbundling of after-sales contracts. Expand backward integration into specialty gas blending to neutralize supplier concentration risk. For New Entrants and Emerging Players: Outpatient surgery centers in India and Southeast Asia represent underserved buyer archetypes with unmet demand for compact field-deployable testers. Target CDSCO production-linked incentive zones near Ahmedabad and Hyderabad for local calibration facility establishment. Pursue software-as-a-Service test automation partnerships to bypass capital-intensive equipment manufacturing. For Investors and Strategic Acquirers: Distressed-cycle entries favor ISO 17025-accredited laboratories with active implantable device specialization in Germany. Long-term viability over the next decade rests on regulatory harmonization exposure between FDA and EU MDR protocols. Monitor CDSCO manufacturing incentive uptake as inflection indicator for capacity relocation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR traceability mandates expand electrical safety documentation requirements for notified body submission. |
| Hospital System Partnership | Consolidated United States health systems standardize tester fleets across multi-site biomedical engineering departments. |
| Software Companion Development | Cloud-based preventive maintenance platforms reduce on-site engineering headcount through remote calibration tracking. |
| Backward Integration | In-house specialty gas blending neutralizes supply concentration risk for anesthesia tester calibration. |
| FDA Submission | Updated Quality System Regulation compels expanded pre-market verification laboratory investment. |
Study Parameters
Document review covered FDA 510(k) filings, EU MDR technical documentation, ISO 13485 audit records, and hospital procurement databases, complemented by interviews with biomedical engineering directors, GPO contracts managers, notified body assessors, and equipment manufacturer product managers. Secondary sources included customs trade data for test equipment imports, SEC filings of publicly listed testing service providers, and CMS Medicare equipment utilization statistics. Bottom-up equipment unit economics were triangulated against top-down market size estimates.
Historical shipment data was cross-referenced against panel input from hospital purchasing committees and regulatory affairs specialists. The analytical framework modeled segmentation across product type, technology tier, end-user category, and service type throughout the forecast period. CAGRs were derived from regression analysis of installed base growth and replacement cycle compression. Industry-specific inputs incorporated EU MDR compliance deadline phasing and CDSCO manufacturing incentive uptake trajectories.
Revisions become necessary when regulatory harmonization gaps between FDA and EU MDR protocols materialize or when biomedical engineering talent scarcity extends recruitment cycles beyond modeled assumptions. Forecasts reflect documented assumptions regarding accreditation timeline stability and specialty gas supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Medical Devices Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
India Biopsy Devices Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
Artificial Urinary Sphincters Market
Medical Devices
Global Defibrillators Market
Medical Devices
Saudi Arabia Anesthesia Devices Market
Medical Devices
Manual Resuscitators Market
Medical Devices
Sinus Implants Market
Medical Devices
South Korea Massage Equipment Market
Medical Devices
Bone Anchored Hearing Aids Market
Medical Devices
Global Pupillometer Market
Medical Devices
Brazil Cardiac Pacemakers Market
Medical Devices
Phlebotomy Equipments Market
Medical Devices
Global Medical Composite Market
Medical Devices
Global Intraoperative Neuromonitoring (IONM) Market