
 North America Portable Medical and Healthcare Devices Market | 2026-2036
North America Portable Medical and Healthcare Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Portable Medical and Healthcare Devices Market Intelligence
Silicon-based microfabrication is shifting toward flexible polymer substrates in wearable biosensors, reducing unit costs and enabling skin-conformal form factors. Medtronic leverages its vertically integrated sensor supply chain to dominate cardiac patch manufacturing in the region. Koninklijke Philips NV sustains R&D intensity across pulse oximetry and sleep apnea platforms. Abbott Laboratories specializes in continuous glucose monitoring systems that anchor its position in diabetes management.
Portable medical and healthcare devices comprise battery-powered, handheld or body-worn instruments designed for diagnostic measurement, therapeutic delivery, or physiological monitoring outside fixed clinical installations, typically operating with power budgets under 10 watts and wireless data transmission to electronic health record systems. Their primary purpose is to extend clinical-grade accuracy into ambulatory, home, and remote settings while reducing facility-dependent care costs. Diagnostic devices lead product-type revenue pools due to recurring consumable attachments and test strip economics, while wearable technology segments expand fastest as skin-interfaced sensors achieve IEC 60601-1-2 electromagnetic compatibility certification. Homecare end users command margin concentration because CMS reimbursement codes for remote therapeutic monitoring create predictable payment streams.
FDA 510(k) clearance requirements and FCC Part 15 rules for radio-frequency medical transmitters shape product development timelines and market access barriers for new entrants in the United States. Health Canada and the country's national pharmaceutical regulator impose parallel but non-identical electromagnetic safety standards that manufacturers must navigate for cross-border commercialization. Stakeholders must monitor evolving CMS national coverage determinations for remote patient monitoring codes, as reimbursement granularity will determine which application segments achieve scalable deployment across North American health systems.
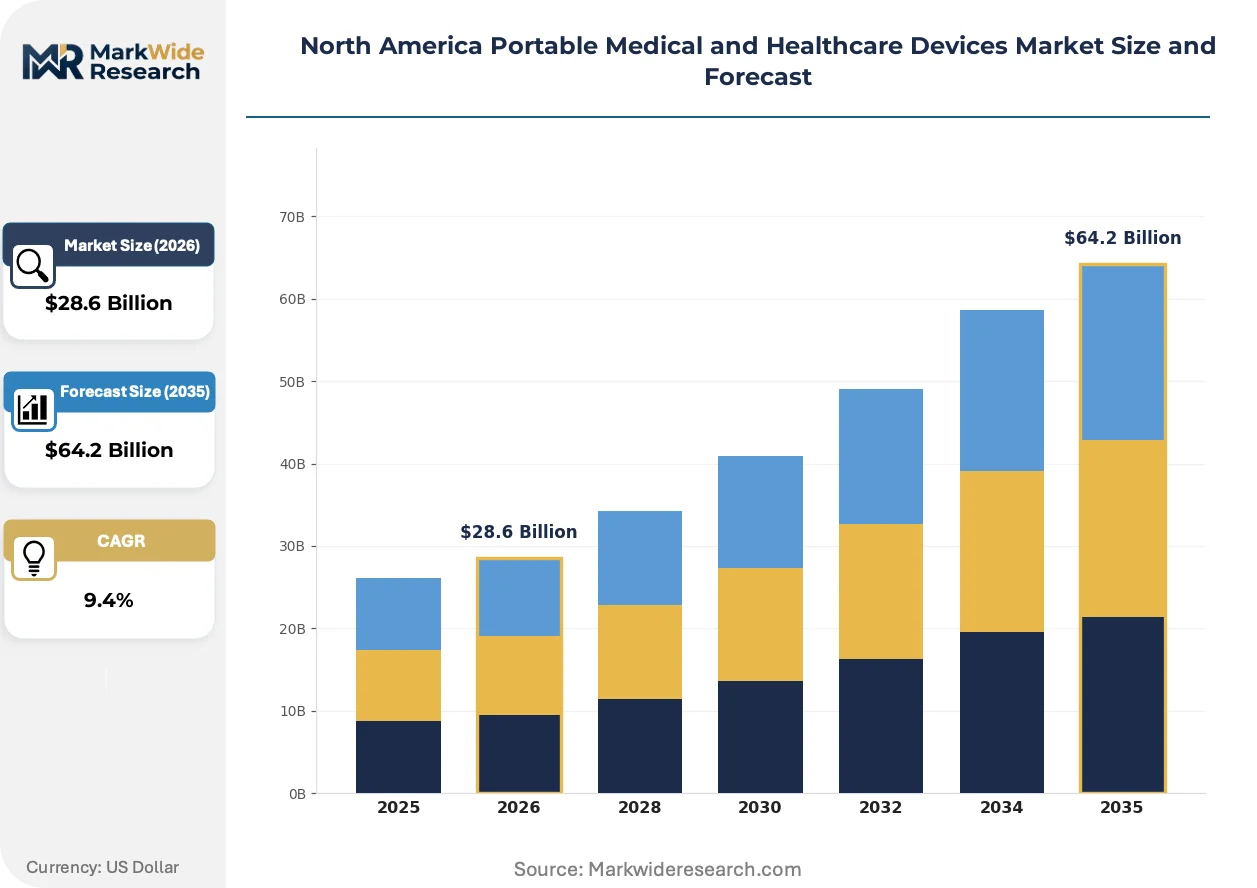
Market Dynamics
CMS reimbursement code expansions for remote therapeutic monitoring are restructuring payment flows, pulling capital toward homecare-optimized device architectures and compressing hospital-centric supply chains.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for predicate-based submissions reduce time-to-market for iterative biosensor designs. Device developers now prioritize incremental innovation over de novo classification.
- Homecare end-use concentration:Aging demographics in Florida, Arizona, and California drive demand for ambulatory cardiac and respiratory monitors. Integrated health systems consolidate purchasing power around remote patient monitoring bundles.
- Flexible polymer substrate adoption:Silicon-to-polymer manufacturing shifts cut unit costs for wearable patches. Skin-conformal form factors expand addressable populations beyond traditional clinical candidates.
Market Restraints
- Semiconductor supply concentration:Analog front-end chips and low-power microcontrollers face allocation constraints from concentrated Asian foundry capacity. Lead times for medical-grade components extend procurement cycles.
- FCC Part 15 compliance friction:Radio-frequency medical transmitters require extensive electromagnetic compatibility testing. Certification costs disproportionately burden mid-tier device developers.
- Reimbursement code granularity limits:Narrow CMS national coverage determinations exclude emerging diagnostic categories. Uncertain payment streams deter investment in non-established therapeutic areas.
Strategic Opportunities
- Mexico manufacturing expansion:Nearshoring assembly operations reduces tariff exposure and logistics costs. Tijuana and Guadalajara clusters attract FDA-registered contract manufacturers.
- Continuous glucose monitoring convergence:Integration with insulin pump systems creates closed-loop therapeutic platforms. Diabetes management ecosystems expand beyond standalone sensors.
- Health Canada parallel pathway utilization:Simultaneous FDA and Canadian submissions accelerate North American market access. Electromagnetic safety standard harmonization reduces dual-certification overhead.
Industry Challenges
- IEC 60601-1-2 certification bottlenecks:Third-party testing laboratory capacity constraints delay product launches. Electromagnetic immunity validation requires specialized anechoic chamber access.
- Biocompatibility testing backlogs:ISO 10993 cytotoxicity and sensitization studies face contracted laboratory queue times. Skin-contact wearable devices require extended evaluation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Portable Medical and Healthcare Devices Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitor, Infuser, Diagnostic Device, Therapeutic Device End User: Homecare, Hospitals, Clinics, Laboratories Technology: Wearable, Telehealth, Wireless, Sensor-Based Application: Cardiology, Diabetes Management, Pain Management, Respiratory |
| Companies Covered | Medtronic, Koninklijke Philips NV, GE Healthcare, OMRON Corporation, Samsung, Vyaire Medical, Abbott Laboratories, Johnson & Johnson, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Portable Medical and Healthcare Devices Market Strategic Shifts & Innovations
Wearable biosensor architectures are fragmenting into specialized form factors while regulatory frameworks coalesce around remote monitoring reimbursement. Material science advances and payment model shifts are compressing traditional device development cycles.
Flexible printed circuit board assemblies paired with microfluidic sampling layers are modularizing continuous analyte detection platforms. Homecare providers in Texas and Pennsylvania adopt these systems for chronic kidney disease management. The technology is modularizing what were previously integrated diagnostic instruments into swappable cartridge-and-reader configurations.
CMS national coverage determinations for remote therapeutic monitoring codes are expanding qualifying clinical indications beyond cardiology and pulmonology. Device developers now engineer multi-parameter platforms anticipating broader reimbursement eligibility. Sleep apnea and hypertension monitoring segments respond fastest to these payment signal changes.
Hospital procurement committees are unbundling device hardware from data analytics subscriptions. Direct-to-consumer channels and specialty durable medical equipment distributors capture margin previously held by integrated health system contracts. This disintermediation is most visible in California and New York, where patient cost-sharing sensitivity drives retail-accessible device preference.
North America Portable Medical and Healthcare Devices Market Segmentation
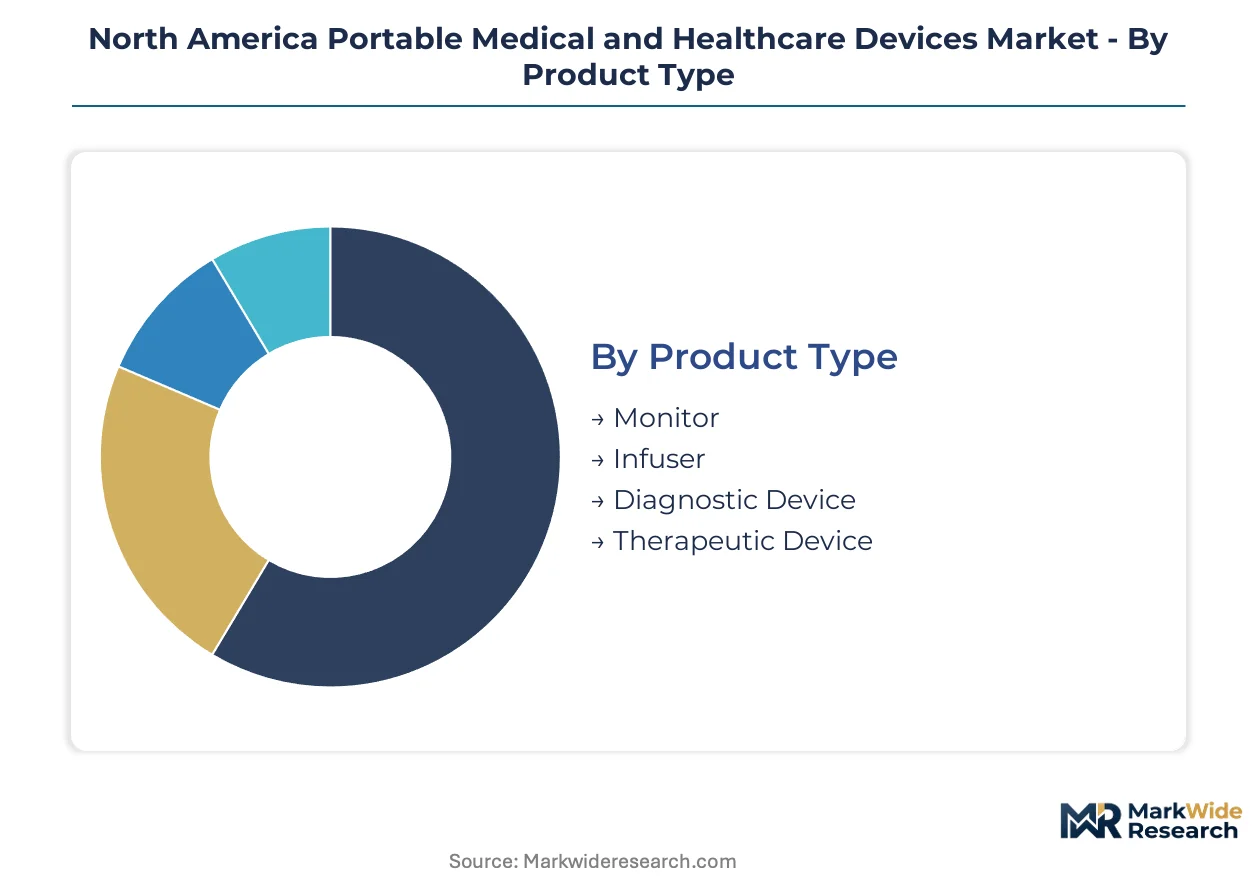
Segmentation reveals how capital deployment and reimbursement flows concentrate across device architectures in North America. Distinct technology-product combinations face divergent regulatory pathways and margin structures.
Product Type:
Capital intensity varies sharply across product categories, with diagnostic platforms requiring the heaviest upfront investment in consumable manufacturing and predicate clearance portfolios.
- Diagnostic Device:These systems integrate biosensor cartridges with portable readers for point-of-care chemistry and immunoassay detection. Demand clusters in homecare settings across Florida and Arizona, where CMS reimbursement for remote patient monitoring codes creates predictable revenue streams. Recurring test strip economics sustain margin profiles that hardware-only categories cannot match.
- Monitor:Continuous physiological tracking instruments span cardiac, respiratory, and metabolic parameters. Hospital procurement committees in California and Texas consolidate purchasing around multi-parameter platforms that anticipate expanded CMS national coverage determinations.
- Infuser:Ambulatory drug delivery pumps with dose-control algorithms and wireless connectivity to electronic health records.
- Therapeutic Device:Portable instruments for physical rehabilitation and pain intervention, including TENS units and neuromuscular stimulators.
Diagnostic Device absorbs the bulk of installed capacity; Monitor is expanding most quickly.
End User:
Customer-type concentration shapes pricing power and channel strategy, with integrated health system purchasing distinct from fragmented retail-accessible demand.
- Homecare:Patients and family caregivers operating devices in residential settings with remote clinician oversight. Demand concentrates in states with aging demographics—Florida, Arizona, California—where CMS reimbursement code expansions for remote therapeutic monitoring pull capital toward ambulatory-optimized architectures.
- Hospitals:Acute care facilities deploying portable instruments for bedside monitoring and early discharge protocols. Margin compression from unbundled procurement committees in New York and Pennsylvania drives preference for hardware-analytics subscription separability.
- Clinics:Outpatient facilities requiring rapid-deployment diagnostic platforms for episodic care.
- Laboratories:Reference and hospital-affiliated labs utilizing portable sample preparation and point-of-care verification instruments.
Homecare commands the steepest expansion trajectory; Hospitals retain the largest installed base.
Technology:
Technology-layer selection determines electromagnetic compliance burden and supply chain exposure to semiconductor allocation constraints.
- Wearable:Skin-interfaced biosensors on flexible polymer substrates with IEC 60601-1-2 certification. FDA 510(k) pathway streamlining accelerates clearance for iterative designs, reducing time-to-market versus de novo classifications.
- Sensor-Based:Discrete detection modules for analyte quantification and physiological signal acquisition. Analog front-end chip shortages from concentrated Asian foundry capacity extend procurement cycles and compress development timelines.
- Telehealth:Video-integrated diagnostic platforms with synchronous clinician interaction capabilities.
- Wireless:Radio-frequency medical transmitters operating under FCC Part 15 rules with extensive electromagnetic compatibility testing requirements.
Wearable gains share fastest; Sensor-Based anchors the largest revenue pool.
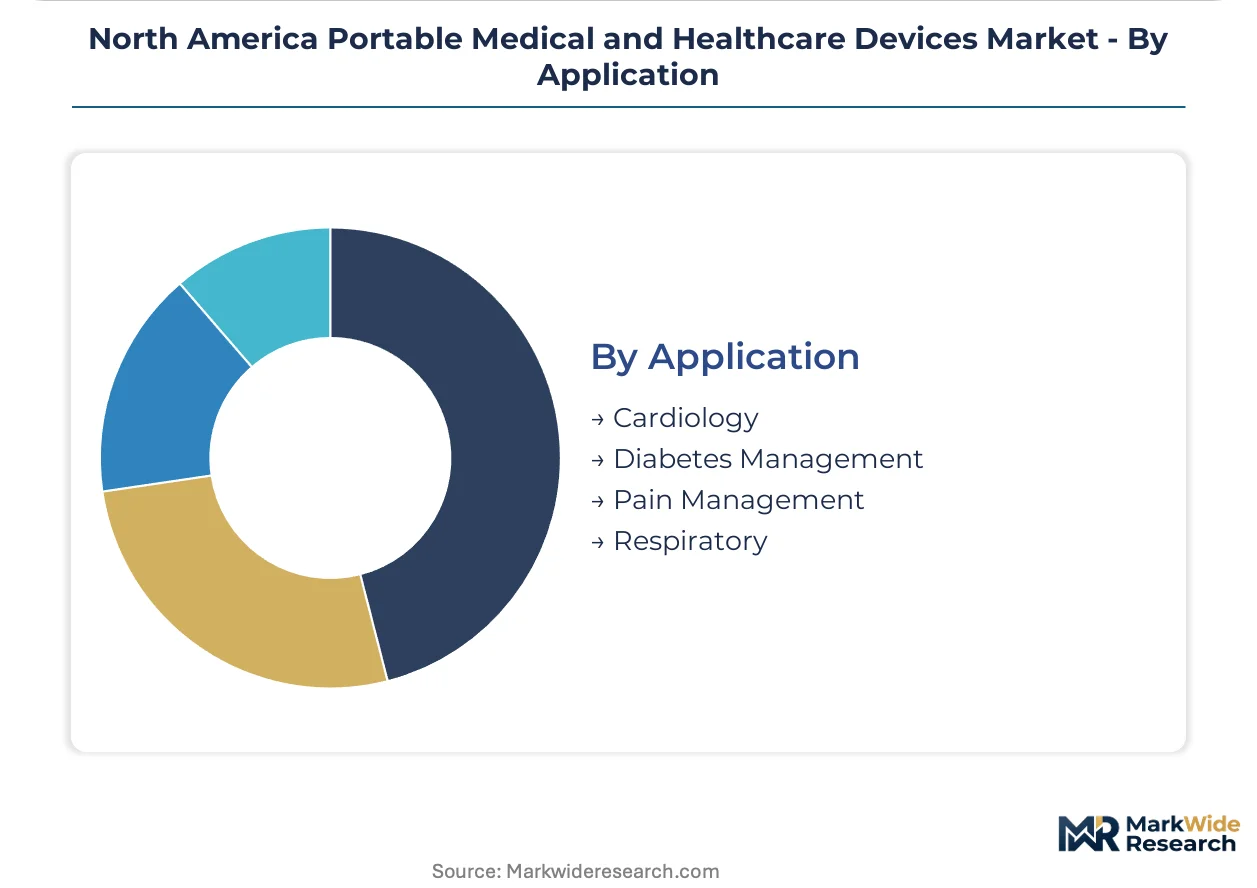
Application:
Clinical indication selection determines addressable reimbursement breadth and competitive density from established therapeutic ecosystems.
- Diabetes Management:Continuous glucose monitoring systems with insulin pump convergence creating closed-loop therapeutic platforms. Abbott Laboratories anchors this segment with sensor supply chain control and integrated pump partnerships.
- Cardiology:Ambulatory ECG and blood pressure monitoring for arrhythmia detection and heart failure management. Medtronic dominates cardiac patch manufacturing through vertically integrated sensor production in the region.
- Respiratory:Pulse oximetry and sleep apnea platforms responding fastest to CMS national coverage determination expansions beyond traditional cardiology and pulmonology codes.
- Pain Management:Portable TENS and neuromodulation devices for chronic and post-surgical pain intervention.
Diabetes Management captures the deepest revenue concentration; Respiratory climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign-trade zones along the US-Mexico border and maquiladora corridors concentrate assembly capacity for FDA-registered contract manufacturers serving North American demand.
United States
Aging demographics in Florida, Arizona, and California drive homecare adoption of ambulatory cardiac and respiratory monitors. FDA 510(k) clearance pathways and CMS reimbursement code expansions for remote therapeutic monitoring accelerate deployment timelines. Minneapolis and Boston anchor cardiac patch manufacturing and glucose monitoring R&D clusters.
Canada
Provincial health system procurement consolidation in Ontario and Quebec favors multi-parameter monitoring platforms. Health Canada and the country's national pharmaceutical regulator impose parallel electromagnetic safety standards that manufacturers navigate for cross-border commercialization. Toronto and Vancouver concentrate telehealth-integrated diagnostic development.
Mexico
Nearshoring momentum pulls assembly operations from Asian supply chains to Tijuana and Guadalajara industrial corridors. Reduced tariff exposure and logistics costs attract FDA-registered contract manufacturers serving US demand. Baja California and Jalisco states anchor medical device manufacturing clusters with growing IEC 60601-1-2 testing infrastructure.
North America Portable Medical and Healthcare Devices Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated health system purchasing favoring established device developers while retail-accessible channels open entry points for emerging players. The vendor base concentrates around cardiac monitoring, respiratory platforms, and diabetes management ecosystems where predicate clearance portfolios create defensive moats. Three archetypes dominate: vertically integrated sensor producers, multi-parameter platform developers, and flexible polymer substrate specialists. Competitive dynamics center on M&A for FDA clearance portfolios and capacity expansion into Mexican manufacturing zones.
Among diversified health technology conglomerates, Medtronic, Koninklijke Philips NV, and Abbott Laboratories occupy anchor positions across distinct therapeutic vectors. Medtronic represents vertically integrated sensor production with captive cardiac patch manufacturing. Koninklijke Philips NV exemplifies multi-parameter platform development spanning pulse oximetry and sleep apnea. Abbott Laboratories anchors continuous glucose monitoring ecosystems with insulin pump convergence strategies.
| Leading Market Players |
|---|
| Medtronic |
| Koninklijke Philips NV |
| GE Healthcare |
| OMRON Corporation |
| Samsung |
| Vyaire Medical |
| Abbott Laboratories |
| Johnson & Johnson |
| Stryker |
| Others |
Cost & Logistics Intelligence
CMS reimbursement code expansions for remote therapeutic monitoring are forcing device manufacturers toward homecare-optimized architectures, compressing hospital-centric supply chains and redistributing pricing power toward integrated health system purchasers with consolidated procurement authority.
Pricing Analysis
Premium pricing for short lead times on analog front-end chips and low-power microcontrollers has become standard as semiconductor allocation constraints from Asian foundries extend procurement cycles. Pricing stratifies across FDA 510(k)-cleared premium tiers, standard predicate-based submissions, and economy non-connected devices. Cost compression in the mid-tier is intensifying because hospital procurement committees unbundle hardware from analytics subscriptions. Homecare end users show highest price sensitivity due to patient cost-sharing exposure, while integrated health systems leverage volume scale for least sensitivity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Medtronic and Abbott Laboratories, while specialty durable medical equipment distributors serve fragmented retail-accessible segments. Manufacturing draws from Taiwan and South Korea for analog front-end semiconductors, China for flexible polymer substrates, and Mexico for final assembly in Tijuana and Guadalajara corridors. Single-source vulnerability concentrates in medical-grade microcontroller supply from concentrated Asian foundry capacity. Distribution runs through FDA-registered contract manufacturers nearshoring from Asian supply chains to reduce tariff exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America portable medical and healthcare devices market sits in a substrate-transition phase, with flexible polymer manufacturing displacing silicon-based microfabrication and rewiring competitive moats around skin-conformal form factors.
For Market Incumbents: Cement predicate clearance portfolio depth as the primary defensive barrier against iterative biosensor entrants leveraging FDA 510(k) pathway streamlining. Deepen backward integration into flexible polymer substrate supply to secure unit cost advantages as wearable patches commoditize. Control sensor supply chains against allocation volatility from Asian foundry concentration.
For New Entrants and Emerging Players: CMS reimbursement code expansions in the United States open a window for multi-parameter platform developers anticipating broader remote therapeutic monitoring eligibility beyond cardiology and pulmonology. Target sleep apnea and hypertension monitoring segments as fastest-responding white spaces to payment signal changes. Pursue direct-to-consumer channel strategies in California and New York where patient cost-sharing sensitivity drives retail-accessible device preference.
For Investors and Strategic Acquirers: Re-rating potential sits with flexible polymer substrate specialists given material science advances compressing traditional device development cycles. Long-term viability centers on FDA clearance portfolio depth rather than single-product innovation. Watch IEC 60601-1-2 electromagnetic compatibility certification bottlenecks as inflection indicator for launch timeline risk and testing laboratory capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated clearance timelines for predicate-based biosensor designs reduce time-to-market versus de novo pathways. |
| Hospital System Partnership | Integrated health systems in Florida and Arizona consolidate purchasing power around remote patient monitoring bundles. |
| Software Companion Development | Data analytics subscriptions unbundled from hardware capture margin previously held by device-only contracts. |
| Reimbursement Strategy | CMS national coverage determination alignment determines scalable deployment across North American health systems. |
| Geographic Manufacturing Footprint | Nearshoring to Tijuana and Guadalajara reduces tariff exposure and logistics costs for US market access. |
Research Approach
Document review covered FDA 510(k) clearance databases, CMS national coverage determinations, and FCC Part 15 electromagnetic compatibility filings, complemented by interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and remote patient monitoring platform developers. Secondary validation drew from hospital procurement databases, GPO contract repositories, and CMS Medicare reimbursement data. Bottom-up unit economics triangulated against top-down health system spending patterns.
Historical revenue trajectories cross-referenced against panel input from device manufacturers and contract manufacturing executives shaped the analytical framework. Segmentation dimensions modeled include product type, end user, technology layer, and clinical application across the analysis window. CAGRs derived from regression analysis of reimbursement code expansion rates and semiconductor supply allocation trends. Forecast inputs incorporated FDA clearance pipeline velocity and Health Canada parallel pathway utilization patterns.
The model assumes a particular technology adoption path; alternative pathways for flexible polymer substrate manufacturing would alter the outlook if silicon-based microfabrication cost curves shift unexpectedly. Forecasts reflect assumptions about CMS reimbursement granularity expansion and electromagnetic safety standard harmonization between FDA and Health Canada. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Catheter Stabilization Devices Market
Medical Devices
Disposable Thermometer Market
Medical Devices
Europe Smart Medical Devices Market
Medical Devices
Transplant Monitoring Kits Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market
Medical Devices
Hip Kits Market
Medical Devices
Global Dermatoscope Market
Medical Devices
Pulmonary Heart Valve Replacement Market
Medical Devices
Sentinel Node Biopsy Market
Medical Devices
Canada Respiratory Devices Market
Medical Devices
Bone Growth Stimulators Market
Medical Devices
Artificial Cornea and Corneal Implant Market
Medical Devices
Transcranial Magnetic Stimulation System Market
Medical Devices
Electronic Skin Patch Market
Medical Devices
Mexico Respiratory Devices Market
Medical Devices
Annuloplasty System Market