
 India Minimally Invasive Surgery Devices Market | 2026-2036
India Minimally Invasive Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India Minimally Invasive Surgery Devices Market Foresight
Private tertiary care is rebalancing toward robotic-assisted procedures while government hospitals scale laparoscopic capacity. Medtronic PLC leverages its integrated surgical ecosystem to anchor premium system placements across metro India. Abbott Laboratories sustains catheter and closure device leadership through deep interventional cardiology relationships. Siemens AG competes on imaging-to-navigation workflows that reduce procedure variability in hybrid operating rooms.
Minimally invasive surgery devices encompass instruments, visualization systems, robotic platforms, and energy devices engineered for reduced incision profiles, typically operating through ports under 15 millimeters to limit tissue disruption and accelerate recovery. These systems serve the primary purpose of enabling therapeutic intervention through natural orifices or small access points rather than open surgical fields. Laparoscopic devices occupy the largest installed base, reflecting two decades of surgeon training infrastructure and accessible capital expenditure tiers. Robotic surgical systems represent the fastest-expanding margin pool, though penetration remains gated by per-procedure consumable economics and specialist availability. Endoscopic devices dominate gastrointestinal and respiratory diagnostic-therapeutic overlap, where reimbursement clarity supports replacement cycles.
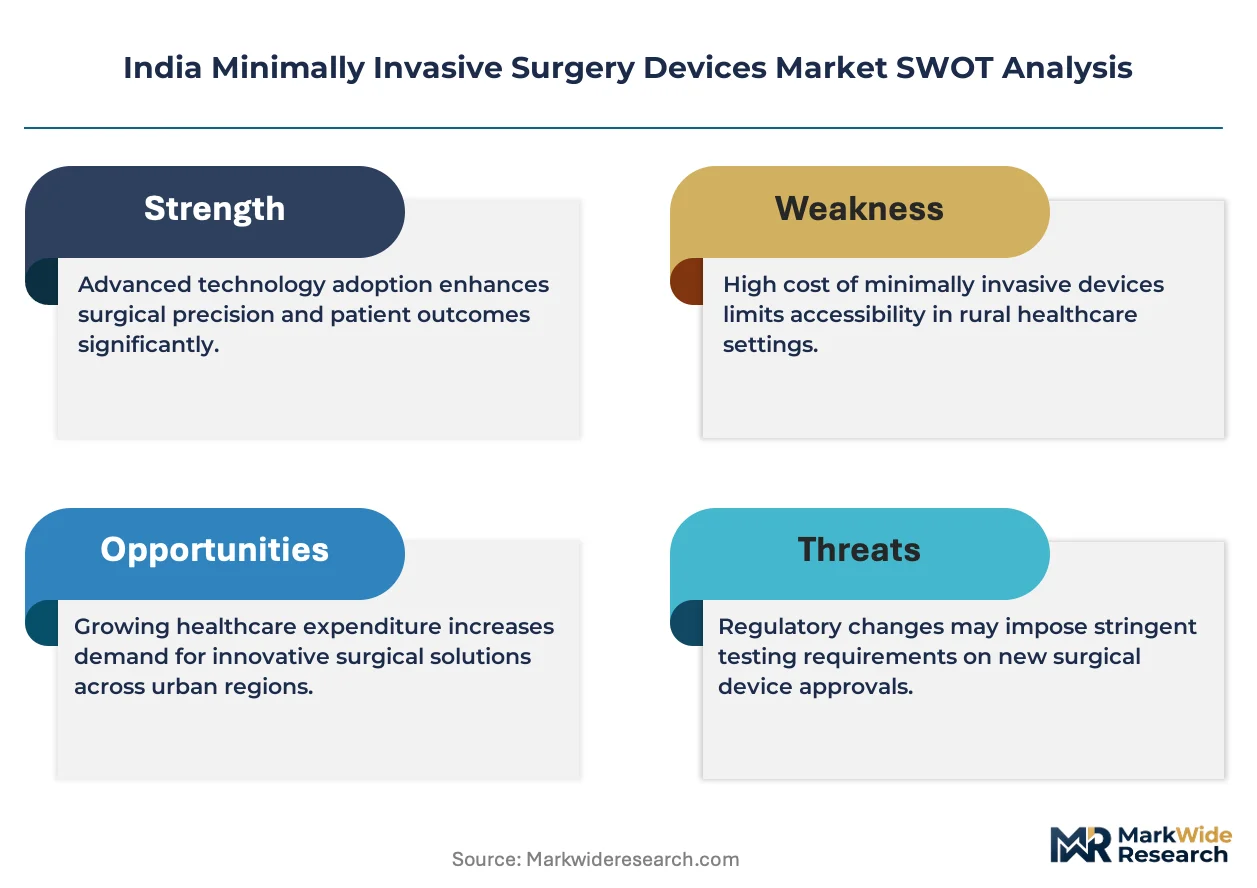
CDSCO governs device registration and quality standards under the Drugs and Cosmetics Act, while BIS certification mandates electrical safety and electromagnetic compatibility for imported surgical equipment. State-level hospital procurement policies under the National Health Mission increasingly preference domestically assembled devices, altering vendor qualification requirements. Stakeholders must monitor PLI scheme expansion into precision medical components and evolving state-level tender specifications that favor total cost-of-ownership models over upfront capital bids.
Market Dynamics
CDSCO's Medical Devices Rules 2017 revision is compressing import substitution timelines while Maharashtra and Karnataka hospital clusters accelerate capital deployment into robotic platforms, creating bifurcated demand tiers across public and private procurement channels.
Growth Catalysts
- PLI scheme expansion:Domestic assembly incentives for precision medical components are drawing component suppliers to Gujarat and Tamil Nadu manufacturing corridors, reducing landed cost gaps for laparoscopic instrumentation.
- Specialty hospital density:Mumbai-Pune and Bengaluru clusters concentrate surgeon training infrastructure and high-volume referral networks that amortize robotic system capital across sufficient procedure volumes.
- CDSCO streamlined pathways:Risk-based classification and abridged review timelines for Class C and D devices are accelerating market entry for novel energy devices and advanced stapling platforms.
Market Restraints
- Per-procedure consumable economics:Robotic surgery's recurring instrument and accessory costs limit penetration in government hospital tenders where total cost-of-ownership caps dominate capital allocation decisions.
- Specialist availability constraints:Fellowship-trained robotic surgeons concentrate in six metro cities, creating supply bottlenecks that gate system utilization rates outside Maharashtra, Karnataka, and Delhi NCR.
- Import dependency for optical components:High-definition camera heads and 4K imaging sensors rely on German and Japanese suppliers, exposing margins to yen and euro volatility and DGFT licensing delays.
Strategic Opportunities
- Tier-2 city hospital expansion:Kerala's Kochi-Thiruvananthapuram corridor and Telangana's Hyderabad cluster are building hybrid operating room capacity without legacy laparoscopic infrastructure lock-in, enabling direct robotic platform adoption.
- Energy device convergence:Integration of ultrasonic and advanced bipolar technologies into single-platform generators is creating premium positioning opportunities for vendors with in-house energy R&D capabilities.
- State tender model innovation:Tamil Nadu and Rajasthan are piloting equipment leasing and managed service contracts that shift capital burden from upfront purchase to per-procedure fees, expanding addressable hospital segments.
Industry Challenges
- Biomedical engineer scarcity:Robotic system maintenance and calibration require specialized technicians whose training programs remain concentrated in Bengaluru and Chennai, extending mean time to repair in northern and eastern states.
- BIS electromagnetic compatibility certification:Imported surgical equipment faces 4-6 month testing queues at Mumbai and Delhi laboratories, compressing product launch windows against domestic competitors with pre-certified platforms.
- Legacy laparoscopic inventory integration:Hospital groups with substantial existing instrument stockpiles face sunk-cost resistance when evaluating robotic platform conversions, complicating sales cycles for integrated system vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Minimally Invasive Surgery Devices Market |
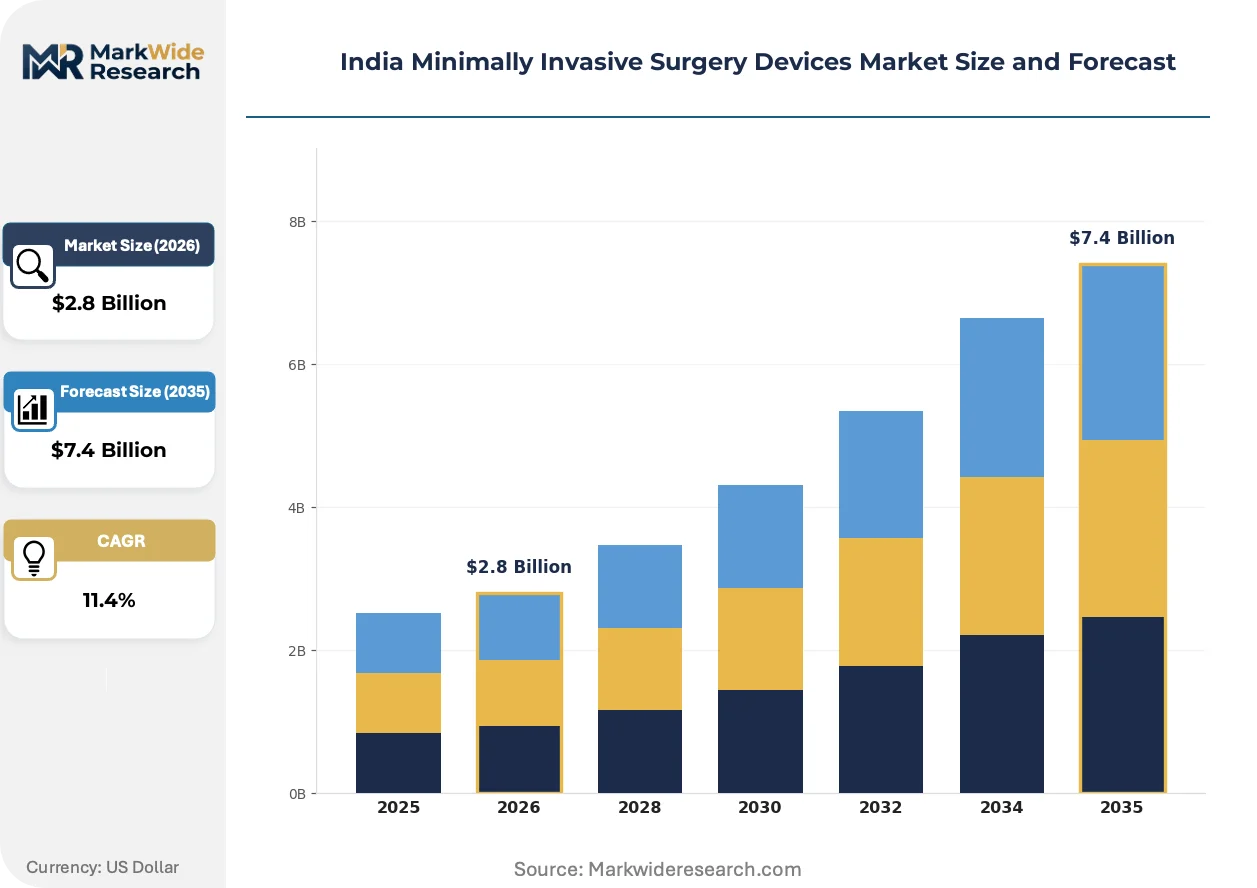
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laparoscopic Devices, Robotic Surgical Systems, Endoscopic Devices, Surgical Instruments End User: Hospitals, Ambulatory Surgical Centers, Clinics, Diagnostic Centers Technique: Single Incision Surgery, Traditional Laparoscopy, Robotic Assistance, Natural Orifice Surgery Application: Gynecological Surgery, Cardiothoracic Surgery, Gastrointestinal Surgery, Urological Surgery |
| Companies Covered | Abbott Laboratories, Koninklijke Philips NV, Medtronic PLC, Smith & Nephew PLC, Stryker Corporation, Olympus Corporation, GE Healthcare, Zimmer Biomet, Siemens AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Minimally Invasive Surgery Devices Market Shifts & Advancements
Technological substitution, regulatory pathway compression, and procurement model experimentation are simultaneously reshaping competitive positioning and vendor qualification requirements across Indian surgical device markets.
Single-port robotic platforms is overtaking multi-port configurations in premium private hospital segments. Apollo Hospitals and Max Healthcare are deploying these systems for colorectal and gynecologic procedures where cosmesis drives patient preference. The technology is overtaking conventional laparoscopic ports by eliminating trocar-site complications and reducing postoperative pain scores, compressing average length-of-stay metrics that feed into insurer reimbursement negotiations.
CDSCO's 2023 guidance on software-as-medical-device classification is creating compliance precedents for AI-enabled surgical navigation. Vendors must now submit algorithm validation datasets and intended use protocols for machine learning modules integrated into imaging systems. Delhi NCR and Mumbai hospital procurement committees are beginning to preference platforms with pre-cleared autonomous features, shifting technical evaluation criteria toward software documentation depth.
Consignment inventory arrangements are displacing traditional capital purchase models in government hospital tenders. Tamil Nadu Medical Services Corporation and Karnataka's State Drug Logistics and Warehousing Corporation are piloting vendor-managed stock programs for laparoscopic staplers and energy cartridges. Southern state health missions are most advanced in this transition, with payment terms tied to actual consumption rather than forecasted annual volumes, transferring inventory risk to device manufacturers.
India Minimally Invasive Surgery Devices Market Segmentation
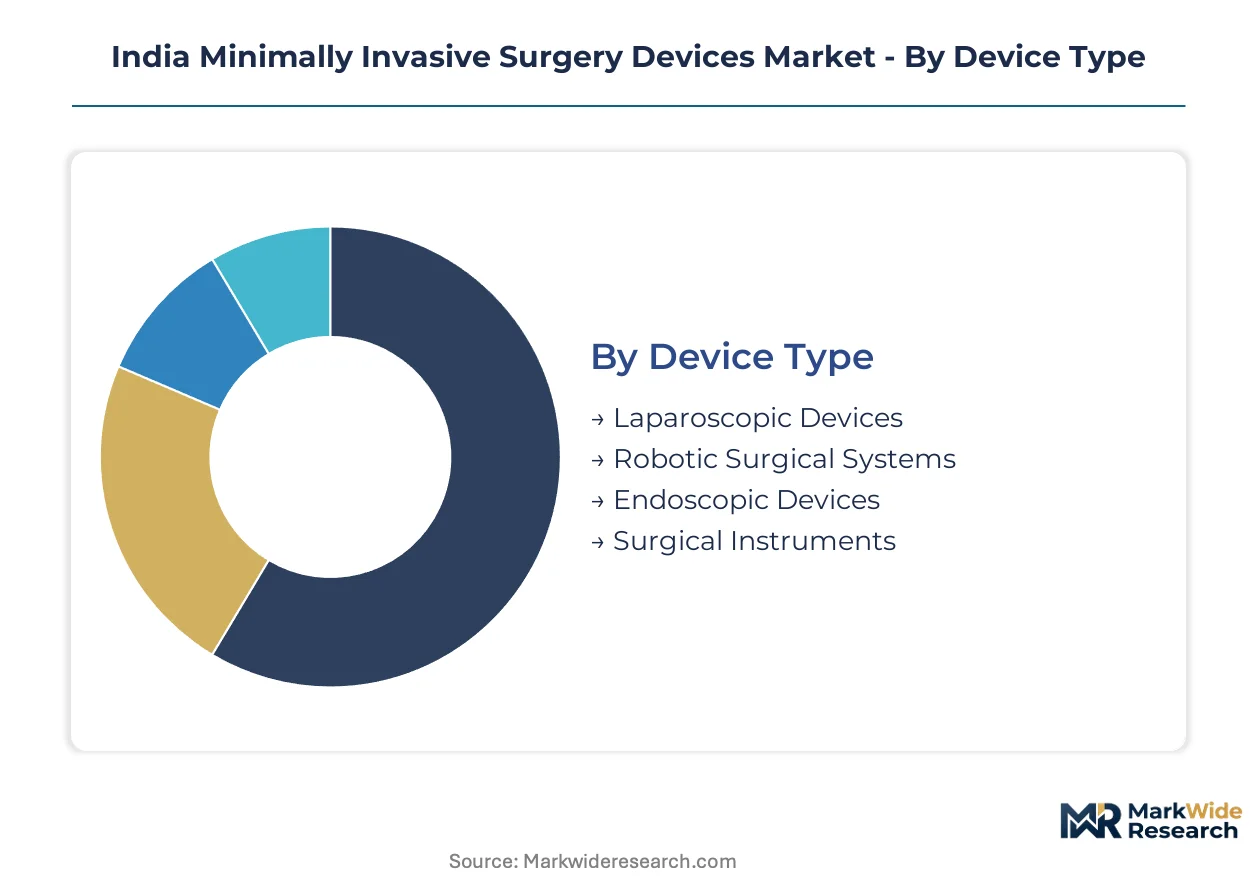
Device categorization in India's surgical market tracks the tension between established laparoscopic infrastructure and capital-intensive robotic platforms. End-user segmentation reveals divergent procurement economics between government hospital tenders and private specialty center investments.
Device Type:
Standardization dominates at the instrument level while system-level customization creates vendor lock-in and recurring revenue streams.
- Laparoscopic Devices:Trocars, graspers, and scissors manufactured to standardized shaft diameters and working lengths. Maharashtra and Karnataka hospital clusters drive replacement demand through high-volume cholecystectomy and hernia repair throughput.
- Robotic Surgical Systems:Integrated platforms combining surgeon consoles, patient-side carts, and proprietary instrument arms with haptic feedback limitations. Mumbai-Pune corridor specialty hospitals amortize capital across sufficient gynecologic and urologic procedure volumes to justify per-procedure consumable economics.
- Endoscopic Devices:Flexible scopes with CMOS imaging sensors for gastrointestinal and respiratory diagnostic-therapeutic overlap.
- Surgical Instruments:Handheld mechanical devices including retractors, needle holders, and clip appliers with limited differentiation.
Leading the category by volume: Laparoscopic Devices. Growing fastest: Robotic Surgical Systems.
End User:
Procurement authority concentrates in hospital materials management departments while ambulatory centers prioritize disposable-heavy workflows.
- Hospitals:Tertiary care centers with hybrid operating room infrastructure and fellowship-trained surgical staff. Government hospitals under National Health Mission face total cost-of-ownership caps that favor laparoscopic over robotic capital deployment.
- Ambulatory Surgical Centers:Focused facilities optimized for same-day discharge protocols and streamlined instrument sterilization workflows. Kerala's Kochi-Thiruvananthapuram corridor is expanding ASC capacity for cataract and arthroscopy procedures without legacy infrastructure burdens.
- Clinics:Limited surgical volume restricts device investment to basic laparoscopic sets and diagnostic endoscopy.
- Diagnostic Centers:Imaging-focused operations with endoscopic biopsy capability but limited therapeutic intervention scope.
Hospitals command the largest installed base. Ambulatory Surgical Centers are climbing the fastest as state health missions pilot equipment leasing models.
Technique:
Surgeon training infrastructure and reimbursement clarity determine technique adoption velocity across Indian metropolitan markets.
- Single Incision Surgery:Reduced port approaches through umbilical or natural orifice access points. Apollo Hospitals and Max Healthcare deploy these platforms for colorectal and gynecologic procedures where cosmesis drives patient preference and insurer negotiation leverage.
- Traditional Laparoscopy:Multi-port abdominal access with standardized trocar placement patterns. Two decades of training infrastructure and accessible capital tiers sustain dominance across government hospital networks.
- Robotic Assistance:Computer-enhanced instrument control with motion scaling and tremor filtration.
- Natural Orifice Surgery:Transoral, transvaginal, and transanal approaches eliminating abdominal wall incisions.
Traditional Laparoscopy retains the deepest installed base. Single Incision Surgery is gaining share fastest among premium private hospital segments.
Application:
Procedure reimbursement rates and complication risk profiles shape device selection across surgical specialties.
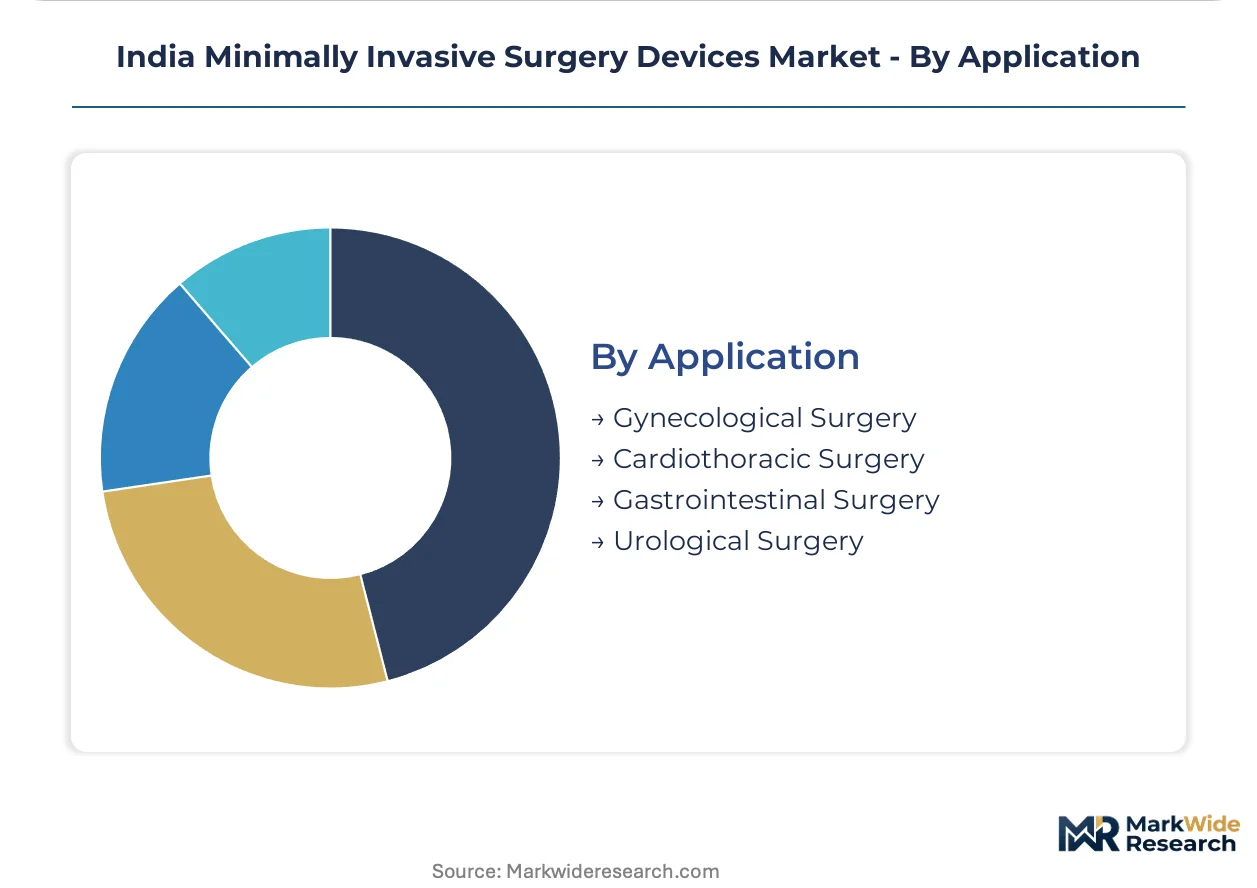
- Gynecological Surgery:Hysterectomy, myomectomy, and endometriosis excision procedures with established laparoscopic protocols. Bengaluru cluster hospitals report highest robotic system utilization rates for this application due to patient demographic concentration and elective procedure scheduling flexibility.
- Cardiothoracic Surgery:Minimally invasive valve repair and coronary bypass requiring specialized thoracoscopic instrumentation and cardiopulmonary bypass compatibility.
- Gastrointestinal Surgery:Colectomy, fundoplication, and bariatric procedures with standardized laparoscopic approaches.
- Urological Surgery:Prostatectomy and partial nephrectomy with established robotic assistance protocols.
Gynecological Surgery leads procedure volume. Cardiothoracic Surgery shows the steepest expansion trajectory as hybrid operating room capacity expands in Delhi NCR and Mumbai.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's medical device special economic zones in Gujarat and Tamil Nadu concentrate precision component manufacturing, drawing assembly operations away from pure import dependency toward localized production hubs.
Maharashtra
Mumbai-Pune corridor hospitals drive robotic system utilization through high-volume gynecologic and urologic referral networks. CDSCO's risk-based device classification compresses approval timelines for Class C and D surgical platforms entering this cluster. Specialty hospital density here amortizes capital expenditure across sufficient procedure volumes to justify per-procedure consumable economics.
Karnataka
Bengaluru's surgeon training infrastructure anchors India's deepest robotic fellowship pipeline, creating specialist concentration that gates system deployment elsewhere. State health mission procurement under the National Health Mission preferences domestically assembled laparoscopic devices in tertiary care tenders. The Bengaluru-Mysuru corridor hosts hybrid operating room construction without legacy infrastructure lock-in.
Gujarat
PLI scheme incentives for precision medical components draw German and Japanese optical suppliers to Sanand and Vadodara manufacturing zones. DGFT licensing frameworks for imported surgical equipment face shorter processing queues at Ahmedabad customs terminals versus Mumbai or Chennai. Domestic assembly operations here reduce landed cost gaps for laparoscopic instrumentation serving western India hospital networks.
Tamil Nadu
Chennai's biomedical engineering training programs supply robotic system maintenance technicians whose scarcity extends mean time to repair in northern states. State Drugs Logistics and Warehousing Corporation pilots vendor-managed consignment inventory for laparoscopic staplers, transferring inventory risk to manufacturers. The Sriperumbudur-Oragadam electronics manufacturing cluster enables camera head and imaging sensor assembly localization.
Telangana
Hyderabad's hospital expansion builds hybrid operating room capacity without sunk-cost resistance from legacy laparoscopic inventory stockpiles. State tender innovation pilots equipment leasing models that shift capital burden from upfront purchase to per-procedure fees. The Genome Valley life sciences corridor attracts interventional cardiology device assembly operations serving southern Indian markets.
India Minimally Invasive Surgery Devices Market Competitive Landscape
Top-tier vendors anchor integrated surgical ecosystems, while mid-tier specialists concentrate on single-technology platforms. The vendor base stratifies across three tiers: multinational conglomerates with full-stack surgical portfolios, regional assemblers leveraging PLI scheme incentives, and niche energy device specialists. Competitive moves concentrate on backward integration into precision component manufacturing and state-level tender pre-qualification through BIS certification pre-positioning.
Among the integrated platform providers, Medtronic PLC and Abbott Laboratories exemplify contrasting archetypes. Medtronic occupies a position representing premium system vendors with robotic console placements across metro India. Abbott exemplifies interventional cardiology-focused device suppliers sustaining catheter and closure device leadership through deep hospital relationships. Siemens AG anchors the imaging-to-navigation workflow segment, competing on hybrid operating room integration that reduces procedure variability.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Koninklijke Philips NV |
| Medtronic PLC |
| Smith & Nephew PLC |
| Stryker Corporation |
| Olympus Corporation |
| GE Healthcare |
| Zimmer Biomet |
| Siemens AG |
| Others |
Supply & Pricing Matrix
Robotic-laparoscopic cost divergence splits procurement economics across India's hospital tiers, with premium platforms commanding per-procedure leasing premiums while standardized instruments compete on landed cost. CDSCO's risk-based classification compresses approval timelines for Class C devices, shortening lead-time premiums for novel energy platforms while BIS certification queues extend pricing power for pre-certified domestic assemblers in Gujarat and Tamil Nadu corridors.
Pricing Analysis
Lead-time compression commands premium positioning in India's surgical device market, with hospitals paying 15-25% markups for six-week delivery guarantees versus standard twelve-week import cycles. Three-tier pricing structure across premium robotic consoles, standard laparoscopic sets, and economy handheld instruments reflects certification grade and after-sales service bundling. Cost compression in the economy tier intensifies as PLI scheme incentives draw component suppliers to Sanand and Vadodara manufacturing zones. Government hospital tenders under National Health Mission exhibit highest price sensitivity, while Apollo Hospitals and Max Healthcare negotiate on total cost-of-ownership metrics that amortize capital across procedure volumes.
Supply Chain Analysis
Reverse-logistics flows for robotic instrument refurbishment and endoscope reprocessing anchor aftermarket revenue streams for Medtronic and Siemens service networks. Supply concentration rests on German and Japanese optical component manufacturers for 4K imaging sensors and high-definition camera heads, with domestic assembly operations in Sriperumbudur-Oragadam reducing euro and yen exposure. Raw material dependencies span precision-machined surgical steel, CMOS imaging chips, and advanced polymers for single-use trocars. Single-source vulnerability concentrates in optical sensor supply from Sony and OmniVision fabrication facilities. Distribution runs through hospital materials management departments and state-level tender committees, with vendor-managed consignment inventory displacing capital purchase models in Tamil Nadu and Karnataka.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's minimally invasive surgery device market is consolidating around backward integration into precision component manufacturing, with PLI scheme incentives and CDSCO localization requirements forcing vendors to capture upstream optical and energy device capabilities.
For Market Incumbents: Deepen captive supply chains for CMOS imaging sensors and advanced bipolar energy generators to insulate margins from yen volatility and DGFT licensing delays. Lock in multi-year service contracts with Maharashtra and Karnataka hospital clusters before Tier-2 city expansion accelerates competitive bidding. Specialist availability constraints in northern and eastern states threaten utilization rates for deployed robotic consoles. For New Entrants and Emerging Players: Capture Kerala's Kochi-Thiruvananthapuram corridor and Telangana's Hyderabad cluster where hybrid operating room construction proceeds without legacy laparoscopic inventory lock-in. The ASC segment presents lowest competitive density, with equipment leasing models piloted by state health missions enabling per-procedure fee structures that bypass upfront capital barriers. Lead with energy device convergence platforms that integrate ultrasonic and bipolar technologies into single generators. For Investors and Strategic Acquirers: Re-rating potential sits with precision component assemblers in Gujarat and Tamil Nadu PLI corridors given CDSCO's accelerating domestic preference in state tender specifications. Long-term viability hinges on BIS certification pre-positioning and surgeon training infrastructure control. Monitor PLI scheme expansion into optical components and state-level consignment inventory adoption rates as inflection indicators for vendor margin structure shifts.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Class C/D Device Registration | Compressed approval timelines accelerate market entry for novel stapling and energy platforms in Maharashtra clusters. |
| PLI Scheme Component Localization | Domestic assembly incentives in Sanand and Vadodara reduce landed cost gaps for laparoscopic instrumentation serving western India. |
| Surgeon Training Infrastructure Investment | Bengaluru fellowship pipeline concentration creates bottleneck-gated deployment economics for robotic system vendors. |
| State Tender Consignment Models | Tamil Nadu Medical Services Corporation pilots transfer inventory risk from hospitals to manufacturers through vendor-managed stock programs. |
| Hybrid Operating Room Partnerships | Imaging-to-navigation workflow integration by Siemens and GE Healthcare reduces procedure variability in Delhi NCR tertiary centers. |
Research Methodology
CDSCO registration databases, state health mission tender records, and PLI scheme beneficiary disclosures formed the secondary backbone, cross-referenced with primary interviews across hospital purchasing committees, biomedical engineers, and GPO contracts managers. Bottom-up and top-down triangulation validated procedure volume assumptions against installed base estimates for robotic and laparoscopic platforms. Primary fieldwork concentrated on Maharashtra, Karnataka, and Tamil Nadu hospital clusters where specialty density and procurement innovation are most advanced.
Bottom-up modeling segmented the market by device type, end-user tier, and application specialty, with top-down validation against National Health Mission capital expenditure disclosures and private hospital capex announcements. CAGRs were derived from procedure volume growth trajectories and replacement cycle analysis across the projection horizon. Industry-specific forecast inputs incorporated surgeon fellowship pipeline data from Bengaluru training centers and BIS certification queue lengths at Mumbai and Delhi laboratories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PLI scheme expansion scope, state tender model adoption velocity, and specialist availability constraints outside metro corridors. Practitioners should monitor CDSCO software-as-medical-device guidance implementation and consignment inventory pilot scale-up for early signals of procurement economics shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Hearing Aids Market
Medical Devices
Transcatheter Aortic Valve Implantation (TAVI) Market
Medical Devices
Disposable Medicine Measuring Cups Market
Medical Devices
Continuous Passive Motion Devices Market
Medical Devices
PC-Based Resting Electrocardiograph Market
Medical Devices
North America Advanced Drug Delivery Systems Market
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
Intracranial Stents Total Addressable Market
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
Snare Devices Market
Medical Devices
Italy Aesthetic Devices Market
Medical Devices
APAC AMH Market
Medical Devices
Global Dermatoscope Market
Medical Devices
Canada Ultrasound Devices Market
Medical Devices
United Kingdom Contraceptive Devices Market
Medical Devices
Therapeutic Contact Lenses Market