
 Weapon Mounts Market | 2026-2036
Weapon Mounts Market Size, Share, and Industry Trends Forecast 2026-2036
Weapon Mounts Market Analysis
The gap between precision-engineered stabilized mounts and basic static brackets is expanding as defense budgets polarize around mission-critical systems versus cost-constrained auxiliary equipment. Kongsberg Gruppen ASA leverages its remote weapon station portfolio to anchor premium naval and ground vehicle programs across Scandinavian and NATO fleets. Rheinmetall AG competes through integrated turret systems that combine mounts with fire control electronics, sustaining manufacturing depth in German defense supply chains. BAE Systems plc dominates Anglo-American procurement channels through long-term platform integration contracts with the US Army and Royal Navy.
Weapon mounts are mechanical or electro-mechanical assemblies engineered to secure firearms, cannons, or missile launchers to vehicles, vessels, aircraft, or fixed emplacements, typically machined from aluminum or steel alloys to withstand recoil forces exceeding 50,000 newtons while maintaining boresight alignment under vibration and thermal stress. Their primary purpose is to stabilize firing platforms, absorb shock loads, and enable rapid target acquisition across mobile defense and security applications. Rail systems and adjustable mounts are capturing disproportionate investment as modular weapon architecture becomes standard across Western military procurement, while fixed mounts retain volume dominance in naval deck gun installations where retrofit flexibility remains limited. Composite material segments are gaining traction in unmanned aerial vehicle applications where gram-level weight reductions translate directly to endurance gains.
US Department of Defense MIL-STD-810 environmental testing requirements and NATO STANAG 4385 ballistic protection standards shape product qualification timelines and barrier entry for non-aligned suppliers. Germany's KBA and France's DGA enforce national security clearance protocols that restrict mount sourcing to domestic or EU-controlled entities, fragmenting vendor eligibility across European tenders. Stakeholders must monitor evolving ITAR export control classifications and emerging EU defense procurement reciprocity rules to anticipate which production footprints will retain contract eligibility.
Market Dynamics
Defense procurement officers now prioritize modular weapon architecture over fixed installations, compressing qualification timelines for adaptable rail systems while extending validation cycles for legacy deck mounts.
Growth Catalysts
- Defense Modernization Mandates:NATO members including Germany and Poland are retrofitting armored vehicle fleets with remote weapon stations, creating sustained demand for stabilized electro-mechanical assemblies.
- ITAR Compliance Frameworks:US export control classifications for defense articles are consolidating supplier eligibility around domestic and allied production footprints, protecting incumbent manufacturers from low-cost competition.
- Titanium-Graphite Composites:Additive manufacturing of lattice-structured mounts is reducing weight by 40% in unmanned aerial vehicle applications without sacrificing recoil absorption capacity.
Market Restraints
- Aluminum Alloy Price Volatility:Aerospace-grade 7075-T6 input costs fluctuate with energy markets, squeezing margin structures for precision-machined bracket suppliers.
- Supplier Concentration in German Industrial Basins:Rheinmetall and KNDS control critical forging capacity for large-caliber turret rings, creating single-source vulnerability for NATO ground vehicle programs.
- Ballistic Certification Timelines:NATO STANAG 4385 live-fire validation protocols extend product development cycles to 18-24 months, freezing out capital-constrained entrants.
Strategic Opportunities
- Indian Indigenous Procurement:India's Defense Acquisition Procedure 2020 prioritizes domestic weapon station production under the Make-in-India framework, opening offset partnership pathways for foreign subsystem suppliers.
- Maritime Autonomous Surface Vessels:Uncrewed naval platforms require compact, corrosion-resistant mounts for small-caliber deterrent systems, a category absent from traditional shipbuilder specifications.
- EU Defense Procurement Reciprocity:Emerging European Commission rules on cross-border defense tender access are reshaping vendor eligibility, favoring production footprints within EU member states.
Industry Challenges
- Precision Welding Talent Scarcity:Certified aluminum welders for armor-grade fabrication remain concentrated in German and US industrial clusters, constraining capacity expansion in emerging supply bases.
- Legacy Turret Integration Complexity:Retrofitting stabilized mounts into 1980s-era vehicle hulls requires custom interface engineering that defies standardization, fragmenting engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weapon Mounts Market |
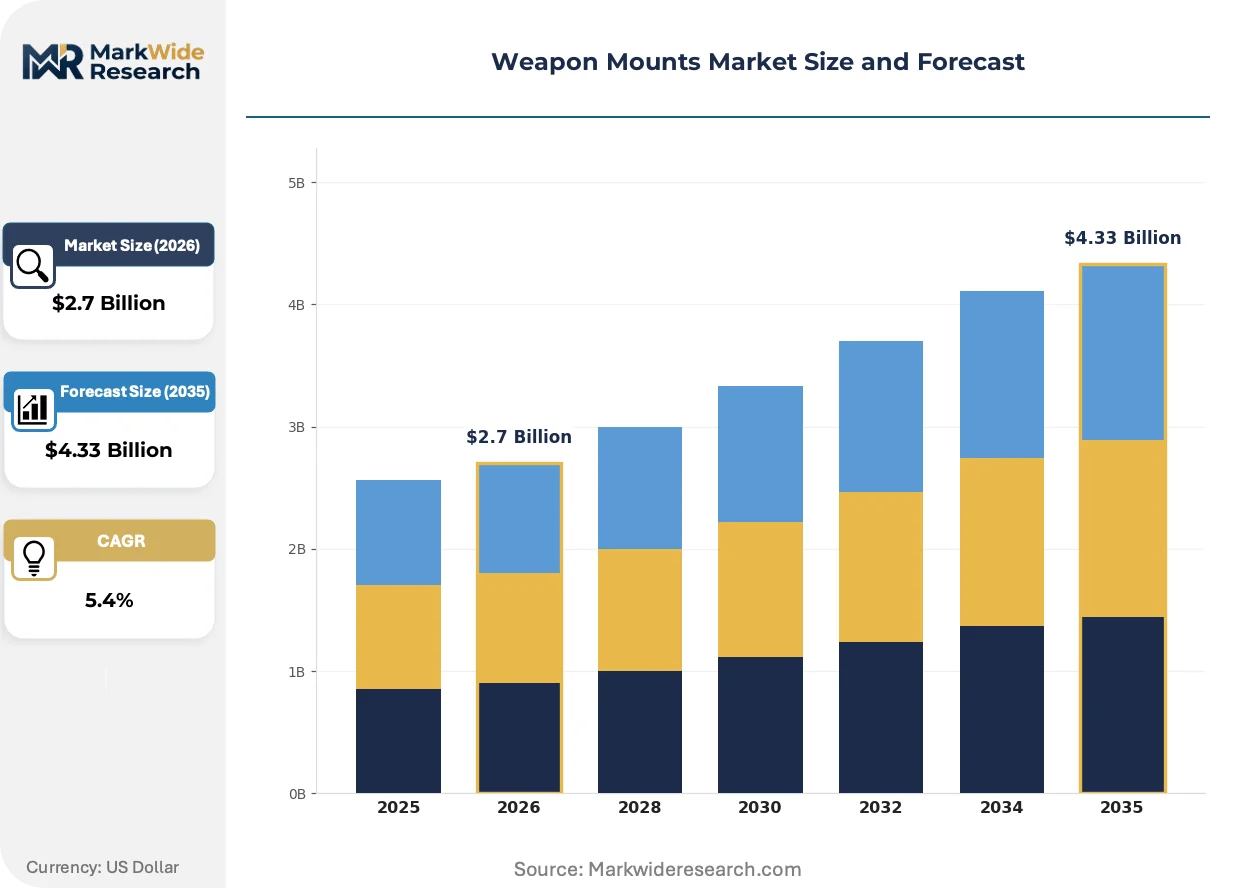
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $4.33 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Mounts, Adjustable Mounts, Rail Systems, Specialty Mounts Material: Aluminum, Steel, Polymer, Composite End User: Military, Law Enforcement, Civilian, Security Forces Application: Firearm Mounting, Tactical Operations, Sporting Events, Defense Applications |
| Companies Covered | Kongsberg Gruppen ASA, BAE Systems plc, Rheinmetall AG, Elbit Systems Ltd., RTX Corporation, FN Herstal, Leonardo S.p.A., Thales Group, General Dynamics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weapon Mounts Market Emerging Trajectories
Active stabilization algorithms and generative design software are compressing the performance gap between premium remote weapon stations and cost-optimized static mounts, forcing vendors to differentiate through integrated fire control rather than mechanical precision alone.
Carbon-fiber reinforced polymer recoil absorption systems are expanding into crew-served weapon applications previously dominated by steel forgings. French and Israeli special operations units are field-testing these assemblies for vehicle-borne heavy machine guns. The technology is expanding into conventional infantry carrier procurement channels as weight reduction becomes a decisive evaluation criterion.
REACH chemical substance restrictions are compelling European mount manufacturers to eliminate hexavalent chromium surface treatments from corrosion protection protocols. German KBA certification bodies now require alternative coating validation data prior to production approval. Suppliers with established plasma electrolytic oxidation capabilities are capturing qualification priority in French and Scandinavian naval tenders.
Lifecycle service contracts are displacing transactional hardware sales among NATO procurement agencies. Danish and Dutch defense materiel organizations now mandate 15-year availability guarantees for vehicle-integrated weapon stations, bundling mount hardware with predictive maintenance software. This shift concentrates revenue with vendors possessing integrated logistics support infrastructure across multiple European maintenance depots.
Weapon Mounts Market Segmentation
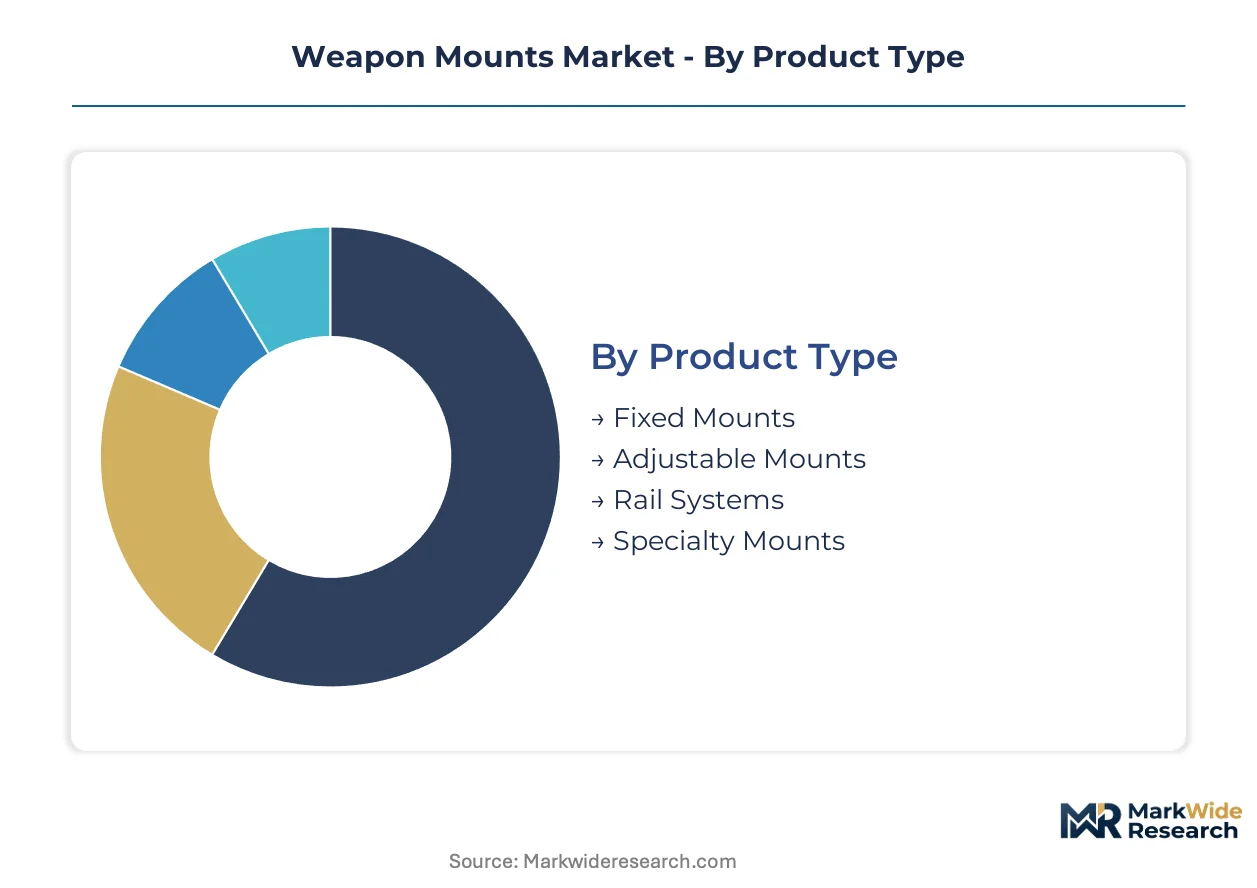
Weapon mounts demand fragments across precision-grade military systems and cost-optimized commercial equipment, with material selection and application environment dictating margin structures. Procurement officers evaluate segments through divergent qualification protocols that compress timelines for modular architectures while extending validation for legacy deck installations.
Product Type:
Fixed mounts dominate unit volume through naval deck gun installations, while rail systems command premium pricing in vehicle-integrated remote weapon stations.
- Fixed Mounts:Machined steel or aluminum assemblies permanently secured to vessel decks or vehicle hulls, engineered to withstand sustained recoil exceeding 50,000 newtons. Demand concentrates in US and German naval modernization programs where retrofit flexibility remains constrained by hull architecture. NATO STANAG 4385 ballistic certification timelines extend to 24 months, freezing out capital-constrained suppliers.
- Rail Systems:Modular quick-detach interfaces enabling rapid weapon reconfiguration across multiple platforms, typically incorporating NATO-standard 1913 or M-LOK attachment geometries. Israeli and Scandinavian special operations units drive procurement for vehicle-borne applications where mission adaptability outweighs acquisition cost. ITAR compliance frameworks protect incumbent US and allied manufacturers from price-based competition.
- Adjustable Mounts:Elevation and traverse mechanisms for crew-served weapons, balancing precision adjustment against weight penalties in armored vehicle turrets.
- Specialty Mounts:Custom-engineered solutions for unmanned platforms and non-standard weapon interfaces, requiring application-specific interface engineering.
Mature deployment sits with Fixed Mounts in conventional naval fleets. Newer deployment is concentrated in Rail Systems across NATO ground vehicle modernization.
Material:
Aluminum and steel alloys retain procurement dominance through established supply chains, while composite formulations capture share in weight-constrained unmanned applications.
- Aluminum:Aerospace-grade 7075-T6 and 6061-T6 alloys machined for precision brackets and vehicle mounts, offering strength-to-weight ratios essential for mobile platforms. German KBA and US Army TACOM specifications mandate this grade for armored vehicle applications, though energy-linked price volatility squeezes supplier margins.
- Composite:Carbon-fiber reinforced polymer and titanium-graphite lattice structures reducing mass by 40% in unmanned aerial vehicle mounts without sacrificing recoil absorption. French special operations units field-test these assemblies for vehicle-borne heavy machine guns, with expansion into conventional infantry carrier procurement channels underway.
- Steel:Forged and welded assemblies for large-caliber naval mounts where absolute stiffness outweighs weight considerations.
- Polymer:Glass-reinforced nylon formulations for commercial sporting and training equipment, excluded from military qualification pathways.
Established procurement channels favor Aluminum and Steel. Composite formulations are expanding most quickly in unmanned platform segments.
End User:
Military agencies dominate value capture through integrated turret programs, while security forces drive volume in standardized commercial derivatives.
- Military:National defense ministries procuring stabilized electro-mechanical assemblies for armored vehicle and naval combatant integration. US Department of Defense MIL-STD-810 environmental testing requirements shape product qualification timelines, with long-term platform integration contracts concentrating revenue with vendors possessing established logistics infrastructure.
- Law Enforcement:Municipal and federal tactical units requiring vehicle-mounted solutions for urban counter-threat operations, typically sourcing through commercial distributors with accelerated delivery schedules.
- Security Forces:Private and government-contracted protective services operating in high-threat environments, prioritizing cost-optimized rail systems over precision-stabilized platforms.
- Civilian:Sporting shooters and collectors purchasing commercial-grade mounts through retail channels, subject to national firearms regulations rather than defense procurement protocols.
Integrated systems revenue concentrates with Military end users. Commercial volume expansion is steepest in Security Forces procurement.
Application:
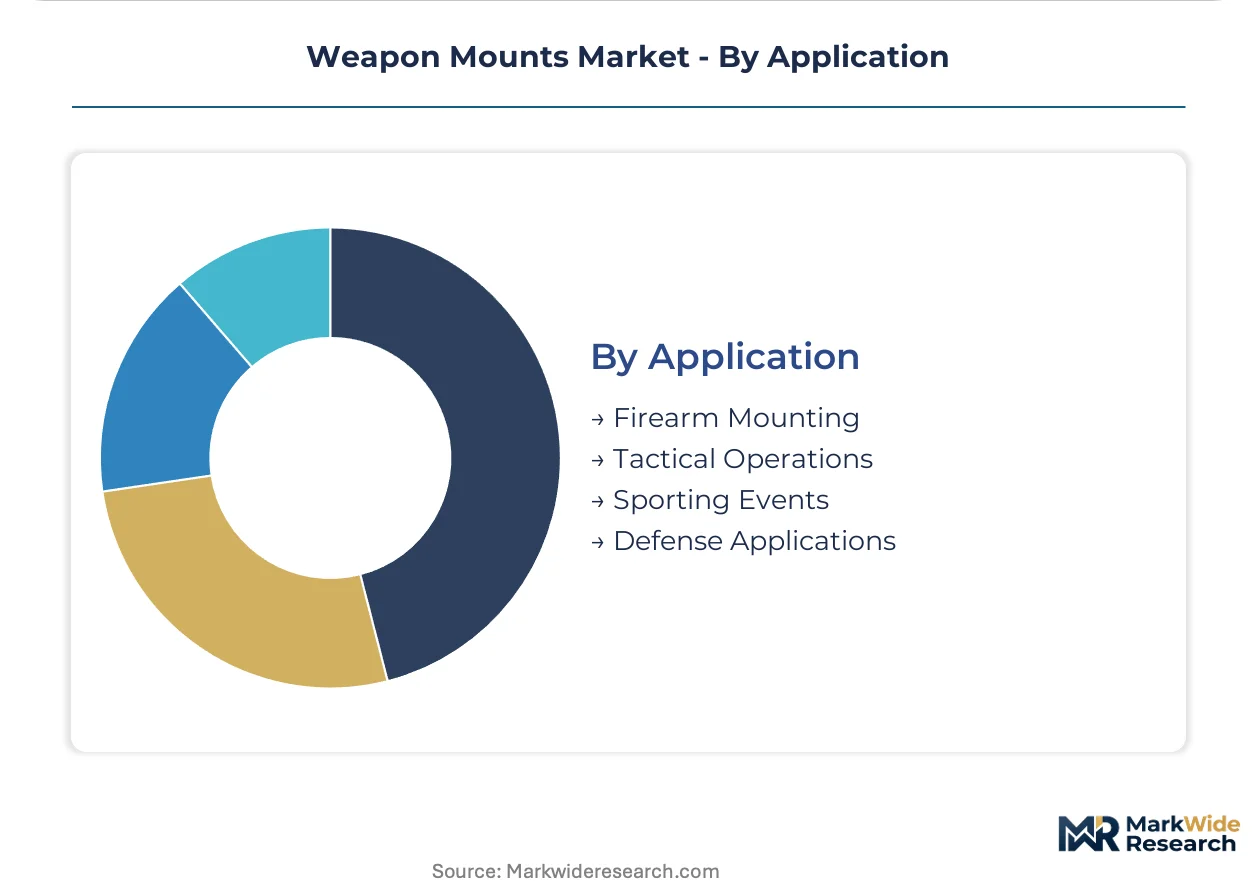
Defense Applications anchor premium pricing through fire control integration requirements, while Tactical Operations standardize around modular rail architectures.
- Defense Applications:Vehicle-integrated weapon stations and naval deck mounts combining mechanical stabilization with sensor fusion and remote operation capabilities. Danish and Dutch defense materiel organizations mandate 15-year availability guarantees, bundling hardware with predictive maintenance software.
- Tactical Operations:Rapid-deployment mounting solutions for special operations and emergency response units, emphasizing interoperability across NATO-standard small arms. German and Polish armored vehicle retrofits sustain demand for adaptable rail systems.
- Firearm Mounting:Direct-attachment solutions for individual weapons, spanning optical sight interfaces to under-barrel accessories.
- Sporting Events:Competitive shooting and hunting equipment, excluded from defense qualification pathways and subject to consumer pricing pressure.
Lifecycle service contracts dominate Defense Applications. Procurement velocity is climbing fastest in Tactical Operations as special operations units modernize vehicle fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rheinmetall's Düsseldorf headquarters anchors European weapon mount engineering, while Kongsberg's Norwegian facilities drive Scandinavian remote weapon station exports. Defense procurement concentrates in established NATO industrial corridors with specialized forging and precision machining capabilities.
United States
The US Army's TACOM specifications and Navy shipbuilding programs sustain demand for MIL-STD-810 qualified mounts. ITAR export controls consolidate supplier eligibility around domestic production footprints. Michigan and Ohio industrial clusters host precision machining capacity for armored vehicle turret rings.
Germany
KBA certification protocols restrict mount sourcing to domestic or EU-controlled entities, fragmenting vendor eligibility across European tenders. Rheinmetall and KNDS control critical forging capacity for large-caliber applications. Bavaria and North Rhine-Westphalia concentrate armor-grade fabrication expertise.
Israel
Special operations procurement drives investment in modular rail systems for vehicle-borne heavy machine guns. Domestic defense procurement mandates prioritize indigenous production under offset frameworks. Tel Aviv and Haifa technology corridors integrate electro-mechanical stabilization with fire control systems.
Poland
Armored vehicle fleet retrofits with remote weapon stations create sustained demand for NATO-standard interfaces. Defense modernization programs align procurement with EU defense reciprocity rules. Silesian industrial basins expand precision welding capacity for armor-grade fabrication.
India
The Defense Acquisition Procedure 2020 prioritizes domestic weapon station production under Make-in-India frameworks. Foreign subsystem suppliers pursue offset partnerships to access procurement channels. Tamil Nadu and Maharashtra defense corridors expand component manufacturing for vehicle-integrated systems.
Weapon Mounts Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification complexity and platform integration depth. The vendor base stratifies between integrated turret system providers and component specialists. Three archetypes dominate: defense primes with logistics infrastructure, mid-tier specialists in electro-mechanical stabilization, and regional fabricators serving national procurement mandates. Competitive moves concentrate on qualification timeline compression and lifecycle service contract bundling.
Within the integrated systems tier, Kongsberg Gruppen ASA and Rheinmetall AG exemplify archetypes anchoring premium naval and ground vehicle programs across Scandinavian and NATO fleets. BAE Systems plc occupies a position reflecting long-term platform integration relationships with Anglo-American procurement channels. These three represent distinct competitive vectors: Norwegian remote weapon station specialization, German manufacturing depth in turret systems, and UK-US transatlantic logistics infrastructure.
| Leading Market Players |
|---|
| Kongsberg Gruppen ASA |
| BAE Systems plc |
| Rheinmetall AG |
| Elbit Systems Ltd. |
| RTX Corporation |
| FN Herstal |
| Leonardo S.p.A. |
| Thales Group |
| General Dynamics Corporation |
| Others |
Supply Flow & Price Mechanics
REACH chemical substance restrictions gate qualified supply for European naval tenders while compressing margin structures for vendors lacking plasma electrolytic oxidation capabilities. Premium-tier pricing access now requires validated alternative coating data submitted to German KBA certification bodies before production approval.
Pricing Analysis
Lifecycle service contracts anchored to 15-year availability guarantees command premium positioning above transactional hardware sales. Three-tier pricing structure across integrated turret systems, component subsystems, and commercial rail assemblies reflects certification depth and platform integration scope. Cost compression in aluminum alloy inputs intensifies margin pressure on precision-machined bracket suppliers serving NATO ground vehicle programs. Security forces procurement exhibits highest price sensitivity, while Danish and Dutch defense materiel organizations demonstrate lowest sensitivity due to bundled predictive maintenance requirements.
Supply Chain Analysis
India's Defense Acquisition Procedure 2020 domestic-content mandates are reshaping sourcing footprints for foreign subsystem suppliers pursuing offset partnerships. Critical forging capacity for large-caliber turret rings concentrates in Germany, with secondary machining clusters in the United States and emerging welding capacity in Poland's Silesian industrial basins. Aerospace-grade 7075-T6 aluminum, carbon-fiber reinforced polymer formulations, and titanium-graphite lattice structures constitute primary material dependencies. Single-source vulnerability around Rheinmetall and KNDS-controlled forging capacity creates structural supply risk for NATO armored vehicle programs. Distribution runs through defense primes with established logistics infrastructure across multiple European maintenance depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified aluminum welders for armor-grade fabrication remain concentrated in German and US industrial clusters, propping pricing power for vendors possessing captive welding capacity.
For Market Incumbents: Deploy lifecycle service contract bundling to lock in Danish and Dutch defense materiel organizations through 15-year availability guarantees. Anchor premium positioning by deepening backward integration into plasma electrolytic oxidation coating capabilities ahead of REACH compliance deadlines. Carbon-fiber reinforced polymer recoil absorption systems from emerging French and Israeli suppliers threaten mechanical precision differentiation. For New Entrants and Emerging Players: Maritime autonomous surface vessel programs represent an underserved buyer archetype lacking established mount specifications from traditional shipbuilders. Uncrewed naval platforms require compact, corrosion-resistant mounts for small-caliber deterrent systems absent from conventional procurement channels. Pursue qualification pathway compression through modular rail system architectures rather than legacy deck mount validation cycles. For Investors and Strategic Acquirers: EU defense procurement reciprocity rule finalization is the leading indicator that production footprint eligibility will concentrate contract access within EU member states. Long-term viability over the projection horizon favors vendors with integrated logistics support infrastructure spanning multiple European maintenance depots. Acquisition target archetype: mid-tier specialists in electro-mechanical stabilization possessing established KBA or DGA security clearance protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Electrolytic Oxidation Certification | REACH-compliant coating validation secures priority access to French and Scandinavian naval tenders. |
| Offset Partnership Structuring | Make-in-India framework compliance unlocks Defense Acquisition Procedure 2020 procurement channels. |
| Lifecycle Service Contract Bundling | 15-year availability guarantees align with Danish and Dutch defense materiel organization mandates. |
| Additive Manufacturing Scale-Up | Titanium-graphite lattice production reduces UAV mount mass by 40% without recoil absorption sacrifice. |
| Precision Welding Capacity Expansion | Certified aluminum welder pools in Poland's Silesian basins address NATO armored vehicle program bottlenecks. |
Methodological Framework
Defense procurement databases, NATO STANAG certification records, and customs trade data formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with program managers at defense materiel organizations, procurement officers at national defense ministries, platform integration engineers at armored vehicle OEMs, and aftermarket service heads at maintenance depots validated demand assumptions. Bottom-up unit demand modeling triangulated against top-down defense budget allocation analysis across the analysis window.
Historical trendline analysis of remote weapon station procurement volumes informed baseline trajectory establishment. Segmentation modeling spanned product type, material formulation, end-user agency tier, and application environment complexity. CAGRs derived from weighted regression across platform modernization schedules and offset partnership formation timelines. Forecast inputs incorporated ITAR compliance framework evolution and EU defense procurement reciprocity rule progression.
Revisions become necessary when aluminum alloy price volatility exceeds historical bands or when ballistic certification timelines extend beyond 24-month baselines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Sniper Rifle Market
Weapons and Ammunition
Directed Energy Weapons Market
Weapons and Ammunition
Asia-Pacific Cruise Missile Market
Weapons and Ammunition
Small Caliber Ammunition Market
Weapons and Ammunition
Detonator Market
Weapons and Ammunition
Medium Caliber Ammunition Market
Weapons and Ammunition
US Small Caliber Ammunition Market
Weapons and Ammunition
Military Helmet Market
Weapons and Ammunition
Military Fuze Market
Weapons and Ammunition
North America Small Arms Market
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
Artillery Ammunition Market
Weapons and Ammunition
Hypersonic Missile Market
Weapons and Ammunition
Surface to Air Missiles Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Enclosed Smokeless Flares Market