
 Directed Energy Weapons Market | 2026-2036
Directed Energy Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
Directed Energy Weapons Market Analysis
ISO 14253 tolerance certification for optical component manufacturing is collapsing the supplier base eligible for prime-tier contracts. Lockheed Martin Corporation leverages captive crystal growth and coating facilities to sustain beam quality advantages in high-energy laser assemblies. Raytheon Technologies Corporation competes through integrated power-and-thermal management architectures that reduce platform footprint for naval installations.
Directed energy weapons are systems that generate and focus electromagnetic radiation or particle streams to deliver precise, scalable effects against targets at the speed of light, with power levels ranging from kilowatts for sensor denial to multi-megawatt classes for structural defeat of missiles and aircraft. Their primary purpose is to provide deep-magazine, cost-per-shot-efficient alternatives to kinetic interceptors against saturation threats including drone swarms and hypersonic vehicles. Laser technology dominates current procurement budgets due to maturing solid-state and fiber architectures, while microwave platforms are gaining traction for area denial against electronics-dependent threats. Naval platform integration commands the largest share of funded programs, though airborne self-protection systems represent the fastest-expanding application segment as podded configurations achieve tactical aircraft compatibility.
The U.S. Department of Defense directs requirements through the Missile Defense Agency and service-specific rapid capabilities offices, with export control via ITAR restricting technology transfer to allied nations. European procurement frameworks under the European Defence Fund and Permanent Structured Cooperation are creating alternative qualification pathways that reduce transatlantic supplier concentration. Stakeholders must monitor whether congressional appropriations for directed energy transition from prototyping lines to multi-year production contracts, as this shift will determine which platform-technology combinations achieve operational scale versus remaining experimental.
Market Dynamics
ISO 14253 tolerance certification for optical component manufacturing is collapsing the supplier base eligible for prime-tier contracts, compressing procurement timelines and elevating captive production advantages for systems integrators with in-house crystal growth capabilities.
Growth Catalysts
- Replicator Initiative:The U.S. Department of Defense's rapid prototyping directives compress development timelines for deployable directed energy platforms, accelerating field testing cycles.
- Solid-state laser maturation:Fiber and diode-pumped architectures achieve tactical power thresholds for counter-drone missions, expanding addressable threat sets.
- Pacific theater readiness:Naval fleets across NATO members expand procurement of high-energy laser systems for missile defense, concentrating demand in maritime platforms.
Market Restraints
- Optical supply concentration:ISO 14253 certification requirements restrict qualified suppliers to a handful of specialty manufacturers, creating single-source vulnerabilities.
- Power-thermal integration costs:Multi-megawatt cooling systems require rare-earth heat exchanger materials subject to price volatility and export licensing delays.
- ITAR friction:U.S. export controls block technology transfer to allied nations, fragmenting procurement frameworks and duplicating development costs across jurisdictions.
Strategic Opportunities
- Airborne podded configurations:Tactical aircraft compatibility for self-protection systems opens faster-expanding application segments beyond naval dominance.
- European Defence Fund pathways:Permanent Structured Cooperation creates alternative qualification routes that reduce transatlantic supplier concentration.
- Microwave area denial:Electronics-defeat missions against drone swarms converge with cyber-physical warfare doctrines, broadening platform addressability.
Industry Challenges
- Beam control engineering scarcity:Adaptive optics and atmospheric compensation expertise concentrates in national laboratories, limiting private-sector workforce pipelines.
- Multi-year production transition:Congressional appropriations remain trapped in prototyping lines, delaying operational scale for platform-technology combinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Directed Energy Weapons Market |
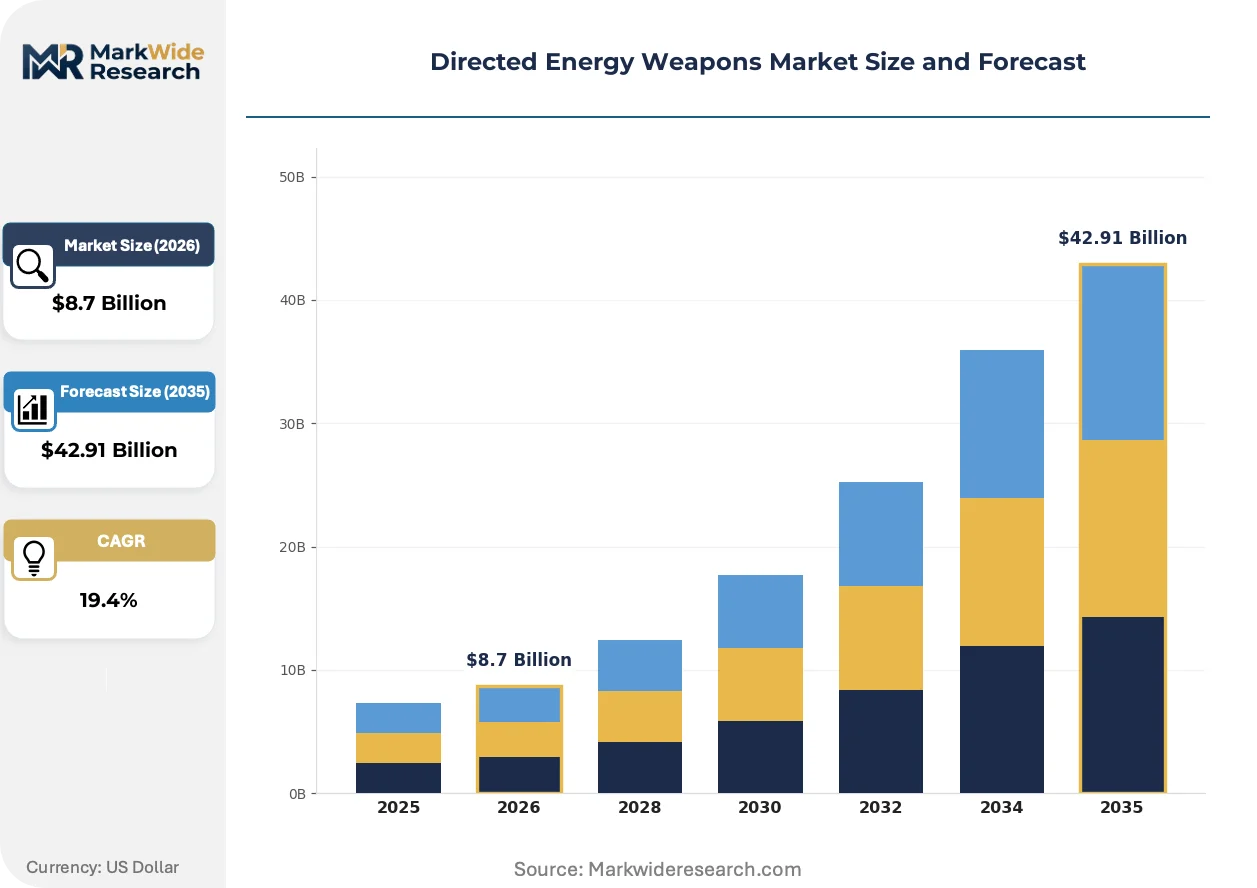
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Laser, Microwave, Particle Beam, Acoustic Application: Military, Defense, Law Enforcement, Commercial Platform: Airborne, Ground-based, Naval, Space Power Source: Batteries, Solar, Diesel, Nuclear |
| Companies Covered | The Boeing Company, L3Harris Technologies, Inc., Lockheed Martin Corporation, Rheinmetall AG, General Atomics, Raytheon Technologies Corporation, BAE Systems plc, Thales Group, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Directed Energy Weapons Market Emerging Trajectories
Solid-state and fiber laser architectures are fragmenting competitive positioning across power classes, while procurement frameworks splinter between rapid-fielding directives and traditional acquisition cycles. Three forces dominate near-term trajectory.
Fiber laser technology is fragmenting the high-energy segment as kilowatt-class systems achieve tactical aircraft pod integration. Air Force rapid capabilities offices accelerate test schedules for self-protection suites. The technology is fragmenting prime contractor dominance by enabling mid-tier suppliers with specialized beam-combining expertise to capture subsystem awards.
EU Green Deal industrial policy is redirecting defense innovation funding toward dual-use energy infrastructure, tightening eligibility for pure weapons-platform grants. European Defence Fund calls now require civil-military technology spillover demonstrations. Naval laser programs in France and Germany respond by emphasizing port-energy applications to secure co-finance.
Buyers are compressing switching cycles between prototype and production contracts, demanding operational data packages before multi-year commitments. Traditional milestone-based procurement is yielding to spiral development with field-insertion checkpoints. This pattern concentrates in U.S. Pacific theater commands where threat saturation timelines override standard acquisition hygiene.
Directed Energy Weapons Market Segmentation
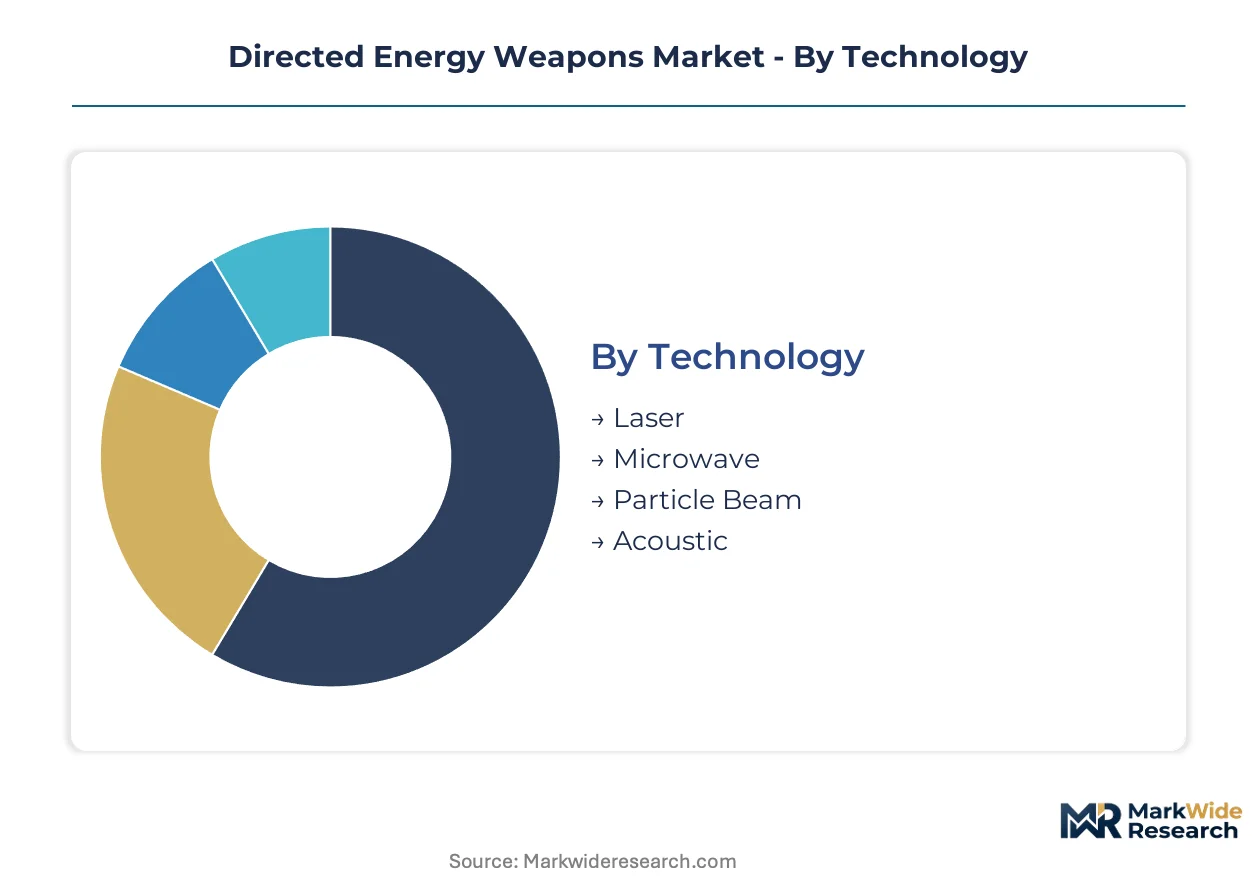
Segmentation in directed energy weapons determines procurement eligibility, platform integration costs, and operational deployment timelines. Technology and platform choices dictate supply chain requirements, while application scope sets regulatory boundaries under ITAR and allied export frameworks.
Technology:
Substitution pressure from conventional kinetic interceptors remains highest for immature particle beam architectures, while solid-state laser systems face the weakest substitute threat due to proven counter-drone performance.
- Laser:Solid-state and fiber architectures dominate current procurement, delivering kilowatt to multi-megawatt outputs through diode-pumped configurations. Naval fleets across NATO members concentrate demand for counter-drone and missile defense missions, with Pacific theater readiness requirements accelerating field testing.
- Microwave:High-power microwave systems generate electromagnetic pulses for electronics defeat against drone swarms and sensor networks. Area denial applications are gaining traction under cyber-physical warfare doctrines, broadening platform addressability beyond structural kill missions.
- Particle Beam:Charged particle acceleration remains experimental for tactical applications, constrained by atmospheric scattering and massive power requirements.
- Acoustic:Directed sound energy platforms serve non-lethal crowd control and vessel interdiction roles with limited weapons-class penetration.
Laser technology anchors the volume base while microwave platforms gain share at the steepest rate.
Application:
Cost tier stratification separates multi-billion-dollar military programs from constrained law enforcement budgets, with defense applications occupying the mid-tier funding band.
- Military:Offensive strike and force protection missions drive the largest procurement volumes, requiring hardened systems for contested electromagnetic environments. The U.S. Department of Defense's Replicator initiative compresses development timelines for deployable platforms.
- Defense:Missile defense and airbase protection represent institutionalized procurement lines with established testing infrastructure. Congressional appropriations for these programs remain concentrated in prototyping phases, delaying operational scale.
- Law Enforcement:Non-lethal directed energy systems for riot control and perimeter security operate under stricter use-of-force protocols.
- Commercial:Maritime piracy deterrence and critical infrastructure protection constitute emerging demand pockets with fragmented purchasing authority.
Defense applications anchor the volume base while military programs expand most quickly under rapid-fielding directives.
Platform:
Integration complexity varies dramatically by mobility requirements, with airborne configurations demanding the most severe weight and thermal constraints.
- Naval:Surface combatants provide stable power generation and thermal management capacity for multi-megawatt installations. NATO naval fleets are expanding procurement of high-energy laser systems, with shipboard integration commanding the largest share of funded programs.
- Airborne:Podded configurations for tactical aircraft self-protection represent the fastest-expanding application segment as fiber laser systems achieve tactical power thresholds. Air Force rapid capabilities offices accelerate test schedules for self-protection suites.
- Ground-based:Fixed-site missile defense and expeditionary counter-drone systems leverage trailer-mounted or vehicle-integrated architectures.
- Space:Orbital power-beaming and satellite defense concepts remain pre-prototyping, constrained by launch mass limitations and treaty considerations.
Naval platforms anchor the volume base while airborne systems climb the fastest toward operational deployment.
Power Source:
Supply concentration in rare-earth heat exchanger materials creates single-source vulnerabilities for high-output diesel and nuclear configurations.
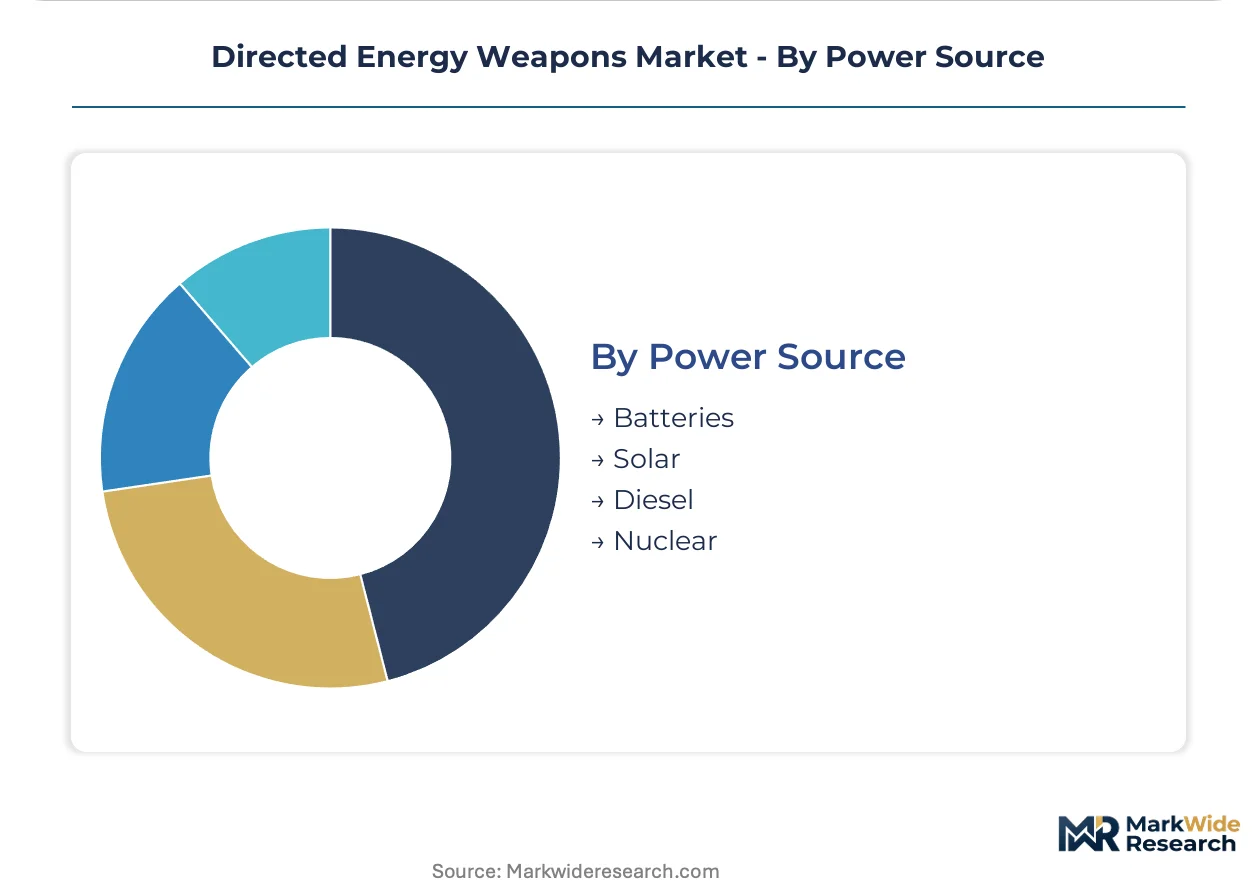
- Diesel:Tactical generators provide field-proven power density for expeditionary ground and naval platforms, though fuel logistics burden operational tempo.
- Batteries:Solid-state and flow battery architectures enable silent operations for short-duration engagements, with energy density improvements expanding mission envelopes.
- Solar:Photovoltaic arrays serve persistent low-power applications and orbital platforms with unlimited endurance potential.
- Nuclear:Compact reactor concepts for megawatt-class shipboard lasers remain in early development, blocked by regulatory and safety certification timelines.
Diesel systems anchor the volume base while battery architectures show the steepest expansion trajectory for tactical mobility applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Department of Defense's Replicator initiative and Pacific theater readiness requirements are concentrating procurement acceleration in specific national defense ecosystems. NATO naval modernization programs and alternative European qualification pathways are redistributing supplier access across jurisdictions.
United States
Naval fleet expansion for counter-drone and missile defense missions drives procurement concentration. The Missile Defense Agency and service-specific rapid capabilities offices direct requirements through ITAR-controlled channels. California and Virginia defense corridors host prime-tier systems integrators with captive crystal growth facilities.
Germany
Rheinmetall AG anchors European high-energy laser development for naval platform integration. The European Defence Fund and Permanent Structured Cooperation create alternative qualification pathways that reduce transatlantic supplier concentration. Bavaria and North Rhine-Westphalia host dual-use energy infrastructure projects securing co-finance for defense applications.
France
Port-energy applications for naval laser programs emphasize civil-military technology spillover demonstrations required by EU Green Deal industrial policy. The European Defence Fund tightens eligibility for pure weapons-platform grants. Provence-Alpes-Côte d'Azur and Île-de-France clusters advance shipboard integration with shore-power compatibility.
United Kingdom
BAE Systems plc and Thales Group operations support NATO interoperability requirements for directed energy platforms. Export control alignment with ITAR frameworks maintains transatlantic technology access. Southeast England and Scotland host beam control engineering expertise concentrated in national laboratory partnerships.
Israel
Airborne self-protection systems and counter-drone applications drive rapid field-testing cycles outside formal NATO procurement structures. Domestic defense innovation funding operates independently of European Defence Fund civil-military requirements. Tel Aviv and Haifa corridors specialize in adaptive optics and atmospheric compensation subsystems.
Directed Energy Weapons Market Vendor Landscape
Player mix skews toward vertically integrated defense primes with captive optical component manufacturing. The supplier base compresses under ISO 14253 tolerance certification requirements that disqualify specialty manufacturers lacking prime-tier contract eligibility. Three archetypes dominate: systems integrators with in-house crystal growth, power-and-thermal management specialists, and beam-combining subsystem providers. Competitive moves concentrate on strategic partnerships for rare-earth heat exchanger supply security and spiral development contracts with field-insertion checkpoints.
Among U.S.-based defense primes, Lockheed Martin Corporation and Raytheon Technologies Corporation exemplify contrasting integration strategies. Lockheed Martin Corporation leverages captive production advantages in high-energy laser assemblies. Raytheon Technologies Corporation competes through integrated architectures reducing platform footprint. Rheinmetall AG represents the European archetype navigating EU Green Deal dual-use funding requirements.
| Leading Market Players |
|---|
| The Boeing Company |
| L3Harris Technologies, Inc. |
| Lockheed Martin Corporation |
| Rheinmetall AG |
| General Atomics |
| Raytheon Technologies Corporation |
| BAE Systems plc |
| Thales Group |
| Northrop Grumman Corporation |
| Others |
Supply Flow & Price Mechanics
Spiral development contracts with field-insertion checkpoints lock in multi-year supply commitments for rare-earth heat exchanger materials while capping price volatility exposure for naval platform integrators. This structure concentrates procurement leverage with systems integrators possessing captive crystal growth facilities, compressing margins for non-certified optical component suppliers.
Pricing Analysis
Certification level under ISO 14253 tolerance standards creates the primary spread between prime-tier and specialty-tier contract awards. Project-based pricing dominates high-energy laser assemblies, with three-tier pricing structure across prime-integrator, subsystem-specialist, and component-supplier levels. Cost compression in fiber laser subsystems is intensifying because mid-tier beam-combining specialists are capturing awards from vertically integrated primes. Defense rapid capabilities offices show least price sensitivity due to threat saturation timelines, while commercial maritime applications exhibit highest sensitivity to capital expenditure thresholds.
Supply Chain Analysis
The United States and Germany anchor high-grade optical component fabrication, with Israel specializing in adaptive optics subsystems. Supply chains draw from rare-earth mining concentrates in Australia and refined neodymium-doped yttrium aluminum garnet crystal boules from specialty growers. Single-source vulnerability concentrates in ITAR-restricted coating facilities for naval laser assemblies. Distribution runs through defense prime captive production networks and European Defence Fund co-financed dual-use pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-technology fragmentation creates entry niches as fiber laser maturation enables mid-tier subsystem specialists to displace prime-tier dominance in tactical aircraft pod integration.
For Market Incumbents: Compound captive production advantages by securing long-term offtake agreements for rare-earth heat exchanger materials before congressional appropriations shift from prototyping to production. Deepen backward integration into diode-pumped crystal growth to neutralize ISO 14253 supplier compression. Prioritize spiral development contract capture with Pacific theater commands to lock out beam-combining specialists. For New Entrants and Emerging Players: Post-contract aftermarket support for atmospheric compensation calibration represents the most penetrable service-layer gap where Lockheed Martin and Raytheon maintain minimal field presence. Target airborne self-protection system retrofits for legacy tactical aircraft fleets requiring podded laser integration without platform redesign. Establish go-to-market positioning through Air Force rapid capabilities office test-range partnerships rather than traditional milestone-based procurement channels. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier specialists with beam-combining intellectual property and existing ITAR facility clearances. Long-term viability hinges on whether congressional appropriations achieve multi-year production contract scale or remain trapped in prototyping cycles. Monitor European Defence Fund call outcomes for dual-use energy infrastructure co-finance as the inflection signal for transatlantic supplier access redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Crystal Growth Facility Expansion | ISO 14253 certification collapse eliminates non-integrated suppliers from prime-tier eligibility. |
| Rare-Earth Heat Exchanger Supply Agreement | Multi-megawatt naval lasers rest on neodymium supply security amid export licensing delays. |
| Airborne Podded Configuration Development | Fiber laser tactical power thresholds unlock fastest-expanding application segment beyond naval dominance. |
| European Defence Fund Qualification Pathway | Permanent Structured Cooperation reduces transatlantic supplier concentration for NATO interoperability. |
| Spiral Development Contract Capture | Pacific theater readiness requirements override standard acquisition hygiene for field-insertion checkpoints. |
Methodological Framework
A standing panel of program executive officers at service-specific rapid capabilities offices, beam control engineering leads at national laboratories, naval fleet laser integration managers, and European Defence Fund grant administrators provided ongoing calibration across primary interviews. Secondary validation drew from Missile Defense Agency budget justification materials, SEC 10-K filings from listed defense primes, ITAR-controlled contract award databases, and NATO procurement transparency reports. Bottom-up segment sizing triangulated against top-down defense appropriations analysis.
Consistency checks validated volume and value outputs against independent benchmarks from defense trade publications and congressional research service assessments. The analytical framework modeled technology substitution dynamics, platform integration complexity tiers, power class segmentation, and regional procurement framework variations across the projection horizon. CAGRs derived from year-over-year contract award velocity and production ramp assumptions, with specific inputs including Replicator initiative funding trajectories and Pacific theater operational test schedules.
Underlying assumptions cover congressional appropriation continuity for directed energy prototyping lines, with deviation risk concentrated in ITAR regulatory friction and rare-earth supply export licensing delays. Forecasts reflect these conditions without scenario weighting. Recalibration cycles align with material shifts in defense authorization act markup outcomes and European Defence Fund call announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Military Helmet Market
Weapons and Ammunition
Global Small Arms and Light Weapons (SALW) Market
Weapons and Ammunition
Light Weapons Market
Weapons and Ammunition
Next-Generation Assault Rifles Market
Weapons and Ammunition
Electromagnetic Weapons Market
Weapons and Ammunition
Command Fuzes Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Electrical Weapon Market
Weapons and Ammunition
Man-Portable Anti-Armor Weapons Market
Weapons and Ammunition
Guided Munitions Market
Weapons and Ammunition
Man-Portable Rocket Launcher Market
Weapons and Ammunition
Shotgun and Rifles Market
Weapons and Ammunition
Explosives for Civil Uses Market
Weapons and Ammunition
NIJ III Ballistic Bullet Resistant Panel Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Nuclear Bombs and Missiles Market