
 Detonator Market | 2026-2036
Detonator Market Size, Share, and Industry Trends Forecast 2026-2036
Detonator Market Intelligence
The UN's model regulations on the transport of dangerous goods is pivoting the cost-of-entry calculus for detonator logistics and handling. Orica Limited leverages its global footprint to navigate these complex compliance requirements. Dyno Nobel differentiates with its focus on advanced electronic initiation systems for North American mining. Solar Industries India anchors its position through large-scale production capacity serving both domestic and export markets.
A detonator is a small device used to initiate a larger, less sensitive secondary explosive. These devices typically contain a small charge of a primary explosive, such as lead azide, which is initiated by heat, shock, or an electrical impulse. Electronic detonators are displacing traditional non-electric and electric types, offering superior timing accuracy for complex blasts. The mining application, encompassing coal and mineral extraction, constitutes the largest end-use segment by a significant margin.
Market access is governed by stringent safety and security protocols enforced by bodies like the US Bureau of Alcohol, Tobacco, Firearms and Explosives (ATF) and Australia's state-level mining safety regulators. CE marking under the European Union's directive on civil explosives is mandatory for products sold within the bloc. A key strategic decision for end-users involves weighing the higher upfront investment in programmable systems against the long-term benefits of improved fragmentation and operational efficiency.
Market Dynamics
The transition from conventional to programmable electronic detonators is the central force redefining the market. This shift prioritizes blast precision and data-driven optimization, particularly within large-scale extractive industries, influencing both technology investment and operator skill requirements.
Growth Catalysts
- Programmable Systems:Enhanced control over blast timing with electronic detonators improves rock fragmentation, reducing downstream processing costs for mining operations.
- Infrastructure Growth:Global public works projects sustain demand for detonators in quarrying and civil engineering, particularly in fast-developing Asian economies.
- Mining Modernization:Mandates in Chile and Australia for safer technologies accelerate adoption of advanced initiation systems in the extractive sector.
Market Restraints
- Logistical Complexity:Stringent UN model regulations on transporting dangerous goods create significant cost and compliance overhead for global supply chains.
- High Capital Outlay:The substantial upfront investment for electronic initiation systems and associated training presents a barrier for smaller operators.
- Input Material Sensitivity:Production costs are exposed to price volatility and supply disruptions for key primary explosive compounds like lead azide.
Strategic Opportunities
- Specialized Demolition:Requirements for controlled demolition in dense urban environments create a niche for precise, low-vibration electronic detonator applications.
- IoT Integration:Embedding wireless connectivity into detonator systems offers a pathway to real-time blast monitoring and performance data analytics.
- Service Model Expansion:Developing bundled service offerings including blast design and support can unlock value in markets with limited in-house expertise.
Industry Challenges
- Skilled Labor Scarcity:A shortage of technicians certified to operate sophisticated programmable electronic initiation systems constrains effective deployment and use.
- Regulatory Fragmentation:Manufacturers must navigate a patchwork of safety protocols, from the US ATF to Australian state regulators, increasing compliance costs.
- Legacy System Integration:Ensuring interoperability between new electronic detonators and older, existing blasting equipment on a site can be technically complex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Detonator Market |
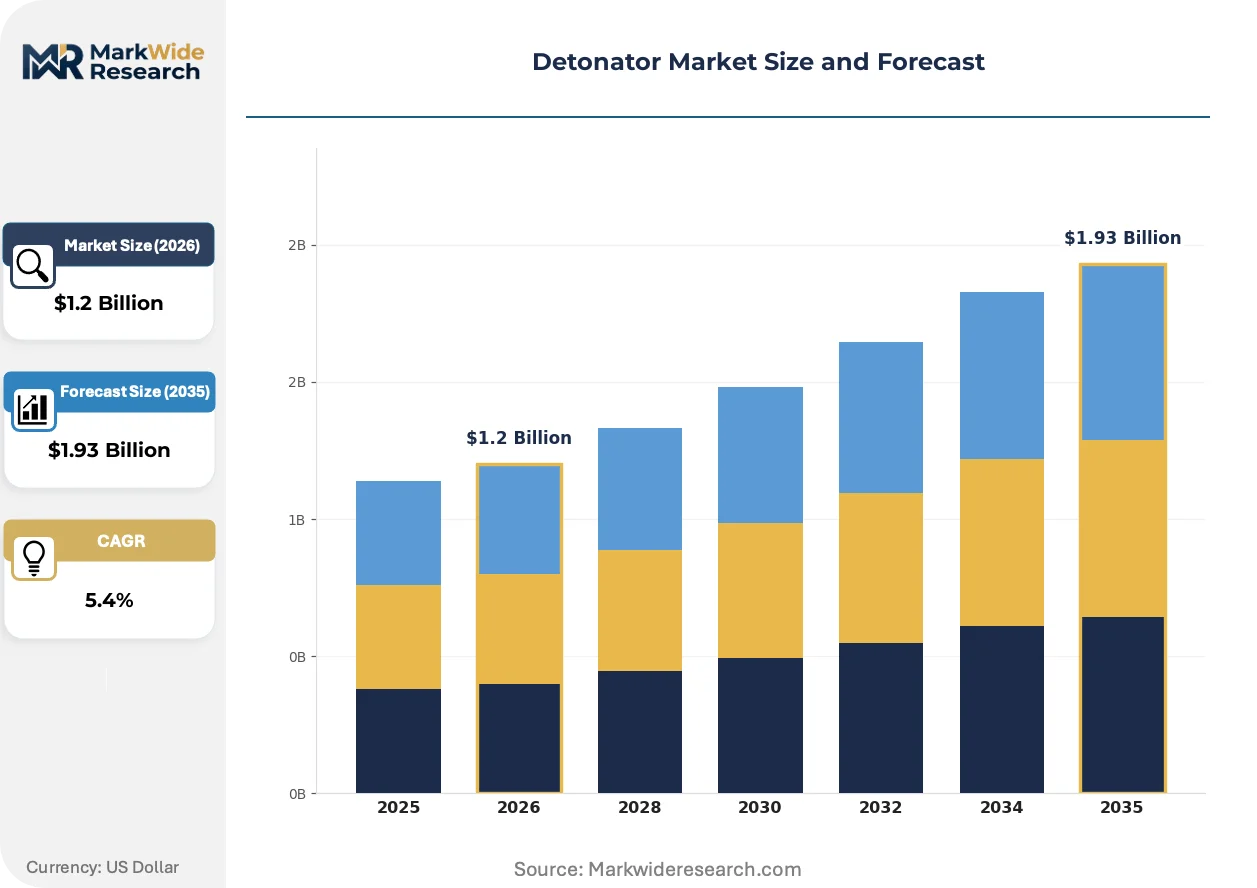
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $1.93 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Non-Electric, Electronic, Delay, Shock Tube Technology: Instantaneous, Timed, Programmable, Encapsulated, Non-Encapsulated Application: Mining, Quarrying, Construction Blasting, Fireworks Manufacturing, Demolition End User Industry: Extractive Sector, Civil Engineering, Ordnance Factories, Pyrotechnics, Explosive Manufacturers |
| Companies Covered | MAXAM, Hanwha Corporation, Orica Limited, Solar Industries India, AEL Mining Services, Austin Powder, Enaex, Ensign-Bickford Aerospace & Defense Company, Dyno Nobel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Detonator Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of digital control and physical initiation. This integration enhances safety protocols, enables new operational models, and tightens the link between blast design and real-world outcomes.
Wireless initiation systems eliminate the need for physical downlines, using radio signals to communicate with in-hole detonators. Major open-pit mining operations are the primary adopters, seeking to improve safety and operational speed. This technology is absorbing the labor and risk associated with wiring complex blast patterns, reducing setup times and mitigating misfires.
European Union directives for civil explosives, requiring CE marking, increasingly emphasize full lifecycle traceability. This mandate compels manufacturers to implement secure track-and-trace systems for each detonator. All suppliers targeting the EU market are affected, investing in digital serialization and database management to comply with anti-diversion goals.
A behavioral change toward procuring integrated blasting solutions is gaining traction over simple component purchasing. This disrupts the traditional sales model, with suppliers offering packages including blast design software and post-blast analysis. This trend is most advanced within large-scale mining operations in Australia and Canada, where efficiency gains are paramount.
Detonator Market Segmentation
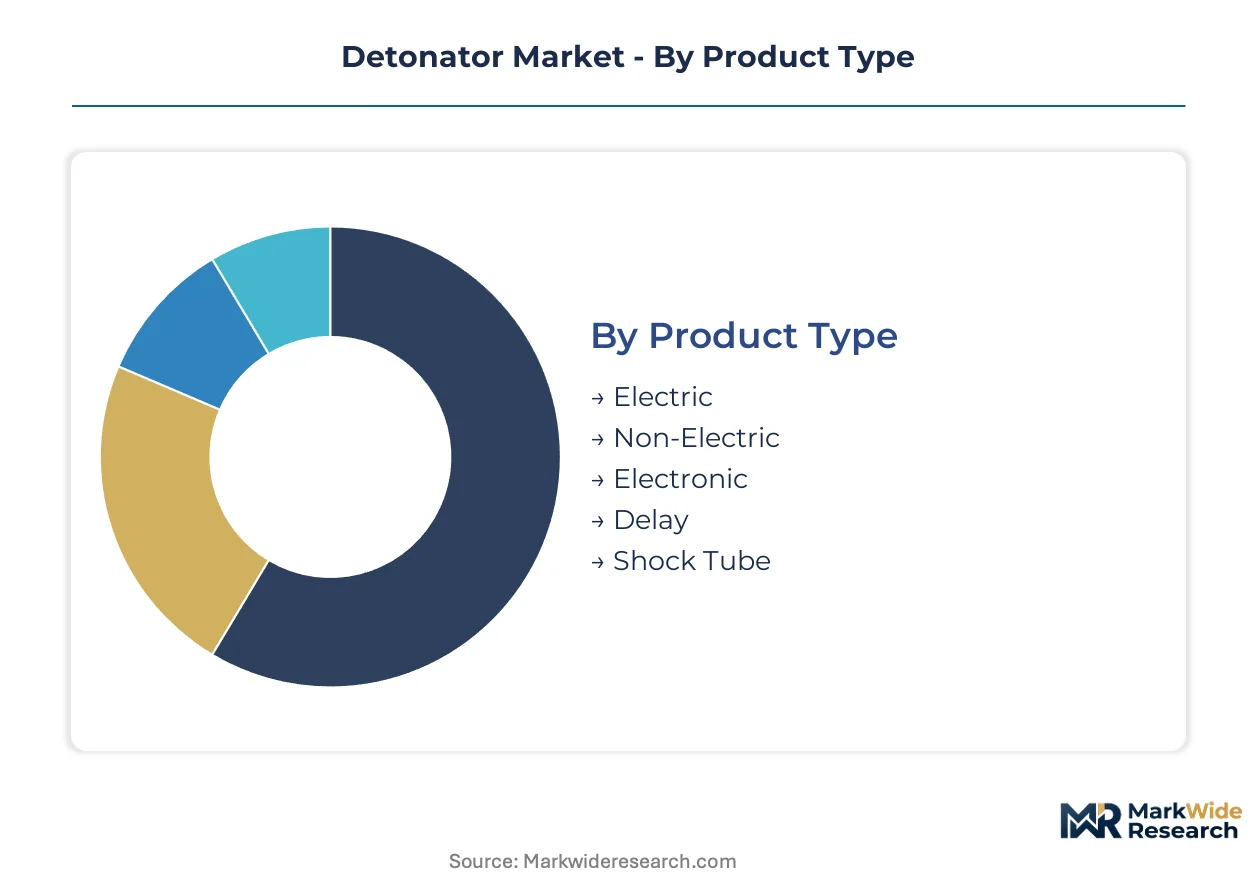
Market segmentation provides a critical framework for understanding the diverse operational requirements and technological preferences shaping the detonator industry. Analyzing these distinct segments helps manufacturers align product development with specific end-user needs and regulatory landscapes. This granular view clarifies where investment in advanced initiation systems yields the greatest operational efficiencies.
Product Type:
Segments within product type often reflect varying levels of capital intensity for both manufacturing and deployment, influencing market entry and operational overhead. Electronic detonators, for instance, demand higher upfront investment in sophisticated programming and handling equipment.
- Electronic:These devices incorporate microprocessors for precise, millisecond-level timing accuracy, enabling complex blast designs for optimal rock fragmentation. Demand from large-scale mining operations in Australia and Chile concentrates here, driven by mandates for enhanced safety and operational efficiency.
- Non-Electric:Utilizing a shock tube filled with a reactive powder, these detonators transmit an initiation signal without electricity, reducing risks associated with stray current. Mining and quarrying operations across developing economies widely adopt non-electric systems due to their reliability and lower initial cost.
- Electric:These traditional detonators use an electrical current to ignite a primary explosive, offering basic initiation for simpler blasting tasks.
- Delay:Designed to fire at specific, predetermined intervals, delay detonators control the sequence of explosions in a blast pattern.
- Shock Tube:This component transmits the initiation impulse over distances, providing a safe and flexible method for connecting detonators in a blast.
Most installed capacity flows through Non-Electric systems. Expansion is steepest in Electronic detonators.
Technology:
The technology segment reveals how specific initiation methods address different application requirements, from rapid, single-point blasts to highly coordinated, multi-point detonations. Programmable systems offer significant advantages in complex environments.
- Programmable:These advanced systems allow users to precisely set individual delay times for each detonator via software, optimizing blast outcomes and minimizing ground vibration. Large mining enterprises and specialized demolition contractors increasingly prefer programmable technology for its superior control and data analytics capabilities.
- Timed:Detonators with fixed delay elements provide sequential firing, crucial for achieving desired fragmentation and reducing seismic impact in quarrying and construction. Civil engineering projects in Europe frequently specify timed initiation for controlled rock breaking.
- Instantaneous:These detonators fire immediately upon receiving an initiation signal, suitable for simple, single-point blasting where precise sequencing is not critical.
- Encapsulated:Detonators with protective casings are designed for harsh environments, ensuring reliability in wet or abrasive conditions.
- Non-Encapsulated:These standard detonators are suitable for general blasting applications in less demanding environmental conditions.
Demand for Timed technology remains robust for general use. Programmable technology is gaining share fastest in specialized applications.
Application:
Understanding the application landscape highlights the primary industries driving detonator consumption and their specific operational demands. Large-scale extractive activities dominate volume, while specialized uses like demolition require distinct product characteristics.
- Mining:This sector utilizes detonators for extracting coal, metals, and minerals from both open-pit and underground operations, requiring high volumes and precision for rock fragmentation. Major mining companies in Canada prioritize advanced electronic systems to optimize ore recovery and safety.
- Demolition:Controlled demolition of structures in urban environments demands extremely precise and low-vibration detonator systems to minimize collateral damage. Specialized contractors in dense European cities rely on accurate electronic initiation for critical projects.
- Quarrying:Detonators are essential for breaking down rock in quarries to produce aggregates for construction materials.
- Construction Blasting:This application involves using explosives for excavation, trenching, and site preparation in infrastructure projects.
- Fireworks Manufacturing:Detonators are used in the production of pyrotechnic devices to initiate explosive charges for display.
The Mining segment commands the largest share of detonator volume. Demolition applications are climbing the fastest due to urban development.
End User Industry:
This segmentation clarifies which industries are the ultimate consumers of detonator products, each with unique regulatory compliance, safety protocols, and purchasing criteria. The extractive sector represents the most significant commercial opportunity.
- Extractive Sector:Encompassing mining and quarrying, this industry is the largest consumer of detonators, driven by the need to efficiently break rock for resource extraction. Companies like Orica Limited primarily serve this high-volume segment globally.
- Civil Engineering:This sector uses detonators for large-scale infrastructure projects, including road construction, tunneling, and dam building, requiring reliable and often precise blasting solutions. Public works initiatives in Asian economies fuel significant demand.
- Ordnance Factories:These government-controlled facilities produce military-grade explosives and munitions, requiring specialized detonators for weapon systems.
- Pyrotechnics:Manufacturers in this industry use detonators to ignite explosive compositions for fireworks and other display items.
- Explosive Manufacturers:These companies produce bulk explosives and often integrate detonators as part of a complete blasting solution for their clients.
The Extractive Sector holds the dominant position in end-user consumption. The Civil Engineering sector's expansion trajectory is steepest in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled technical workforces in key mining regions drive detonator market evolution. These specialized personnel anchor demand for advanced blasting solutions across diverse geographical landscapes. Their expertise is crucial for deploying sophisticated programmable systems in the extractive sector.
Australia
Mining modernization mandates in Western Australia propel demand for electronic detonators in large-scale operations. TGA regulations ensure product safety and quality for explosive materials, influencing procurement decisions. The Pilbara region sees significant investment in precise blast design for iron ore extraction, optimizing resource recovery.
Chile
The copper mining industry in Chile sustains a high volume demand for advanced initiation systems. Mandates for safer technologies from the national mining safety regulator accelerate the adoption of electronic detonators. The Antofagasta region is a hub for specialized blasting services supporting major copper mines.
United States
Infrastructure projects and quarrying operations across the United States create consistent demand for detonators. The US Bureau of Alcohol, Tobacco, Firearms and Explosives (ATF) enforces strict safety and security protocols for explosive handling. Mining operations in states like Nevada and Arizona increasingly utilize programmable systems for efficiency.
India
Large-scale production capacity in India serves both domestic and export markets for detonators. The country's central explosives controller regulates the manufacturing and use of blasting agents. Industrial clusters around Nagpur support significant manufacturing and distribution of detonators for coal mining.
Germany
Civil engineering projects and controlled demolition in Germany require precise and reliable detonator systems. CE marking under the European Union's directive on civil explosives is mandatory for market access. Urban centers like Berlin and Munich drive specialized demand for low-vibration electronic detonator applications.
Detonator Market Key Industry Players
The competitive structure tilts toward a blend of global manufacturers with extensive distribution networks and regional specialists. The market features a few large-scale players alongside numerous mid-sized entities focused on specific applications or geographies. Strategic archetypes include those prioritizing advanced technology development, those leveraging vast production capacity, and those excelling in complex regulatory compliance. Geographic expansion and technology licensing are common competitive moves.
Global players like Orica Limited exemplify the strategy of leveraging an extensive international footprint to navigate complex compliance requirements across various regions. Dyno Nobel occupies a position as a specialist in advanced electronic initiation systems, particularly for the North American mining sector, focusing on innovation. Solar Industries India anchors its presence through substantial production capacity, serving both domestic demand and export markets for various detonator types, including non-electric systems. These companies represent different strategic approaches within the evolving detonator industry, from global reach to technological niche and volume leadership.
| Leading Market Players |
|---|
| MAXAM |
| Hanwha Corporation |
| Orica Limited |
| Solar Industries India |
| AEL Mining Services |
| Austin Powder |
| Enaex |
| Ensign-Bickford Aerospace & Defense Company |
| Dyno Nobel |
| Others |
Cost & Logistics Intelligence
Large-scale mining operations and civil engineering contractors often operate on contract-based pricing models for detonator procurement, emphasizing long-term supply agreements over spot market transactions. This approach prioritizes supply reliability and technical support for complex blasting projects.
Pricing Analysis
The bundled service model, including blast design and analysis, commands premium pricing compared to unbundled component purchasing. Price differentiation stems from the technological sophistication of electronic detonators and the volume scale of the order. Pricing pressure emerges from the continued availability of lower-cost non-electric systems for general use. Smaller operators in quarrying and construction blasting exhibit greater price sensitivity, often opting for traditional, less expensive initiation methods.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks are critical for managing the complex logistics of detonators as dangerous goods. Supply concentration centers in countries like India, Australia, and the United States, reflecting major manufacturing bases. The supply chain relies on raw materials such as lead azide for primary explosives and microprocessors for electronic systems. Regulatory restriction, particularly stringent UN model regulations on transport, represents a significant structural risk. Distribution runs through a combination of direct sales from manufacturers and specialized, licensed distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with mandates for safer technologies and environmental controls, such as CE marking requirements, driving demand for advanced systems. These regulations compel manufacturers to innovate and end-users to upgrade their blasting solutions.
For Market Incumbents: Anticipate continued regulatory pressure for enhanced safety and traceability, necessitating ongoing investment in R&D for programmable electronic detonators. Reinforce global distribution networks to navigate complex compliance requirements, leveraging existing footprints like Orica Limited's. Expand value-added service offerings, including blast design and data analytics, to counter competitive threats from niche technology specialists.
For New Entrants and Emerging Players: Specialized blasting service providers represent an effective channel partner to penetrate markets with limited in-house expertise. Target the specialized demolition segment in dense urban environments, where precise, low-vibration electronic detonators offer significant advantages. Focus on developing bundled service models that simplify adoption for smaller quarrying and construction contractors in fast-developing Asian economies.
For Investors and Strategic Acquirers: Technology-focused strategic buyers are the most active acquirers in this space, seeking advanced electronic initiation systems and IoT integration capabilities. Long-term viability rests on the ongoing modernization of the extractive sector and global infrastructure growth over the next decade. A key signal to watch is the increasing patent activity and M&A for wireless initiation technologies, indicating future market direction.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Electronic Detonator R&D | Dyno Nobel enhances its advanced initiation systems for North American mining operations. |
| Expand Service Model Offerings | Orica Limited provides comprehensive blast design and post-blast analysis support globally. |
| Develop IoT Integration Solutions | Real-time blast monitoring capabilities improve safety protocols in large open-pit mines. |
| Secure Raw Material Supply | Lead azide sourcing strategies mitigate production cost volatility for detonator manufacturers. |
| Target Specialized Demolition | Precise electronic detonators enable controlled urban demolition projects in Germany. |
Research Approach
Coverage spans Australia, Chile, United States, India, and Germany, with primary inputs from each region informing market dynamics. This analysis combines extensive primary interviews with industry stakeholders, including mining engineers, blasting contractors, regulatory compliance officers, and R&D specialists. Secondary validation draws from government safety reports like those from the US Bureau of Alcohol, Tobacco, Firearms and Explosives, industry association publications, company financial filings, and UN dangerous goods regulations, ensuring robust bottom-up and top-down triangulation.
The forecast framework applies a rate-of-change decomposition across the analysis window, modeling market evolution. Segmentation dimensions include product type (Electronic, Non-Electric), technology (Programmable, Timed), application (Mining, Demolition), end user industry (Extractive Sector, Civil Engineering), and regional regulatory mandates. Compound annual growth rates are derived from historical trends and projected adoption rates, incorporating industry-specific forecast inputs such as mining investment cycles and infrastructure spending.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical instability affecting raw material supply and changes in mining regulations. All forecasts reflect assumptions documented within this study. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Smart Bullets Market
Weapons and Ammunition
Shotgun Shell Market
Weapons and Ammunition
Airborne Weapon System Market
Weapons and Ammunition
APAC Ballistic Missile Market
Weapons and Ammunition
Man-Portable Rocket Launcher Market
Weapons and Ammunition
Small Arms Market
Weapons and Ammunition
Military Fuze Market
Weapons and Ammunition
Missile Seekers Market
Weapons and Ammunition
Hypersonic Missile Market
Weapons and Ammunition
Ballistic Protection Market
Weapons and Ammunition
North Korea Nuclear Bombs and Missiles Market
Weapons and Ammunition
US Perforating Gun Market
Weapons and Ammunition
High Power Microwave Directed Energy Weapons Market
Weapons and Ammunition
Smoke Grenade Market
Weapons and Ammunition
Middle East and North Africa Perforating Gun Market
Weapons and Ammunition
Next-Generation Assault Rifles Market