
 Weapons Carriage and Release System Market | 2026-2036
Weapons Carriage and Release System Market Size, Share, and Industry Trends Forecast 2026-2036
Weapons Carriage and Release System Market Analysis
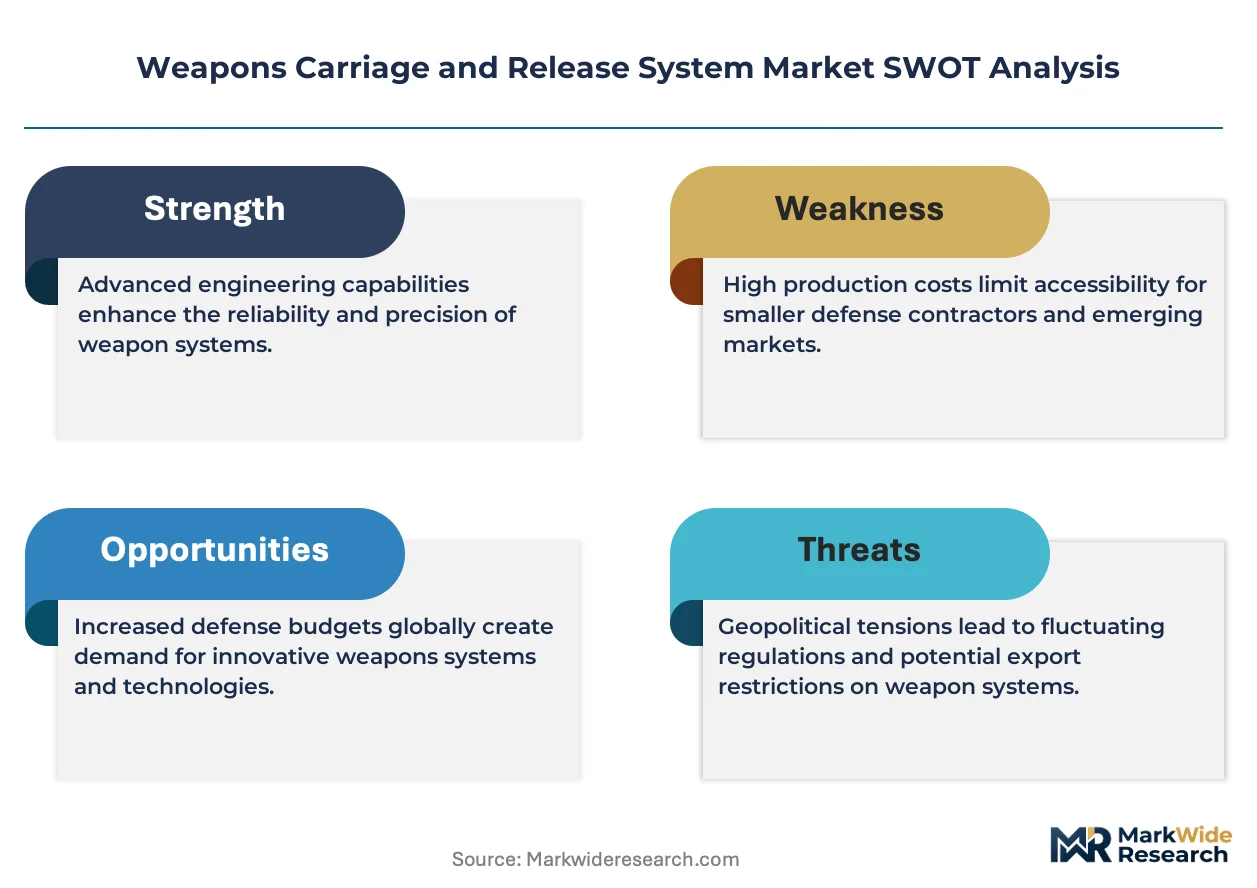
REACH is expanding compliance burdens for European suppliers of carriage systems containing specialty alloys and surface coatings. L3Harris Technologies leverages its integrated avionics footprint to bundle digital control interfaces with mechanical release hardware. RTX Corporation sustains long-term positions through captive airframe integration contracts with prime contractors. Moog dominates precision electromechanical actuator supply for next-generation bomb rack programs.
Weapons carriage and release systems comprise mechanically actuated or electromechanically driven assemblies that secure ordnance to airframes and execute commanded release sequences, typically rated for load capacities exceeding 2,500 pounds and operating across temperature ranges from -65°F to +200°F. Their primary purpose is to ensure safe retention during high-G maneuvers and reliable separation during combat or training operations. Bomb racks and bomb release units command the largest share of product-type revenue, reflecting sustained fighter and bomber fleet activity across Western militaries. Electromechanical systems are displacing legacy hydraulic architectures in new platforms, driven by weight reduction targets and reduced maintenance intervals. Combat aircraft applications anchor absolute demand volumes, though unmanned aerial vehicles represent the fastest-growing application segment as armed drone procurement accelerates.
The US FAA and NHTSA maintain limited direct jurisdiction, yet the US Department of Defense's MIL-STD-8591 and MIL-STD-1760 standards effectively govern mechanical interface and electrical interoperability requirements for all carriage systems entering US service. Europe's EASA certifies dual-use platforms under military-type certificate pathways, while REACH restricts hexavalent chromium and cadmium in surface treatments, forcing material substitutions across BAE Systems and Collins Aerospace supply chains. Stakeholders must monitor evolving open systems architecture mandates and their implications for proprietary control interface lock-in.
Market Dynamics
The US Department of Defense's open systems architecture mandates are dismantling proprietary control interface lock-in, forcing electromechanical release system suppliers to decouple hardware from software stacks and expose APIs to prime contractor avionics suites.
Growth Catalysts
- MIL-STD-1760 electrical interoperability mandates:The US DoD standardization of digital weapon interfaces accelerates electromechanical rack adoption across fighter modernization programs, eliminating hydraulic maintenance burdens.
- Armed UAV procurement acceleration:NATO member states are expanding precision strike drone fleets, generating demand for miniaturized carriage systems rated below 500-pound load classes.
- REACH material substitution deadlines:European hexavalent chromium and cadmium restrictions force coating technology upgrades, opening retrofit markets for compliant surface treatment providers.
Market Restraints
- Titanium alloy supply concentration:Specialty aerospace-grade titanium sourcing clusters in Russia and China expose Western suppliers to export control volatility and price spikes.
- Airframe integration contract captivity:Prime contractors like Boeing and Lockheed Martin lock suppliers into decade-long sole-source agreements, blocking new entrants from platform qualification.
- Electromechanical actuator technical maturity gaps:Precision release mechanisms for hypersonic weapon carriage remain unproven above Mach 5 thermal and vibration thresholds.
Strategic Opportunities
- India's indigenous fighter programs:The AMCA and TEDBF development contracts offer carriage system qualification pathways for suppliers establishing local production under offset requirements.
- Digital twin integration:Physics-based modeling of release dynamics converges with predictive maintenance platforms, enabling aftermarket software subscription revenue streams.
- US Navy unmanned carrier aviation:The MQ-25 Stingray and future UCAV programs require salt-corrosion-resistant electromechanical racks, a specification underserved by current suppliers.
Industry Challenges
- Embedded software talent scarcity:Real-time control firmware for fault-tolerant release sequences requires cleared engineers with DO-178C certification experience, a shallow labor pool.
- Platform-specific qualification timelines:Each fighter or bomber variant demands 18-36 months of flight testing before carriage system approval, compressing revenue recognition windows.
- Legacy hydraulic system interoperability:Electromechanical racks must maintain backward compatibility with 1960s-era bomb rack mechanical interfaces, constraining design optimization.
Report Scope
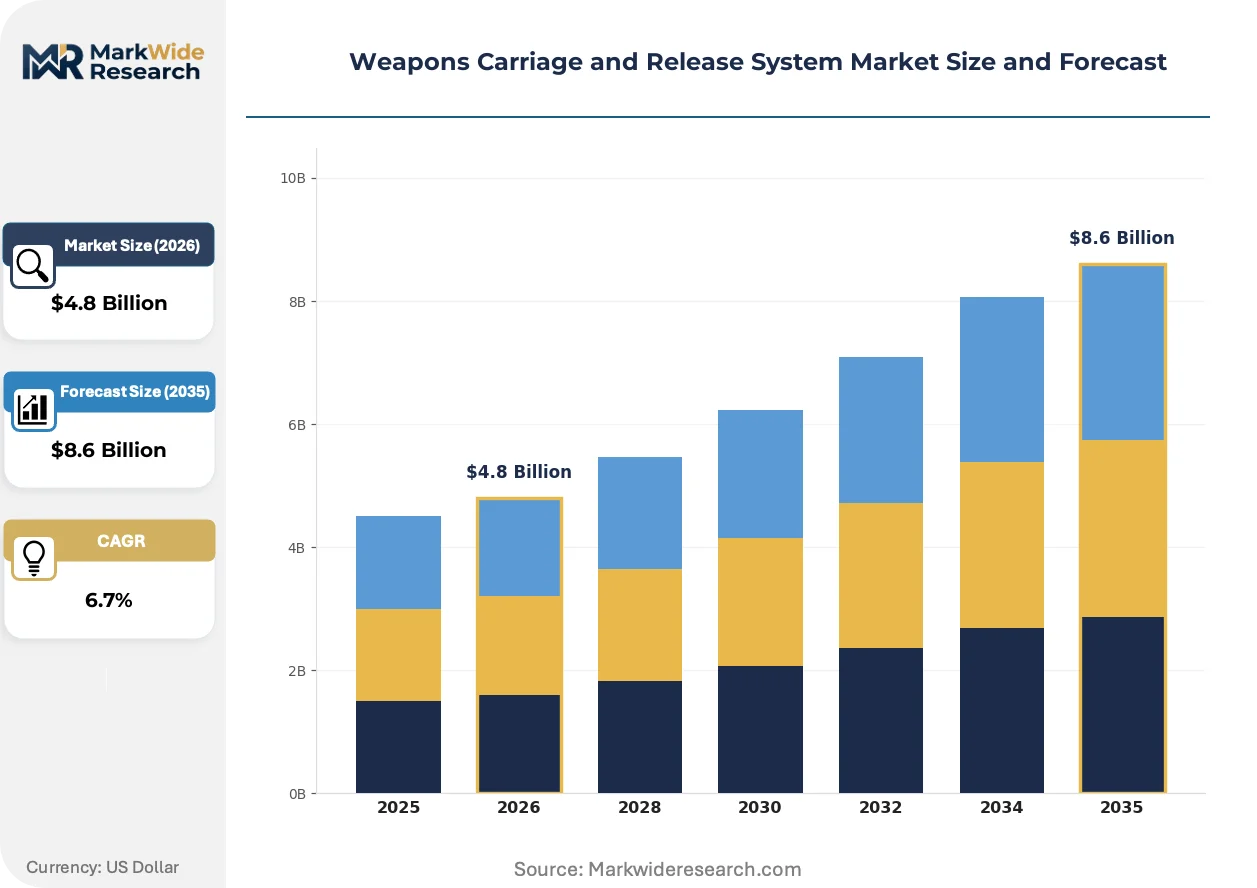
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weapons Carriage and Release System Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bomb Racks, Hardpoints, Pylons, Bomb Release Units End User: Military Services, Defense Contractors, Aerospace Manufacturers, Research Institutions Technology: Electromechanical Systems, Hydraulic Systems, Pneumatic Systems, Digital Control Interfaces Application: Combat Aircraft, Unmanned Aerial Vehicles, Naval Vessels, Ground Vehicles |
| Companies Covered | L3Harris Technologies, Cobham, RTX Corporation, Moog, The Marvin Group, Lockheed Martin, Northrop Grumman, BAE Systems, Collins Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weapons Carriage and Release System Market Emerging Trajectories
Electromechanical architectures are displacing hydraulics through distributed actuator networks, while digital control interfaces and predictive maintenance algorithms restructure supplier value capture away from hardware alone.
Model-based systems engineering (MBSE) is converging with digital thread documentation for weapon carriage hardware. US prime contractors now mandate MBSE-native suppliers for new fighter programs, compressing design iteration cycles and enabling virtual qualification of release sequences before physical prototyping.
REACH enforcement is accelerating hexavalent chromium elimination from cadmium-plated bomb rack surfaces. European suppliers at BAE Systems and Collins Aerospace are deploying zinc-nickel and ion vapor deposition aluminum alternatives, though salt spray performance gaps persist for naval aviation applications requiring 2,000-hour corrosion protection.
Armed forces are consolidating carriage system procurement under platform-level performance-based logistics contracts. The US Air Force's Agile Combat Employment doctrine drives demand for rapid reconfiguration kits, shifting supplier relationships from discrete hardware sales to integrated availability guarantees covering spares, technical data, and field engineering across dispersed operating locations.
Weapons Carriage and Release System Market Segmentation
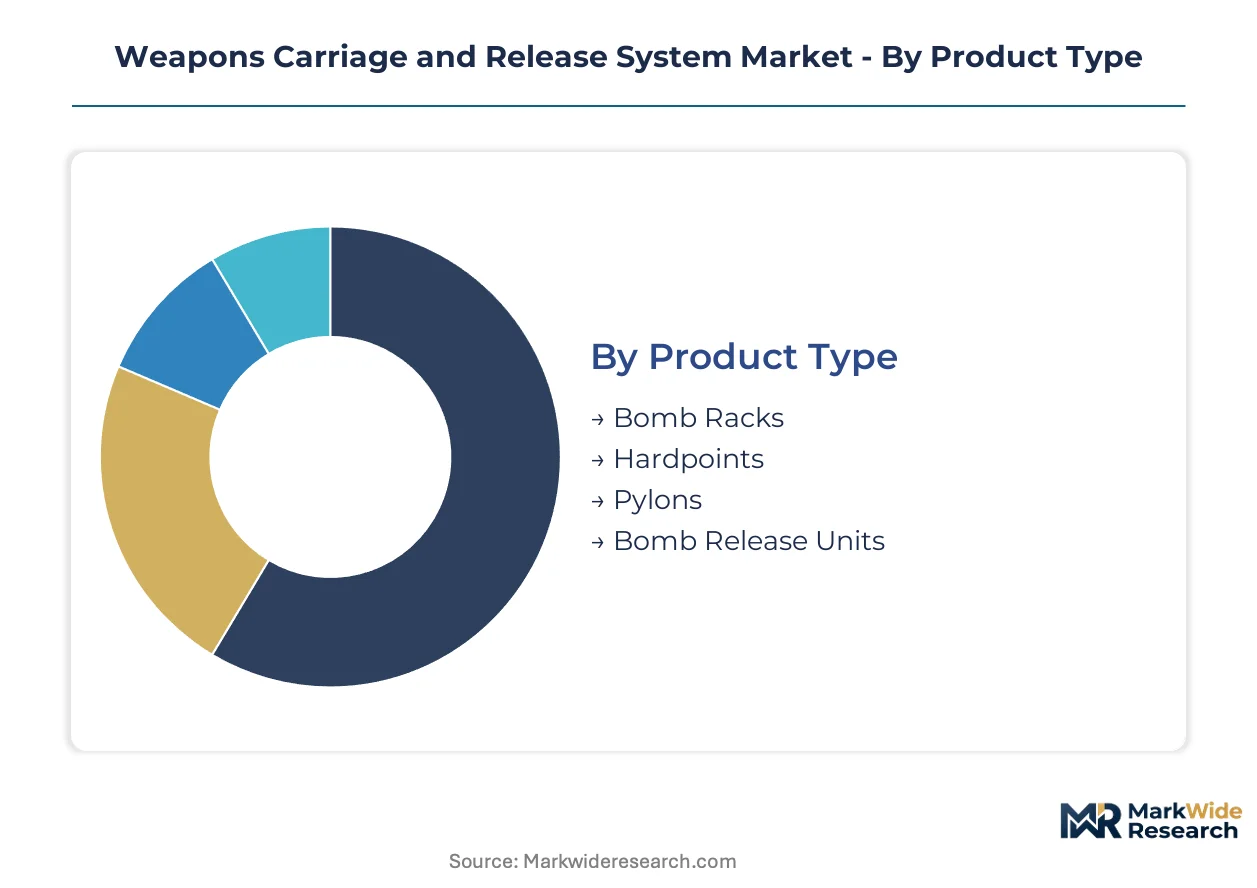
Segmentation in weapons carriage and release systems determines qualification pathways and procurement access. Each dimension—product architecture, customer type, actuation method, and platform integration—carries distinct capital requirements and technical barriers that shape supplier positioning.
Product Type:
Bomb racks and bomb release units absorb the heaviest upfront engineering investment due to MIL-STD-1760 electrical interoperability mandates and flight-critical safety certification.
- Bomb Racks:Mechanically actuated or electromechanically driven assemblies rated for load capacities exceeding 2,500 pounds. Demand concentrates in United States fighter modernization programs at California and Texas defense aerospace clusters, where open systems architecture standards are dismantling proprietary control interface lock-in.
- Bomb Release Units:Precision electromechanical mechanisms executing commanded separation sequences across temperature ranges from -65°F to +200°F. United States Department of Defense procurement anchors absolute volumes, though NATO member states are expanding electromechanical release system adoption for fleet upgrades.
- Hardpoints:Structural attachment points integrating carriage hardware with airframe load-bearing structures.
- Pylons:Aerodynamic fairings housing electrical and mechanical interfaces between bomb racks and aircraft wings.
Most installed capacity flows through Bomb Racks. Expansion is steepest in Bomb Release Units.
End User:
Customer type determines contract structure, with military services driving volume through multi-year platform-level awards while defense contractors control subsystem integration decisions.
- Military Services:National air forces and naval aviation branches procuring carriage systems through performance-based logistics contracts. United States Air Force Agile Combat Employment doctrine shifts supplier relationships toward integrated availability guarantees covering spares and field engineering.
- Defense Contractors:Prime contractors like Boeing and Lockheed Martin locking suppliers into decade-long sole-source airframe integration agreements. These captivity arrangements block new entrants from platform qualification while sustaining incumbent positions.
- Aerospace Manufacturers:Tier-1 airframe builders requiring backward-compatible electromechanical racks for mixed fleet operations.
- Research Institutions:Defense laboratories validating next-generation release mechanisms for hypersonic weapon carriage above Mach 5 thresholds.
Military Services command the dominant share of procurement volume. Defense Contractors are gaining share fastest through expanded subsystem integration mandates.
Technology:
Actuation architecture separates legacy-installed base from new platform adoption, with electromechanical systems displacing hydraulic maintenance burdens across Western fighter programs.
- Electromechanical Systems:Distributed actuator networks eliminating hydraulic fluid lines and reducing weight. United States Department of Defense open systems architecture mandates force suppliers to decouple hardware from software stacks and expose APIs to prime contractor avionics suites.
- Digital Control Interfaces:Real-time control firmware for fault-tolerant release sequences requiring DO-178C certification. Embedded software talent scarcity constrains supplier expansion as cleared engineers with avionics safety-critical experience remain a shallow labor pool.
- Hydraulic Systems:Legacy pressure-actuated architectures requiring intensive maintenance intervals.
- Pneumatic Systems:Compressed-gas mechanisms for specialized naval aviation applications.
Hydraulic Systems retain the largest installed base. Electromechanical Systems are climbing the fastest as fighter modernization programs accelerate.
Application:
Platform integration determines environmental qualification requirements, with combat aircraft demanding full MIL-STD-8591 compliance and unmanned systems enabling miniaturized specifications.
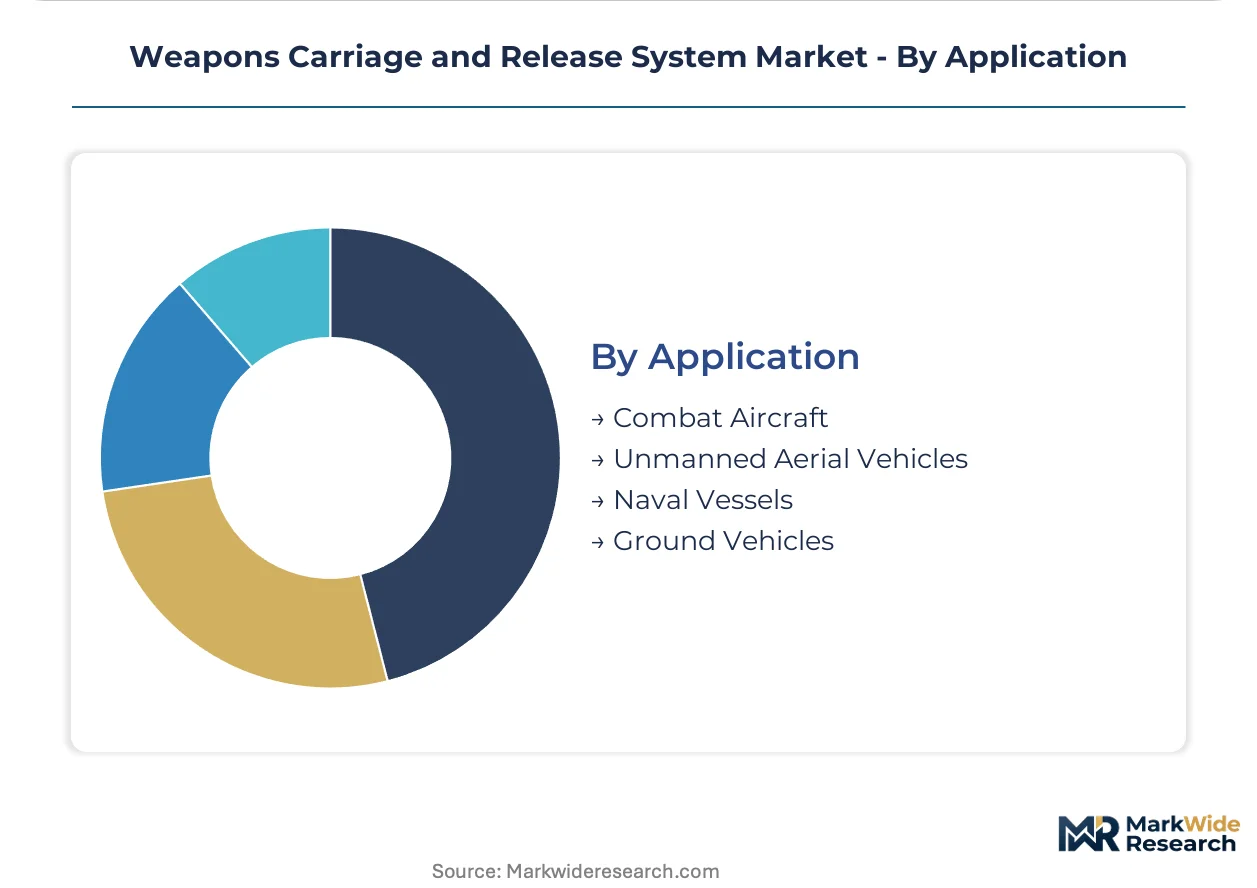
- Combat Aircraft:Fighter and bomber applications anchoring absolute demand volumes through sustained fleet activity across Western militaries. Each variant demands 18-36 months of flight testing before carriage system approval, compressing revenue recognition windows for suppliers.
- Unmanned Aerial Vehicles:Armed drone procurement generating demand for miniaturized carriage systems rated below 500-pound load classes. NATO member states are expanding precision strike drone fleets while United States Navy MQ-25 Stingray and future UCAV programs require salt-corrosion-resistant electromechanical racks.
- Naval Vessels:Shipboard vertical launch and helicopter deck systems requiring 2,000-hour corrosion protection.
- Ground Vehicles:Mobile artillery and air defense platforms with shock-hardened carriage requirements.
Combat Aircraft absorb the majority of current procurement. Unmanned Aerial Vehicles show the steepest expansion trajectory as armed drone procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The weapons carriage and release system industry traces its modern scale to Cold War-era fighter production in the United States, where MIL-STD standards first codified electromechanical release requirements for combat aircraft fleets.
United States
The US Department of Defense drives procurement volume through F-35 and F-15EX modernization programs, with open systems architecture mandates forcing suppliers to expose software APIs. California and Texas defense aerospace clusters concentrate electromechanical actuator development, particularly around Fort Worth and Palmdale production facilities.
United Kingdom
Royal Air Force Tempest and Typhoon fleet upgrades sustain demand for precision bomb release units. BAE Systems integration contracts lock suppliers into long-term airframe partnerships, while REACH deadlines force coating substitutions at manufacturing sites in Lancashire and Hampshire.
Germany
The Luftwaffe's participation in FCAS and Tornado replacement programs generates carriage system qualification opportunities. German defense procurement offices enforce EU defense procurement directives, with industrial activity clustering in Bavaria and Baden-Württemberg around Airbus Defence and Space facilities.
France
Dassault Aviation's Rafale export contracts and SCAF fighter development anchor regional demand for MIL-STD-1760 compliant racks. French defense procurement agency DGA mandates technology transfer provisions, with supply chain concentration in Île-de-France and Provence-Alpes-Côte d'Azur regions.
India
Indigenous fighter programs AMCA and TEDBF offer qualification pathways for foreign suppliers establishing local production under offset requirements. India's Ministry of Defence enforces phased manufacturing programs, with defense aerospace industrial corridors developing in Karnataka and Telangana states.
Weapons Carriage and Release System Market Vendor Landscape
The competitive structure tilts toward prime contractor captivity arrangements that lock subsystem suppliers into decade-long platform-specific agreements. Boeing and Lockheed Martin control airframe integration decisions, blocking new entrants from qualification pathways. Two strategic archetypes dominate: diversified aerospace conglomerates with captive avionics capabilities, and specialized electromechanical actuator manufacturers. Competitive moves center on strategic partnerships for digital control interface development and geographic expansion through offset-driven local production.
Among US-based diversified suppliers, L3Harris Technologies and RTX Corporation exemplify the integrated avionics archetype, bundling digital control layers with mechanical hardware. Moog occupies a distinct position as a precision electromechanical specialist, supplying next-generation bomb rack actuation systems. These three companies anchor the supplier landscape through contrasting approaches to the hardware-software decoupling mandated by open systems architecture standards.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Cobham |
| RTX Corporation |
| Moog |
| The Marvin Group |
| Lockheed Martin |
| Northrop Grumman |
| BAE Systems |
| Collins Aerospace |
| Others |
Supply Flow & Price Mechanics
Prime contractor captivity arrangements and sole-source airframe integration contracts concentrate pricing power among Boeing and Lockheed Martin procurement teams, compressing supplier margins while locking electromechanical actuator manufacturers into decade-long agreements with limited renegotiation leverage.
Pricing Analysis
Platform-specific performance-based logistics contracts dominate procurement, bundling hardware, spares, and field engineering into integrated availability guarantees. Price differentiation rests on MIL-STD-1760 certification tier and after-sales service bundling, with prime contractors least sensitive to unit cost and foreign suppliers in offset-driven markets most exposed to margin pressure. Cost compression in legacy hydraulic replacement segments is intensifying as open systems architecture mandates force software API exposure without corresponding hardware premium capture.
Supply Chain Analysis
Domestic-content mandates under India's phased manufacturing program and the US DoD's Buy American provisions are reshaping sourcing patterns for titanium alloy forgings and precision electromechanical components. Supply concentrates in the United States, Germany, and Japan for aerospace-grade actuators, while specialty coatings draw from EU suppliers adapting to REACH hexavalent chromium restrictions. Single-source vulnerability around Russian and Chinese titanium sponge exposes Western bomb rack manufacturers to export control volatility. Distribution runs through prime contractor tier-1 integration facilities with limited direct military procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The weapons carriage and release system market functions as a regulatory compounder, where MIL-STD-1760 electrical interoperability mandates continuously refresh procurement cycles across fighter modernization programs.
For Market Incumbents: To counter open systems architecture mandates dismantling proprietary control interface lock-in, Moog and L3Harris Technologies should deepen API standardization partnerships with prime contractor avionics suites while securing captive positions in next-generation hypersonic weapon carriage development programs before thermal threshold validation completes. For New Entrants and Emerging Players: Unmanned carrier aviation programs represent the most penetrable buyer archetype, particularly salt-corrosion-resistant electromechanical racks for the US Navy MQ-25 Stingray and future UCAV platforms where incumbent qualification gaps persist. Establishing digital twin integration capabilities offers a software-first go-to-market angle that sidesteps hardware qualification timeline barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized electromechanical actuator manufacturers with hypersonic weapon carriage exposure but unproven Mach 5 thermal thresholds, offering asymmetric upside if validation succeeds. The signal to watch is flight test milestone announcements from DARPA or Air Force Research Laboratory programs indicating technology maturation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Open Systems Architecture Compliance | API standardization with Lockheed Martin and Boeing avionics suites unlocks platform integration access. |
| Hypersonic Weapon Carriage Development | Mach 5 thermal validation positions suppliers for next-generation bomber and fighter programs. |
| Digital Twin Integration | Physics-based release modeling enables predictive maintenance subscription revenue beyond hardware sales. |
| Offset-Driven Local Production | Indian AMCA and TEDBF qualification pathways require domestic manufacturing under Ministry of Defence mandates. |
| REACH-Compliant Surface Treatment | Zinc-nickel and ion vapor deposition aluminum substitutions secure European supplier continuity. |
Methodological Framework
Bottom-up combat aircraft and unmanned aerial vehicle platform modeling reconciled against top-down electromechanical actuator supply tracking forms the analytical core of this study. Primary interviews with fighter program procurement officers, bomb rack engineering directors, prime contractor subsystem integration leads, and defense laboratory research scientists combined with secondary validation from MIL-STD-1760 specification documents, US Department of Defense budget justification materials, and NATO member state defense procurement announcements.
Input-output matrices map platform-level carriage system content per fighter variant against production run projections across the analysis window. Segmentation dimensions include product architecture, actuation technology, application platform, and end-user contract structure. CAGRs derive from weighted average of platform delivery schedules and technology transition curves, with specific incorporation of electromechanical displacement rates for hydraulic legacy systems and armed UAV procurement acceleration trajectories.
Underlying measurement precision varies by segment; bomb racks and bomb release units with established MIL-STD qualification histories carry tighter precision than hypersonic weapon carriage mechanisms where technical maturity gaps persist. Forecasts reflect assumptions around open systems architecture adoption timelines and REACH material substitution compliance deadlines, with electromechanical actuator thermal threshold validation and titanium alloy supply disruption representing primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Nuclear Bombs and Missiles Market
Weapons and Ammunition
Ballistic Missile Market
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Decoy Flares Market
Weapons and Ammunition
North America Weapon Night Sight Market
Weapons and Ammunition
France Nuclear Bombs and Missiles Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Electrical Weapon Market
Weapons and Ammunition
Airsoft Guns Market
Weapons and Ammunition
Missile Seekers Market
Weapons and Ammunition
Ammunition Handling Systems Market
Weapons and Ammunition
Ammunition Storage Market
Weapons and Ammunition
Turret System Market
Weapons and Ammunition
Shotgun Shell Market
Weapons and Ammunition
Guided Munitions Market
Weapons and Ammunition
Electromagnetic Weapons Market