
 Small Caliber Ammunition Market | 2026-2036
Small Caliber Ammunition Market Size, Share, and Industry Trends Forecast 2026-2036
Small Caliber Ammunition Market Intelligence
The divergence between premium match-grade rounds and commodity training ammunition is shifting procurement patterns across defense and civilian channels. Olin Corporation leverages its Lake City Army Ammunition Plant contract to anchor military supply continuity. Vista Outdoor competes across retail distribution with a portfolio spanning rimfire through centerfire lines. Rheinmetall AG specializes in NATO-standardized small caliber production for European defense customers.
Small caliber ammunition comprises cartridges generally below twenty millimeters in diameter, incorporating a primer, propellant, and projectile within a brass or steel case designed for handheld firearms. Centerfire configurations dominate military and law enforcement procurement due to reloadability and higher pressure tolerance, while rimfire rounds maintain cost advantages in sports shooting and small game hunting. The end user segmentation reveals military training as the most volume-intensive category, with personal protection and competition shooting commanding premium pricing per round. Material composition is transitioning toward copper and nickel-plated projectiles as regulatory pressure on lead intensifies across multiple jurisdictions.
The United States Army's specifications through the Department of Defense shape global standards for interoperability, while EPA oversight of lead emissions at ranges influences domestic range remediation costs and ammunition selection. European REACH restrictions on lead content in outdoor ammunition are forcing reformulation investments by manufacturers serving EFTA and EU markets. Stakeholders must monitor the pace of regulatory harmonization between NATO procurement standards and emerging environmental constraints, as compliance investments will determine which suppliers retain access to defense contracts and civilian retail channels simultaneously.
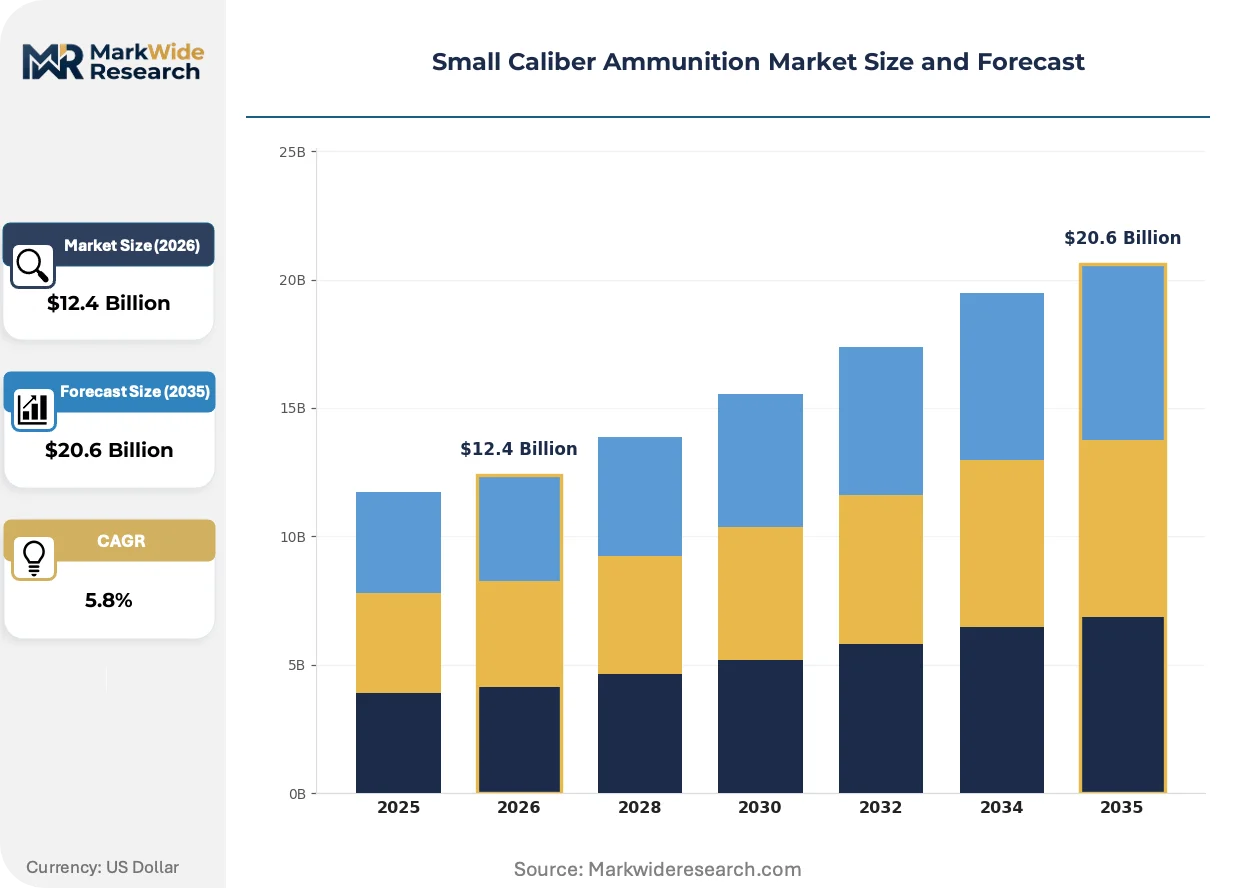
Market Dynamics
Regulatory mandates on lead content are forcing simultaneous reformulation of projectile materials and range remediation protocols across NATO defense procurement and civilian retail channels. This environmental compliance pressure now sits at the center of supplier qualification decisions.
Growth Catalysts
- REACH lead restrictions:ECHA mandates on outdoor ammunition are accelerating copper and tungsten alloy adoption in European defense and hunting segments. Reformulation investments by manufacturers serving EFTA markets are creating first-mover certification advantages.
- Military training volume:NATO standardization protocols are expanding order volumes for interoperable 5.56mm and 7.62mm rounds across member state armed forces. Joint procurement frameworks reduce per-unit qualification costs for approved suppliers.
- Civilian sports shooting:Competitive precision disciplines and recreational range use in the United States sustain the world's largest consumption base for rimfire and centerfire ammunition. Reloading culture extends customer lifetime value through component sales.
Market Restraints
- Raw material concentration:Brass sheet and propellant precursor supply chains concentrate in a limited number of specialty chemical and metallurgical producers. Price volatility in copper and nitrocellulose feedstocks compresses margin predictability.
- Technical performance gaps:Lead-free projectiles currently exhibit ballistic coefficient and terminal performance trade-offs against traditional jacketed lead-core designs. Military acceptance testing timelines extend procurement cycles for non-lead alternatives.
- Range infrastructure lock-in:Existing indoor and outdoor firing ranges face capital-intensive ventilation and soil remediation requirements under EPA lead emission guidelines. Facility upgrade costs deter new range development in regulated jurisdictions.
Strategic Opportunities
- Polymer-cased ammunition:Hybrid case technology combining steel base and polymer body reduces weight and material cost for training rounds. Military logistics commands are evaluating field trials for reduced soldier carry burden.
- Precision-guided small arms:Integration of micro-electronics and fin-stabilized projectiles is creating new match-grade categories for long-range competition and designated marksman applications. Early adopters in competitive shooting are driving performance benchmarking.
- Direct-to-consumer reloading components:E-commerce channels for brass, primers, and propellants bypass traditional retail distribution markups. Specialty suppliers are capturing hobbyist segments through subscription-based component kits.
Industry Challenges
- Ballistician and metallurgist talent scarcity:Specialized expertise in interior ballistics and non-toxic projectile design concentrates at legacy defense contractors. Smaller manufacturers face recruitment competition from aerospace and automotive sectors.
- Lot consistency certification:Military and law enforcement procurement requires statistical process control documentation and destructive testing protocols. Compliance documentation burdens extend sales cycles for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Caliber Ammunition Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rimfire, Centerfire, Match, Self-Defense End User: Military, Law Enforcement, Sports Shooting, Hunting Material: Lead, Copper, Brass, Nickel-Plated Use Case: Training, Competition, Personal Protection, Wildlife Management |
| Companies Covered | Olin Corporation, Nammo AS, Northrop Grumman Corporation, BAE Systems, General Dynamics Ordnance and Tactical Systems, Vista Outdoor, CBC Global Ammunition, Rheinmetall AG, Elbit Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Caliber Ammunition Market Strategic Shifts & Innovations
Material science advances and digital manufacturing are compressing development cycles for specialized projectile designs while regulatory pressure accelerates environmental performance standards.
Copper monolithic projectile construction is consolidating market share in premium hunting and law enforcement segments due to weight retention and barrier penetration advantages. Federal agencies and state wildlife departments are specifying copper solids for duty and regulated hunting applications. This technology is consolidating procurement specifications around single-material designs that simplify compliance documentation.
EPA oversight of firing range lead management is mandating engineered backstop systems and soil remediation bonding across commercial and municipal facilities. Range operators face capital calls for ventilation upgrades and closed-loop bullet capture. Indoor training facilities in the United States are responding with HEPA filtration investments and total containment trap installations.
Reloading component kit subscriptions are displacing traditional retail box purchases among high-volume competition shooters. Specialty distributors now offer monthly primer, powder, and projectile allocations with ballistic data support. This channel shift is most visible in the United States, where precision rifle series competitors prioritize load development consistency over factory ammunition convenience.
Small Caliber Ammunition Market Segmentation
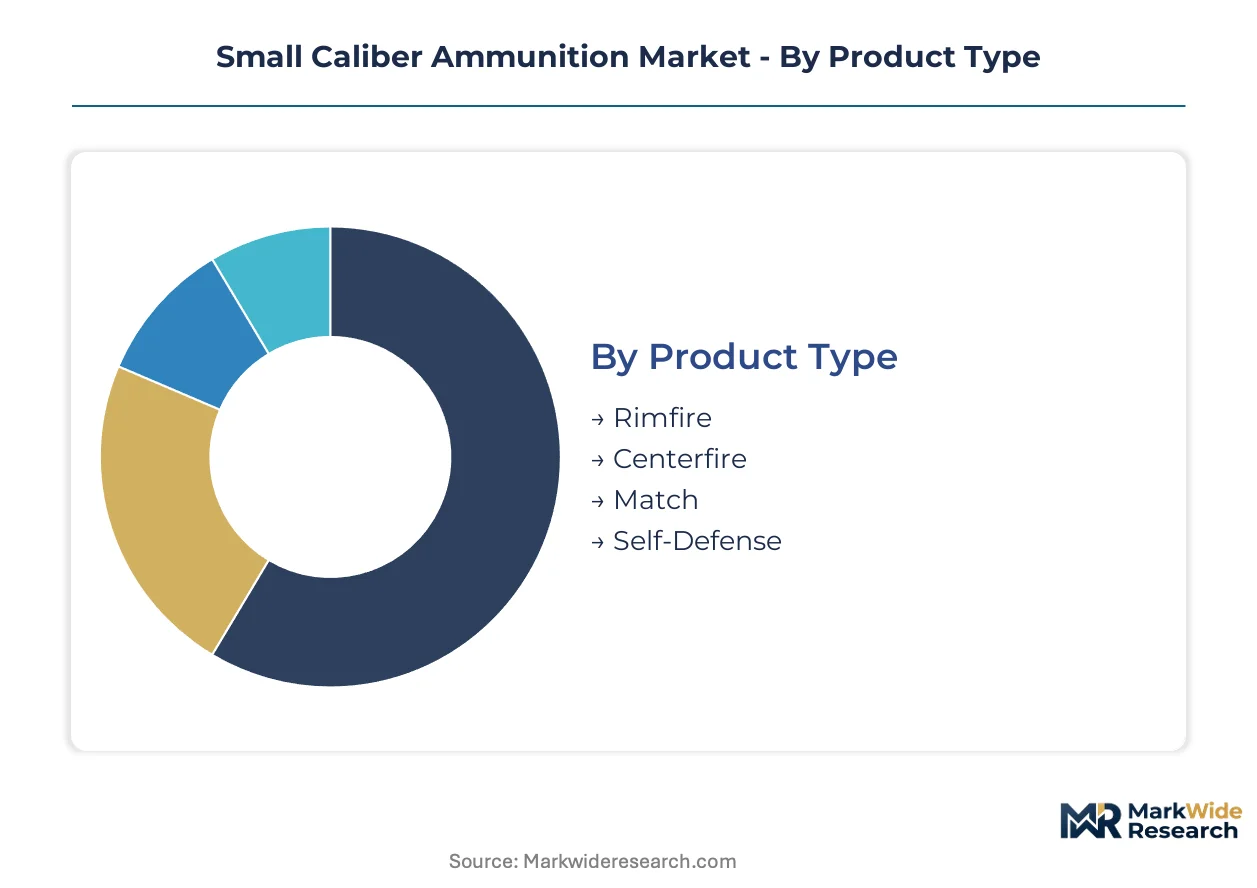
Segmentation in small caliber ammunition reveals how capital deployment, regulatory exposure, and end-use specifications fragment manufacturing priorities across product lines. Procurement officers and retail buyers operate on fundamentally different selection criteria, forcing suppliers to maintain parallel qualification tracks.
Product Type:
Capital intensity peaks in centerfire manufacturing due to primer assembly precision and brass case drawing requirements, while rimfire demands continuous high-volume production lines to amortize fixed costs.
- Centerfire:Reloadable brass cases with separate primer pockets dominate military and law enforcement procurement. Lake City Army Ammunition Plant specifications anchor NATO interoperability standards, with reloadability extending customer lifetime value in civilian markets.
- Rimfire:Integral priming in the case rim enables cost-efficient production for high-volume sports shooting. United States recreational consumption sustains the world's largest rimfire demand base, particularly for .22LR target and small game applications.
- Match:Tight tolerance specifications for projectile concentricity and propellant consistency serve competitive precision disciplines.
- Self-Defense:Jacketed hollow point and bonded core designs optimize terminal ballistics for personal protection applications.
Most installed capacity flows through Centerfire. Expansion is steepest in Match as competitive shooting disciplines proliferate.
End User:
Customer procurement scale ranges from billion-round military frameworks to individual retail transactions, with qualification documentation intensity inversely correlated to purchase volume.
- Military:Standardized 5.56mm and 7.62mm NATO specifications drive volume procurement across allied defense ministries. Joint qualification protocols reduce supplier certification burdens, though lot consistency documentation demands remain stringent.
- Sports Shooting:Precision rifle series and three-gun competitions sustain premium pricing for match-grade factory and handloaded ammunition. Reloading component sales extend distributor margins beyond finished cartridge transactions.
- Law Enforcement:Duty ammunition specifications prioritize barrier penetration and terminal performance over cost minimization.
- Hunting:State wildlife agency regulations increasingly mandate non-toxic projectiles for waterfowl and big game applications.
Military procurement absorbs the highest absolute volumes. Sports Shooting climbs fastest as competitive participation expands.
Material:
Raw material selection now hinges on regulatory compliance timelines rather than purely ballistic optimization, with copper and nickel-plated alternatives commanding reformulation investments.
- Copper:Monolithic solid projectiles retain weight through barrier penetration and satisfy ECHA REACH restrictions on outdoor lead use. Federal agency specifications for duty ammunition and state wildlife mandates accelerate adoption in premium segments.
- Lead:Traditional jacketed lead-core designs maintain cost advantages in training ammunition and jurisdictions without environmental restrictions. EPA range remediation guidelines and European outdoor bans compress accessible market scope.
- Brass:Case material standard for centerfire reloadability and pressure tolerance.
- Nickel-Plated:Enhanced corrosion resistance and feeding reliability in semi-automatic firearms.
Lead still dominates installed production capacity. Copper gains share fastest under regulatory pressure.
Use Case:
Application-specific requirements fragment product development priorities, with training rounds prioritizing cost and competition loads demanding extreme consistency.
- Training:Volume-intensive military and law enforcement qualification firing consumes the majority of standard ball ammunition production. Polymer-cased alternatives under evaluation by United States Army logistics commands promise reduced soldier carry weight.
- Personal Protection:Terminal performance testing against FBI protocol standards drives hollow point design evolution. Concealed carry permit expansion in multiple United States jurisdictions sustains civilian demand for defensive handgun cartridges.
- Competition:Precision rifle and pistol disciplines require lot-to-lot velocity consistency for predictable ballistic solutions.
- Wildlife Management:State agency culling programs and regulated hunting seasons generate seasonal demand spikes.
Training absorbs the bulk of manufacturing throughput. Personal Protection expands most quickly as defensive carry permits proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge sharply in ammunition procurement philosophy, with German manufacturers accelerating lead-free reformulation under ECHA mandates while United States producers balance military volume contracts against civilian retail channels.
United States
Lake City Army Ammunition Plant in Missouri anchors the world's largest small caliber production footprint, supplying standardized NATO rounds for allied defense ministries. EPA oversight of range lead emissions drives indoor facility upgrades toward HEPA filtration and total containment trap systems. Civilian sports shooting concentrates in Texas, Arizona, and Florida, where high-volume competition circuits sustain rimfire and centerfire demand.
Germany
Rheinmetall AG's Unterlüß facility specializes in NATO-interoperable 5.56mm and 7.62mm production for European defense customers. ECHA REACH restrictions on outdoor lead ammunition mandate copper and tungsten alloy adoption across hunting and military training segments. Bavaria and Baden-Württemberg host precision engineering clusters supplying projectile manufacturing equipment to ammunition producers.
United Kingdom
BAE Systems maintains defense ammunition supply relationships through Radway Green and other legacy Royal Ordnance facilities. Ministry of Defence standardization protocols align procurement with NATO STANAG specifications for interoperability with allied forces. Scotland and Northern England retain specialized metalworking capabilities supporting brass case drawing and primer assembly operations.
Israel
Elbit Systems Ltd. supplies small caliber ammunition integrated with broader tactical systems for defense export markets. Israeli Defense Forces training requirements drive continuous procurement of standardized rounds compatible with NATO and non-NATO platforms. The Negev Desert hosts outdoor range complexes where lead management alternatives are under evaluation.
Brazil
CBC Global Ammunition operates from São José dos Campos and other industrial centers, serving Latin American defense and law enforcement markets with domestic production capacity. Brazilian military police and armed forces procurement prioritizes cost-efficient training ammunition alongside duty-specification hollow points. São Paulo state concentrates metallurgical supply chains for brass sheet and propellant precursor chemicals.
Small Caliber Ammunition Market Key Industry Players
Top-tier vendors anchor defense procurement frameworks, while mid-tier specialists compete for law enforcement and premium civilian segments. The market exhibits tiered concentration around military contract holders and diversified sporting goods suppliers. Strategic archetypes include integrated defense primes with captive ammunition divisions, standalone ammunition pure-plays, and diversified outdoor recreation conglomerates. Capacity expansion and lead-free reformulation partnerships represent the dominant competitive moves across supplier tiers.
Within the defense prime tier, Northrop Grumman Corporation and General Dynamics Ordnance and Tactical Systems exemplify integrated military suppliers with ammunition operations embedded within broader tactical systems portfolios. Olin Corporation and Vista Outdoor occupy positions spanning government contracts and civilian retail channels. Rheinmetall AG represents European specialization in NATO-standardized production. Nammo AS, Elbit Systems Ltd., and BAE Systems each anchor regional supply relationships with defense ministries in their respective geographies.
| Leading Market Players |
|---|
| Olin Corporation |
| Nammo AS |
| Northrop Grumman Corporation |
| BAE Systems |
| General Dynamics Ordnance and Tactical Systems |
| Vista Outdoor |
| CBC Global Ammunition |
| Rheinmetall AG |
| Elbit Systems Ltd. |
| Others |
Cost & Logistics Intelligence
Brass sheet and nitrocellulose feedstock costs cascade through three distinct pricing tiers, with Lake City Army Ammunition Plant contract volumes anchoring economy-grade training rounds while copper monolithic projectiles command premium positioning in European hunting segments constrained by ECHA REACH mandates.
Pricing Analysis
Capacity additions in Brazil and Israel are reshaping price floors for standard ball ammunition, compressing margins on commodity training rounds. Three-tier pricing structure across match-grade, duty-specification, and economy training levels separates lot-consistency certification costs from basic interoperability standards. Pricing pressure stems from raw material volatility in copper and propellant precursors, with military procurement officers exhibiting lowest price sensitivity due to qualification lock-in effects.
Supply Chain Analysis
Domestic-content mandates under the United States Buy American Act and European defense procurement directives are reshaping sourcing patterns for brass case and primer assembly inputs. Concentrated supply in the United States, Germany, and Brazil draws from copper mining in Chile, tungsten processing in China, and specialty chemical production in Switzerland. Single-source vulnerability in nitrocellulose feedstocks creates exposure to export restriction shocks. Distribution runs through defense logistics commands, law enforcement cooperative purchasing agreements, and specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between United States military volume contracts and European lead-free reformulation premiums, with ECHA compliance costs in Germany creating pricing umbrellas that domestic producers can undercut.
For Market Incumbents: Extend qualification documentation advantages into polymer-cased ammunition trials with United States Army logistics commands. Deepen backward integration into brass sheet rolling to offset copper price volatility. Lock in multi-year propellant supply agreements before specialty chemical capacity tightens further.
For New Entrants and Emerging Players: Begin with direct-to-consumer reloading component subscriptions in United States precision rifle competition circuits. Target states with concealed carry permit expansion for defensive handgun ammunition white space. Pursue niche certification as a copper monolithic projectile specialist for state wildlife agency non-toxic mandates.
For Investors and Strategic Acquirers: Consolidation pressure builds where lead-free reformulation investments exceed $50 million and military qualification timelines stretch beyond 36 months. Mid-tier ammunition pure-plays with captive NATO STANAG certification represent prime acquisition targets. Watch EPA range remediation enforcement intensity as inflection indicator for indoor training facility upgrade demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Lead-Free Projectile Reformulation | ECHA REACH compliance unlocks European defense and hunting procurement access. |
| Polymer-Cased Ammunition Trials | United States Army logistics evaluation reduces soldier carry burden in training scenarios. |
| Direct-to-Consumer Component Kits | Subscription models bypass retail markups in United States precision shooting segments. |
| Range Remediation Technology Partnerships | HEPA filtration and total containment trap installations address EPA lead emission guidelines. |
| NATO Joint Qualification Pursuit | STANAG interoperability certification reduces per-unit approval costs across allied defense ministries. |
Research Approach
Direct dialogue with defense procurement officers, ammunition plant operations managers, range facility engineers, and sporting goods distribution executives anchored qualitative findings. Secondary validation drew from Department of Defense contract announcements, EPA enforcement databases, ECHA restriction dossiers, and NATO standardization documents. Bottom-up production capacity tallies triangulated against top-down defense budget appropriation flows.
Bottom-up modeling aggregated individual facility throughput estimates across Lake City, Unterlüß, Radway Green, and São José dos Campos production sites. Top-down verification checked aggregate outputs against NATO ammunition consumption surveys and United States civilian retail audit data. Segmentation dimensions spanned product type, end user, material composition, and use case across the projection horizon. CAGR derivation incorporated military training cycle intensity, regulatory compliance phase-in schedules, and competitive capacity addition timelines.
Several conditions sit outside the modeled scope, including sudden export control impositions on propellant precursors, unilateral NATO procurement standard revisions, and breakthrough advances in caseless ammunition technology. Forecasts assume continuity in current regulatory trajectories and defense alliance structures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Missile Launching Systems Market
Weapons and Ammunition
Non Lethal Projectiles Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Artillery Ammunition Market
Weapons and Ammunition
Europe Ammunition Market
Weapons and Ammunition
Riflescope Market
Weapons and Ammunition
Man-Portable Rocket Launcher Market
Weapons and Ammunition
North America Small Arms Market
Weapons and Ammunition
Ammunition Belt Market
Weapons and Ammunition
Middle East and Africa Ammunition Market
Weapons and Ammunition
Medium Caliber Ammunition Market
Weapons and Ammunition
Close-In Weapon Systems Market
Weapons and Ammunition
Sonobuoy Launcher Market
Weapons and Ammunition
Precision Guided Munition Market
Weapons and Ammunition
Ballistic Composite Market
Weapons and Ammunition
Mortar Ammunition Market