
 Hypersonic Missile Market | 2026-2036
Hypersonic Missile Market Size, Share, and Industry Trends Forecast 2026-2036
Hypersonic Missile Market Analysis
The EU Green Deal is restructuring defense procurement criteria across European member states, compelling suppliers to demonstrate lower-carbon manufacturing footprints and sustainable supply chains for strategic weapons programs. Lockheed Martin Corporation leverages its vertically integrated thermal protection systems division to secure long-term government contracts. Raytheon Technologies Corporation sustains R&D intensity through dedicated hypersonic research centers in multiple US states. Northrop Grumman Corporation anchors its position via specialized guidance and control subsystems for extreme-velocity platforms.
Hypersonic missiles are weapons systems that sustain flight at speeds exceeding Mach 5, utilizing scramjet or rocket-based propulsion combined with advanced ceramic-matrix composite thermal shields to survive atmospheric friction during sustained high-velocity maneuvering. Their primary purpose is to penetrate sophisticated integrated air defense networks through unpredictable trajectory profiles and compressed engagement timelines. Boost-glide vehicles currently dominate procurement budgets due to their proven test records and lower technical risk relative to air-breathing alternatives. Air-breathing scramjet technology represents the fastest-expanding segment as programs mature toward operational deployment, though margin pools remain concentrated in rocket-based systems where production experience runs deepest.
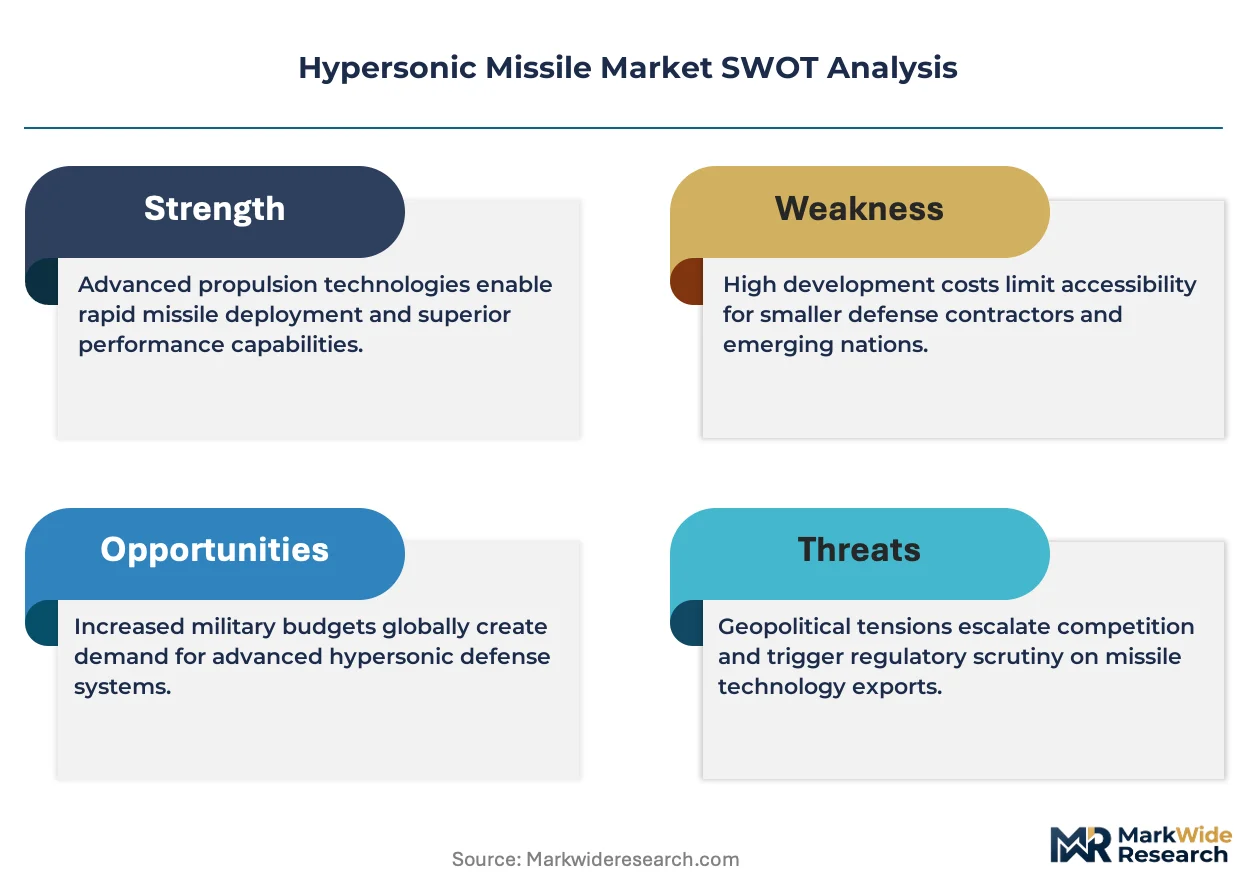
The US Department of Defense, China's SAMR, and Russia's military procurement framework each impose distinct testing protocols and export controls that fragment supplier eligibility and shape platform specifications. NATO interoperability standards and ITAR restrictions further constrain technology transfer pathways, limiting vendor mobility across defense procurement blocs. Stakeholders must monitor evolving counter-hypersonic defense investments by adversarial nations to anticipate shifts in platform requirements and mission profiles.
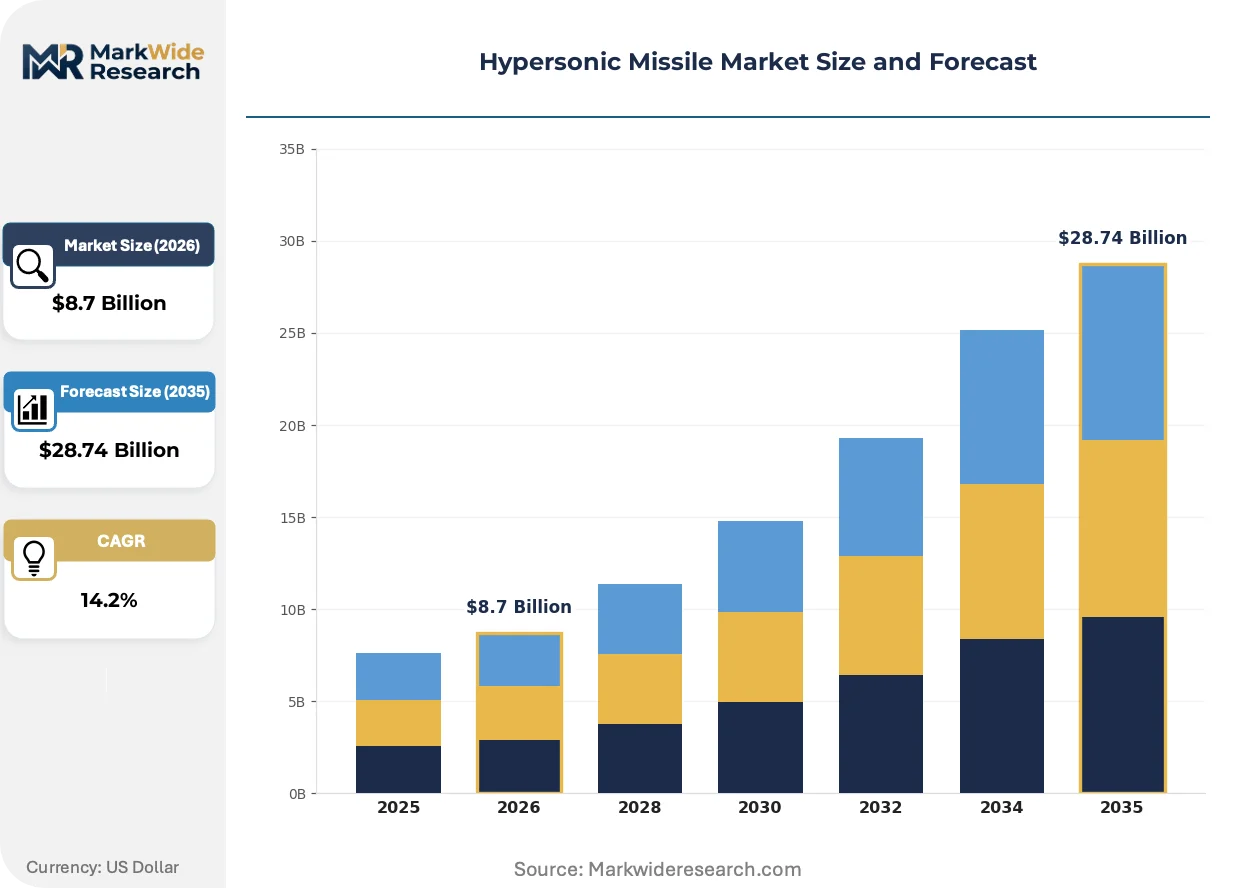
Market Dynamics
Scramjet propulsion maturation is compressing development timelines for air-breathing hypersonic platforms, forcing defense contractors to restructure thermal protection supply chains around ceramic-matrix composite foundries.
Growth Catalysts
- US Department of Defense Accelerated Testing Protocols:Streamlined flight-test schedules compress weapon system validation cycles. Pentagon procurement offices now prioritize boost-glide vehicles with proven atmospheric reentry performance.
- Ceramic-Matrix Composite Thermal Shields:Advances in silicon carbide fiber architectures enable sustained Mach 8+ flight durations. Material suppliers are scaling production capacity to match prime contractor demand.
- Integrated Air Defense Network Saturation:Adversarial investments in layered missile defense systems drive demand for maneuvering reentry vehicles. Military planners specify unpredictable trajectory profiles as mandatory mission requirements.
Market Restraints
- High-Temperature Alloy Supply Concentration:Refractory metal feedstock for scramjet combustors concentrates among a limited supplier base. Price volatility in niobium and tantalum ores directly impacts production economics.
- ITAR Export Control Friction:US State Department licensing requirements block technology transfer to allied nations seeking hypersonic capability. European and Indo-Pacific partners face extended procurement delays.
- Technical Limitation in Sustained Scramjet Ignition:Air-breathing engines require precise fuel injection across expanding Mach number ranges. Combustion instability above Mach 6 restricts operational envelope expansion.
Strategic Opportunities
- Underpenetrated Australian Defense Market:AUKUS security framework creates pathway for technology sharing with Canberra. Royal Australian Air Force seeks long-range strike capabilities compatible with allied command structures.
- Dual-Use Space Launch Applications:Hypersonic boost-glide architectures adapt to small satellite orbital insertion missions. Commercial launch providers evaluate military-derived thermal protection for reusable first stages.
- EU Green Deal Defense Procurement Criteria:European Commission mandates lower-carbon manufacturing footprints for strategic weapons programs. Suppliers demonstrating sustainable supply chains gain preferential contract evaluation.
Industry Challenges
- Aerothermodynamics Simulation Talent Scarcity:Computational fluid dynamics specialists capable of modeling non-equilibrium plasma effects command premium compensation. Prime contractors compete for limited university pipeline output.
- Flight-Test Infrastructure Bottlenecks:Western range capacity constraints limit annual test event throughput. Pacific and Atlantic test corridors face scheduling conflicts across multiple weapons programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypersonic Missile Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Glide Vehicle, Cruise Missile, Boost-Glide Vehicle, Others Technology: Air-Breathing, Rocket-Based, Hybrid, Others Application: Defense, Research, Military Operations, Offensive Operations End User: Government, Defense Contractors, Military Organizations, Research Institutions |
| Companies Covered | The Boeing Company, MBDA, Lockheed Martin Corporation, Aerojet Rocketdyne, BAE Systems, Raytheon Technologies Corporation, General Dynamics Corporation, L3Harris Technologies, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypersonic Missile Market Emerging Trajectories
Active research programs are converging on air-breathing propulsion architectures that promise extended range and payload flexibility compared to rocket-boosted alternatives. Defense laboratories prioritize technologies that compress sensor-to-shooter timelines.
Ceramic-matrix composite nose cones and leading-edge assemblies are absorbing thermal loads that previously forced trajectory compromises. US Air Force Research Laboratory flight demonstrations validate multi-use thermal protection systems. Platform designers now specify integrated structural-thermal components rather than discrete heat shield attachments, reducing mass fraction penalties.
China's SAMR and Russia's military procurement framework impose distinct testing protocols that fragment supplier eligibility across defense blocs. NATO interoperability standards constrain subsystem interchangeability between national programs. European defense agencies respond by funding indigenous scramjet research through the European Defence Fund, reducing technology dependency on transatlantic supply chains.
Defense procurement offices consolidate vendor relationships around full-system integrators rather than component suppliers. Prime contractors internalize guidance and control subsystem development to protect proprietary trajectory algorithms. This concentration shifts contract award criteria toward demonstrated platform integration experience rather than discrete technology performance.
Hypersonic Missile Market Segmentation
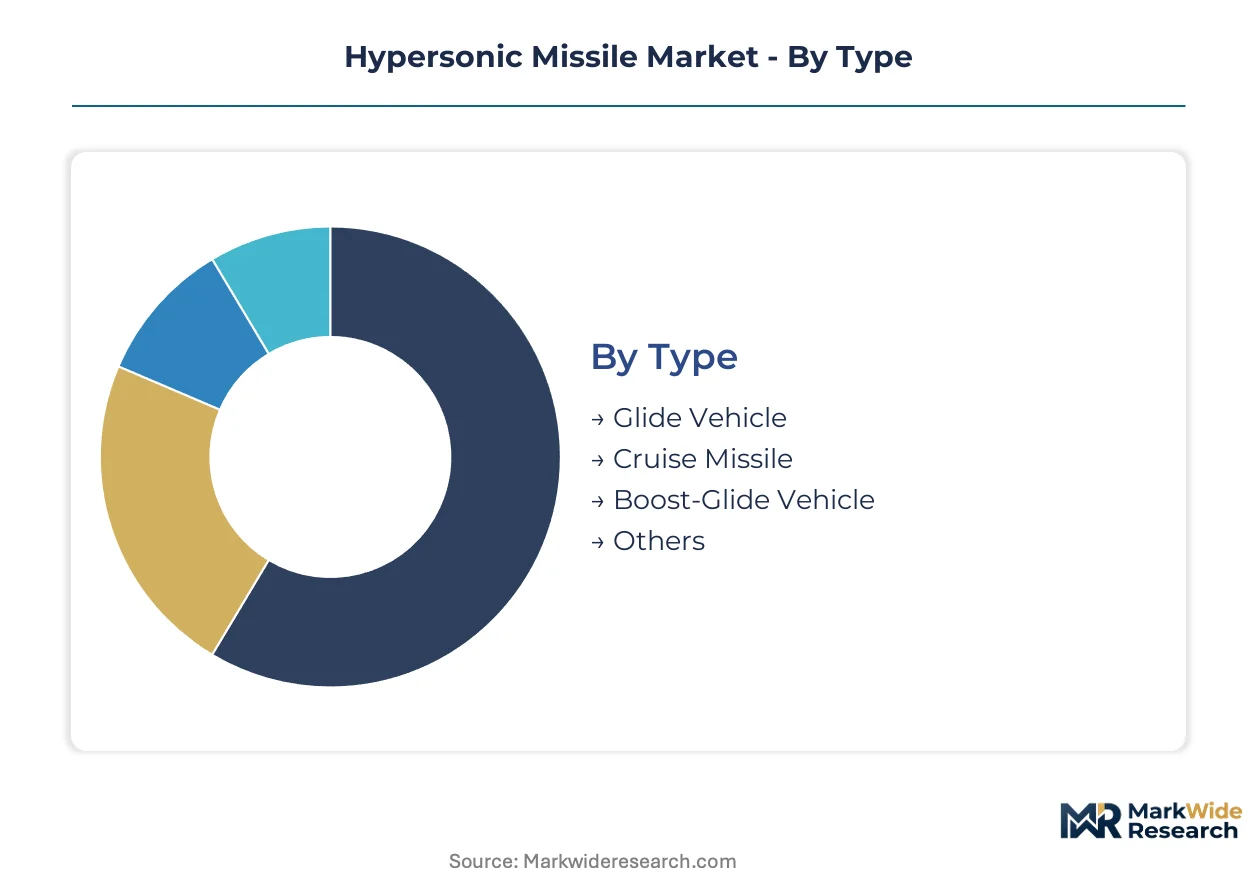
Segmentation in the hypersonic missile market reveals how procurement budgets flow toward proven architectures while development funding chases next-generation propulsion. Platform type and propulsion technology together determine supplier eligibility, test infrastructure requirements, and timeline-to-deployment.
Type:
Volume procurement concentrates in boost-glide vehicles with established test records, while premium development spending targets air-breathing alternatives promising extended range.
- Boost-Glide Vehicle:Rocket-boosted systems release unpowered maneuvering reentry vehicles at altitude. Pentagon procurement offices prioritize these platforms for near-term operational capability given their proven atmospheric reentry performance and compressed validation cycles.
- Glide Vehicle:Hypersonic glide bodies sustain controlled flight through aerodynamic lift without continuous propulsion. China's SAMR channels substantial development resources toward maneuvering reentry vehicles capable of penetrating integrated air defense networks through unpredictable trajectory profiles.
- Cruise Missile:Air-breathing platforms utilizing scramjet propulsion for sustained atmospheric flight.
- Others:Experimental architectures including waverider configurations and combined-cycle propulsion demonstrators.
Mature deployment sits with boost-glide vehicles. Newer deployment is concentrated in cruise missile platforms.
Technology:
Propulsion architecture determines thermal protection requirements, test range needs, and supplier specialization.
- Rocket-Based:Solid or liquid rocket motors deliver predictable thrust profiles with extensive production heritage. Prime contractors leverage decades of ballistic missile manufacturing experience to compress development timelines and satisfy urgent operational requirements.
- Air-Breathing:Scramjet engines ingest atmospheric oxygen to sustain combustion across Mach 5+ flight regimes. US Air Force Research Laboratory flight demonstrations validate multi-use thermal protection systems enabling extended duration at Mach 8+.
- Hybrid:Combined rocket-scramjet architectures transition between propulsion modes during flight.
- Others:Emerging concepts including rotating detonation engines and pulse detonation propulsion.
Rocket-based systems anchor current procurement volumes. Air-breathing platforms are expanding most quickly as scramjet maturation compresses development timelines.
Application:
Mission profile shapes platform specifications for maneuverability, payload capacity, and sensor integration.
- Defense:Counter-hypersonic and area denial systems designed to intercept adversary platforms. NATO interoperability standards constrain subsystem interchangeability between national programs, fragmenting supplier eligibility across defense blocs.
- Military Operations:Theater strike systems with compressed sensor-to-shooter timelines. Military planners specify unpredictable trajectory profiles as mandatory mission requirements to saturate layered missile defenses.
- Offensive Operations:Strategic strike platforms targeting high-value fixed and mobile assets.
- Research:Technology demonstration and risk reduction programs advancing propulsion and materials.
Defense applications dominate current procurement. Offensive operations represent the steepest expansion trajectory as deterrence doctrines evolve.
End User:
Customer type determines contracting mechanisms, security clearance requirements, and technology access tiers.
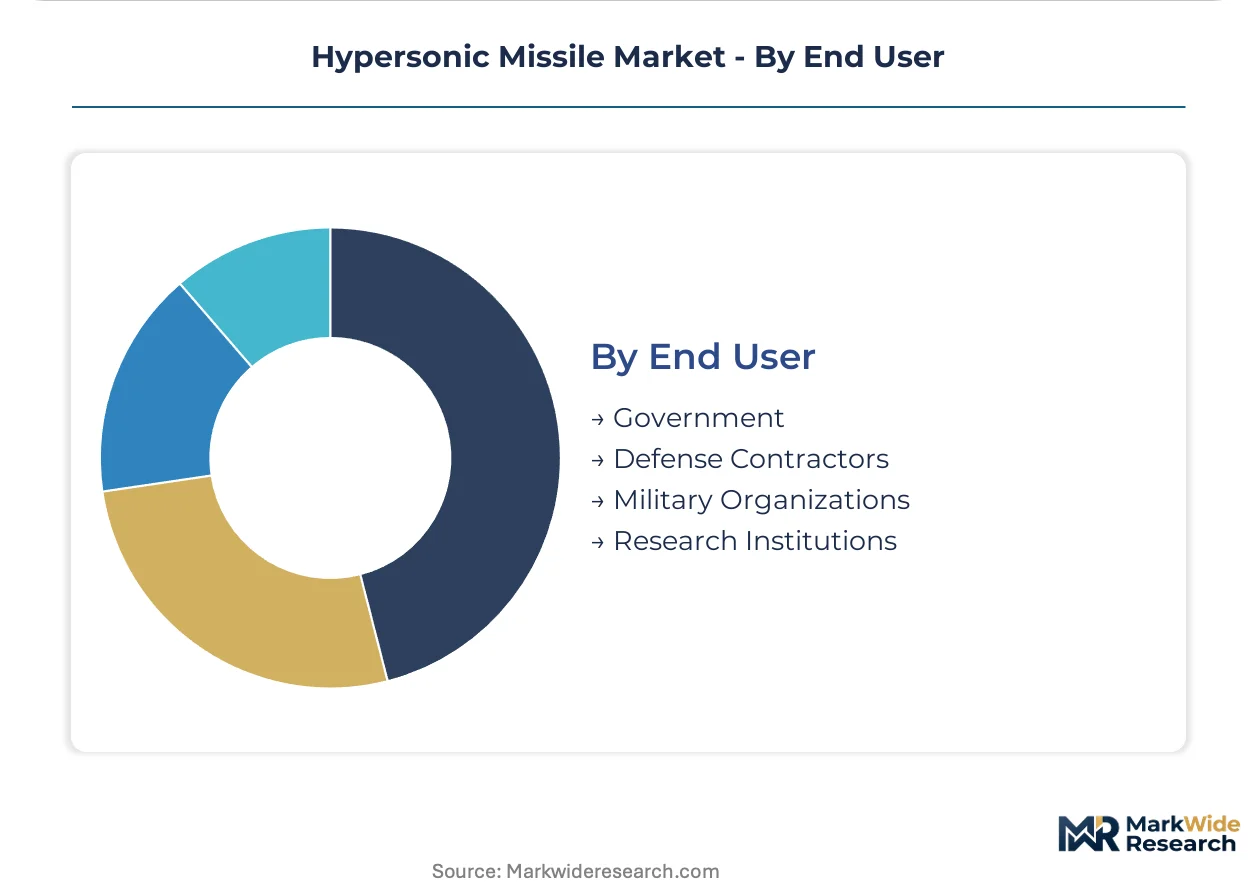
- Government:National defense ministries and military procurement offices specifying platform requirements. The US Department of Defense accelerates testing protocols to compress weapon system validation cycles and prioritize proven atmospheric reentry performance.
- Defense Contractors:Prime integrators and subsystem suppliers executing development and production contracts. Lockheed Martin Corporation leverages vertically integrated thermal protection systems to secure long-term government awards.
- Military Organizations:Operational commands defining mission profiles and deployment concepts.
- Research Institutions:National laboratories and university affiliates conducting foundational aerothermodynamics research.
Government customers anchor procurement authority. Defense contractors concentrate execution risk and margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hypersonic missile production concentrates in defense industrial bases with established aerospace manufacturing heritage, while operational demand clusters in nations pursuing strategic deterrence modernization. Procurement authorities in Washington, Beijing, and Moscow channel the dominant share of development funding toward boost-glide and scramjet platforms.
United States
The US Department of Defense accelerates flight-test schedules through streamlined validation protocols at Pacific and Atlantic ranges. Pentagon procurement offices prioritize boost-glide vehicles with proven atmospheric reentry performance, compressing weapon system development cycles. Lockheed Martin Corporation leverages vertically integrated thermal protection systems manufacturing in California and Texas to secure long-term government contracts for strategic deterrence missions.
China
China's SAMR channels substantial development resources toward maneuvering reentry vehicles capable of penetrating integrated air defense networks. The national military procurement framework imposes distinct testing protocols that fragment supplier eligibility across defense blocs. Beijing's aerospace industrial complex concentrates scramjet research in specialized facilities across the Yangtze River Delta, advancing ceramic-matrix composite architectures for sustained Mach 8+ flight.
Russia
Russia's military procurement framework emphasizes rocket-boosted hypersonic platforms with operational deployment timelines measured in months rather than years. The country's defense industrial base maintains extensive production heritage in ballistic missile manufacturing, compressing development timelines for urgent operational requirements. Moscow's research institutions prioritize thermal protection materials testing at specialized facilities in the Volga region.
United Kingdom
BAE Systems anchors British hypersonic capability development through specialized guidance and control subsystems for extreme-velocity platforms. The UK Ministry of Defence participates in NATO interoperability standards development while navigating ITAR restrictions that constrain technology transfer from transatlantic partners. Research partnerships between British universities and defense laboratories concentrate in the Cambridge-Oxford corridor, advancing aerothermodynamics simulation capabilities.
Australia
The Royal Australian Air Force seeks long-range strike capabilities compatible with allied command structures under the AUKUS security framework. Canberra's defense procurement offices evaluate technology sharing pathways that circumvent traditional export control barriers. Australian research institutions collaborate with US and UK partners on scramjet propulsion maturation at facilities in South Australia, targeting operational integration within compressed timelines.
Hypersonic Missile Market Vendor Landscape
The competitive structure tilts toward full-system integrators rather than component suppliers. Prime contractors internalize guidance and control subsystem development to protect proprietary trajectory algorithms, concentrating execution risk and margin capture among a limited tier of defense conglomerates. Two strategic archetypes dominate: vertically integrated aerospace conglomerates controlling thermal protection supply chains, and specialized propulsion houses with scramjet combustion expertise. Competitive moves center on M&A activity targeting ceramic-matrix composite foundries and strategic partnerships securing access to restricted test range infrastructure.
Among US-based defense conglomerates, Lockheed Martin Corporation and Raytheon Technologies Corporation exemplify the vertically integrated archetype, while Northrop Grumman Corporation occupies a specialized position in guidance and control subsystems. These entities anchor contract award criteria around demonstrated platform integration experience rather than discrete technology performance, consolidating vendor relationships and shifting procurement evaluation toward full-system delivery capabilities.
| Leading Market Players |
|---|
| The Boeing Company |
| MBDA |
| Lockheed Martin Corporation |
| Aerojet Rocketdyne |
| BAE Systems |
| Raytheon Technologies Corporation |
| General Dynamics Corporation |
| L3Harris Technologies |
| Northrop Grumman Corporation |
| Others |
Supply Flow & Price Mechanics
Niobium and tantalum ore price indices cascade through scramjet combustor manufacturing into three distinct procurement tiers across defense procurement offices. Rocket-based thermal protection systems anchor premium pricing due to captive silicon carbide fiber supply chains, while air-breathing platform developers absorb margin compression from refractory metal feedstock volatility.
Pricing Analysis
Flight-test validation throughput serves as the primary value-based pricing anchor for hypersonic platform contracts. Three-tier pricing structure across boost-glide, scramjet cruise, and experimental demonstrator levels reflects technical maturity and reentry performance guarantees. Price differentiation rests on thermal protection system certification grade and integrated guidance subsystem complexity. Cost compression in scramjet development tiers is intensifying because combustion instability above Mach 6 extends validation cycles. Government procurement offices demonstrate lowest price sensitivity relative to defense contractors managing fixed-price development contracts.
Supply Chain Analysis
Regional distribution centers for ceramic-matrix composite foundries concentrate in California, Texas, and the Yangtze River Delta to serve prime contractor assembly sites. Raw material dependencies center on silicon carbide fiber architectures, niobium-tantalum alloys for scramjet combustors, and high-temperature adhesives for thermal shield bonding. Supply chain risk concentrates in single-source vulnerability for refractory metal feedstock extraction. Distribution runs through classified logistics corridors directly to government-owned test range facilities and prime contractor integration plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hypersonic missile market sits in a propulsion-transition phase where scramjet air-breathing architectures displace rocket-boosted legacy systems for extended-range missions. This technology displacement compresses development timelines and reshapes supplier qualification criteria across defense procurement frameworks.
For Market Incumbents: Hedge scramjet program exposure by maintaining parallel boost-glide production capacity to satisfy urgent operational requirements from Pentagon procurement offices. Lockheed Martin Corporation and Raytheon Technologies Corporation should deepen captive supply of silicon carbide fiber architectures as ITAR restrictions fragment allied nation access. Vertical integration into thermal protection foundries protects margin capture against refractory metal price volatility.
For New Entrants and Emerging Players: The EU Green Deal in Europe opens a window for sustainable ceramic-matrix composite suppliers to penetrate defense procurement criteria mandating lower-carbon manufacturing footprints. Target Australian defense procurement under AUKUS technology-sharing frameworks as the Royal Australian Air Force accelerates long-range strike capability acquisition. Position as scramjet propulsion specialists with combustion stability solutions above Mach 6 to differentiate from established rocket-boosted incumbents.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized aerothermodynamics simulation houses in the Cambridge-Oxford corridor and South Australian research clusters where talent scarcity commands premium compensation. Long-term viability hinges on five-to-ten-year scramjet maturation trajectories toward operational deployment. Monitor flight-test infrastructure expansion at Pacific and Atlantic ranges as the inflection signal for validation throughput scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-Matrix Composite Foundry Acquisition | Captive silicon carbide fiber supply secures thermal protection margins against refractory metal volatility. |
| Scramjet Combustion Stability Program | US Air Force Research Laboratory validation above Mach 6 unlocks extended-range operational envelopes. |
| AUKUS Technology Sharing Agreement | Royal Australian Air Force integration creates allied demand outside ITAR-constrained procurement blocs. |
| EU Green Deal Certification Pathway | European Commission preferential evaluation rewards sustainable supply chain demonstration for strategic weapons. |
| Flight-Test Infrastructure Partnership | Pacific range capacity expansion resolves scheduling conflicts across multiple weapons programs. |
Methodological Framework
US Department of Defense budget justifications, China's SAMR procurement disclosures, and Russia's military procurement framework documents formed the secondary backbone for platform-level demand assessment. Primary interviews with scramjet propulsion engineers, thermal protection materials scientists, defense procurement officers, and flight-test range operators combined with secondary validation across NATO interoperability standards and ITAR licensing databases. Bottom-up triangulation of prime contractor production capacity and top-down defense budget allocation analysis converged on segment-level estimates.
Historical trendline analysis of boost-glide and scramjet test event frequency established baseline validation throughput patterns across the projection horizon. The analytical framework modeled propulsion technology type, platform application, and end-user customer tier alongside regional procurement framework clusters. CAGRs derived from segment-level growth rate reconciliation against aggregate defense modernization budget trajectories. Forecast inputs incorporated ceramic-matrix composite production scaling curves and aerothermodynamics simulation talent pipeline constraints.
Caveats apply where flight-test infrastructure bottlenecks, ITAR policy shifts, or scramjet combustion breakthroughs could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
NIJ III Ballistic Bullet Resistant Panel Market
Weapons and Ammunition
Enclosed Smokeless Flares Market
Weapons and Ammunition
Turret System Market
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
Decoy Flares Market
Weapons and Ammunition
Shoulder Fixed Weapons Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Recoilless Rifle Market
Weapons and Ammunition
US Small Caliber Ammunition Market
Weapons and Ammunition
Tank Ammunition Market
Weapons and Ammunition
Programmable Ammunition Market
Weapons and Ammunition
Martial Art Weapon Market
Weapons and Ammunition
Electromagnetic Weapons Market
Weapons and Ammunition
Ballistic Missile Market
Weapons and Ammunition
North America Nuclear Bombs and Missiles Market
Weapons and Ammunition
Asia-Pacific Ammunition Market