
 Air-Based Remote Weapon Stations Market | 2026-2036
Air-Based Remote Weapon Stations Market Size, Share, and Industry Trends Forecast 2026-2036
Air-Based Remote Weapon Stations Market Outlook
Electro-optical sensor fusion with artificial intelligence-driven targeting algorithms is tilting development priorities toward autonomous engagement capabilities. Kongsberg Gruppen leverages its Protector family lineage to sustain Nordic market dominance in helicopter-mounted systems. Elbit Systems Ltd. anchors Middle Eastern demand through vertically integrated production of mission computers and gimbal assemblies. Rafael Advanced Defense Systems competes on precision-strike integration, occupying a distinctive niche in lightweight configurations for tactical unmanned platforms.
Air-based remote weapon stations constitute stabilized, remotely operated turret systems mounted on rotary-wing aircraft, typically incorporating gyroscopic stabilization, ballistic computation engines, and multi-spectral sensors to deliver accurate suppressive or precision fire without exposing crew to hostile fire. Electro-optical and radar technology segments command the largest current procurement volumes, though laser-based designation systems represent the fastest-expanding capability layer as forces prioritize non-kinetic target marking. Military forces constitute the dominant end-user category, with defense contractors capturing expanding margin pools through performance-based logistics contracts for sustainment and spiral upgrades.
FAA airworthiness certification requirements and NATO STANAG 4670 standards constrain platform integration timelines, while national procurement regulations in Turkey and Norway mandate minimum local content thresholds that reshape supplier qualification. The EU AI Act introduces emerging compliance obligations for autonomous targeting algorithms deployed on European-registered platforms. Stakeholders must monitor divergence between sovereign data-localization mandates and coalition interoperability requirements as software-defined capabilities outpace legacy hardware certification cycles.
Market Dynamics
Artificial intelligence-driven target recognition is compressing engagement timelines and forcing hardware manufacturers to requalify legacy stabilization architectures against software-defined performance benchmarks.
Growth Catalysts
- EU AI Act compliance mandates:European defense procurement now requires algorithmic transparency documentation for autonomous targeting systems, accelerating investment in certifiable machine-learning pipelines by integrators serving NATO rotary-wing programs.
- Performance-based logistics contracting:Military end-users are bundling sustainment and spiral upgrade obligations into initial acquisition awards, extending revenue capture for turret manufacturers across multi-decade platform lifecycles.
- Turkey's local content thresholds:Ankara's defense procurement regulations mandate minimum domestic manufacturing ratios that channel foreign subsystem suppliers into joint-venture arrangements with Turkish aerospace firms.
Market Restraints
- Gyroscopic sensor supply concentration:Precision inertial measurement units for stabilization depend on a concentrated supplier base in Japan and the United States, exposing integrators to single-source vulnerability and extended lead times.
- FAA airworthiness certification friction:Civil-military platform conversions for domestic security applications face protracted validation timelines under Federal Aviation Administration Part 29 rotorcraft standards, delaying revenue recognition for dual-use configurations.
- Directed-energy substitution threat:Solid-state laser systems for non-kinetic counter-UAS missions are capturing experimental procurement budgets that might otherwise flow to kinetic remote weapon stations.
Strategic Opportunities
- Norwegian Arctic sovereignty patrols:Oslo's expanding helicopter fleet for High North surveillance creates demand for cold-weather-hardened turrets with extended sensor ranges against low-thermal-contrast targets.
- Convergence of electro-optical and signals intelligence:Fusing visual targeting with electronic warfare receivers enables single-mount multi-mission capability, reducing platform weight and power budgets for tactical unmanned rotorcraft.
- India's defense production-linked incentive scheme:New Delhi's PLI framework for aerospace components offers offset credits to foreign original equipment manufacturers establishing local final-assembly capacity for helicopter-mounted systems.
Industry Challenges
- AI/ML systems engineering talent scarcity:The specialized workforce required for autonomous targeting algorithm development concentrates in commercial autonomous vehicle and consumer electronics sectors, forcing defense contractors into compensation wars.
- NATO STANAG 4670 interoperability certification:Achieving standardized interface compliance for coalition-operated platforms demands extensive regression testing across national communication architectures, extending development cycles.
- Legacy analog turret retrofit complexity:Upgrading fielded mechanical stabilization systems to digital bus architectures requires platform-level rewiring and structural modification, complicating fleet modernization programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air-Based Remote Weapon Stations Market |
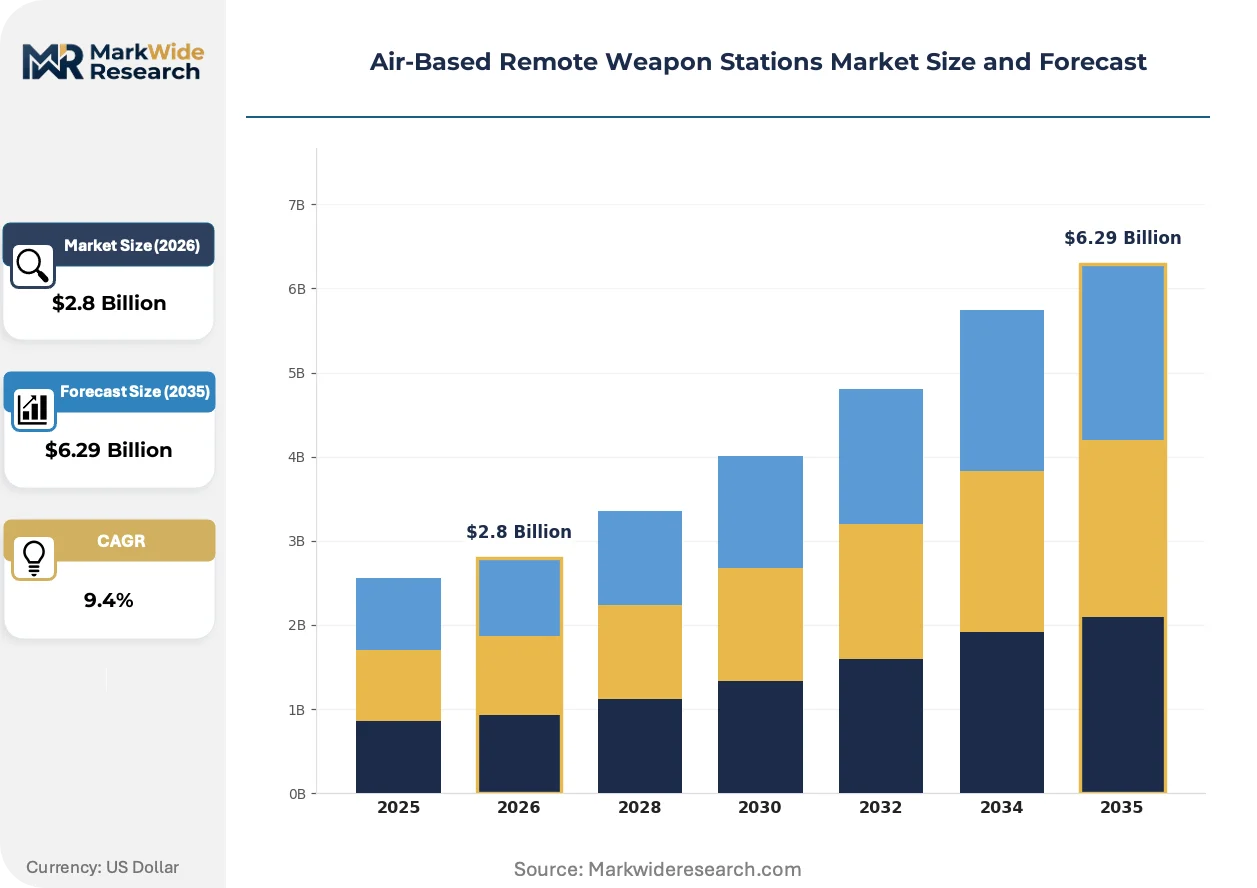
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electro-Optical, Laser, Radar, Guidance Systems End User: Military Forces, Security Agencies, Defense Contractors, OEMs Deployment: Airborne Platforms, Ground Vehicles, Naval Vessels, Drones Application: Surveillance, Targeting, Reconnaissance, Combat Operations |
| Companies Covered | Kongsberg Gruppen, BAE Systems, Elbit Systems Ltd., General Dynamics Corporation, Leonardo S.p.A., Rafael Advanced Defense Systems, Northrop Grumman Corporation, Aselsan A.S., Rheinmetall AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air-Based Remote Weapon Stations Market Strategic Shifts
Software-defined targeting architectures are displacing hardware-centric stabilization approaches, compressing product refresh cycles and reordering competitive advantage toward firms with captive algorithm development.
Synthetic aperture radar integration with electro-optical sensor suites is rendering obsolete pure-visual targeting chains dependent on atmospheric line-of-sight. Attack helicopter operators in the United States and Turkey are fielding combined RF-EO mounts for degraded-weather engagement, collapsing the traditional segmentation between fair-weather and all-weather fire control. This convergence is compressing procurement evaluation criteria around single-vendor integrated solutions rather than modular subsystem sourcing.
The EU AI Act's risk-classification framework for autonomous weapons systems is mandating algorithmic audit trails and human-in-the-loop validation protocols for platforms registered in European Union member states. Defense contractors serving NATO interoperability requirements must now maintain dual code bases: one optimized for European regulatory compliance, another for less restrictive operational theaters. Rotary-wing programs with multi-national crew training pipelines face the steepest compliance cost absorption.
Defense ministries are unbundling hardware acquisition from through-life support, awarding separate contracts for platform delivery and performance-based availability guarantees. This bifurcation is channeling margin toward specialized sustainment integrators with predictive maintenance analytics, while original equipment manufacturers face pressure to open proprietary diagnostic interfaces. The United Kingdom's helicopter fleet renewal program exemplifies this structural separation most visibly.
Air-Based Remote Weapon Stations Market Segmentation
Segmentation of air-based remote weapon stations reveals how stabilization hardware, sensor payloads, and platform integration requirements fragment procurement decisions across NATO rotary-wing programs and sovereign defense industrial bases. Technology choices determine certification pathways, while end-user categories dictate sustainment contracting structures and spiral upgrade obligations.
Technology:
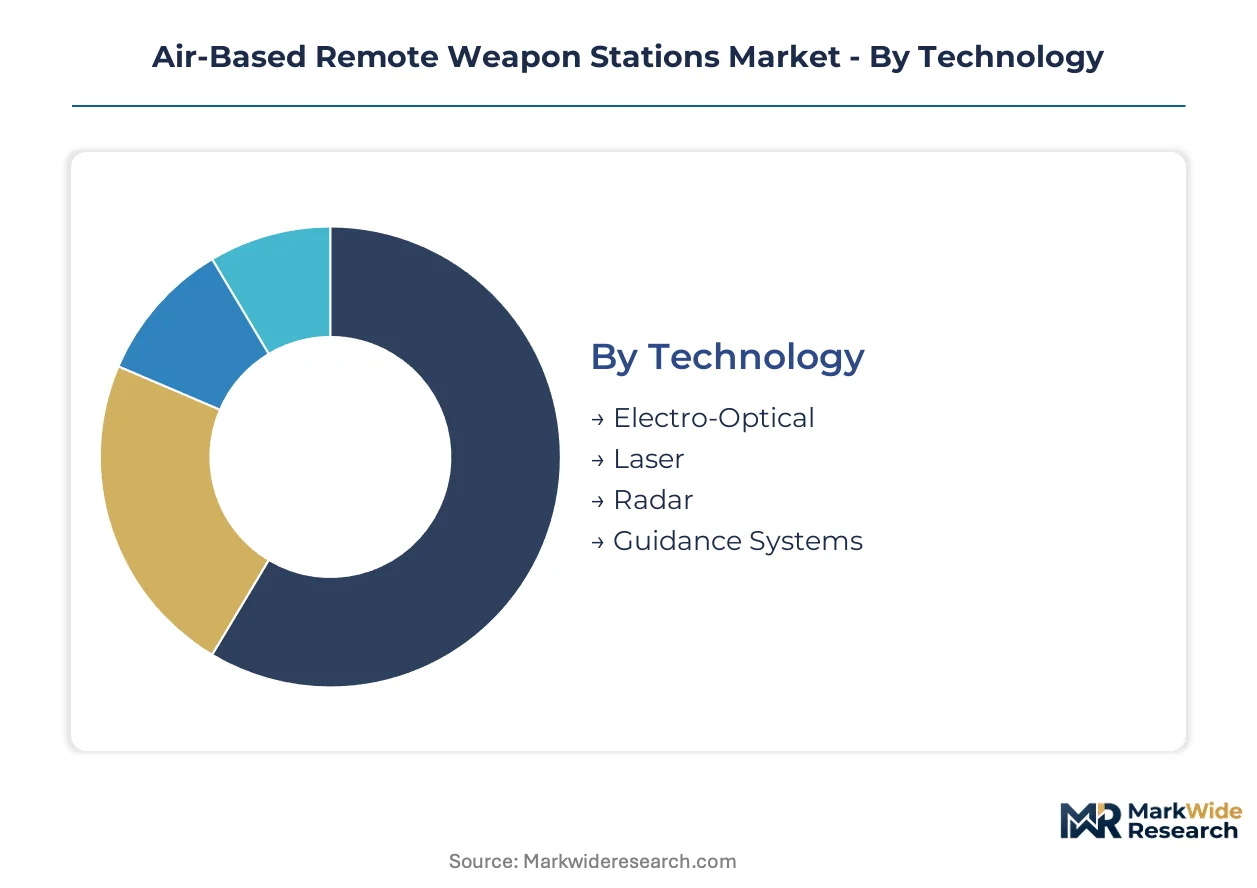
Mature electro-optical architectures dominate current fleet installations, though emerging laser and radar modalities are capturing experimental procurement budgets as forces prioritize all-weather engagement and non-kinetic countermeasures.
- Electro-Optical:Multi-spectral sensor suites combining daylight cameras, thermal imagers, and laser rangefinders deliver stabilized targeting under clear atmospheric conditions. United States Army Apache modernization programs concentrate demand here, constrained by FAA Part 29 airworthiness validation timelines for civil-military platform conversions.
- Laser:Solid-state laser designation and directed-energy systems enable precision target marking and experimental counter-UAS missions without kinetic expenditure. Turkey's domestic defense procurement regulations channel foreign subsystem suppliers into joint-venture arrangements with Turkish aerospace firms developing sovereign laser capabilities.
- Radar:Synthetic aperture radar integration penetrates weather and obscurant conditions that blind pure-visual targeting chains. Norwegian High North surveillance requirements drive cold-weather-hardened radar turret procurement for low-thermal-contrast Arctic targets.
- Guidance Systems:Ballistic computation engines and fire-control algorithms translate sensor data into weapon release commands. EU AI Act compliance mandates now require algorithmic transparency documentation for autonomous targeting functions on European-registered platforms.
Electro-optical configurations handle the majority of throughput; laser systems are the fastest mover on share.
End User:
Customer concentration tilts toward sovereign military procurement with long-cycle sustainment obligations, while defense contractors and OEMs capture margin through performance-based availability guarantees and spiral technology insertion.
- Military Forces:National armed forces constitute the dominant procurement channel, bundling platform acquisition with multi-decade logistics support. United Kingdom helicopter fleet renewal exemplifies structural separation between hardware delivery and through-life support contracting.
- Security Agencies:Domestic security applications face protracted FAA certification friction for rotorcraft weaponization, delaying revenue recognition for dual-use configurations intended for border patrol and counter-narcotics missions.
- Defense Contractors:Specialized sustainment integrators with predictive maintenance analytics capture expanding margin pools as ministries unbundle acquisition from availability guarantees. These firms require open proprietary diagnostic interfaces from original equipment manufacturers.
- OEMs:Original equipment manufacturers face pressure to localize final-assembly capacity under India's PLI framework for aerospace components, trading offset credits for established production infrastructure.
Military end-users anchor procurement volume; defense contractors are expanding most quickly as sustainment unbundling accelerates.
Deployment:
Platform integration requirements vary sharply by operational domain, with airborne configurations commanding premium pricing for gyroscopic stabilization and weight minimization against naval and ground variants.
- Airborne Platforms:Rotary-wing aircraft demand the most compact, lightweight turret assemblies with gyroscopic stabilization for high-vibration environments. NATO STANAG 4670 interoperability certification forces extensive regression testing across national communication architectures.
- Ground Vehicles:Wheeled and tracked platforms accommodate heavier sensor payloads with less stringent weight optimization, though stabilization requirements persist for mobile firing positions.
- Naval Vessels:Maritime deployments prioritize corrosion resistance and stabilization against vessel motion rather than airborne vibration profiles, with distinct supply chains for naval-grade electro-optics.
- Drones:Tactical unmanned rotorcraft impose severe power and payload constraints, driving convergence of electro-optical and signals intelligence functions into single-mount multi-mission configurations.
Airborne platforms concentrate procurement investment; drones are climbing the fastest as tactical unmanned programs proliferate.
Application:
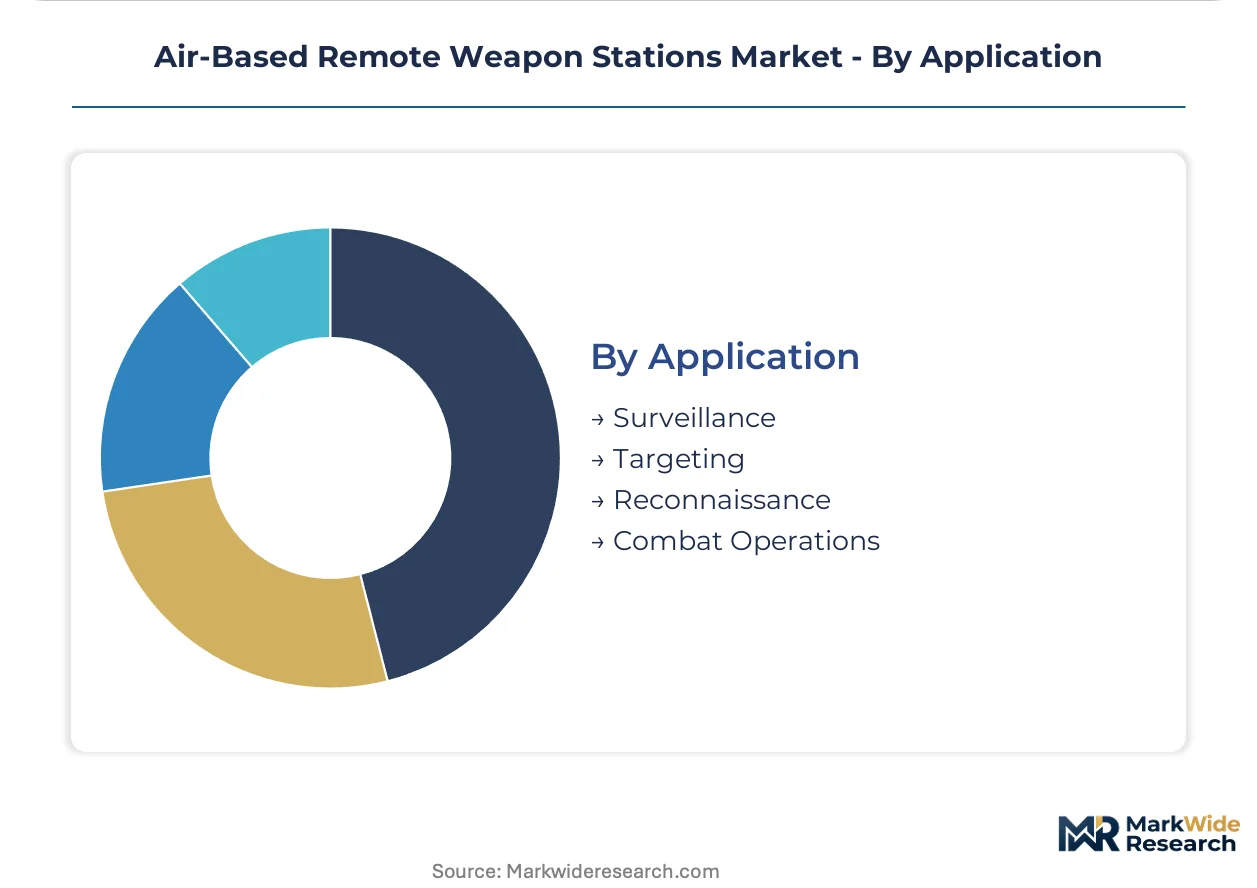
Mission profiles differentiate sensor and weapon integration requirements, with surveillance and reconnaissance applications prioritizing endurance and resolution while combat operations demand minimized engagement timelines.
- Surveillance:Persistent wide-area coverage requires stabilized long-range optics with low-power consumption for extended sorties. Norwegian Arctic sovereignty patrols exemplify demand for extended sensor ranges against difficult thermal backgrounds.
- Targeting:Precision fire control integration compresses sensor-to-shooter timelines, with artificial intelligence-driven target recognition forcing hardware manufacturers to requalify legacy stabilization architectures.
- Reconnaissance:Multi-spectral data collection for intelligence preparation of the battlefield fuses visual targeting with electronic warfare receivers, enabling single-vendor integrated solutions rather than modular subsystem sourcing.
- Combat Operations:Suppressive and precision fire delivery under hostile conditions demands hardened turret protection and redundant control linkages, with human-in-the-loop validation protocols mandated by EU AI Act risk classifications.
Surveillance missions handle the majority of installed base; combat operations are gaining share fastest as autonomous engagement capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of stabilized turret systems concentrate among NATO member states with sovereign manufacturing capacity, while import demand rises in emerging helicopter operators seeking rapid capability acquisition. Trade balances favor established defense industrial bases with captive gyroscopic sensor supply chains.
United States
Army Apache modernization programs drive procurement of multi-spectral electro-optical suites, with FAA Part 29 airworthiness standards constraining civil-military platform conversions. The Department of Defense bundles multi-decade sustainment into initial acquisition awards. Arizona and Texas host final assembly clusters where prime contractors integrate mission computers with gimbal assemblies.
Turkey
Ankara's defense procurement regulations mandate minimum domestic manufacturing ratios that channel foreign subsystem suppliers into joint-venture arrangements with Turkish aerospace firms. The Presidency of Defense Industries enforces local content thresholds across rotary-wing programs. Ankara and Istanbul anchor production clusters where Aselsan A.S. coordinates sovereign laser capability development with international partners.
Norway
High North surveillance requirements generate demand for cold-weather-hardened turrets with extended sensor ranges against low-thermal-contrast Arctic targets. NATO STANAG 4670 interoperability certification shapes procurement specifications for coalition-operated platforms. Kongsberg hosts the primary integration cluster where the Protector family lineage sustains Nordic market dominance.
Germany
Bundeswehr helicopter fleet renewal prioritizes all-weather engagement capabilities through synthetic aperture radar integration with electro-optical sensor suites. EU AI Act risk-classification frameworks mandate algorithmic audit trails for autonomous targeting functions. Bavaria and Lower Saxony concentrate subsystem development where Rheinmetall AG coordinates fire-control algorithm qualification.
India
Defense production-linked incentive schemes offer offset credits to foreign original equipment manufacturers establishing local final-assembly capacity for helicopter-mounted systems. The Ministry of Defence channels procurement toward domestic value capture. Bangalore and Hyderabad emerge as integration hubs where foreign primes partner with Hindustan Aeronautics Limited for platform-level weaponization.
Air-Based Remote Weapon Stations Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated defense primes with captive algorithm development and sovereign manufacturing mandates. Tiered competitive dynamics separate full-system integrators from specialized subsystem suppliers. Two strategic archetypes dominate: Nordic and Israeli firms leveraging multi-decade turret lineages, and diversified aerospace conglomerates spanning fixed-wing and rotary-wing applications. Competitive moves center on performance-based logistics contracting and joint-venture localization to satisfy national content requirements.
Among Nordic specialists, Kongsberg Gruppen represents the stabilized-turret heritage archetype, while Rafael Advanced Defense Systems exemplifies precision-strike integration for lightweight configurations. Elbit Systems Ltd. anchors the Middle Eastern demand cluster through vertically integrated production. These three firms occupy positions that reflect distinct geographic industrial bases and regulatory compliance specializations rather than interchangeable commodity supply.
| Leading Market Players |
|---|
| Kongsberg Gruppen |
| BAE Systems |
| Elbit Systems Ltd. |
| General Dynamics Corporation |
| Leonardo S.p.A. |
| Rafael Advanced Defense Systems |
| Northrop Grumman Corporation |
| Aselsan A.S. |
| Rheinmetall AG |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Japanese precision inertial measurement unit fabrication drives dual sourcing mandates among NATO integrators, compressing margins on gyroscopic stabilization subsystems while elevating premium pricing for qualified alternative suppliers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across multi-decade platform lifecycles. Pricing stratifies across NATO STANAG 4670-certified configurations, standard military-grade systems, and economy-tier retrofit kits for legacy analog turrets. Cost compression in economy-tier retrofits is intensifying because India's PLI scheme channels foreign primes toward local final-assembly partnerships. Defense contractors with performance-based logistics obligations exhibit lowest price sensitivity; security agencies facing FAA Part 29 civil-military conversion timelines show highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Export-control restrictions under the US International Traffic in Arms Regulations and EU dual-use technology frameworks constrain cross-border flows of synthetic aperture radar components and AI-enabled fire-control algorithms. Supply concentrates in Japan for precision gyroscopic sensors, the United States for mission computers and gimbal assemblies, and Turkey for sovereign laser capability development through joint-venture structures. Raw material dependencies span rare-earth elements for laser rangefinders, high-grade aluminum alloys for turret housings, and specialized semiconductors for ballistic computation engines. Single-source vulnerability in Japanese inertial measurement unit production constitutes the dominant structural risk. Distribution runs through prime contractor integration clusters in Arizona, Texas, Kongsberg, and Ankara with direct military procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat structure sustained by regulatory entrenchment: NATO STANAG 4670 interoperability certification and FAA Part 29 airworthiness standards create multi-year qualification barriers that protect incumbent positions.
For Market Incumbents: Insulate algorithm development capabilities through captive machine-learning pipeline investment, countering talent scarcity from commercial autonomous vehicle sectors. Expand backward integration into precision inertial measurement unit supply through qualified secondary sourcing in Norway or domestic US fabrication, mitigating Japanese single-source exposure. Deepen performance-based logistics contracting structures to capture through-life revenue streams as defense ministries unbundle acquisition from sustainment. For New Entrants and Emerging Players: India's defense production-linked incentive scheme offers the most penetrable entry vector for foreign original equipment manufacturers seeking offset credits through local final-assembly partnerships. Target tactical unmanned rotorcraft segments where severe power and payload constraints favor lightweight, single-mount multi-mission configurations over established heavy-lift helicopter systems. Pursue joint-venture arrangements with Turkish aerospace firms to satisfy Ankara's local content thresholds across rotary-wing programs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-enabled targeting algorithm development, favoring acquisition of specialized software-defined capability shops over hardware-centric turret manufacturers. Long-term viability over the coming decade rests on regulatory compliance specialization rather than commodity stabilization hardware. Target acquisition archetype: mid-tier firms with EU AI Act audit-trail documentation and dual code-base maintenance for European versus non-European operational theaters. The signal to watch is divergence between sovereign data-localization mandates and coalition interoperability requirements as software refresh cycles compress.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Logistics Contracting | Bundles sustainment with acquisition, extending revenue capture for Kongsberg and Elbit across platform lifecycles. |
| Joint Venture Localization | Satisfies Turkish local content thresholds and Indian PLI offset requirements through Aselsan and HAL partnerships. |
| AI/ML Talent Acquisition | Addresses algorithm development scarcity by recruiting from commercial autonomous vehicle sectors for fire-control qualification. |
| Cold-Weather Hardening Investment | Captures Norwegian High North surveillance demand for extended sensor ranges against low-thermal-contrast Arctic targets. |
| Dual Code-Base Maintenance | Enables EU AI Act compliance for European-registered platforms alongside less restrictive operational theater configurations. |
Study Parameters
Operator-level perspectives from rotary-wing program managers, defense procurement officers, turret integration engineers, and performance-based logistics contract administrators anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation against NATO STANAG documentation, FAA Part 29 airworthiness filings, EU AI Act regulatory texts, and national defense procurement regulations. Bottom-up platform-level demand assessment triangulated against top-down military budget allocation analysis across the United States, Turkey, Norway, Germany, and India.
Scenario-bracketing around EU AI Act implementation timelines, Turkish local content threshold enforcement, and Indian PLI scheme expansion framed analytical boundaries. Segmentation dimensions modeled encompass technology modality, end-user category, deployment platform, and application mission profile alongside geographic regulatory cluster. CAGRs derived from fitted growth curves against historical procurement trajectories, with inputs spanning defense ministry budget disclosures, helicopter fleet modernization announcements, and sustainment contract award values.
Macroeconomic conditions sit as an overlay; deviation in defense budget prioritization, rare-earth element pricing, or semiconductor availability would shift the trajectory. Forecasts reflect documented assumptions regarding NATO interoperability requirements and sovereign manufacturing mandate evolution. Material shifts in autonomous weapons systems regulation or directed-energy technology maturation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
FLIR and Laser Designator Targeting Pods Market
Military Equipment and Infrastructure
Military Displays Market
Military Equipment and Infrastructure
CBRN Protection Equipment Market
Military Equipment and Infrastructure
Soft Wall Military Shelter Market
Military Equipment and Infrastructure
Latin America Defense Market
Military Equipment and Infrastructure
Military Test Equipment Market
Military Equipment and Infrastructure
Global Mine Countermeasures Market
Military Equipment and Infrastructure
Manpack Military Antennas Market
Military Equipment and Infrastructure
Rocket Solid Propulsion Market
Military Equipment and Infrastructure
Deployable Military Shelters Market
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Global Stealth Warfare Market
Military Equipment and Infrastructure
Global Remote Weapon Station Market
Military Equipment and Infrastructure
Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Military Infrastructure and Logistics Market
Military Equipment and Infrastructure
Military Optoelectronic System Market