
 Sniper Rifle Market | 2026-2036
Sniper Rifle Market Size, Share, and Industry Trends Forecast 2026-2036
Sniper Rifle Market Intelligence
Gunsmithing expertise scarcity is reorganizing production capacity across the precision firearms sector. Accuracy International leverages its British engineering heritage to sustain premium bolt-action dominance in military tender markets. Barrett anchors the heavy-caliber segment through in-house .50 BMG manufacturing scale. Sig Sauer competes across semi-automatic platforms with integrated suppressor and optic ecosystem control.
A sniper rifle is a precision-manufactured long gun featuring match-grade barrel construction, free-floated handguards, and adjustable trigger systems typically set below 3.5 pounds, designed to deliver sub-MOA accuracy at extended ranges for designated marksman or special operations roles. Bolt action configurations occupy the highest-margin military and law enforcement tiers where reliability under field contamination remains non-negotiable. Semi-automatic platforms represent the fastest-growing type segment as security contractors and competitive shooters prioritize rapid follow-up shot capability. The 6.5mm Creedmoor caliber category is displacing legacy 7.62mm NATO inventories among marksmen seeking superior ballistic coefficients at intermediate distances.
The US State Department's Directorate of Defense Trade Controls enforces ITAR export licensing that constrains cross-border sales of precision rifle systems and associated night vision optics. The EU Firearms Directive, implemented through national regulators like Germany's KBA, mandates end-user certification and tracking documentation that lengthens procurement cycles for European law enforcement agencies. Stakeholders must monitor evolving ammunition classification debates and end-user verification protocol changes that could restrict channel access or trigger compliance-driven product redesign requirements.
Market Dynamics
Gunsmithing expertise scarcity is concentrating production capacity among a handful of specialized manufacturers with in-house barrel-making capabilities, while NATO military procurement standardization accelerates platform consolidation across allied forces.
Growth Catalysts
- ITAR Export Licensing Modernization:Proposed streamlining of US State Department Directorate of Defense Trade Controls review timelines is reducing order-to-delivery cycles for precision rifle systems bound to Five Eyes partners.
- 6.5mm Creedmoor Ballistic Migration:US special operations units and European marksmanship programs are replacing legacy 7.62mm NATO inventories, driving replacement demand for matched barrel, bolt, and magazine systems.
- Suppressor-Integrated Platform Demand:Law enforcement tactical teams and security contractors are specifying factory-integrated sound suppression, eliminating aftermarket compatibility risks and accelerating semi-automatic platform adoption.
Market Restraints
- Match-Grade Barrel Input Concentration:Premium hammer-forged barrel blanks rely on a limited supplier base in Austria and Germany, exposing manufacturers to 18-24 month order backlogs during surge demand periods.
- EU Firearms Directive Certification Friction:Germany's KBA and France's ANSM end-user verification protocols add 6-12 months to European law enforcement tender cycles, compressing vendor cash conversion.
- Optics-Night Vision ITAR Bundling:Thermal and clip-on night vision devices classified under the same export control categories as rifle systems restrict complete-weapon-package sales to non-NATO buyers.
Strategic Opportunities
- Poland and Baltic Procurement Surge:NATO eastern flank defense modernization programs are creating first-time precision rifle procurement opportunities outside traditional US, UK, and German buyer pools.
- Competitive Shooting Ammunition Convergence:Factory match-grade 6.5mm Creedmoor and .300 Norma Magnum ammunition availability is bridging the gap between military specification and civilian precision rifle performance standards.
- Carbon Fiber Barrel Sleeve Technology:Hybrid steel-carbon fiber barrel constructions are reducing weight penalties in long-range platforms without sacrificing harmonic stability, opening mobile sniper team applications previously dominated by lighter calibers.
Industry Challenges
- Master Gunsmith Workforce Attrition:Retirement waves among precision barrel lappers and action truing specialists are extending production lead times at established manufacturers unable to replicate tacit knowledge through automated processes.
- Suppressor Baffle Stack IP Litigation:Patent disputes over flow-through and K-baffle geometries are forcing secondary suppliers into costly licensing arrangements or redesign cycles that delay platform certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sniper Rifle Market |
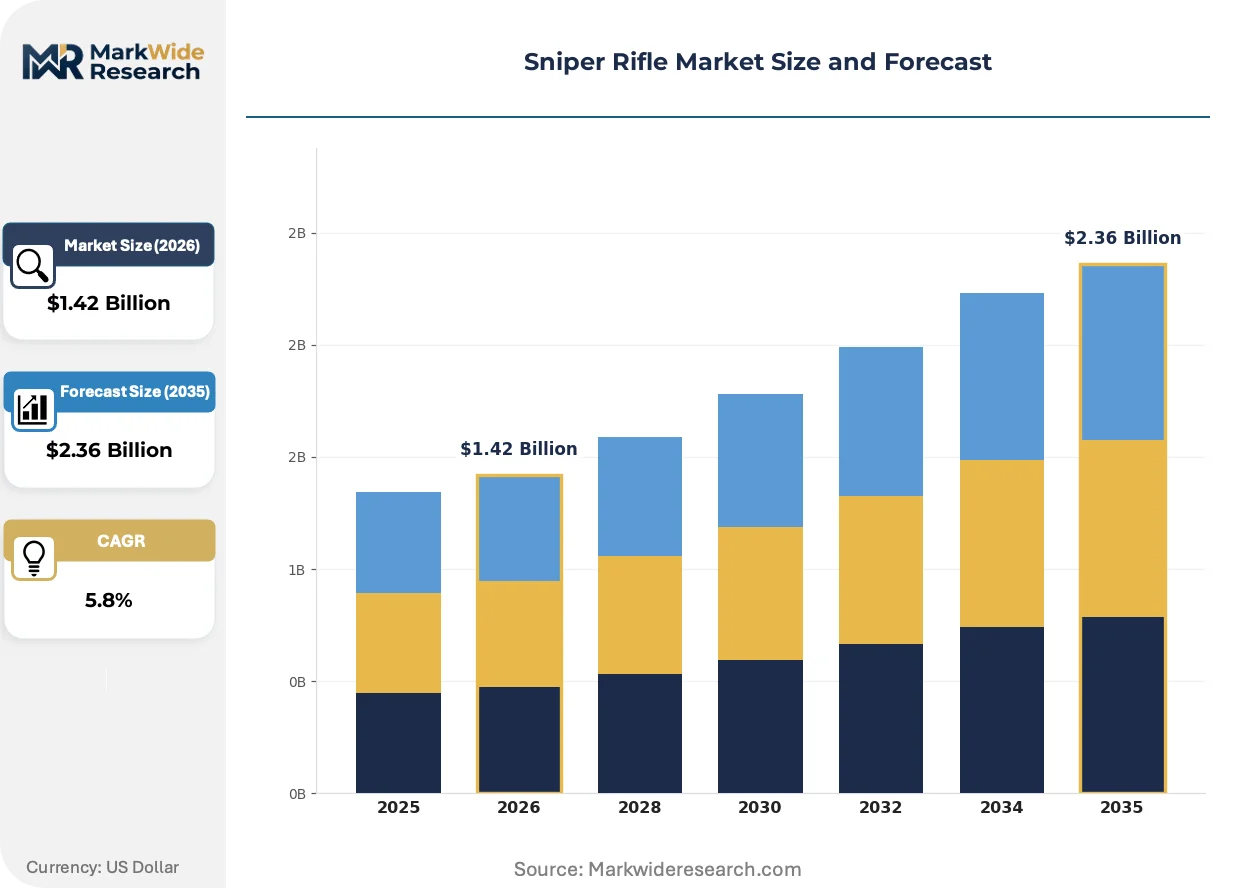
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Bolt Action, Semi-Automatic, Pump Action, Lever Action Caliber: 7.62mm, .50 BMG, 6.5mm Creedmoor, .338 Lapua Magnum, .300 Winchester Magnum Application: Military, Law Enforcement, Competitive Shooting, Wildlife Management End User: Special Forces, Border Patrol, Security Contractors, Marksmen |
| Companies Covered | Tikka, Accuracy International, Barrett, Sig Sauer, Horizon Lord, Ruger, Bergara, FN Herstal, McMillan Firearms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sniper Rifle Market Strategic Shifts & Innovations
Precision rifle architecture is converging around modular chassis systems that separate fire control, barrel, and stock interfaces, enabling caliber and configuration swaps without armorer-level gunsmithing intervention.
Hybrid polymer-steel receiver constructions are displacing traditional aluminum billet machining in law enforcement and security contractor segments. Sig Sauer and Daniel Defense have accelerated polymer-reinforced lower receiver adoption for patrol-designated marksman rifles. This material shift is compressing unit production costs while maintaining sub-MOA accuracy guarantees through bedding interface standardization.
The EU Firearms Directive's 2021 implementing guidelines are mandating serialized component tracking from manufacturer through end-user destruction. Germany's KBA and France's ANSM are enforcing blockchain-anchored custody documentation for law enforcement tenders. European precision rifle vendors are responding by integrating RFID-enabled grip modules and bolt assemblies that automate chain-of-custody logging.
Security contractor procurement offices are consolidating vendor relationships around single-source platform ecosystems. End-users in Iraq, Afghanistan, and African stability operations now specify complete weapon-optic-suppressor-ammunition packages from sole manufacturers. This bundling behavior favors vendors with captive suppressor and optic divisions, compressing aftermarket accessory margins and raising barriers for component specialists lacking integrated catalog depth.
Sniper Rifle Market Segmentation
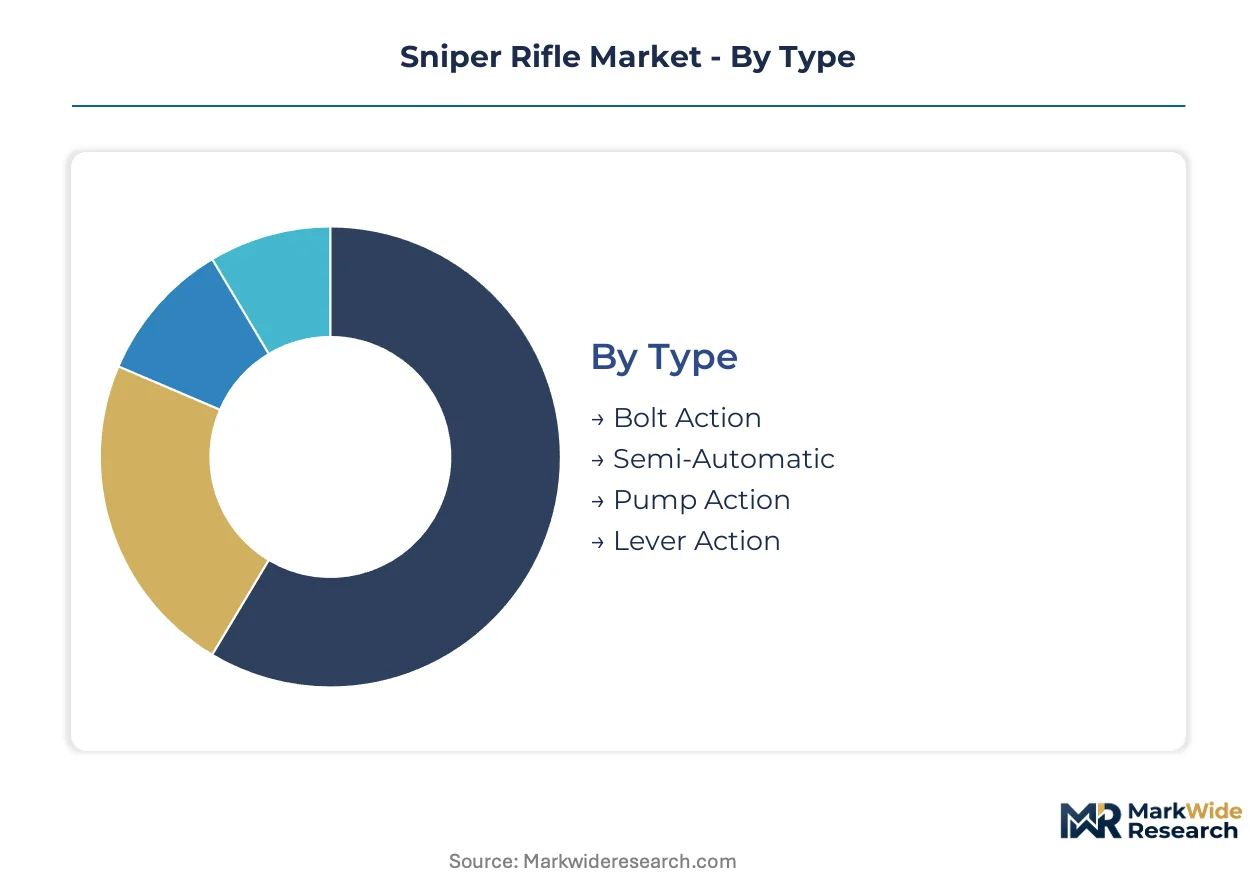
Precision rifle procurement splits across operational requirements that dictate reliability thresholds, engagement distances, and ammunition logistics. Regulatory frameworks in NATO member states and US export controls create divergent certification pathways for each segment configuration.
Type:
ITAR export licensing distinguishes bolt-action platforms as unrestricted military articles versus semi-automatic systems facing enhanced State Department review timelines.
- Bolt Action:Manually operated rotating bolt systems with two-lug or three-lug locking configurations deliver sub-MOA accuracy through rigid receiver-to-barrel interfaces. US special operations units and British Army sniper programs specify these platforms for field contamination tolerance. The US State Department classifies these as less sensitive munitions items, streamlining Five Eyes partner transfers.
- Semi-Automatic:Gas-operated or short-stroke piston mechanisms enable rapid follow-up shot capability through detachable box magazines. Law enforcement tactical teams in Germany and security contractors in Poland prioritize factory-integrated suppressor variants. Germany's KBA mandates enhanced end-user verification for these systems, extending tender cycles.
- Pump Action:Sliding forend manual cycling provides reliability in extreme environmental conditions with minimal maintenance requirements. Wildlife management agencies in Canada specify these for harsh-weather predator control programs.
- Lever Action:Tubular magazine under-barrel configurations offer compact handling for close-range precision applications. Competitive shooting disciplines in Australia and heritage law enforcement units maintain limited procurement of these platforms.
Established volume favors Bolt Action; emerging adoption favors Semi-Automatic.
Caliber:
Ballistic coefficient performance and ammunition supply chain availability determine caliber selection across military specification and civilian precision markets.
- 7.62mm:Legacy NATO standard cartridge with extensive logistics infrastructure and match-grade ammunition availability. European marksmanship programs and reserve military units maintain inventories despite ballistic limitations at extended ranges.
- .50 BMG:Heavy machine gun-derived cartridge delivering anti-materiel capability at 1,800+ meter distances. US military designated marksmen and Middle Eastern security contractors specify Barrett-manufactured platforms for vehicle and equipment interdiction.
- 6.5mm Creedmoor:Optimized case geometry and superior sectional density drive replacement of 7.62mm inventories in precision applications. US special operations command and Scandinavian military programs are expanding adoption fastest.
- .338 Lapua Magnum:Magnum-length action cartridge bridging intermediate and heavy-caliber performance for 1,500-meter engagements. British and Dutch military sniper programs specify these for overmatch against body-armored targets.
- .300 Winchester Magnum:Belted magnum case design with established long-range performance in military and competitive applications. US Marine Corps and elite law enforcement units maintain these for mixed-terrain operations.
Logistics infrastructure anchors 7.62mm procurement; ballistic migration accelerates 6.5mm Creedmoor expansion.
Application:
End-use certification requirements and operational tempo dictate platform specification, maintenance protocols, and ammunition resupply models.
- Military:Full-spectrum combat operations requiring reliability under contamination, extreme temperatures, and sustained firing schedules. NATO standardization agreements drive platform consolidation across allied forces.
- Law Enforcement:Urban and suburban precision engagement with strict collateral damage constraints. German KBA and French ANSM documentation requirements lengthen procurement cycles for these agencies.
- Competitive Shooting:Factory match-grade ammunition convergence and standardized course-of-fire requirements drive civilian precision rifle specifications. US-based precision rifle series and European practical rifle competitions sustain demand.
- Wildlife Management:Selective culling and predator control operations requiring subsonic capability and reduced signature. Canadian and Australian government agencies specify these for environmental management programs.
Procurement standardization concentrates Military volume; Competitive Shooting shows steepest expansion trajectory.
End User:
Training investment levels and mission profiles create distinct procurement authority structures and platform lifecycle expectations.
- Special Forces:Tier-one units with dedicated armorer support and unlimited ammunition budgets for proficiency maintenance. US Joint Special Operations Command and British Special Boat Service specify premium chassis systems with multi-caliber capability.
- Border Patrol:Extended-area surveillance and interdiction operations requiring vehicle-portable precision systems. US Customs and Border Protection maintains the largest federal law enforcement precision rifle inventory.
- Security Contractors:Private military companies operating under government contracts with variable equipment authorization. Iraqi and Afghan stability operations drove consolidated vendor relationships around complete weapon-optic-suppressor packages.
- Marksmen:Individual competitive shooters and designated marksman role fillers with personal equipment investment capacity. Civilian precision rifle series participants and military reservists self-fund platform upgrades.
Budget concentration favors Special Forces; procurement flexibility favors Security Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across procurement authorities. United States special operations units prioritize rapid-replacement cycles and multi-caliber chassis systems, while European agencies emphasize serialized-component tracking and extended tender documentation under EU Firearms Directive mandates.
United States
Joint Special Operations Command and Customs and Border Protection sustain the largest federal precision rifle inventories through dedicated armorer support and unlimited ammunition budgets. The State Department's Directorate of Defense Trade Controls enforces ITAR licensing that constrains complete-weapon-package exports to non-NATO buyers. Manufacturing clusters concentrate in New Hampshire and Arizona, where in-house barrel-making capabilities anchor premium bolt-action production.
Germany
Federal Police tactical teams and Bundeswehr marksmanship programs drive semi-automatic platform demand with factory-integrated suppressor specifications. The Kraftfahrt-Bundesamt mandates enhanced end-user verification protocols that extend law enforcement tender cycles by 6-12 months. Industrial capacity clusters in Suhl and Oberndorf am Neckar, where centuries-old gunsmithing heritage supports hammer-forged barrel production for domestic and export markets.
United Kingdom
British Army sniper programs and Special Boat Service units specify premium bolt-action systems with field contamination tolerance requirements. Ministry of Defence procurement operates under consolidated NATO standardization agreements that streamline cross-border platform transfers. Precision engineering concentrates in Portsmouth and Birmingham, where match-grade receiver machining and chassis system assembly serve allied military tender markets.
Poland
Ministry of National Defence modernization programs are creating first-time precision rifle procurement opportunities as NATO eastern flank defense spending accelerates. Territorial Defence Forces and special units prioritize vehicle-portable systems for extended-area surveillance operations. Emerging industrial partnerships in Radom and Łucznik facilities are developing licensed production capabilities to reduce import dependency.
France
GIGN counter-terrorism units and Army marksmanship programs specify hybrid polymer-steel receiver constructions for patrol-designated marksman applications. The Agence Nationale de Sécurité du Médicament enforces blockchain-anchored custody documentation for law enforcement tenders under EU Firearms Directive implementing guidelines. Manufacturing activity concentrates in Saint-Étienne, where state-owned arsenals and private contractors co-locate for NATO-compliant platform assembly.
Sniper Rifle Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in precision rifle manufacturing. The upper tier commands premium pricing through captive barrel-making capabilities and in-house suppressor divisions. The specialist tier competes on match-grade accuracy guarantees and aftermarket customization services. Two strategic archetypes dominate: vertically integrated chassis-to-optic ecosystem vendors, and component-focused shops with deep gunsmithing expertise. Competitive dynamics center on NATO tender certification speed and ITAR compliance bundling.
Within the integrated-leader tier, Accuracy International and Barrett exemplify divergent scale strategies. Accuracy International occupies a position anchored in British engineering heritage and military tender dominance. Barrett represents heavy-caliber specialization through in-house manufacturing scale. Sig Sauer sits within the ecosystem-control archetype, competing across semi-automatic platforms with suppressor and optic integration. These three anchors illustrate how geographic origin and structural configuration shape competitive positioning under divergent regulatory frameworks.
| Leading Market Players |
|---|
| Tikka |
| Accuracy International |
| Barrett |
| Sig Sauer |
| Horizon Lord |
| Ruger |
| Bergara |
| FN Herstal |
| McMillan Firearms |
| Others |
Cost & Logistics Intelligence
Long-term military procurement contracts with NATO standardization clauses lock in multi-year barrel blank allocations and suppress component price volatility for prime vendors. These agreements tether unit pricing to raw material indices while guaranteeing capacity reservation at Austrian and German hammer-forged suppliers, insulating defense contractors from spot-market ammunition cost swings that disrupt commercial precision rifle margins.
Pricing Analysis
Project-based tender pricing dominates military and law enforcement segments, with unit costs scaling to certification grade and ITAR compliance bundling. Price differentiation separates NATO-standard platforms with end-user verification documentation from commercial match-grade systems lacking export licensing overhead. Cost compression in semi-automatic law enforcement tiers intensifies as Sig Sauer and Daniel Defense expand polymer-receiver manufacturing scale. Security contractors exhibit lowest price sensitivity due to consolidated vendor relationships, while civilian competitive shooters face greatest budget constraints.
Supply Chain Analysis
Hammer-forged barrel blank production in Austria and Germany underwrites global precision rifle accuracy guarantees, with single-source vulnerability concentrated at Lothar Walther and Steyr Mannlicher facilities. Raw material dependencies center on chromium-molybdenum steel alloys, match-grade stainless stock, and carbon fiber sleeve prepregs. Supply chain risk manifests as 18-24 month order backlogs during NATO procurement surges, with no qualified secondary suppliers for premium hammer-forging capacity. Distribution runs through defense trade intermediaries with State Department licensing authority, channeling complete weapon systems to verified end-users under ITAR end-use monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment moat where ITAR licensing and NATO tender certification create insurmountable switching costs for non-compliant competitors. Master gunsmith workforce scarcity amplifies incumbent advantages through tacit knowledge capture.
For Market Incumbents: Compound defensive positioning through captive suppressor division expansion and in-house barrel-making capacity addition in New Hampshire or Arizona manufacturing clusters. Master gunsmith retirement waves threaten production lead times; secure apprenticeship pipelines with Suhl or Oberndorf am Neckar heritage facilities. Reinforce NATO tender certification speed advantages against emerging Polish and Baltic procurement opportunities. For New Entrants and Emerging Players: Differentiate on carbon fiber barrel sleeve technology for mobile sniper team applications, where weight reduction demands outpace legacy vendor R&D cycles. Target Polish Territorial Defence Forces and Baltic military modernization programs outside established US-UK-German vendor relationships. Pursue licensed production partnerships with Radom or Łucznik facilities to bypass import dependency barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated chassis-to-optic ecosystem vendors with captive suppressor divisions. Long-term viability hinges on regulatory compliance infrastructure rather than pure manufacturing scale. Monitor 6.5mm Creedmoor ammunition standardization signals across US special operations command procurement as inflection indicator for caliber migration investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Suppressor Division Acquisition | Captive baffle stack production eliminates licensing disputes and accelerates platform certification for law enforcement tenders. |
| Carbon Fiber Barrel Partnership | Hybrid sleeve technology reduces mobile sniper system weight penalties without sacrificing harmonic stability guarantees. |
| NATO Eastern Flank Licensing | Poland and Baltic procurement surge creates first-time precision rifle opportunities outside traditional Five Eyes buyer pools. |
| Master Gunsmith Apprenticeship Program | Suhl heritage facility pipelines replicate tacit knowledge in barrel lapping and action truing as retirement waves accelerate. |
| Blockchain Custody Integration | RFID-enabled grip modules and bolt assemblies automate chain-of-custody logging for Germany KBA and France ANSM compliance. |
Research Approach
Operator-level perspectives from military procurement officers, law enforcement armorer specialists, defense trade compliance attorneys, and precision rifle competitive shooters anchored the qualitative base. Primary interviews with Bundeswehr marksmanship program directors and US Customs and Border Protection equipment managers cross-referenced against secondary validation from ITAR licensing databases, NATO standardization agreement documentation, EU Firearms Directive implementing guidelines, and hammer-forged barrel supplier order backlog disclosures. Bottom-up platform shipment estimates triangulated with top-down military budget allocation analysis across the analysis window.
Sensitivity analysis tested forecast robustness across ammunition standardization scenarios, regulatory enforcement intensity variations, and master gunsmith workforce attrition rates. Segmentation dimensions modeled include action type, caliber category, end-use application, and end-user procurement authority tier. CAGRs derived from weighted average of historical replacement cycle patterns and announced NATO modernization program timelines, with 6.5mm Creedmoor ballistic migration velocity and suppressor-integrated platform adoption curves as key industry-specific inputs throughout the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained NATO defense spending commitments or ITAR licensing modernization would require recalibration. Forecasts reflect documented assumptions regarding Five Eyes partner transfer velocity and EU Firearms Directive enforcement consistency. Practitioners should keep alternative scenarios live as eastern flank procurement surge sustainability and ammunition classification debates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Middle East and North Africa Perforating Gun Market
Weapons and Ammunition
Manned Anti-Tank Guided Missile System Market
Weapons and Ammunition
Weapons Release System Market
Weapons and Ammunition
Sports Shotgun Market
Weapons and Ammunition
Missile Seekers Market
Weapons and Ammunition
Recoilless Rifle Market
Weapons and Ammunition
Light Weapons Market
Weapons and Ammunition
Martial Art Weapon Market
Weapons and Ammunition
Middle East and Africa Ammunition Market
Weapons and Ammunition
Detonator Market
Weapons and Ammunition
Precision Guided Munition Market
Weapons and Ammunition
Less Lethal Ammunition Market
Weapons and Ammunition
Small and Medium Caliber Ammunition Market
Weapons and Ammunition
Anti-Tank Missile System Market
Weapons and Ammunition
Small Arms Market
Weapons and Ammunition
Southeast Asia, Middle-East and Africa Small Arms and Ammunition Market