

Enclosed Smokeless Flares Market Size, Share, and Industry Trends Forecast 2026-2036
Enclosed Smokeless Flares Market Insights
Specialized combustion engineering firms in the United States Gulf Coast is repositioning capacity toward higher-efficiency enclosed flare fabrication. Zeeco leverages its vertical integration across burner design and control systems to dominate project bids for refinery retrofits. John Zink Hamworthy Combustion anchors its competitive stance through sustained R&D intensity in low-NOx combustion architecture. Honeywell UOP differentiates by embedding process control software into flare management platforms, extending its reach beyond hardware supply.
Enclosed smokeless flares are sealed combustion devices engineered to destroy hydrocarbon waste gases without visible flame or smoke emissions, typically operating at destruction efficiencies exceeding 98.5% through controlled air-fuel mixing and elevated combustion temperatures. These systems serve primarily to eliminate methane and volatile organic compound releases from industrial process vents, storage tank vapors, and emergency relief streams while maintaining continuous operational visibility for safety compliance. Thermal oxidation technology leads the technology segment due to proven reliability across sour gas applications, while catalytic combustion occupies the fastest-growing niche as operators seek reduced fuel gas consumption at lower calorific value feeds. The oil and gas processing application category sustains the largest revenue pool, though chemical manufacturing is concentrating new order flow as Asian producers expand capacity.
EPA New Source Performance Standards and OSHA Process Safety Management requirements shape product design mandates for U.S. installations, while EU Industrial Emissions Directive and F-Gas Regulation drive comparable specification tightening across European refinery upgrades. Regulatory divergence between methane intensity thresholds in North America and carbon border adjustment mechanisms emerging in Europe is forcing manufacturers to develop modular platform architectures adaptable to multiple compliance regimes. Stakeholders must monitor how emerging state-level methane fees and carbon border taxes reshape total cost of ownership calculations for flare system investments.
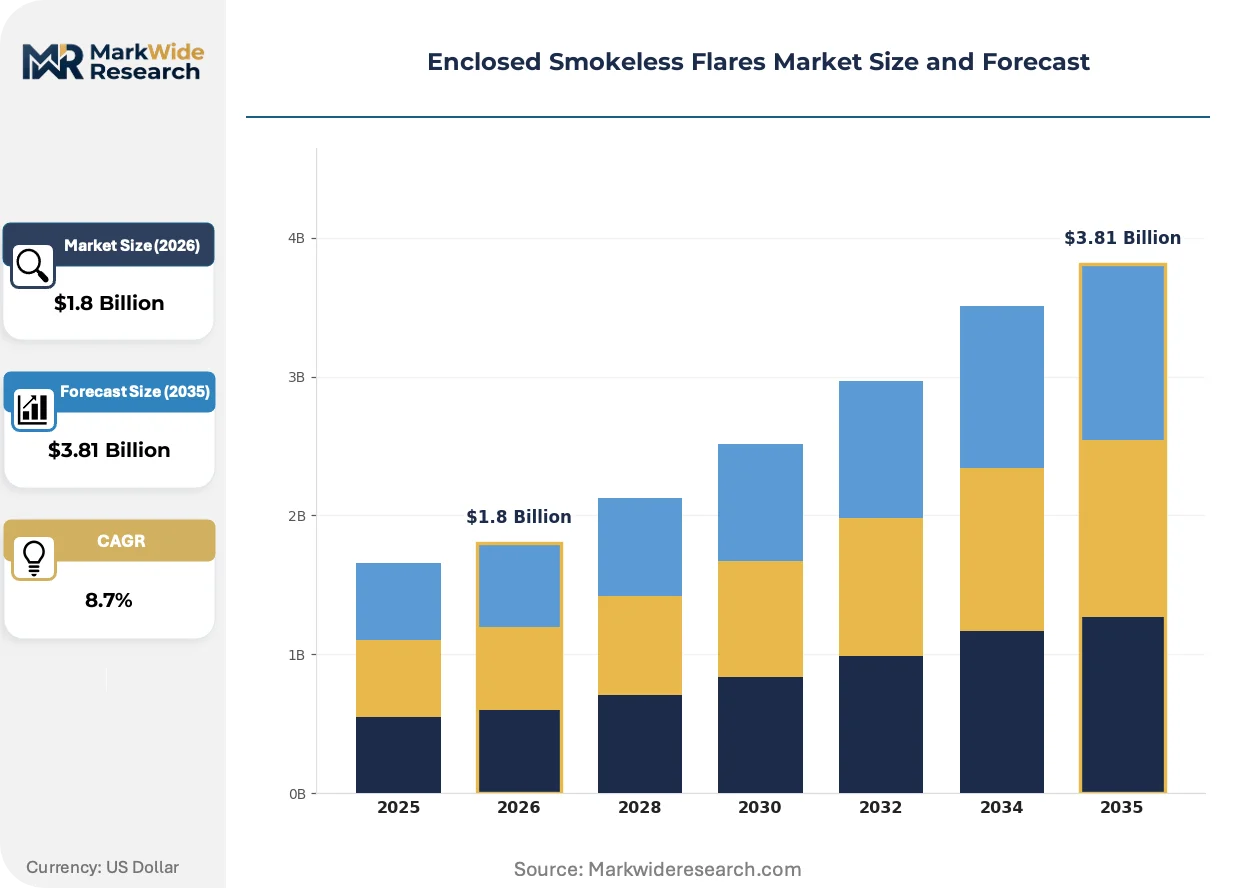
Market Dynamics
Thermal oxidation technology is displacing open-flare infrastructure across petrochemical corridors as methane emission thresholds tighten. Refinery operators face capital allocation decisions between retrofitting legacy systems versus greenfield enclosed flare installations, with compliance timelines compressing procurement cycles.
Growth Catalysts
- EPA New Source Performance Standards:The agency's methane intensity mandates for petroleum refineries are mandating enclosed combustion for new and modified flare systems, driving replacement demand across Gulf Coast processing clusters.
- Sour gas processing expansion:Middle Eastern refinery operators are prioritizing thermal oxidation systems capable of handling high-hydrogen sulfide waste streams without visible emissions or sulfur dioxide breakthrough.
- Modular platform architectures:Equipment fabricators are engineering standardized skid-mounted units that reduce field installation time and accommodate varying calorific value feeds without custom engineering.
Market Restraints
- Specialized refractory material costs:High-alumina ceramic linings and silicon carbide burner tiles face price volatility tied to bauxite and petroleum coke feedstock markets, inflating total installed costs.
- Fabrication capacity concentration:United States Gulf Coast and German industrial zones dominate precision combustion equipment manufacturing, creating geographic supply risk for Asian project developers.
- Catalytic combustion temperature sensitivity:Precious metal catalyst beds degrade rapidly when exposed to sulfur or silicon contaminants, limiting applicability in unconditioned refinery off-gas streams.
Strategic Opportunities
- Indian petrochemical corridor expansion:Reliance Industries and Indian Oil Corporation are building world-scale refinery complexes in Gujarat that specify enclosed flares for export-oriented production meeting EU carbon border adjustment readiness.
- Electrified auxiliary systems:Integration of electric air preheaters and variable frequency drive combustion air blowers is reducing fuel gas consumption and enabling renewable power sourcing for flare operation.
- Remote monitoring service contracts:Continuous emissions monitoring system vendors are bundling predictive maintenance algorithms with hardware supply, capturing recurring revenue from distributed processing facilities.
Industry Challenges
- Combustion engineering talent scarcity:Experienced thermal oxidizer designers with sour gas expertise are concentrated among a handful of specialized firms, constraining project execution bandwidth.
- Legacy distributed control system integration:Refineries operating Honeywell TDC3000 or Yokogawa CENTUM platforms require custom protocol gateways to interface with modern flare management controllers, extending commissioning timelines.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enclosed Smokeless Flares Market Trends and Innovations
Digital twin modeling and real-time emissions analytics are compressing the design-validation loop for enclosed flare systems. Equipment suppliers are repositioning from hardware vendors to performance-guarantee partners, with contractual structures evolving to align payment milestones with verified destruction efficiency outcomes.
Plasma-assisted ignition technology is electrifying startup reliability for low-calorific value waste gas streams that resist conventional pilot flame stabilization. Offshore platform operators in the North Sea are adopting these systems to eliminate continuous pilot fuel consumption, with field trials demonstrating ignition energy requirements below five kilowatts for methane-lean vent gases. The technology is compressing fuel gas infrastructure needs and enabling smaller footprint skid designs for congested offshore facilities.
The EU F-Gas Regulation and its delegated acts are tightening specifications for fluorinated greenhouse gas containment in process refrigeration systems, indirectly elevating enclosed flare demand as chemical manufacturers upgrade vapor recovery and destruction infrastructure. German and Dutch refinery operators are front-loading capital expenditures to secure engineering resources ahead of anticipated implementation deadlines. Equipment procurement cycles are compressing as operators race to lock in fabrication slots.
Refinery procurement functions are consolidating combustion equipment buying under centralized technical standards teams, displacing site-level engineering autonomy with corporate-approved vendor lists and standardized performance specifications. This concentration is compressing supplier margins while elevating importance of documented reference installations and third-party emissions verification. The pattern is most visible among integrated supermajors operating across multiple United States and European sites.
Enclosed Smokeless Flares Market Segmentation
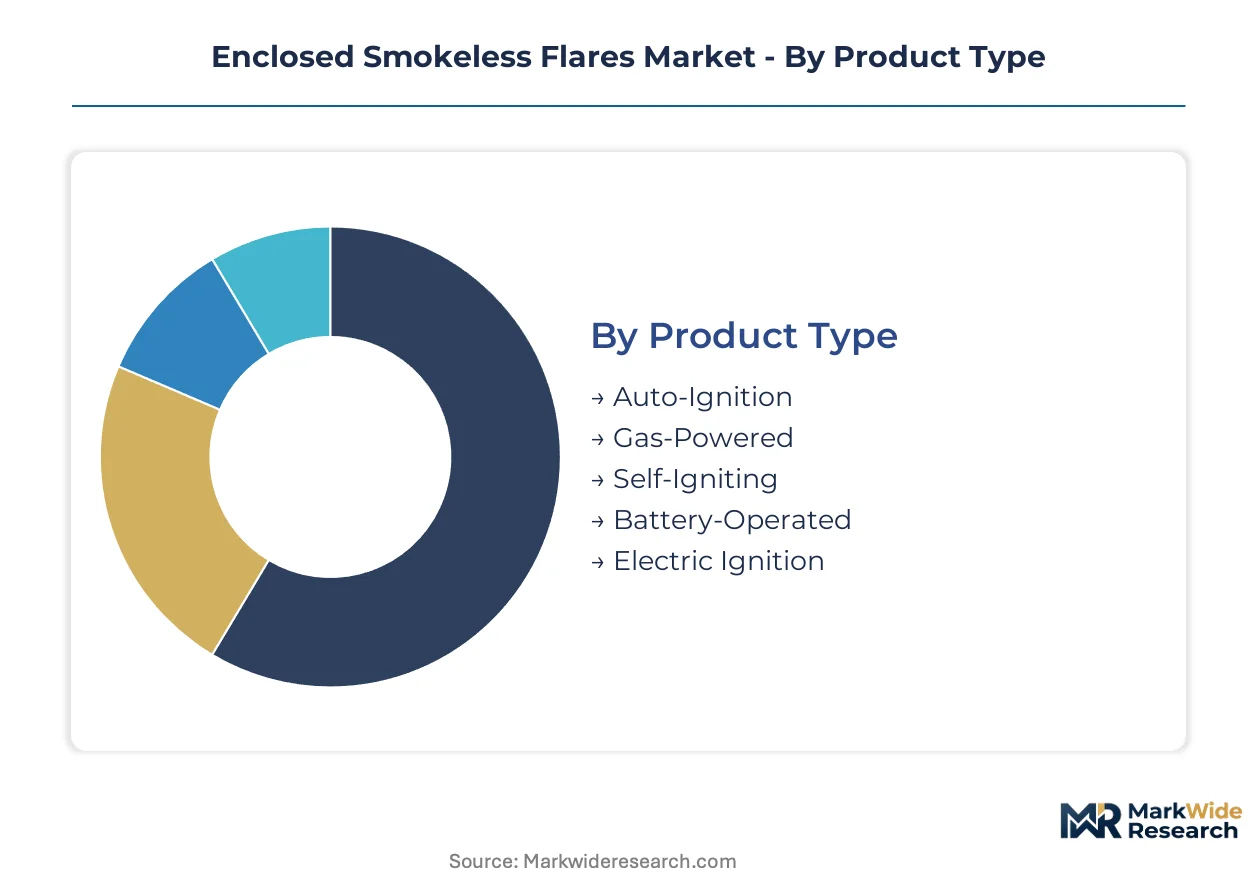
Enclosed smokeless flare procurement decisions hinge on waste gas composition, calorific value, and destruction efficiency requirements. Segment-specific certification burdens from EPA, EU Industrial Emissions Directive, and national environmental regulators create divergent specification pathways across product categories.
Product Type:
Certification requirements vary sharply across ignition architectures, with electric and battery-operated systems facing additional IECEx and ATEX compliance burdens for hazardous area deployment.
- Auto-Ignition:Systems employ thermocouple-actuated fuel valves that trigger combustion automatically when vent gas temperatures exceed ignition thresholds. Demand concentrates in Texas and Louisiana refinery clusters where continuous operation mandates minimize manual intervention and EPA compliance automation is paramount.
- Gas-Powered:Conventional pilot flame systems utilize refinery fuel gas streams for ignition energy, offering proven reliability across sour gas applications. Operators in the Middle Eastern petrochemical corridor favor these units for high-hydrogen sulfide waste streams where electrical spark hazards present operational constraints.
- Self-Igniting:Pyrophoric metal injection systems enable flameless startup for ultra-lean methane vent streams.
- Battery-Operated:Portable ignition modules serve temporary flare installations and maintenance turnaround scenarios.
- Electric Ignition:High-voltage spark systems integrate with distributed control architectures for remote start capability.
Gas-powered systems sit at the top of the volume ranking, with electric ignition climbing the fastest as renewable power sourcing gains traction.
Technology:
Capital intensity and operating cost profiles diverge substantially across destruction technologies, with thermal oxidation commanding premium project budgets while catalytic approaches target fuel efficiency optimization.
- Catalytic Combustion:Precious metal catalyst beds enable hydrocarbon oxidation at temperatures below 500°C, slashing supplemental fuel requirements for low-calorific value feeds. Chemical manufacturers in the Netherlands and Germany are deploying these systems to meet EU carbon border adjustment readiness and minimize operational carbon intensity.
- Thermal Oxidation:Direct flame combustion at 760-1100°C achieves destruction efficiencies exceeding 98.5% across the broadest waste gas spectrum. Sour gas processors in Saudi Arabia and the United Arab Emirates specify thermal oxidation for high-hydrogen sulfide streams where catalyst poisoning risks preclude alternative approaches.
- Incineration:Multi-chamber designs accommodate solid particulate loads and liquid waste injection.
- Plasma Gasification:Electric arc systems decompose hydrocarbons into syngas fractions for potential recovery.
- Photocatalysis:UV-activated titanium dioxide systems target trace VOC destruction at ambient temperatures.
Thermal oxidation dominates current installation value, with catalytic combustion expanding most quickly in carbon-constrained European jurisdictions.
Application:
End-use sector requirements shape burner specification, refractory selection, and emissions monitoring architecture with distinct intensity across industrial verticals.
- Oil & Gas Processing:Upstream gathering and midstream compression facilities deploy compact skid-mounted units for tank vapor and blowdown gas destruction. Permian Basin operators in Texas are retrofitting legacy open flares to satisfy EPA methane intensity mandates and avoid state-level emission fees.
- Refineries:Integrated processing complexes require multi-burner systems capable of handling emergency relief streams and continuous process vent flows. Reliance Industries' Gujarat complex specifications are setting new benchmarks for enclosed flare deployment in Indian export-oriented production.
- Petrochemical Plants:Olefins and aromatics producers specify low-NOx combustion architecture to meet local air quality standards.
- Chemical Manufacturing:Specialty chemical producers prioritize modular platforms for batch process flexibility.
- Waste Treatment:Landfill gas and anaerobic digester applications emphasize siloxane-resistant materials.
Refinery applications command the largest project scale, with chemical manufacturing gaining share fastest on Asian capacity expansion.
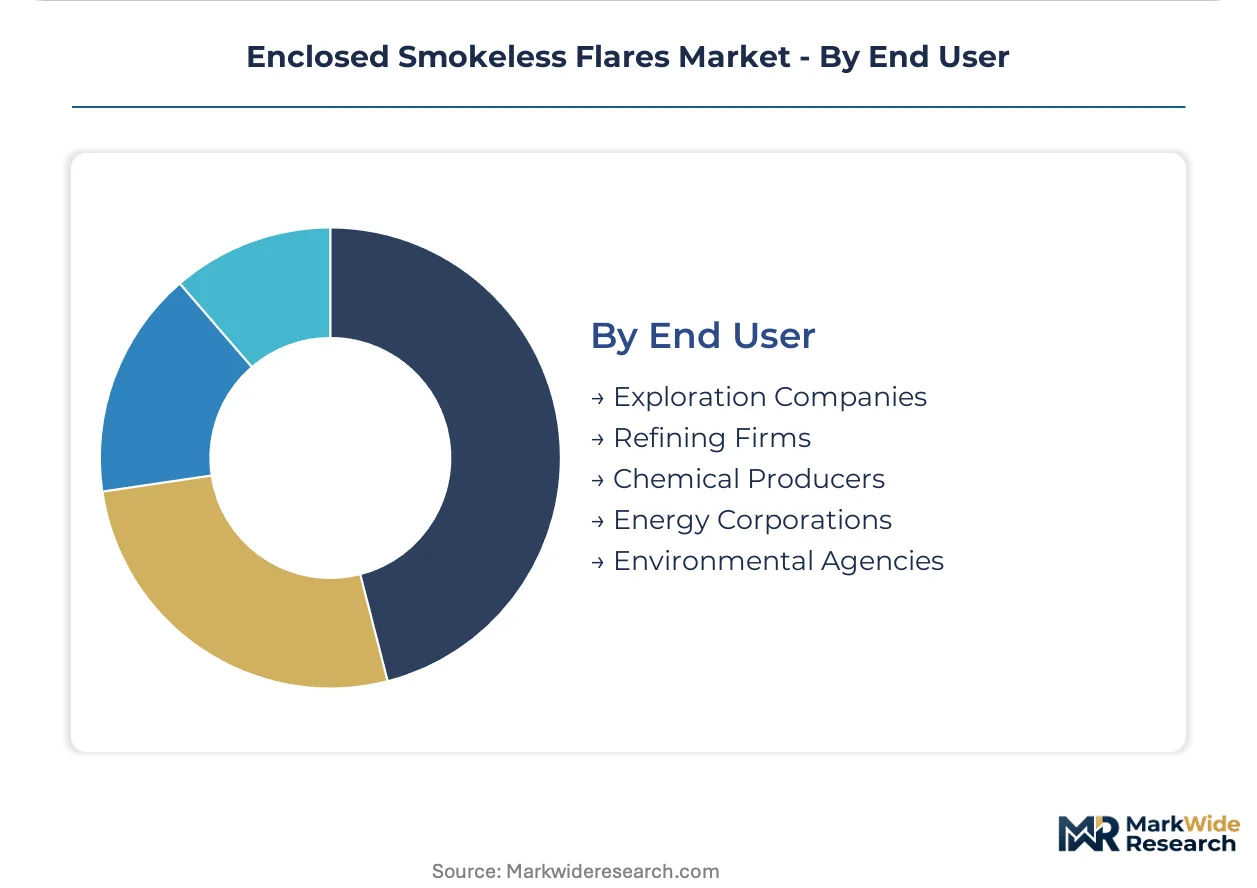
End User:
Procurement authority and technical specification control varies dramatically across buyer categories, influencing vendor selection criteria and contract structuring.
- Refining Firms:Integrated supermajors operate centralized technical standards teams that consolidate combustion equipment buying across multiple sites, compressing supplier margins while elevating documented reference installation requirements. ExxonMobil and Shell procurement functions are displacing site-level engineering autonomy with corporate-approved vendor lists.
- Chemical Producers:Specialty and commodity chemical manufacturers prioritize total cost of ownership optimization and modular platform adaptability for multi-product facility reconfiguration.
- Exploration Companies:Upstream operators emphasize rapid deployment and mobile skid configurations for remote field locations.
- Energy Corporations:Utility and power generation entities specify auxiliary fuel integration for grid stabilization applications.
- Environmental Agencies:Government remediation contractors procure destruction systems for superfund and industrial cleanup sites.
Refining firms anchor procurement volume, with environmental agencies representing the steepest expansion trajectory on remediation backlog growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States refinery operators are expanding enclosed smokeless flare adoption at roughly twice the pace of European chemical manufacturers, reflecting divergent regulatory timelines and capital allocation priorities across Atlantic petrochemical corridors.
United States
Texas and Louisiana processing clusters drive procurement volume as EPA New Source Performance Standards mandate enclosed combustion for modified flare systems. The agency's methane intensity thresholds compress compliance timelines for Gulf Coast refineries. Houston-area engineering fabricators report order backlogs extending into 2026 as operators race to retrofit legacy open-flare infrastructure.
Saudi Arabia
Sour gas processing expansion in the Eastern Province prioritizes thermal oxidation systems capable of handling high-hydrogen sulfide waste streams without visible emissions. The country's national environmental regulator is aligning local standards with emerging methane intensity frameworks. Jubail Industrial City complexes specify destruction efficiencies exceeding 98.5% for export-oriented petrochemical production.
Germany
EU Industrial Emissions Directive and F-Gas Regulation are tightening specifications for vapor recovery infrastructure across Rhine-Ruhr chemical manufacturing belts. BASF and Lanxess operations in Ludwigshafen are front-loading capital expenditures to secure engineering resources ahead of delegated act implementation deadlines. Catalytic combustion systems are gaining share as operators seek reduced fuel gas consumption.
India
Reliance Industries and Indian Oil Corporation are building world-scale refinery complexes in Gujarat that specify enclosed flares for EU carbon border adjustment readiness. The country's central environmental regulator is drafting methane emission standards for petroleum refining that mirror European benchmarks. Jamnagar processing facilities are setting new regional benchmarks for enclosed flare deployment density.
United Arab Emirates
Abu Dhabi National Oil Company is expanding enclosed flare specifications across Ruwais refining and petrochemical assets as part of operational decarbonization commitments. The emirate's environmental regulator is introducing methane intensity disclosure requirements for large industrial facilities. Dubai-based engineering procurement offices are consolidating combustion equipment buying under centralized technical standards teams.
Enclosed Smokeless Flares Market Competitive Landscape
United States Gulf Coast producers anchor one tier of fabrication capacity; German and Dutch specialists hold advanced combustion architecture positions in European project bidding. The vendor base stratifies across integrated combustion engineering conglomerates, regional equipment fabricators, and process control technology providers. Three archetypes dominate: vertically integrated burner-to-control-system suppliers, refractory-focused niche specialists, and software-embedded platform vendors. Consolidation pressure is intensifying through strategic partnerships between hardware fabricators and emissions monitoring service providers, alongside capacity expansion announcements from established refractory material suppliers.
Among United States-based combustion engineering firms, Zeeco exemplifies the vertically integrated archetype spanning burner design through control system integration. John Zink Hamworthy Combustion occupies a position within the premium-tier equipment segment, while Honeywell UOP represents the software-embedded platform vector extending beyond hardware supply into process control software. These three anchors illustrate how competitive positioning is concentrating around bundled performance guarantees rather than discrete equipment sales.
| Leading Market Players |
|---|
| Zeeco |
| John Zink Hamworthy Combustion |
| Honeywell UOP |
| Wärtsilä |
| Envent Corporation |
| NAO |
| AEREON |
| Flares International |
| Callidus Technologies |
| Others |
Pricing and Supply Chain Analysis
EPA methane intensity mandates gate both qualified supply and premium-tier pricing access for enclosed smokeless flare systems, compressing procurement timelines for Gulf Coast refineries while elevating entry barriers for uncertified fabricators. This regulatory filtering concentrates pricing power among vertically integrated combustion engineering firms with demonstrated destruction efficiency guarantees.
Pricing Analysis
Capacity additions in Germany and the United States Gulf Coast are reshaping price floors for thermal oxidation systems. Project-based contract structures dominate, with price differentiation anchored in EPA certification tier and after-sales service bundling. Cost compression in standard-tier equipment is intensifying because modular platform standardization reduces engineering customization. Exploration companies exhibit highest price sensitivity; integrated supermajors prioritize destruction efficiency guarantees over unit economics.
Supply Chain Analysis
Direct-to-refinery channels handle hyperscale buyer demand from integrated supermajors with centralized procurement functions. Manufacturing concentrates in the United States, Germany, and Saudi Arabia. Production draws from high-alumina ceramic linings, silicon carbide burner tiles, and precious metal catalyst beds. Single-source vulnerability in bauxite feedstock markets elevates refractory material cost volatility. Distribution runs through EPC contractors and specialized combustion engineering firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The enclosed smokeless flares market represents a late-cycle quality story as methane emission regulations harden specifications toward 98.5%+ destruction efficiency tiers. Refinery operators are consolidating procurement under corporate technical standards teams, privileging vendors with documented reference installations.
For Market Incumbents: Anchor competitive position through captive supply of high-performance refractory materials and backward integration into burner control system firmware. Emerging modular platform vendors threaten margin compression in standard-tier equipment; defend through certification investment in EPA and EU Industrial Emissions Directive compliance tiers. Prioritize R&D in plasma-assisted ignition to capture offshore platform electrification demand. For New Entrants and Emerging Players: Environmental remediation contractors represent the most penetrable buyer archetype as government superfund backlog expands fastest. White-space targets include Indian petrochemical corridor greenfield projects and chemical manufacturing facilities seeking EU carbon border adjustment readiness. Go-to-market through predictive maintenance service bundling rather than hardware-only positioning. For Investors and Strategic Acquirers: Valuations sit cheapest among refractory-focused niche specialists with sour gas expertise and limited geographic diversification. Long-term viability hinges on regulatory enforcement continuity across methane intensity frameworks. Acquisition target archetype: combustion engineering firms with proprietary low-NOx architecture and Middle Eastern reference installations. Watch state-level methane fee implementation as inflection indicator for replacement demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refractory Materials | Captive supply of silicon carbide burner tiles insulates margin from bauxite price volatility. |
| Modular Platform Standardization | Skid-mounted thermal oxidation units reduce field installation time for Texas refinery retrofits. |
| Predictive Maintenance Service Contracts | Continuous emissions monitoring bundling captures recurring revenue from Permian Basin operators. |
| Plasma-Assisted Ignition Development | Electric startup reliability eliminates pilot fuel consumption for North Sea offshore platforms. |
| EU Carbon Border Adjustment Certification | Documented destruction efficiency enables Indian refinery exports to European chemical markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary research encompassed combustion engineering executives, refinery procurement directors, EPC contractor project managers, and environmental compliance officers at petrochemical facilities. Secondary validation drew from EPA enforcement and compliance databases, EU Industrial Emissions Directive delegated acts, SEC 10-K filings from integrated supermajors, and customs trade records for combustion equipment imports. Bottom-up project pipeline analysis triangulated against top-down regulatory mandate sizing.
Historical reference periods anchored volume and value trajectories across the projection horizon. The analytical framework modeled segmentation across technology type, ignition architecture, application vertical, and regional regulatory cluster. CAGRs derived from regression analysis of capital expenditure patterns and compliance timeline compression. Industry-specific inputs included methane intensity threshold evolution and refractory material price indices.
Underlying measurement precision varies by segment; refinery applications carry tighter precision than exploration company deployments due to consolidated procurement data availability. Forecasts reflect assumptions regarding regulatory enforcement continuity and sour gas processing capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.