
 NATO Ammunition Market | 2026-2036
NATO Ammunition Market Size, Share, and Industry Trends Forecast 2026-2036
NATO Ammunition Market Analysis
Poland is narrowing the supply gap for 155mm artillery shells through expanded domestic manufacturing lines. Rheinmetall AG leverages its German engineering base to sustain high-volume output of precision munitions, while Nammo AS anchors Nordic supply security through its Norwegian and Finnish production sites. General Dynamics Corporation competes across multiple caliber categories with integrated propellant-to-projectile capabilities.
NATO ammunition encompasses projectiles, propellants, primers, and fuzes manufactured to STANAG specifications ensuring cross-national interoperability in coalition operations. These munitions typically employ nitrocellulose-based propellants with chamber pressures calibrated to specific weapon platforms, serving the alliance's core deterrence and collective defense mission under Article 5 obligations. Small caliber rounds remain the highest-volume segment with mature pricing, while smart munitions command premium positioning due to guidance system complexity and limited supplier bases. Ground forces procurement dominates use case demand as member states prioritize infantry and artillery readiness over air-delivered payloads.
NATO's STANAG framework, the U.S. Department of Defense MIL-STD system, and the EU's REACH chemicals regulation collectively shape product specifications, supply chain compliance costs, and market access for non-alliance producers. Germany's KBA and Poland's national military procurement office enforce additional national certification layers that extend qualification timelines for new entrants. Stakeholders must monitor how the EU Defense Industrial Strategy reshapes cross-border procurement rules and whether allied funding mechanisms accelerate smart munitions adoption beyond current acquisition cycles.
Market Dynamics
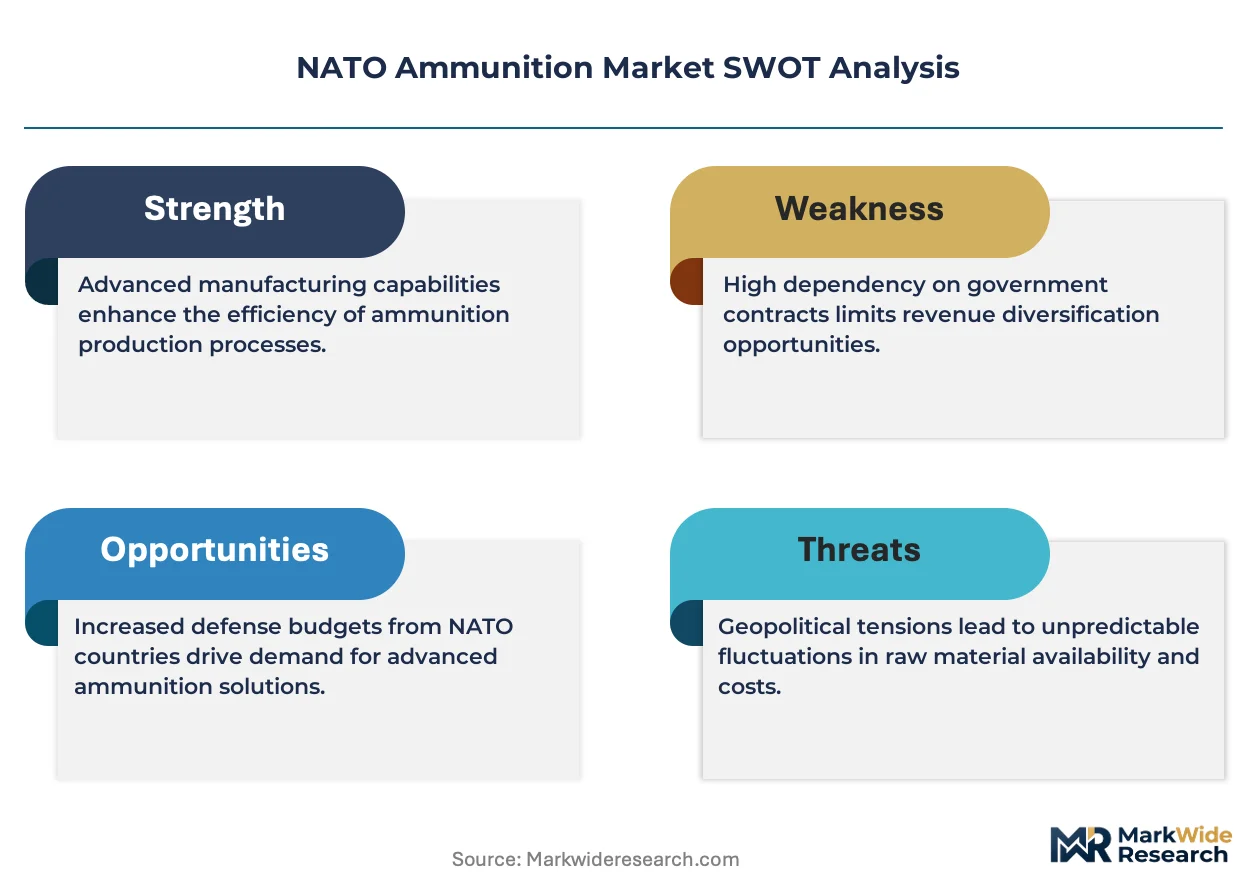
Allied defense ministries are rebuilding depleted war reserves through accelerated multi-year procurement frameworks, while STANAG standardization mandates reshape supplier qualification pathways across member states. This structural pressure is concentrating production capacity in facilities capable of certified interoperability at scale.
Growth Catalysts
- Artillery modernization programs:NATO members are fielding new 155mm howitzer platforms requiring compatible precision munitions. Ground forces procurement offices in Poland and Germany are issuing long-term supply agreements to qualified manufacturers.
- REACH regulatory adaptation:EU chemicals registration requirements are forcing propellant reformulation toward reduced-toxicity compositions. Compliant suppliers gain preferential access to continental defense tenders.
- Smart fuze integration:Programmable airburst and proximity fuzes are displacing mechanical alternatives in counter-UAS and personnel suppression roles. Integration demands are pulling precision electronics capabilities into traditional metal-bashing supply chains.
Market Restraints
- Nitrocellulose supply concentration:Cotton linters and specialized cellulose feedstocks for propellant production concentrate in Asian agricultural processing hubs. Price volatility in these inputs compresses margins for European and North American formulators.
- KBA certification timelines:Germany's national weapons authority imposes extended qualification protocols for new production lines. Facility approvals routinely extend 18-24 months beyond technical readiness.
- Legacy caliber substitution:Standardization around 155mm NATO artillery is displacing 105mm and 203mm systems in member inventories. Manufacturers maintaining only legacy tooling face stranded capacity without conversion investment.
Strategic Opportunities
- Polish production expansion:New manufacturing complexes near Radom and Dęblin are scaling capacity for artillery shell forging and propellant blending. Qualified entrants can capture offset obligations from Warsaw's procurement acceleration.
- Guided mortar munitions:81mm and 120mm precision mortar rounds represent underdeveloped segments with limited qualified suppliers. Integration of MEMS guidance packages creates differentiation against commodity competitors.
- EU Defense Industrial Strategy:Proposed joint procurement mechanisms and cross-border facility financing could reduce national certification fragmentation. Early positioning in collaborative frameworks offers preferential access to pooled demand.
Industry Challenges
- Skilled pyrotechnician scarcity:Demographic contraction in explosives chemistry and propellant engineering programs limits workforce expansion. Recruitment competition from civilian chemical sectors intensifies retention pressure.
- STANAG revision synchronization:Interoperability standard updates require simultaneous retooling across multiple production lines. Coordination failures between national certification bodies delay market re-entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NATO Ammunition Market |
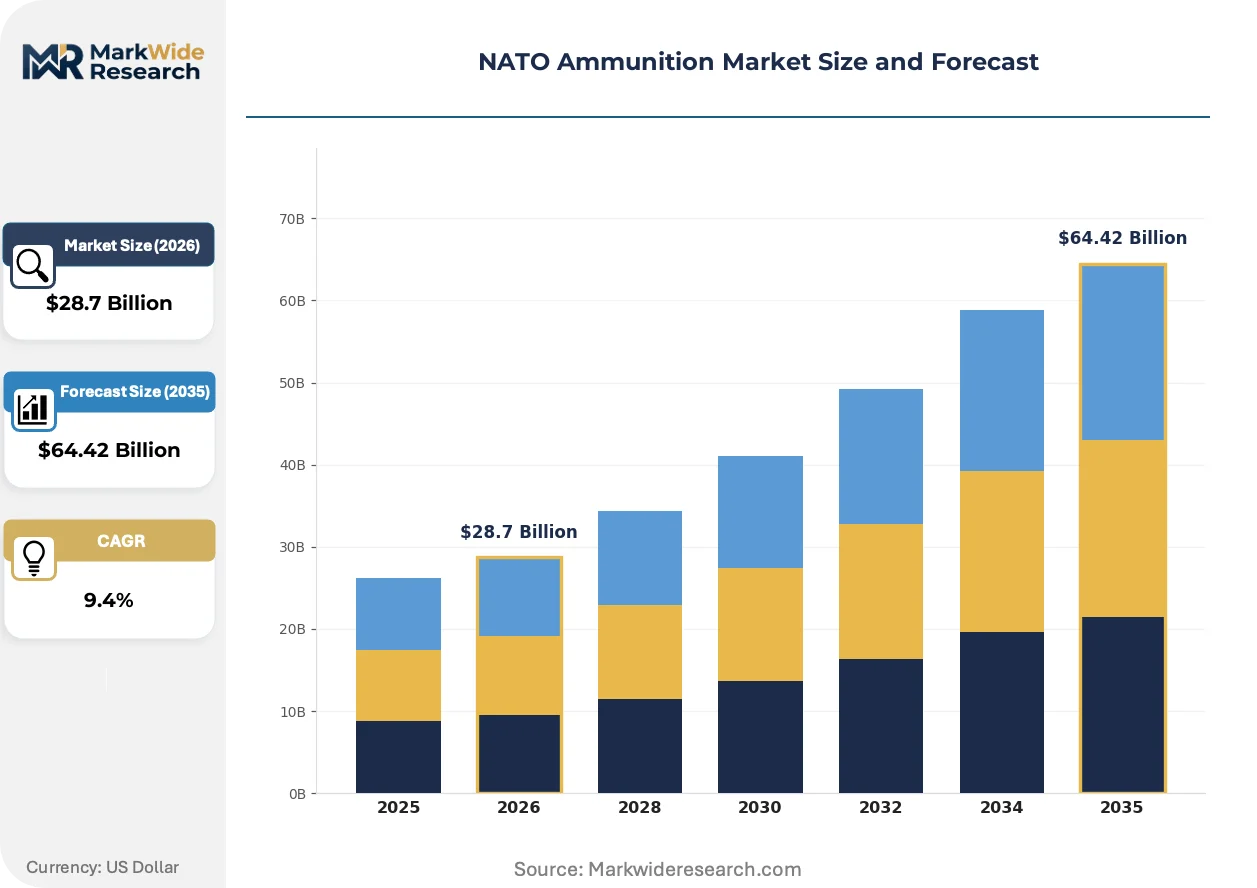
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $64.42 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Caliber, Medium Caliber, Large Caliber, Artillery Use Case: Ground Forces, Air Forces, Naval Forces, Special Operations Deployment: Combat Zones, Training Facilities, Stockpiles, Peacekeeping Missions Technology: Smart Munitions, Conventional Rounds, Non-Lethal Ammunition, Specialty Ammunition |
| Companies Covered | Nammo AS, FN Herstal SA, Rheinmetall AG, Diehl Stiftung and Co. KG, Northrop Grumman Corporation, General Dynamics Corporation, MESKO S.A., Polska Grupa Zbrojeniowa SA, BAE Systems plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NATO Ammunition Market Emerging Trajectories
Digital manufacturing and precision guidance architectures are compressing development cycles while regulatory chemistry mandates force material substitutions. These intersecting pressures favor suppliers with integrated R&D-to-production capabilities.
Modular propellant charge systems are digitizing artillery fire mission preparation. These configurable modular artillery charge systems enable rapid caliber adaptation and automated ballistic calculation. Field artillery units in Baltic member states are adopting them for reduced crew burden and faster mission turnaround. The technology is digitizing ammunition logistics by enabling inventory tracking at individual module granularity and predictive resupply algorithms.
REACH Annex XVII restrictions on lead styphnate priming compounds are mandating diazodinitrophenol and organic peroxide alternatives. Germany's KBA and France's national regulator are enforcing accelerated compliance deadlines ahead of broader EU harmonization. Small-caliber ammunition manufacturers serving domestic police and military markets are reformulating primer compositions, with qualification bottlenecks favoring integrated chemical synthesis capabilities.
Stockpile rotation contracts are compressing traditional acquisition cycles. Defense ministries are moving from periodic bulk awards to continuous replenishment agreements with performance guarantees. This pattern is most pronounced in Nordic member states where Nammo AS and domestic suppliers manage vendor-managed inventory at military depots. The shift rewards production flexibility and geographic proximity over unit cost optimization.
NATO Ammunition Market Segmentation
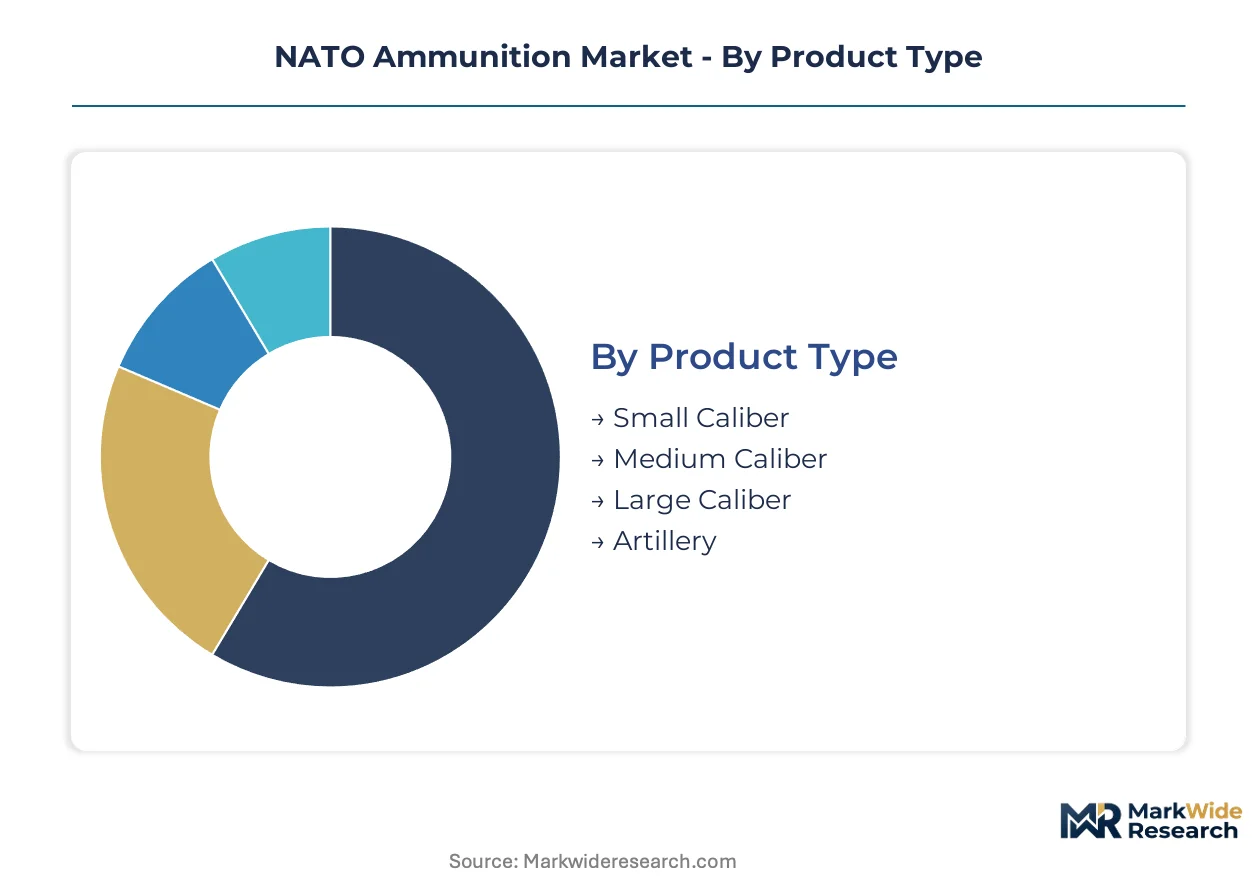
Segmentation in the NATO ammunition market reveals how STANAG standardization creates procurement clusters around specific operational requirements. Defense ministries align multi-year acquisition frameworks to these categories, concentrating supplier qualification investments where interoperability mandates intersect with volume demand.
Product Type:
After-sales service intensity varies sharply across caliber classes, with artillery and large-caliber systems demanding sustained technical support for propellant stability monitoring and precision fuze recalibration.
- Small Caliber:Standardized 5.56mm and 7.62mm rounds employ nitrocellulose propellants with consistent chamber pressure specifications. Polish and German ground forces procurement offices dominate volume demand as they rebuild infantry stockpiles depleted by sustained military assistance programs.
- Artillery:155mm precision munitions integrate programmable airburst fuzes and modular propellant charge systems. Demand concentrates in Baltic member states fielding new howitzer platforms, with qualification bottlenecks favoring suppliers with integrated forging and blending capabilities.
- Medium Caliber:20-40mm autocannon rounds serve vehicle-mounted systems with higher cyclic rates than small arms.
- Large Caliber:Tank-fired kinetic energy penetrators and high-explosive squash heads require specialized tungsten or depleted uranium feedstocks.
Artillery holds the largest share; momentum sits with small caliber as stockpile rotation accelerates across member states.
Use Case:
Cost tier differentiation separates expeditionary rapid-response units from garrison-based formations, with special operations commanding premium pricing for mission-specific loadouts.
- Ground Forces:Infantry and artillery units consume the highest ammunition volumes across NATO's collective defense posture. Procurement offices in Poland, Germany, and the United States are issuing accelerated replenishment agreements for compatible STANAG-qualified stocks.
- Special Operations:Low-signature subsonic rounds and precision breaching charges serve counter-terrorism and direct action missions. Nordic member states prioritize vendor-managed inventory for rapid deployment readiness.
- Air Forces:Aircraft-mounted gun systems and precision air-to-ground munitions require distinct certification pathways.
- Naval Forces:Naval gunfire support and close-in weapon systems demand corrosion-resistant packaging and stabilized propellant formulations.
Ground forces dominate procurement volume; special operations are climbing the fastest as irregular warfare capabilities expand.
Deployment:
Supply chain configuration shifts dramatically between static stockpiles and forward-deployed combat zones, with peacekeeping missions imposing additional rules-of-engagement constraints on permissible munitions types.
- Stockpiles:Long-term strategic reserves require climate-controlled storage and periodic propellant stability testing. Germany's KBA enforces extended recertification protocols that extend supplier retention contracts.
- Combat Zones:Forward ammunition supply points demand palletized modular packaging compatible with automated logistics systems. Baltic member states are digitizing inventory tracking for predictive resupply algorithms.
- Training Facilities:High-volume consumption of reduced-lead or lead-free practice rounds accelerates REACH compliance investments.
- Peacekeeping Missions:Restricted rules of engagement favor non-lethal and precision low-collateral alternatives.
Stockpiles hold the largest share; combat zones are gaining share fastest as forward presence commitments expand.
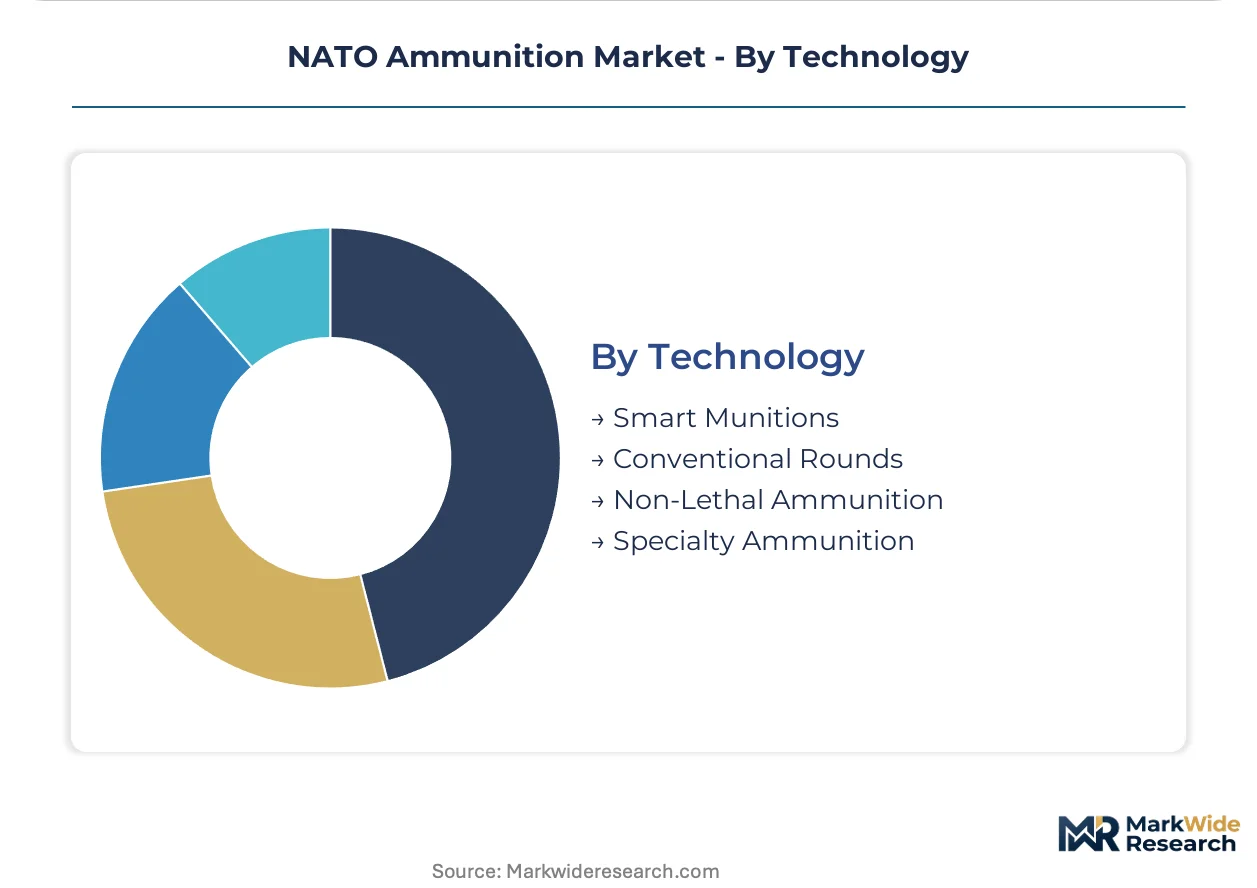
Technology:
Margin structures diverge sharply between commodity conventional rounds and smart munitions, where guidance system complexity limits qualified supplier bases and sustains premium positioning.
- Smart Munitions:Precision guidance packages integrate MEMS inertial measurement units with GPS or laser designation. REACH regulatory adaptation and STANAG fuze interoperability standards concentrate demand among suppliers with captive electronics capabilities.
- Conventional Rounds:Ball projectiles and mechanical fuzes serve volume applications with mature pricing. Nitrocellulose supply concentration in Asian agricultural processing hubs compresses margins for European formulators.
- Non-Lethal Ammunition:Rubber projectiles, flash-bang rounds, and chemical irritant payloads serve crowd control and escalation-of-force protocols.
- Specialty Ammunition:Tracer, armor-piercing, and incendiary variants satisfy specific tactical requirements with limited production runs.
Conventional rounds hold the largest share; smart munitions show the steepest expansion trajectory as precision engagement requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA anchors the regulatory landscape for NATO ammunition certification, with its extended qualification protocols shaping supplier access across the alliance. National procurement offices in Poland, Germany, and the United States are accelerating multi-year replenishment frameworks to rebuild depleted war reserves.
United States
The Department of Defense MIL-STD system governs interoperability specifications for allied coalition operations. Ground forces procurement offices are issuing accelerated replenishment agreements for STANAG-qualified artillery and small-caliber stocks. Production clusters in the Midwest and Southern states are scaling nitrocellulose blending and precision fuze assembly capacity to meet sustained demand from military assistance programs.
Germany
Rheinmetall AG leverages its engineering base to sustain high-volume output of precision munitions for domestic and allied customers. KBA certification timelines routinely extend 18-24 months beyond technical readiness, creating qualification bottlenecks for new entrants. Industrial concentration in the Rhineland and Bavaria supports integrated propellant-to-projectile manufacturing with captive supply chain control.
Poland
Domestic manufacturing complexes near Radom and Dęblin are scaling capacity for 155mm artillery shell forging and propellant blending. Poland's national military procurement office enforces additional certification layers that extend qualification timelines. New production facilities are capturing offset obligations from Warsaw's procurement acceleration while narrowing the supply gap for artillery shells.
Norway
Nammo AS anchors Nordic supply security through Norwegian and Finnish production sites serving alliance requirements. National regulators enforce REACH Annex XVII compliance deadlines ahead of broader EU harmonization for reduced-toxicity propellant formulations. Coastal industrial zones maintain vendor-managed inventory at military depots under continuous replenishment agreements.
United Kingdom
BAE Systems plc competes across multiple caliber categories with integrated manufacturing capabilities. The UK's national procurement framework prioritizes STANAG interoperability for coalition operational readiness. Defense industrial clusters in England and Scotland are adapting primer compositions to meet accelerated regulatory compliance deadlines for lead-free alternatives.
NATO Ammunition Market Vendor Landscape
Capability concentration sits with integrated R&D-to-production specialists; scale advantage sits with diversified defense conglomerates with captive chemical synthesis. The market structures around three tiers: precision guidance integrators, volume manufacturers with STANAG-certified forging capacity, and national champions serving domestic procurement with offset obligations. Dominant competitive moves include backward integration into nitrocellulose feedstocks and strategic partnerships for modular propellant charge system development.
Among European defense industrial groups, Rheinmetall AG, Nammo AS, and General Dynamics Corporation exemplify contrasting archetypes. Rheinmetall AG represents the integrated engineering-to-manufacturing model with German regulatory anchoring. Nammo AS occupies a position as a Nordic specialist with multi-site production security. General Dynamics Corporation sits within the diversified conglomerate tier with cross-caliber portfolio breadth.
| Leading Market Players |
|---|
| Nammo AS |
| FN Herstal SA |
| Rheinmetall AG |
| Diehl Stiftung and Co. KG |
| Northrop Grumman Corporation |
| General Dynamics Corporation |
| MESKO S.A. |
| Polska Grupa Zbrojeniowa SA |
| BAE Systems plc |
| Others |
Supply Flow & Price Mechanics
Baltic corridor freight rates from Polish manufacturing clusters to forward ammunition supply points compress margins for high-volume conventional rounds while amplifying premiums for STANAG-certified precision munitions with shorter logistics tails. This geographic cost wedge separates commodity suppliers tethered to bulk transport from integrated manufacturers with captive distribution networks serving defense ministry vendor-managed inventory programs.
Pricing Analysis
Polish-German artillery shell pricing spreads widen where KBA certification adds eighteen-month qualification premiums against Radom-forged alternatives. Three-tier pricing structure across precision-guided, STANAG-certified conventional, and legacy surplus tiers reflects certification grade and volume scale differentiation. Cost compression in conventional 155mm runs through nitrocellulose feedstock volatility from Asian cotton linter markets. Ground forces procurement offices show highest price sensitivity for infantry small-caliber replenishment, while special operations units absorb premiums for low-signature mission-specific loadouts.
Supply Chain Analysis
Tariff exposure between European propellant blenders and Asian cotton linter processors concentrates risk in nitrocellulose supply security. Production gravity centers on Germany, Poland, and Norway for STANAG-qualified forging and blending capacity. Raw material dependencies rest on cotton linters, tungsten feedstocks for kinetic penetrators, and precision electronics for programmable fuzes. Single-source vulnerability in MEMS guidance component fabrication threatens smart munitions output scaling. Distribution runs through defense ministry vendor-managed inventory systems with automated logistics integration at Baltic forward supply points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Propellant stability monitoring and precision fuze recalibration contracts are expanding faster than hardware procurement across NATO member state replenishment frameworks. This service-attach dynamic favors suppliers with integrated technical support capabilities embedded at military depot level.
For Market Incumbents: Harden STANAG certification moats through accelerated KBA qualification investments before EU Defense Industrial Strategy harmonization opens cross-border access. Deepen backward integration into nitrocellulose feedstocks to offset Asian agricultural processing hub price volatility. Lock in vendor-managed inventory contracts at Baltic combat zone supply points to anchor volume against emerging Polish production capacity. For New Entrants and Emerging Players: Build out guided mortar munitions capabilities in 81mm and 120mm segments where MEMS guidance integration limits qualified supplier bases. Polish offset obligations from Warsaw's procurement acceleration represent the most penetrable entry channel. Pursue joint venture structures with established propellant blenders to compress KBA timeline risk. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified defense conglomerates with stranded legacy caliber capacity facing 155mm standardization displacement. Mid-tier forging specialists with latent STANAG qualification offer five-to-ten year viability windows under sustained replenishment demand. Watch EU Defense Industrial Strategy joint procurement mechanism announcements as inflection signals for cross-border facility financing access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrocellulose | Captive cotton linter sourcing from Asian agricultural processors insulates margin compression from feedstock volatility. |
| STANAG Certification Acceleration | Compressed KBA qualification timelines in Germany unlock preferential access to Bundeswehr multi-year replenishment frameworks. |
| Smart Fuze Electronics Integration | In-house MEMS guidance capabilities differentiate precision munitions against commodity forging competitors in Baltic procurement. |
| Vendor-Managed Inventory Expansion | Embedded technical support at Nordic military depots captures recurring propellant stability monitoring revenue streams. |
| Polish Production Facility Scale-Up | Radom and Dęblin manufacturing complexes capture offset obligations from Warsaw's artillery shell procurement acceleration. |
Methodological Framework
Operator-level perspectives from defense ministry procurement officers, pyrotechnician workforce managers, KBA certification specialists, and propellant chemical synthesis directors anchored the qualitative base. Primary interview insights triangulated against secondary validation from NATO STANAG documentation, EU REACH Annex XVII regulatory filings, national customs trade data for nitrocellulose feedstock flows, and SEC 10-K disclosures from diversified defense conglomerates. Bottom-up segment sizing across caliber categories, use cases, and technology tiers reconciled with top-down defense budget allocation analysis.
Scenario-bracketing across replenishment acceleration, regulatory harmonization, and smart munitions adoption curves shaped the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product caliber class, deployment configuration, guidance technology tier, and national procurement framework type. CAGRs derived from volume-demand elasticity against defense budget trajectories, with specific inputs from artillery modernization program announcements and REACH compliance deadline acceleration patterns.
Stress conditions across nitrocellulose supply disruption, KBA certification timeline extension, and EU Defense Industrial Strategy implementation delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sustained military assistance program demand and STANAG standardization continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Explosives for Civil Uses Market
Weapons and Ammunition
Global Artillery Systems Market
Weapons and Ammunition
US Perforating Gun Market
Weapons and Ammunition
Close-In Weapon Systems Market
Weapons and Ammunition
Automatic Weapons Market
Weapons and Ammunition
Vehicle Mounted Anti-Tank Missile System Market
Weapons and Ammunition
Smart Weapons Market
Weapons and Ammunition
Ballistic Protection Market
Weapons and Ammunition
Weapon Mounts Market
Weapons and Ammunition
Next-Generation Assault Rifles Market
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Enclosed Smokeless Flares Market
Weapons and Ammunition
Ammunition Handling Systems Market
Weapons and Ammunition
Smart Bullets Market
Weapons and Ammunition
Non Lethal Projectiles Market
Weapons and Ammunition
Detonator Market