
 Military Helmet Market | 2026-2036
Military Helmet Market Size, Share, and Industry Trends Forecast 2026-2036
Military Helmet Market Intelligence
Modular helmet systems with detachable communications and night-vision mounts is shifting procurement preferences toward configurable platforms rather than single-purpose designs. BAE Systems leverages its integrated electronics expertise to bundle sensor arrays with ballistic shells. Gentex Corporation anchors the aviation segment with specialized rotary-wing crew helmets. MKU Limited dominates South Asian supply chains through localized manufacturing and regional offset agreements.
A military helmet is a protective headgear engineered to ballistic and impact specifications, typically constructed from layered aramid fibers, ultra-high-molecular-weight polyethylene, or hybrid composite matrices, designed to attenuate ballistic threats, blunt trauma, and blast overpressure while accommodating communications and optical equipment. Ballistic helmets command the largest value share due to mandatory issue across frontline infantry, while communications helmets represent the fastest-expanding category as networked warfare protocols proliferate. Composite materials technology leads R&D investment, though polyethylene is displacing legacy Kevlar in weight-critical applications. Law enforcement end users generate stable replacement demand distinct from military procurement cycles.
The U.S. Army's Program Executive Office Soldier, NIJ ballistic resistance standards, and NATO STANAG 2920 fragmentation test protocols collectively dictate product certification requirements and market access conditions across allied defense procurement systems. The EU AI Act and emerging autonomous targeting regulations will increasingly govern helmet-integrated sensor suites and data processing modules. Stakeholders must weigh material substitution timelines against qualification delays as next-generation threats outpace existing test methodologies.
Market Dynamics
Ultra-high-molecular-weight polyethylene is displacing aramid fibers as the dominant ballistic material, compressing qualification timelines and forcing suppliers to revalidate shell architectures against NIJ and NATO STANAG protocols.
Growth Catalysts
- Enhanced Combat Helmet program:The U.S. Army's modernization mandate drives volume procurement of next-generation shells with integrated rail systems and improved fragmentation protection.
- NATO STANAG 2920:Standardized fragmentation test protocols across allied defense procurement systems create harmonized demand for certified suppliers.
- Rotary-wing avionics integration:Attack and transport helicopter crews require specialized helmets with built-in display systems, sustaining aviation segment expansion.
Market Restraints
- UHMWPE feedstock concentration:Polyethylene resin supply clusters among specialized chemical producers, exposing armor manufacturers to input price volatility and allocation risk.
- NIJ Type IIIA requalification:Material substitution triggers extended ballistic testing cycles, freezing product portfolios for 18-24 months.
- Blunt trauma trade-offs:Lightweight shells reduce neck strain but complicate backface deformation management, limiting adoption in heavy-infantry roles.
Strategic Opportunities
- Indian offset manufacturing:Defense procurement rules mandate local production, creating joint-venture openings for foreign helmet suppliers.
- Sensor-helmet convergence:Fusing ballistic protection with biometric monitoring and targeting displays opens special operations budgets.
- EU AI Act compliance services:Emerging rules on autonomous targeting systems create advisory and retrofit demand for helmet-integrated electronics.
Industry Challenges
- Composite layup technician scarcity:Hand-crafted helmet shell production requires skilled labor pools that defense contractors struggle to replenish.
- Legacy communications interoperability:New helmet-mounted radio systems must interface with decades-old vehicle and base station equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Helmet Market |
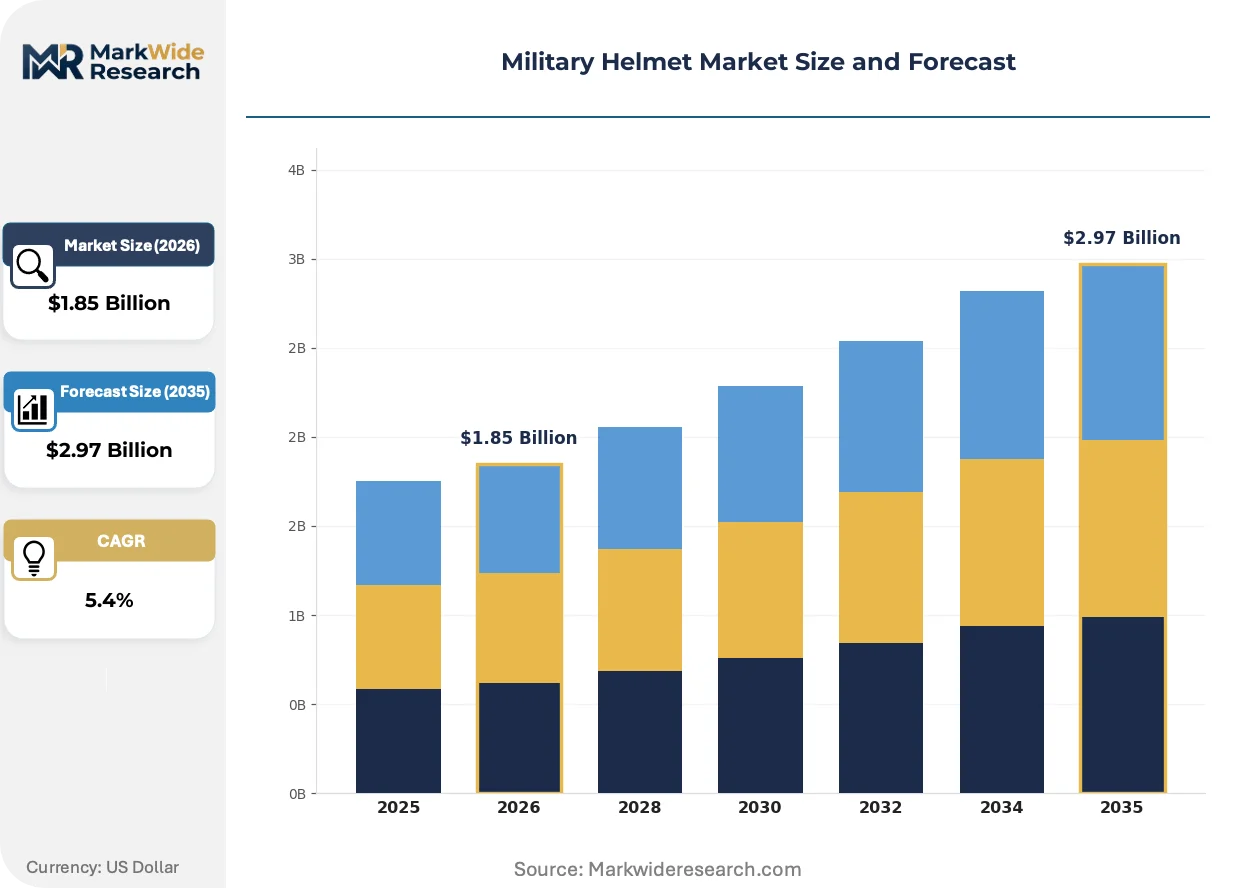
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballistic Helmets, Bump Helmets, Communications Helmets, Riot Helmets Technology: Composite Materials, Polyethylene, Kevlar, Advanced Graphics Systems End User: Military Forces, Law Enforcement, Security Personnel, Private Contractors Deployment: On-field Usage, Training Exercises, Tactical Operations, Peacekeeping Missions |
| Companies Covered | BAE Systems, MKU Limited, ArmorSource LLC, Point Blank Enterprises Inc., Honeywell International Inc., Gentex Corporation, Avon Rubber p.l.c., Rheinmetall, Revision Military, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Helmet Market Strategic Shifts & Innovations
Helmet architecture is converging with wearable computing platforms, transforming protective gear into distributed sensor nodes. This shift demands new material science, regulatory frameworks, and procurement models simultaneously.
Modular rail and shroud systems is unifying previously separate helmet functions into single platforms. Special operations units across NATO forces are mandating universal mount compatibility for night-vision devices, cameras, and bone-conduction headsets. This unification is compressing supplier margins on standalone communications helmets while expanding total platform value.
The EU AI Act is imposing algorithmic transparency requirements on helmet-integrated targeting and threat-detection modules. Manufacturers must now document decision logic for autonomous sensor suites sold into European defense markets. Aviation and mechanized infantry segments face the steepest compliance costs, driving partnerships with certified software auditors.
Multi-year platform contracts are replacing transactional helmet purchases in major defense ministries. The British Army's Virtus program and similar integrated soldier systems bundle head protection with torso armor, load carriage, and power management. This consolidation favors full-system integrators over component specialists, visible across Scandinavian and Baltic procurement patterns.
Military Helmet Market Segmentation
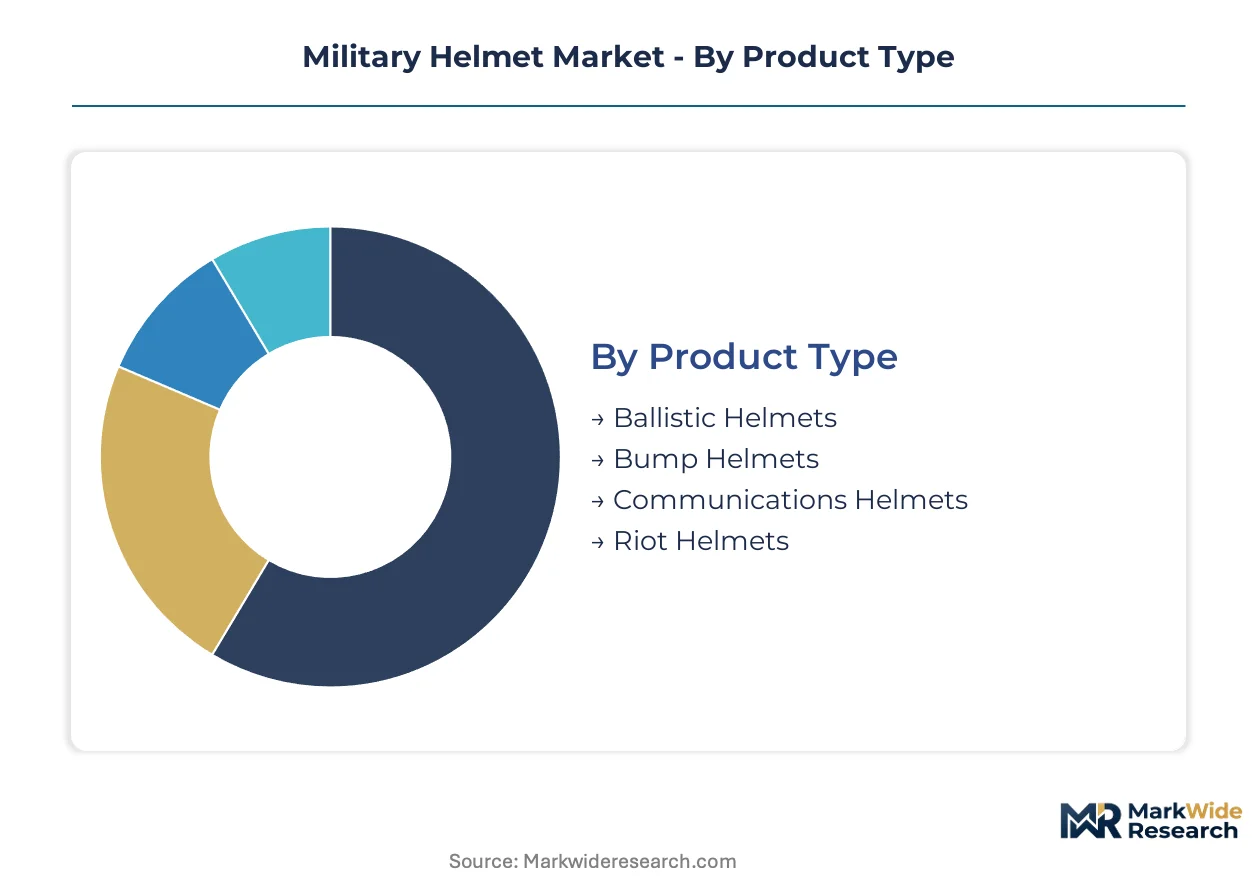
Military helmet procurement splits sharply between volume-driven standard issue and premium integrated systems. Segment boundaries blur as modular platforms absorb communications and sensor functions previously sold separately.
Product Type:
Ballistic shells dominate procurement volumes while communications-enabled variants capture expanding special operations budgets.
- Ballistic Helmets:Layered aramid or polyethylene composite shells engineered to NIJ Type IIIA and NATO STANAG 2920 fragmentation standards. Frontline infantry across U.S. Army brigade combat teams generate sustained replacement demand through the Enhanced Combat Helmet program.
- Communications Helmets:Integrated headborne platforms combining ballistic protection with bone-conduction audio, radio interfaces, and power distribution. NATO special operations units in Poland and Norway are mandating universal rail compatibility for night-vision and targeting modules.
- Bump Helmets:Lightweight polymer shells for training and vehicle crew protection where ballistic threats are secondary.
- Riot Helmets:Face-shield equipped designs for crowd control and detention facility security.
Today's leader: Ballistic Helmets. Tomorrow's challenger: Communications Helmets.
Technology:
Material substitution timelines separate incumbent suppliers from qualified polyethylene producers.
- Composite Materials:Hybrid matrix constructions layering ceramic strike faces with fiber-reinforced backings. British Army Virtus program specifications and similar integrated soldier systems in Sweden and Finland specify multi-material architectures.
- Polyethylene:Ultra-high-molecular-weight polyethylene fibers delivering equivalent ballistic performance at reduced areal density. U.S. Army qualification cycles for polyethylene shells are compressing as Enhanced Combat Helmet procurement accelerates.
- Kevlar:Legacy aramid fiber construction with established supply chains and proven multi-hit durability.
- Advanced Graphics Systems:Helmet-mounted display and augmented reality projection modules for aviation and mechanized crew applications.
Polyethylene is climbing the fastest as weight-critical applications displace legacy aramid.
End User:
Budget cycles and threat profiles create distinct procurement rhythms across user categories.
- Military Forces:National defense ministries with multi-year platform contracts and integrated soldier system mandates.
- Law Enforcement:Municipal and federal agencies with stable replacement demand distinct from military modernization waves.
- Security Personnel:Private sector guarding contracts and critical infrastructure protection roles.
- Private Contractors:Logistics and training support firms operating in active theaters under government contracts.
Military Forces anchor platform development. Law Enforcement sustains component suppliers through aftermarket cycles.
Deployment:
Usage intensity determines wear rates and replacement velocity across helmet categories.
- On-field Usage:Continuous wear in active theaters driving accelerated shell degradation and suspension system fatigue.
- Tactical Operations:High-intensity missions requiring integrated communications and night-vision compatibility.
- Training Exercises:Repetitive donning and doffing cycles stressing retention systems and rail attachments.
- Peacekeeping Missions:Extended deployments with mixed threat environments and multinational equipment interoperability requirements.
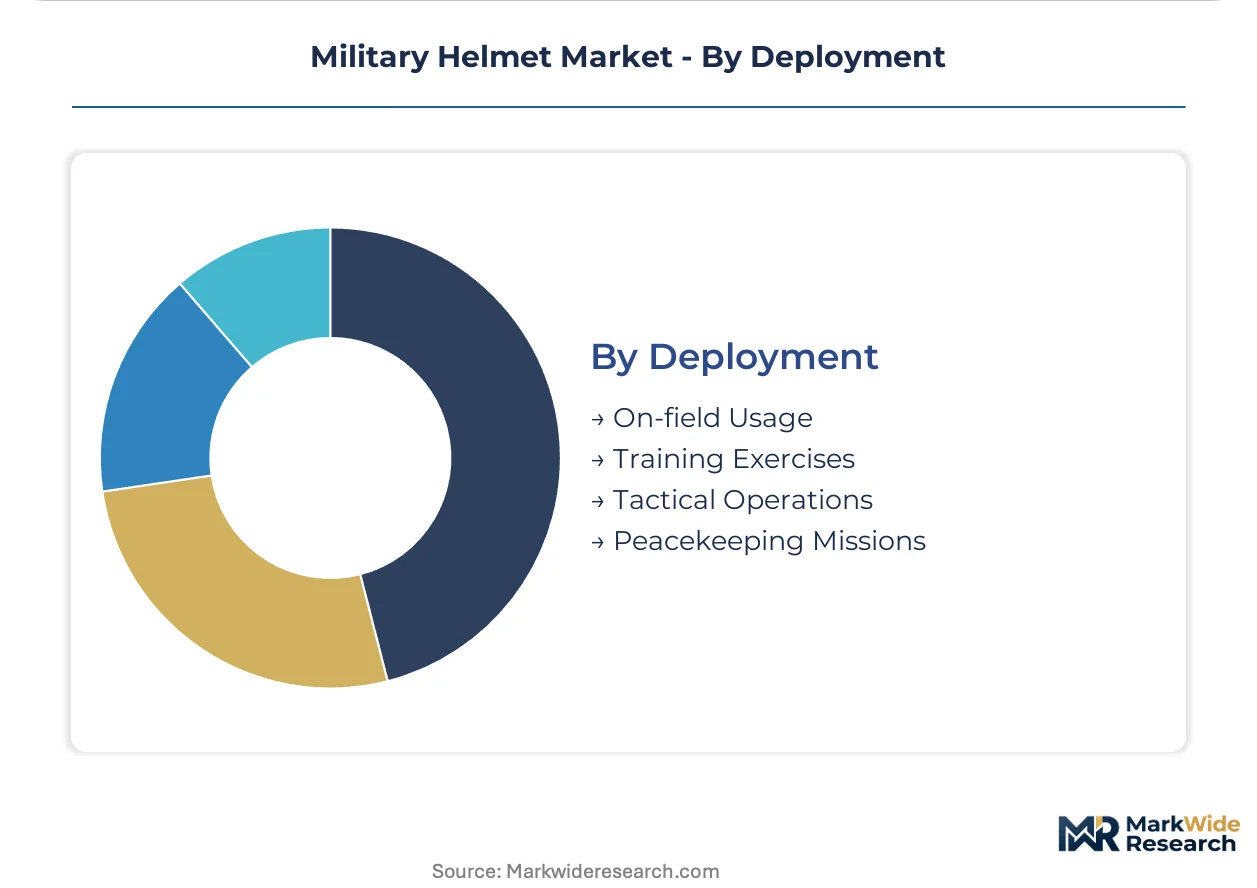
On-field Usage generates replacement pull. Tactical Operations commands premium pricing for integrated configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern military helmet industry traces its scaled manufacturing origins to mid-20th century U.S. defense procurement, with the M1 steel helmet establishing mass production protocols that persist in today's composite fabrication facilities.
United States
The Enhanced Combat Helmet program and sustained brigade combat team modernization sustain the world's largest procurement volume. NIJ Type IIIA certification requirements and Program Executive Office Soldier specifications govern all domestic supplier qualification. Production clusters concentrate in Pennsylvania and Michigan, where legacy automotive composite expertise feeds defense contractor supply chains.
Germany
Rheinmetall's integrated soldier system contracts and Bundeswehr IdZ-ES program upgrades anchor European demand. NATO STANAG 2920 fragmentation protocols and KBA military vehicle certification standards shape product specifications. The Bavaria and North Rhine-Westphalia industrial corridors host specialized polyethylene fiber processing and helmet shell molding operations.
United Kingdom
The British Army's Virtus integrated platform and ongoing infantry modernization cycles drive replacement procurement. Ministry of Defence DEF STAN 00-35 environmental testing requirements complement NATO standards. Manufacturing concentrates in the Midlands and South West England, where BAE Systems leverages existing aerospace composite facilities for defense headgear production.
India
Defense Procurement Procedure offset mandates and expanding special operations capacity generate joint-venture opportunities for foreign suppliers. BIS certification requirements and DGFT import licensing frameworks govern market access. MKU Limited anchors production in Kanpur and Manesar, with state-level industrial corridors in Uttar Pradesh and Haryana attracting component manufacturing.
Israel
Active theater deployments and counter-terrorism operations sustain premium demand for lightweight polyethylene configurations. Israeli Defense Forces specification protocols and Ministry of Defense tender processes favor rapid qualification cycles. Industrial activity concentrates in the Central District and Haifa Bay area, where specialized armor workshops serve both domestic and export special operations markets.
Military Helmet Market Key Industry Players
The competitive structure tilts toward full-system integrators with established defense ministry relationships. Tiered specialization separates ballistic shell fabricators from communications-integrated platform providers, with mid-scale regional manufacturers occupying offset-driven procurement niches. Three archetypes dominate: aerospace-defense conglomerates with composite expertise, specialized armor houses with regional supply chain control, and avionics specialists with rotary-wing helmet legacy. Capacity expansion and strategic partnerships represent the dominant competitive vectors as procurement consolidates around multi-year platform contracts.
Within the aerospace-defense conglomerate tier, BAE Systems exemplifies full-spectrum integration capability spanning sensor arrays to ballistic shells. MKU Limited occupies a distinct position as a regional anchor with localized manufacturing depth in South Asian supply chains. Gentex Corporation represents the specialized avionics archetype, with rotary-wing crew helmet expertise sustaining aviation segment presence. These three entities illustrate how geographic origin and structural focus shape competitive positioning without guaranteeing procurement outcomes.
| Leading Market Players |
|---|
| BAE Systems |
| MKU Limited |
| ArmorSource LLC |
| Point Blank Enterprises Inc. |
| Honeywell International Inc. |
| Gentex Corporation |
| Avon Rubber p.l.c. |
| Rheinmetall |
| Revision Military |
| Others |
Cost & Logistics Intelligence
Captive polyethylene fiber production anchors both cost positions and supplier pricing power, as UHMWPE resin concentration among specialized chemical producers forces armor manufacturers to absorb input volatility or pursue backward integration into polymer processing. The Enhanced Combat Helmet program's volume procurement and Indian offset mandates reshape how suppliers balance qualification timelines against margin protection.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates communications-integrated platforms from basic ballistic shells and training-grade bump helmets. Certification grade under NIJ Type IIIA and NATO STANAG 2920 protocols creates the primary price differentiation, while volume scale through multi-year platform contracts compresses unit economics for qualified suppliers. Pricing pressure stems from polyethylene material substitution forcing 18-24 month requalification cycles that freeze product portfolios. Law enforcement agencies exhibit highest price sensitivity due to municipal budget constraints, whereas special operations units demonstrate lowest sensitivity given mission-critical performance requirements.
Supply Chain Analysis
Domestic-content mandates in India's Defense Procurement Procedure and similar offset frameworks in NATO member states are reshaping sourcing patterns toward localized shell molding and regional component integration. UHMWPE resin supply clusters in the United States, Germany, and Japan, drawing from specialized chemical producers with limited alternative sources. Ballistic shell production depends on skilled composite layup technicians, polyethylene fiber weaving operations, and suspension system hardware. Single-source vulnerability in UHMWPE feedstock creates allocation risk during defense procurement surges. Distribution runs through defense ministry tender processes, prime contractor integration contracts, and specialized law enforcement procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in polyethylene-qualified suppliers capturing premium-tier communications helmet demand, as material substitution compresses legacy aramid margins while integrated platform contracts reward full-system capability.
For Market Incumbents: Extend qualification pipelines into EU AI Act-compliant sensor-helmet convergence to defend against aerospace-electronics entrants, while consolidating backward integration into UHMWPE fiber processing to offset resin price volatility and secure supply allocation during Enhanced Combat Helmet procurement waves. For New Entrants and Emerging Players: The price-point gap between premium communications-integrated platforms and economy ballistic shells creates entry space for mid-tier modular helmet suppliers targeting NATO special operations units in Poland and Norway with universal rail compatibility offerings, leveraging joint-venture structures to satisfy Indian offset manufacturing requirements. For Investors and Strategic Acquirers: Roll-up economics work for regional armor houses with localized certification depth because defense procurement consolidation around multi-year platform contracts favors suppliers with established ministry relationships and captive manufacturing footprints. Target acquisition archetypes include polyethylene-qualified shell fabricators in South Asian supply chains and avionics-helmet integration specialists serving rotary-wing segments. The signal to watch is EU AI Act implementation timelines accelerating compliance-driven consolidation among helmet-integrated electronics suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into UHMWPE Fiber Production | Captive resin processing insulates ArmorSource and Point Blank from Dow and DSM allocation decisions during Enhanced Combat Helmet surges. |
| EU AI Act Compliance Certification | Algorithmic transparency documentation for helmet-mounted targeting modules opens advisory revenue streams from BAE Systems' European defense customers. |
| Indian Joint-Venture Manufacturing | Localized shell production satisfies DGFT import licensing while positioning foreign suppliers for Defence Procurement Procedure offset credits. |
| Multi-Year Platform Contract Pursuit | British Army Virtus-style integrated soldier system bundling captures head-to-toe procurement budgets away from component specialists. |
| Composite Layup Technician Training Pipeline | Skilled labor replenishment programs address the scarcity constraining Gentex and Revision Military capacity expansion in Pennsylvania and Michigan clusters. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Program Executive Office Soldier procurement officers, composite materials R&D directors at defense contractors, special operations equipment program managers, and law enforcement agency procurement leads. Secondary validation drew from NIJ ballistic resistance certification databases, NATO STANAG 2920 test protocol documentation, SEC 10-K filings of listed defense suppliers, and customs records tracking UHMWPE resin imports. Bottom-up unit demand modeling and top-down defense budget allocation analysis provided cross-check triangulation.
Historical reference periods anchored the projection horizon through verified procurement volumes from the Enhanced Combat Helmet program and comparable NATO modernization cycles. The analytical framework modeled demand across product type, material technology, end-user category, and deployment intensity dimensions, with regional regulatory clusters capturing EU AI Act, Indian Defence Procurement Procedure, and U.S. NIJ certification pathway variations. CAGRs derived from segment-level volume trajectories weighted by platform contract visibility and material substitution timelines. Industry-specific inputs included polyethylene qualification cycle durations and special operations unit equipment refresh rates.
Caveats apply where UHMWPE feedstock allocation disruptions, NIJ requalification delays, or EU AI Act enforcement intensity could materially shift the outlook. Forecasts reflect assumptions regarding defense ministry budget continuity and NATO STANAG protocol harmonization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Martial Art Weapon Market
Weapons and Ammunition
Global Artillery Systems Market
Weapons and Ammunition
Detonator Market
Weapons and Ammunition
Smart Bullets Market
Weapons and Ammunition
Man-Portable Anti-Armor Weapons Market
Weapons and Ammunition
Europe Cruise Missile Market
Weapons and Ammunition
Intercontinental Ballistic Missile Market
Weapons and Ammunition
Non Lethal Projectiles Market
Weapons and Ammunition
Global Rockets and Missiles Market
Weapons and Ammunition
Command Fuzes Market
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Manned Anti-Tank Guided Missile System Market
Weapons and Ammunition
Hypersonic Missile Market
Weapons and Ammunition
APAC Ballistic Missile Market
Weapons and Ammunition
US Perforating Gun Market
Weapons and Ammunition
Asia-Pacific Medium and Large Caliber Ammunition Market