
 Medium Caliber Ammunition Market | 2026-2036
Medium Caliber Ammunition Market Size, Share, and Industry Trends Forecast 2026-2036
Medium Caliber Ammunition Market Outlook
REACH is repositioning the cost-of-entry calculus for European manufacturers by mandating replacement of traditional nitrocellulose propellants with lower-toxicity alternatives. Rheinmetall AG leverages its captive nitrochemistry capacity to sustain margin stability under these rules. Nammo AS anchors Nordic supply security through vertically integrated propellant production. General Dynamics Corporation competes on scale across NATO-aligned armored vehicle programs.
Medium caliber ammunition encompasses projectiles and cartridges typically ranging from 20mm to 40mm, engineered with brass or steel casings, smokeless powder propellants, and specialized primers for sustained automatic fire from crew-served and vehicle-mounted weapons. These rounds serve military forces for suppression, armor defeat, and area target engagement. Armor-piercing product types concentrate the highest engineering value due to tungsten and depleted uranium core requirements. Military end users dominate procurement volume, though law enforcement demand for specialized training ammunition is expanding. Combat applications absorb the majority of production capacity, while training rounds face cost-pressure from simulators and reduced-lead mandates.
NATO standardization agreements, U.S. Department of Defense MIL-SPEC frameworks, and EU REACH chemical restrictions collectively constrain design freedom while creating compliance-driven supplier consolidation. The U.S. EPA adds pressure through perchlorate and lead remediation rules affecting firing ranges and manufacturing discharge. Stakeholders must monitor propellant chemistry transitions, NATO stockpile replenishment rhythms, and shifting U.S. Army Next Generation Squad Weapon requirements to align capacity with procurement windows.
Market Dynamics
EU REACH chemical restrictions are forcing wholesale propellant reformulation across European production lines while NATO stockpile replenishment creates simultaneous demand pull from allied defense ministries. This regulatory-demand tension compresses margins for non-integrated manufacturers while rewarding captive chemistry capabilities.
Growth Catalysts
- NATO Standardization Agreements:STANAG frameworks harmonize procurement specifications across 31 member states, reducing qualification overhead for certified suppliers and accelerating multi-year ammunition contracts.
- Perchlorate Remediation Mandates:U.S. EPA discharge rules for firing ranges and manufacturing sites are accelerating adoption of alternative oxidizer chemistries in propellant formulations.
- Next-Generation Vehicle Programs:U.S. Army Next Generation Squad Weapon requirements are driving qualification cycles for 6.8mm medium-caliber systems and associated ammunition families.
Market Restraints
- Tungsten Supply Concentration:Armor-piercing core production depends on Chinese tungsten processing dominance, creating strategic vulnerability for non-allied sourcing.
- Nitrocellulose Feedstock Volatility:Cotton linter availability and pricing swings directly impact smokeless powder cost structures across European and North American load lines.
- REACH Registration Burden:ECHA compliance costs for novel propellant ingredients create multi-year barriers to formulation innovation for mid-tier manufacturers.
Strategic Opportunities
- Training Simulator Substitution Gap:Live-fire range restrictions in Germany and Benelux countries are expanding demand for force-on-force simulation systems that preserve ammunition procurement budgets.
- Lead-Free Mandate Convergence:U.S. Army and EU Green Deal timelines are aligning to create unified specification demand for copper-alloy projectile cores.
- Indigenous Production Incentives:Poland's military modernization program includes domestic ammunition manufacturing capacity expansion with technology transfer requirements.
Industry Challenges
- Propellant Chemist Talent Pipeline:Specialized expertise in nitrochemistry and ballistics formulation is retiring faster than university programs replenish qualified personnel.
- Dual-Use Export Control Complexity:ITAR and EU Common Position 2008/944/CFSP classification reviews extend contract award timelines by 12-18 months for cross-border sales.
- Legacy Case Crimp Standards:NATO and U.S. MIL-SPEC cartridge construction specifications require redundant tooling investments for manufacturers serving both specification families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medium Caliber Ammunition Market |
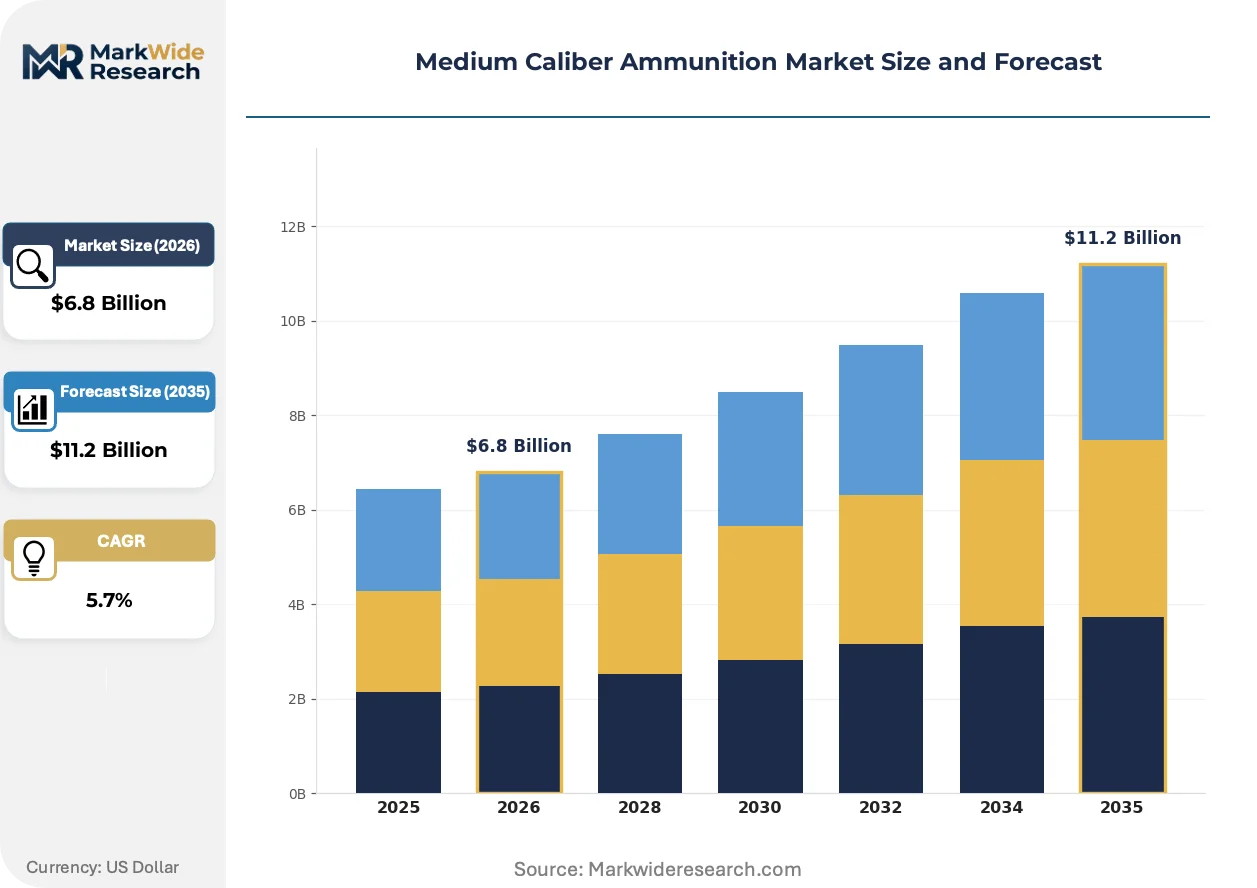
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rifled, Tracer, Armor-Piercing, Incendiary End User: Military, Law Enforcement, Private Security, Civilian Application: Combat, Training, Hunting, Target Shooting Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Rheinmetall AG, Nammo AS, General Dynamics Corporation, CBC Global Ammunition, Arsenal JSCo, BAE Systems PLC, FN Herstal, ST Engineering, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medium Caliber Ammunition Market Strategic Shifts
Propellant chemistry innovation and procurement model restructuring are converging to reshape competitive positioning in medium-caliber ammunition. Manufacturers must now balance regulatory compliance velocity against qualification timeline compression.
Caseless ammunition technology is integrating polymer-bound propellant charges with telescoped projectile seating to reduce cartridge mass and eliminate brass sourcing dependency. U.S. Army Next Generation Squad Weapon program offices are evaluating these systems for fielding trials. The structural consequence is compressing traditional cartridge manufacturing capacity planning horizons as qualification outcomes remain uncertain.
REACH authorization requirements for diphenylamine stabilizers and other traditional propellant ingredients are forcing European manufacturers toward novel chemistries with shorter shelf-life validation histories. ECHA sunset dates for unregistered substances are accelerating reformulation investments. Armor-piercing product lines face the steepest compliance curves due to core-jacket bonding chemistry dependencies.
Multi-year indefinite delivery contracts are displacing annual procurement cycles for major NATO defense ministries, concentrating volume with pre-qualified suppliers and extending production planning horizons. Danish and Norwegian defense procurement agencies have adopted this model for 25mm and 30mm vehicle ammunition. The shift is most visible in Nordic countries where joint acquisition frameworks amplify buyer concentration effects.
Medium Caliber Ammunition Market Segmentation
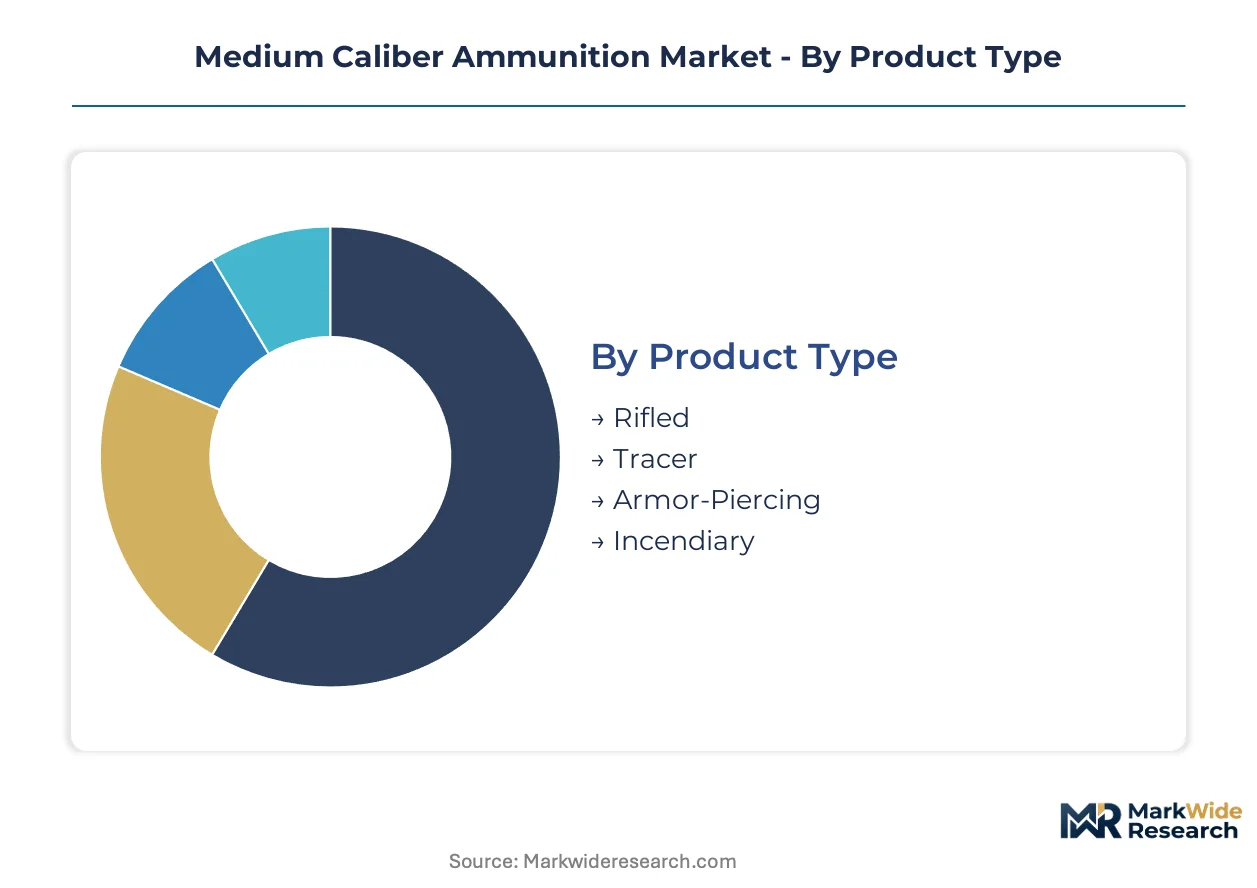
Segmentation in medium-caliber ammunition reflects divergent specification requirements across NATO procurement frameworks and national regulatory regimes. Procurement officers balance interoperability mandates against specialized mission profiles, creating tiered demand structures that reward qualified suppliers differently across each category.
Product Type:
Customization intensity varies sharply across this category, from mass-producible training rounds to mission-specific armor-defeat systems requiring exotic core materials and bonded construction.
- Armor-Piercing:Tungsten or depleted uranium cores bonded to copper alloy jackets deliver kinetic energy penetration against hardened vehicle armor. U.S. Army Next Generation Squad Weapon programs and NATO vehicle modernization drives concentrate procurement for these highest-unit-value rounds.
- Tracer:Pyrotechnic compounds embedded in the projectile base provide visible trajectory marking for machine gun fire correction. German and Norwegian defense ministries specify reduced-burn formulations to minimize range fire hazards during extended training exercises.
- Rifled:Standard ball ammunition with spin-stabilized projectiles optimized for rifled barrels serves baseline suppression and area target engagement. Cotton linter price volatility directly impacts smokeless powder cost structures for this highest-volume segment.
- Incendiary:Thermite-based payloads ignite fuel and ammunition stores through armor penetration. ITAR classification extends contract timelines for cross-border sales.
Leading the category by volume: Rifled. Expanding most quickly: Armor-Piercing.
End User:
Procurement scale and specification complexity separate state actors with multi-year indefinite delivery contracts from fragmented private demand with spot-market purchasing patterns.
- Military:National defense ministries account for the overwhelming majority of medium-caliber procurement volume through STANAG-harmonized multi-year agreements. REACH compliance costs and ECHA authorization timelines for novel propellant chemistries most acutely affect suppliers serving European defense ministries.
- Law Enforcement:Specialized training ammunition demand is expanding as German and Benelux range restrictions tighten. Reduced-lead mandates from U.S. EPA and EU Green Deal timelines are converging specification requirements.
- Private Security:Maritime protection and critical infrastructure contracts drive irregular procurement of linked ammunition for vehicle-mounted weapons. Export control complexity extends fulfillment timelines.
- Civilian:Collectors and competitive shooters purchase limited volumes of decommissioned military surplus or specially manufactured match-grade ammunition. Distribution concentrates through licensed retail channels.
Military end users dominate absolute volume. Law Enforcement procurement is climbing the fastest amid range modernization mandates.
Application:
Mission-criticality determines specification tolerance, with combat-rated rounds requiring full environmental qualification against training alternatives facing cost-pressure from simulator substitution.
- Combat:Full-spectrum environmental qualification from arctic to desert conditions, with shelf-life validation exceeding two decades. Armor-piercing product lines absorb disproportionate engineering resources due to core-jacket bonding chemistry dependencies under REACH sunset timelines.
- Training:Cost-optimized formulations face demand erosion from force-on-force simulation systems in range-restricted jurisdictions. Polish domestic production incentives are preserving live-fire procurement budgets through indigenous manufacturing capacity expansion.
- Hunting:Medium-caliber applications are limited to specific large-game regulations in Nordic countries. Lead-free projectile mandates are accelerating copper-alloy core adoption.
- Target Shooting:Match-grade consistency requirements drive small-batch production with premium pricing. Nitrocellulose feedstock quality directly impacts batch uniformity.
Combat applications command the largest production capacity allocation. Training rounds face the steepest demand pressure from simulator substitution.
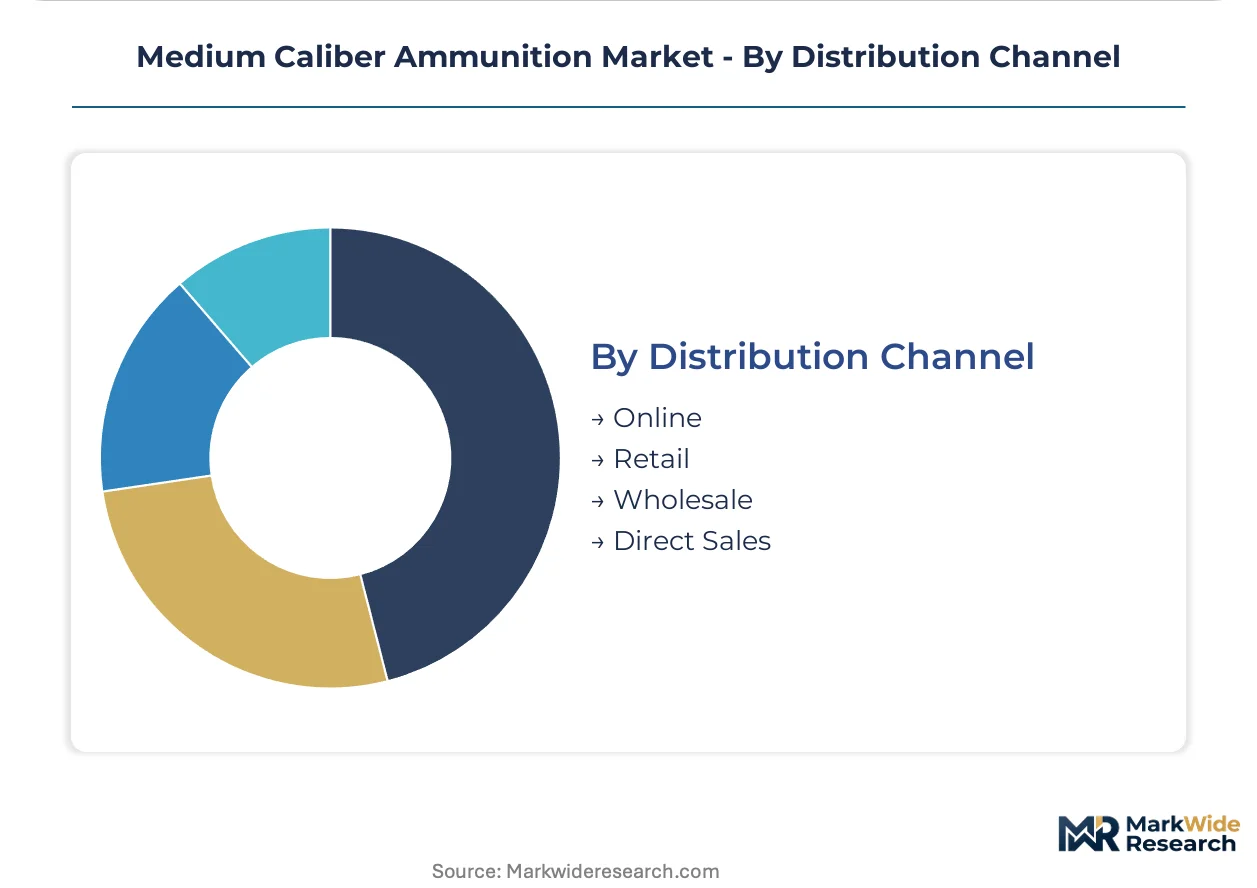
Distribution Channel:
Regulatory compliance burden and transaction scale separate direct government procurement from fragmented retail pathways subject to national firearms licensing frameworks.
- Direct Sales:Defense ministry contracts negotiated through national procurement agencies concentrate volume with pre-qualified suppliers. Danish and Norwegian joint acquisition frameworks amplify buyer concentration effects for 25mm and 30mm vehicle ammunition.
- Wholesale:Distributors aggregate demand from multiple NATO allies for standardized STANAG ammunition, reducing per-country qualification overhead. Legacy case crimp standards require redundant tooling investments for manufacturers.
- Retail:Licensed firearms dealers serve law enforcement and civilian segments with batch-controlled traceability requirements. U.S. EPA perchlorate remediation mandates affect firing range discharge compliance.
- Online:Digital platforms face strict ITAR and EU Common Position 2008/944/CFSP classification reviews for cross-border transactions. Age verification and end-user certification create fulfillment friction.
Direct Sales channels move the highest volume through multi-year agreements. Wholesale distribution is gaining share fastest through Nordic joint procurement frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Poland and tax incentives for domestic defense manufacturing are concentrating European medium-caliber ammunition investment. These zones attract technology transfer agreements and offset procurement commitments from NATO allies.
United States
Department of Defense multi-year indefinite delivery contracts for 6.8mm Next Generation Squad Weapon systems drive procurement volume. EPA perchlorate remediation mandates accelerate alternative oxidizer adoption in propellant formulations. Lake City Army Ammunition Plant in Missouri anchors government-owned production capacity with contractor-operated modernization programs underway.
Germany
Rheinmetall AG leverages captive nitrochemistry facilities to supply NATO vehicle programs with REACH-compliant propellants. ECHA sunset timelines for diphenylamine stabilizers force accelerated reformulation investments. Unterlüß in Lower Saxony concentrates armor-piercing round engineering and testing infrastructure.
Poland
Military modernization programs prioritize indigenous ammunition manufacturing with technology transfer requirements from foreign partners. EU Green Deal alignment mandates drive lead-free projectile core development. Special economic zones near Warsaw and Poznań attract joint venture investments for 25mm and 30mm vehicle ammunition production lines.
Norway
Nordic joint acquisition frameworks with Denmark amplify buyer concentration for standardized STANAG ammunition. Nammo AS maintains vertically integrated propellant production for supply security. Raufoss hosts specialized nitrochemistry facilities serving allied defense ministries across northern Europe.
United Kingdom
BAE Systems PLC operates legacy cartridge manufacturing with MOD procurement for Challenger 3 and Ajax vehicle programs. REACH chemical registration burdens affect cross-border sourcing from European suppliers. Radway Green in Cheshire retains case production and load-assemble-pack capacity for national stockpile replenishment.
Medium Caliber Ammunition Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across NATO procurement frameworks. The market structure concentrates volume with pre-qualified suppliers holding STANAG certifications and captive chemistry capabilities. Three archetypes dominate: integrated defense conglomerates with nitrochemistry assets, regional specialists leveraging joint procurement frameworks, and government-linked manufacturers serving national stockpile programs. Competitive moves center on backward integration into propellant ingredients and multi-year contract positioning ahead of qualification windows.
Among European integrated producers, Rheinmetall AG and Nammo AS exemplify the chemistry-captive archetype that sustains margin stability under REACH reformulation mandates. General Dynamics Corporation represents the scale-driven defense conglomerate competing across NATO armored vehicle programs. These three occupy positions that align with divergent procurement rhythms: German-led EU regulatory compliance, Nordic joint acquisition concentration, and U.S. multi-year indefinite delivery contracting.
| Leading Market Players |
|---|
| Rheinmetall AG |
| Nammo AS |
| General Dynamics Corporation |
| CBC Global Ammunition |
| Arsenal JSCo |
| BAE Systems PLC |
| FN Herstal |
| ST Engineering |
| Northrop Grumman Corporation |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between STANAG-qualified combat rounds and commercial training ammunition manifests in both pricing premiums and supply chain redundancy requirements. NATO defense ministries pay lead-time premiums for qualified armor-piercing rounds while spot-market training ammunition faces cost compression from simulator substitution and reduced-lead mandates.
Pricing Analysis
Lead-time-driven pricing premiums reward manufacturers with pre-qualified STANAG certifications and compressed delivery windows for NATO defense ministries. Three-tier pricing structure across premium combat-rated, standard training, and economy surplus segments reflects certification burden and shelf-life validation investment. Pricing pressure stems from ECHA authorization timelines forcing reformulation costs onto mid-tier European manufacturers. Law enforcement training procurement shows highest price sensitivity amid budget constraints and simulator competition.
Supply Chain Analysis
Single-source vulnerability sits with Chinese tungsten processing dominance for armor-piercing core production. Raw material flows draw from German nitrochemistry clusters, Nordic cotton linter suppliers, and Belgian propellant stabilizer manufacturers. Supply chain risk centers on REACH sunset timelines for diphenylamine and other traditional propellant ingredients. Distribution runs through Danish-Norwegian joint acquisition frameworks for standardized vehicle ammunition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Caseless ammunition technology is displacing brass-cased legacy systems across U.S. Army Next Generation Squad Weapon programs, compressing planning horizons for traditional cartridge manufacturers.
For Market Incumbents: Hedge against propellant chemistry transition risk by securing captive nitrochemistry capacity or joint venture partnerships with REACH-compliant stabilizer suppliers. Rheinmetall's backward integration model offers template value. Accelerate qualification cycles for 6.8mm systems before contract windows close. For New Entrants and Emerging Players: Begin with Polish special economic zones where technology transfer requirements and domestic production incentives create accessible entry points for 25mm and 30mm vehicle ammunition. Target law enforcement training segments with lead-free copper-alloy formulations as regulatory timelines converge across U.S. and EU markets. For Investors and Strategic Acquirers: Re-rating potential sits with nitrochemistry-captive mid-cap specialists given ECHA authorization bottlenecks and propellant reformulation mandates. Long-term viability favors assets with demonstrated REACH compliance velocity and NATO STANAG certification depth. Monitor U.S. Army caseless ammunition fielding trials as inflection signal for traditional capacity obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrochemistry | Rheinmetall's captive stabilizer production insulates margins from ECHA sunset timelines. |
| Joint Venture in Polish Special Economic Zones | Technology transfer requirements unlock NATO vehicle program access for new manufacturing capacity. |
| Lead-Free Projectile Core Development | Copper-alloy formulations align U.S. Army and EU Green Deal procurement specifications. |
| Multi-Year Indefinite Delivery Contract Positioning | Danish-Norwegian frameworks concentrate volume with pre-qualified STANAG suppliers. |
| Caseless Ammunition Qualification Investment | U.S. Army Next Generation Squad Weapon trials determine future cartridge architecture winners. |
Study Parameters
Multi-period observation of NATO stockpile replenishment rhythms, REACH compliance investment flows, and propellant chemistry patent filings anchored the trend analysis, supplemented by interviews with defense procurement officers, nitrochemistry plant managers, ammunition load-assemble-pack engineers, and ECHA regulatory consultants. Secondary validation drew from NATO STANAG documentation, ECHA authorization databases, U.S. Army program executive office disclosures, and customs trade data for tungsten and cotton linter flows. Bottom-up volume modeling triangulated against top-down defense budget allocation analysis.
Segment-weighting across product type, end user, application, and distribution channel dimensions shaped the analytical framework across the projection horizon. CAGRs derived from procurement contract award trajectories, modernization program timelines, and regulatory phase-in schedules. Industry-specific forecast inputs included propellant reformulation capital expenditure curves and Nordic joint acquisition framework expansion patterns.
Underlying measurement precision varies by segment; military end-user and armor-piercing product type categories carry tighter precision than fragmented law enforcement and civilian channels. Forecasts reflect documented assumptions regarding NATO defense spending continuity, REACH authorization timeline adherence, and caseless ammunition program progression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Southeast Asia, Middle-East and Africa Small Arms and Ammunition Market
Weapons and Ammunition
Recoilless Rifle Market
Weapons and Ammunition
Small and Medium Caliber Ammunition Market
Weapons and Ammunition
Europe Medium and Large Caliber Ammunition Market
Weapons and Ammunition
North America Weapon Night Sight Market
Weapons and Ammunition
North Korea Nuclear Bombs and Missiles Market
Weapons and Ammunition
Man-Portable Anti-Armor Weapons Market
Weapons and Ammunition
Less Lethal Ammunition Market
Weapons and Ammunition
Directed Energy Weapons Market
Weapons and Ammunition
North America Small Arms Market
Weapons and Ammunition
Small Arms Market
Weapons and Ammunition
Nuclear Bomb Market
Weapons and Ammunition
Cruise Missile Market
Weapons and Ammunition
Global Rockets and Missiles Market
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Weapon Mounts Market