
 Sea-Based Remote Weapon Systems Market | 2026-2036
Sea-Based Remote Weapon Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Sea-Based Remote Weapon Systems Market Analytics
Coast guard services and littoral combat commands are rotating procurement priority toward unmanned platforms with integrated remote firing capability. Kongsberg Defence & Aerospace leverages its Protector naval remote weapon station lineage to anchor Nordic and allied fleet retrofit programs. Elbit Systems competes through vertical integration across electro-optical and fire-control subsystems. Saab AB differentiates via compact stabilized turrets optimized for fast-attack craft and patrol vessel displacement classes.
Sea-based remote weapon systems comprise stabilized weapon mounts, sensor suites, and fire-control electronics that enable operators to acquire, track, and engage targets from a protected position without direct line-of-sight exposure. These systems integrate gyroscopic stabilization, thermal imaging, and ballistic computation to deliver accurate engagement in sea states up to severe conditions. Missile systems command the largest value share within weapon type segmentation due to standoff engagement requirements against fast incoming threats. Unmanned surface vessels represent the fastest-expanding platform category as navies field optionally crewed craft for mine countermeasures and perimeter security. Artificial intelligence integration across targeting pipelines is concentrating R&D investment and reshaping competitive positioning.
The U.S. Navy's Naval Sea Systems Command imposes shock qualification and electromagnetic interference standards that filter vendor eligibility for domestic programs. NATO STANAG agreements harmonize interface protocols but create compliance burden for non-aligned suppliers seeking cross-border integration. The EU AI Act and concurrent export control frameworks under the Wassenaar Arrangement constrain autonomous engagement algorithm deployment. Procurement officers must weigh interoperability certification timelines against operational urgency when selecting system architectures.
Market Dynamics
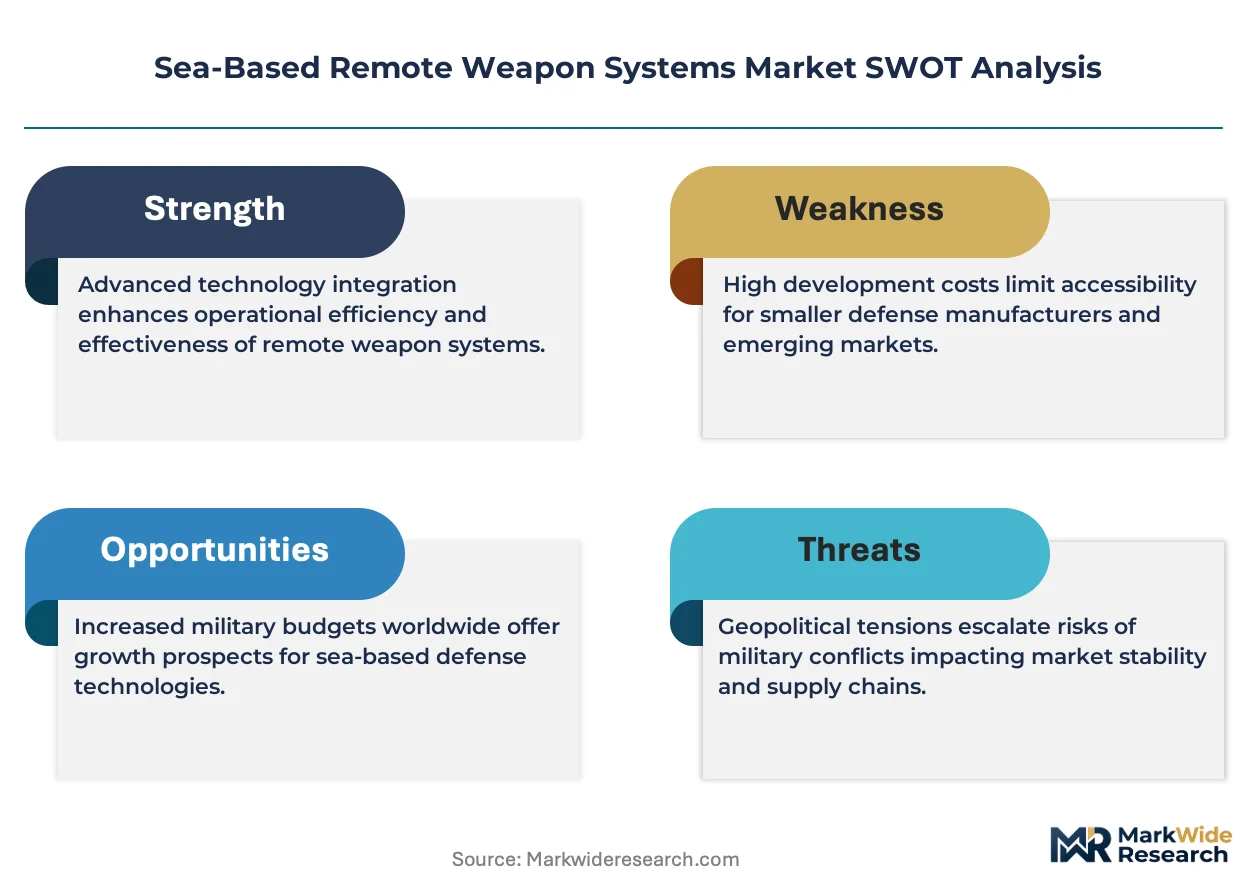
The distributed maritime operations doctrine adopted by the U.S. Navy is compressing procurement cycles and forcing integration of gallium nitride radar components into compact naval platforms. This structural shift toward distributed lethality is reshaping vendor qualification requirements and platform architecture decisions across NATO-aligned fleets.
Growth Catalysts
- Directed-energy platform maturation:Solid-state laser weapon systems are achieving tactical power thresholds for counter-UAS and small boat defense, driving retrofit demand on destroyer and littoral combat ship classes.
- NATO STANAG 4695:Harmonized interface protocols for remote weapon stations are reducing integration costs and enabling cross-border fleet standardization among allied navies.
- Indo-Pacific littoral contested zones:Coastal defense modernization programs across Vietnam, Philippines, and Indonesia are accelerating procurement of stabilized turrets for fast-attack craft.
Market Restraints
- Gallium nitride substrate supply:Defense-grade GaN-on-SiC wafers concentrate among three qualified foundries, creating chokepoint vulnerability for radar and electronic warfare subsystem production.
- EU AI Act autonomous engagement constraints:Algorithmic target classification and engagement authorization protocols face compliance burden that extends development timelines by 18-24 months for European suppliers.
- Shock qualification cost structure:Naval Sea Systems Command MIL-STD-901D heavy weight shock testing requires dedicated barge facilities that filter mid-tier vendors from domestic U.S. programs.
Strategic Opportunities
- Unmanned surface vessel weaponization:Optionally crewed mine countermeasures craft represent greenfield platform category requiring compact stabilized mounts with reduced manning footprints.
- Wassenaar Arrangement control list revision:Export control harmonization discussions are creating pathway for allied supplier qualification in previously restricted autonomous targeting algorithm markets.
- Artificial intelligence targeting pipeline convergence:Sensor fusion architectures combining thermal imaging, radar track files, and electro-optical feeds enable predictive fire control with reduced operator cognitive load.
Industry Challenges
- Electromagnetic interference certification:MIL-STD-461G compliance for conducted emissions and radiated susceptibility requires specialized anechoic chamber access that bottlenecks vendor throughput.
- Legacy combat system integration:Aegis Baseline 9 and earlier shipboard computing architectures present protocol translation complexity for modern Ethernet-based remote weapon stations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sea-Based Remote Weapon Systems Market |
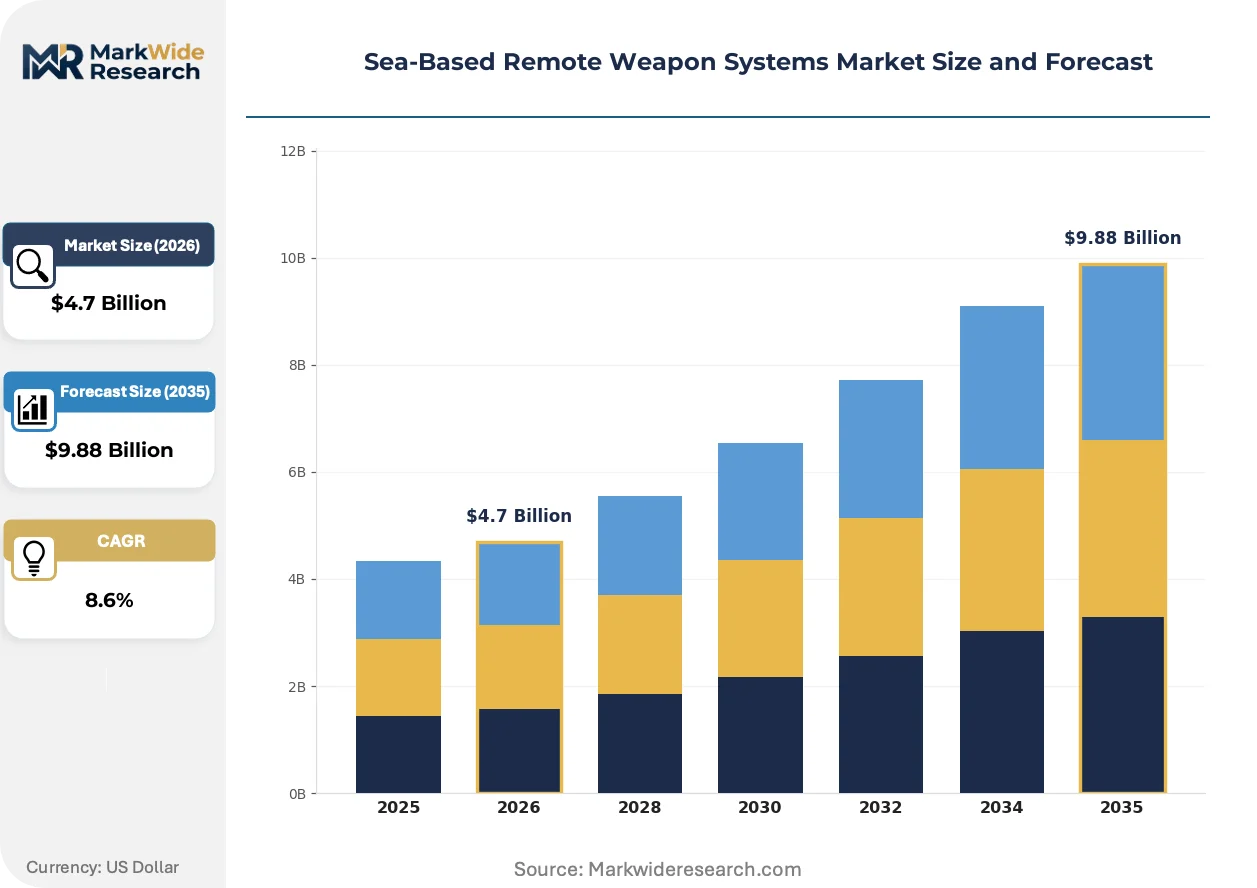
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Weapon Type: Laser Systems, Gun Systems, Missile Systems, Drone Systems Platform: Naval Vessels, Unmanned Surface Vessels, Submarines, Coastal Defense Technology: Electro-Optical, Radar, Robotics, Artificial Intelligence End User: Military, Coast Guard, Private Security, Government Agencies |
| Companies Covered | Raytheon Company, Saab AB, Kongsberg Defence & Aerospace, Rafael Advanced Defense Systems, Rheinmetall AG, Leonardo S.p.A., General Dynamics Corporation, ASELSAN A.S, Elbit Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sea-Based Remote Weapon Systems Market Evolving Landscape
Active electronically scanned array technology is migrating from major combatants to patrol vessel displacement classes, compressing sensor-to-shooter timelines and enabling over-the-horizon targeting for previously unequipped platforms.
Gallium nitride monolithic microwave integrated circuit technology is miniaturizing radar front-end components while doubling power efficiency. Fast-attack craft operators in Southeast Asian navies are adopting these compact arrays for fire-control radar upgrades. The resulting footprint reduction is enabling weapon-sensor integration on vessels below 500 tons displacement previously excluded from networked targeting architectures.
The EU AI Act classification of autonomous engagement algorithms as high-risk AI systems imposes conformity assessment and CE marking requirements on European suppliers. This regulatory friction is diverting R&D investment toward explainable AI architectures that satisfy human-in-the-loop mandates. Nordic and Baltic fleet procurement programs are prioritizing vendors with pre-certified algorithmic transparency documentation.
Buyer concentration among NATO naval procurement agencies is consolidating specification-setting authority and compressing vendor negotiation leverage. Tier-1 system integrators are responding by unbundling sensor suites from weapon mounts to participate in upgrade-only contracts. This service-model pivot is most visible in Royal Navy Type 26 frigate and Canadian Surface Combatant programs, where through-life support contracts now exceed initial hardware value.
Sea-Based Remote Weapon Systems Market Segmentation
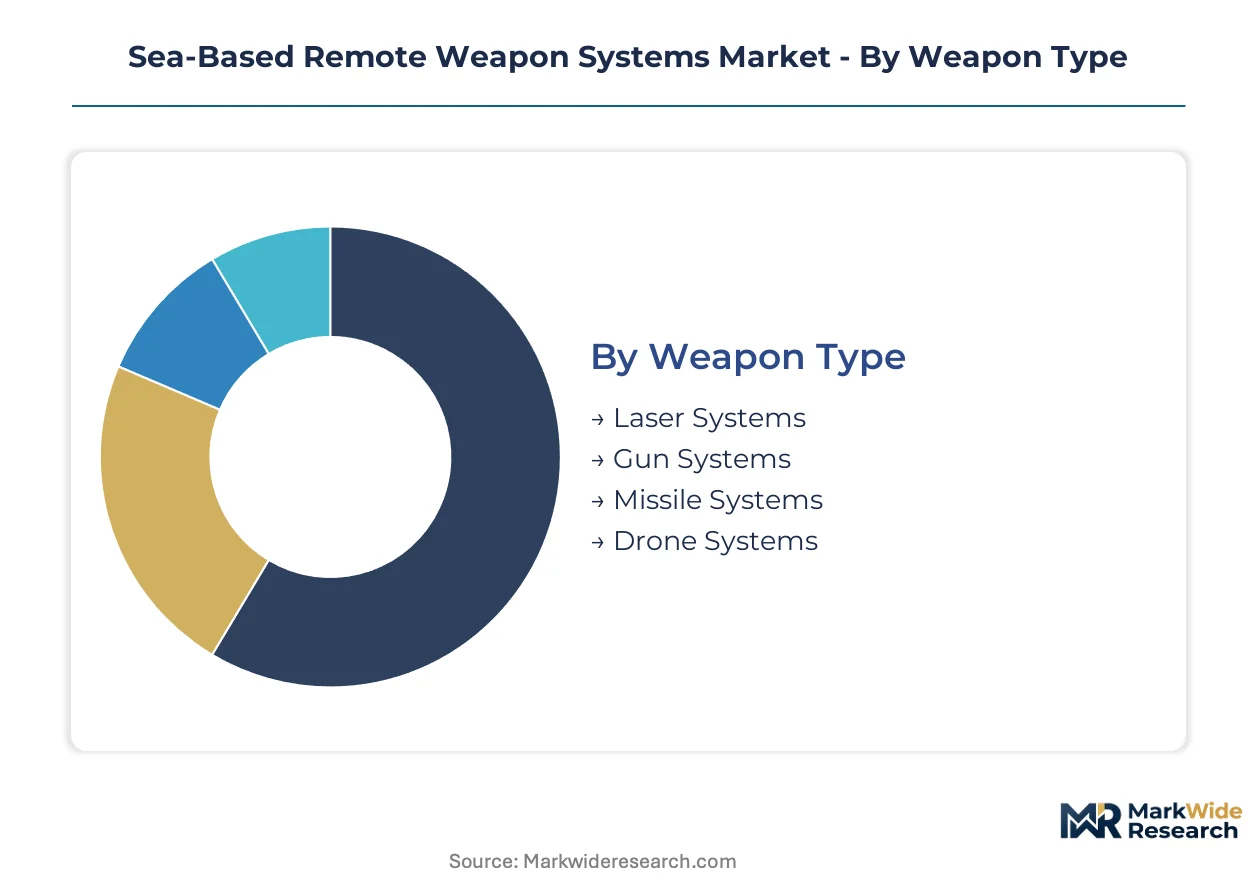
Weapon type and platform configurations determine shock qualification requirements and electromagnetic interference standards for sea-based remote weapon systems. Technology integration choices cascade through procurement cycles, certification timelines, and interoperability mandates across NATO and allied fleets.
Weapon Type:
Domestic procurement concentrates in gun and missile systems for NATO member states, while laser and drone platforms drive export-led demand from Indo-Pacific coastal defense programs.
- Missile Systems:Long-range standoff engagement capability integrates thermal imaging with gyroscopic stabilization for severe sea states. Procurement concentrates in Vietnam, Philippines, and Indonesia for fast-attack craft modernization against littoral threats.
- Gun Systems:Stabilized naval mounts chambering medium-caliber ammunition deliver precision fire against small boat swarms. NATO STANAG 4695 harmonization reduces integration costs for cross-border fleet standardization among allied navies.
- Laser Systems:Solid-state directed-energy platforms achieve tactical power thresholds for counter-UAS defense on destroyer classes.
- Drone Systems:Weaponized unmanned aerial platforms extend sensor-to-shooter networks for perimeter security missions.
Missile systems command the established base. The steepest expansion runs through laser systems.
Platform:
Cost tier stratification separates capital-intensive naval vessel retrofits from lower-entry unmanned surface vessel programs attracting mid-tier defense budgets.
- Unmanned Surface Vessels:Optionally crewed mine countermeasures craft require compact stabilized mounts with reduced manning footprints. Nordic and Baltic fleet procurement prioritizes vendors with pre-certified algorithmic transparency documentation under EU AI Act mandates.
- Naval Vessels:Major combatant integration demands MIL-STD-901D heavy weight shock testing and MIL-STD-461G electromagnetic compliance. U.S. Navy distributed maritime operations doctrine compresses development cycles for gallium nitride radar component insertion.
- Submarines:Periscope-mounted remote weapon stations enable covert surface engagement without hull penetration.
- Coastal Defense:Fixed and mobile shore batteries deploy stabilized turrets for harbor protection and chokepoint denial.
Naval vessels anchor current procurement value. Unmanned surface vessels are climbing the fastest as greenfield platform categories attract fresh investment.
Technology:
Application maturity separates field-proven electro-optical and radar systems from emerging robotics and artificial intelligence architectures facing regulatory compliance burdens.
- Artificial Intelligence:Algorithmic target classification and engagement authorization face 18-24 month development timeline extensions under EU AI Act high-risk system classification. R&D investment diverts toward explainable AI architectures satisfying human-in-the-loop mandates.
- Electro-Optical:Thermal imaging and laser rangefinder integration enables accurate engagement in degraded visibility conditions. Royal Navy Type 26 frigate and Canadian Surface Combatant programs unbundle sensor suites from weapon mounts for upgrade-only contract participation.
- Radar:Gallium nitride monolithic microwave integrated circuits miniaturize front-end components while doubling power efficiency for patrol vessel displacement classes.
- Robotics:Autonomous turret traverse and ammunition handling reduce crew exposure in contested environments.
Electro-optical systems retain the installed base. Artificial intelligence is gaining share fastest as sensor fusion architectures reshape competitive positioning.
End User:
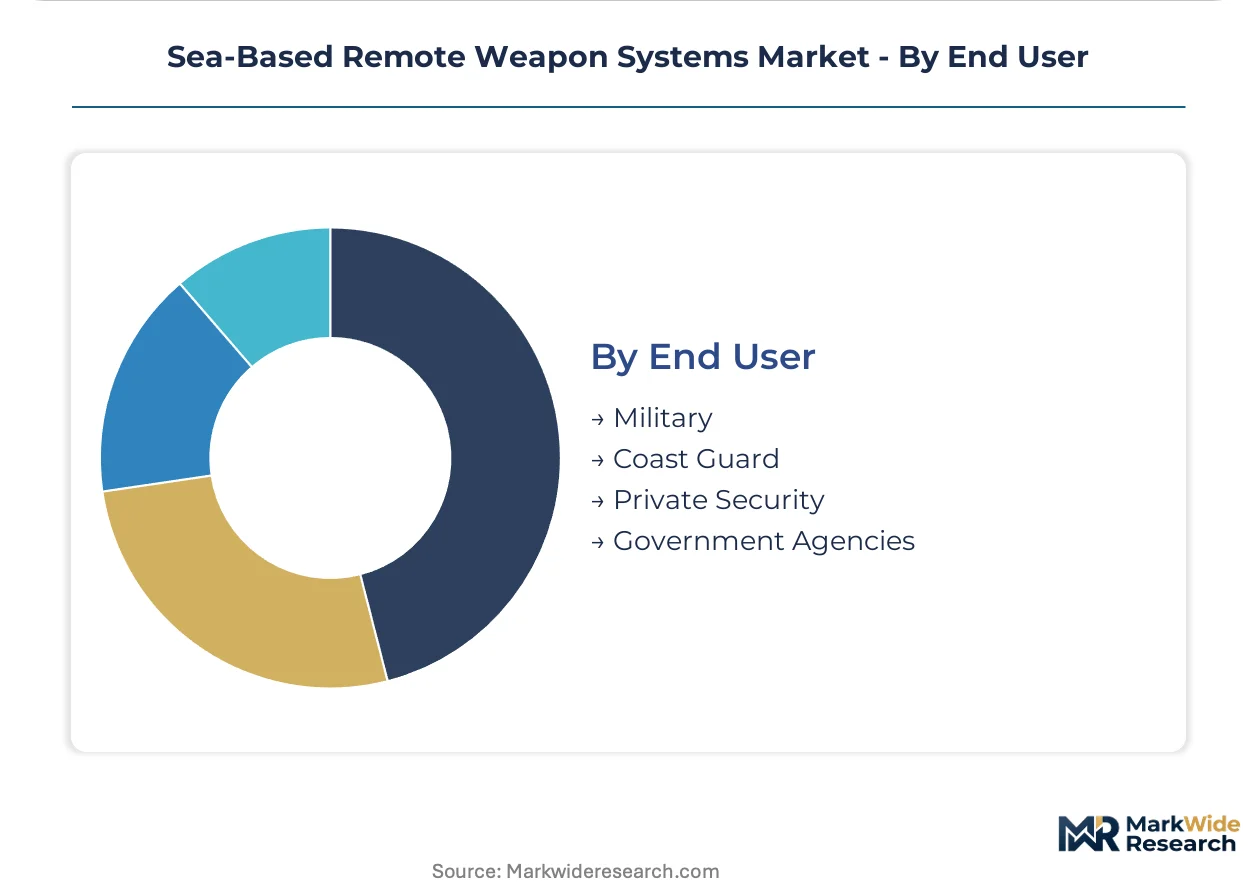
Customer type determines specification authority and contract structure, with military procurement consolidating requirements while coast guard and security services pursue modular upgrade paths.
- Military:Naval Sea Systems Command imposes shock qualification and electromagnetic interference standards that filter vendor eligibility for domestic U.S. programs. Aegis Baseline 9 integration presents protocol translation complexity for modern Ethernet-based remote weapon stations.
- Coast Guard:Littoral combat commands rotate procurement priority toward unmanned platforms with integrated remote firing capability. Through-life support contracts now exceed initial hardware value in Nordic retrofit programs.
- Government Agencies:Border enforcement and maritime patrol services demand interoperable systems for multi-agency coordination.
- Private Security:Commercial vessel protection programs drive demand for compact, exportable remote weapon stations with simplified training requirements.
Military end users dominate contract value. Coast guard services are expanding most quickly as coastal defense modernization accelerates across Southeast Asian littoral zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Navy's Pacific Fleet headquarters at Pearl Harbor anchors Indo-Pacific procurement coordination for distributed maritime operations. NATO naval integration centers on North Sea and Baltic Sea littoral zones where STANAG harmonization drives cross-border fleet standardization.
United States
Naval Sea Systems Command procurement concentrates at Norfolk Naval Station and San Diego Naval Base for shock-qualified remote weapon station integration. MIL-STD-901D heavy weight shock testing requirements filter vendor eligibility through dedicated barge facilities at Naval Surface Warfare Center Carderock. The Pacific Northwest hosts gallium nitride radar component development clusters supporting compact platform insertion.
Norway
Kongsberg Defence & Aerospace anchors Nordic fleet retrofit programs through Protector naval remote weapon station lineage. The country's national defense procurement agency coordinates STANAG 4695 compliance certification for allied cross-border integration. Oslo defense technology corridor concentrates electro-optical and fire-control subsystem development for fast-attack craft applications.
United Kingdom
Royal Navy Type 26 frigate programs drive through-life support contract structures exceeding initial hardware value. The Ministry of Defence's Defence Equipment and Support organization mandates human-in-the-loop algorithmic transparency for autonomous engagement systems. Glasgow shipbuilding cluster hosts stabilized turret integration facilities for patrol vessel displacement classes.
Israel
Rafael Advanced Defense Systems and Elbit Systems anchor directed-energy platform maturation for counter-UAS defense applications. The country's national defense export regulator oversees Wassenaar Arrangement compliance for autonomous targeting algorithm markets. Haifa defense technology corridor concentrates electro-optical and fire-control subsystem vertical integration.
Australia
Royal Australian Navy Hunter-class frigate procurement prioritizes Aegis combat system integration for Ethernet-based remote weapon station architectures. The Department of Defence's Capability Acquisition and Sustainment Group manages shock qualification timelines against operational urgency trade-offs. Adelaide shipbuilding cluster hosts gallium nitride radar component testing for Indo-Pacific littoral contested zone requirements.
Sea-Based Remote Weapon Systems Market Competitive Landscape
Concentration sits with tier-1 system integrators unbundling sensor suites from weapon mounts to capture upgrade-only contracts. The vendor base stratifies across full-stack platform providers, specialized sensor subsystem houses, and regional combat system integrators. Two dominant competitive moves define current positioning: technology licensing partnerships for gallium nitride radar component access, and geographic expansion through NATO STANAG certification pre-qualification.
Within the full-stack platform tier, Kongsberg Defence & Aerospace, Saab AB, and Elbit Systems exemplify divergent specialization vectors. Kongsberg occupies a position anchored in Nordic fleet heritage and Protector lineage standardization. Saab exemplifies compact stabilized turret optimization for fast-attack craft displacement classes below 500 tons. Elbit represents vertical integration across electro-optical and fire-control subsystems for algorithmic transparency compliance under EU AI Act mandates.
| Leading Market Players |
|---|
| Raytheon Company |
| Saab AB |
| Kongsberg Defence & Aerospace |
| Rafael Advanced Defense Systems |
| Rheinmetall AG |
| Leonardo S.p.A. |
| General Dynamics Corporation |
| ASELSAN A.S |
| Elbit Systems |
| Others |
Value Network & Pricing Analysis
Defense-grade gallium nitride wafer fabrication concentrates among three qualified foundries, creating scale economies that anchor price floors for radar subsystem integration while filtering mid-tier vendors from NATO procurement pools. This concentration compresses margin structures for European suppliers facing EU AI Act compliance timelines, forcing algorithmic transparency investments that cascade through contract pricing.
Pricing Analysis
Volume-discount tiering structures separate full-stack platform providers from sensor-subsystem specialists, with NATO STANAG certification status commanding premium positioning against uncertified competitors. Price differentiation rests on shock qualification pedigree and electromagnetic interference certification grade, with MIL-STD-901D heavy weight shock testing creating entry barriers that protect incumbent pricing. Cost compression in the mid-tier intensifies as tier-1 integrators unbundle sensor suites to capture upgrade-only contracts. Coast guard services exhibit highest price sensitivity due to modular procurement mandates, while major naval combatant programs demonstrate lowest sensitivity given through-life support contract structures.
Supply Chain Analysis
Inventory lead times for gallium nitride monolithic microwave integrated circuits extend 18-24 months due to defense-grade epitaxy bottlenecks, constraining rapid platform deployment. Supply concentrates in the United States, Japan, and Germany for qualified GaN-on-SiC substrate production, with radar front-end assembly drawing from Israeli and South Korean electro-optical specialists. Single-source vulnerability pervades directed-energy platform power conditioning subsystems. Distribution runs through prime contractor integration facilities at major naval shipyards, with tier-2 subsystem houses feeding via long-term development agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among NATO naval procurement agencies, compressing vendor negotiation leverage as specification-setting authority centralizes within tier-1 fleet modernization programs.
For Market Incumbents: Compound algorithmic transparency advantages by pre-certifying explainable AI architectures under EU AI Act mandates before competitors complete conformity assessments. Defend shock qualification moats through exclusive barge facility access at Naval Surface Warfare Center Carderock, while accelerating gallium nitride radar component insertion via technology licensing partnerships that lock out emerging entrants from foundry allocation.
For New Entrants and Emerging Players: NATO STANAG 4695 certification fast-tracks offer the most penetrable entry pathway for unmanned surface vessel weaponization programs, where greenfield platform categories lack incumbent legacy integration burdens. Target Southeast Asian coastal defense modernization in Vietnam, Philippines, and Indonesia for fast-attack craft retrofit demand. Pursue sensor-subsystem unbundling strategies that bypass full-stack qualification requirements.
For Investors and Strategic Acquirers: Electro-optical fire-control specialists with pre-integrated AI targeting pipelines represent the priority acquisition archetype, as sensor fusion architectures reshape competitive positioning. Long-term viability hinges on regulatory compliance velocity rather than raw technical performance, with EU AI Act certification timelines serving as the critical inflection signal for European supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Transparency Certification | EU AI Act pre-certification accelerates procurement eligibility for Nordic and Baltic fleet programs. |
| Gallium Nitride Technology Licensing | Foundry access agreements compress radar subsystem development cycles for compact platform insertion. |
| Shock Qualification Facility Investment | MIL-STD-901D barge access filters competitors from U.S. Navy distributed maritime operations programs. |
| Sensor Suite Unbundling | Component-level contracting captures upgrade-only revenue in Royal Navy Type 26 frigate programs. |
| Indo-Pacific Distribution Partnership | Local integration presence in Vietnam and Philippines accelerates fast-attack craft retrofit timelines. |
Research Methodology
Initial hypotheses were tested against primary input from naval program executives, shipyard integration engineers, defense procurement officers, and subsystem R&D directors, then refined through secondary validation against NATO STANAG documentation, U.S. Naval Sea Systems Command specification releases, EU AI Act regulatory filings, and customs trade data for gallium nitride component flows. Bottom-up platform deployment forecasts triangulated against top-down fleet modernization budget allocations across NATO member states and Indo-Pacific coastal defense programs.
Variance decomposition across weapon type, platform configuration, technology maturity, and end-user procurement authority shaped the analytical framework throughout the projection horizon. CAGRs derived from segment-level unit economics and replacement cycle dynamics, with gallium nitride radar adoption curves and autonomous engagement algorithm regulatory clearance timelines serving as critical forecast inputs.
Underlying assumptions cover NATO fleet modernization continuity, gallium nitride foundry capacity expansion, and EU AI Act enforcement consistency, with deviation risk concentrated in Wassenaar Arrangement control list revisions and Indo-Pacific regional security environment shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Submarine Combat System Market
Naval Warfare
Marine Penetrators Market
Naval Warfare
Bow and Stern Thrusters Market
Naval Warfare
Fast Attack Craft (FAC) Market
Naval Warfare
Amphibious Landing Craft Market
Naval Warfare
Combat Management System Market
Naval Warfare
Sea Based C4ISR Market
Naval Warfare
Naval Combat Weapons Market
Naval Warfare
Aircraft Carrier Ship Market
Naval Warfare
Coastal Patrol Military Vessels Market
Naval Warfare
Global Naval Vessel MRO Market
Naval Warfare
Asia-Pacific Naval Vessels Market
Naval Warfare
Global Naval Ship Propeller Market
Naval Warfare
Naval Artillery System Market
Naval Warfare
Naval Vessel Defense Systems Market
Naval Warfare
Naval Radar Market