
 Airplane Brackets Market | 2026-2036
Airplane Brackets Market Size, Share, and Industry Trends Forecast 2026-2036
Airplane Brackets Market Insights
China is reconfiguring aerospace supplier geography through expanded titanium machining capacity and state-backed composite fabrication parks. Precision Castparts Corp leverages captive titanium melt capabilities to anchor premium engine mount bracket supply. Triumph Group competes across multiple product lines while sustaining broad qualification portfolios with Airbus and Boeing.
Airplane brackets are structural fasteners engineered to transfer loads between airframe components, typically machined from aluminum or titanium alloys to tolerances within thousandths of an inch and often finished with cadmium or zinc-nickel plating for corrosion resistance. Their primary purpose is to secure control surfaces, engine assemblies, and interior monuments while minimizing parasitic weight. Wing brackets and engine mount brackets concentrate margin pools due to fatigue-critical specifications and sole-source qualification requirements, while composite material brackets represent the fastest-growing segment as airframers pursue fuel burn reductions. Aluminum alloy brackets remain the volume baseline for narrowbody programs where cost sensitivity dominates material selection.
FAA Part 25 airworthiness standards, EASA CS-25 certification requirements, and ISO 9001/AS9100 quality frameworks govern bracket design validation, traceability, and production conformity across all supply tiers. These regulations shape demand by mandating material certifications, destructive test protocols, and digital thread documentation that elevate supplier entry barriers. Stakeholders must monitor how sustainable aviation fuel mandates and corresponding airframe efficiency targets redirect material specifications toward thermoplastic composites and hybrid titanium structures.
Market Dynamics
Commercial aviation OEMs are compressing bracket procurement cycles while simultaneously tightening material specifications, forcing suppliers to absorb certification costs upfront without guaranteed volume commitments.
Growth Catalysts
- FAA Part 25 fatigue testing mandates:Airframers must replace legacy aluminum brackets on aging narrowbody fleets, creating replacement demand across Boeing 737 and Airbus A320 programs.
- Titanium alloy adoption:Next-generation engine mounts require Ti-6Al-4V for temperature resistance, pulling machining capacity toward aerospace from medical and industrial applications.
- China's composite fabrication parks:State-backed industrial zones in Xi'an and Chengdu are qualifying thermoplastic bracket suppliers for COMAC C919 second-source contracts.
Market Restraints
- Titanium sponge price volatility:Russian and Ukrainian feedstock disruptions have compressed smelter margins, passing cost uncertainty to bracket fabricators locked into long-term OEM pricing.
- Sole-source qualification inertia:Boeing and Airbus design control agreements prevent second-source bracket approval without 18-24 month requalification cycles, freezing supplier rosters.
- Additive manufacturing substitution ceiling:Powder bed fusion cannot yet achieve the fatigue life of wrought titanium for primary structure brackets, limiting geometric freedom gains.
Strategic Opportunities
- India MRO expansion:IndiGo and Air India's fleet growth is creating demand for PMA-certified replacement brackets outside OEM channels, opening aftermarket revenue streams.
- Sustainable aviation fuel alignment:EASA's CO2 reduction targets are accelerating thermoplastic composite bracket trials on wing trailing edge assemblies to shave parasitic weight.
- Digital thread integration:AS9100D's enhanced traceability requirements favor suppliers with model-based definition capabilities, creating a capability moat against legacy machine shops.
Industry Challenges
- Destructive testing bottleneck:Each bracket lot requires statistically valid sample sacrifice, consuming 3-5% of production volume and compressing effective yields.
- Cadmium plating phase-out compliance:REACH Annex XVII restrictions on hexavalent chromium and cadmium force zinc-nickel process conversion without performance degradation, requiring capital retooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airplane Brackets Market |
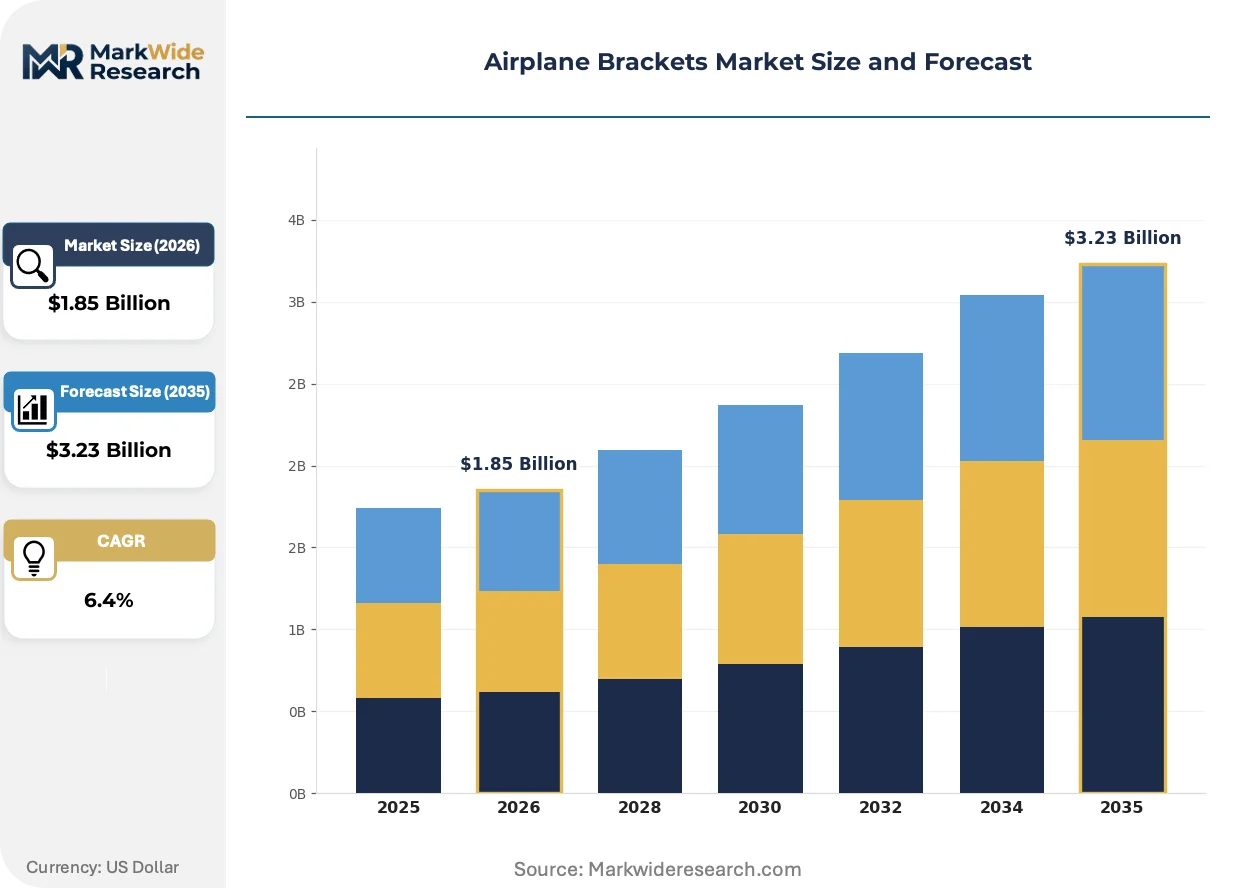
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wing Brackets, Fuselage Supports, Engine Mount Brackets, Landing Gear Brackets, Cabin Fixtures Material: Aluminum Alloy, Titanium Alloy, Stainless Steel, Composite Materials, Carbon Fiber Application: Commercial Aircraft, Military Jets, Cargo Planes, Private Jets, Rotorcraft End User: OEM Manufacturers, Tier-1 Suppliers, Maintenance Repair Organizations, Aircraft Retrofitters |
| Companies Covered | Precision Castparts Corp, Stroco Manufacturing, Triumph Group, Tri-Mack Plastics Manufacturing, Denroy Plastics, Arconic, Spirit Aerosystems, AIM Aerospace, Premium AEROTEC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airplane Brackets Market Trends and Innovations
Bracket manufacturing is bifurcating between legacy machined metal volumes and additive-enabled geometric optimization, with regulatory documentation standards tightening simultaneously across both paths.
Topology optimization software paired with selective laser melting is virtualizing bracket design iteration, allowing airframers to validate load paths digitally before committing to hard tooling. Airbus Defense and Space programs have adopted this workflow for satellite bracket development, compressing prototype cycles from months to weeks. The technology is virtualizing traditional forge-and-machine supply chains by collapsing the tooling lead time barrier that once protected incumbent fabricators.
REACH Annex XVII restrictions on cadmium and hexavalent chromium are forcing plating chemistry transitions across European supply chains, with zinc-nickel and ion vapor deposited aluminum emerging as qualified alternatives. Surface treatment houses in Germany and France are absorbing the capital burden of line conversion while awaiting OEM specification revisions. Wing and empennage bracket categories face the steepest compliance timelines due to exposure to de-icing fluid corrosion.
Airline procurement departments are consolidating bracket buys through airframe OEM direct ship programs, bypassing traditional tier-two distributors. Lufthansa Technik and Delta TechOps have both shifted toward OEM-managed inventory for rotable brackets, transferring carrying cost to suppliers. North American MRO hubs in Oklahoma City and Atlanta are the most visible testing grounds for this consolidation, with regional carriers following network carrier precedent within 18-24 month lag patterns.
Airplane Brackets Market Segmentation
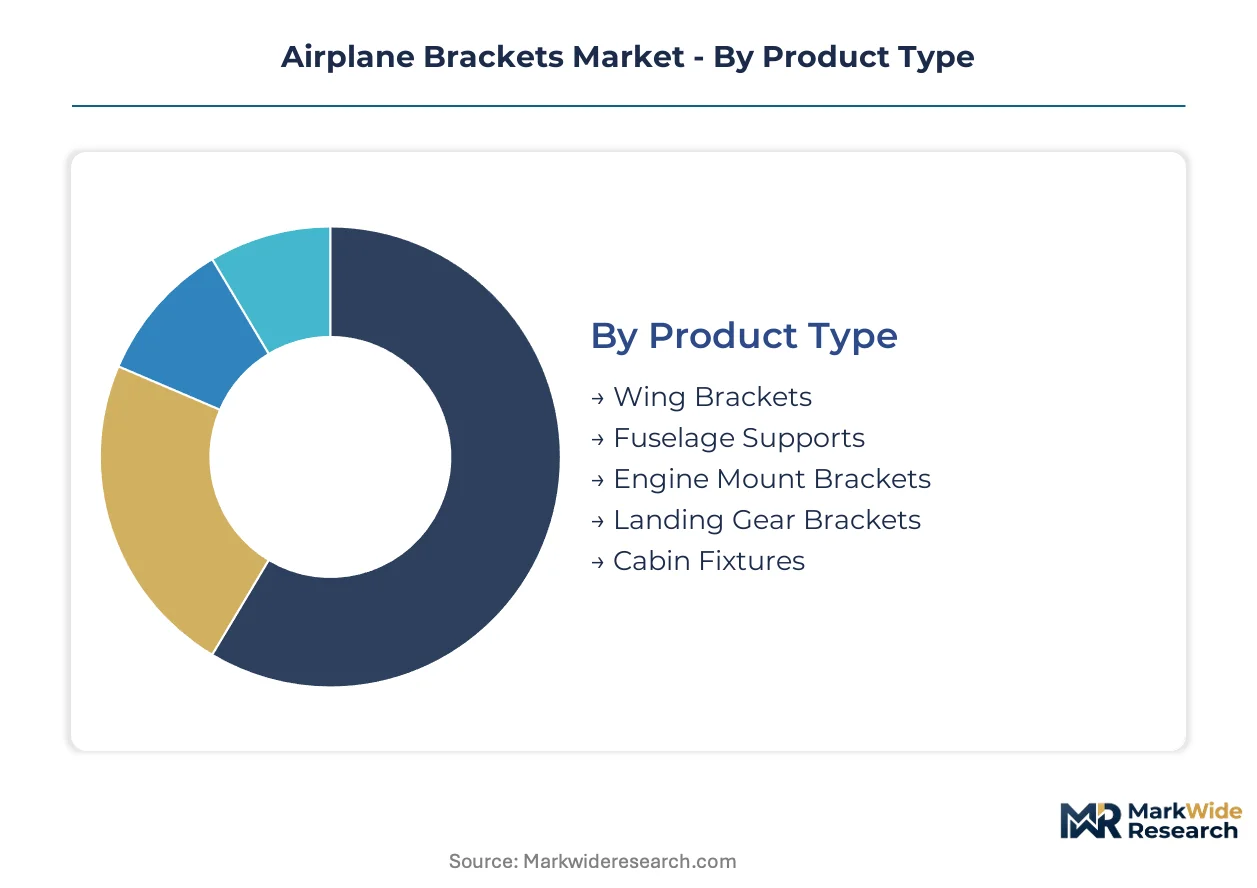
Bracket segmentation reveals divergent service intensity patterns across product lines. Wing and engine mount brackets demand intensive field monitoring due to fatigue-critical specifications, while cabin fixtures operate on scheduled replacement cycles with lower technical oversight.
Product Type:
After-sales service intensity varies dramatically across bracket categories, with primary structure components requiring continuous airworthiness monitoring versus interior hardware on predictable refurbishment timelines.
- Wing Brackets:These flight-critical fasteners transfer aerodynamic loads between wing skin and spar assemblies, typically machined from Ti-6Al-4V or 7075-T6 aluminum to sub-thousandth tolerances. Boeing 737 MAX and Airbus A320neo production lines in Washington state and Hamburg concentrate procurement, with fatigue test mandates from FAA Part 25 driving replacement schedules on aging fleets.
- Engine Mount Brackets:Temperature-resistant titanium forgings secure powerplants to wing or fuselage hardpoints, enduring vibration cycles exceeding 10^7 over service life. Precision Castparts Corp anchors supply through captive titanium melt capacity, while COMAC C919 qualification trials in Xi'an pull second-source capacity development.
- Fuselage Supports:Longitudinal and circumferential frame connectors distribute cabin pressurization loads across aluminum alloy substrates.
- Landing Gear Brackets:High-stress forgings attach strut assemblies to wing carry-through structure, subject to hard landing inspection protocols.
- Cabin Fixtures:Overhead bin, galley, and seat track brackets prioritize weight reduction over structural redundancy, enabling polymer composite substitution.
By volume, cabin fixtures lead due to per-aircraft multiplicity. By growth pace, engine mount brackets are ahead on next-generation engine adoption.
Material:
Material selection stratifies across cost-performance tradeoffs, with procurement patterns reflecting airframe OEM design control agreements and long-term alloy qualification timelines.
- Aluminum Alloy:7075-T6 and 2024-T3 remain the narrowbody baseline, offering mature machining infrastructure and established supply chains. Airbus A320 family production in Toulouse and Hamburg anchors European demand, while Boeing's Renton facility drives North American volume, with REACH Annex XVII cadmium restrictions forcing zinc-nickel plating conversions.
- Titanium Alloy:Ti-6Al-4V dominates engine-adjacent applications requiring specific strength above 250°C, with Russian and Ukrainian sponge disruptions compressing smelter margins. Xi'an and Chengdu composite fabrication parks are qualifying thermoplastic alternatives, though wrought titanium retains fatigue life advantages for primary structures.
- Stainless Steel:17-4PH and 15-5PH serve corrosive environments including lavatory and galley installations where nickel content justifies cost premium.
- Composite Materials:Thermoplastic brackets from PEEK and PEI resin systems enable 30-40% weight reduction on non-structural applications.
- Carbon Fiber:Continuous fiber reinforced brackets target satellite and unmanned platforms where electromagnetic transparency matters.
Aluminum alloy brackets dominate unit shipments. Composite materials are climbing the fastest on sustainable aviation fuel alignment.
Application:
Application segmentation tracks divergent certification burdens, with civil transport facing sustained airworthiness oversight versus military programs prioritizing mission-specific ruggedization.
- Commercial Aircraft:Narrowbody and widebody programs generate bracket demand through both OEM production and aftermarket replacement, with FAA and EASA Part 25 fatigue mandates creating predictable renewal cycles. Boeing's 737 and 787 lines in Everett and Charleston, plus Airbus A350 final assembly in Toulouse, concentrate procurement.
- Military Jets:Fighter and trainer platforms prioritize damage tolerance and battle damage repairability over weight optimization, with longer qualification cycles but higher per-unit bracket counts.
- Cargo Planes:Freighter conversions and purpose-built cargo aircraft demand reinforced floor and sidewall brackets for payload density extremes.
- Private Jets:Business aviation brackets emphasize cabin customization flexibility and reduced lead times over production scale.
- Rotorcraft:Helicopter brackets endure unique vibration spectra and autorotation load cases, requiring specialized fatigue test protocols.
Commercial aircraft generate the largest absolute demand. Rotorcraft brackets are gaining share fastest on urban air mobility platform development.
End User:
End user structure reflects supply chain tier compression, with OEMs consolidating direct procurement while MRO channels fragment across PMA-certified and OEM-original replacement strategies.
- OEM Manufacturers:Boeing and Airbus design control agreements lock bracket specifications through sole-source qualifications, with 18-24 month requalification cycles freezing supplier rosters. Direct ship programs now bypass traditional tier-two distributors, transferring inventory carrying costs to fabricators.
- Tier-1 Suppliers:Spirit AeroSystems and GKN Aerospace integrate bracket subassemblies into larger structural shipsets, absorbing certification documentation burdens under AS9100D traceability mandates.
- Maintenance Repair Organizations:Lufthansa Technik and Delta TechOps are shifting toward OEM-managed inventory for rotable brackets, consolidating procurement leverage.
- Aircraft Retrofitters:Passenger-to-freighter conversion specialists demand bracket kits for structural reinforcement and cargo door cutout support.
OEM manufacturers command the highest per-bracket pricing power. MRO channels are expanding most quickly on India fleet growth and PMA certification acceptance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bracket procurement clusters around final assembly sites where Boeing and Airbus operate, with supplier qualification requirements locking fabrication capacity to specific airframe programs. Raw material access and machining infrastructure further reinforce geographic concentration.
United States
Boeing's 737 MAX and 787 lines in Renton and Everett anchor North American demand, with FAA Part 25 fatigue mandates driving replacement schedules on aging narrowbody fleets. The FAA's airworthiness directives enforce material certification standards that elevate supplier entry barriers. Wichita's precision machining corridor concentrates tier-two bracket fabricators serving Spirit AeroSystems and other major subcontractors.
China
COMAC's C919 production ramp and state-backed composite fabrication parks in Xi'an and Chengdu are reconfiguring aerospace supplier geography. MIIT industrial policies channel investment toward titanium machining capacity and thermoplastic qualification programs. The Yangtze River Delta cluster around Shanghai houses emerging bracket suppliers targeting second-source contracts for domestic airframe programs.
Germany
Airbus A320 family production in Hamburg and A350 final assembly in Toulouse (with German supply chain integration) anchor European procurement volumes. REACH Annex XVII restrictions on cadmium and hexavalent chromium force plating chemistry transitions across surface treatment houses. Bavaria's aerospace supplier corridor absorbs capital burdens of zinc-nickel process conversion while awaiting OEM specification revisions.
France
Airbus headquarters and A350 production in Toulouse concentrate design control agreements that freeze bracket specifications through sole-source qualifications. EASA CS-25 certification requirements mandate destructive test protocols and digital thread documentation. The Occitanie region's aerostructure ecosystem hosts tier-one integrators managing bracket subassemblies under AS9100D traceability mandates.
India
IndiGo and Air India's fleet expansion creates aftermarket demand for PMA-certified replacement brackets outside OEM channels. DGFT export promotion schemes support aerospace component manufacturing under the PLI scheme. Bangalore's precision engineering corridor and Hyderabad's defense-aerospace cluster are developing bracket fabrication capabilities for both civil and military applications.
Airplane Brackets Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on narrower product lines. The vendor base stratifies between tier-one structural shipset providers with broad qualification portfolios and precision machining houses locked to single-source contracts. Three archetypes dominate: captive titanium melt-to-part integrators, multi-product aerospace fabricators, and polymer composite specialists. Competitive moves center on capacity expansion into thermoplastic bracket production and backward integration into raw material processing.
Among North American fabricators, Precision Castparts Corp exemplifies the captive-materials archetype through vertical control of titanium supply chains. Triumph Group occupies a diversified position across multiple bracket product lines while sustaining broad OEM qualification portfolios. Tri-Mack Plastics Manufacturing represents the polymer composite specialization vector, with thermoplastic capabilities aligned to sustainable aviation fuel weight reduction targets. These three anchors illustrate how supplier positioning stratifies around material control, product breadth, and technology specialization.
| Leading Market Players |
|---|
| Precision Castparts Corp |
| Stroco Manufacturing |
| Triumph Group |
| Tri-Mack Plastics Manufacturing |
| Denroy Plastics |
| Arconic |
| Spirit Aerosystems |
| AIM Aerospace |
| Premium AEROTEC |
| Others |
Pricing and Supply Chain Analysis
Wichita's precision machining corridor concentrates titanium and aluminum bracket fabrication capacity, translating geographic supplier density into asymmetric pricing power for tier-one structural shipset providers. OEM design control agreements lock sole-source qualifications, compressing margin negotiation leverage for tier-two fabricators while captive melt-to-part integrators extract premium pricing on fatigue-critical engine mount brackets.
Pricing Analysis
FAA Part 25 and EASA CS-25 certification requirements dictate the pricing tier structure across airplane bracket categories, separating fatigue-critical primary structure components from non-structural cabin hardware. Three-tier pricing structure across premium, standard, and economy levels reflects qualification depth, with sole-source titanium engine mount brackets commanding substantial premiums over aluminum narrowbody hardware. Cost compression in standard-tier aluminum brackets is intensifying because REACH Annex XVII plating conversions force capital retooling without corresponding specification relief. Narrowbody program procurement teams exhibit highest price sensitivity, while engine OEMs demonstrate lowest sensitivity on temperature-resistant titanium forgings.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for bracket fabricators serving dual-source qualification requirements. Production gravity centers on the United States, China, and Germany, with raw material supply drawing from Russian and Ukrainian titanium sponge channels and domestic aluminum smelter networks. Component dependencies rest on precision forging capacity, CNC machining infrastructure, and surface treatment houses qualified to OEM specifications. Single-source vulnerability permeates the tier-one integrator tier where Spirit AeroSystems and GKN Aerospace control bracket subassembly flows. Distribution runs through direct ship programs that bypass traditional tier-two distributors, transferring inventory carrying costs to fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Additive manufacturing substitution threatens wrought titanium bracket incumbents as powder bed fusion fatigue performance gaps narrow, forcing established suppliers to defend process moats through accelerated digital thread integration.
For Market Incumbents: Pre-empt selective laser melting encroachment by embedding model-based definition capabilities across AS9100D traceability workflows, collapsing prototype iteration cycles that once protected forge-and-machine supply chains. Secure captive titanium melt capacity or long-term sponge offtake agreements to buffer Russian and Ukrainian feedstock disruption risks. Deepen backward integration into thermoplastic composite bracket production before EASA CO2 reduction targets accelerate material substitution timelines. For New Entrants and Emerging Players: India's MRO expansion presents the most penetrable aftermarket channel, where IndiGo and Air India fleet growth outpaces PMA-certified replacement bracket supply. Target PMA qualification pathways for Boeing 737 and Airbus A320 legacy fleet hardware, bypassing 18-24 month OEM requalification inertia that freezes incumbent rosters. Lead with zinc-nickel plating capabilities that anticipate REACH Annex XVII cadmium phase-out compliance, converting European surface treatment house capital burdens into first-mover specification advantages. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision machining houses with broad OEM qualification portfolios and latent thermoplastic composite capacity. Long-term viability hinges on bracket suppliers' ability to bridge legacy metal volumes toward additive-enabled geometric optimization without sacrificing fatigue-critical performance. Acquisition target archetype: tier-two fabricators with AS9100D digital thread infrastructure and pending COMAC C919 second-source qualifications. Monitor Xi'an and Chengdu composite fabrication park qualification timelines as inflection indicators for thermoplastic bracket adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Thread Integration | AS9100D traceability mandates favor model-based definition capabilities against legacy machine shops. |
| Thermoplastic Capacity Expansion | EASA CO2 targets accelerate PEEK and PEI bracket trials on wing trailing edge assemblies. |
| PMA Certification Pathway | India MRO growth opens aftermarket revenue streams outside OEM direct ship channels. |
| Captive Titanium Supply | Vertical control of sponge-to-forge chains buffers Russian and Ukrainian feedstock disruptions. |
| Zinc-Nickel Process Conversion | REACH Annex XVII compliance creates specification moat against cadmium-plated incumbents. |
Research Methodology
Desk research of FAA airworthiness directives, EASA certification databases, and OEM supplier qualification records preceded structured interviews with tier-one procurement directors, precision machining plant managers, surface treatment house technical leads, and MRO aftermarket buyers. Primary fieldwork validated bracket demand patterns across Boeing 737 MAX, Airbus A320neo, and COMAC C919 production lines, with secondary triangulation against customs trade data, AS9100D audit disclosures, and REACH Annex XVII compliance filings. Bottom-up fabrication capacity assessments and top-down airframe production forecasts were reconciled through iterative stakeholder feedback loops.
Assumptions held fixed include FAA Part 25 fatigue test mandates, EASA CS-25 material certification timelines, and OEM design control agreement structures; variables included titanium sponge price volatility bands, thermoplastic qualification trial outcomes, and additive manufacturing fatigue performance improvement trajectories. The analytical framework modeled bracket demand across product type, material substrate, application segment, and end-user tier throughout the forecast period. CAGRs were derived from airframe delivery schedules, fleet age distributions, and replacement cycle frequencies specific to wing, engine mount, and cabin fixture categories.
Practitioners should monitor titanium sponge supply disruptions, REACH Annex XVII specification revision timing, and powder bed fusion fatigue test breakthroughs for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Military Trainer Aircraft Market
Aircraft
Europe Freighter Aircraft Market
Aircraft
Commercial Aircraft Manufacturing Market
Aircraft
Asia-Pacific Freighter Aircraft Market
Aircraft
Aircraft Door Market
Aircraft
Commercial Aerospace Market
Aircraft
Aircraft Galley Equipment Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
Glider Aircraft Market
Aircraft
Europe Aircraft Engines Market
Aircraft
Aircraft Galley Systems Market
Aircraft
Europe Business Jet Market
Aircraft
North America Business Jet Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Aircraft Hangar Market
Aircraft
Asia-Pacific Attack Helicopter Market