
 Artillery Ammunition Market | 2026-2036
Artillery Ammunition Market Size, Share, and Industry Trends Forecast 2026-2036
Artillery Ammunition Market Analysis
Direct military procurement channels across NATO Europe are reshaping how prime contractors allocate production capacity. Rheinmetall AG leverages its German manufacturing footprint to anchor supply commitments for 155mm artillery rounds across multiple allied nations. BAE Systems plc sustains long-term shell production through its British and American facilities, competing for national stockpile replenishment contracts. Nammo AS specializes in precision fuzing and propellant chemistry, differentiating its offerings in the Nordic and Baltic procurement corridors.
Artillery ammunition encompasses propellant-loaded projectiles, shells, and cartridges designed for tube-fired delivery against area or point targets, typically incorporating steel casings, high-explosive or dual-purpose payloads, and mechanical or electronic fuzes calibrated for impact, proximity, or time-delayed detonation. The 155mm caliber dominates current procurement volumes due to its compatibility with NATO-standard towed and self-propelled howitzer platforms. Projectile types incorporating electronic fuzes represent the fastest-expanding segment as militaries prioritize accuracy over saturation bombardment. Military end users control the largest margin pools through multi-year framework agreements that lock in capacity before spot-market allocation.
The US Department of Defense, NATO Standardization Office, and national defense procurement agencies in Germany and France regulate artillery ammunition through performance specifications, safety certification protocols, and cross-border transfer licensing frameworks that constrain which suppliers can bid on allied contracts. These bodies enforce interoperability standards for propellant charge systems and projectile dimensions, effectively filtering market access to pre-qualified manufacturers with certified quality systems. Stakeholders must monitor how shifting alliance burden-sharing agreements alter the geographic distribution of long-term supply commitments.
Market Dynamics
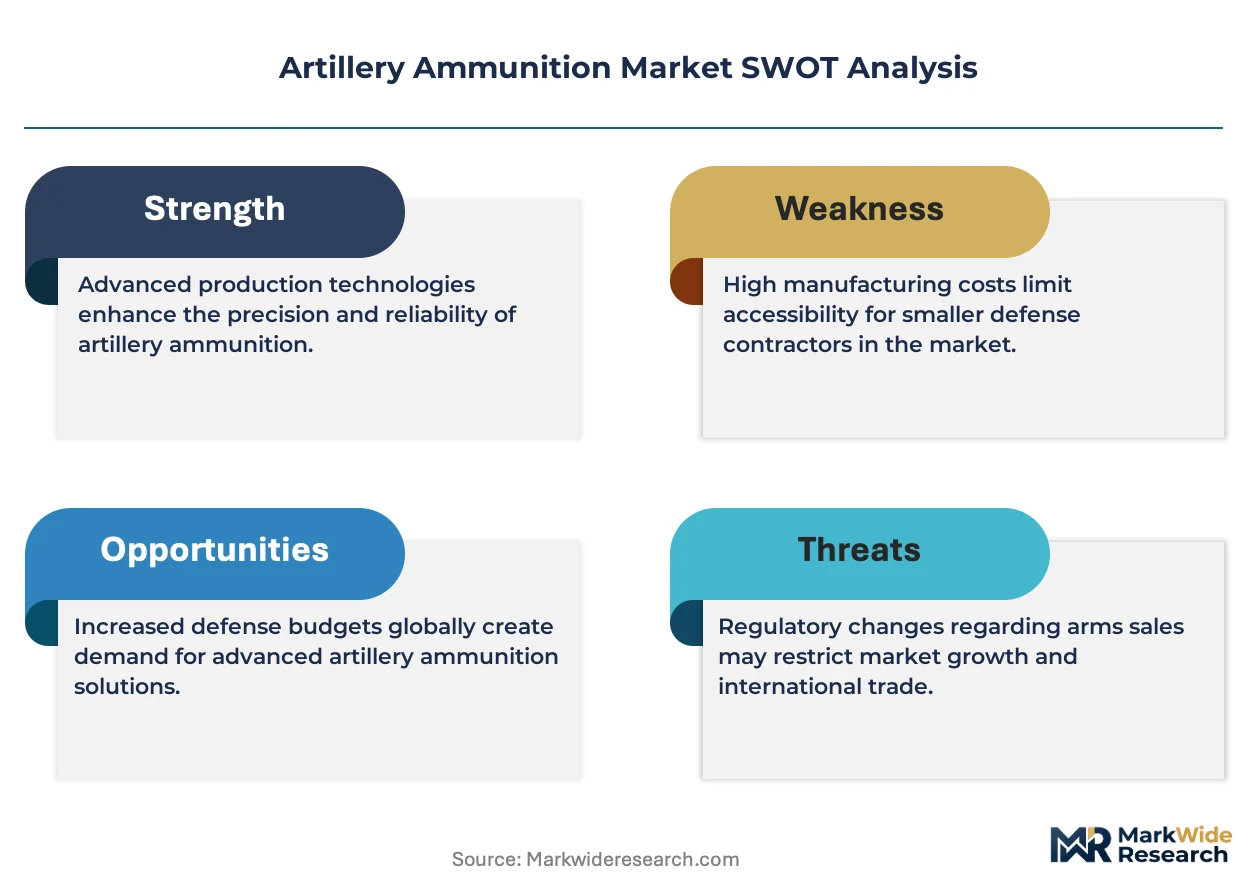
The artillery ammunition market is restructuring around precision-guided projectile demand as NATO allies replace stockpiles depleted by sustained operational tempo. This shift concentrates contract awards on manufacturers capable of certified 155mm production with electronic fuzing integration.
Growth Catalysts
- Precision Strike Missile Program:The US Department of Defense's procurement redirection under this framework is absorbing contractor capacity for guided munitions, creating spillover demand for complementary artillery systems.
- Strategic Reserve Replenishment:Poland, Germany, and the United Kingdom are executing multi-year framework agreements to rebuild depleted national stockpiles, locking in production slots before spot-market allocation.
- NATO Standardization Office Interoperability Mandates:Cross-border transfer licensing frameworks and unified propellant charge specifications are consolidating demand around certified suppliers with established quality systems.
Market Restraints
- Nitrocellulose Supply Concentration:Propellant chemistry feedstock availability is constrained by limited qualified suppliers in Eastern European manufacturing corridors, creating input cost volatility.
- Cross-Border Transfer Licensing:National defense procurement agencies in France and Germany enforce strict export control protocols that extend contract fulfillment timelines for allied nations outside immediate treaty structures.
- Tube Artillery Substitution:Loitering munitions and tactical unmanned aerial systems are displacing saturation bombardment missions in certain operational scenarios, compressing demand for unguided high-explosive shells.
Strategic Opportunities
- Baltic Procurement Corridors:Nordic and Baltic defense ministries are establishing dedicated ammunition acquisition frameworks with accelerated certification pathways for precision fuzing specialists.
- Modular Propellant Charge Systems:Convergence of insensitive munition formulations with adjustable ballistics modules enables platform-agnostic compatibility across towed and self-propelled howitzer fleets.
- US Inflation Reduction Act Defense Provisions:Domestic content incentives for critical munitions manufacturing are redirecting supply chain investment toward American production facilities with qualified workforce pipelines.
Industry Challenges
- Skilled Pyrotechnician Shortage:Qualified personnel for propellant blending and fuze assembly are concentrated at aging specialist facilities with limited training pipeline capacity.
- Insensitive Munition Certification Timelines:NATO STANAG 4439 compliance testing for reduced-sensitivity formulations extends product qualification cycles by 18-24 months.
- Legacy Platform Integration:Electronic fuze systems require fire control software modifications for towed howitzer fleets fielded prior to digital ballistic computer adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artillery Ammunition Market |
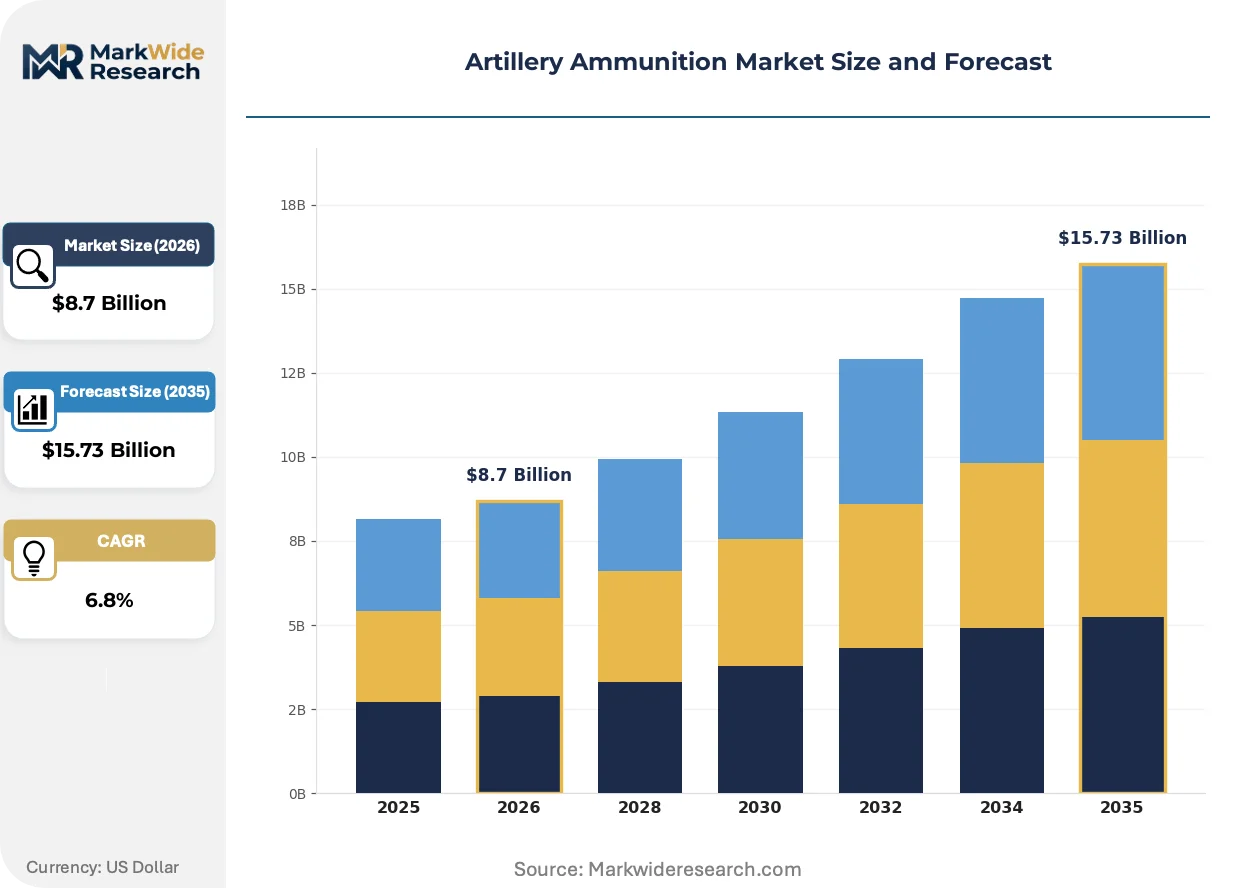
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Projectile, Shell, Missile, Cartridge Caliber: 105mm, 155mm, 203mm, 300mm Fuze Type: Impact, Proximity, Time, Electronic End User: Military, Defense Contractors, Governments, Others |
| Companies Covered | Rheinmetall AG, General Dynamics Corporation, BAE Systems plc, Nammo AS, Elbit Systems Ltd., Thales, Hanwha Aerospace, Nexter, General Dynamics Ordnance & Tactical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artillery Ammunition Market Emerging Trajectories
Artillery ammunition development is pivoting from area-effect saturation toward precision engagement capabilities, with electronic fuzing and guidance modules displacing mechanical impact systems as the primary value-creation layer.
Modular precision guidance kits are hybridizing conventional spin-stabilized projectiles with GPS-aided inertial navigation. Artillery brigades in Poland and Germany are fielding these retrofitted rounds at scale for counter-battery missions. The technology is compressing the circular error probable differential between tube artillery and precision strike missiles, enabling role consolidation within existing platform fleets.
The EU Green Deal defense industrial adaptation framework is imposing propellant chemistry disclosure requirements on contractors bidding for strategic stockpile contracts. Manufacturers must now document lifecycle emissions from nitrocellulose synthesis through demilitarization. German and French procurement agencies are prioritizing bidders with certified insensitive munition formulations that reduce accidental detonation risk during storage and transport.
Multi-year framework agreements are displacing annual spot-market purchases as the dominant contracting mechanism. Allied defense ministries are locking in five-to-seven-year production commitments with penalty clauses for capacity diversion. This pattern concentrates most visibly in the United Kingdom, where the Ministry of Defence is consolidating fragmented artillery ammunition budgets into single-source national stockpile replenishment programs with predetermined escalation terms.
Artillery Ammunition Market Segmentation
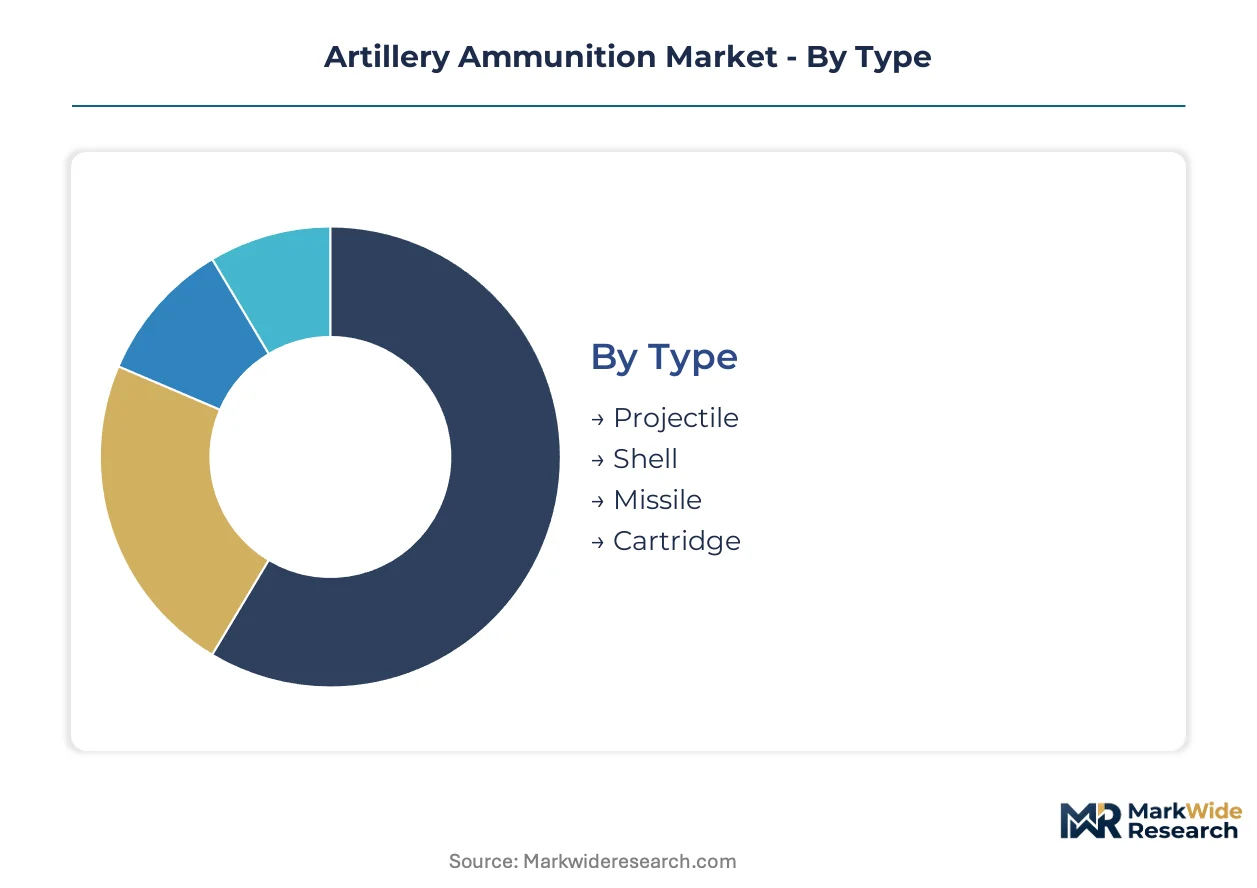
Artillery ammunition procurement patterns diverge sharply across technical specifications and institutional buyers. Caliber standardization and fuze sophistication determine contract eligibility for NATO framework agreements.
Type:
Application context determines which projectile architecture delivers optimal lethality against area or point targets.
- Projectile:Spin-stabilized steel bodies with high-explosive or dual-purpose payloads constitute the baseline inventory for saturation bombardment. Polish and German arsenals are prioritizing precision-guided variants for counter-battery missions.
- Shell:Integrated cartridge-case assemblies with pre-loaded propellant charges enable rapid loading cycles in self-propelled howitzer autoloaders. British Army procurement concentrates here for AS90 platform compatibility.
- Missile:Rocket-assisted projectiles extend range beyond conventional tube artillery envelopes.
- Cartridge:Complete round assemblies with matched propellant and projectile combinations streamline logistics.
Shell commands the established base. The steepest expansion runs through Projectile.
Caliber:
Platform fleet composition across allied militaries fixes procurement volumes to specific bore diameters.
- 155mm:NATO-standard dimensions enable cross-national supply pooling and unified logistics chains. German, Polish, and British procurement agencies are locking multi-year production commitments for this caliber under strategic reserve replenishment programs.
- 105mm:Lightweight towed howitzer compatibility sustains demand for rapid deployment artillery brigades. Mountain and airborne units in NATO's eastern flank maintain specialized stockpiles despite platform obsolescence pressures.
- 203mm:Heavy siege artillery applications persist in limited national inventories.
- 300mm:Rocket artillery systems operate outside traditional tube artillery classifications.
155mm dominates contract awards. The fastest volume gains concentrate in 105mm for expeditionary formations.
Fuze Type:
Detonation control sophistication separates commodity rounds from premium precision-guided inventory.
- Electronic:Programmable multi-mode fuzes with proximity, delay, and height-of-burst options enable single-round effects previously requiring saturation fires. Polish artillery brigades are fielding these at scale under accelerated Nordic-Baltic procurement corridors.
- Proximity:Radio-frequency sensing for airburst detonation against personnel and soft targets in open terrain.
- Time:Mechanical or pyrotechnic delay trains for airburst or penetration sequencing.
- Impact:Simple point-detonating mechanisms for direct surface contact.
Impact fuzes retain the legacy installed base. Electronic systems are climbing the fastest as precision requirements displace area bombardment doctrine.
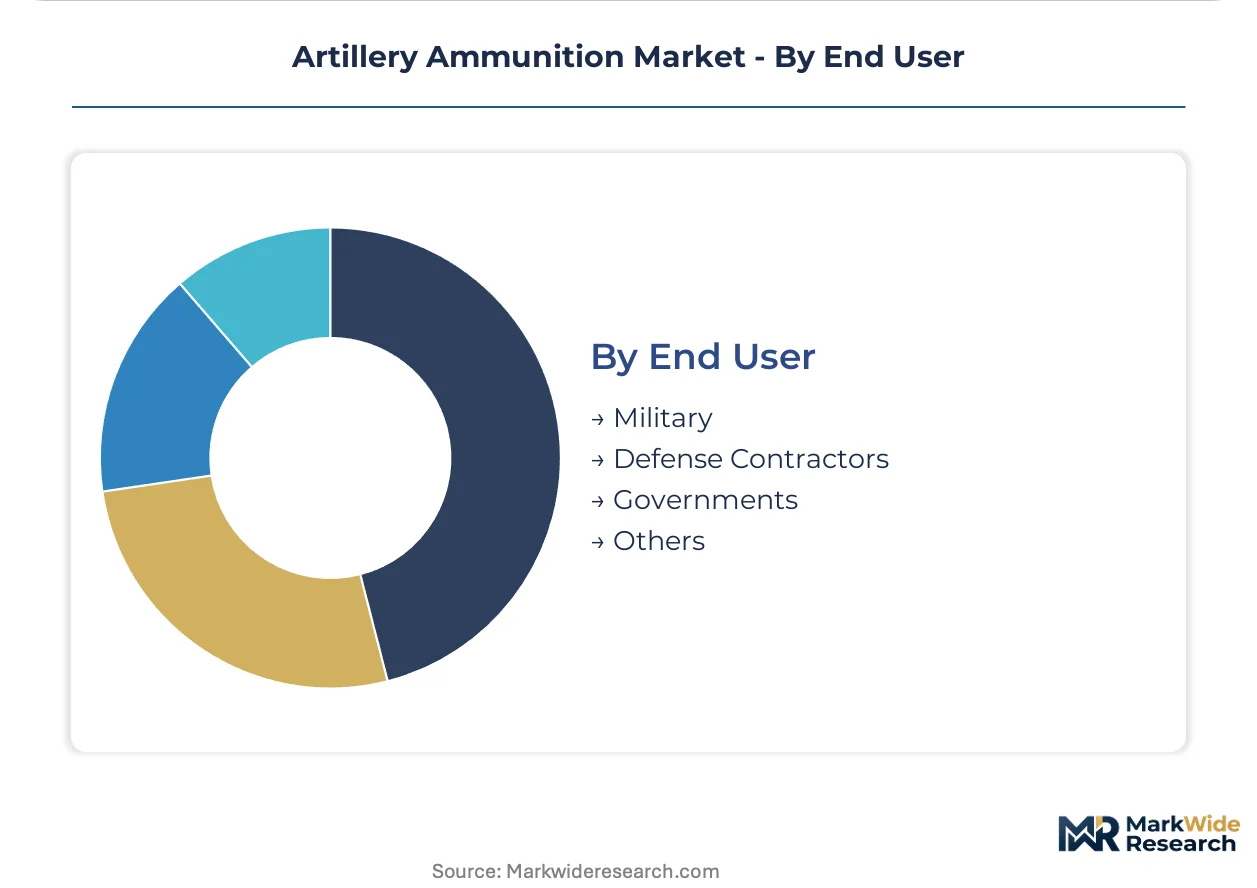
End User:
Institutional procurement authority determines contract structure, pricing tolerance, and technical specification stringency.
- Military:National armed forces execute multi-year framework agreements with penalty clauses for capacity diversion. The US Department of Defense and British Ministry of Defence are consolidating fragmented budgets into single-source national stockpile programs.
- Defense Contractors:Prime systems integrators procure ammunition as sub-tier components for platform delivery contracts.
- Governments:Central procurement agencies manage strategic reserve warehousing and cross-border transfer licensing.
- Others:Training institutions and demilitarization contractors absorb limited secondary market volumes.
Military end users anchor procurement value. Defense Contractors represent the most volatile demand swing as platform delivery schedules shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish defense procurement commands premium pricing for 155mm precision rounds while Canadian stockpiles absorb discounted legacy inventory, creating a transatlantic arbitrage that manufacturers exploit through capacity allocation protocols.
United States
The US Department of Defense's Precision Strike Missile program is absorbing prime contractor capacity for guided munitions, redirecting artillery ammunition investment toward complementary tube-fired systems. Domestic content incentives under Inflation Reduction Act defense provisions are reshaping supplier qualification pathways. Production clusters in Tennessee and Iowa are expanding nitrocellulose blending facilities to secure propellant supply chains.
Germany
Rheinmetall AG anchors European 155mm production through multi-year framework agreements with the Bundeswehr and allied export customers. The EU Green Deal defense industrial adaptation framework is imposing propellant chemistry disclosure requirements on strategic stockpile bidders. Manufacturing concentration in Unterlüß and Fröndenberg is scaling output for NATO burden-sharing commitments.
Poland
Polish defense procurement agencies are executing the fastest stockpile replenishment program in NATO Europe, locking in five-to-seven-year production commitments with penalty clauses. Cross-border transfer licensing from German and French regulators is accelerating through dedicated Nordic-Baltic procurement corridors. Industrial partnerships near the Baltic coast are establishing regional ammunition integration facilities.
United Kingdom
The Ministry of Defence is consolidating fragmented artillery ammunition budgets into single-source national stockpile replenishment programs with predetermined escalation terms. British Army AS90 platform compatibility requirements are concentrating shell procurement with integrated cartridge-case assemblies. BAE Systems plc sustains long-term production through its Glascoed and Washington facilities.
France
Nexter and Thales are positioning precision fuzing capabilities within NATO interoperability mandates enforced by the NATO Standardization Office. ANSM export control protocols extend contract fulfillment timelines for allied nations outside immediate treaty structures. The Bourges and La Chapelle-Saint-Ursin industrial cluster is prioritizing insensitive munition certification under STANAG 4439 compliance pathways.
Artillery Ammunition Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in propellant chemistry and precision fuzing. The artillery ammunition market exhibits moderate consolidation around prime contractors with certified NATO production facilities, while specialist suppliers concentrate in Nordic and Baltic corridors. Three archetypes dominate: diversified defense conglomerates with cross-platform ammunition divisions, state-affiliated national champions serving single-country strategic reserves, and precision components specialists capturing premium electronic fuze margins. Competitive positioning hinges on multi-year framework agreement capture and backward integration into nitrocellulose supply.
Within the diversified conglomerate tier, Rheinmetall AG and BAE Systems plc exemplify platform-agnostic ammunition producers with transatlantic manufacturing footprints. Nammo AS occupies a specialist position in precision fuzing and propellant chemistry, differentiating through Nordic-Baltic procurement corridor access. These three anchors represent distinct competitive vectors: German production scale, British-American dual-facility redundancy, and Norwegian niche technology integration.
| Leading Market Players |
|---|
| Rheinmetall AG |
| General Dynamics Corporation |
| BAE Systems plc |
| Nammo AS |
| Elbit Systems Ltd. |
| Thales |
| Hanwha Aerospace |
| Nexter |
| General Dynamics Ordnance & Tactical Systems |
| Others |
Supply Flow & Price Mechanics
Nitrocellulose blending capacity concentration in Eastern European manufacturing corridors determines where margin pools accumulate across the artillery ammunition value chain. German and Polish propellant chemistry facilities command premium pricing for certified insensitive munition formulations, while spot-market buyers absorb volatility from feedstock supply constraints.
Pricing Analysis
Configured-to-order precision-guided projectiles with integrated electronic fuzing systems command substantial premiums over standard mechanical-fuze saturation rounds. Three-tier pricing structure across precision-guided, insensitive munition-certified, and legacy high-explosive inventory reflects NATO STANAG 4439 compliance tiers and volume scale commitments. Cost compression in legacy unguided shells is intensifying because loitering munitions are displacing saturation bombardment missions. National defense procurement agencies executing multi-year framework agreements demonstrate lowest price sensitivity, while spot-market buyers for training ammunition exhibit highest elasticity.
Supply Chain Analysis
Rheinmetall AG, BAE Systems plc, and Nammo AS hold the majority of certified NATO production capacity for 155mm artillery ammunition systems. Manufacturing concentrates in Germany, the United Kingdom, and Norway, with emerging integration facilities scaling near Poland's Baltic coast. Propellant chemistry draws from nitrocellulose feedstocks, steel casings, and electronic fuze components sourced from qualified supplier networks. Single-source vulnerability in Eastern European nitrocellulose corridors creates structural exposure to input cost volatility. Distribution runs through national defense procurement agencies with cross-border transfer licensing frameworks governing allied shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The artillery ammunition market represents an early-cycle expansion story as NATO allies replace stockpiles depleted by sustained operational tempo and redirect procurement toward precision-guided systems under accelerated burden-sharing frameworks.
For Market Incumbents: Build certification moats around NATO STANAG 4439 insensitive munition compliance and electronic fuze integration capabilities. Lock multi-year framework agreements with penalty clauses for capacity diversion before spot-market allocation tightens. Expand nitrocellulose blending capacity in Tennessee and Iowa to secure propellant supply chains against Eastern European feedstock concentration. Counter tube artillery substitution threats by positioning precision-guided projectiles as complementary to loitering munitions for counter-battery missions. For New Entrants and Emerging Players: Baltic procurement corridors with accelerated certification pathways for precision fuzing specialists represent the most penetrable entry point for niche component suppliers. Nordic and Baltic defense ministries are establishing dedicated ammunition acquisition frameworks outside dominant German-British supply channels. Modular propellant charge systems enabling platform-agnostic compatibility across towed and self-propelled howitzer fleets offer a differentiated go-to-market angle for mid-tier specialists seeking to bypass prime contractor gatekeeping. For Investors and Strategic Acquirers: Capital is best deployed toward precision components specialists with captive electronic fuze technology and established Nordic-Baltic procurement corridor access. Long-term viability hinges on backward integration into nitrocellulose supply or exclusive multi-year framework agreement capture with predetermined escalation terms. Monitor NATO burden-sharing agreement revisions as the primary inflection signal for geographic redistribution of production commitments. Quarterly review of framework agreement award announcements and STANAG 4439 certification timelines is advised to detect inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Insensitive Munition Certification | NATO STANAG 4439 compliance unlocks strategic stockpile contracts in Germany and France. |
| Backward Integration into Propellant Chemistry | Captive nitrocellulose blending secures margin pools against Eastern European feedstock volatility. |
| Multi-Year Framework Agreement Capture | Five-to-seven-year production commitments with penalty clauses lock capacity before spot-market tightening. |
| Electronic Fuze Technology Acquisition | Precision guidance capabilities differentiate offerings in Polish and German counter-battery procurement. |
| Baltic Corridor Manufacturing Footprint | Regional integration facilities near Poland's coast accelerate Nordic-Baltic defense ministry access. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of NATO Standardization Office technical specifications, national defense procurement agency contract announcements, and EU Green Deal defense industrial adaptation framework disclosures. Primary interviews engaged artillery program executives at allied defense ministries, propellant chemistry technical directors, precision fuze engineering leads, and strategic stockpile logistics officers. Secondary validation incorporated US Department of Defense budget justification materials, Bundeswehr equipment procurement reports, and British Ministry of Defence single-source contract registers. Bottom-up production capacity modeling triangulated against top-down national stockpile replenishment budget aggregation.
Forecast inputs incorporate platform fleet composition shifts, precision-guided projectile adoption curves, and NATO interoperability mandate enforcement intensity across the projection horizon. Segmentation dimensions modeled include caliber standardization trajectories, fuze sophistication tiers, end-user procurement authority structures, and regional regulatory cluster alignment. CAGRs derived from production capacity expansion schedules mapped against framework agreement award pipelines. Industry-specific inputs encompass nitrocellulose supply concentration indices and electronic fuze integration cost curves.
Practitioners should monitor NATO burden-sharing agreement revisions, loitering munition procurement acceleration, and nitrocellulose supply disruptions for early signals of forecast deviation. Quarterly review of framework agreement penalty clause enforcement and STANAG 4439 certification timeline extensions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Missile Launching Systems Market
Weapons and Ammunition
Smoke Grenade Market
Weapons and Ammunition
Small Arms Market
Weapons and Ammunition
North America Nuclear Bombs and Missiles Market
Weapons and Ammunition
Automatic Weapons Market
Weapons and Ammunition
Guided Munitions Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Light Weapons Market
Weapons and Ammunition
North Korea Nuclear Bombs and Missiles Market
Weapons and Ammunition
Global Artillery Systems Market
Weapons and Ammunition
Man-Portable Rocket Launcher Market
Weapons and Ammunition
NIJ III Ballistic Bullet Resistant Panel Market
Weapons and Ammunition
Medium Caliber Ammunition Market
Weapons and Ammunition
Manned Anti-Tank Guided Missile System Market
Weapons and Ammunition
Global Multiple Launch Rocket Systems Market
Weapons and Ammunition
Turret System Market