
 Smart War Weapon Market | 2026-2036
Smart War Weapon Market Size, Share, and Industry Trends Forecast 2026-2036
Smart War Weapon Market Insights
Aerospace engineering talent is rotating toward software-defined systems faster than legacy hardware disciplines can replenish, tightening the labor pool for guidance-system architects. Lockheed Martin Corporation leverages classified R&D facilities to sustain vertical integration in hypersonic glide vehicles. RTX Corporation anchors its position through captive production of radar seekers and electronic warfare subsystems. BAE Systems competes on trans-Atlantic program participation, dominating Anglo-French missile development frameworks.
Smart war weapons integrate precision guidance, networked communications, and autonomous decision loops to deliver kinetic or non-kinetic effects against time-critical targets with minimal collateral damage. These systems typically employ GPS-denied navigation, multi-spectral seekers, and real-time data links operating across contested electromagnetic spectra. Missiles and electronic warfare systems occupy the largest margin pools, with sensor fusion architectures growing fastest as militaries demand all-weather target discrimination. Artificial intelligence and machine learning segments attract disproportionate venture inflow, though remote piloting retains volume leadership due to lower certification barriers.
The US Department of Defense imposes stringent cybersecurity maturity requirements through NIST SP 800-171 and DFARS 252.204-7012, while the EU Green Deal and F-Gas Regulation constrain propellant chemistries in European supply chains. NATO STANAG interoperability standards shape procurement eligibility, forcing non-aligned vendors into costly redesign cycles. Stakeholders must monitor how ITAR reform debates and emerging autonomous-weapon governance at the UN Convention on Certain Conventional Weapons reshape market-access rules before committing to platform-specific investments.
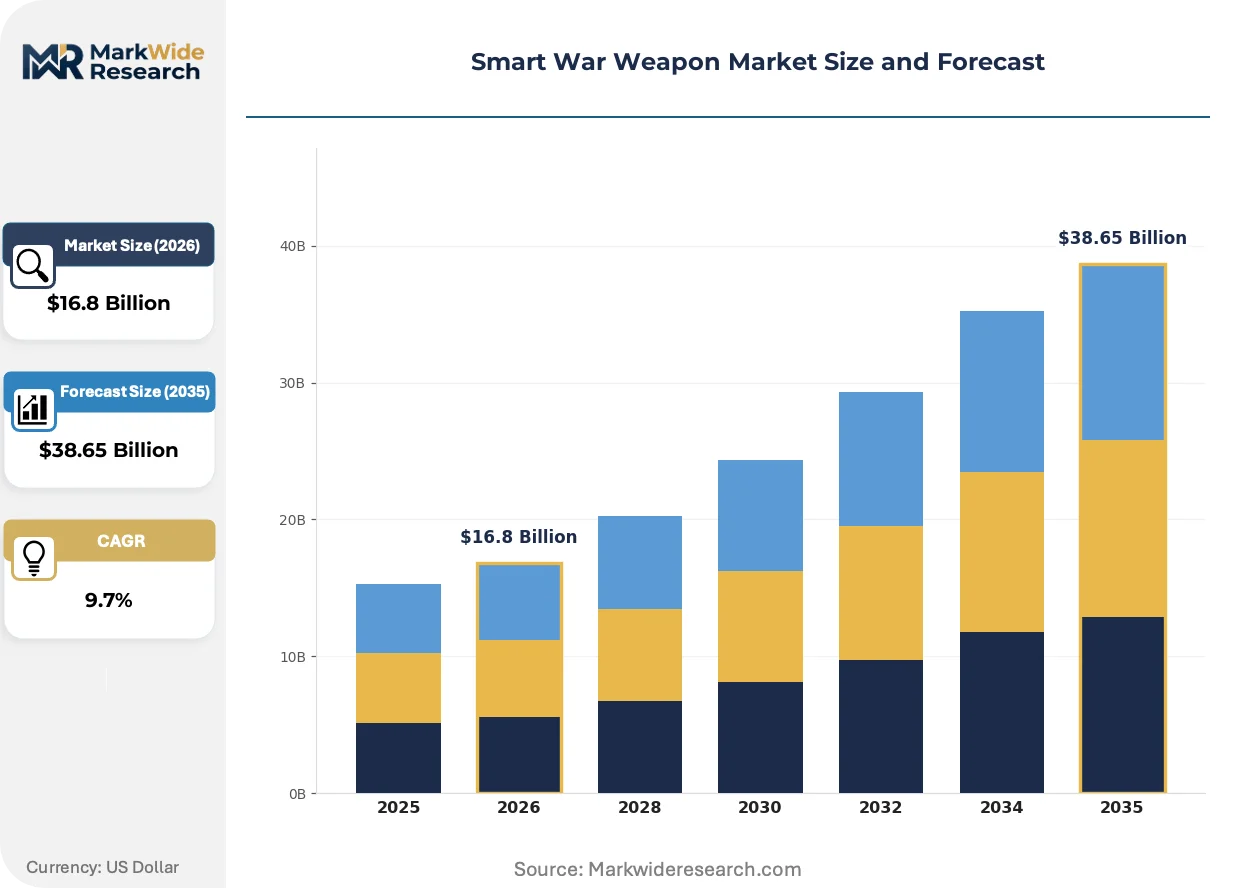
Market Dynamics
The migration of guidance-system engineering toward software-defined architectures is compressing development cycles while depleting legacy hardware talent pools faster than universities can replenish them. Defense primes now compete with commercial AI labs for the same embedded-systems specialists.
Growth Catalysts
- NATO STANAG Interoperability Mandates:Allied procurement frameworks now require cross-border sensor fusion and data-link compatibility, forcing upgrade cycles across European arsenals and disqualifying non-compliant vendors.
- Contested Electromagnetic Spectrum Operations:Pentagon doctrine prioritizes GPS-denied navigation and anti-jam seekers for Indo-Pacific scenarios, accelerating investment in multi-spectral target discrimination.
- AI-Enabled Targeting Loops:Machine learning for real-time collateral-damage estimation is compressing sensor-to-shooter timelines below human reaction thresholds in urban warfare applications.
Market Restraints
- ITAR Export Control Tightening:The US State Department's classification of AI-enabled fire-control algorithms as munitions items is fragmenting supplier access and delaying non-NATO technology transfer.
- Propellant Chemistry Constraints:The EU F-Gas Regulation and Green Deal emission targets are forcing reformulation of solid-rocket motor compositions, raising qualification costs for European manufacturers.
- Rare Earth Magnet Concentration:Precision actuator and seeker-gimbal production depends on Chinese-processed neodymium and samarium, creating single-source vulnerability for Western guidance systems.
Strategic Opportunities
- Autonomous Swarm Architectures:Distributed lethality concepts using networked loitering munitions remain underdeveloped outside US and Israeli arsenals, offering first-mover advantage in Southeast Asian maritime defense.
- Non-Kinetic Effect Integration:Convergence of directed-energy weapons with conventional hard-kill systems creates new product categories for electromagnetic pulse and cyber-physical attack missions.
- Modular Open Systems Approach:US DoD mandates for MOSA-compliant interfaces are displacing proprietary bus architectures, enabling subsystem vendors to penetrate previously closed prime-dominated programs.
Industry Challenges
- Guidance-System Architect Scarcity:The talent pipeline for inertial navigation and seeker-optics design is thinning as aerospace programs lose graduates to autonomous vehicle and robotics sectors.
- Cross-Domain Certification Complexity:Air-, sea-, and ground-launch qualification regimes demand redundant test matrices, extending development timelines for multi-platform weapon families.
- Legacy Platform Integration Friction:Fourth-generation aircraft and surface vessels lack the power, cooling, and data-bus capacity for full-spectrum smart-weapon employment, forcing expensive airframe modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart War Weapon Market |
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Weapon Type: Missiles, Drones, Guided Bombs, Laser Weapons, Electronic Warfare Systems Technology: Artificial Intelligence, Machine Learning, Remote Piloting, Target Recognition, Sensor Fusion Application: Surveillance Operations, Tactical Strikes, Electronic Disruption, Battlefield Support, Reconnaissance Missions End User: Defense Contractors, Special Forces, Military Intelligence Units, Border Security, Naval Operations |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, The Boeing Company, BAE Systems, Northrop Grumman Corporation, General Dynamics Corporation, MBDA, Raytheon Technologies Corporation, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart War Weapon Market Trends and Innovations
Weapon-system architectures are fragmenting into modular, software-upgradable components that decouple hardware refresh cycles from capability evolution. This structural shift favors vendors with firmware-development velocity over traditional hardware-integration scale.
Software-defined radio is decomposing the traditional stack of discrete communications, navigation, and electronic-warfare subsystems into reprogrammable waveform engines. Naval strike-missile programs are adopting these consolidated payloads to reduce part count and simplify logistics chains. The resulting compression of supplier tiers is eliminating niche radio-frequency component vendors who cannot port to general-purpose processing platforms.
The EU AI Act's risk-classification framework for autonomous targeting systems is forcing European defense contractors to segregate human-in-the-loop verification modules from machine-learning inference engines. This architectural mandate is inflating software-assurance costs but creating competitive differentiation for vendors with pre-certified ethical-AI governance structures. Anglo-French missile programs are most affected, with MBDA restructuring development workflows to satisfy conformity-assessment requirements before 2026 implementation deadlines.
Defense procurement offices are consolidating vendor relationships through multi-year system-of-systems contracts that bundle weapons, platforms, and sustainment under single prime accountability. This pattern displaces the traditional component-supplier model in which primes assembled best-of-breed subsystems. The UK Ministry of Defence's Complex Weapons framework exemplifies this concentration, with BAE Systems absorbing lifecycle responsibility previously distributed across Raytheon and smaller specialist firms.
Smart War Weapon Market Segmentation
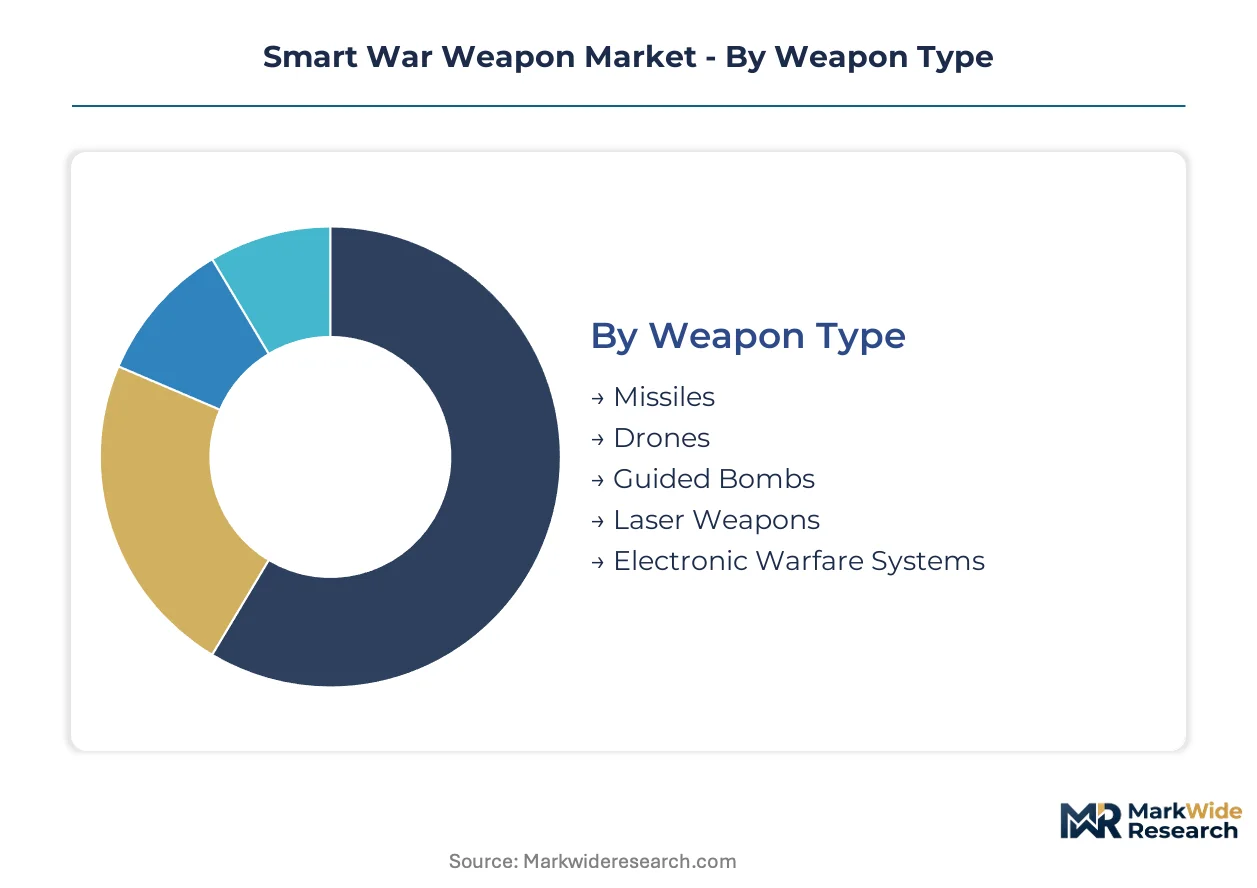
Segmentation reveals where defense procurement dollars concentrate across weapon architectures and decision-system layers. Understanding these divisions exposes which technology bets carry platform-level consequences versus subsystem substitution risks.
Weapon Type:
Margin pools cluster in precision-strike systems with integrated seekers and propulsion, while directed-energy platforms remain pre-commercial despite heavy development spend.
- Missiles:Hypersonic glide vehicles and anti-ship variants absorb the largest R&D allocations from Pentagon modernization accounts. US Navy Distributed Maritime Operations doctrine drives demand for long-range anti-surface weapons with GPS-denied terminal guidance.
- Drones:Loitering munitions and attritable platforms are displacing reusable systems in Indo-Pacific force-structure planning. Israeli and Turkish combat-proven designs are penetrating Southeast Asian procurement cycles ahead of NATO-certified alternatives.
- Guided Bombs:JDAM-ER derivatives with wing-kit extensions dominate Air Force inventory refresh programs.
- Laser Weapons:Shipboard and ground-based directed-energy prototypes remain tethered to power-density limitations and atmospheric-interference constraints.
- Electronic Warfare Systems:Podded and embedded jamming architectures are standardizing across F-35 and Eurofighter fleets.
Missiles hold installed capacity. Drones are rotating up the share rankings.
Technology:
Procurement prioritization splits between certified autonomous functions and human-retained control loops, with liability frameworks determining adoption velocity.
- Artificial Intelligence:Real-time collateral-damage estimation and target-priority algorithms are entering operational test under US Army Project Convergence. EU AI Act risk-classification requirements are forcing architectural segregation of inference engines from verification modules in Anglo-French programs.
- Machine Learning:Adaptive electronic-warfare waveform generation is compressing countermeasure development cycles from months to hours. Royal Air Force Rapid Capabilities Office contracts prioritize ML-enabled threat-library updates for stand-in jamming platforms.
- Remote Piloting:Volume leadership persists in ISR and light-strike missions due to lower airworthiness-certification barriers compared to autonomous systems.
- Target Recognition:Multi-spectral fusion combining radar, electro-optical, and signals-intelligence feeds is standardizing on MOSA-compliant interfaces.
- Sensor Fusion:All-weather target discrimination architectures are climbing the fastest as militaries demand contested-spectrum operability.
Remote piloting retains volume dominance. Sensor fusion is gaining share fastest.
Application:
Operational concepts are shifting from platform-centric to effects-based employment, rewiring which application layers capture integration value.
- Tactical Strikes:Time-sensitive targeting against mobile missile launchers and command nodes absorbs precision-weapon inventory at the highest burn rates. US Indo-Pacific Command exercise scenarios prioritize distributed kill chains compressing sensor-to-shooter timelines below four minutes.
- Surveillance Operations:Persistent wide-area motion imagery is migrating toward AI-enabled tipping-and-cueing architectures that reduce analyst manpower requirements.
- Electronic Disruption:GPS denial and communications jamming are integrating with kinetic strike planning as combined-arms packages.
- Battlefield Support:Close air support and casualty evacuation missions retain human-in-the-loop requirements that constrain full autonomy.
- Reconnaissance Missions:Penetrating platforms with low-observable signatures are competing with commercial-satellite augmentation for strategic indication-and-warning functions.
Tactical strikes hold installed capacity. Electronic disruption is rotating up the share rankings.
End User:
Procurement authority is fragmenting between traditional service acquisition commands and theater-level rapid-equipping cells with delegated spending authority.
- Defense Contractors:Prime-led system-of-systems contracts are consolidating lifecycle accountability previously distributed across component suppliers. UK Ministry of Defence Complex Weapons framework exemplifies this concentration.
- Special Forces:Compartmented units with direct congressional funding lines are bypassing standard requirements-validation processes for urgent operational need statements.
- Military Intelligence Units:Technical-collection organizations are weaponizing signals-intelligence infrastructure for offensive cyber-physical effects.
- Border Security:Coast Guard and customs agencies are adopting military-surplus loitering systems for maritime domain awareness.
- Naval Operations:Distributed surface-action-group concepts are driving demand for magazine-depth expansion on destroyer and frigate platforms.
Defense contractors hold installed capacity. Special forces are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes smart war weapons as integrated system-of-systems packages bundling weapons, platforms, and sustainment, whereas European procurement emphasizes modular subsystem interoperability and Israeli deployment favors rapid fielding of attritable platforms over lifecycle contracts.
United States
The Department of Defense drives demand through Distributed Maritime Operations and Project Convergence, prioritizing GPS-denied navigation and sub-four-minute sensor-to-shooter timelines. NIST SP 800-171 and DFARS 252.204-7012 impose stringent cybersecurity maturity requirements on contractors. Huntsville, Alabama anchors missile defense development, while the Route 128 corridor outside Boston concentrates AI-enabled targeting algorithm firms serving Pentagon modernization accounts.
United Kingdom
The Ministry of Defence's Complex Weapons framework consolidates lifecycle accountability under single primes, displacing previous multi-vendor component assemblies. NATO STANAG interoperability standards shape procurement eligibility for cross-border sensor fusion programs. Stevenage and Bristol host BAE Systems and MBDA facilities dominating Anglo-French missile development, with the former specializing in guidance electronics and the latter in propulsion systems.
France
The Direction Générale de l'Armement prioritizes autonomous systems with human-in-the-loop verification under EU AI Act risk-classification deadlines approaching 2026. The EU Green Deal and F-Gas Regulation constrain solid-rocket motor propellant chemistries, forcing costly reformulation. Le Plessis-Robinson and Bourges concentrate MBDA and Thales operations, with the Île-de-France cluster specializing in seeker-optics and the Centre-Val de Loire hub focusing on warhead integration.
Germany
The Bundeswehr accelerates procurement of networked loitering munitions through rapid-equipping cells with delegated spending authority, bypassing standard validation processes. KBA and federal export-control offices enforce ITAR-aligned restrictions on AI-enabled fire-control algorithms. Schrobenhausen and Überlingen host Diehl Defence and Rheinmetall facilities, with Bavaria specializing in precision actuator production and Baden-Württemberg concentrating on electronic warfare subsystem integration.
Israel
The Israel Defense Forces operationalize combat-proven loitering munitions and attritable platforms through direct congressional funding lines for urgent operational needs. The country's national defense regulator maintains strict compartmentalization of autonomous targeting capabilities. Haifa and Be'er Sheva concentrate Rafael Advanced Defense Systems and Elbit Systems operations, with the northern coastal cluster specializing in electro-optical seekers and the southern desert hub focusing on unmanned platform endurance testing.
Smart War Weapon Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that supplies modular subsystems into prime-dominated programs. The upper tier captures lifecycle value through system-of-systems contracts bundling weapons, platforms, and sustainment, while the lower tier competes on firmware-development velocity for software-defined radio and sensor-fusion architectures. Two strategic archetypes dominate: vertically integrated primes with classified R&D facilities, and subsystem specialists with MOSA-compliant interfaces penetrating previously closed programs. Competitive moves concentrate on multi-year consolidation contracts and captive production of radar seekers and electronic warfare components.
Within the integrated prime tier, Lockheed Martin Corporation and RTX Corporation occupy positions exemplifying contrasting integration strategies. Lockheed Martin leverages classified R&D facilities to sustain in-house production of hypersonic glide vehicle architectures. RTX Corporation anchors its market position through captive supply of radar seekers and electronic warfare subsystems. BAE Systems sits within the trans-Atlantic program participation archetype, representing vendors competing on Anglo-French missile development frameworks rather than purely domestic procurement cycles.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| The Boeing Company |
| BAE Systems |
| Northrop Grumman Corporation |
| General Dynamics Corporation |
| MBDA |
| Raytheon Technologies Corporation |
| Thales Group |
| Others |
Pricing and Supply Chain Analysis
Neodymium magnet substitution with ferrite alternatives in actuator designs simultaneously relocates component sourcing from Chinese processors to European foundries and compresses unit economics for precision seeker gimbals. This material transition reshapes procurement negotiations between prime contractors and tier-two suppliers across NATO arsenals.
Pricing Analysis
Multi-year system-of-systems contracts dominate procurement, bundling weapons, platforms, and sustainment under single-prime accountability. Price differentiation stems from ITAR certification tier and MOSA compliance grade, with non-aligned vendors facing costly redesign cycles. Margins are tightening due to EU F-Gas Regulation compliance costs for solid-rocket motor reformulation. Defense contractors show lowest price sensitivity given lifecycle value capture, while border security agencies exhibit highest sensitivity due to surplus-equipment alternatives.
Supply Chain Analysis
China processes over 80 percent of global rare earth magnet feedstock for precision actuators, while the United States and Australia anchor alternative mining and separation investments. Western guidance systems draw from Chinese-processed neodymium, Japanese ceramic substrates, and German precision optics. Single-source vulnerability concentrates in rare earth magnet concentration. Distribution runs through defense prime captive production networks and classified R&D facilities with vertical integration into seeker-optics and electronic warfare subsystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards entities controlling scarce guidance-system architecture talent, as aerospace programs hemorrhage graduates to commercial autonomous vehicle and robotics sectors faster than universities replenish pipelines.
For Market Incumbents: Fortify captive production of radar seekers and electronic warfare subsystems to defend against modular open systems approach mandates displacing proprietary bus architectures. Deepen backward integration into hypersonic glide vehicle architectures through classified R&D facility expansion. Prioritize NIST SP 800-171 and DFARS 252.204-7012 cybersecurity certification investment to disqualify non-compliant vendors from Pentagon modernization accounts.
For New Entrants and Emerging Players: Lead with MOSA-compliant firmware-development velocity for software-defined radio and sensor-fusion architectures penetrating previously closed prime-dominated programs. Target Southeast Asian maritime defense procurement for autonomous swarm architectures, where distributed lethality concepts remain underdeveloped outside US and Israeli arsenals. Deploy rapid fielding partnerships with Israeli defense contractors possessing direct congressional funding lines for urgent operational needs.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed subsystem specialists possessing pre-certified ethical-AI governance structures satisfying EU AI Act risk-classification requirements. Long-term viability hinges on 5-10 year windows for autonomous-weapon governance crystallization at the UN Convention on Certain Conventional Weapons. Monitor ITAR reform debates as the critical inflection signal for non-NATO technology transfer access.
| Strategic Initiative | Industry Significance |
|---|---|
| MOSA-Compliant Interface Development | Enables subsystem vendors to penetrate prime-dominated programs under US DoD mandates. |
| Captive Rare Earth Magnet Production | Mitigates Chinese single-source vulnerability for Western guidance system actuators. |
| EU AI Act Conformity Assessment | Creates competitive differentiation for vendors with pre-certified ethical-AI governance. |
| Autonomous Swarm Architecture Fielding | Captures first-mover advantage in Southeast Asian maritime defense procurement cycles. |
| Multi-Year System-of-Systems Contracting | Consolidates lifecycle accountability previously distributed across component suppliers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with guidance-system architects, defense prime procurement executives, electronic warfare subsystem engineers, and rapid-equipping cell officers from NATO member states. Secondary validation drew from ITAR classification bulletins, NATO STANAG documentation, EU AI Act implementation guidance, DFARS cybersecurity clause updates, and UN Convention on Certain Conventional Weapons position papers. Bottom-up segment sizing triangulated against top-down defense budget appropriation analysis.
Across the analysis window, the forecasting framework modeled weapon type, technology layer, application mission profile, and end-user procurement authority. CAGRs derived from segment-level budget trajectory analysis and platform retirement-replacement cycle timing. Hypersonic glide vehicle R&D allocation patterns and loitering munition force-structure planning inputs shaped scenario weightings.
The analysis sits within stated boundaries; outcomes outside sustained Indo-Pacific theater prioritization or ITAR classification stability would require recalibration. Forecasts reflect documented assumptions regarding NATO STANAG interoperability mandate adherence and rare earth magnet supply diversification progress. Recalibration cycles align with material shifts in autonomous-weapon governance negotiations and Pentagon doctrine updates for contested electromagnetic spectrum operations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Battle Management System (BMS) Market
Defense and Military Systems and Equipment
Military Embedded System Market
Defense and Military Systems and Equipment
Command and Control Systems Market
Defense and Military Systems and Equipment
Military Embedded System Software Market
Defense and Military Systems and Equipment
Military Aerospace and Defense Lifecycle Management Market
Defense and Military Systems and Equipment
Europe Defense Logistics Market
Defense and Military Systems and Equipment
Middle East and Africa Defense Market
Defense and Military Systems and Equipment
Anti-Drone Guns Market
Defense and Military Systems and Equipment
Europe Missiles and Missile Defense Systems Market
Defense and Military Systems and Equipment
Global Non Lethal Biochemical Weapon Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Displays Market
Defense and Military Systems and Equipment
Cognitive Electronic Warfare System Market
Defense and Military Systems and Equipment
United Kingdom Defense Market
Defense and Military Systems and Equipment
Missiles and Missile Defense Systems Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Display Systems Market
Defense and Military Systems and Equipment
Global Digital Battlefield Market