
 US Small Caliber Ammunition Market | 2026-2036
US Small Caliber Ammunition Market Size, Share, and Industry Trends Forecast 2026-2036
US Small Caliber Ammunition Market Intelligence
Customer concentration in the US small caliber ammunition market is shifting from large, cyclical government contracts toward the more fragmented civilian end-user base. This change favors manufacturers with strong consumer brand recognition and extensive commercial distribution channels. Vista Outdoor Operations LLC leverages its portfolio of consumer brands to capture share in sports shooting. Hornady Manufacturing Company specializes in high-performance and niche hunting rounds, while Winchester Ammunition sustains a broad presence across both civilian and law enforcement segments.
US small caliber ammunition encompasses cartridges with a bullet diameter of 12.7mm (.50 inches) or smaller, designed for pistols, rifles, and shotguns. These cartridges consist of a case, primer, propellant, and projectile, engineered for specific ballistic performance. The centerfire product type dominates sales volume, serving a wide array of firearms. Within applications, the sports shooting segment represents the fastest-growing area of civilian consumption, eclipsing traditional hunting use in many US states.
The market operates under the oversight of the US Bureau of Alcohol, Tobacco, Firearms and Explosives (ATF), which governs commerce and licensing. Concurrently, Sporting Arms and Ammunition Manufacturers' Institute (SAAMI) standards guide product safety and interoperability for manufacturers. These regulations create a complex compliance environment for all participants. The key decision for manufacturers involves allocating production capacity between volatile government defense contracts and the more stable, but price-sensitive, civilian market.
Market Dynamics
The market's central dynamic involves manufacturers rebalancing production between cyclical government contracts and the fragmented civilian sector. This structural tension prioritizes commercial distribution networks and consumer brand strength, particularly within the sports shooting segment.
Growth Catalysts
- Sports Shooting Participation:Increased engagement in competitive and recreational shooting sports, especially in states like Texas and Florida, drives consistent volume demand for training and competition-grade ammunition.
- Hunting Regulation Expansion:State-level wildlife management policies that expand hunting seasons or open new areas for specific game directly increase the consumption of specialized hunting cartridges.
- Lead-Free Initiatives:Environmental regulations and shooter preferences push development and adoption of non-toxic projectiles and primers, creating a new product category for environmentally sensitive areas and indoor ranges.
Market Restraints
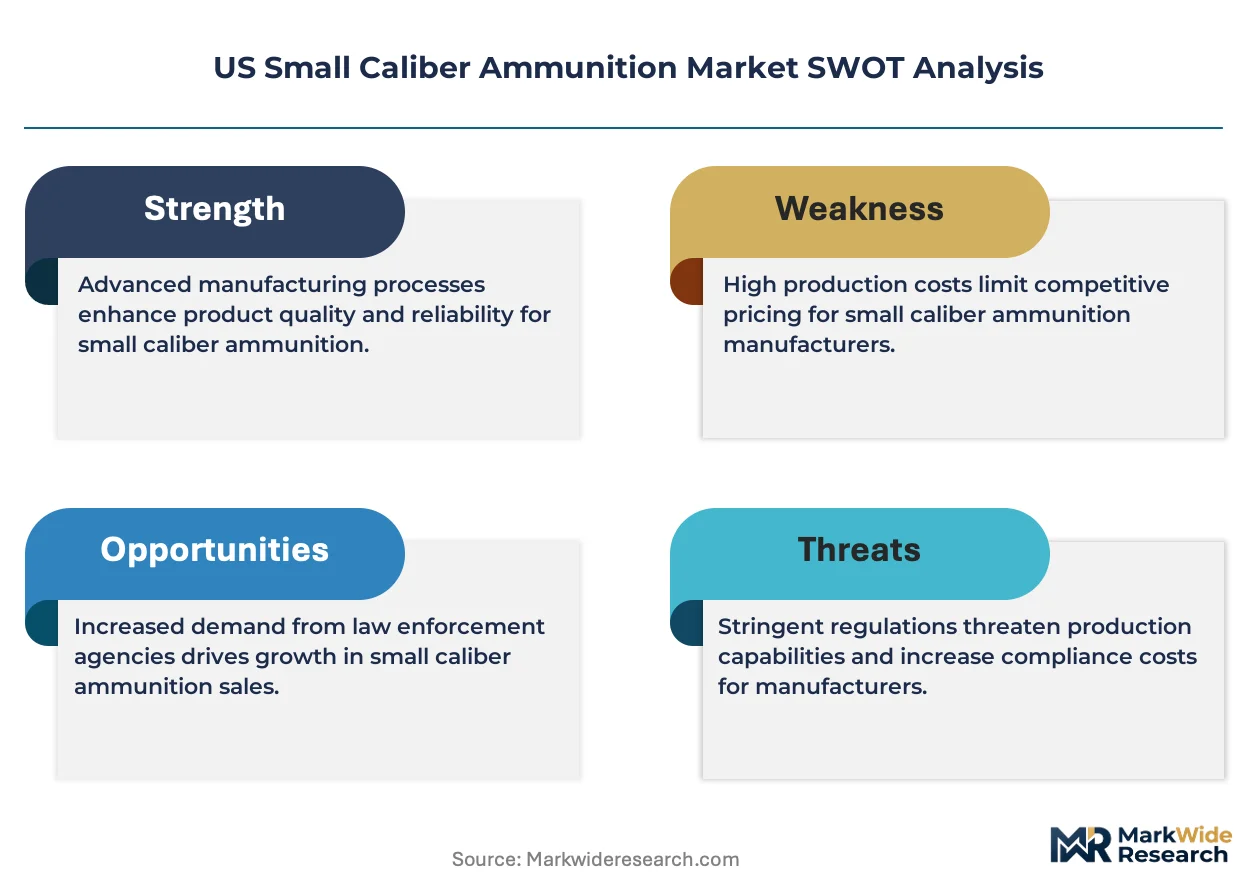
- Raw Material Volatility:Price fluctuations in key commodities like copper, lead, and zinc create significant margin pressure, as these costs are difficult to pass on quickly to the price-sensitive civilian market.
- Complex State-Level Laws:A patchwork of state and local regulations on ammunition sales, shipping, and possession creates significant compliance burdens and logistical hurdles, fragmenting the national market.
- Primer Supply Bottlenecks:The highly specialized and concentrated nature of primer manufacturing creates a persistent bottleneck, limiting overall cartridge production capacity across the US industry during demand surges.
Strategic Opportunities
- Smart Ammunition Development:Integrating micro-electronics for tracer or data-logging functions presents an opportunity to create high-margin products for specialized law enforcement and military training applications.
- Direct-to-Consumer Channels:Expanding online direct-to-consumer sales models, where legally permissible, allows manufacturers to capture higher margins and build direct relationships with end-users, bypassing traditional distribution tiers.
- Subsonic Ammunition Growth:The rising popularity of firearm suppressors creates a distinct opportunity for optimizing and marketing subsonic ammunition lines for recreational shooting and hunting.
Industry Challenges
- ATF Regulatory Adherence:Navigating the Bureau of Alcohol, Tobacco, Firearms and Explosives' stringent licensing, record-keeping, and production reporting requirements demands significant administrative resources and legal expertise.
- Production Modernization:The high capital expenditure required to modernize aging production lines to improve efficiency and accommodate new materials, like lead-free components, presents a significant financial challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Small Caliber Ammunition Market |
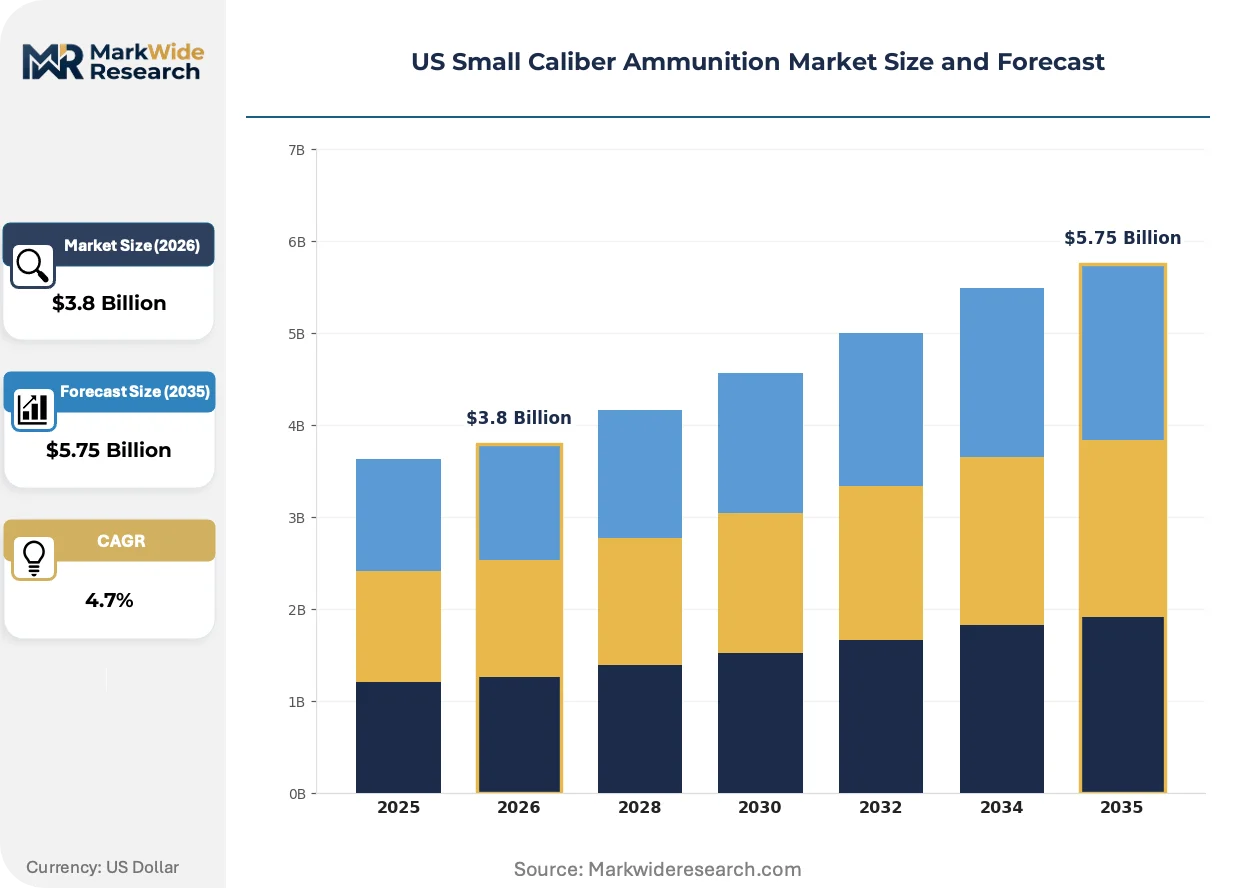
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rimfire, Centerfire, Shotshell, Blank Application: Military, Law Enforcement, Hunting, Sports Shooting End User: Civilian, Government, Security Forces, Defense Contractors Distribution Channel: Online Retail, Specialty Stores, Wholesalers, Sporting Goods |
| Companies Covered | FN Herstal, Hornady Manufacturing Company, Northrop Grumman Corporation, Winchester Ammunition, Remington Ammunition, Olin Corporation, Vista Outdoor Operations LLC, General Dynamics Ordnance and Tactical Systems, Nammo AS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Small Caliber Ammunition Market Strategic Shifts & Innovations
Material science advancements and digital manufacturing techniques are transforming ammunition from a commodity product into a highly specialized system. These shifts occur alongside evolving consumer behaviors that prioritize performance and customization over pure volume.
Advanced polymer-cased ammunition offers significant weight reduction and improved thermal properties compared to traditional brass. Military and specialized law enforcement segments are the primary early adopters, testing for reliability and performance. This innovation is modularizing the cartridge itself, separating the case from the projectile and propellant as independent design elements.
The US Environmental Protection Agency (EPA) continues to scrutinize the environmental impact of lead at shooting ranges, particularly those on federal lands. This pressure accelerates the industry's transition toward alternative, non-toxic materials for projectiles, such as copper and zinc alloys. The hunting ammunition segment is most affected, with manufacturers reformulating popular loads to meet state-specific lead-free zone requirements.
A growing preference for precision and long-range shooting is driving demand for highly consistent, match-grade ammunition. This trend disrupts the traditional bulk-purchase model, favoring smaller, specialized batches with documented performance metrics. This shift is most pronounced within the civilian sport shooting community, particularly in competitive disciplines across the US.
US Small Caliber Ammunition Market Segmentation
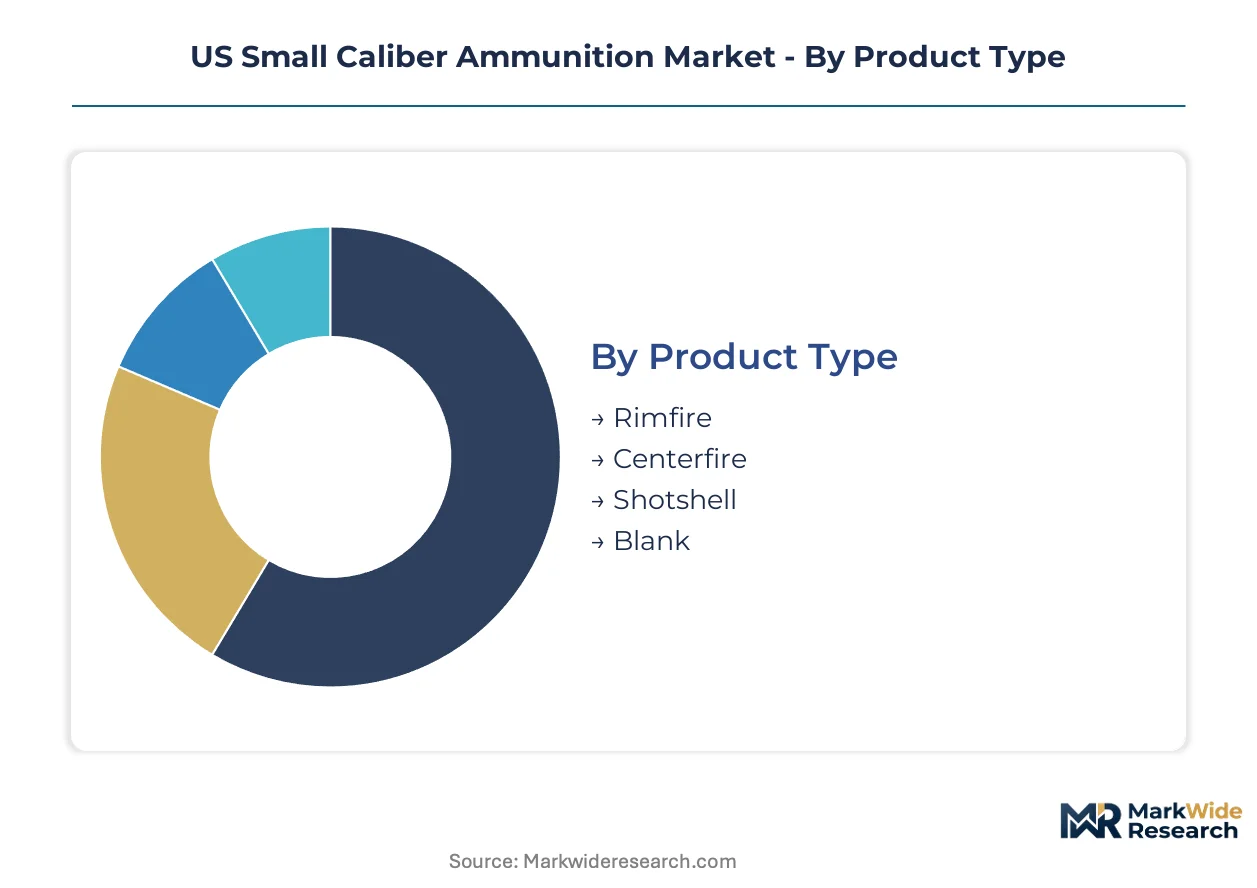
Understanding the US small caliber ammunition market through segmentation reveals distinct demand patterns and supply chain configurations. This granular analysis helps manufacturers align production capabilities with evolving consumer preferences and regulatory landscapes. Differentiating by product type, application, end user, and distribution channel clarifies the diverse forces shaping market expansion.
Product Type:
The varying integration depths of small caliber ammunition types define their market utility and production complexities.
- Centerfire:Centerfire cartridges consist of a case, primer, propellant, and projectile, featuring a primer located centrally in the cartridge base. Demand concentrates heavily in the sports shooting segment, driven by high-volume training and competitive events across US states like Texas and Florida.
- Shotshell:These cartridges typically contain multiple small pellets (shot) or a single projectile (slug) within a plastic or paper hull. Hunting regulation expansion directly increases shotshell consumption, particularly for waterfowl and upland game in various US states.
- Rimfire:Rimfire ammunition integrates the priming compound into the rim of the cartridge case, simplifying manufacturing processes.
- Blank:Blank cartridges contain propellant but no projectile, primarily serving training, signaling, and ceremonial purposes for military and law enforcement.
Volume placements concentrate in Centerfire; the faster expansion belongs to Rimfire.
Application:
The US small caliber ammunition market's application segments vary significantly by volume demand and operational cost structures.
- Sports Shooting:This application involves recreational and competitive target practice, demanding consistent performance and high-volume training ammunition. Increased engagement in competitive and recreational shooting sports, particularly in states like Texas and Florida, drives consistent volume demand.
- Hunting:Hunting applications utilize specialized ammunition designed for specific game animals, emphasizing terminal performance and ethical take-down. State-level wildlife management policies that expand hunting seasons or open new areas directly increase the consumption of specialized hunting cartridges.
- Military:Military applications require ammunition meeting stringent performance specifications for combat, training, and specialized operations.
- Law Enforcement:Law enforcement applications involve ammunition for duty, training, and specialized tactical situations, balancing reliability with controlled penetration.
The most significant volume driver is Military; the steepest expansion trajectory belongs to Sports Shooting.
End User:
End-user segments in the US small caliber ammunition market are differentiated by purchasing power and regulatory oversight.
- Civilian:This end-user base comprises individual citizens purchasing ammunition for sports shooting, hunting, and personal defense. The shift from large government contracts towards this fragmented civilian end-user base favors manufacturers with strong consumer brand recognition.
- Government:Government end-users, including federal and state agencies, procure ammunition through large, often cyclical, contracts for various departmental needs. Allocating production capacity between these volatile government defense contracts and the civilian market presents a key decision for manufacturers.
- Security Forces:Security forces, encompassing private and public entities, acquire ammunition for specialized protective services and training exercises.
- Defense Contractors:Defense contractors often source ammunition for integration into larger weapon systems or for fulfilling specific military support requirements.
The primary revenue concentration resides with Government; market share gains are most pronounced in Civilian.
Distribution Channel:
The various distribution channels for US small caliber ammunition reflect differing levels of supply concentration and margin structures.
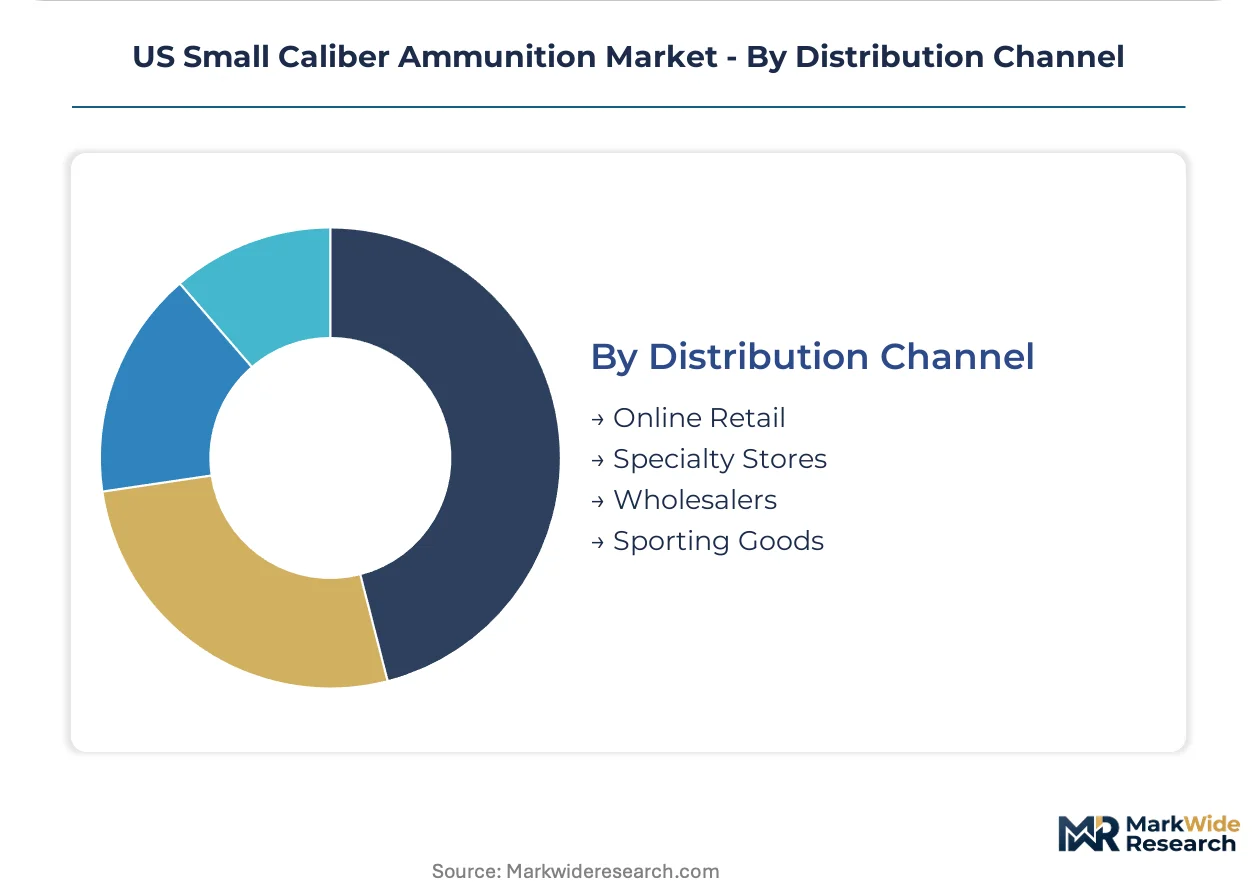
- Online Retail:This channel leverages e-commerce platforms for direct sales to consumers, offering convenience and broader product access, where legally permissible. Expanding online direct-to-consumer sales models allows manufacturers to capture higher margins and build direct relationships with end-users.
- Specialty Stores:These retail outlets focus on firearms and ammunition, providing expert advice, niche product selections, and a personalized shopping experience. They cater to experienced shooters and hunters seeking specific performance characteristics or specialized equipment.
- Wholesalers:Wholesalers act as intermediaries, distributing large volumes of ammunition to various retail outlets and smaller dealers.
- Sporting Goods:Large sporting goods chains offer a wide array of ammunition alongside other outdoor and recreational equipment, targeting a broad consumer base.
Access to the broadest customer base is achieved through Sporting Goods; the most dynamic growth path is through Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration in the US small caliber ammunition market increasingly shifts toward the civilian end-user base. This structural change emphasizes commercial distribution networks and consumer brand strength for manufacturers. Specific US states exhibit distinct demand patterns influenced by cultural practices and regulatory environments.
Texas
Texas drives consistent volume demand for training and competition-grade ammunition through its robust sports shooting participation. The US Bureau of Alcohol, Tobacco, Firearms and Explosives (ATF) governs commerce and licensing for ammunition sales within the state. Major distribution hubs in Dallas-Fort Worth facilitate the flow of ammunition to a wide consumer base.
Florida
Florida exhibits high engagement in recreational shooting sports, contributing significantly to civilian consumption. State-level wildlife management policies expanding hunting seasons directly increase specialized hunting cartridge consumption. Orlando and Tampa areas host numerous shooting ranges and retail outlets catering to recreational shooters.
California
California faces environmental regulations and shooter preferences pushing the adoption of non-toxic projectiles and primers. The US Environmental Protection Agency (EPA) scrutinizes lead's environmental impact at shooting ranges, particularly on federal lands across California. Specialized manufacturers in the Los Angeles and Bay Area regions focus on developing and distributing lead-free ammunition solutions.
Midwest
The Midwest region, encompassing states like Illinois and Michigan, sustains a broad presence for both civilian hunting and sport shooting activities. Sporting Arms and Ammunition Manufacturers' Institute (SAAMI) standards guide product safety and interoperability for manufacturers with facilities here. East Alton, Illinois, notably hosts significant ammunition manufacturing operations, supplying national demand.
US Small Caliber Ammunition Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue high-performance niche segments and environmentally compliant solutions. The US small caliber ammunition market exhibits a tiered structure, with diversified conglomerates alongside specialized manufacturers. Key strategic archetypes include large-scale integrators, niche product specialists, and government contract-focused suppliers. Dominant competitive moves involve portfolio diversification through brand acquisition and continuous technology development for new materials.
Specialists in high-performance and niche hunting rounds, like Hornady Manufacturing Company, exemplify a focus on ballistic precision for specific applications. Vista Outdoor Operations LLC represents the strategy of leveraging a broad portfolio of consumer brands to capture share in sports shooting. Winchester Ammunition maintains a broad presence across both civilian and law enforcement segments, indicating a balanced market approach.
| Leading Market Players |
|---|
| FN Herstal |
| Hornady Manufacturing Company |
| Northrop Grumman Corporation |
| Winchester Ammunition |
| Remington Ammunition |
| Olin Corporation |
| Vista Outdoor Operations LLC |
| General Dynamics Ordnance and Tactical Systems |
| Nammo AS |
Cost & Logistics Intelligence
Lead-free primer development reshapes ammunition cost economics by requiring new materials and production processes. This shift simultaneously concentrates supply in specialized component manufacturers.
Pricing Analysis
Volume-driven civilian sales operate on narrow margins, contrasting with higher-margin specialized government contracts. The dominant pricing structure is per-unit transactional, with some long-term contracts for government end-users. Price differentiation stems from specialized ballistic performance, brand recognition, and specific application like match-grade ammunition. Raw material volatility exerts significant margin pressure on manufacturers, particularly within the price-sensitive civilian segment.
Supply Chain Analysis
Domestic-content mandates within US defense contracts reshape sourcing for key components like primers, concentrating manufacturing in the US, notably East Alton, Illinois. The supply chain draws from critical raw materials including copper, lead, and zinc. Primer supply bottlenecks represent a structural risk, limiting overall production capacity. Distribution runs through wholesalers, specialty stores, and growing online retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US small caliber ammunition market presents a consolidation play, as high capital expenditure for production modernization pressures smaller players. Complex regulatory adherence further strains companies lacking scale.
For Market Incumbents: Anticipate continued raw material volatility by securing long-term supply agreements for copper and zinc. Diversify product portfolios to mitigate the impact of cyclical government contracts, leveraging strong consumer brand recognition for civilian sports shooting. Invest in lead-free primer R&D to meet evolving environmental regulations, positioning for future market shifts. Modernize aging production lines to improve efficiency and accommodate new materials.
For New Entrants and Emerging Players: Launch via direct-to-consumer online channels to capture higher margins in niche segments. Target the growing demand for subsonic ammunition, optimizing lines for recreational shooting with suppressors. Develop smart ammunition with data-logging functions for specialized law enforcement training applications. Focus on environmentally compliant lead-free solutions for states with strict regulations like California, leveraging material science advancements.
For Investors and Strategic Acquirers: Exit pathways concentrate in niche product specialists with proprietary technology or strong commercial distribution networks. The market offers long-term viability driven by stable civilian sports shooting and critical military training needs. Target manufacturers innovating in lead-free materials or high-performance, match-grade ammunition. The signal to watch is any significant expansion in primer manufacturing capacity, indicating broader industry growth potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Lead-Free Product Development | Addresses environmental regulations and consumer preferences for non-toxic materials. |
| Direct-to-Consumer Channel Integration | Captures higher margins and builds direct relationships with end-users. |
| Production Line Modernization | Improves manufacturing efficiency and accommodates new material technologies. |
| Brand Portfolio Diversification | Mitigates revenue volatility from cyclical government procurement contracts. |
| Subsonic Ammunition Optimization | Capitalizes on rising popularity of firearm suppressors for recreational shooting. |
Research Approach
Document review covered ATF reports, SAAMI standards, EPA guidelines, and relevant trade publications, complemented by interviews. Primary research engaged ammunition manufacturers, distributors, sport shooting organization representatives, and law enforcement procurement officers. This approach combined bottom-up market sizing with top-down validation. The analysis triangulated insights from industry stakeholders against published data.
Historical data was cross-referenced against expert panel input to project market trajectories over the projection horizon. The analytical framework modeled segmentation across product type, application, end user, and distribution channel. Compound Annual Growth Rates (CAGRs) were derived from a synthesis of historical trends and projected participation rates in sports shooting. Raw material price forecasts also informed the model.
The model assumes a particular technology adoption path; alternative pathways for polymer-cased ammunition or lead-free components would alter the outlook. Forecasts reflect assumptions regarding future ATF regulatory shifts and raw material supply stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Sports Shotgun Market
Weapons and Ammunition
Military Fire Control Systems Market
Weapons and Ammunition
Guided Munitions Market
Weapons and Ammunition
France Nuclear Bombs and Missiles Market
Weapons and Ammunition
Vehicle Mounted Anti-Tank Missile System Market
Weapons and Ammunition
Smoke Grenade Market
Weapons and Ammunition
Small Arms Market
Weapons and Ammunition
APAC Ballistic Missile Market
Weapons and Ammunition
Shotgun and Rifles Market
Weapons and Ammunition
Asia-Pacific Nuclear Bombs and Missiles Market
Weapons and Ammunition
Man-Portable Rocket Launcher Market
Weapons and Ammunition
Americas Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Nuclear Bombs and Missiles Market
Weapons and Ammunition
Middle East and Africa Ammunition Market
Weapons and Ammunition
Airborne Weapon System Market
Weapons and Ammunition
Automatic Weapons Market