
 Annular Cooler Market | 2026-2036
Annular Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Annular Cooler Market Analysis
Aftermarket service revenue is reshaping profit pools across the annular cooler supply chain. Metso Outotec leverages its global installed base to capture recurring refurbishment contracts. Northern Heavy Industry Group Co., Ltd. anchors its position through captive steel-plant relationships in Liaoning Province. MCC North Engineering Technology Co., Ltd. differentiates via integrated engineering-procurement-construction capabilities for greenfield sintering lines.
An annular cooler is a rotating drum apparatus that recovers sensible heat from hot sintered ore through controlled air circulation, typically operating at discharge temperatures between 120°C and 150°C with diameters spanning 2.5 to 5 meters; its primary purpose is to cool agglomerated ferrous feedstock while preheating combustion air for upstream sintering machines. Air-cooled configurations dominate existing installations due to lower capital intensity, though hybrid systems are gaining traction where water scarcity constrains operations. Industrial cooling applications anchor current demand volumes, while power generation end users represent an emerging margin pool as waste-heat recovery integrations spread.
China's MEE enforces GB 28662 emissions limits on sintering plants, directly mandating heat recovery efficiency upgrades that expand annular cooler replacement cycles. Japan's METI promotes JIS-standard equipment retrofits through energy conservation subsidies, tightening technical compliance thresholds for imported systems. South Korea's MFDS-aligned industrial safety protocols require sensor-integrated monitoring architectures, reshaping procurement specifications for control system technology tiers. Stakeholders must weigh captive maintenance investments against third-party service outsourcing as regulatory compliance costs escalate across Northeast Asian steel corridors.
Market Dynamics
China's dual carbon goals and GB 28662 emissions limits are compressing replacement cycles for legacy annular coolers, forcing steel producers toward heat-recovery-integrated systems that preheat combustion air while cutting particulate discharge.
Growth Catalysts
- GB 28662 enforcement:China's MEE mandates heat recovery efficiency upgrades at sintering plants, expanding equipment replacement demand across Liaoning and Hebei steel corridors.
- Sintering capacity expansion:Agglomerated ferrous feedstock processing volumes are climbing in East Asian steel manufacturing, directly pulling annular cooler installations.
- Sensor-integrated monitoring:South Korea's MFDS-aligned safety protocols require real-time temperature and vibration tracking, accelerating control system retrofits.
Market Restraints
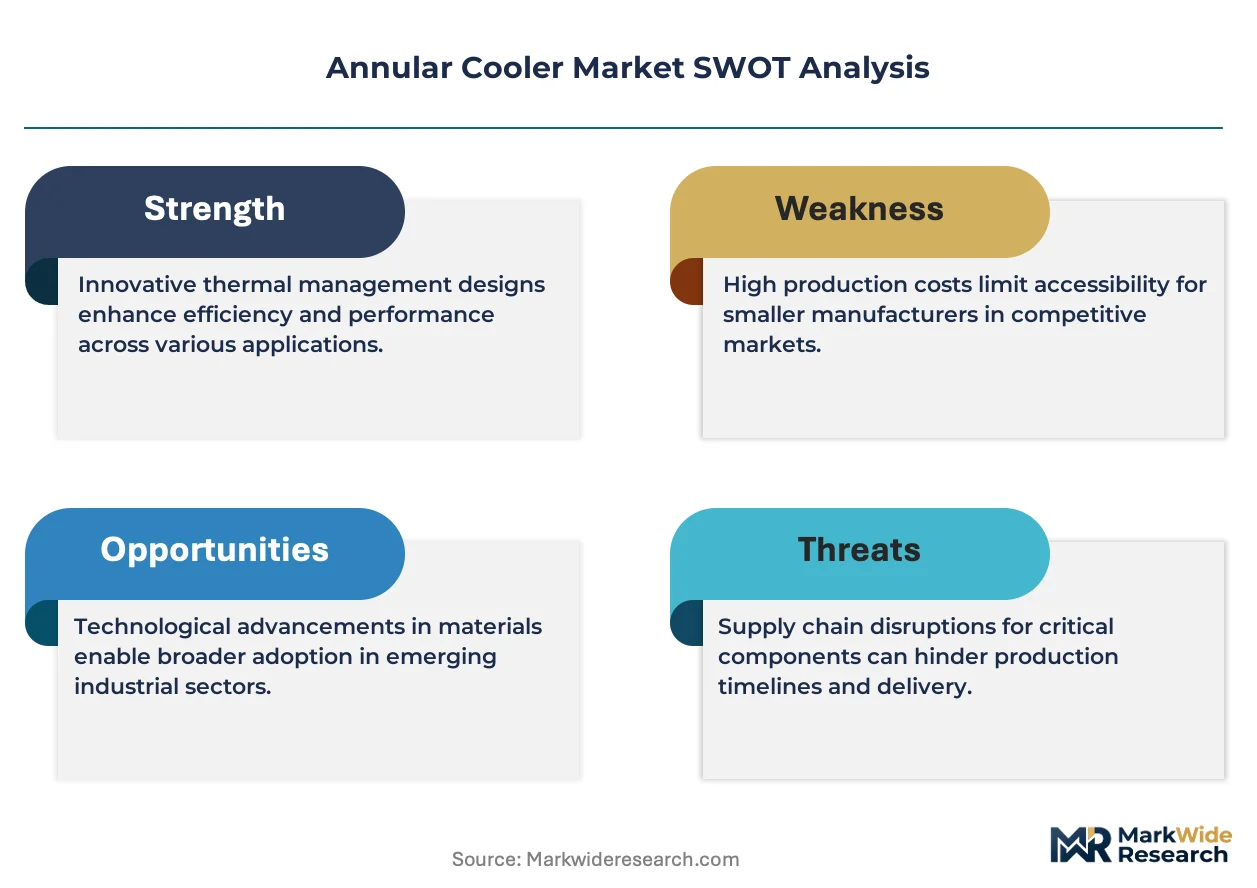
- Refractory material cost volatility:Magnesia-chrome brick prices fluctuate with Chinese export quotas, squeezing margins on maintenance contracts.
- Supply concentration in Liaoning:Heavy fabrication capacity clusters around Shenyang and Dalian, creating geographic vulnerability to regional logistics disruptions.
- Water-cooled system substitution:Where water scarcity constrains operations, hybrid cooling architectures displace pure air-cooled configurations.
Strategic Opportunities
- Waste-heat power generation:Organic Rankine cycle integrations at sintering plants open margin pools beyond basic cooling equipment sales.
- Japan's METI subsidies:JIS-standard retrofit incentives create compliance-driven replacement demand at aging integrated steel mills.
- Aftermarket service unbundling:Third-party refurbishment providers are capturing recurring revenue streams previously held by original equipment suppliers.
Industry Challenges
- Skilled refractory technician scarcity:Specialized lining installation expertise concentrates at legacy state-owned enterprises, constraining expansion timelines.
- Legacy DCS integration friction:New sensor architectures must interface with decades-old distributed control systems at Japanese and Korean steel plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Annular Cooler Market |
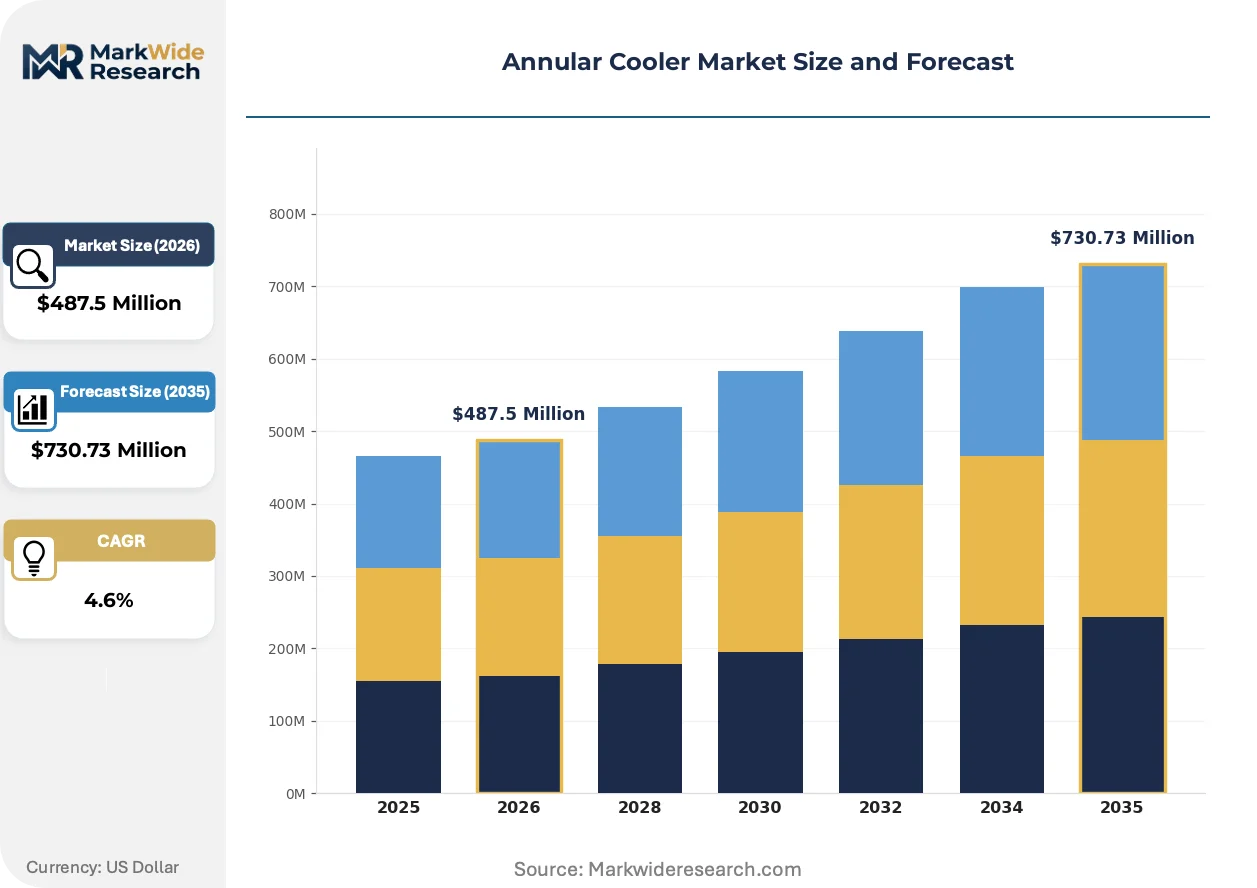
| Market Size in 2026 | $487.5 Million |
| Market Size in 2035 | $730.73 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Evaporative, Hybrid Application: Industrial Cooling, HVAC Systems, Power Generation, Marine End User: Manufacturing Facilities, Power Plants, Marine Operators, Commercial Buildings Technology: Heat Exchangers, Pumps, Control Systems, Sensors |
| Companies Covered | MCC North Engineering Technology Co., Ltd., Northern Heavy Industry Group Co., Ltd., Metso Outotec, Hebei Huatong Heavy Industry Machinery Manufacturing Co., Ltd., Chaoyang Heavy Machine Metallurgical Industry Co., Ltd., JP Steel Plantech Co., Tangshan Ruitai Machinery Co., Ltd., AGICO, Hunan Zhongye Changtian Heavy Industry Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Annular Cooler Market Emerging Trajectories
Digital instrumentation and regulatory tightening are converging to transform annular cooler specifications, with steel producers demanding predictive maintenance capabilities and emissions-compliant heat recovery as baseline procurement criteria.
Edge computing architectures with embedded thermocouple arrays are digitizing temperature mapping across cooler annular segments. Japanese integrated steel mills are piloting these systems at Kobe and Chiba facilities. Real-time thermal profiling is digitizing maintenance scheduling, compressing unplanned downtime windows from weeks to days.
China's GB standards on industrial emissions are tightening particulate and thermal efficiency thresholds for sintering operations. Steel producers in Tangshan and Handan must document heat recovery rates above mandated minima to maintain operating licenses. Equipment vendors are responding with integrated air-preheater designs that bundle compliance documentation into delivery packages.
Service contracting is fragmenting as steel producers unbundle aftermarket work from original equipment procurement. Chinese state-owned mills now tender refurbishment and spare parts supply separately from capital equipment purchases. This pattern is most visible in Liaoning Province, where Northern Heavy Industry Group faces independent competitors for maintenance contracts at captive steel plants.
Annular Cooler Market Segmentation
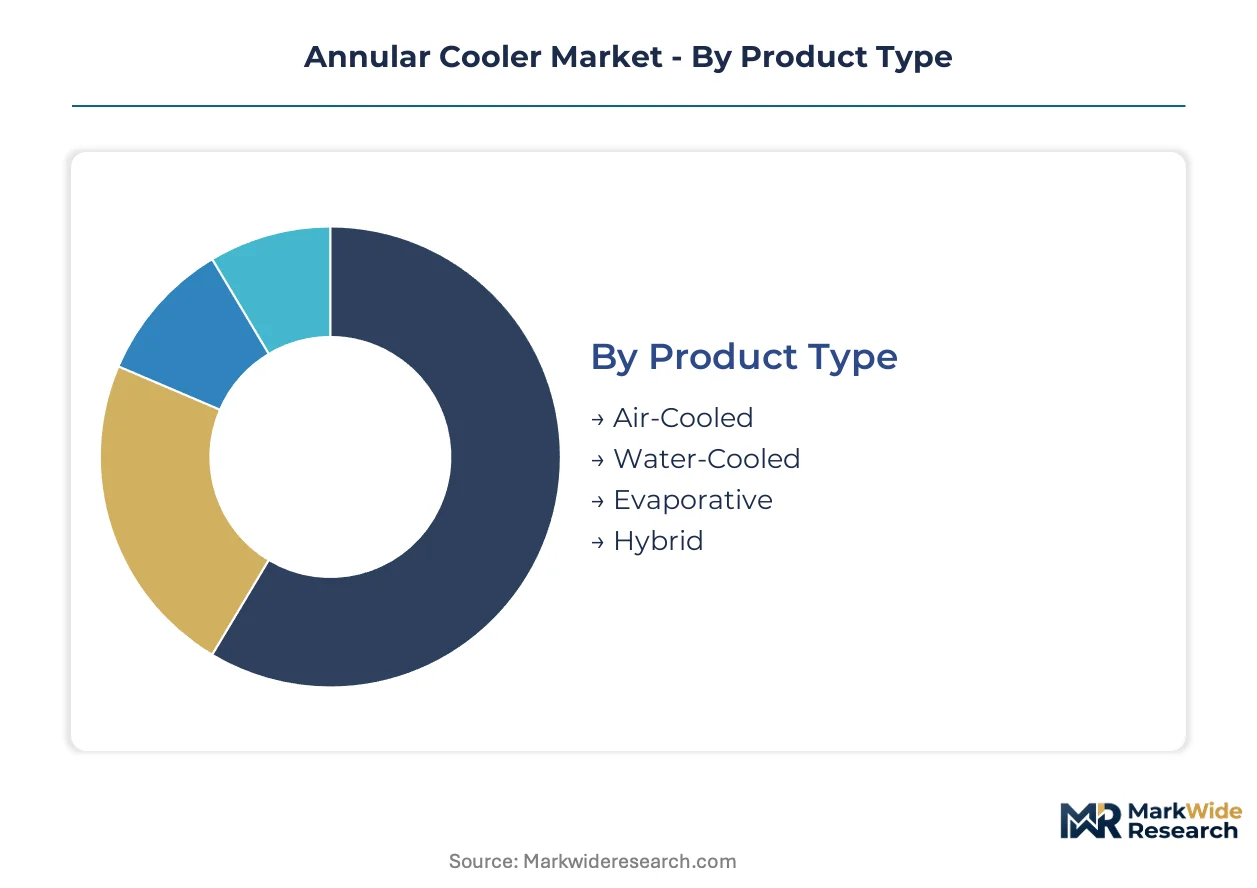
Annular cooler procurement patterns diverge sharply across cooling architectures, end-use applications, and technology tiers. Steel producers in East Asia prioritize heat recovery integration and emissions compliance, while marine operators and commercial buildings emphasize footprint constraints and energy efficiency.
Product Type:
Cost tier positioning separates capital-intensive configurations from maintenance-heavy alternatives in procurement decisions.
- Air-Cooled:Dominant configuration uses forced convection through finned heat exchange surfaces, eliminating water treatment infrastructure. Demand concentrates at integrated steel mills in China's Hebei and Liaoning corridors where MEE's GB 28662 particulate limits favor dry cooling to avoid wastewater discharge compliance.
- Hybrid:Combines air-cooled primary stages with evaporative trim cooling, optimizing for water-scarce environments. Expanding most quickly at sintering plants in South Korea's Pohang and Gwangyang steel complexes where MFDS safety protocols mandate redundant thermal management.
- Water-Cooled:Closed-loop shell-and-tube designs with cooling tower integration.
- Evaporative:Direct contact cooling using atomized water injection into air streams.
Air-Cooled commands the established base. The steepest expansion runs through Hybrid.
Application:
End-use thermal load characteristics dictate cooler sizing, materials selection, and control system complexity.
- Industrial Cooling:Sintered ore cooling at discharge temperatures of 120°C to 150°C requires magnesia-chrome refractory linings and controlled air circulation rates. Steel manufacturing in Japan's Chiba and Kobe works drives specification intensity through METI energy conservation retrofit subsidies.
- Power Generation:Waste-heat recovery integrations preheat combustion air or feed Organic Rankine cycle systems. Gaining share fastest at captive power plants attached to Chinese state-owned steel enterprises seeking dual carbon compliance documentation.
- HVAC Systems:District cooling and large-scale building climate control applications.
- Marine:Compact footprint cooling for engine exhaust and auxiliary systems.
Industrial Cooling anchors volume concentration. Power Generation shows the strongest margin expansion trajectory.
End User:
Customer scale and captive maintenance capabilities reshape procurement channel preferences and service contracting terms.
- Manufacturing Facilities:Integrated steel mills with in-house refractory maintenance teams favor unbundled equipment procurement, separating capital purchases from aftermarket service. Tangshan and Handan producers leverage state-owned status to tender refurbishment contracts independently of original equipment vendors.
- Power Plants:Utilities and industrial captive generators prioritize waste-heat recovery economics and long-term efficiency guarantees.
- Marine Operators:Shipyards and fleet operators demand space-optimized cooling with classification society certification.
- Commercial Buildings:District energy systems and large-scale HVAC installations.
Manufacturing Facilities dominate equipment replacement cycles. Power Plants are pulling technology upgrade intensity fastest.
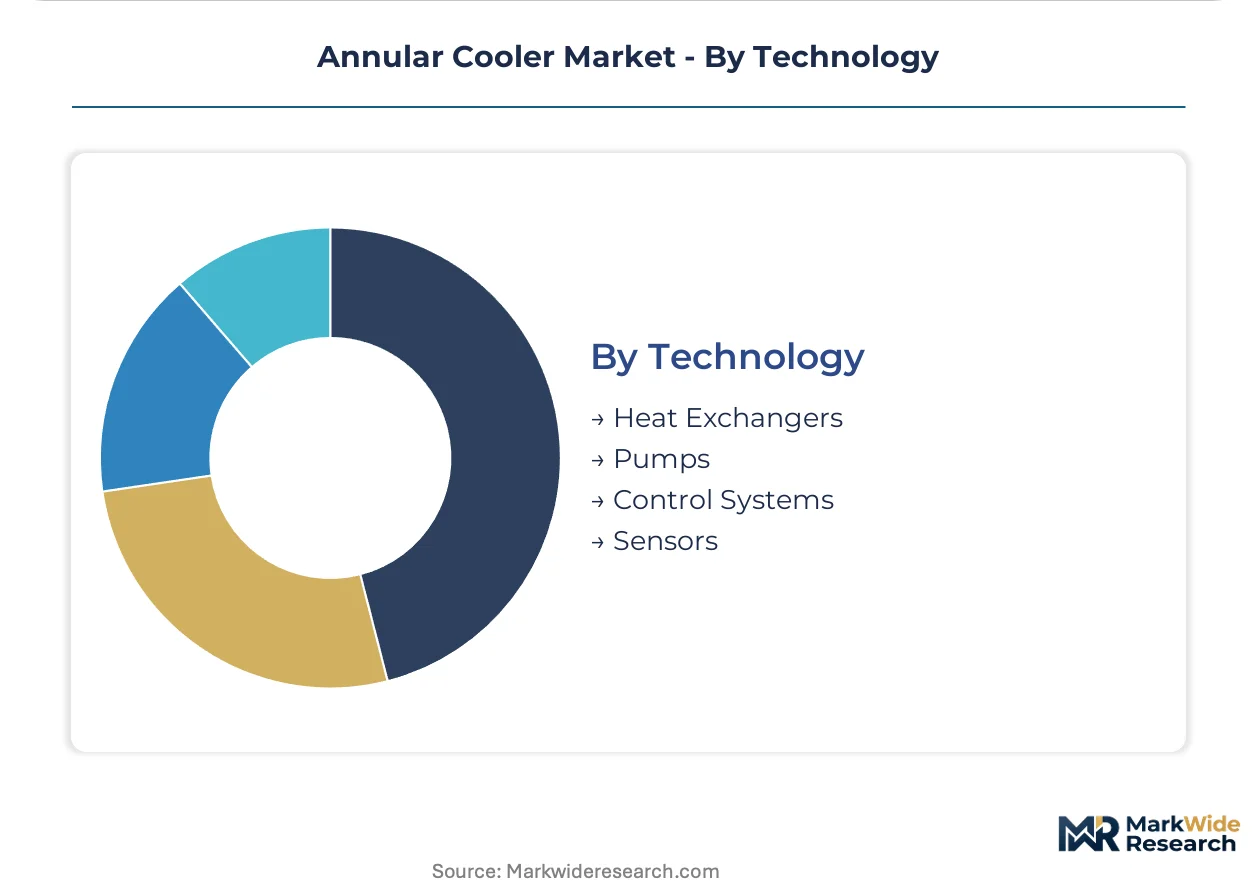
Technology:
Component-level specification depth determines system integration complexity and regulatory compliance documentation.
- Control Systems:Distributed control architectures with legacy DCS integration capabilities anchor procurement at Japanese and Korean steel plants. Real-time temperature mapping through edge computing nodes is climbing fastest where MFDS-aligned safety protocols mandate predictive maintenance architectures.
- Sensors:Thermocouple arrays and vibration monitors enable condition-based maintenance scheduling.
- Heat Exchangers:Finned tube bundles and plate configurations for air-to-air or air-to-fluid heat transfer.
- Pumps:Forced draft fans and coolant circulation equipment.
Control Systems concentrate value capture. Sensors are expanding most quickly through retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fabrication capacity clusters heavily in Liaoning Province and Hebei Province, creating geographic concentration around Shenyang, Dalian, Tangshan, and Handan. Steel producers across East Asia source annular coolers from these manufacturing hubs while adapting equipment specifications to local emissions enforcement.
China
GB 28662 particulate limits from MEE are compressing replacement cycles at Tangshan and Handan steel mills. Dual carbon documentation requirements force heat-recovery-integrated system upgrades. Liaoning Province fabricators in Shenyang and Dalian dominate domestic supply while exporting to Southeast Asian sintering projects.
Japan
METI energy conservation subsidies accelerate JIS-standard retrofits at aging Chiba and Kobe integrated steel works. Real-time thermal profiling pilots are digitizing maintenance scheduling at these facilities. Equipment procurement emphasizes legacy DCS integration capabilities for decades-old plant control architectures.
South Korea
MFDS-aligned safety protocols mandate sensor-integrated monitoring at Pohang and Gwangyang steel complexes. Hybrid cooling configurations expand fastest here where water scarcity constraints meet redundant thermal management requirements. Control system retrofits concentrate value capture in this regulatory environment.
India
BIS certification requirements and PLI scheme incentives for domestic steel capacity are pulling annular cooler demand toward integrated sintering lines in Odisha and Jharkhand. State-owned steel enterprises tender equipment separately from aftermarket service, fragmenting procurement patterns.
Germany
EU Green Deal industrial decarbonization targets and REACH chemical compliance reshape specifications for European steel imports. Engineering-procurement-construction capabilities from Asian vendors compete with domestic fabricators for greenfield sintering modernization projects in the Ruhr industrial corridor.
Annular Cooler Market Vendor Landscape
State-affiliated heavy machinery conglomerates and independent engineering specialists split the market along procurement channel preferences. Captive steel-plant relationships in Liaoning Province anchor volume concentration for domestic Chinese demand. Three strategic archetypes dominate: integrated EPC contractors bundling greenfield sintering lines, aftermarket service unbundlers capturing refurbishment contracts separately from capital sales, and refractory-technology hybrids leveraging lining expertise. Competitive moves center on geographic expansion into Southeast Asian steel corridors and technology licensing for waste-heat recovery integrations.
Within the state-affiliated tier, MCC North Engineering Technology Co., Ltd. and Northern Heavy Industry Group Co., Ltd. occupy positions shaped by captive relationships with steel producers in Liaoning Province. Metso Outotec represents the aftermarket-focused archetype, leveraging global installed base presence for recurring service revenue. Hebei Huatong Heavy Industry Machinery Manufacturing Co., Ltd. and Tangshan Ruitai Machinery Co., Ltd. exemplify the Hebei-based fabrication cluster serving domestic replacement demand. JP Steel Plantech Co. anchors Japanese-origin positioning in JIS-standard compliance markets.
| Leading Market Players |
|---|
| MCC North Engineering Technology Co., Ltd. |
| Northern Heavy Industry Group Co., Ltd. |
| Metso Outotec |
| Hebei Huatong Heavy Industry Machinery Manufacturing Co., Ltd. |
| Chaoyang Heavy Machine Metallurgical Industry Co., Ltd. |
| JP Steel Plantech Co. |
| Tangshan Ruitai Machinery Co., Ltd. |
| AGICO |
| Hunan Zhongye Changtian Heavy Industry Technology Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Liaoning Province's fabrication cluster around Shenyang and Dalian concentrates heavy machinery capacity, granting domestic suppliers pricing leverage over steel producers in Hebei and Jiangsu who lack alternative sourcing within compliant lead times. GB 28662 enforcement compresses replacement cycles, forcing buyers to absorb premium pricing for heat-recovery-integrated configurations while refractory material volatility squeezes margin pools across maintenance contracts.
Pricing Analysis
GB 28662 dictates the pricing tier structure across China's annular cooler procurement landscape. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated predictive maintenance systems from basic air-cooled configurations and refurbished legacy units. Price differentiation centers on certification grade against MEE emissions thresholds and after-sales service bundling. Cost compression in standard tiers is intensifying because magnesia-chrome brick export quotas from China disrupt maintenance contract economics. State-owned steel mills in Tangshan exhibit highest price sensitivity through unbundled tendering, while Japanese integrated works at Chiba and Kobe show lowest sensitivity due to METI subsidy absorption.
Supply Chain Analysis
Heavy fabrication capacity rests with contract manufacturers clustered in Liaoning Province and Hebei Province, supplemented by specialized engineering-procurement-construction integrators in Beijing and Tianjin. Geographic supply concentration centers on China, Japan, and South Korea for core equipment, with secondary component sourcing from Germany for precision control systems. Raw material dependencies include magnesia-chrome refractory brick, high-grade structural steel plate, and thermocouple sensor arrays. Single-source vulnerability runs through Liaoning's Shenyang-Dalian corridor where regional logistics disruptions cascade into delivery delays. Distribution runs through direct OEM relationships with integrated steel mills, fragmented third-party refurbishment providers, and EPC contractors bundling greenfield sintering lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steel manufacturing's capital expenditure cycle is recovering from trough conditions, with sintering capacity expansion in East Asian corridors pulling equipment replacement demand through regulatory compliance mandates rather than discretionary upgrades.
For Market Incumbents: Insulate installed base relationships by embedding predictive maintenance architectures before third-party service unbundlers capture refurbishment contracts. Deepen backward integration into refractory lining supply to offset magnesia-chrome price volatility from Chinese export quota shifts. Prioritize certification investment against evolving GB standards to maintain procurement gatekeeper status at state-owned steel mills.
For New Entrants and Emerging Players: Establish a beachhead in aftermarket service unbundling at Liaoning Province steel plants where Northern Heavy Industry Group faces independent competition for maintenance contracts. Target power generation waste-heat recovery integrations as the most penetrable segment, where Organic Rankine cycle expertise creates differentiation from legacy cooling-focused incumbents. Pursue technology licensing partnerships with Japanese engineering houses to accelerate JIS-standard compliance credibility.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors control system specialists with edge computing architectures that interface with legacy DCS infrastructure at aging Japanese and Korean steel works. Long-term viability hinges on regulatory compliance automation rather than commodity cooling equipment fabrication. Acquisition target archetype: sensor-integrated monitoring providers with MFDS-aligned safety protocol certifications. Watch GB 28662 enforcement intensity at Tangshan and Handan mills as inflection indicator for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refractory Supply | Magnesia-chrome brick sourcing control offsets Chinese export quota volatility squeezing maintenance margins. |
| Sensor-Integrated Control System Launch | MFDS-aligned safety protocols at Pohang and Gwangyang complexes mandate predictive maintenance architectures. |
| Waste-Heat Recovery Technology Licensing | Organic Rankine cycle integrations open margin pools beyond basic cooling at Chinese dual carbon compliance projects. |
| Aftermarket Service Unbundling | Independent refurbishment contracts fragment procurement patterns previously held by original equipment vendors. |
| JIS-Standard Certification Investment | METI subsidies at Chiba and Kobe works accelerate compliance-driven replacement demand for certified systems. |
Methodological Framework
A standing panel of maintenance directors at integrated steel mills, plant engineers specifying sintering line upgrades, OEM procurement teams evaluating equipment bids, and aftermarket service heads managing refurbishment contracts provided ongoing calibration across primary fieldwork. Secondary validation drew from MEE GB standard filings, METI energy conservation subsidy disclosures, customs trade data on refractory material flows, and SEC filings of listed heavy machinery suppliers. Bottom-up equipment shipment tracking and top-down steel capacity expansion modeling were triangulated against regulatory compliance timelines.
Scenario-bracketing framed analytical approach across the projection horizon, with segmentation dimensions spanning cooling architecture type, end-use application intensity, and technology tier depth. CAGRs were derived from installed base replacement cycle compression under emissions enforcement and greenfield capacity addition pipelines. Industry-specific forecast inputs included sintering machine utilization rates at Chinese state-owned enterprises and METI retrofit subsidy budget trajectories.
Stress conditions across refractory material price bands, logistics disruption severity in Liaoning Province, and GB standard enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory compliance timelines and steel demand elasticity. Quarterly review of MEE inspection schedules at Tangshan mills and METI subsidy allocation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Temporary Power and Cooling Solutions Market
Cooling Systems
Microchannel Heat Exchanger Market
Cooling Systems
Global Evaporative Cooling Market
Cooling Systems
Aftercoolers Market
Cooling Systems
Cooling Tower Rental Market
Cooling Systems
Solar Cold Room Market
Cooling Systems
Chilled Water System Market
Cooling Systems
Low Temperature Radiators Market
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
Water Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Global Chiller Market
Cooling Systems
Fluid Coolers Market
Cooling Systems
Global Evaporative Cooler Market
Cooling Systems
Global Air Cooled Condenser Market
Cooling Systems
Radiant Cooling Systems Market
Cooling Systems
Flue Gas Coolers Market