
 Global Magnetic Refrigeration Market | 2026-2036
Global Magnetic Refrigeration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Magnetic Refrigeration Market Intelligence
A transition from single-source R&D partnerships to multi-source procurement for magneto-caloric materials is expanding the addressable market for component suppliers. This shift allows large-scale manufacturers like Haier Smart Home Co., Ltd to explore integration into commercial cooling systems. Meanwhile, specialist firms such as Kiutra GmbH sustain their focus on high-performance cryogenic applications for research institutions. Danfoss AS positions itself as a critical supplier of system-level components, navigating the needs of diverse end users.
Magnetic refrigeration is a cooling technology that utilizes the magneto-caloric effect, a phenomenon where certain materials heat up when magnetized and cool down when demagnetized. This process, often implemented in an Active Magnetic Regeneration (AMR) cycle, provides cooling without the use of traditional vapor-compression refrigerants. The Magneto-Caloric technology segment currently leads development efforts due to its higher efficiency potential. While residential and commercial cooling represent long-term targets, applications in specialized medical equipment and cryogenics are seeing initial commercial adoption.
Regulatory frameworks are a primary accelerant for market development. The EU's F-Gas Regulation and the US EPA's directives under the SNAP program create market access challenges for conventional refrigerants, thereby incentivizing alternatives. Similarly, China's national dual carbon goals encourage the adoption of high-efficiency technologies. The pace of commercialization now depends on achieving cost-parity and long-term reliability in magneto-caloric alloys for mass-market applications.
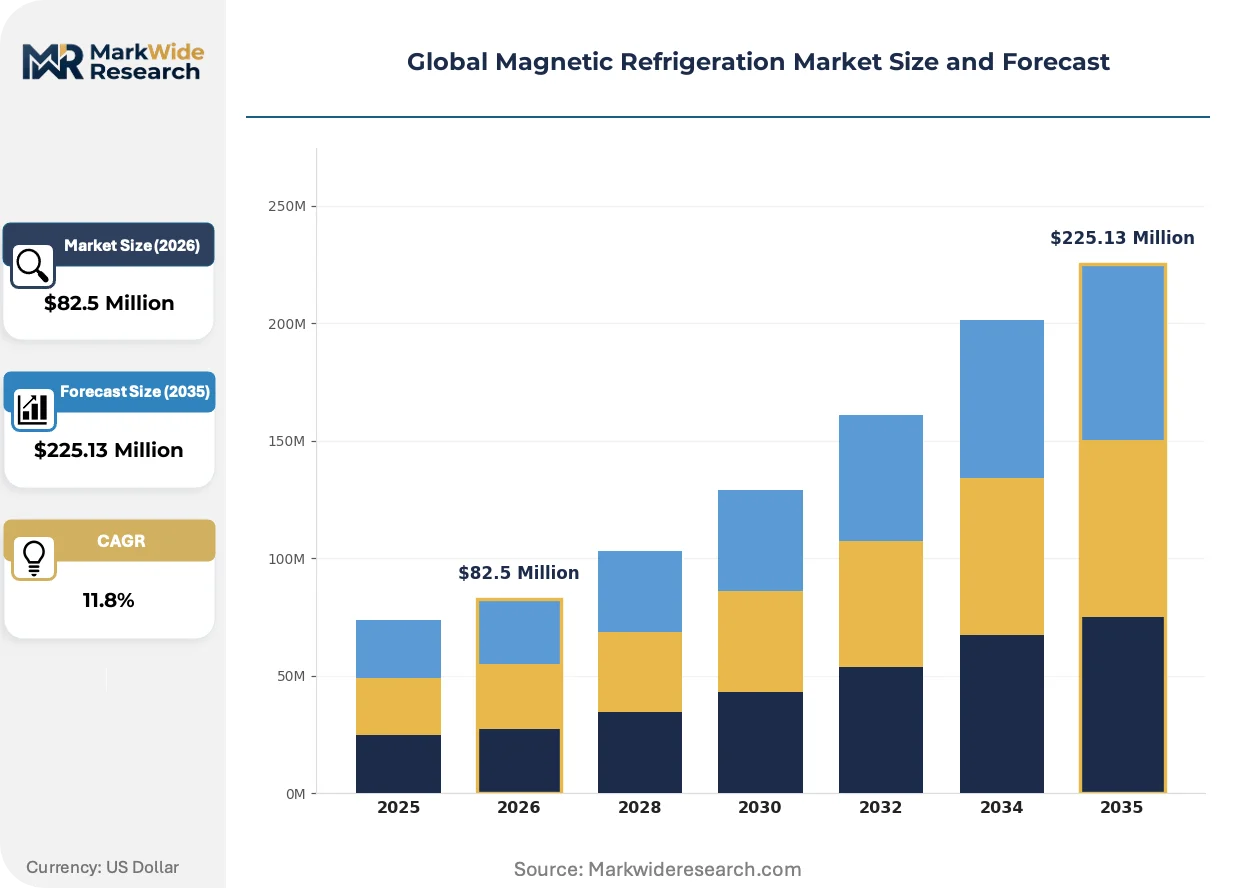
Market Dynamics
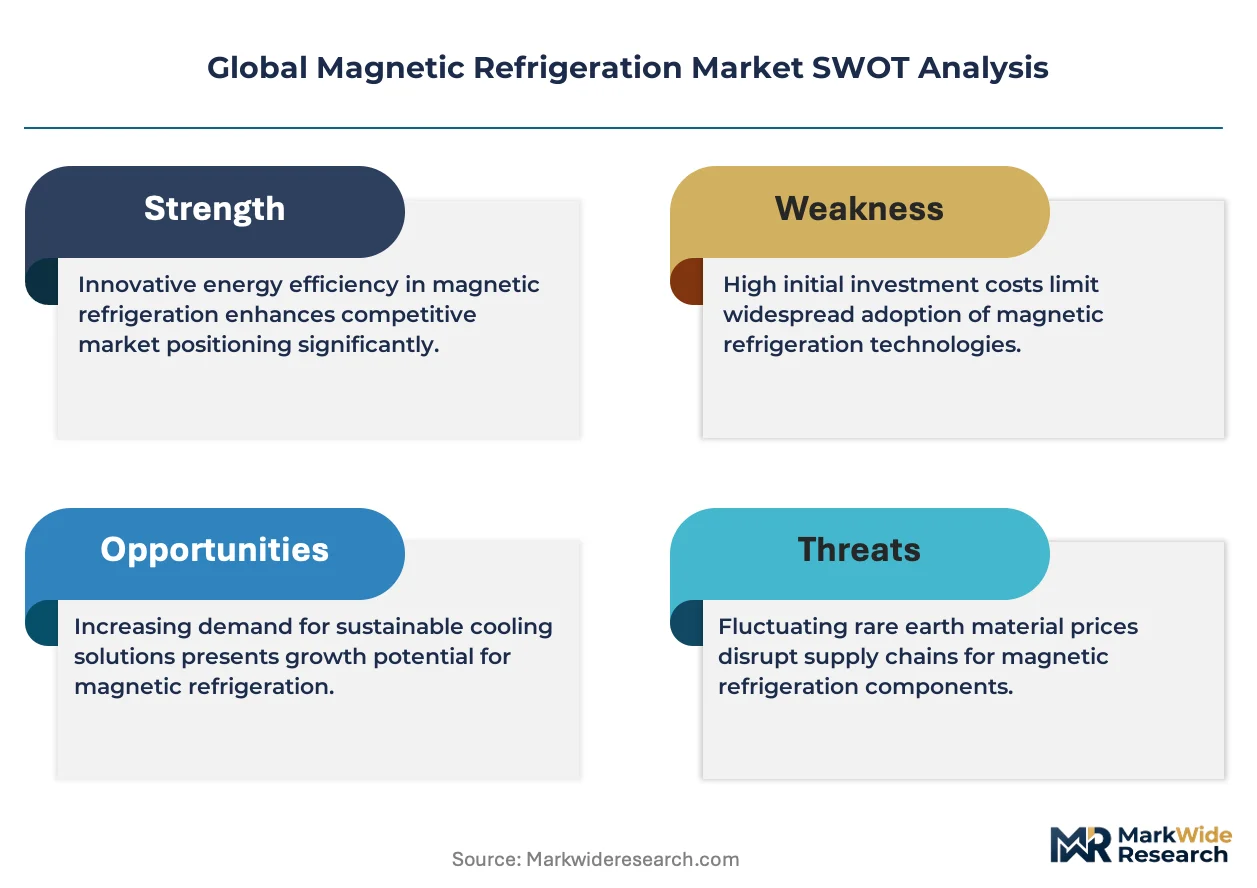
Regulatory pressure to phase out hydrofluorocarbon refrigerants is the central force creating market opportunities for magnetic refrigeration. The EU's F-Gas Regulation, in particular, acts as a powerful catalyst, compelling industries to invest in alternative cooling technologies for compliance.
Growth Catalysts
- Regulatory Mandates:Strict regulations like the EU's F-Gas Regulation and directives under the US EPA's SNAP program are phasing out conventional refrigerants, creating a direct market need for alternative technologies like magnetic refrigeration.
- Technology Maturation:Advances in magneto-caloric materials, particularly gadolinium-based alloys, are improving efficiency and operational stability, making the technology viable for specialized applications such as medical equipment cooling.
- Industrial Application Pull:Demand from Germany's advanced manufacturing and research sectors provides a concentrated base for early adoption and system refinement, especially in high-performance cryogenic and scientific instrumentation.
Market Restraints
- Material Cost:The high cost of rare-earth elements like gadolinium, which are essential for high-performance magneto-caloric alloys, presents a significant economic barrier to cost-parity with conventional vapor-compression systems.
- Supply Chain Concentration:The global supply of rare-earth metals is heavily concentrated in China, creating geopolitical and price volatility risks for magneto-caloric material manufacturers dependent on these inputs.
- Technical Performance Gaps:Magnetic refrigeration systems currently exhibit a narrower optimal operating temperature range and lower cooling power density in certain contexts, limiting their application scope compared to mature technologies.
Strategic Opportunities
- New Geographic Markets:The high-tech electronics and automotive manufacturing sectors in Japan and South Korea represent significant, underpenetrated markets for specialized, high-efficiency cooling solutions in industrial processes.
- Emerging Applications:Data center cooling is a promising future application, where the high energy efficiency of magnetic refrigeration can offer substantial operational cost savings and help meet sustainability targets.
- Policy-Driven Expansion:China's national dual carbon goals create strong government-backed incentives for adopting high-efficiency industrial technologies, positioning magnetic refrigeration for potential large-scale deployment.
Industry Challenges
- Lack of Standardization:The absence of universally accepted industry standards for testing and certifying the performance and reliability of Active Magnetic Regeneration (AMR) components slows broader commercial acceptance and complicates procurement.
- System Integration Complexity:Integrating magnetic refrigeration units into existing product architectures designed for vapor-compression systems requires significant and costly re-engineering, delaying adoption by large-scale manufacturers.
- Specialized Talent Scarcity:A skills gap exists for engineers who possess the cross-disciplinary expertise in both materials science for alloy development and mechanical engineering for AMR cycle design and optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Magnetic Refrigeration Market |
| Market Size in 2026 | $82.5 Million |
| Market Size in 2035 | $225.13 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Active Magnetic Regeneration, Thermo-Magnetic, Electro-Caloric, Elastocaloric, Magneto-Caloric Product Type: Residential Cooling, Commercial Cooling, Industrial Cooling, Medical Equipment, Automotive Systems Application: Air Conditioning, Refrigerators, Cold Storage, Cryogenics, Heat Pumps End User: Consumer Electronics Brands, Food Processing Units, Pharmaceutical Manufacturers, Vehicle Manufacturers, Research Institutions |
| Companies Covered | Camfridge Ltd, Cooltech Applications, Haier Smart Home Co., Ltd, Magnoric Inc., Kiutra GmbH, Astronautics Corporation of America, Ubiblue, Danfoss AS, VACUUMSCHMELZE GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Magnetic Refrigeration Market Strategic Shifts & Innovations
Development is shifting from pure laboratory research toward creating commercially viable components and systems. This transition is driven by parallel progress in magneto-caloric material performance and mounting regulatory pressure against incumbent refrigerant technologies, opening pathways for niche applications.
Solid-state heat pumps utilizing the magneto-caloric effect provide cooling without compressors or gaseous refrigerants. Medical equipment manufacturers are early adopters, using the technology for precise thermal control in diagnostic devices. This application of solid-state cooling is converging with advanced thermal management solutions for high-power electronics, creating new design possibilities beyond traditional refrigeration.
The US EPA's directives under the Significant New Alternatives Policy (SNAP) program directly impact the market. These rules restrict specific hydrofluorocarbons based on their global warming potential, forcing equipment manufacturers to qualify alternative cooling methods. The commercial refrigeration sector is most affected, accelerating research into HFC-free systems to ensure future market access.
A notable shift in purchasing behavior involves moving from exclusive R&D partnerships to multi-source procurement for magneto-caloric materials. This change disrupts the established channel of specialist labs supplying prototype alloys, opening the market to larger industrial material suppliers. This trend is most visible in Germany and China, where appliance manufacturers are building resilient supply chains.
Global Magnetic Refrigeration Market Segmentation
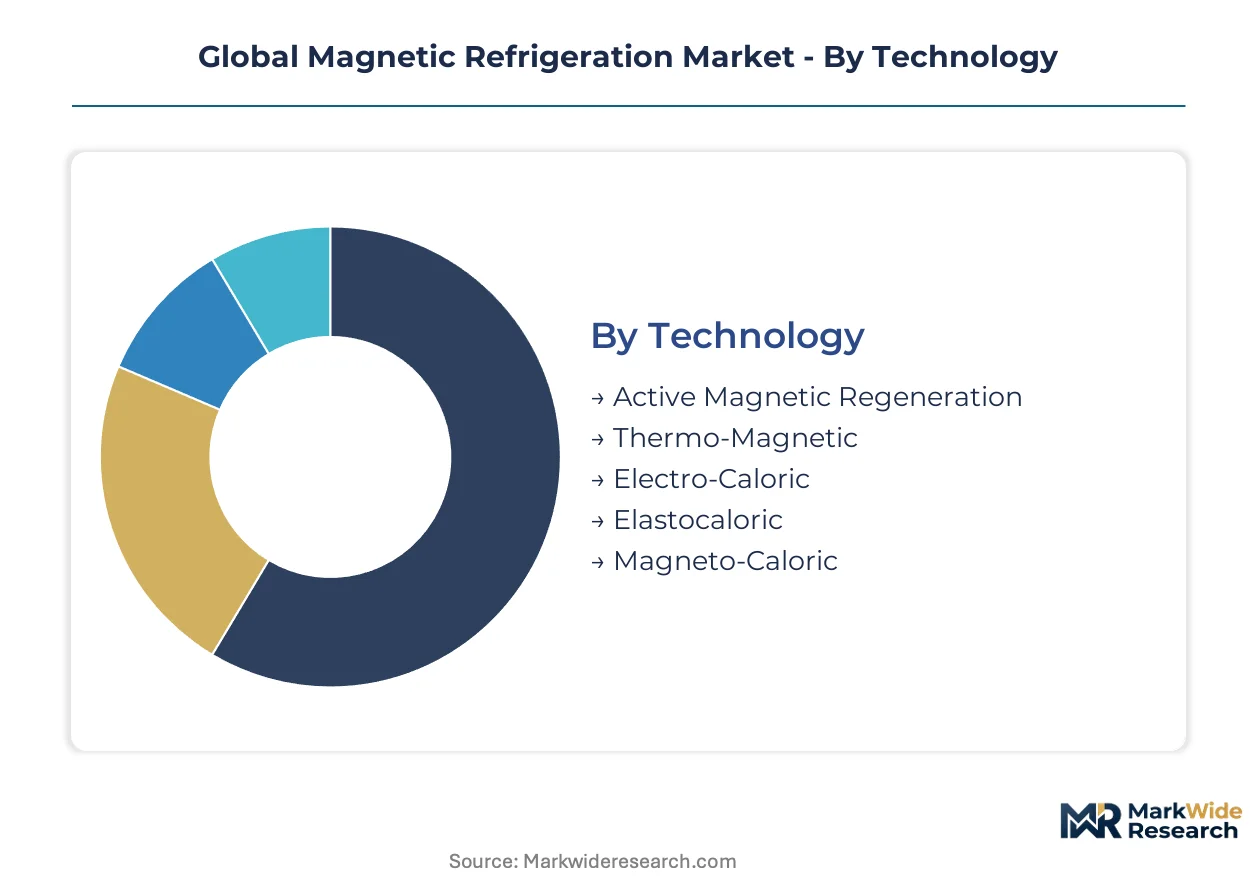
The Global Magnetic Refrigeration Market segmentation reveals distinct operational profiles and adoption pathways for this emerging cooling technology. Analysis across technology types, product applications, and end-user demands clarifies current commercial viability and future growth trajectories. This granular view assists stakeholders in targeting specific development and market entry points.
Technology:
The technology segment highlights a clear distinction between established magneto-caloric principles and the various approaches to implementing these effects, influencing both performance and cost.
- Magneto-Caloric:This core technology relies on materials that heat up when magnetized and cool when demagnetized, forming the fundamental principle of magnetic refrigeration. It currently leads development efforts due to its higher theoretical efficiency potential, particularly for specialized medical equipment applications.
- Active Magnetic Regeneration (AMR):AMR is a thermodynamic cycle that utilizes a porous bed of magneto-caloric material to transfer heat between two fluid streams, enhancing the cooling effect. This implementation method is critical for achieving practical temperature spans and efficiency in commercial cooling systems.
- Thermo-Magnetic:This approach exploits temperature-dependent magnetic properties in materials, often used in niche thermal switching or sensing applications.
- Electro-Caloric:Electro-caloric materials exhibit a temperature change when an electric field is applied or removed, offering an alternative solid-state cooling mechanism.
- Elastocaloric:Elastocaloric technology uses materials that change temperature under mechanical stress, presenting another solid-state cooling option under active research.
Today's leader: Magneto-Caloric. Tomorrow's challenger: Active Magnetic Regeneration.
Product Type:
Demand patterns vary significantly across product types, reflecting diverse technical requirements and market readiness for magnetic refrigeration solutions.
- Medical Equipment:This segment includes precise thermal control for diagnostic devices and laboratory cooling, where the technology's HFC-free operation and precise temperature management offer distinct advantages. Early commercial adoption is evident in specialized medical applications within Germany and the US.
- Commercial Cooling:This category encompasses refrigeration for supermarkets, restaurants, and data centers, representing a significant long-term target driven by regulatory pressures like the EU's F-Gas Regulation. Manufacturers like Haier Smart Home Co., Ltd. explore integration here.
- Residential Cooling:This segment targets household refrigerators and air conditioning units, requiring cost-effective and compact magnetic refrigeration systems for mass market appeal.
- Industrial Cooling:Applications include process cooling in manufacturing and specialized industrial freezers, where energy efficiency and environmental compliance are becoming critical.
- Automotive Systems:This emerging area focuses on vehicle cabin cooling and battery thermal management, seeking compact and efficient alternatives to traditional vapor-compression units.
Medical equipment currently drives initial commercialization, while commercial cooling holds substantial future potential.
Application:
The maturity of magnetic refrigeration technology varies across different applications, influencing commercial adoption rates and the scope of system integration.
- Cryogenics:This application involves achieving extremely low temperatures for scientific research, specialized industrial processes, and aerospace, where high-performance and precise temperature control are paramount. Specialist firms like Kiutra GmbH focus on these demanding applications.
- Refrigerators:Magnetic refrigeration aims to displace conventional vapor-compression systems in household and commercial refrigerators, offering energy efficiency and eliminating harmful refrigerants. This segment represents a significant volume opportunity for future deployment.
- Air Conditioning:This application targets residential and commercial HVAC systems, requiring larger cooling capacities and broader operating temperature ranges for widespread adoption.
- Cold Storage:This segment includes large-scale refrigerated warehouses and logistics, where energy consumption and environmental impact are key considerations for new cooling technologies.
- Heat Pumps:Magnetic heat pumps can provide both heating and cooling, offering a versatile solution for buildings and industrial processes with potential for high energy efficiency.
Cryogenics represents a high-value niche, and refrigerators offer a pathway to broader market penetration.
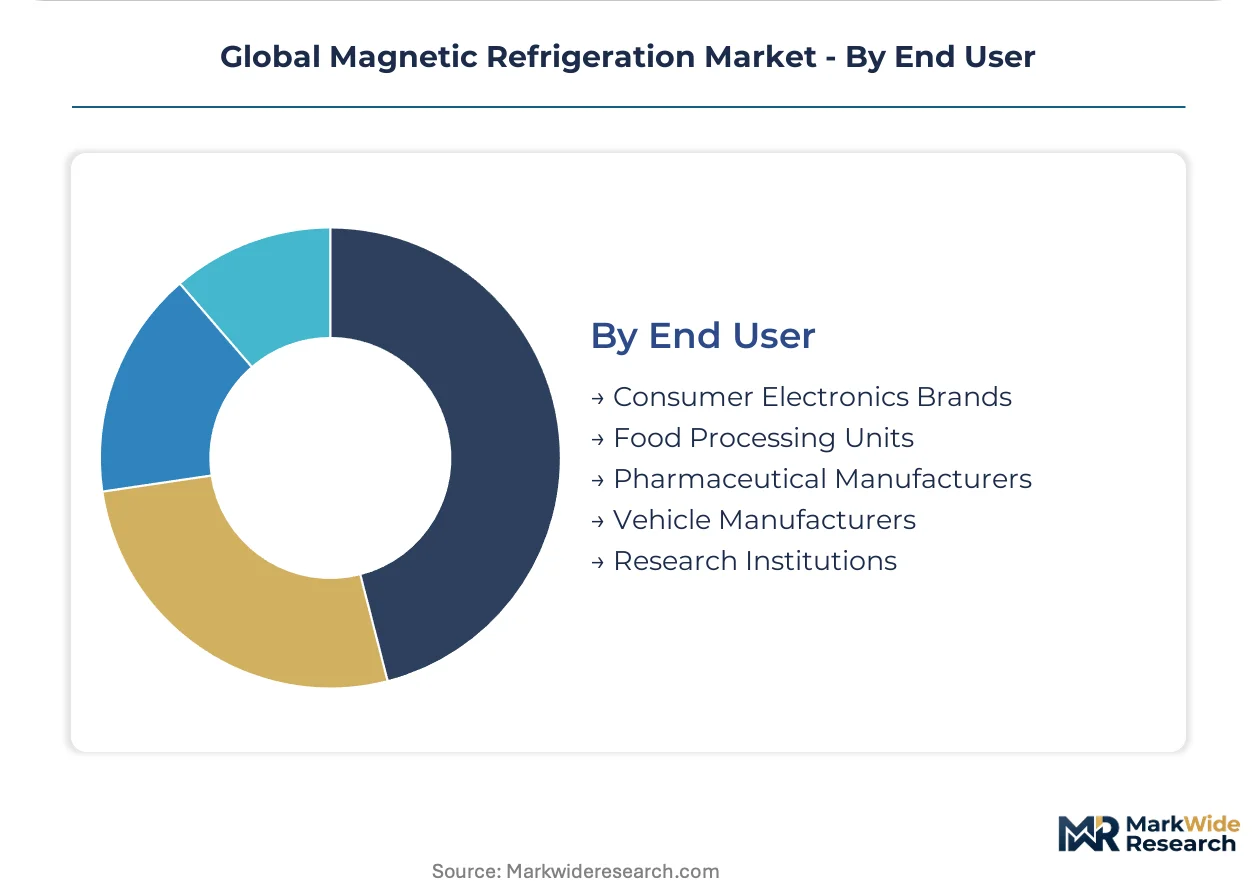
End User:
Procurement strategies and cost sensitivities differ among end-user groups, shaping the design and commercialization pathways for magnetic refrigeration solutions.
- Research Institutions:These entities are early adopters and key drivers of technology validation, using magnetic refrigeration for advanced scientific instruments and experimental setups. They prioritize performance and precision over initial cost.
- Pharmaceutical Manufacturers:This segment requires precise and stable temperature control for drug storage and manufacturing processes, driven by strict regulatory compliance and product integrity needs. Magnetic refrigeration offers a reliable, HFC-free solution.
- Consumer Electronics Brands:These manufacturers seek compact and efficient cooling solutions for high-performance devices, potentially reducing noise and improving battery life.
- Food Processing Units:This sector demands reliable and energy-efficient refrigeration for food preservation and processing, with an increasing focus on sustainable technologies.
- Vehicle Manufacturers:Automotive companies explore magnetic refrigeration for efficient cabin climate control and battery cooling systems in electric vehicles, aiming for improved range and comfort.
Research institutions drive early technology validation, and pharmaceutical manufacturers require specialized, reliable cooling solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial and research base drives early adoption of magnetic refrigeration technology, particularly for high-performance cryogenic applications. The market's global scope expands as regulatory pressures and technological advancements create opportunities in diverse economies. Countries worldwide explore magnetic refrigeration for energy efficiency and environmental compliance.
Germany
Germany's advanced manufacturing and research sectors drive significant demand for high-performance cryogenic and scientific instrumentation. The EU's F-Gas Regulation acts as a powerful catalyst, compelling industries to invest in alternative cooling technologies. Industrial hubs like Munich and Dresden are centers for early adoption and system refinement.
United States
The United States market sees demand from specialized medical equipment and commercial refrigeration sectors. The US EPA's SNAP program directly impacts market development by restricting specific hydrofluorocarbons. Research institutions in areas like Boston and Silicon Valley are validating technology for broader commercial acceptance.
China
China presents substantial opportunities in industrial processes and appliance manufacturing, driven by sustainability targets. The nation's dual carbon goals provide strong government-backed incentives for adopting high-efficiency industrial technologies. Appliance manufacturers in the Yangtze River Delta are building resilient supply chains for magneto-caloric materials.
Japan
Japan's high-tech electronics and automotive manufacturing sectors represent significant markets for specialized, high-efficiency cooling solutions. The Ministry of Economy, Trade and Industry (METI) promotes energy-efficient industrial technologies across various sectors. Research and development centers in Tokyo and Nagoya explore compact and efficient magnetic refrigeration systems.
South Korea
South Korea's advanced electronics and automotive industries seek efficient cooling for high-performance devices and vehicle systems. Government initiatives actively support the development and adoption of green technologies to meet national environmental targets. Manufacturers in the Seoul Capital Area are evaluating magnetic refrigeration for industrial processes and data center cooling.
Global Magnetic Refrigeration Market Key Industry Players
Global majors compete with regional champions across technology development and market access within the magnetic refrigeration sector. The market exhibits a tiered structure, combining large diversified companies with specialist firms focused on high-performance niche applications. Strategic archetypes include advanced material developers, comprehensive system integrators, and application-specific solution providers for medical and cryogenic uses. Key competitive moves involve strategic partnerships for R&D and portfolio diversification into new geographic and application areas.
At the scale-driven end, Haier Smart Home Co., Ltd, a Chinese manufacturer, exemplifies efforts to integrate magnetic refrigeration into commercial cooling systems. Specialist firms like Kiutra GmbH, a German-based company, sustain their focus on high-performance cryogenic applications for research institutions, representing a niche-driven approach. Danfoss AS, a Danish corporation, occupies a position as a critical supplier of system-level components, navigating the needs of diverse end users across various product types. These players collectively illustrate the market's evolving structure, from mass-market ambitions to specialized high-value solutions.
| Leading Market Players |
|---|
| Camfridge Ltd |
| Cooltech Applications |
| Haier Smart Home Co., Ltd |
| Magnoric Inc. |
| Kiutra GmbH |
| Astronautics Corporation of America |
| Ubiblue |
| Danfoss AS |
| VACUUMSCHMELZE GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and specialist firms like Kiutra GmbH drive high-performance magneto-caloric material supply, enabling premium pricing for niche cryogenic applications. This structure influences long-term contract stability and material cost pass-through for advanced cooling systems.
Pricing Analysis
Input cost pass-through for rare-earth elements significantly influences magnetic refrigeration component pricing. The dominant pricing model involves contract-based long-term offtake agreements for specialized materials, with price differentiation driven by material performance and customization for specific applications. Pricing softness emerges from the commercial cooling sector, which demands cost-parity with conventional systems. Research institutions exhibit lower price sensitivity for high-precision components, while mass-market appliance manufacturers are highly price-sensitive.
Supply Chain Analysis
Dual-sourcing requirements are increasing for critical magneto-caloric materials to mitigate supply risks. The supply of rare-earth elements like gadolinium and dysprosium is heavily concentrated in China, creating significant commodity price volatility. Specialized component manufacturing, particularly for Active Magnetic Regeneration systems, also has concentrations in Germany. This supply chain relies on direct sales channels to original equipment manufacturers (OEMs) and specialized integrators. Geopolitical risks associated with rare-earth metal extraction present a structural vulnerability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The magnetic refrigeration market represents a late-cycle quality story, as demand shifts toward premium, energy-efficient cooling solutions in medical equipment and cryogenics. This transition underscores the need for high-performance, environmentally compliant technologies.
For Market Incumbents: Acquire specialized material intellectual property to secure next-generation alloy formulations. Incumbents should scale up manufacturing of Active Magnetic Regeneration components to meet anticipated demand from commercial cooling, countering the long-term threat of cost-competitive vapor-compression systems. Investing in certification for medical-grade applications establishes a strong market position. Control over the distribution channels for system-level components helps maintain market share.
For New Entrants and Emerging Players: Enter via strategic partnerships with automotive OEMs for battery thermal management solutions. New entrants can target specialized industrial cooling applications in Japan, leveraging energy efficiency as a key differentiator. Focusing on data center cooling offers a significant white-space opportunity for high-efficiency systems. A go-to-market angle emphasizing sustainability compliance and operational cost savings resonates with industrial clients.
For Investors and Strategic Acquirers: Valuations sit cheapest among early-stage material science startups focused on non-gadolinium alloys. The market offers long-term viability over a five-to-ten-year window, driven by persistent regulatory tailwinds against hydrofluorocarbons. Acquisition targets should include specialist firms developing novel magneto-caloric materials and those with proven system integration capabilities. A critical signal to watch is the achievement of cost-parity and long-term reliability for magnetic refrigeration in commercial cooling systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for AMR Components | Ensures readiness for large-scale deployment in commercial cooling systems. |
| Partnership for Non-Rare Earth Alloys | Reduces material cost dependency and geopolitical supply risks for manufacturers. |
| Certification for Medical Devices | Unlocks broader adoption in precision thermal control for diagnostic equipment. |
| Pilot Programs in Data Centers | Validates energy efficiency and operational savings for high-power electronics. |
| Standardization Initiative for Testing | Accelerates broader commercial acceptance and procurement for end-users. |
Research Approach
Direct dialogue with material scientists, thermal engineers, medical device procurement specialists, and HVAC system integrators informed the primary research. This was validated through extensive secondary data, including EU F-Gas reports, US EPA SNAP program documents, academic journals, and company 10-K filings. A rigorous bottom-up and top-down triangulation approach ensured data consistency across all market segments.
The forecast employed a bottom-up methodology, validating market size estimates through top-down checks across the analysis window. Segmentation dimensions modeled included technology type, product application, end-user industry, and material composition. Compound Annual Growth Rates (CAGRs) were derived from historical data trends and projected adoption rates. Regulatory phase-out schedules for conventional refrigerants and magneto-caloric material cost projections served as key forecast inputs.
Inputs from regulatory bodies, academic research, and company disclosures were available through the study window; gaps in long-term material cost stability introduce uncertainty bands into the projections. Forecasts reflect assumptions regarding commercialization pace and technology maturation. Deviation in rare-earth element pricing or new regulatory mandates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Industrial Water Cooling System Market
Cooling Systems
Saudi Arabia Desert Air Coolers Market
Cooling Systems
Europe Air Source Heat Pump Market
Cooling Systems
Global Evaporative Cooler Market
Cooling Systems
Battery Cooling Plate Market
Cooling Systems
Global Chiller Market
Cooling Systems
Global Air Cooled Condenser Market
Cooling Systems
Europe Cooling Systems Market
Cooling Systems
Cryosystem Market
Cooling Systems
Global Secondary Refrigerants Market
Cooling Systems
Aftercoolers Market
Cooling Systems
Absorption Chillers Market
Cooling Systems
Global Evaporative Cooling Market
Cooling Systems
Turbine Inlet Cooling Systems Market
Cooling Systems
Lithium Battery Liquid Cooling Pump Market
Cooling Systems
Horizontal Air Flow Condensers Market