
 United States Heat Pump Market | 2026-2036
United States Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
United States Heat Pump Market Analytics
ENERGY STAR certification is collapsing the field of qualified manufacturers as minimum efficiency thresholds ratchet upward. Carrier Global Corporation leverages its broad distribution network to sustain contractor loyalty across the Southeast. Daikin Industries Ltd anchors its position through captive inverter compressor production. Trane Technologies plc differentiates via cold-climate performance guarantees that exceed baseline ENERGY STAR requirements.
A heat pump is a vapor-compression refrigeration device that transfers thermal energy between indoor and outdoor environments using a refrigerant with a coefficient of performance typically exceeding three. The equipment serves as both heating and cooling apparatus, displacing separate furnace and air conditioner installations in residential and commercial buildings. Air source systems dominate unit volumes due to lower installed cost, though ground source configurations command premium pricing and superior efficiency in extreme temperature zones. Variable refrigerant flow technology leads commercial adoption by enabling zone-level climate control. Residential applications generate the deepest replacement cycle demand as aging HVAC infrastructure reaches end of service life.
The Department of Energy sets minimum efficiency standards under 10 CFR 430, while the EPA administers refrigerant phase-down schedules through the AIM Act. State-level mandates in California and Washington now require heat pump readiness in new construction, compressing the timeline for builder specification shifts. Stakeholders must track refrigerant transition timelines and cold-climate performance testing protocols as these dual pressures determine which product portfolios retain market access.
Market Dynamics
The Inflation Reduction Act's tax credit architecture is restructuring residential replacement economics, compressing payback periods for cold-climate air-source systems and redirecting contractor inventory commitments toward qualifying efficiency tiers.
Growth Catalysts
- IRA Tax Credits:The federal incentive structure covers up to thirty percent of installed costs for ENERGY STAR-certified equipment, activating dormant replacement demand across the Northeast corridor.
- Cold-Climate Performance Standards:Advanced compressor modulation technologies now maintain rated capacity at subzero temperatures, unlocking viable electrification pathways for Minnesota and Wisconsin homeowners.
- State-Level Building Codes:California and Washington mandates requiring heat pump readiness in new construction are forcing builder specification shifts ahead of national standards.
Market Restraints
- Refrigerant Supply Concentration:Domestic production capacity for low-global-warming-potential blends remains concentrated with limited chemical manufacturers, exposing installers to allocation volatility during transition periods.
- Electrical Infrastructure Gaps:Rural and older urban service territories lack the panel capacity and circuit availability to support cold-climate heat pump loads without costly upgrades.
- Technical Performance Skepticism:Persistent homeowner uncertainty about heating adequacy in extreme cold zones slows conversion rates despite improved laboratory ratings.
Strategic Opportunities
- Texas and Florida Retrofit Expansion:Cooling-dominated markets with aging air conditioner fleets represent underpenetrated territory for dual-function heat pump displacement.
- Grid-Interactive Thermal Storage:Utility-controlled thermal batteries paired with variable-speed compressors create new revenue streams for demand response program participation.
- Multifamily Central System Retrofits:Packaged terminal heat pump configurations address boiler replacement cycles in aging apartment inventories across Chicago and Philadelphia.
Industry Challenges
- Refrigerant Handling Certification:The EPA's Section 608 technician certification requirements create bottlenecks as the industry scales workforce for R-454B transition timelines.
- Legacy Control Integration:Smart thermostat compatibility gaps with proprietary inverter communication protocols force costly controller replacements during retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Heat Pump Market |
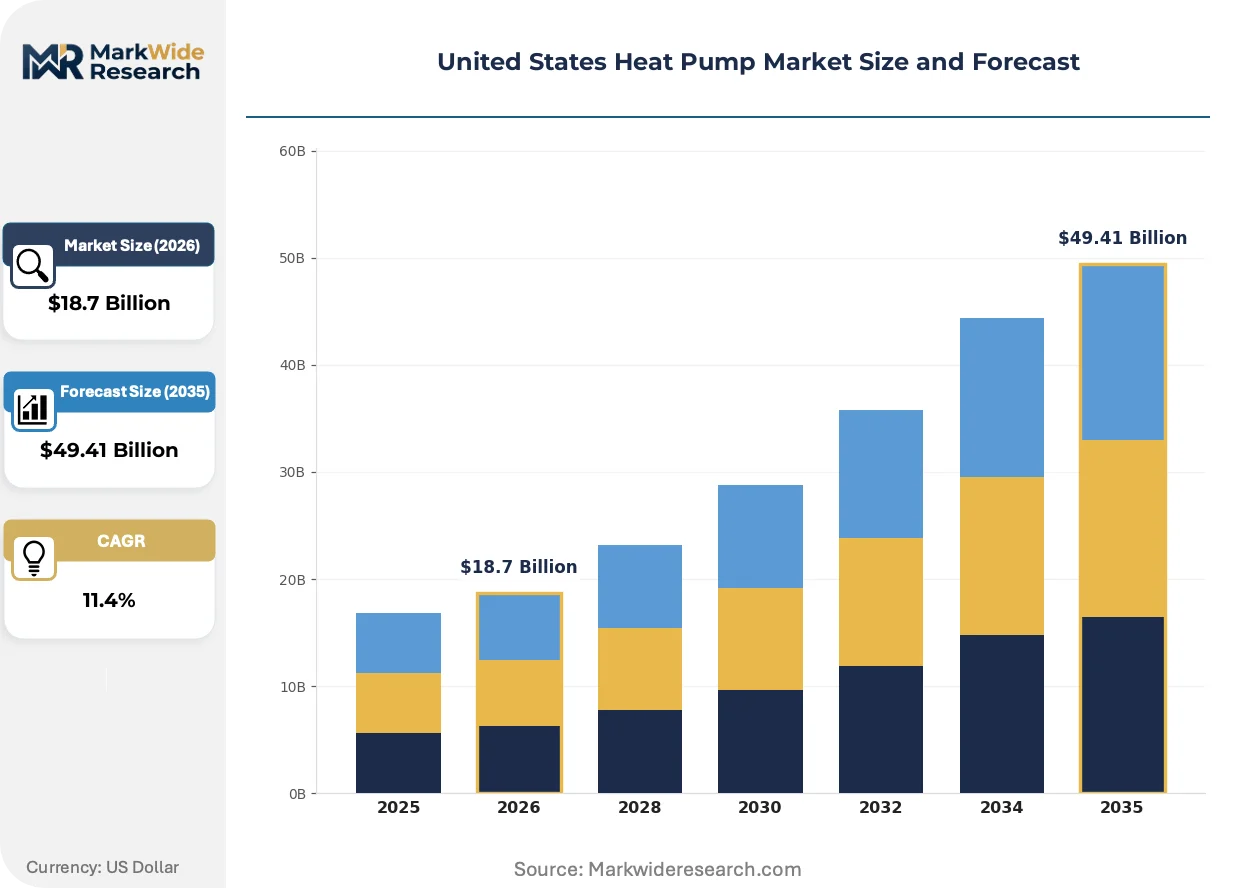
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Source, Ground Source, Water Source, Hybrid Application: Residential, Commercial, Industrial, Agricultural Technology: Variable Refrigerant Flow, Direct Expansion, Chiller Heat Pumps, Thermoelectric End User: Homeowners, Facility Managers, Contractors, Energy Providers |
| Companies Covered | Carrier Global Corporation, Daikin Industries Ltd, Trane Technologies plc, Rheem Manufacturing Company, Lennox International Inc, Johnson Controls International plc, Mitsubishi Electric Corporation, Nortek Air Management, Robert Bosch GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Heat Pump Market Evolving Landscape
Refrigerant chemistry transitions and grid-interactive controls are converging to redefine equipment value propositions beyond thermal efficiency metrics alone.
Variable refrigerant flow systems are fragmenting the commercial HVAC specification landscape by enabling zone-level climate control without ductwork retrofit. Building owners in mixed-use developments from Seattle to Boston are specifying VRF for simultaneous heating and cooling recovery. This capability is fragmenting traditional chiller-boiler pairings in mid-rise construction.
The EPA's refrigerant phase-down schedule under the AIM Act is compressing product development cycles for A2L-class blends with lower flammability ratings. Equipment manufacturers must recertify safety systems and ignition control modules ahead of mandated production deadlines. Cold-climate product lines face the steepest redesign burden given their higher refrigerant charge requirements.
Utility-managed installation programs are displacing traditional retail channel dominance in high-penetration markets. Efficiency Vermont and Mass Save now capture substantial residential volumes through direct contractor networks and instant rebate processing. This channel shift concentrates buyer influence with program administrators rather than equipment distributors.
United States Heat Pump Market Segmentation
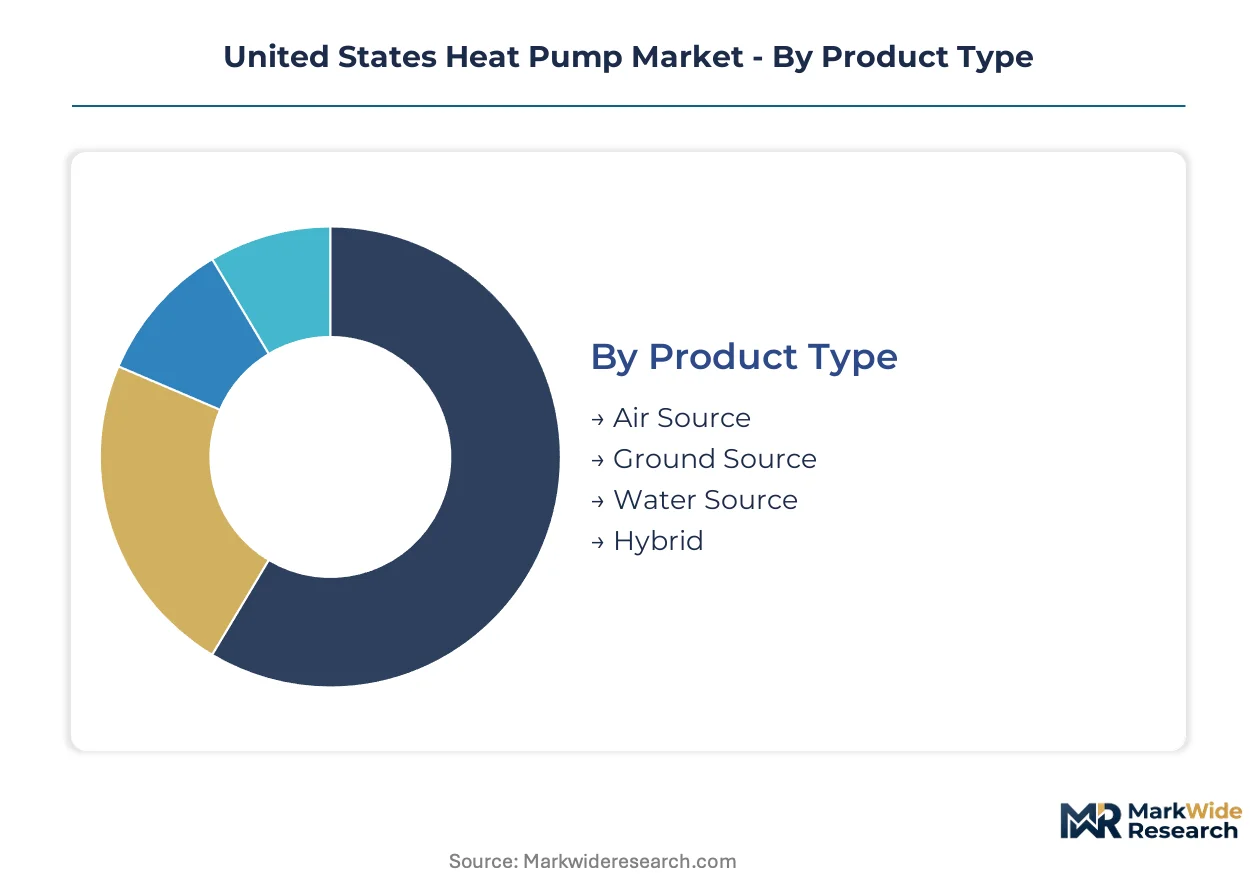
Segmentation in the United States Heat Pump Market reveals distinct margin architectures across product configurations and customer types. Procurement patterns diverge sharply between residential retrofits chasing IRA incentives and commercial specifications prioritizing zone-level control.
Product Type:
Margin pools concentrate in ground source installations where drilling costs and specialized labor create pricing power for certified installers.
- Air Source:These systems extract thermal energy from ambient outdoor air through vapor-compression cycles, utilizing aluminum fin-and-tube heat exchangers. Demand clusters heaviest in Massachusetts and New York where IRA tax credits compress payback periods for cold-climate rated units. Cold-climate compressor modulation technologies now maintain capacity at subzero temperatures, unlocking Minnesota and Wisconsin markets previously deemed unsuitable.
- Ground Source:Geothermal configurations circulate fluid through buried loop fields to access stable subsurface temperatures year-round. Premium pricing persists in rural Illinois and Ohio where lot sizes accommodate horizontal loop trenches, though vertical bore systems penetrate suburban Chicago and Cleveland despite higher drilling costs. The technology commands superior coefficient of performance in extreme temperature zones.
- Water Source:Open-loop and closed-loop systems leverage adjacent water bodies for heat exchange, requiring specific hydrogeological conditions.
- Hybrid:Dual-fuel configurations pair electric heat pumps with fossil fuel backup, addressing homeowner skepticism about heating adequacy in extreme cold.
The dominant share belongs to Air Source, while Ground Source is closing the gap fastest in states with aggressive building electrification mandates.
Application:
Volume concentration tilts toward replacement cycles in aging residential housing stock across the Northeast corridor.
- Residential:Single-family and multifamily installations displace separate furnace and air conditioner configurations, with retrofits driving procurement in cold-climate states. The Inflation Reduction Act's thirty percent tax credit activates dormant replacement demand from Maine through Pennsylvania. Aging HVAC infrastructure reaching end of service life generates the deepest replacement cycle demand.
- Commercial:Office, retail, and hospitality specifications prioritize variable refrigerant flow systems for zone-level climate control without ductwork retrofit. Building owners in mixed-use developments from Seattle to Boston specify simultaneous heating and cooling recovery capabilities. This capability fragments traditional chiller-boiler pairings in mid-rise construction.
- Industrial:Process heating and waste heat recovery applications demand higher capacity units with specialized refrigerant circuits.
- Agricultural:Greenhouse and livestock facility climate control represents a niche but growing specification channel.
Residential captures the volume base, though Commercial specifications yield higher margins per installed ton.
Technology:
Specification influence increasingly rests with controls integration and grid-interactive capabilities rather than thermal efficiency alone.
- Variable Refrigerant Flow:Multi-zone systems modulate refrigerant flow to individual indoor units, enabling simultaneous heating and cooling recovery. VRF dominates commercial adoption in mixed-use developments from Seattle to Boston. Building owners specify these systems for zone-level climate control without costly ductwork retrofit.
- Direct Expansion:Single-zone split systems serve residential retrofits with simpler installation requirements and lower equipment costs.
- Chiller Heat Pumps:Large-capacity centrifugal and screw configurations address district heating applications and central plant retrofits.
- Thermoelectric:Solid-state heat pumping using Peltier effects serves niche applications requiring precise temperature control without moving parts.
Variable Refrigerant Flow leads commercial specification value, while Direct Expansion maintains residential volume dominance.
End User:
Purchasing authority fragments across decision-makers with divergent priorities: first cost, operating cost, installation speed, or grid integration.
- Homeowners:Individual purchasers respond to IRA tax credit economics and contractor recommendations, with cold-climate performance skepticism slowing conversion rates despite improved laboratory ratings. Utility-managed installation programs through Efficiency Vermont and Mass Save displace traditional retail channel dominance.
- Facility Managers:Commercial building operators prioritize lifecycle operating costs and zone-level control capabilities. Procurement runs through engineered specifications with extended warranty requirements.
- Contractors:Installation firms influence equipment selection through inventory commitments and manufacturer loyalty programs. EPA Section 608 certification bottlenecks constrain workforce scaling for refrigerant transition timelines.
- Energy Providers:Utilities specify grid-interactive thermal storage configurations for demand response program participation, creating new revenue streams beyond commodity electricity sales.
Homeowners drive absolute unit volumes, though Energy Providers are expanding their procurement influence fastest through managed installation programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration varies sharply across state lines, with cold-climate retrofits, new construction mandates, and utility-managed programs creating distinct procurement clusters. The Northeast corridor anchors replacement demand, while the Southeast and Texas represent displacement opportunities for aging cooling infrastructure.
Northeast Corridor
Massachusetts and New York drive the deepest residential retrofit activity as IRA tax credits compress payback periods below seven years for cold-climate rated systems. EPA refrigerant phase-down timelines under the AIM Act accelerate contractor inventory turnover in Greater Boston and Albany metro areas. Efficiency Vermont and Mass Save capture substantial volumes through direct contractor networks, displacing traditional distributor channels.
Midwest Cold-Climate States
Minnesota and Wisconsin unlock as viable electrification markets as compressor modulation technologies maintain rated capacity at subzero temperatures. State energy office technical assistance programs address homeowner skepticism through field demonstration projects. The Twin Cities and Milwaukee metro areas concentrate installation firm capacity for ground-source vertical bore systems.
California
New construction mandates require heat pump readiness, compressing builder specification shifts ahead of national standards. The California Energy Commission updates Title 24 building codes on three-year cycles. The Central Valley and Inland Empire see rising adoption for dual-function displacement of separate furnace and air conditioner configurations.
Texas
Cooling-dominated markets with aging air conditioner fleets represent underpenetrated territory for heat pump displacement. ERCOT grid reliability concerns accelerate interest in dual-fuel backup configurations. Houston and Dallas-Fort Worth metro areas concentrate HVAC contractor density for rapid retrofit scaling.
Pacific Northwest
Washington state mandates heat pump readiness in new construction, forcing builder specification shifts comparable to California. Seattle and Portland metro areas prioritize VRF systems for mixed-use developments requiring simultaneous heating and cooling recovery. Utility demand response programs pilot grid-interactive thermal storage paired with variable-speed compressors.
United States Heat Pump Market Competitive Landscape
Player mix skews toward diversified HVAC conglomerates with captive distribution networks and captive component production. Consolidation pressure intensifies as ENERGY STAR certification thresholds ratchet upward, collapsing the field of qualified manufacturers. Two strategic archetypes dominate: full-system integrators controlling compressor technology and inverter controls, and regional assemblers dependent on outsourced core components. Competitive moves center on cold-climate performance certification racing and refrigerant transition timeline acceleration.
Among diversified HVAC conglomerates, Carrier Global Corporation, Daikin Industries Ltd, and Trane Technologies plc exemplify contrasting defensive positions. Carrier leverages broad distribution networks to sustain contractor loyalty across the Southeast. Daikin anchors its position through captive inverter compressor production. Trane differentiates via cold-climate performance guarantees that exceed baseline ENERGY STAR requirements.
| Leading Market Players |
|---|
| Carrier Global Corporation |
| Daikin Industries Ltd |
| Trane Technologies plc |
| Rheem Manufacturing Company |
| Lennox International Inc |
| Johnson Controls International plc |
| Mitsubishi Electric Corporation |
| Nortek Air Management |
| Robert Bosch GmbH |
| Others |
Value Network & Pricing Analysis
R-454B refrigerant substitution for legacy R-410A blends is simultaneously relocating compressor sourcing toward Asian chemical manufacturers and compressing margin structures for domestic equipment assemblers facing allocation volatility during the AIM Act transition timeline.
Pricing Analysis
Cost-plus contracts indexed to copper and aluminum commodity exchanges dominate equipment procurement between manufacturers and distributor networks. Price differentiation stratifies across ENERGY STAR certification tiers, with cold-climate performance ratings commanding premiums over baseline efficiency units. Cost compression in mid-tier residential systems is intensifying because captive inverter production advantages at integrated conglomerates force price-matching responses from component-dependent assemblers. Homeowners in utility-managed program territories exhibit lowest price sensitivity due to instant rebate processing, while rural retrofit buyers face highest sensitivity given electrical upgrade cost exposure.
Supply Chain Analysis
China and Japan anchor rotary and scroll compressor fabrication, while Mexico and Thailand concentrate heat exchanger coil production for North American assembly. The industry draws from copper tube mills in Tennessee and Alabama, aluminum fin stock from domestic rolling operations, and rare-earth magnet supply for inverter motors concentrated with Chinese processors. Single-source vulnerability in low-global-warming-potential refrigerant blends exposes installers to allocation constraints during EPA-mandated phase-down windows. Distribution runs through manufacturer-authorized dealer networks with exclusive territory arrangements, though utility-managed programs in Vermont and Massachusetts are displacing traditional wholesale channel dominance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified technician scarcity for A2L refrigerant handling and inverter control integration represents the binding constraint on market expansion, with workforce development gaps outpacing equipment production capacity across the Northeast and Midwest corridors.
For Market Incumbents: Compound cold-climate performance certification advantages by accelerating R-454B product line transitions ahead of EPA production deadlines, while capturing contractor loyalty through exclusive refrigerant allocation guarantees that neutralize emerging entrant price aggression in Texas and Florida retrofit territories. For New Entrants and Emerging Players: ENERGY STAR cold-climate fast-track certification unlocks viable entry through direct-to-utility program partnerships, bypassing entrenched distributor relationships. Texas cooling-dominated retrofits and multifamily boiler replacement cycles in Chicago represent the most penetrable white-space segments, with grid-interactive thermal storage bundling as the differentiated go-to-market angle against established equipment-only vendors. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors vertically integrated compressor manufacturers with captive inverter technology and EPA Section 608 training infrastructure. Long-term viability centers on controlling refrigerant transition timing and cold-climate testing protocol influence, with acquisition targets clustering around regional installers with utility program administrator relationships. The signal to watch is EPA acceleration of A2L production mandates that would strand non-compliant inventory at component-dependent assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Climate Performance Certification | ENERGY STAR tier advancement unlocks IRA tax credit eligibility in Massachusetts and New York corridors. |
| Refrigerant Transition Acceleration | R-454B product line readiness ahead of AIM Act deadlines captures contractor inventory commitments during replacement cycles. |
| Utility Program Partnership | Direct alignment with Efficiency Vermont and Mass Save displaces traditional distributor channel control. |
| Workforce Certification Infrastructure | EPA Section 608 training scale-up removes installation bottlenecks constraining market expansion. |
| Grid-Interactive Control Integration | Variable-speed compressor pairing with thermal storage creates demand response revenue streams beyond equipment sales. |
Research Methodology
Desk research of EPA AIM Act regulatory filings, DOE 10 CFR 430 efficiency standards, and utility program administrator annual reports preceded structured interviews with HVAC contractor operations managers, distributor inventory planners, manufacturer product directors, and state energy office electrification leads. Primary fieldwork captured installation cost structures, refrigerant allocation patterns, and cold-climate field performance validation. Secondary validation drew from EIA residential energy consumption surveys, ENERGY STAR certification databases, and state building code adoption tracking. Bottom-up equipment shipment analysis triangulated against top-down construction permit and retrofit incentive redemption data.
Variance decomposition across product type, application, technology, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from replacement cycle modeling, new construction mandate adoption curves, and IRA incentive uptake elasticity estimates. Industry-specific forecast inputs included heat pump readiness code adoption timelines in California and Washington, compressor modulation technology cost curves, and utility-managed program budget allocations across the Northeast corridor.
Underlying assumptions cover IRA tax credit continuity, EPA refrigerant phase-down schedule adherence, and copper-aluminum commodity price stability, with deviation risk concentrated in federal incentive policy shifts and electrical infrastructure upgrade funding availability. Recalibration cycles align with material shifts in state building code adoptions, ENERGY STAR threshold revisions, and utility program administrator procurement pattern changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Solar Ventilation Systems Market
Cooling Systems
Global Chiller Market
Cooling Systems
Global Secondary Refrigerants Market
Cooling Systems
Solar Refrigerators Market
Cooling Systems
Saudi Arabia Desert Air Coolers Market
Cooling Systems
Global Transcritical Co2 Systems Market
Cooling Systems
Temperature Controlled Container Market
Cooling Systems
Temporary Power and Cooling Solutions Market
Cooling Systems
Global Scroll and Absorption Chillers Market
Cooling Systems
Process Chillers Market
Cooling Systems
Portable Chiller Market
Cooling Systems
Horizontal Air Flow Condensers Market
Cooling Systems
Plate and Frame Heat Exchangers Market
Cooling Systems
Microchannel Heat Exchanger Market
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
Global Magnetic Refrigeration Market