
 Turbine Inlet Cooling Systems Market | 2026-2036
Turbine Inlet Cooling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Turbine Inlet Cooling Systems Market Analysis
Advanced composite coatings and corrosion-resistant alloys is shifting material selection away from conventional galvanized steel in fogging system manifolds and nozzle assemblies. General Electric leverages its turbine OEM relationships to bundle inlet cooling retrofits with long-term service agreements. Siemens anchors European demand through integrated power plant solutions that combine gas turbine upgrades with thermal energy storage cooling. Mee Industries specializes in high-pressure fogging systems for desert climates, competing on installation speed and water efficiency.
Turbine inlet cooling systems condition combustion air entering gas turbines to boost mass flow and power output, typically achieving inlet temperature reductions of 15–30°C through evaporative fogging, mechanical chilling, or thermal energy storage media. The technology addresses the fundamental thermodynamic constraint that gas turbine efficiency and capacity decline as ambient air temperature rises above ISO conditions. Evaporative cooling dominates installed base economics in arid regions where water access permits fogging operations, while mechanical chillers command premium positioning in humid coastal zones where wet-bulb depression limits evaporative performance. Thermal energy storage is gaining traction among utilities seeking to shift cooling energy consumption to off-peak periods, capturing margin pools where time-of-use electricity pricing creates arbitrage value.
The US EPA enforces emissions limits under the Clean Air Act that effectively penalize capacity derating, incentivizing inlet cooling investments that sustain rated output without additional fuel burn. Saudi Arabia's national energy efficiency programs and the country's regulator for electricity and cogeneration mandate performance standards that align with inlet cooling retrofits on existing gas turbine fleets. Stakeholders must monitor how evolving carbon border mechanisms and regional water scarcity regulations reshape technology selection between water-intensive evaporative systems and electrically-driven mechanical alternatives.
Market Dynamics
The US EPA's tightening emissions benchmarks for thermal power plants are forcing operators toward efficiency upgrades that sustain rated output without additional fuel burn. This regulatory pressure is compressing decision timelines for inlet cooling retrofits across aging gas turbine fleets.
Growth Catalysts
- Combined cycle expansion:Power plant operators in Saudi Arabia are expanding adoption of inlet cooling to sustain output during ambient temperature spikes, creating sustained demand for evaporative and mechanical chiller-based systems.
- Emissions compliance mandates:The US EPA enforces limits under the Clean Air Act that effectively penalize capacity derating, directly incentivizing inlet cooling investments that maintain power output.
- Arid climate necessity:Gas turbine capacity additions in desert regions create structural pull for high-pressure fogging systems where wet-bulb depression limits evaporative performance.
Market Restraints
- Water scarcity constraints:Regional water scarcity regulations in the Middle East and North America are reshaping technology selection between water-intensive evaporative systems and electrically-driven mechanical alternatives.
- Input cost volatility:Corrosion-resistant alloys and advanced composite coatings command premium pricing, elevating material costs for fogging system manifolds and nozzle assemblies.
- Technical performance limits:Wet-bulb depression constraints in humid coastal zones cap evaporative cooling effectiveness, restricting addressable market for fogging-only solutions.
Strategic Opportunities
- Thermal energy storage convergence:Utilities seeking to shift cooling energy consumption to off-peak periods are adopting thermal energy storage media, capturing margin pools where time-of-use electricity pricing creates arbitrage value.
- Service contract bundling:Long-term service agreements that integrate inlet cooling retrofits with turbine OEM relationships are opening recurring revenue streams for system providers.
- Retrofit penetration:Saudi Arabia's national energy efficiency programs and electricity regulator mandates create white space for inlet cooling retrofits on existing gas turbine fleets.
Industry Challenges
- Integration complexity:Retrofitting inlet cooling onto legacy gas turbine installations requires coordination with existing control systems and combustion tuning protocols.
- Certification timeline compression:Performance standards mandated by Saudi Arabia's regulator for electricity and cogeneration compress validation windows for new system deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turbine Inlet Cooling Systems Market |
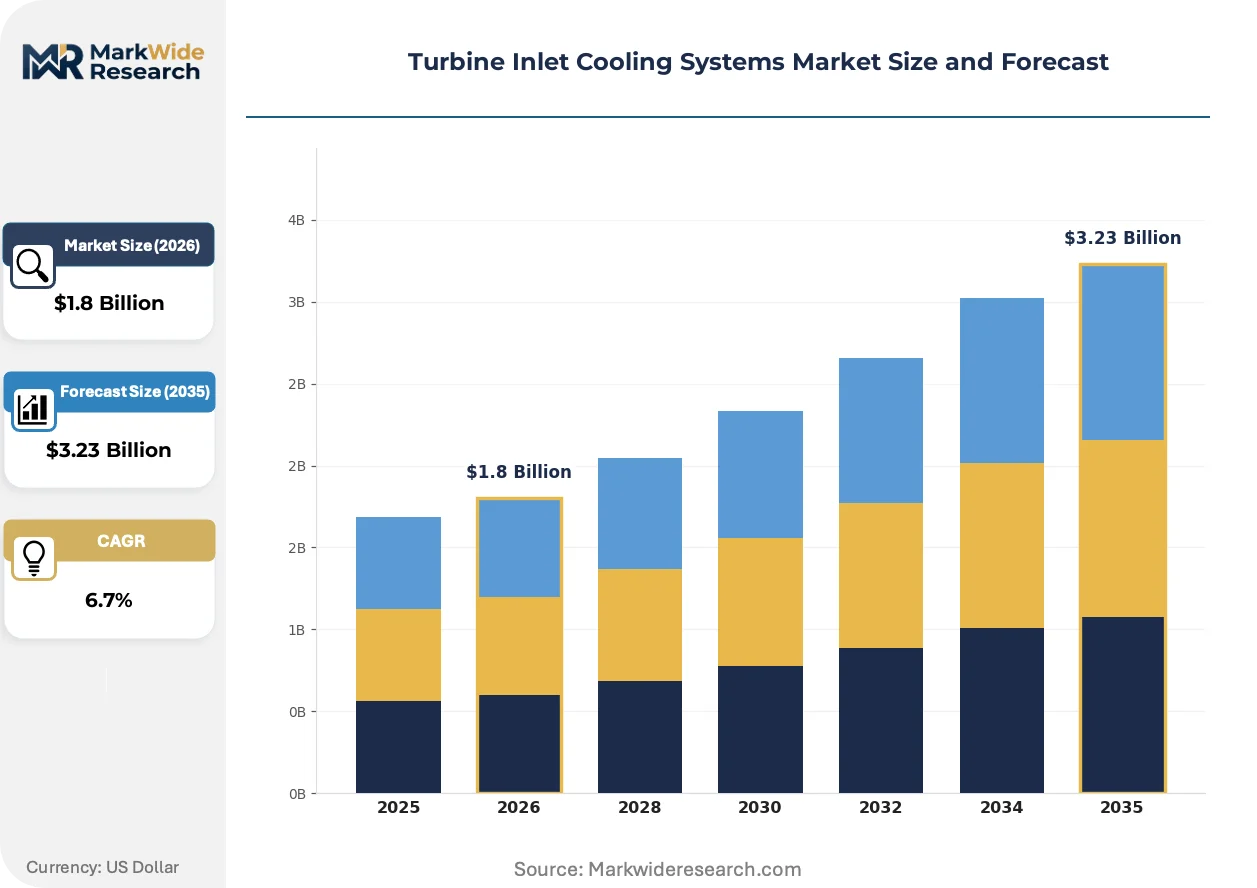
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Evaporative Cooling, Mechanical Chillers, Thermal Energy Storage, Heat Exchangers Application: Gas Turbines, Combined Cycle Power Plants, Peak Load Plants, Industrial Processes End User: Utilities, Power Generation Companies, Manufacturing Plants, Oil & Gas Industry Deployment: Onshore, Offshore, Industrial Sites, Power Facilities |
| Companies Covered | General Electric, Schneider Electric, Johnson Controls, Camfil, Emerson Electric, Mee Industries, Mitsubishi Power, Caldwell Energy, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turbine Inlet Cooling Systems Market Emerging Trajectories
Material science advances and regulatory tightening are actively rewriting competitive positioning in turbine inlet cooling. Three developments are compressing technology adoption curves and reshaping supplier relationships.
Advanced composite coatings and corrosion-resistant alloys are rewriting material selection protocols for fogging system manifolds and nozzle assemblies. Power plant operators in arid climates are accelerating replacement of conventional galvanized steel to extend component life in high-salinity environments. This shift is compressing supplier margins on legacy steel fabrication while elevating specialty alloy providers.
The US EPA's emissions benchmarks under the Clean Air Act are tightening enforcement timelines for thermal power operators. Industrial consequence includes mandatory capacity maintenance without incremental fuel burn, forcing derating-sensitive plants toward inlet cooling investments. Combined cycle facilities in the US Gulf Coast region are responding fastest, prioritizing mechanical chiller retrofits over evaporative alternatives.
After-sales service unbundling is fragmenting traditional turbine OEM lock-in. Independent inlet cooling specialists are capturing retrofit contracts through installation speed and water efficiency guarantees, displacing bundled service agreements. This pattern is most visible in Saudi Arabia, where national energy efficiency programs have created procurement pathways outside OEM channels.
Turbine Inlet Cooling Systems Market Segmentation
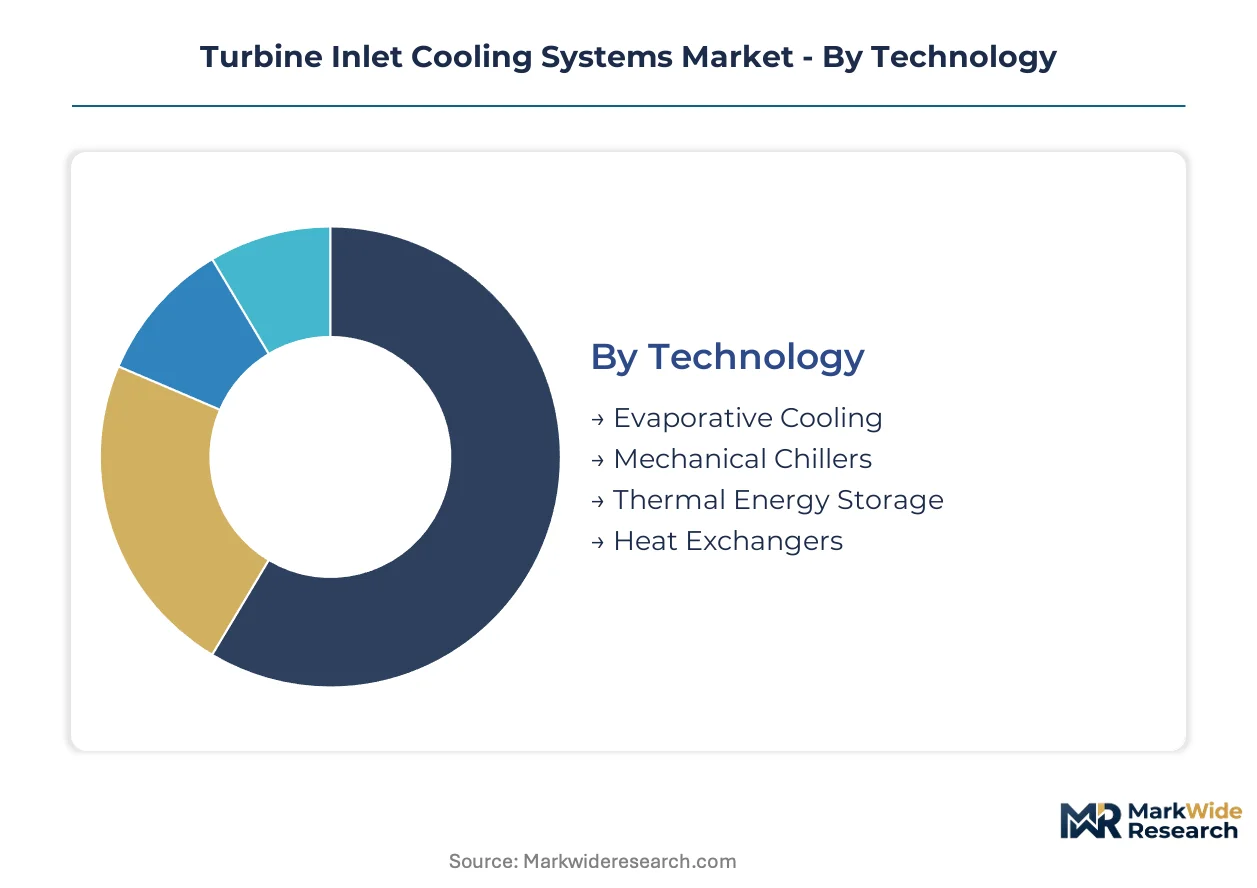
Technology selection in turbine inlet cooling hinges on water availability, ambient humidity, and electricity pricing structures. Deployment patterns reveal divergent capital requirements across evaporative and mechanical systems, with implications for utility procurement strategies and OEM bundling decisions.
Technology:
Capital intensity varies dramatically across cooling architectures, with mechanical chillers demanding the highest upfront investment for compressor trains and electrical infrastructure.
- Evaporative Cooling:High-pressure fogging systems atomize demineralized water into combustion air streams, achieving 15–25°C temperature depression at ISO conditions. Demand concentrates in Saudi Arabia and the US Southwest, where arid climates and low wet-bulb temperatures maximize system effectiveness. Water scarcity regulations in these regions are compressing allowable consumption rates per megawatt-hour.
- Mechanical Chillers:Electrically-driven vapor-compression or absorption refrigeration systems deliver precise temperature control independent of ambient humidity. US Gulf Coast combined cycle plants favor this technology where wet-bulb depression limits evaporative performance. Premium positioning reflects higher installed costs offset by guaranteed capacity during peak demand periods.
- Thermal Energy Storage:Ice or chilled water systems shift cooling load to off-peak electricity periods, capturing arbitrage value where time-of-use pricing differentials exceed storage capital costs.
- Heat Exchangers:Closed-loop indirect systems separate cooling fluid from combustion air, protecting turbine hardware in corrosive or particulate-laden environments.
Evaporative cooling absorbs the bulk of installed capacity; mechanical chillers are expanding most quickly in humid coastal zones.
Application:
Plant configuration dictates cooling duty cycles, with baseload combined cycle facilities requiring sustained performance versus peaking units prioritizing rapid deployment flexibility.
- Gas Turbines:Simple cycle aeroderivative and heavy-frame turbines in utility fleets represent the foundational installed base for inlet cooling retrofits. Saudi Arabia's regulator for electricity and cogeneration mandates efficiency standards that align with cooling investments on existing units.
- Combined Cycle Power Plants:Heat recovery steam generator integration creates compound efficiency gains when inlet cooling sustains gas turbine output at elevated ambient temperatures. US EPA emissions limits under the Clean Air Act penalize capacity derating, forcing these facilities toward cooling upgrades.
- Peak Load Plants:Fast-start combustion turbines serving grid balancing roles prioritize installation speed over absolute efficiency, favoring modular fogging skids over permanent mechanical chiller infrastructure.
- Industrial Processes:Cogeneration facilities in petrochemical and refining sectors apply inlet cooling to maintain process steam reliability during summer demand spikes.
Combined cycle power plants command the dominant share of cooling system value; peak load applications are climbing the fastest as grid volatility intensifies.
End User:
Procurement sophistication separates regulated utilities with long-term planning horizons from merchant generators exposed to spot market price volatility.
- Utilities:Vertically integrated electric utilities with rate-base recovery mechanisms amortize inlet cooling capital across regulated asset lives, favoring permanent mechanical installations over evaporative alternatives.
- Power Generation Companies:Independent power producers and merchant generators prioritize operational flexibility, selecting modular systems that preserve fuel optionality across seasonal demand cycles.
- Manufacturing Plants:On-site cogeneration operators in cement, steel, and paper industries apply cooling to maintain captive power reliability during grid instability events.
- Oil & Gas Industry:Upstream and midstream facilities deploy portable fogging systems for temporary power at remote drilling and compression sites.
Utilities anchor the established installed base; power generation companies are gaining share fastest as merchant capacity expands.
Deployment:
Site constraints and environmental exposure determine material specifications and maintenance protocols across installation environments.
- Onshore:Permanent utility-scale installations at established power stations dominate capital deployment, with corrosion-resistant alloys replacing galvanized steel in coastal and desert environments.
- Offshore:Platform-based gas turbine installations require compact, salt-tolerant cooling systems with minimal water consumption, favoring closed-loop mechanical chillers over evaporative alternatives.
- Industrial Sites:Refinery and petrochemical complexes integrate inlet cooling with existing utility infrastructure, sharing cooling towers and water treatment assets.
- Power Facilities:Greenfield combined cycle plants specify cooling systems during initial engineering, avoiding retrofit integration complexity.
Onshore power facilities hold the majority of operating systems; offshore deployments are expanding most rapidly with platform electrification trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in arid regions where ambient temperature spikes erode gas turbine output most severely. Saudi Arabia, the United States, and the UAE anchor installed capacity, with emerging pull from India and Australia's grid-stressed coastal zones.
Saudi Arabia
The kingdom's gas turbine fleet expansion and national energy efficiency programs create structural demand for evaporative and mechanical cooling systems. The national regulator for electricity and cogeneration mandates performance standards that align directly with inlet cooling retrofits. Riyadh and the Eastern Province host the densest concentration of combined cycle capacity, where operators deploy high-pressure fogging systems to combat summer temperature extremes.
United States
Combined cycle plants across the Gulf Coast and Southwest prioritize mechanical chillers where wet-bulb depression limits evaporative effectiveness. The US EPA enforces emissions limits under the Clean Air Act that penalize capacity derating, forcing operators toward efficiency upgrades. Texas and California lead retrofit deployment, with merchant generators in the ERCOT and CAISO markets seeking sustained output during peak pricing periods.
United Arab Emirates
Dubai and Abu Dhabi power authorities specify inlet cooling for greenfield gas turbine installations to secure rated capacity through summer months. The country's national water and electricity regulator emphasizes efficiency benchmarks that favor thermal energy storage integration. Jebel Ali and Al Taweelah industrial zones concentrate operational demand, with district cooling providers exploring shared infrastructure models.
India
Grid instability and rising peak demand are pushing utilities toward inlet cooling on aging gas turbine fleets in coastal Maharashtra and Gujarat. The Central Electricity Authority issues technical standards that encourage efficiency retrofits on existing thermal assets. The Mumbai-Pune industrial corridor and Hazira petrochemical complex represent emerging retrofit clusters where captive power operators seek reliability guarantees.
Australia
Grid volatility and summer heat waves are accelerating inlet cooling adoption among gas peaking plants in Queensland and New South Wales. The national electricity market operator's reliability standards effectively mandate sustained capacity during temperature extremes. The Gladstone and Hunter Valley energy hubs concentrate deployment, with liquefied natural gas facilities integrating cooling to protect process power reliability.
Turbine Inlet Cooling Systems Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with turbine OEMs holding bundled service advantages in greenfield projects while independent providers capture retrofit velocity. The market structures around three archetypes: integrated power equipment conglomerates with captive cooling portfolios, dedicated environmental control specialists, and regional fabrication houses serving water-scarce markets. Consolidation pressure is elevating M&A activity among fogging system component suppliers, while technology licensing agreements proliferate between European chiller manufacturers and Middle Eastern EPC contractors.
Within the integrated equipment tier, General Electric leverages its turbine OEM relationships to bundle inlet cooling retrofits with long-term service agreements, while Siemens anchors European demand through combined cycle power plant solutions. Mee Industries occupies a specialist position focused on high-pressure fogging systems for desert climate applications. These three represent divergent strategic postures: full-stack integration, regional solution bundling, and climate-specific technical focus.
| Leading Market Players |
|---|
| General Electric |
| Schneider Electric |
| Johnson Controls |
| Camfil |
| Emerson Electric |
| Mee Industries |
| Mitsubishi Power |
| Caldwell Energy |
| Siemens |
| Others |
Supply Flow & Price Mechanics
Utility procurement officers and combined cycle plant operators command project-based contract structures with long-term service bundling, compressing margins for standalone equipment vendors while elevating aftermarket service pricing power. This buyer concentration forces suppliers toward integrated performance guarantees that shift risk allocation downstream.
Pricing Analysis
High-volume evaporative fogging skids trade on thin equipment margins offset by consumables and maintenance contracts, while mechanical chiller deployments capture premium project values through guaranteed output clauses. Price differentiation rests on wet-bulb effectiveness guarantees and corrosion-resistant alloy specifications. Cost compression in fogging nozzle assemblies is intensifying because Saudi water scarcity regulations are capping allowable consumption rates. Merchant generators in Texas ERCOT markets exhibit highest price sensitivity; Saudi utility procurement through national efficiency programs shows lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale combined cycle plant demand, while independent specialists serve retrofit markets through EPC contractor networks. Manufacturing concentrates in Germany, China, and the United States for compressor trains and heat exchanger cores. Component sourcing draws from nickel-based superalloy foundries in the US and precision nozzle fabricators in Switzerland. Single-source vulnerability in high-pressure pump assemblies creates procurement risk for desert climate deployments. Distribution runs through regional EPC partnerships in the Middle East and utility procurement frameworks in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turbine inlet cooling has become a vertical-integration race as OEMs capture retrofit revenue through captive service networks, while independent specialists pursue backward integration into alloy fabrication to defend margin pools.
For Market Incumbents: To counter independent specialists displacing bundled agreements through installation speed guarantees, deepen control over corrosion-resistant alloy supply through captive foundry investments or exclusive offtake arrangements with German and Swiss precision manufacturers. Anchor Saudi retrofit contracts by pre-certifying systems with the national regulator for electricity and cogeneration before procurement windows open. For New Entrants and Emerging Players: Begin with modular thermal energy storage skids targeting US Gulf Coast combined cycle plants where time-of-use arbitrage creates immediate payback visibility. White space concentrates in offshore platform electrification projects requiring compact salt-tolerant mechanical chillers. Lead with water consumption guarantees that preempt Saudi regulatory compliance reviews. For Investors and Strategic Acquirers: The window for entry favors specialty alloy fabricators with aerospace-grade corrosion coating capabilities transferable to fogging system manifolds. Long-term viability hinges on water-efficiency technology portfolios as regional scarcity regulations tighten. Monitor Saudi national energy efficiency program funding cycles and US EPA Clean Air Act enforcement intensity as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive sourcing of corrosion-resistant materials insulates margin pools from nickel price volatility. |
| Thermal Energy Storage Licensing | Technology transfer agreements with Middle Eastern EPC contractors accelerate deployment velocity. |
| Long-term Service Agreement Bundling | OEM-captive cooling retrofits lock in recurring revenue across Saudi combined cycle fleets. |
| Regulatory Pre-certification Investment | Early alignment with Saudi electricity regulator standards compresses validation timelines. |
| Offshore Platform Specialization | Salt-tolerant compact chillers capture platform electrification demand in the North Sea and Gulf of Mexico. |
Methodological Framework
Trade publications, EPC contractor project databases, and national utility regulatory filings formed the secondary backbone, cross-referenced against primary interviews with gas turbine maintenance directors, power plant procurement officers, and inlet cooling system engineering leads. Bottom-up unit deployment estimates triangulated against top-down capital expenditure flows from integrated power equipment conglomerates.
Historical capacity addition patterns and retrofit penetration rates across combined cycle fleets anchored the analytical framework, with projections developed across technology type, application configuration, and regional regulatory cluster. Modeled CAGRs derived from segment-level growth differentials between evaporative and mechanical cooling architectures, with inputs including Saudi gas turbine fleet expansion schedules and US EPA emissions compliance timelines.
Water scarcity regulation tightening, carbon border mechanism implementation, and turbine OEM service contract restructuring are the dominant revision risks. Forecasts reflect assumptions around continued arid climate capacity additions and sustained time-of-use electricity pricing differentials. Practitioners should monitor Saudi national energy efficiency program disbursements and US Clean Air Act enforcement actions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Europe Air Source Heat Pump Market
Cooling Systems
Energy Storage Temperature Control Equipment Market
Cooling Systems
Flue Gas Coolers Market
Cooling Systems
Solar Ventilation Systems Market
Cooling Systems
Cooling Tower Rental Market
Cooling Systems
Three Phase Cooling Fans Market
Cooling Systems
Thermosiphon Cooling System Market
Cooling Systems
Cryosystem Market
Cooling Systems
Industrial Radiators Market
Cooling Systems
Global Secondary Refrigerants Market
Cooling Systems
Battery Cooling Plate Market
Cooling Systems
Heat Pipe Market
Cooling Systems
Solar Fan Market
Cooling Systems
Solar Cooling Market
Cooling Systems
Horizontal Air Flow Condensers Market
Cooling Systems
Evaporative Condensing Unit Market