
 Thermosiphon Cooling System Market | 2026-2036
Thermosiphon Cooling System Market Size, Share, and Industry Trends Forecast 2026-2036
Thermosiphon Cooling System Market Analytics
Data center cooling is restructuring demand patterns across the thermosiphon landscape. Vertiv Group Corp. dominates hyperscale facility deployments with specialized passive thermal architectures. Alfa Laval leverages its heat exchange engineering heritage to anchor marine and industrial segments. Schneider Electric extends its building technology portfolio into integrated data center cooling systems.
A thermosiphon cooling system circulates working fluid through natural convection driven by density differentials between heated and cooled sections, typically operating with refrigerants or dielectric fluids at temperature differentials of 10–30°C without mechanical pumping. Its primary purpose is to dissipate thermal loads in environments where reliability, noise reduction, or energy efficiency outweighs active cooling precision. Passive Systems occupy the largest installed base due to minimal maintenance requirements and absence of parasitic pump energy, though Hybrid Systems are gaining fastest in data center applications where load variability demands supplemental active capacity. Industrial Cooling represents the most mature application segment with entrenched replacement cycles, while Data Center Cooling concentrates margin pools as operators prioritize power usage effectiveness ratios.
The EPA SNAP program and EU F-Gas Regulation are restricting high-global-warming-potential refrigerants, pushing thermosiphon designers toward CO2, ammonia, and hydrocarbon working fluids that align with emerging compliance thresholds. ISO 5149 and ASHRAE standards govern system safety and thermal performance certification, creating baseline requirements for market access across North American and European jurisdictions. Stakeholders must monitor refrigerant chemistry transitions and efficiency benchmarking protocols to align product roadmaps with tightening environmental performance thresholds.
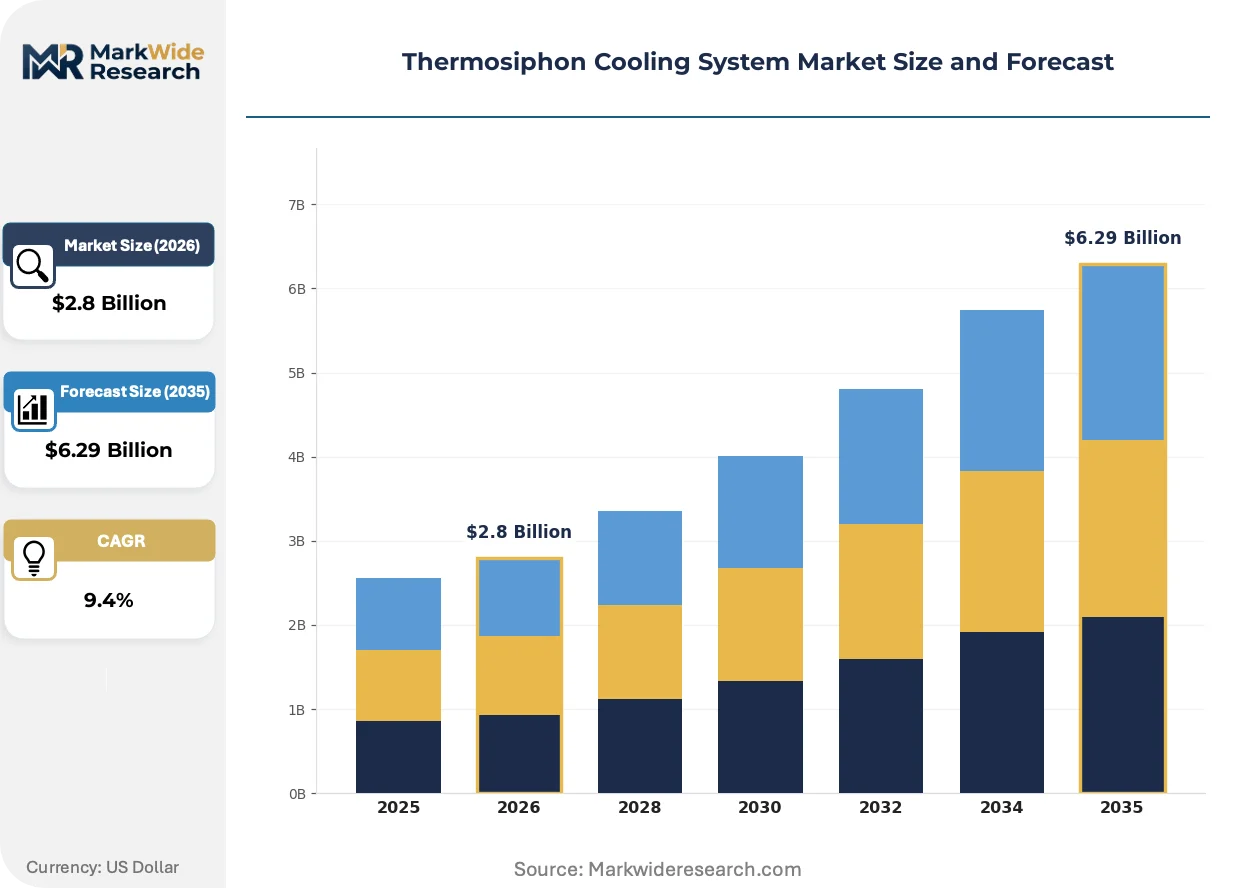
Market Dynamics
Passive thermal architectures are displacing active cooling in data center infrastructure as power density thresholds exceed mechanical chiller efficiency curves, forcing operators toward density-driven convection systems.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant phase-down mandates in Europe accelerate thermosiphon deployments using CO2 and hydrocarbon working fluids, eliminating synthetic refrigerant dependency.
- Data center power density:Hyperscale facilities in Germany and the Netherlands are retrofitting legacy active cooling with passive thermosiphon loops to curb power usage effectiveness ratios.
- Natural convection physics:Elimination of parasitic pump energy draws industrial cooling operators toward gravity-driven circulation for continuous-process thermal stability.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger fabrication depends on non-ferrous metal supply chains concentrated in Chile and Guinea, exposing margin structures to commodity price swings.
- Working fluid safety codes:ISO 5149 and ASHRAE flammability classifications restrict ammonia and hydrocarbon charge sizes in occupied spaces, limiting residential and commercial deployment.
- Precision cooling substitution:Liquid immersion cooling for AI training clusters offers tighter temperature control than thermosiphon passive loops, capturing high-margin density applications.
Strategic Opportunities
- India data center construction:The country's central electricity regulator and state-level renewable purchase obligations create openings for passive cooling in solar-powered edge facilities.
- Marine thermal management:Ammonia-based thermosiphons for container ship reefers align with International Maritime Organization decarbonization timelines for auxiliary engine load reduction.
- Industrial waste heat recovery:Steel and cement plants in Germany are retrofitting thermosiphon preheaters to capture exhaust thermal energy under national efficiency mandate enforcement.
Industry Challenges
- Two-phase flow simulation expertise:Computational fluid dynamics modeling for natural convection systems requires specialized thermal engineering talent scarce outside aerospace and nuclear sectors.
- ASHRAE certification timelines:Thermal performance validation protocols extend product development cycles, compressing competitive response windows for emerging working fluid formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermosiphon Cooling System Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Systems, Active Systems, Hybrid Systems, Pumped Systems End User: Food Processing, Electronics, Automotive, HVAC Application: Industrial Cooling, Residential Cooling, Data Center Cooling, Marine Cooling Technology: Thermal Management, Fluid Circulation, Heat Exchange, Temperature Regulation |
| Companies Covered | Alfa Laval, Danfoss, Modine Manufacturing Company, Kelvion Holding GmbH, Schneider Electric, Vertiv Group Corp., Mitsubishi Electric Corporation, Rittal GmbH & Co. KG, SPX FLOW, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermosiphon Cooling System Market Evolving Landscape
Working fluid chemistry and control electronics are converging to expand thermosiphon applicability beyond steady-state industrial loads into variable-demand environments.
Dielectric fluid formulations with engineered vapor pressure curves are automating temperature response in edge computing enclosures. Colocation operators in Texas and Arizona are piloting these self-regulating loops for outdoor cabinet deployments. The technology is automating thermal management decisions previously requiring active chiller modulation, reducing remote site maintenance dispatch frequency.
The EPA SNAP program and EU F-Gas Regulation are synchronizing refrigerant restrictions across Atlantic markets. Industrial cooling OEMs face converging compliance thresholds for global warming potential limits below 150. Marine and data center segments are responding with ammonia and CO2 charge architectures, accepting higher pressure vessel costs for regulatory alignment.
Colocation buyers are unbundling thermal infrastructure from rack contracts, demanding metered cooling-as-a-utility rather than bundled space-and-power agreements. Wholesale data center developers in Northern Virginia and Frankfurt are restructuring offerings to separate mechanical plant capex from recurring lease terms. This shift is most visible among cloud hyperscalers negotiating direct equipment ownership with site operators.
Thermosiphon Cooling System Market Segmentation
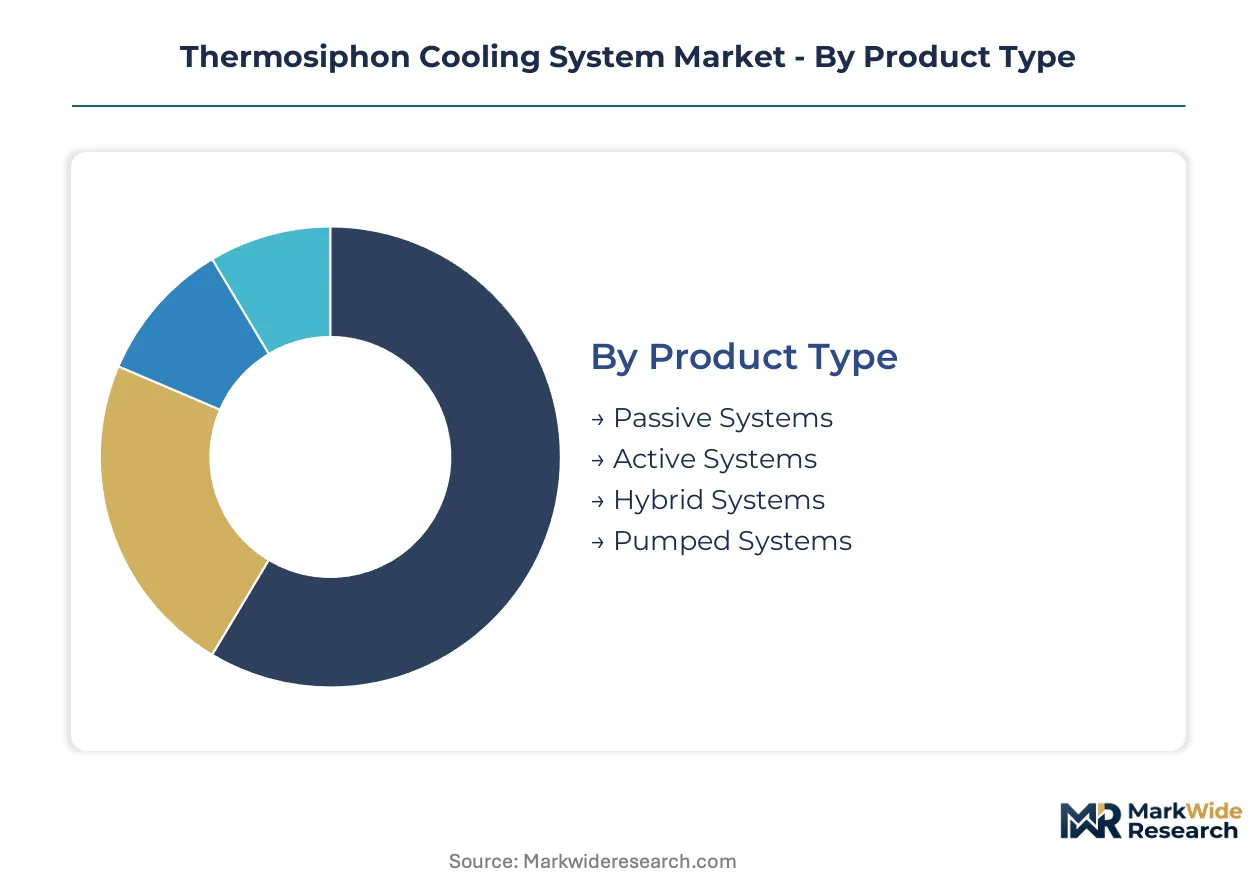
Thermosiphon architectures vary sharply in integration depth — from standalone passive loops to embedded active modules within larger mechanical plants. Understanding where each configuration sits on this spectrum clarifies procurement patterns and margin structures across cooling infrastructure buyers.
Product Type:
Passive Systems deploy as fully autonomous thermal loops requiring no external power or control interfaces, while Active and Hybrid variants embed within broader mechanical ecosystems as sub-components.
- Passive Systems:Gravity-driven circulation eliminates parasitic energy draw entirely. Data center operators in Germany and the Netherlands deploy these for baseline thermal loads where steady-state operation dominates, accepting wider temperature bands in exchange for elimination of pump maintenance and failure modes.
- Hybrid Systems:Combine natural convection with supplemental active capacity for load-following capability. Edge computing facilities in Texas and Arizona pilot these configurations where diurnal ambient swings exceed passive-only thermal budgets, triggering mechanical boost only during peak thermal events.
- Active Systems:Require continuous powered circulation, functioning essentially as pumped loops with thermosiphon-like geometry. These embed most commonly in legacy industrial retrofits where existing control infrastructure accommodates active management.
- Pumped Systems:Use mechanical impellers to overcome hydrostatic head limitations in tall installations or complex piping networks. Chemical processing plants employ these where vertical lift requirements exceed natural convection pressure differentials.
Volume placements concentrate in Passive Systems; the faster expansion belongs to Hybrid Systems.
End User:
Cost tier differentiation separates capital-intensive continuous-process industries from price-sensitive intermittent-use applications.
- Food Processing:Continuous refrigeration demand at dairies and cold storage facilities in Germany drives specifications for ammonia-based thermosiphon architectures. The EU F-Gas Regulation accelerates natural working fluid adoption here, with operators accepting higher pressure vessel costs for regulatory compliance.
- Electronics:Semiconductor fabrication and battery manufacturing require sub-ambient precision that thermosiphons struggle to deliver. Niche deployments concentrate in power electronics cooling where dielectric fluid loops manage inverter thermal loads in renewable energy converters.
- Automotive:Thermal management for electric vehicle battery packs and power electronics represents emerging demand. OEMs in Germany evaluate thermosiphon loops for reducing auxiliary loads that erode driving range.
- HVAC:Building-scale deployments remain limited by working fluid charge size restrictions under ISO 5149 flammability codes. Commercial rooftop units in the United States experiment with CO2 thermosiphons for heat recovery applications.
Food Processing anchors current procurement volumes; Electronics shows steepest expansion trajectory as power density climbs in computing and energy conversion equipment.
Application:
Application maturity separates established industrial replacement cycles from emerging infrastructure buildouts.
- Industrial Cooling:Mature installed base with predictable refresh timelines. Steel and cement plants in Germany retrofit thermosiphon preheaters to capture exhaust thermal energy under national efficiency mandate enforcement.
- Data Center Cooling:Hyperscale facilities prioritize power usage effectiveness ratios, creating margin concentration for passive thermal architectures. Vertiv Group Corp. dominates deployments with specialized convection systems for density-driven loads.
- Residential Cooling:Safety code restrictions on ammonia and hydrocarbon charge sizes in occupied spaces limit penetration. European heat pump manufacturers explore compact CO2 thermosiphons for domestic hot water preheating.
- Marine Cooling:Container ship reefers and auxiliary engine thermal management align with International Maritime Organization decarbonization timelines. Alfa Laval anchors this segment with ammonia-based architectures for auxiliary load reduction.
Industrial Cooling maintains the largest installed base; Data Center Cooling gains share fastest as cloud infrastructure expansion accelerates.
Technology:
Technology layers stack from foundational heat exchange physics through automated control systems.
- Thermal Management:System-level optimization of heat source coupling, working fluid selection, and rejection pathway design. Schneider Electric extends building technology portfolios into integrated cooling systems spanning this layer.
- Fluid Circulation:Two-phase flow dynamics and natural convection physics govern loop performance. Computational fluid dynamics modeling expertise concentrates in aerospace and nuclear engineering sectors, creating talent scarcity for thermosiphon designers.
- Heat Exchange:Fin-and-tube or plate heat exchanger fabrication depends on copper and aluminum supply chains concentrated in Chile and Guinea. Commodity price volatility directly impacts margin structures at this layer.
- Temperature Regulation:Control electronics and dielectric fluid formulations with engineered vapor pressure curves enable autonomous thermal response. Colocation operators pilot self-regulating loops for remote site maintenance reduction.
Heat Exchange captures the majority of bill-of-materials value; Temperature Regulation climbs fastest as automation penetrates edge computing deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for thermosiphon cooling systems clusters in Germany and the United States, while consumption concentrates in data center hubs across the Netherlands, India, and Singapore where passive thermal management addresses power density constraints.
United States
Hyperscale data center construction in Northern Virginia and Phoenix drives thermosiphon deployment for power usage effectiveness optimization. The EPA SNAP program restricts high-global-warming-potential refrigerants, accelerating CO2 and hydrocarbon working fluid adoption. Texas colocation operators pilot dielectric fluid thermosiphons for outdoor edge computing cabinets in high-ambient conditions.
Germany
Industrial cooling retrofits in steel and cement plants combine with data center efficiency mandates to sustain thermosiphon procurement volumes. The EU F-Gas Regulation enforces refrigerant phase-down schedules below 150 GWP thresholds, eliminating synthetic alternatives. Frankfurt's hyperscale cluster anchors European demand for passive thermal architectures in cloud infrastructure.
Netherlands
Data center power density requirements exceed mechanical chiller efficiency curves, forcing operators toward natural convection systems. National efficiency standards for digital infrastructure align with EU Green Deal decarbonization timelines. Amsterdam's metropolitan area hosts concentrated deployments of hybrid thermosiphon loops for load-following capability.
India
Central electricity regulator mandates and state-level renewable purchase obligations create openings for passive cooling in solar-powered edge facilities. The Bureau of Indian Standards governs pressure vessel safety for ammonia-based industrial architectures. Maharashtra's data center corridor near Mumbai attracts thermosiphon installations addressing tropical ambient conditions.
Singapore
Tropical climate constraints and land scarcity elevate passive thermal management priority for data center sustainability certifications. National water and energy efficiency standards restrict active cooling alternatives in new facility approvals. The Jurong and Tuas industrial zones concentrate deployments of CO2 thermosiphons for waste heat recovery applications.
Thermosiphon Cooling System Market Competitive Landscape
Top-tier vendors anchor hyperscale data center deployments, while mid-tier fabricators serve industrial replacement cycles and regional marine applications. The vendor base stratifies across three tiers: integrated building technology conglomerates, specialized heat exchange engineering houses, and regional fabrication specialists. Two dominant competitive moves are reshaping positioning: backward integration into copper and aluminum heat exchanger supply chains, and technology licensing partnerships for CO2 high-pressure system architectures.
Within the integrated systems tier, Schneider Electric and Vertiv Group Corp. exemplify building technology extension strategies into data center thermal infrastructure. Among specialized heat exchange engineering houses, Alfa Laval occupies a position representing marine and industrial segment anchoring. These three companies collectively represent the archetype spectrum spanning integrated building systems, specialized thermal engineering, and hyperscale facility deployment.
| Leading Market Players |
|---|
| Alfa Laval |
| Danfoss |
| Modine Manufacturing Company |
| Kelvion Holding GmbH |
| Schneider Electric |
| Vertiv Group Corp. |
| Mitsubishi Electric Corporation |
| Rittal GmbH & Co. KG |
| SPX FLOW, Inc. |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between ASHRAE-validated passive architectures and uncertified commodity assemblies manifests in pricing spreads exceeding 40 percent, with premium tiers commanding captive supply arrangements for copper heat exchanger forgings while economy segments absorb spot-market aluminum volatility. This divergence concentrates procurement leverage among hyperscale data center operators in Northern Virginia and Frankfurt, who negotiate direct equipment ownership to unbundle thermal infrastructure from colocation lease terms.
Pricing Analysis
Short-lead-time premiums for CO2 high-pressure vessel systems run 15-25 percent above standard contract pricing, reflecting fabrication bottlenecks at certified pressure equipment shops in Germany and the United States. Project-based pricing dominates data center deployments, with three-tier pricing structure across premium, standard, and economy levels differentiated by ASHRAE certification status and working fluid charge size. Cost compression in economy passive loops is intensifying because Chinese fabricators are expanding fin-and-tube capacity. Food processing buyers in Germany exhibit lowest price sensitivity due to EU F-Gas compliance deadlines, while Texas edge computing operators drive hardest bargain negotiations.
Supply Chain Analysis
Single-source vulnerability sits with Chilean copper cathode and Guinean bauxite for aluminum smelter feedstock, exposing heat exchanger fabricators to commodity price swings that transmit directly into bill-of-materials costs. Manufacturing capacity clusters in Germany, the United States, and China, with raw material dependencies spanning Chilean copper, Norwegian aluminum, and Saudi petrochemical feedstocks for dielectric fluid formulations. Tariff exposure on Chinese aluminum extrusions threatens margin structures at mid-tier fabricators. Distribution runs through OEM-direct channels for hyperscale data center contracts, while industrial replacement cycles flow through regional HVAC distributors and marine service integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thermosiphon cooling system market is executing a technology-transition phase as natural working fluid architectures displace synthetic refrigerant systems under converging EPA SNAP and EU F-Gas regulatory timelines.
For Market Incumbents: Deepen backward integration into copper heat exchanger supply chains to defend margin position against commodity volatility, while accelerating ASHRAE certification investments to capture hyperscale data center procurement locked behind thermal performance validation protocols. Vertiv and Schneider Electric's integrated building technology portfolios face substitution pressure from liquid immersion cooling for AI training clusters above 50kW per rack.
For New Entrants and Emerging Players: Direct-to-hyperscaler digital sales channels bypass incumbent distributor relationships and compress customer acquisition costs for ammonia-based marine thermosiphon specialists. Target India's Maharashtra data center corridor and solar-powered edge facilities under CEA renewable purchase obligations as the most penetrable geography. Lead with CO2 charge architecture expertise to differentiate against synthetic refrigerant legacy portfolios.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to building technology conglomerates seeking thermal management capabilities. Long-term viability hinges on regulatory alignment with sub-150 GWP refrigerant mandates across Atlantic markets. Target acquisition archetype: specialized heat exchange engineering houses with ISO 5149 certification infrastructure and two-phase flow simulation talent. Watch EPA SNAP program expansion to additional refrigerant categories as inflection signal for natural working fluid acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Supply | Captive copper and aluminum sourcing insulates margin structures from Chilean and Guinean commodity volatility. |
| CO2 High-Pressure System Architecture Licensing | Technology partnerships with German pressure vessel fabricators accelerate EU F-Gas compliance positioning. |
| ASHRAE Thermal Performance Certification Investment | Validation protocols extend competitive moats against uncertified Chinese entrants in data center segments. |
| Marine Ammonia Thermosiphon Deployment | IMO decarbonization timelines align with Alfa Laval's auxiliary engine load reduction value proposition. |
| Dielectric Fluid Formulation R&D Partnership | Engineered vapor pressure curves enable autonomous temperature response for Texas edge computing pilots. |
Research Methodology
Independent corroboration across data center facility operators, industrial cooling procurement directors, and marine thermal engineering specialists underwrites the qualitative findings, with secondary validation drawing from EPA SNAP regulatory filings, EU F-Gas implementation reports, and ASHRAE standards documentation. Bottom-up triangulation of equipment shipment data and top-down reconciliation against hyperscale capex disclosures anchor volume estimates. Primary fieldwork encompassed plant managers at German steel and cement facilities, procurement leads at Netherlands colocation operators, and technical R&D directors at heat exchange engineering houses.
Comparable-period anchoring to 2020-2023 industrial cooling replacement cycles and 2021-2024 data center construction waves structured the projection horizon, with CAGRs derived from regression analysis of working fluid adoption curves against regulatory phase-down schedules. Segmentation dimensions span product type, application, end-use industry, and working fluid chemistry. Forecast inputs incorporate EU F-Gas GWP threshold enforcement timelines and EPA SNAP program expansion assumptions across the modeling period.
The model holds under steady regulatory enforcement and copper price band stability; deviation in refrigerant chemistry transition speed or aluminum tariff regimes would shift volume trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Flue Gas Coolers Market
Cooling Systems
Global Air Coolers Market
Cooling Systems
Solar Cold Room Market
Cooling Systems
Chilled Water Storage System Market
Cooling Systems
Water Cooling Corona Discharge Ozone Generator Market
Cooling Systems
United States Heat Pump Market
Cooling Systems
Temporary Power and Cooling Solutions Market
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
Europe Cooling Systems Market
Cooling Systems
Cryosystem Market
Cooling Systems
North America Evaporative Cooling Market
Cooling Systems
Cold Trap Market
Cooling Systems
Lithium Battery Liquid Cooling Pump Market
Cooling Systems
Offshore Air Handling Units Market
Cooling Systems
Europe Air Source Heat Pump Market
Cooling Systems
Low Temperature Radiators Market