
 Offshore Air Handling Units Market | 2026-2036
Offshore Air Handling Units Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Air Handling Units Market Intelligence
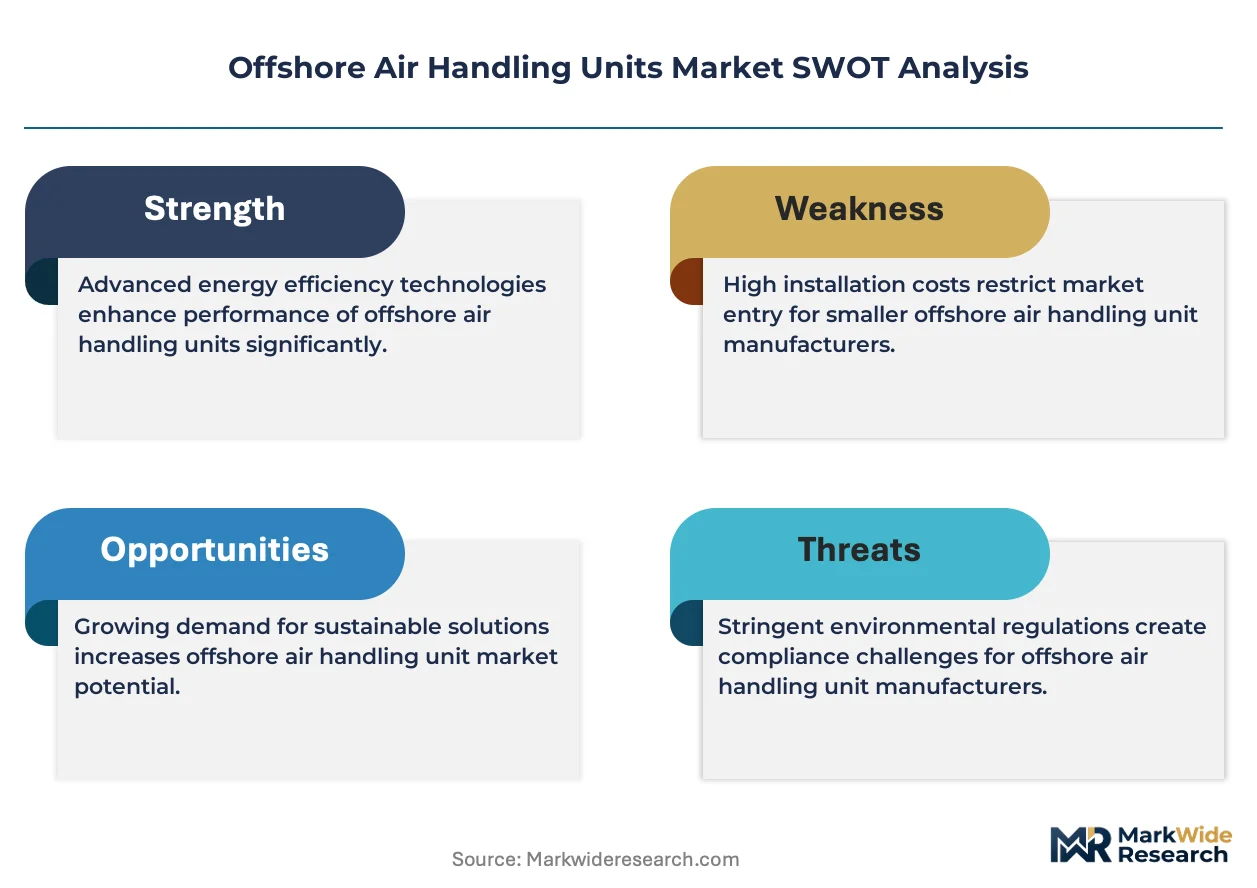
The EU's ATEX directive for equipment in explosive atmospheres is realigning the cost-of-entry calculus for manufacturers. Heinen & Hopman Engineering specializes in custom solutions for harsh marine environments, including explosion-proof units. In contrast, larger players like Johnson Controls and Carrier Corporation leverage their global manufacturing scale and extensive distribution networks to offer standardized, compliant systems for a broader range of offshore applications, from remote monitoring stations to large platforms.
An offshore air handling unit is a specialized HVAC system designed to circulate and condition air on marine platforms and vessels. These units are constructed with materials like stainless steel (316L) to withstand corrosive saltwater environments and often feature explosion-proof components for safety. Custom units command higher margins and are essential for complex floating production systems where space and specifications are unique. Demand-controlled ventilation technology is gaining traction over constant air volume systems due to its superior energy efficiency in variable occupancy environments.
Compliance with maritime safety standards like SOLAS (Safety of Life at Sea) is non-negotiable for all installed equipment. Frameworks like ISO 15138 and Norway's NORSOK standards dictate specific design criteria for HVAC on petroleum and natural gas installations, influencing performance benchmarks. Navigating the patchwork of regional certifications and material requirements for different offshore basins remains a critical challenge for suppliers.
Market Dynamics
The central dynamic is the divergence between demand for highly customized, explosion-proof units for complex assets and the push for standardized, globally compliant systems from large-scale manufacturers, a tension amplified by regulations like the EU's ATEX directive.
Growth Catalysts
- Floating Asset Expansion:The development of complex Floating Production Systems (FPSOs), particularly in deepwater basins like offshore Brazil, creates consistent demand for specialized, custom-engineered air handling units from production contractors.
- Environmental Regulation:The EU's F-Gas Regulation is compelling equipment redesigns to incorporate low-GWP refrigerants, creating a replacement and upgrade cycle for AHU systems across the European continental shelf.
- Energy Efficiency Mandates:Demand-controlled ventilation technology is gaining adoption over constant air volume systems, as platform operators seek to reduce operational expenditures by optimizing energy use in variable occupancy zones.
Market Restraints
- Material Cost Volatility:The high upfront cost and price fluctuations of corrosion-resistant materials, such as 316L stainless steel, directly impact manufacturing margins and project budgets for offshore-grade units.
- Regulatory Fragmentation:Navigating the complex and often overlapping patchwork of regional certifications, such as NORSOK standards in Norway and ISO 15138, increases compliance costs and lengthens project timelines.
- Space and Weight Constraints:The inherent limitations on space and weight aboard offshore platforms, especially floating production units, impose significant design and engineering challenges for fitting powerful HVAC systems.
Strategic Opportunities
- Predictive Maintenance Services:Integrating Industrial IoT sensors and remote monitoring capabilities into AHUs creates an opportunity for new service-based revenue streams centered on predictive maintenance and operational analytics.
- Modular System Development:Designing containerized and modular AHU solutions can address market needs for rapid deployment, easier retrofitting on aging assets, and simplified logistics for remote offshore locations.
- Digital Twin Integration:Creating digital twins of AHU systems allows for simulation of performance under various operating conditions, optimizing design and enabling remote troubleshooting for offshore installations.
Industry Challenges
- Specialized Talent Scarcity:A shortage of engineers possessing dual expertise in both advanced HVAC system design and the stringent requirements of explosion-proof equipment standards like ATEX hinders product development and project execution.
- Legacy System Integration:Integrating modern, energy-efficient AHUs with older, often proprietary, control and automation systems on existing platforms presents significant technical and compatibility hurdles for upgrade projects.
- Certification Bottlenecks:The lengthy and expensive process of achieving certification for explosion-proof components and systems for different regional standards acts as a barrier to entry and slows the introduction of new technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Air Handling Units Market |
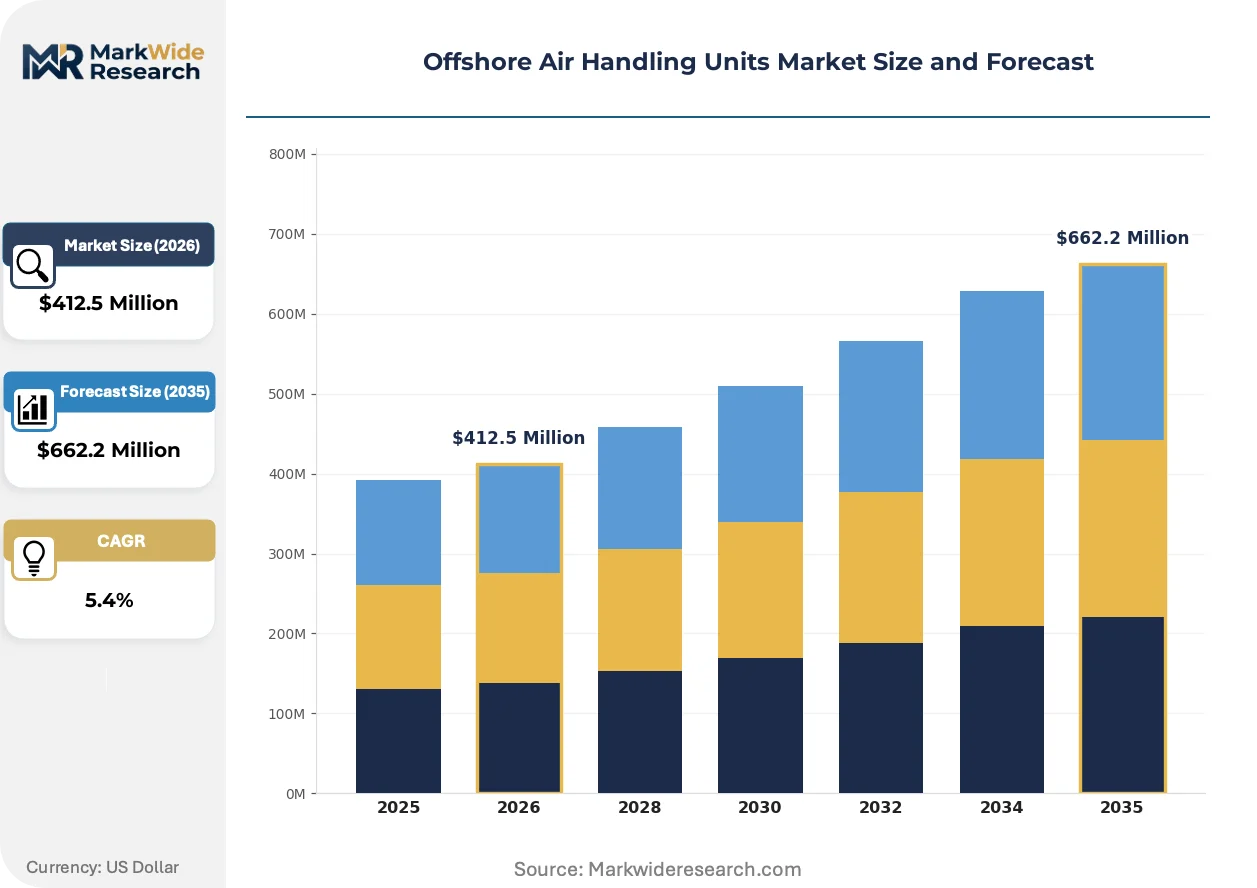
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Units, Custom Units, Packaged Units, Energy Recovery Units, Industrial Units Technology: Variable Air Volume, Constant Air Volume, Demand-Controlled Ventilation, Heat Recovery Ventilation, Desiccant Dehumidification Application: Oil & Gas Platforms, Marine Vessels, Floating Production Systems, Subsea Stations, Remote Monitoring Stations End User: Exploration Firms, Production Contractors, Maintenance Providers, Offshore Service Operators |
| Companies Covered | Johnson Controls, Trane, Inc, Carrier Corporation, Daikin Industries Ltd, Systemair Ltd, Hitachi Appliances, Inc, Thermax, Inc, Heinen & Hopman Engineering, Broad Air Conditioning Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Air Handling Units Market Strategic Shifts & Innovations
A push toward digitalization for operational efficiency now runs parallel with stricter material and safety mandates. This dual pressure is reshaping how offshore air handling units are designed, specified, and maintained over their lifecycle.
Demand-controlled ventilation technology utilizes advanced sensors to modulate airflow based on real-time occupancy and air quality metrics. Production contractors are specifying DCV for new-build floating production systems to achieve stringent energy reduction targets. This intelligent airflow management is rewriting the baseline energy consumption profile for offshore HVAC operations.
The European Union's F-Gas Regulation imposes firm restrictions on the use of refrigerants with a high Global Warming Potential. This forces a shift in equipment design towards natural refrigerants or low-GWP synthetic alternatives. The regulation most directly impacts system specifiers and component suppliers, who must validate new refrigerant compatibility with existing heat exchanger and compressor technologies.
Client specifications for complex projects increasingly favor custom-engineered solutions over standardized, off-the-shelf units. This preference for bespoke design displaces volume-driven procurement from general HVAC distributors in favor of direct collaboration with specialized marine engineering firms. The trend is most pronounced for deepwater assets in regions like the Gulf of Mexico and offshore Brazil, where unique platform layouts dictate equipment form factors.
Offshore Air Handling Units Market Segmentation
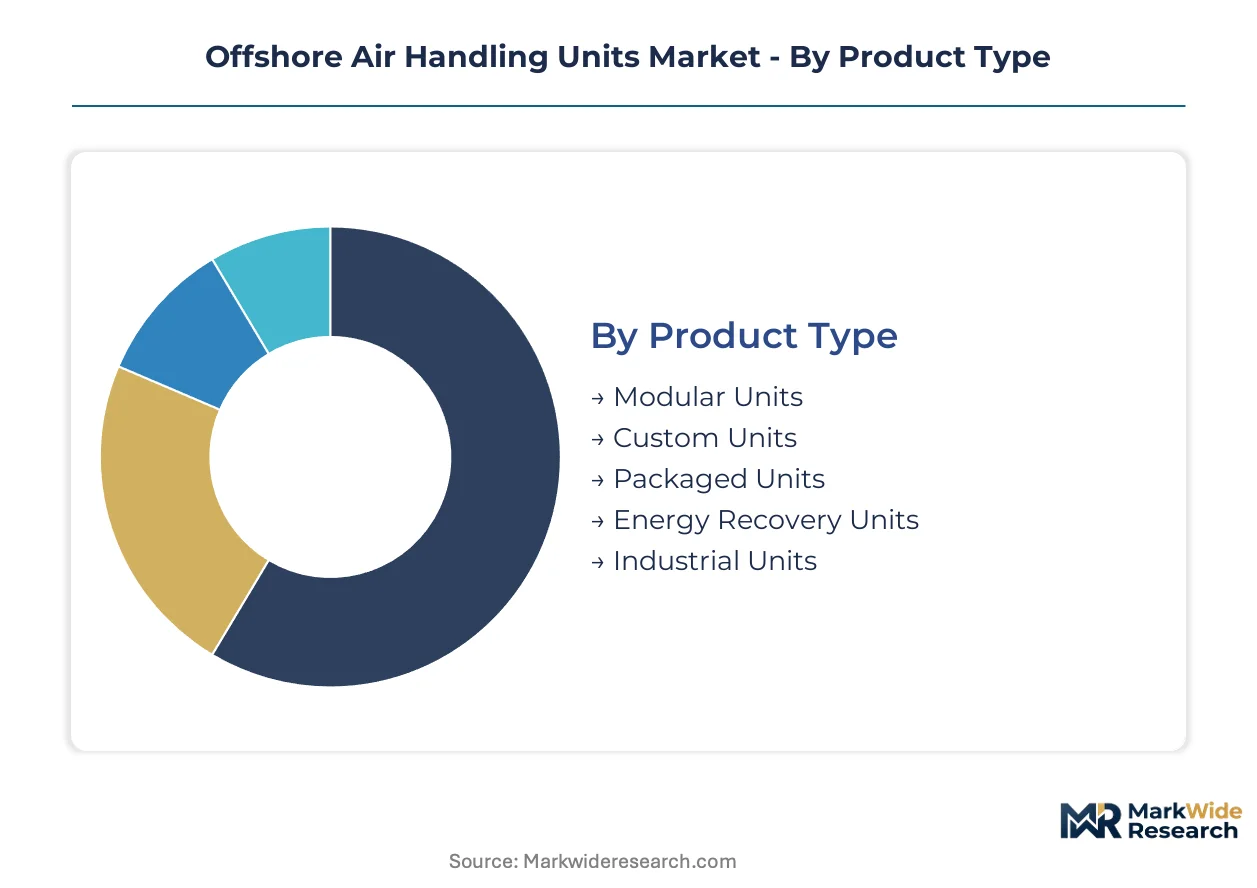
The Offshore Air Handling Units Market segmentation provides a granular view of demand drivers and technological preferences across the marine energy sector. Understanding these distinct segments is crucial for manufacturers to tailor solutions that meet specific operational demands and regulatory compliance in harsh offshore environments.
Product Type:
The lifecycle of offshore assets drives distinct upgrade and replacement cycles, directly influencing the demand for various air handling unit product types.
- Custom Units:These specialized systems are engineered for unique specifications, often integrating explosion-proof components and corrosion-resistant materials like 316L stainless steel. Demand concentrates in complex floating production systems where space and operational parameters are highly constrained.
- Modular Units:Designed for rapid deployment and easier retrofitting, these containerized solutions offer flexibility for aging assets and remote offshore locations. Their standardized interfaces and scalable design address needs for quick installation and simplified logistics.
- Packaged Units:These self-contained systems integrate all necessary components within a single housing, offering a simpler installation process for a range of offshore applications. They typically serve less complex platforms or auxiliary structures.
- Energy Recovery Units:Focused on optimizing energy efficiency, these units capture heat or coolness from exhaust air to condition incoming fresh air. They are increasingly specified to meet stringent energy reduction targets on modern platforms.
- Industrial Units:Robust and heavy-duty, these units are built for continuous operation in demanding industrial settings, including specific zones within large offshore installations.
Custom Units sits at the top of the volume ranking, with Modular Units climbing the fastest.
Technology:
Specific operational requirements across diverse offshore applications dictate the selection of appropriate air handling technologies.
- Demand-Controlled Ventilation:This technology uses advanced sensors to modulate airflow based on real-time occupancy and air quality, optimizing energy use. Production contractors specify DCV for new-build floating production systems to achieve stringent energy reduction targets.
- Variable Air Volume:VAV systems adjust the volume of air supplied to a space based on demand, providing precise temperature control and energy savings. These systems are a foundational choice for modern offshore installations, balancing comfort with efficiency.
- Constant Air Volume:CAV systems deliver a continuous, fixed volume of air, offering simplicity in design and operation. While less energy-efficient than VAV or DCV, they remain present in older installations or specific zones with stable requirements.
- Heat Recovery Ventilation:These systems recover heat from exhaust air to pre-condition incoming fresh air, reducing the energy load on the main HVAC system. They are critical for maintaining thermal efficiency in extreme offshore climates.
- Desiccant Dehumidification:Employing desiccant materials to remove moisture from the air, this technology is essential for maintaining optimal humidity levels in sensitive areas. It prevents corrosion and ensures equipment longevity in humid marine environments.
Demand-Controlled Ventilation technology is increasingly specified for new installations, while Variable Air Volume systems remain a foundational choice.
Application:
The diverse operational mandates of offshore operators shape the demand profile for air handling units across various marine applications.
- Floating Production Systems:These complex assets, including FPSOs, require highly specialized and custom-engineered AHUs due to unique space, weight, and environmental constraints. Demand for these units is consistent in deepwater basins like offshore Brazil.
- Oil & Gas Platforms:Established fixed and semi-submersible platforms represent a significant installed base, driving demand for both new installations and replacement/upgrade cycles of AHU systems. These platforms require robust, explosion-proof components.
- Marine Vessels:Air handling units for marine vessels, such as offshore support vessels and specialized transport ships, prioritize compact design and compliance with maritime safety standards like SOLAS. These units ensure crew comfort and equipment protection.
- Subsea Stations:While often uncrewed, certain subsea control and processing stations require specialized environmental control systems for sensitive electronics. These units must withstand extreme pressure and temperature variations.
- Remote Monitoring Stations:Small, often uncrewed stations for environmental or operational monitoring require compact and highly reliable AHUs to protect sensitive instrumentation. Energy efficiency is paramount for these autonomous installations.
Floating Production Systems drive significant demand for specialized solutions, and Oil & Gas Platforms represent a substantial installed base.
End User:
The maturity of offshore asset development and operational phases directly influences the engagement patterns of different end-user segments.
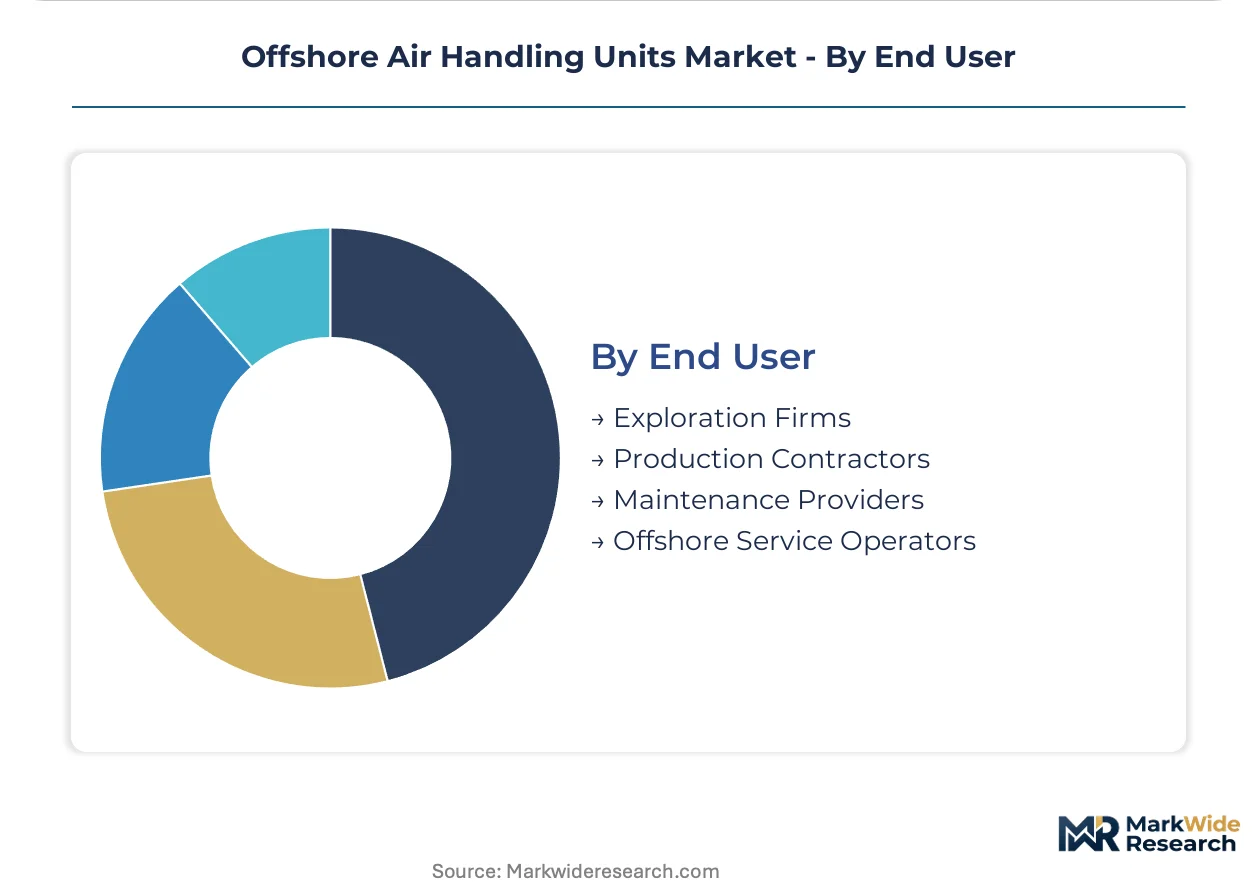
- Production Contractors:These firms are primary procurers for new-build projects, particularly for complex assets like FPSOs, demanding custom-engineered and compliant AHU solutions. They focus on integrating systems for long-term operational efficiency.
- Maintenance Providers:Responsible for the ongoing upkeep and repair of offshore assets, these providers drive demand for replacement parts, upgrade kits, and service contracts for existing AHU installations. Their focus is on reliability and extending asset life.
- Exploration Firms:While not direct procurers of large-scale AHUs, these firms influence early-stage project specifications and environmental control requirements for temporary exploration facilities. They prioritize robust and transportable solutions.
- Offshore Service Operators:This broad category includes companies managing a range of support vessels, accommodation platforms, and specialized services. They require durable and compliant AHUs for crew comfort and operational continuity.
Production Contractors are central to new project procurement, while Maintenance Providers secure recurring service-based revenues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The offshore energy sector, particularly in established regions like the North Sea and the Gulf of Mexico, historically scaled the initial demand for specialized air handling units. This foundational scaling established critical operational requirements and laid the groundwork for current market expansion. These mature basins continue to drive both innovation in equipment design and procurement patterns for advanced AHU systems.
United States
Deepwater developments in the Gulf of Mexico generate consistent demand for custom-engineered air handling units, particularly for Floating Production Systems. Environmental Protection Agency (EPA) regulations concerning refrigerant use influence equipment selection and upgrades. Houston, Texas, serves as a primary hub for offshore engineering, project management, and equipment supply for the region's energy sector.
Brazil
Extensive deepwater Floating Production Storage and Offloading (FPSO) developments in offshore Brazil create substantial demand for highly specialized and explosion-proof AHU solutions. The National Agency of Petroleum, Natural Gas and Biofuels (ANP) enforces stringent safety and environmental compliance for offshore installations. Rio de Janeiro and Espírito Santo states are central to offshore project management, fabrication, and service provision.
Norway
North Sea exploration and production, coupled with harsh environment operations, drive demand for robust and compliant air handling units. NORSOK standards dictate specific HVAC design criteria for petroleum and natural gas installations, influencing performance benchmarks. Stavanger and Bergen are critical centers for offshore technology development, maintenance services, and specialized equipment manufacturing.
United Arab Emirates
The expansion of offshore oil and gas fields and significant investments in new production facilities create sustained demand for industrial-grade air handling units. ADNOC Group environmental and safety guidelines significantly influence equipment specifications and procurement. Abu Dhabi hosts major offshore operators and engineering firms, anchoring regional procurement and project execution.
Offshore Air Handling Units Market Key Industry Players
The competitive structure tilts toward specialized solution providers, balancing bespoke engineering capabilities with the scale of diversified HVAC manufacturers. This market features a tiered landscape, including highly specialized engineering firms and large global industrial players. Companies pursue strategic partnerships to integrate complex systems and diversify their product portfolios to address varying offshore application needs.
At the scale-driven end, Johnson Controls and Carrier Corporation exemplify global manufacturing capabilities and extensive distribution networks for standardized, compliant systems. Heinen & Hopman Engineering, conversely, represents specialized engineering firms, focusing on custom solutions for harsh marine environments, including explosion-proof units. These players collectively address the market's dual demand for both volume and highly specific technical requirements.
| Leading Market Players |
|---|
| Johnson Controls |
| Trane, Inc |
| Carrier Corporation |
| Daikin Industries Ltd |
| Systemair Ltd |
| Hitachi Appliances, Inc |
| Thermax, Inc |
| Heinen & Hopman Engineering |
| Broad Air Conditioning Co. Ltd |
Cost & Logistics Intelligence
Vertical integration into specialized component manufacturing anchors supply positions for custom units, directly influencing pricing power for bespoke solutions. This approach mitigates material cost volatility for key corrosion-resistant materials.
Pricing Analysis
Bundled aftermarket services and unbundled transactional unit sales define pricing in the offshore AHU market. Project-based pricing dominates custom-engineered solutions for Floating Production Systems, reflecting high customization levels and stringent certification requirements like ATEX and NORSOK. Price differentiation stems from specialized engineering, material grades such as 316L stainless steel, and integrated after-sales support. Cost compression affects standardized packaged units, driven by large manufacturers' scale. Production contractors for complex assets exhibit lower price sensitivity compared to offshore service operators procuring simpler systems.
Supply Chain Analysis
Direct sales channels and specialized engineering firms manage the supply of custom offshore AHUs, while global distribution networks serve standardized product lines. Supply concentration for critical components like 316L stainless steel and explosion-proof electricals centers in specialized European and Asian manufacturing hubs. The supply chain relies on a stable flow of low-GWP refrigerants and high-performance compressors. Commodity price volatility for corrosion-resistant materials represents a primary structural risk. Certification bottlenecks for specific regional standards also lengthen delivery timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Offshore Air Handling Units Market functions as a stable compounder, driven by continuous expansion in complex floating production systems. Regulatory mandates for environmental compliance and energy efficiency provide a consistent upgrade cycle.
For Market Incumbents: Anchor market share by deepening vertical integration into specialized component manufacturing, particularly for explosion-proof systems and low-GWP refrigerant compatibility. Invest in advanced certification processes for diverse regional standards like NORSOK and ATEX to counter regulatory fragmentation. Expanding predictive maintenance service offerings creates recurring revenue streams and strengthens client relationships, mitigating competitive pressure from new entrants. Focus R&D on modular designs for easier retrofitting on aging assets.
For New Entrants and Emerging Players: Digital engineering platforms offer a direct route to market by showcasing capabilities in modular system development and digital twin integration. Target aging oil and gas platforms requiring retrofits or remote monitoring stations with compact, energy-efficient AHUs. Focus on providing cost-effective, standardized solutions that meet core safety requirements without the full bespoke engineering overhead. Emphasize superior energy efficiency through demand-controlled ventilation technology.
For Investors and Strategic Acquirers: Roll-up economics work for specialized engineering firms because regulatory fragmentation and unique project specifications create high barriers to entry. The market offers long-term viability, underpinned by consistent deepwater development and regulatory-driven upgrade cycles. Target companies with strong intellectual property in explosion-proof designs or advanced energy recovery units. A key signal to watch is the accelerated integration of Industrial IoT sensors and remote monitoring capabilities in new AHU installations.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Low-GWP Refrigerant R&D | Drives compliance with EU F-Gas Regulation, creating new product opportunities for system specifiers. |
| Expand Predictive Maintenance Services | Generates recurring revenue streams and enhances operational efficiency for platform operators. |
| Develop Modular AHU Solutions | Facilitates rapid deployment and easier retrofitting on aging offshore assets, simplifying logistics. |
| Pursue ATEX and NORSOK Certification | Ensures market access and competitive advantage in established North Sea and European basins. |
| Integrate Digital Twin Technology | Optimizes design and enables remote troubleshooting for complex Floating Production Systems. |
Research Approach
Direct dialogue with production contractors, specialized HVAC engineers, maintenance providers, and regulatory compliance officers informed the qualitative grounding of this analysis. Secondary validation drew from ISO 15138 standards, NORSOK guidelines, EU F-Gas Regulation documents, and maritime safety reports. A robust bottom-up and top-down triangulation approach ensured comprehensive data synthesis. This combined method provides a granular view of market dynamics.
A bottom-up analytical lens, validated by top-down market sizing, guided the forecast across the analysis window. Segmentation dimensions modeled include product type, technology, application, end user, and regional regulatory cluster. Compound Annual Growth Rates were derived from historical trends and projected demand drivers. Key industry-specific inputs included the global offshore project pipeline and 316L stainless steel material cost trends.
Geopolitical instability, commodity price fluctuations, and new environmental regulations are the dominant revision risks for forecasts. These projections reflect a set of underlying assumptions about market conditions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
North America Evaporative Cooling Market
Cooling Systems
Seawater Cooling System Market
Cooling Systems
Cryogenic Systems Market
Cooling Systems
Middle East and Africa Cooling Systems Market
Cooling Systems
Radiant Cooling Systems Market
Cooling Systems
Cold Trap Market
Cooling Systems
Industrial Radiators Market
Cooling Systems
Cooling Tower Rental Market
Cooling Systems
Global Condensing Unit Market
Cooling Systems
Global Evaporative Cooler Market
Cooling Systems
Air to Air Heat Pumps Sales Market
Cooling Systems
Industrial Cooling System Market
Cooling Systems
Plate and Frame Heat Exchangers Market
Cooling Systems
Evaporative Condensing Unit Market
Cooling Systems
Seawater Condensers Market
Cooling Systems
Transformer Oil Coolers Market