
 Solar Cold Room Market | 2026-2036
Solar Cold Room Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Cold Room Market Insights
Lithium iron phosphate is decoupling solar cold room economics from lead-acid dependency, slashing battery replacement cycles and total ownership costs. Ecozen Solutions Private Limited leverages its Indian manufacturing base to anchor South Asian deployment of solar-powered cold chains for horticultural cooperatives. ColdHubs Limited dominates pay-as-you-store models across Nigerian agricultural clusters, sustaining operations through mobile-money integration. Promethean Power Systems specializes in thermal battery technology, differentiating its units from conventional compressor-driven alternatives in South Asian dairy corridors.
A solar cold room is a thermally insulated enclosure powered by photovoltaic arrays, typically maintaining temperatures between minus twenty degrees Celsius and fifteen degrees Celsius through vapor-compression or absorption refrigeration cycles, designed to preserve perishable commodities in off-grid or unreliable-grid environments. Walk-in refrigerators and freezer rooms constitute the core product volume, with freezer rooms commanding higher unit margins due to thicker insulation requirements and lower-temperature compressor specifications. Photovoltaic systems anchor technology deployment, though hybrid solutions integrating grid-tie capability represent the fastest-expanding segment as battery costs decline and rural electrification progresses unevenly.
India's Ministry of New and Renewable Energy and the Bureau of Indian Standards shape product compliance through solar panel certification mandates and cold storage energy-efficiency benchmarks, while Nigeria's Rural Electrification Agency directs subsidy flows toward off-grid agricultural refrigeration. The EU Green Deal's cold chain decarbonization targets and REACH chemical restrictions on refrigerants are forcing refrigerant transitions across export-oriented installations. Stakeholders must track how evolving battery chemistry standards and national solar import tariffs reshape component sourcing strategies before committing to regional manufacturing footprints.
Market Dynamics
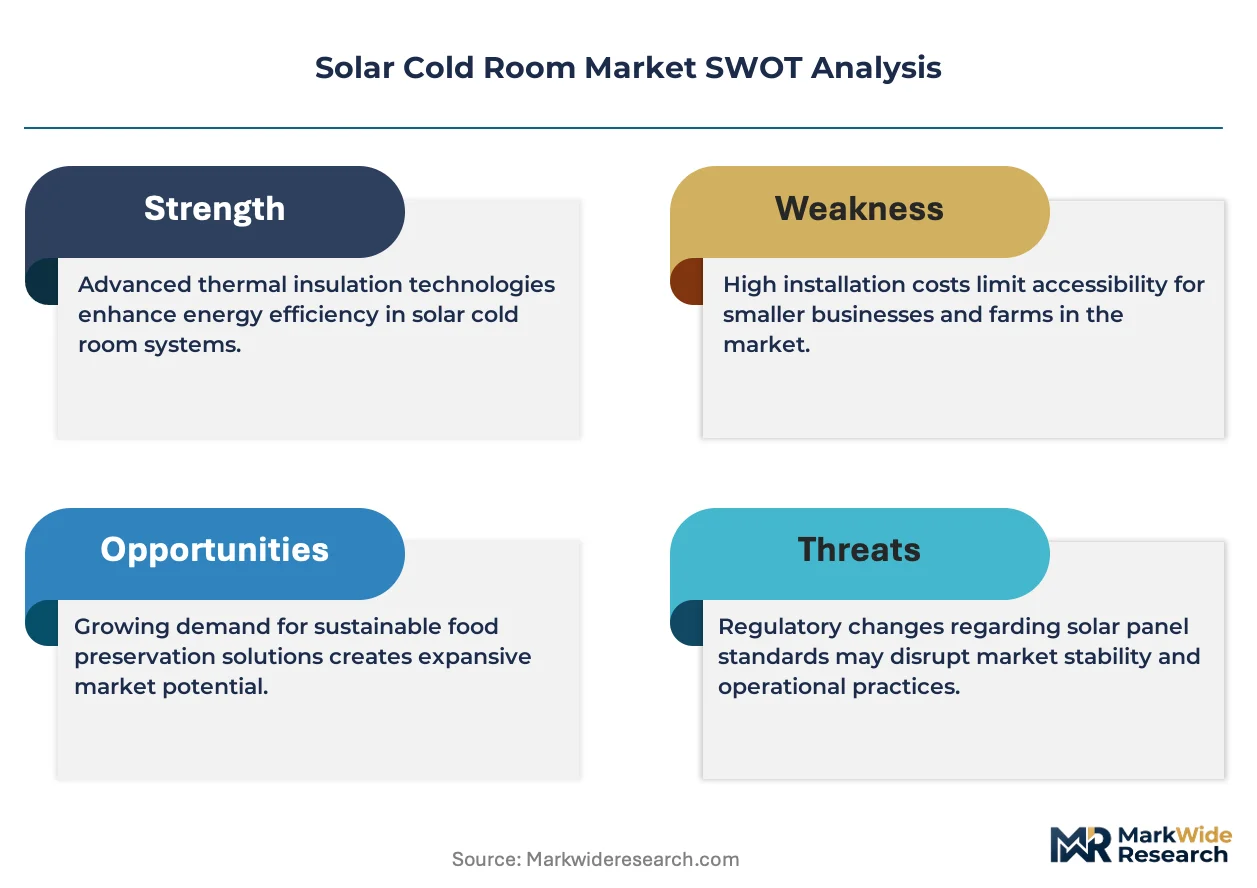
Lithium iron phosphate battery chemistry is decoupling solar cold room economics from lead-acid dependency, slashing replacement cycles and compressing total ownership costs for agricultural cooperatives across sub-Saharan Africa and South Asia.
Growth Catalysts
- India's PLI scheme for solar module manufacturing:Domestic panel supply chains accelerate cold chain infrastructure deployment by reducing import dependency and component lead times for horticultural storage installations.
- Agricultural cooperatives:Smallholder farmer groups across sub-Saharan Africa drive adoption as solar-powered cold storage cuts post-harvest losses for tomato, pepper, and dairy value chains.
- Off-grid refrigeration demand:Grid instability in Nigeria's Kaduna vegetable corridor makes solar cold rooms essential infrastructure for perishable commodity traders operating beyond reliable electrification.
Market Restraints
- Photovoltaic component cost volatility:Polysilicon price swings and solar wafer supply concentration in China create input cost unpredictability for system integrators.
- Refrigerant regulatory friction:The EU Green Deal's cold chain decarbonization targets and REACH chemical restrictions force refrigerant transitions that complicate export-oriented installation compliance.
- Technical limitation of absorption cycles:Vapor-compression systems dominate deployment because absorption refrigeration delivers lower coefficient of performance in humid tropical climates.
Strategic Opportunities
- Pay-as-you-store models:Mobile-money integrated subscription services unlock smallholder farmer segments previously excluded by upfront capital barriers in West African agricultural clusters.
- Hybrid grid-tie capability:Battery cost declines and uneven rural electrification progress position dual-power systems as the fastest-expanding technology segment.
- Thermal battery convergence:Solid-state thermal storage paired with photovoltaic generation enables compressor-free cold rooms for dairy corridors in South Asia.
Industry Challenges
- Certification timeline complexity:India's Bureau of Indian Standards solar panel certification mandates and cold storage energy-efficiency benchmarks create multi-month product approval delays.
- Refrigeration technician scarcity:Vapor-compression and absorption system maintenance requires specialized skills that remain concentrated in urban centers far from rural deployment sites.
- Supply chain reconfiguration friction:Evolving battery chemistry standards and national solar import tariffs force component sourcing strategy pivots mid-contract.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Cold Room Market |
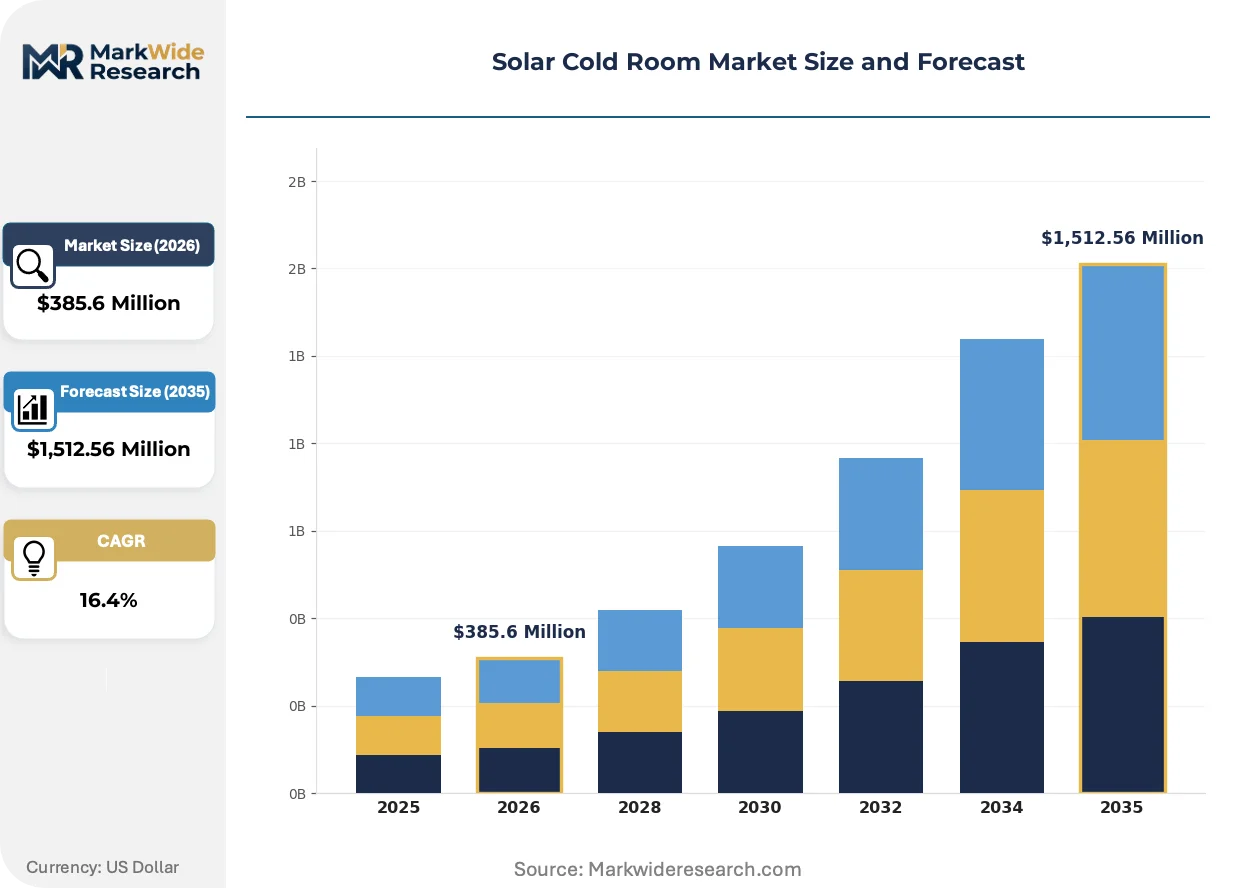
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,512.56 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walk-in Refrigerators, Ice Makers, Refrigerated Containers, Freezer Rooms End User: Agriculture, Food Processing, Retail, Pharmaceutical Installation: New Construction, Retrofit, Prefabricated, Modular Technology: Photovoltaic Systems, Thermoelectric Systems, Hybrid Solutions, Insulated Panels |
| Companies Covered | Ecozen Solutions Private Limited, ColdHubs Limited, SolarChill Systems Inc., Sure Chill Technology, Promethean Power Systems, Solar Freeze Systems, SunDanzer, Dulas Limited, Aldelano Solar Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Cold Room Market Trends and Innovations
Active reshaping of the solar cold room market centers on battery chemistry transitions, regulatory pressure on refrigerants, and the unbundling of traditional ownership models into service-based access.
Thermal battery technology is absorbing capital and engineering attention from conventional compressor-driven alternatives. Dairy cooperatives in South Asian corridors are piloting solid-state thermal storage systems that freeze phase-change materials during daylight hours. This approach is absorbing market share from lithium-ion dependent units by eliminating compressor maintenance and extending system lifespan beyond fifteen years.
The EU F-Gas Regulation and REACH chemical restrictions are forcing refrigerant transitions across export-oriented installations. Hydrofluorocarbon phase-down schedules compel manufacturers to qualify propane and ammonia-based alternatives. Cold room operators serving European-bound horticultural supply chains are retooling specifications to maintain market access compliance.
Smallholder farmers are migrating from capital purchase toward subscription-based cold storage access. Pay-per-use models displace equipment ownership in Nigerian agricultural clusters where mobile-money penetration enables automated billing. This behavioral pivot concentrates demand around service providers with working capital depth rather than hardware manufacturers alone.
Solar Cold Room Market Segmentation
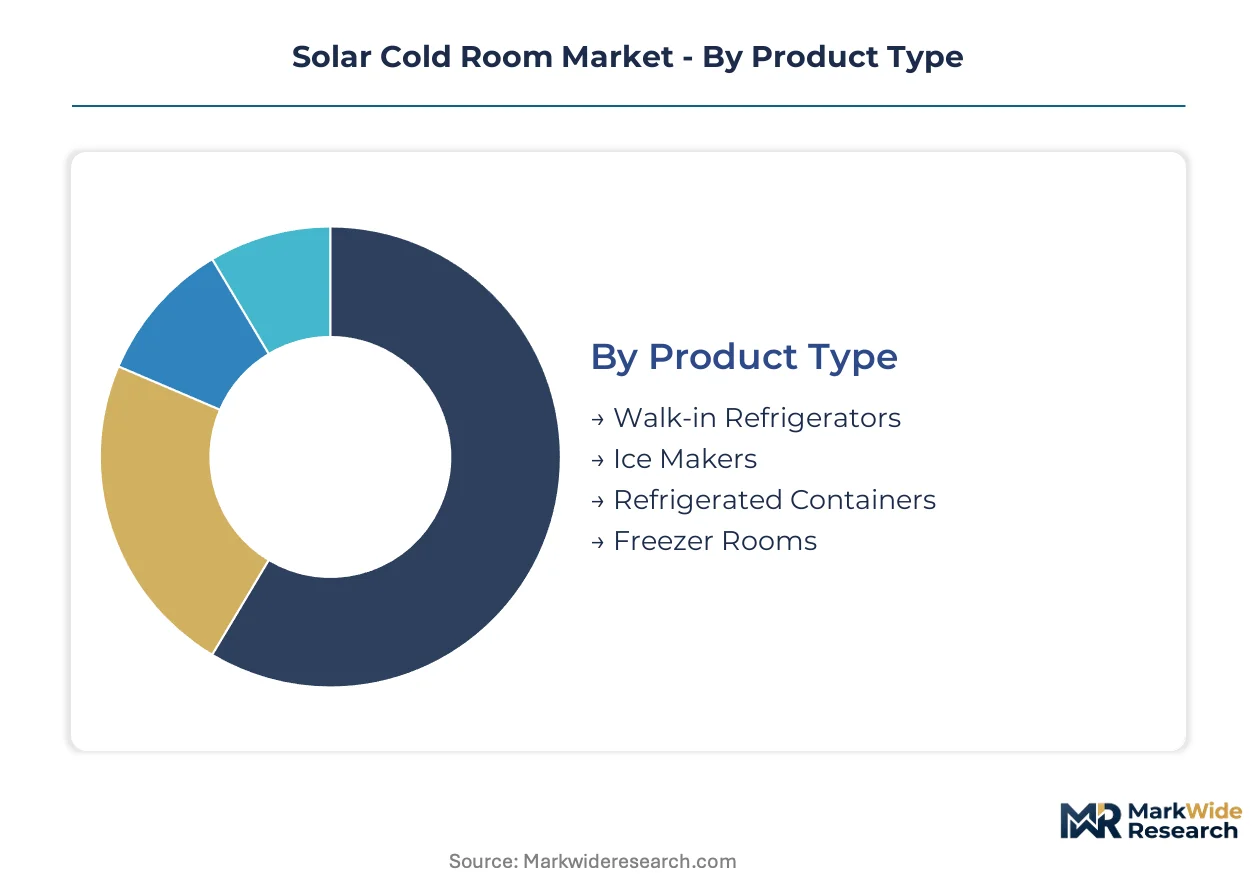
Solar cold room purchasing decisions pivot on thermal performance specifications, power system architecture, and deployment flexibility requirements. Buyers weigh upfront capital against operational autonomy, particularly in off-grid agricultural corridors where grid reliability determines technology selection.
Product Type:
Buyers prioritize thermal envelope performance and compressor duty cycles when selecting enclosure formats.
- Walk-in Refrigerators:These units maintain positive temperatures between two and fifteen degrees Celsius through vapor-compression cycles, with insulated panels typically seventy-five to one hundred millimeters thick. Demand concentrates in Indian horticultural cooperatives where tomato and grape traders require short-term holding capacity before auction dispatch.
- Freezer Rooms:Sub-zero enclosures demand thicker insulation—one hundred twenty to one hundred fifty millimeters—and low-temperature compressors capable of sustaining minus twenty degrees Celsius. Nigerian dairy clusters in Kaduna and Plateau states drive adoption as milk collection centers require frozen storage for butter and ice cream production.
- Ice Makers:Dedicated ice production units serve fish landing sites and mobile vendor networks across West African coastal communities.
- Refrigerated Containers:Standardized twenty-foot and forty-foot formats enable intermodal logistics for export-oriented horticultural operations.
Walk-in refrigerators lead on scale; freezer rooms lead on momentum.
End User:
Application-specific temperature tolerances and throughput volumes shape procurement specifications across verticals.
- Agriculture:Smallholder cooperatives deploy solar cold rooms to arrest post-harvest degradation of perishables between farmgate and market. Nigeria's Rural Electrification Agency channels subsidy flows toward off-grid agricultural refrigeration, accelerating uptake in vegetable corridors.
- Food Processing:Mid-scale processors require HACCP-compliant cold chains for dairy, meat, and ready-to-eat product lines. Cold room specifications here emphasize temperature logging and alarm systems to satisfy FSSAI traceability mandates in India.
- Retail:Independent grocers and wet market vendors adopt compact solar units where grid power is intermittent or prohibitively expensive.
- Pharmaceutical:Vaccine cold chains demand precise temperature control with backup power assurance, though solar penetration remains limited by stringent CDSCO and WHO PQS certification requirements.
Agriculture dominates installation volume; food processing climbs fastest on compliance-driven replacement cycles.
Installation:
Site constraints and capital availability determine whether buyers favor permanent construction or deployable formats.
- New Construction:Ground-up builds allow integrated photovoltaic array sizing and optimal thermal envelope engineering. Indian horticultural infrastructure schemes under the Ministry of Agriculture favor this approach for permanent collection centers.
- Retrofit:Existing cold storage facilities add solar generation and battery banks to reduce diesel generator dependence. Nigerian trading associations retrofit grid-connected rooms with hybrid capability following tariff volatility.
- Prefabricated:Factory-assembled panels reduce on-site labor requirements and accelerate commissioning timelines for remote deployments.
- Modular:Scalable unit formats enable capacity expansion alongside cooperative membership growth, particularly in sub-Saharan farmer groups with variable harvest volumes.
New construction anchors capital deployment; modular formats gain share on flexibility premiums.
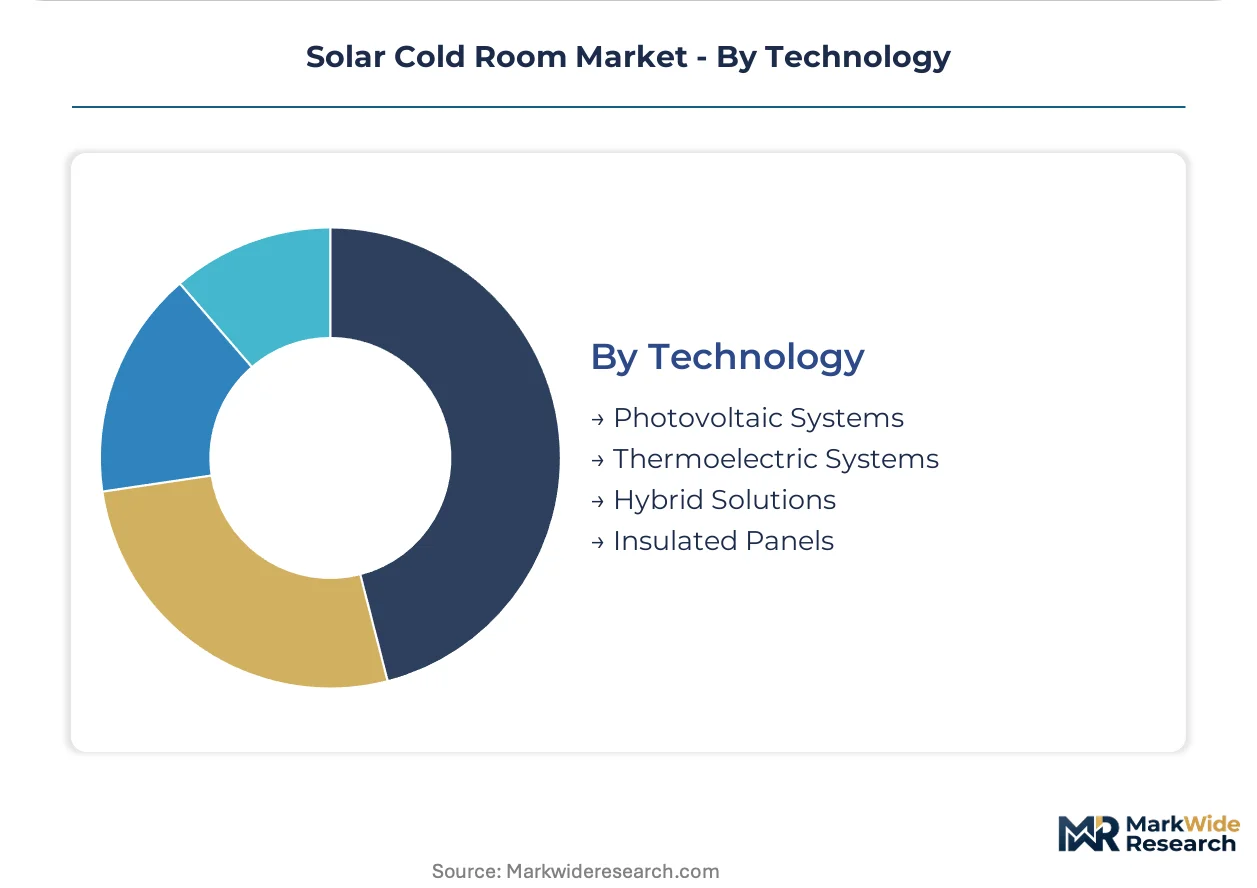
Technology:
Power system architecture determines operational autonomy, maintenance burden, and lifecycle cost profiles.
- Photovoltaic Systems:Dedicated solar arrays with lithium iron phosphate battery banks deliver complete grid independence. These configurations dominate Nigerian agricultural clusters where grid instability makes off-grid refrigeration essential for tomato and pepper traders.
- Hybrid Solutions:Dual-power systems integrate grid-tie capability with solar-battery backup, expanding fastest as battery costs decline and rural electrification progresses unevenly. Indian cold chain operators favor this architecture to hedge against distribution network fluctuations.
- Thermoelectric Systems:Solid-state cooling via Peltier modules serves niche applications with modest thermal loads and extreme maintenance access constraints.
- Insulated Panels:Advanced polyurethane or vacuum-insulated panel systems reduce thermal leakage and compressor duty cycles, improving overall system efficiency.
Photovoltaic systems hold installed base dominance; hybrid solutions expand most quickly on risk-mitigation logic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nigeria's Kaduna vegetable corridor anchors solar cold room deployment as grid instability forces tomato and pepper traders toward off-grid refrigeration infrastructure.
Nigeria
Smallholder cooperatives in Kaduna and Plateau states deploy solar cold storage to arrest post-harvest losses for dairy and vegetable value chains. The Rural Electrification Agency channels subsidy flows toward off-grid agricultural refrigeration, accelerating uptake. ColdHubs Limited operates pay-as-you-store facilities across Lagos and Kano agricultural clusters through mobile-money billing integration.
India
Horticultural cooperatives in Maharashtra and Karnataka require short-term holding capacity for tomato and grape dispatch to auction markets. The PLI scheme for solar module manufacturing accelerates domestic panel supply chains serving cold chain infrastructure. Ecozen Solutions Private Limited anchors South Asian deployment from its manufacturing base in Pune.
Kenya
Dairy cooperatives in the Rift Valley pilot solid-state thermal storage to eliminate compressor maintenance burdens. The national agricultural regulator enforces cold chain traceability standards for export-oriented horticultural operations. Solar Freeze Systems concentrates deployment around Nairobi's peripheral vegetable collection centers.
Bangladesh
Fish landing sites across Chittagong and Khulna divisions adopt dedicated ice production units for mobile vendor networks. The national standards body mandates solar panel certification for off-grid refrigeration installations. Promethean Power Systems positions thermal battery units in Rajshahi dairy corridors as compressor-free alternatives.
South Africa
Independent grocers in Eastern Cape and Limpopo provinces adopt compact solar units where grid power proves intermittent. The national energy regulator integrates off-grid refrigeration into rural electrification planning frameworks. Dulas Limited supplies prefabricated formats to remote deployment sites in Northern Cape mining communities.
Solar Cold Room Market Competitive Landscape
Strategic partnerships dominate the current landscape as technology providers align with mobile-money platforms and agricultural cooperatives to unlock smallholder segments. The vendor base clusters around three archetypes: integrated system manufacturers controlling photovoltaic-to-refrigeration design, pay-as-you-store service operators monetizing access rather than hardware, and thermal storage specialists eliminating compressor dependencies. Geographic expansion and technology licensing represent the principal competitive vectors as battery chemistry standardization accelerates cross-border deployment.
Within the integrated manufacturing tier, Ecozen Solutions Private Limited and Promethean Power Systems exemplify contrasting technology bets—vapor-compression versus thermal battery architectures. ColdHubs Limited occupies the service-operator position, demonstrating how mobile-money integration transforms capital barriers into recurring revenue streams. These three entities collectively map the strategic terrain: hardware ownership, infrastructure-as-service, and solid-state thermal innovation.
| Leading Market Players |
|---|
| Ecozen Solutions Private Limited |
| ColdHubs Limited |
| SolarChill Systems Inc. |
| Sure Chill Technology |
| Promethean Power Systems |
| Solar Freeze Systems |
| SunDanzer |
| Dulas Limited |
| Aldelano Solar Solutions |
| Others |
Pricing and Supply Chain Analysis
Performance-tier bifurcation between lithium iron phosphate battery systems and legacy lead-acid configurations manifests in both upfront capital requirements and component sourcing footprints across Nigerian and Indian deployment corridors. This divergence concentrates procurement power among integrated manufacturers while fragmenting aftermarket service networks around battery replacement cycles.
Pricing Analysis
Input-cost pass-through from polysilicon wafer volatility and lithium carbonate pricing feeds directly into system integrator quotations across sub-Saharan African markets. Three-tier pricing structure across premium, standard, and economy levels separates turnkey installations with thermal battery technology from compressor-driven units with basic photovoltaic arrays. Cost compression in the economy tier is intensifying because Indian PLI scheme subsidies are compressing domestic panel margins. Smallholder cooperatives in Nigeria's Kaduna corridor exhibit highest price sensitivity; export-oriented horticultural processors in Maharashtra demonstrate lowest sensitivity due to compliance-driven replacement cycles.
Supply Chain Analysis
India's domestic-content mandates under the PLI scheme and Nigeria's local assembly requirements for Rural Electrification Agency subsidies are reshaping sourcing patterns for photovoltaic modules and battery enclosures. Manufacturing concentrates in China for polysilicon wafers and lithium cells, India for module assembly and cold room fabrication, and Germany for compressor and control systems. Raw material dependencies center on lithium carbonate, high-purity aluminum for frames, and polyurethane foam for insulation panels. Single-source vulnerability runs through Chinese polysilicon purification capacity. Distribution runs through agricultural cooperative networks and mobile-money-integrated service operators rather than traditional equipment dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's subsidized module manufacturing base undercuts Chinese import costs for Nigerian and Bangladeshi deployment, while EU F-Gas regulatory stringency creates premium export pricing for compliant thermal storage systems.
For Market Incumbents: Anticipate compressor-free thermal battery architectures displacing conventional vapor-compression units in South Asian dairy corridors by investing in solid-state phase-change material R&D and securing BIS certification ahead of efficiency mandate tightening. Capacity addition in Pune and Lagos manufacturing clusters anchors regional service response times against emerging local assemblers. For New Entrants and Emerging Players: Launch via pay-as-you-store subscription models integrated with M-Pesa or similar mobile-money platforms to bypass capital barriers among Nigerian vegetable trader associations. The most penetrable white-space sits in retrofit hybrid installations for existing grid-connected cold storage in Indian food processing clusters where tariff volatility drives backup power demand. For Investors and Strategic Acquirers: Consolidation pressure builds where working capital depth determines service-operator survival in mobile-money-billing models across West African agricultural clusters. Long-term viability hinges on technology licensing revenue from thermal battery patents rather than hardware shipment volume. Acquisition target archetype: regional service operators with established cooperative relationships and mobile-money integration infrastructure. The signal to watch is BIS battery chemistry standardization timelines that could obsolete non-compliant inventory holdings.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Iron Phosphate Cell Production | Captive battery supply secures margin control against raw material volatility for Indian manufacturers. |
| Mobile-Money Platform Partnership | Automated billing integration unlocks smallholder farmer segments previously excluded by upfront capital requirements. |
| Thermal Battery Technology Licensing | Patent revenue streams diversify beyond hardware margins for compressor-free system innovators. |
| Hybrid Grid-Tie Capability Rollout | Dual-power architecture hedges against uneven rural electrification progress across Nigerian agricultural corridors. |
| EU F-Gas Compliance Certification | Refrigerant transition qualification maintains market access for export-oriented horticultural supply chains. |
Research Methodology
Coverage spans South Asia, sub-Saharan Africa, and select European export corridors, with primary inputs from each region combining interviews with cold chain equipment procurement managers at agricultural cooperatives, maintenance technicians at remote deployment sites, and regulatory affairs leads at solar module manufacturers. Secondary validation draws from MNRE subsidy disbursement records, REA project approval databases, BIS certification registries, and EU F-Gas phase-down monitoring reports. Bottom-up installation counts triangulate against top-down addressable market sizing across the analysis window.
Rate-of-change decomposition separates volume growth from value-per-unit shifts across enclosure format, power system architecture, and installation type dimensions. Modeled segmentation captures walk-in refrigerator versus freezer room product splits, photovoltaic versus hybrid versus thermal battery technology tiers, and new construction versus retrofit versus modular deployment formats. CAGRs derive from fitted adoption curves calibrated to subsidy program trajectories and battery cost decline slopes. Industry-specific forecast inputs include MNRE PLI scheme disbursement schedules and Nigerian REA off-grid refrigeration tender pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt lithium carbonate supply disruptions or accelerated EU refrigerant phase-down schedules. Forecasts reflect documented assumptions regarding subsidy continuity, mobile-money penetration trajectories, and compressor technology lifespan benchmarks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Chilled Water System Market
Cooling Systems
Low Temperature Radiators Market
Cooling Systems
Water Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Heat Pump Dryer Market
Cooling Systems
Process Chillers Market
Cooling Systems
Transformer Oil Coolers Market
Cooling Systems
Saudi Arabia Desert Air Coolers Market
Cooling Systems
Global Evaporative Cooler Market
Cooling Systems
Horizontal Air Flow Condensers Market
Cooling Systems
Thermosiphon Cooling System Market
Cooling Systems
Solar-Assisted Heat Pump Market
Cooling Systems
Cold Trap Market
Cooling Systems
District Heating and Cooling Market
Cooling Systems
Global Transcritical Co2 Systems Market
Cooling Systems
North America Evaporative Cooling Market
Cooling Systems
Global Scroll and Absorption Chillers Market