
 France Solar Energy Market | 2026-2036
France Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
France Solar Energy Market Foresight
Software-defined energy management is broadening what French solar developers sell beyond hardware. Engie SA leverages its digital platform to bundle predictive maintenance with long-term power purchase agreements. TotalEnergies SE anchors its strategy through integrated battery-solar offerings for C&I clients. Neoen specializes in agrivoltaic configurations that sustain dual land use across southwestern France.
France solar energy encompasses photovoltaic and concentrated solar power systems converting electromagnetic radiation into electricity through semiconductor junctions or thermal cycles, primarily serving grid decarbonization and distributed generation objectives. Crystalline silicon modules dominate installed capacity, while thin-film cadmium-telluride gains traction in building-integrated applications where weight constraints apply. Utility-scale photovoltaic leads value creation due to streamlined permitting under France's accelerated renewable zones, yet residential rooftop segments exhibit faster deployment velocity as net metering reforms take hold. Floating solar installations occupy nascent but structurally significant positions where land scarcity around hydroelectric reservoirs creates captive demand.
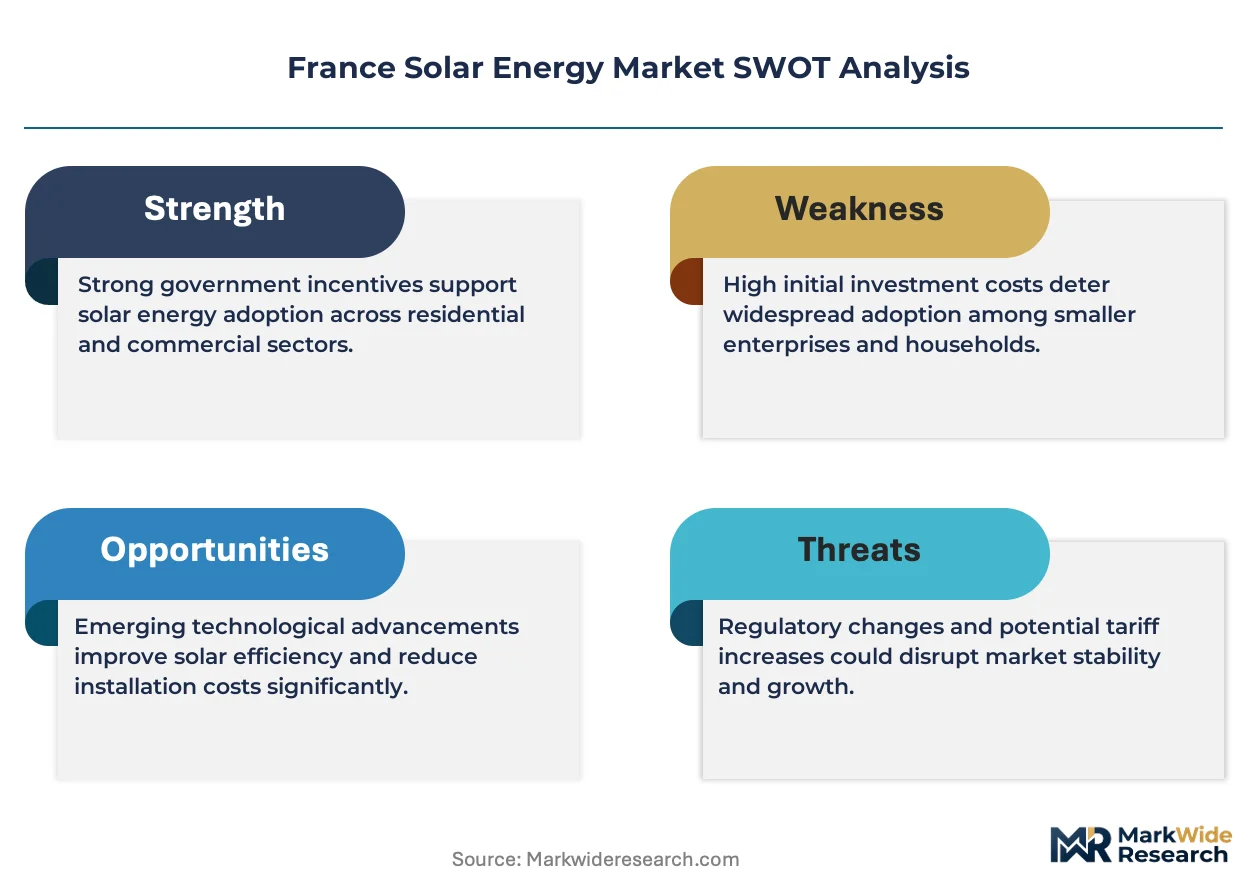
France's national energy regulator CRE sets feed-in tariff frameworks that shape project finance structures, while EU Green Deal taxonomy rules constrain eligible technology configurations. ANSM and CNIL oversight extends to cybersecurity standards for smart inverter data flows, tightening market access for non-compliant hardware vendors. EDF Renewables and Voltalia SA navigate these layered requirements through dedicated regulatory affairs functions. Stakeholders must monitor CRE's upcoming capacity auction designs and their implications for merchant price exposure.
Market Dynamics
France's solar sector is compressing around hybrid project configurations that pair photovoltaic arrays with battery storage and existing nuclear baseload, forcing developers to restructure their revenue models around capacity payments rather than pure energy sales.
Growth Catalysts
- EU Green Deal taxonomy alignment:The EU Green Deal's REPowerEU targets mandate accelerated renewable deployment across industrial manufacturing facilities, creating captive demand for on-site solar generation.
- Occitanie cluster density:Concentrated photovoltaic manufacturing and engineering expertise near Montpellier reduces balance-of-system costs through localized supply chains and specialized labor pools.
- CRE accelerated permitting zones:France's national energy regulator has streamlined authorization timelines for designated renewable development areas, compressing project development cycles.
Market Restraints
- Polysilicon supply concentration:Raw material sourcing remains concentrated among a limited set of Asian suppliers, exposing French developers to input cost volatility and geopolitical supply disruptions.
- Grid interconnection queues:Technical capacity limitations at transmission nodes in southwestern France create structural bottlenecks for utility-scale project commissioning.
- Land-use competition:Agricultural zoning restrictions under France's territorial planning frameworks limit available surface area for ground-mounted installations in prime solar irradiance regions.
Strategic Opportunities
- Floating solar on hydro reservoirs:Land-scarce regions around existing EDF hydroelectric infrastructure present untapped deployment potential for aquatic photovoltaic systems without land-use conflicts.
- Agrivoltaic dual-use configurations:Elevated panel structures enabling simultaneous crop cultivation and energy generation are gaining regulatory support under France's rural development programs.
- Building-integrated photovoltaics:Thin-film cadmium-telluride applications in commercial construction are penetrating weight-constrained retrofit markets where conventional modules face structural limitations.
Industry Challenges
- Smart inverter cybersecurity certification:ANSM and CNIL data protection mandates require specialized compliance protocols that extend hardware vendor qualification timelines and increase development overhead.
- Merchant price exposure management:Developers must build financial hedging capabilities as CRE capacity auctions introduce greater wholesale market price volatility into long-term project economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Solar Energy Market |
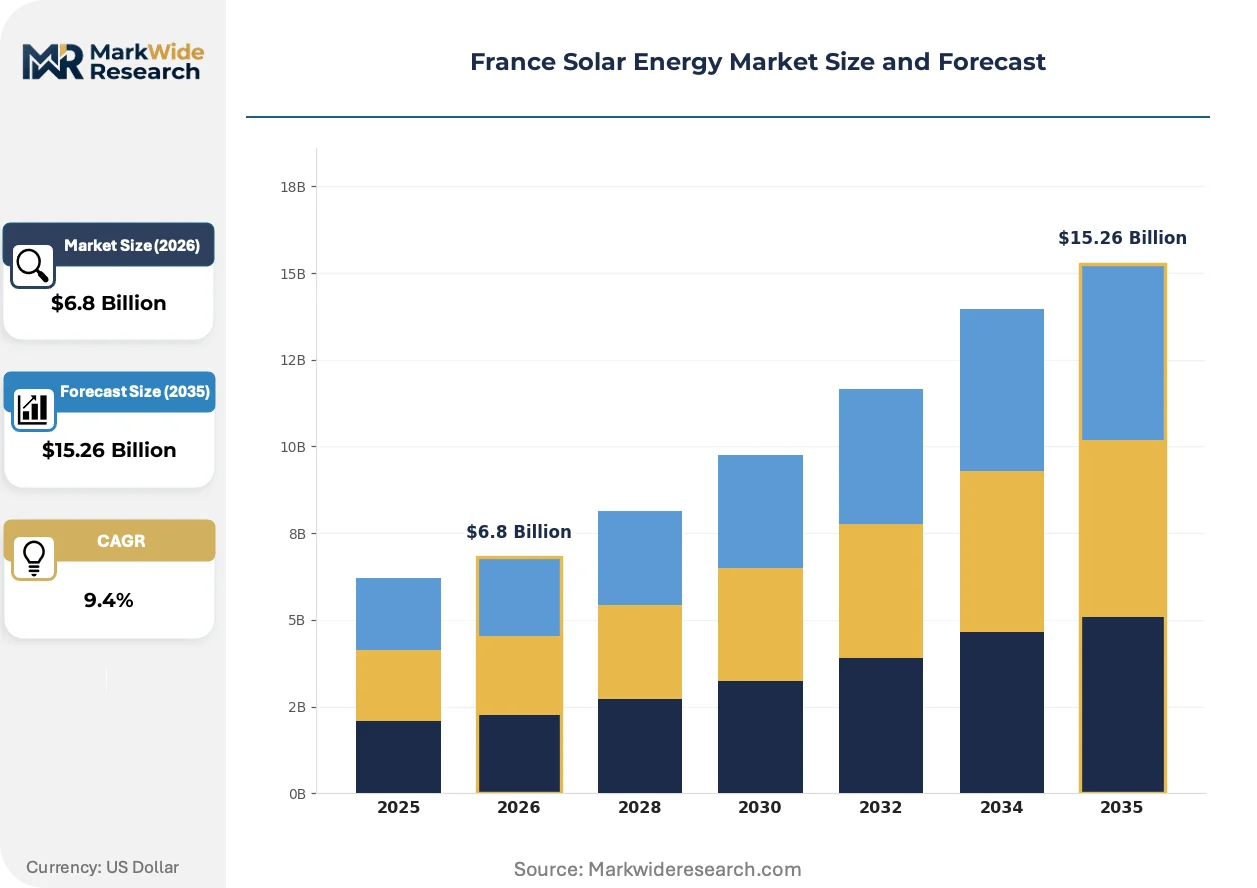
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photovoltaic, Concentrated Solar Power, Thin-Film, Monocrystalline, Polycrystalline Application: Residential, Commercial, Agricultural, Utility-Scale, Governmental Installation Type: Ground-Mounted, Rooftop, Floating, Building-Integrated, Carport End User: Energy Providers, Manufacturing Plants, Real Estate Developers, Educational Institutions, Public Facilities |
| Companies Covered | Engie SA, EDF Renewables, TotalEnergies SE, Neoen, Voltalia SA, Albioma SA, meeco AG, Solairedirect, Arkolia Energies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Solar Energy Market Shifts & Advancements
Digitalization is restructuring how French solar assets are operated and monetized, with software platforms displacing traditional hardware-centric business models and enabling new service revenue streams.
Bifacial photovoltaic module technology is modularizing project design flexibility across France's utility-scale segment. EDF Renewables and independent power producers are adopting double-sided capture configurations in ground-mounted installations to boost energy yield density. This technology is modularizing balance-of-system optimization as developers reduce land footprints per megawatt installed.
France's CRE is revising feed-in tariff frameworks to incorporate grid flexibility requirements into auction scoring criteria. The industrial consequence is a mandatory technology shift toward hybrid solar-plus-storage configurations for new capacity allocations. Utility-scale developers are responding by restructuring project finance around merchant storage revenue stacks rather than pure solar energy sales.
Corporate power purchase agreement structures are displacing traditional utility offtake as the dominant procurement channel for French commercial and industrial solar deployment. Large manufacturing facilities in the Occitanie and Provence-Alpes-Côte d'Azur regions are contracting directly with developers for behind-the-meter installations. This behavioral shift is most visible among automotive and aerospace suppliers seeking to meet Scope 2 emissions reduction commitments under EU Green Deal reporting requirements.
France Solar Energy Market Segmentation
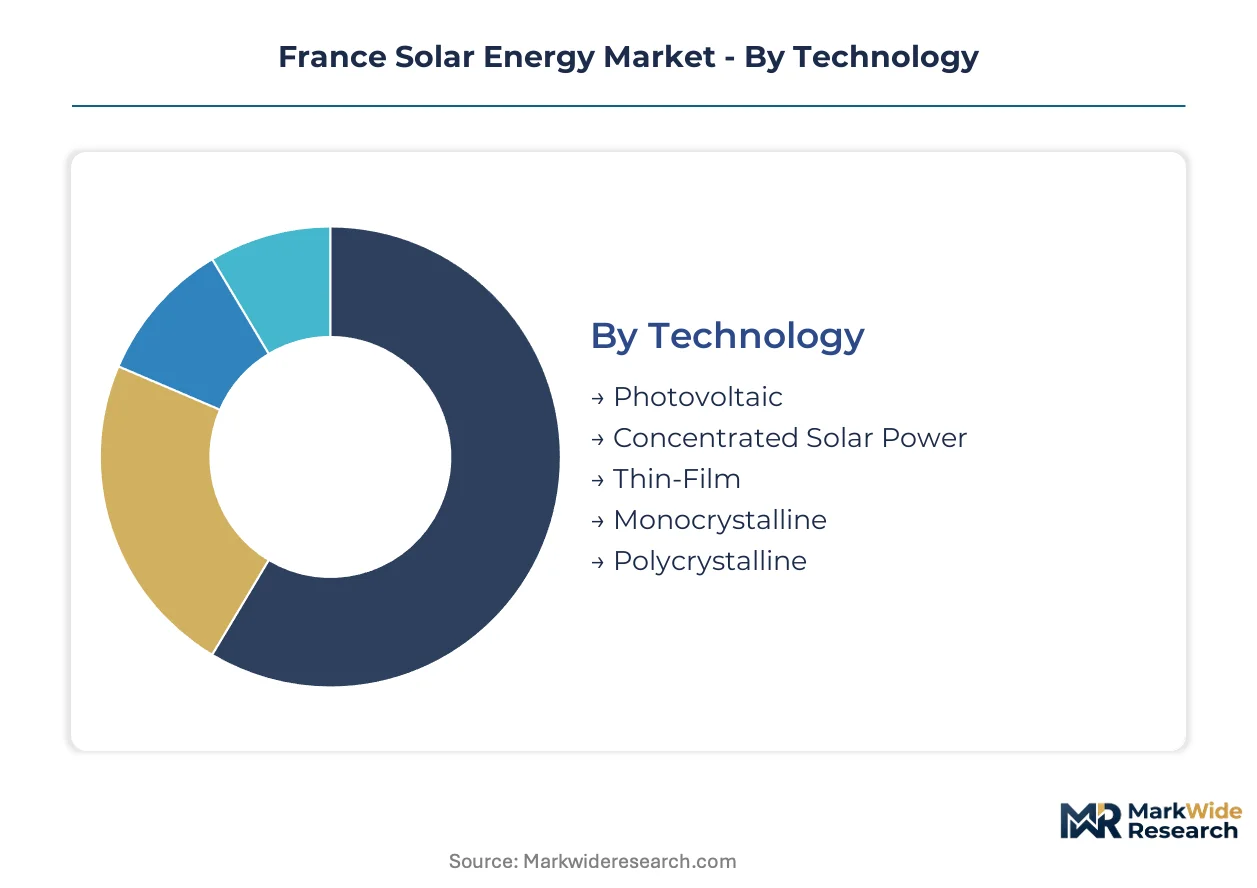
Technology and installation configurations in France's solar sector determine project economics, regulatory eligibility, and grid integration requirements. Segment boundaries are shifting as hybrid systems and agrivoltaic designs blur traditional categories. Understanding these divisions reveals where capital is concentrating and which configurations face structural constraints under French permitting frameworks.
Technology:
Module technology concentration in France tilts toward crystalline silicon suppliers with established distribution networks, while thin-film vendors compete on weight-constrained retrofit applications.
- Photovoltaic:Crystalline silicon junctions dominate installed capacity across French utility-scale and distributed generation projects. Demand concentrates in Occitanie's manufacturing cluster near Montpellier, where localized engineering expertise reduces balance-of-system costs and accelerates project development timelines.
- Concentrated Solar Power:Thermal cycle systems using parabolic troughs or solar towers convert electromagnetic radiation through heat transfer fluids. Deployment remains limited to southern France's highest direct normal irradiance zones, constrained by water access requirements for cooling and higher capital intensity versus photovoltaic alternatives.
- Thin-Film:Cadmium-telluride and CIGS configurations penetrate building-integrated markets where structural load limits exclude conventional modules.
- Monocrystalline:Single-crystal silicon wafers deliver highest conversion efficiencies for space-constrained rooftop installations.
- Polycrystalline:Multi-crystal silicon offers cost advantages in ground-mounted utility applications where land availability reduces efficiency premium requirements.
Today's leader: Photovoltaic. Tomorrow's challenger: Thin-Film.
Application:
End-use demand in France fragments across customer types with divergent procurement timelines, offtake structures, and regulatory exposure.
- Residential:Behind-the-meter rooftop systems serve single-family and multi-unit dwellings under France's net metering reforms. Deployment velocity is climbing fastest in Provence-Alpes-Côte d'Azur as electricity rate visibility improves homeowner payback calculations.
- Commercial:On-site generation for retail, office, and logistics facilities leverages corporate power purchase agreement structures. Manufacturing plants in Occitanie are contracting directly with developers to meet Scope 2 emissions commitments under EU Green Deal reporting requirements.
- Agricultural:Elevated panel configurations enable dual land use for crop cultivation and energy generation across southwestern France's rural development zones.
- Utility-Scale:Grid-connected arrays exceeding several megawatts capacity compete in CRE capacity auctions with merchant price exposure.
- Governmental:Public sector procurement supports military installations, municipal buildings, and state-owned infrastructure under centralized energy efficiency mandates.
Commercial applications are expanding most quickly; utility-scale retains revenue concentration.
Installation Type:
Physical mounting configurations determine land-use permitting pathways, structural engineering requirements, and captive demand sources across French territories.
- Ground-Mounted:Fixed-tilt and tracking arrays on open land dominate utility-scale capacity additions. Agricultural zoning restrictions under France's territorial planning frameworks limit available surface area in prime solar irradiance regions, compressing development toward marginal lands.
- Rooftop:Building-attached systems exploit existing structural footprints without land-use conflicts. Real estate developers in Greater Paris are integrating rooftop photovoltaic into new construction specifications to meet CRE's accelerated renewable zone requirements.
- Floating:Aquatic photovoltaic systems deploy on hydroelectric reservoirs and quarries where land scarcity creates captive demand. EDF's existing hydro infrastructure presents untapped deployment potential without agricultural land-use conflicts.
- Building-Integrated:Photovoltaic materials replace conventional building envelope components in facade and skylight applications.
- Carport:Elevated canopy structures combine parking coverage with electricity generation for commercial and public facilities.
Ground-mounted commands current capacity; floating solar shows steepest expansion trajectory.
End User:
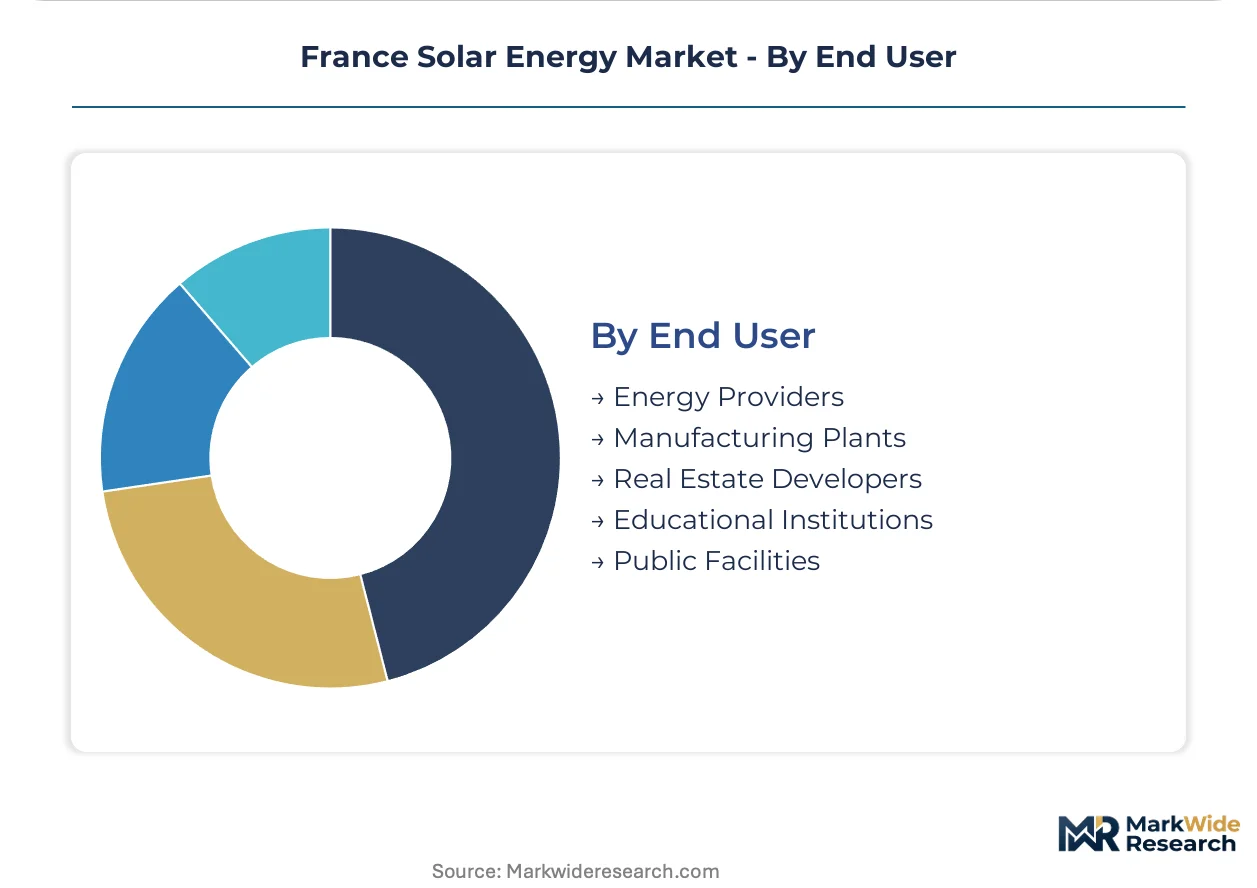
Customer concentration in France's solar market reflects divergent procurement sophistication, balance sheet capacity, and regulatory compliance obligations.
- Energy Providers:EDF Renewables and independent power producers develop grid-scale assets under CRE auction frameworks. These entities navigate layered regulatory requirements through dedicated regulatory affairs functions monitoring capacity auction designs.
- Manufacturing Plants:Industrial facilities deploy on-site generation to reduce Scope 2 emissions and hedge electricity price volatility. Automotive and aerospace suppliers in Occitanie are contracting directly with developers for behind-the-meter installations.
- Real Estate Developers:Construction firms integrate solar into building specifications to meet energy performance certification requirements.
- Educational Institutions:Universities and research facilities deploy rooftop systems for operational cost reduction and curriculum integration.
- Public Facilities:Hospitals, administrative buildings, and transportation infrastructure pursue centralized procurement frameworks.
Energy providers anchor installed base; manufacturing plants are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's solar deployment velocity outpaces France in absolute gigawatts added, yet France's nuclear-solar hybrid model offers distinct grid stability advantages that attract differentiated capital flows.
Germany
Industrial electricity demand from chemical and automotive plants in North Rhine-Westphalia and Bavaria accelerates photovoltaic deployment. The country's national energy regulator, Bundesnetzagentur, administers competitive auction frameworks that compress developer margins. Manufacturing clusters around Leipzig and Dresden concentrate heterojunction module production capacity serving Central European markets.
Spain
Utility-scale solar parks in Extremadura and Andalusia exploit superior direct normal irradiance levels unmatched in Northern Europe. The country's renewable energy auction mechanism, managed by the Ministry for Ecological Transition, prioritizes hybrid storage configurations. Engineering firms in Seville and Málaga specialize in parabolic trough concentrated solar power installations for industrial heat applications.
Italy
Agricultural land availability in Puglia and Sicily enables extensive agrivoltaic deployment without food production conflicts. Gestore dei Servizi Energetici oversees feed-in tariff allocations that favor distributed generation over centralized arrays. Lombardy's manufacturing base around Milan supplies mounting systems and inverters to Mediterranean solar markets.
Netherlands
Floating solar installations on inland waterways and sand extraction lakes address acute land scarcity constraints in the Randstad conurbation. The country's national climate agreement mandates accelerated renewable deployment across greenhouse horticulture operations. Eindhoven's technical universities anchor research partnerships concentrating bifacial module optimization.
Poland
Coal-dependent industrial regions in Silesia pivot toward solar-plus-storage hybrids as EU Just Transition Fund disbursements materialize. The country's energy regulatory office structures capacity market mechanisms that remunerate grid flexibility services. Warsaw-based project developers concentrate distributed generation expertise serving commercial and industrial offtakers.
France Solar Energy Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated energy majors commanding utility-scale tenders while independent developers carve niches in agrivoltaic and floating configurations. Market structure tilts toward consolidation around entities with balance sheet capacity to absorb merchant price exposure under evolving auction designs. Three archetypes dominate: state-affiliated utilities leveraging nuclear baseload synergies, pure-play renewable developers optimizing distributed generation economics, and oil-major subsidiaries repurposing downstream energy expertise. Competitive intensity manifests through strategic partnerships for storage technology access and geographic expansion into adjacent European markets.
Within the state-affiliated utility tier, EDF Renewables exemplifies hybrid portfolio strategies that pair photovoltaic arrays with existing nuclear infrastructure. Among pure-play renewable specialists, Neoen and Voltalia SA occupy positions emphasizing agrivoltaic configurations and merchant storage revenue optimization respectively. These entities represent divergent responses to France's regulatory evolution toward capacity-based remuneration mechanisms.
| Leading Market Players |
|---|
| Engie SA |
| EDF Renewables |
| TotalEnergies SE |
| Neoen |
| Voltalia SA |
| Albioma SA |
| meeco AG |
| Solairedirect |
| Arkolia Energies |
| Others |
Supply & Pricing Matrix
Corporate procurement mandates for hybrid solar-plus-storage configurations under CRE's revised auction scoring are forcing developers to restructure supplier relationships around integrated system vendors rather than discrete component sourcing, compressing margins on pure-play module suppliers while rewarding vertically integrated technology platforms.
Pricing Analysis
Capacity additions in China's polysilicon manufacturing base are reshaping price floors for crystalline silicon modules serving French utility-scale projects. Project-based long-term offtake contracts dominate procurement structures, with price differentiation resting on module efficiency tier and inverter cybersecurity certification level. Cost compression in standard-grade installations is intensifying because polysilicon spot price volatility feeds directly into EPC contractor bidding behavior. Manufacturing plants in Occitanie exhibit lowest price sensitivity due to Scope 2 compliance premiums, while residential rooftop segments remain most exposed to financing rate fluctuations.
Supply Chain Analysis
Single-source vulnerability sits with Xinjiang-based polysilicon refiners supplying French crystalline silicon module assemblers. Geographic supply concentration centers on China for wafer slicing and cell fabrication, Vietnam for module assembly, and Germany for inverter power electronics. Raw material dependencies include metallurgical-grade silicon, silver paste for front-side contacts, and aluminum frames. Tariff exposure through EU anti-dumping duties on Chinese photovoltaic components creates structural procurement risk. Distribution runs through specialized renewable energy EPC contractors with CRE certification rather than open commodity channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's solar sector has entered a late-cycle quality phase where CRE's cybersecurity mandates and hybrid storage requirements favor vendors with integrated technology platforms over hardware assemblers.
For Market Incumbents: Deepen captive supply relationships with European inverter manufacturers to secure ANSM certification pathways before qualification timelines extend further. Incumbent developers must consolidate agrivoltaic project pipelines in Occitanie before specialized entrants capture rural development program allocations. Vertical integration into battery storage systems represents the critical defensive lever as pure solar margins compress under merchant auction exposure. For New Entrants and Emerging Players: Floating photovoltaic platforms on EDF hydro reservoirs offer the most penetrable white-space opportunity given land-use conflict immunity and streamlined permitting. New entrants should target the commercial rooftop segment in Provence-Alpes-Côte d'Azur where net metering reforms accelerate payback visibility for property owners. A technology-first wedge through bifacial module optimization for aquatic installations enables differentiated positioning against ground-mounted incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play renewable developers holding merchant storage revenue optimization capabilities rather than legacy feed-in tariff portfolios. Long-term viability over a multi-year horizon favors entities with demonstrated CRE auction execution and balance sheet capacity to absorb price volatility. Acquisition targets should demonstrate regulatory affairs functions capable of navigating CNIL data protection mandates. The signal to watch is CRE's capacity auction design evolution toward flexibility remuneration mechanisms.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Solar-Plus-Storage Buildout | CRE's revised auction scoring mandates storage co-location, restructuring project finance around merchant flexibility revenue. |
| Agrivoltaic Project Development | Elevated panel configurations enable dual land use, unlocking rural development program subsidies in southwestern France. |
| Floating Solar Deployment | Aquatic photovoltaic systems on EDF hydro reservoirs bypass agricultural zoning restrictions in land-scarce regions. |
| Cybersecurity Certification Investment | ANSM and CNIL compliance protocols extend hardware vendor qualification timelines, creating competitive moats for early certifiers. |
| Corporate PPA Structuring | Direct contracting with automotive and aerospace suppliers in Occitanie displaces traditional utility offtake channels. |
Research Methodology
Direct dialogue with utility planning officers, IPP project developers, EPC contractors, and grid operators anchored qualitative findings, cross-referenced against secondary validation from CRE regulatory filings, IEA renewable deployment databases, EDF infrastructure disclosures, and EU Green Deal implementation reports. Bottom-up project pipeline tracking triangulated with top-down macroeconomic scenario modeling.
Top-down demand modeling segmented the market across technology type, installation configuration, application sector, and end-user archetype throughout the projection horizon. CAGRs were derived from installed capacity build rates and system cost trajectories across the analysis window. Forecast inputs incorporated polysilicon supply elasticity, CRE auction capacity allocation schedules, and corporate PPA procurement velocity from manufacturing sector disclosures.
The model holds under stable EU Green Deal implementation and continued CRE regulatory support; deviation in polysilicon trade policy or nuclear fleet availability would shift deployment trajectories. Forecasts reflect documented assumptions about technology cost curves and policy continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Fuel Market
Solar Power Systems
US Residential Solar PV Market
Solar Power Systems
Flexible Parylene-Based Solar Cells Market
Solar Power Systems
Egypt Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Panel Cleaning Equipment Market
Solar Power Systems
Solar Panel Lights Market
Solar Power Systems
Solar Freezer Market
Solar Power Systems
Solar PV Backsheet Market
Solar Power Systems
Global Solar Panel Materials Market
Solar Power Systems
Solar Module Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
Czech Republic Solar Energy Market
Solar Power Systems
Solar Kiosk Market
Solar Power Systems
Third Generation Solar Cell Sales Market
Solar Power Systems
Optical Solar Reflectors Market