
 Global Chiller Market | 2026-2036
Global Chiller Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chiller Market Analysis
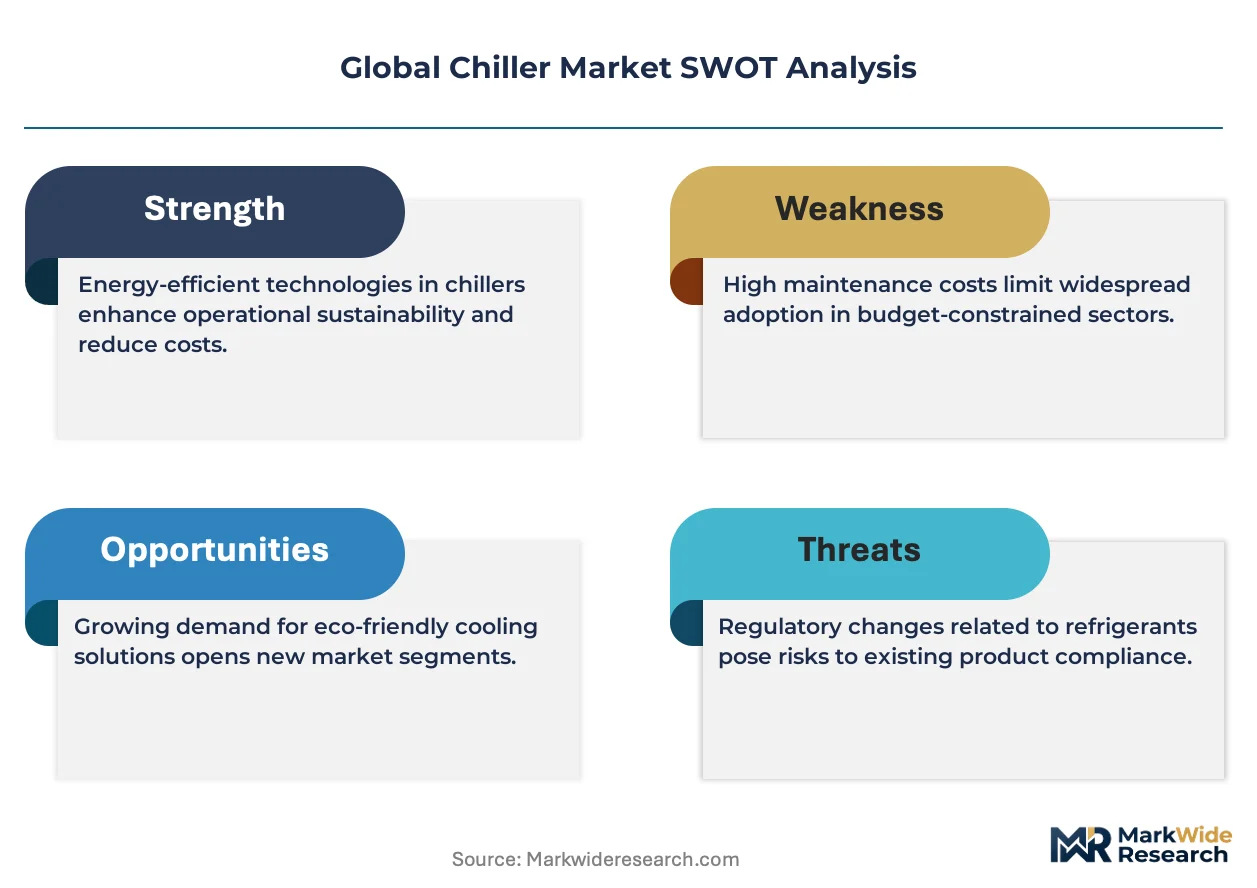
Low-GWP refrigerants are realigning chiller product economics as manufacturers reformulate compressor systems to meet phasedown schedules. Carrier Global Corporation leverages its scroll compressor expertise to sustain margins in the transition. Daikin Industries anchors its position through captive supply of HFC-alternative refrigerants. Trane Technologies competes on chiller plant optimization software integration across North American commercial portfolios.
A chiller is a vapor-compression or absorption refrigeration apparatus that removes heat from a liquid coolant, typically water or brine, through a refrigerant cycle operating between 4°C and 15°C setpoints; the conditioned fluid then circulates through heat exchangers to cool air or process equipment in commercial buildings, industrial facilities, and district cooling networks. Water-cooled centrifugal systems dominate installed base value in large-scale HVAC applications, while air-cooled scroll and screw configurations capture faster expansion in data center and distributed commercial deployments where cooling tower infrastructure is unavailable. Absorption chillers, though mature, retain niche margin pools in industrial cogeneration settings where waste heat recovery economics justify higher capital outlays.
The EPA SNAP program and EU F-Gas Regulation are restricting high-GWP refrigerant availability, compelling OEMs to redesign compressor architectures and secure A2L safety certifications for mildly flammable alternatives. China's MEE enforces GB energy-efficiency standards that ratchet minimum performance coefficients upward on a province-by-province implementation schedule. Stakeholders must monitor refrigerant supply chain readiness and regional certification timelines to avoid stranded inventory as regulatory phase-ins accelerate.
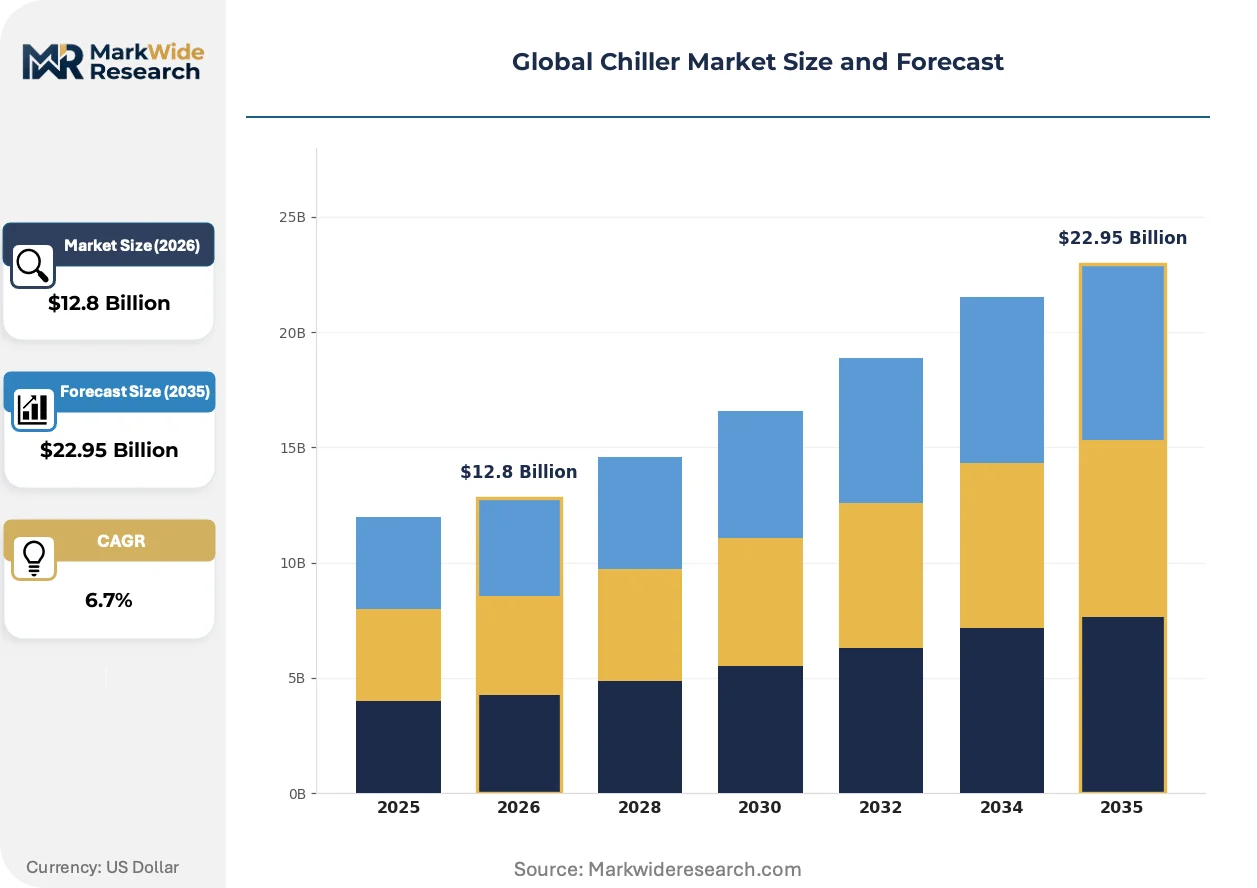
Market Dynamics
The EU F-Gas Regulation and EPA SNAP program are forcing simultaneous refrigerant transitions and compressor redesigns across all major manufacturing bases, compressing product development cycles while fragmenting regional certification requirements.
Growth Catalysts
- Data center thermal loads:AI server clusters in Singapore and Northern Virginia are expanding chiller deployments to manage concentrated heat rejection requirements.
- Industrial retrofit cycles:China's eastern manufacturing corridor is outpacing greenfield additions with cooling system upgrades driven by MEE enforcement of GB energy-efficiency standards.
- District cooling networks:Urban densification in Middle Eastern cities is accelerating centralized chiller plant construction over distributed rooftop units.
Market Restraints
- Refrigerant supply concentration:HFC-alternative chemistries depend on limited fluorochemical feedstock sources concentrated in Chinese and Japanese chemical corridors.
- A2L certification bottlenecks:Mildly flammable refrigerant safety approvals lag product development timelines, stranding engineered systems awaiting regional authorization.
- Copper-aluminum price volatility:Heat exchanger material costs swing with commodity markets, compressing fabrication margins on fixed-price contracts.
Strategic Opportunities
- India's pharmaceutical cold chain:Temperature-controlled logistics expansion creates demand for precision scroll chillers in vaccine and biologics distribution.
- Waste heat recovery integration:Absorption chiller-cogeneration pairing captures stranded industrial thermal energy in European chemical and paper processing facilities.
- Digital twin deployment:Predictive maintenance software subscription models are penetrating North American commercial building portfolios previously served by break-fix contracts.
Industry Challenges
- Refrigerant handling certification gaps:Field technician training programs lag the pace of A2L and CO₂ system rollouts, constraining installation capacity.
- Legacy control system integration:BACnet and Modbus protocol mismatches between new chiller plants and existing building management systems extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chiller Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Absorption, Centrifugal Application: Food & Beverage, HVAC, Chemical Processing, Industrial Manufacturing End User: Commercial, Residential, Healthcare, Hospitality Technology: Variable Speed Drive, Smart Controls, Thermal Energy Storage, Chiller Plant Optimization |
| Companies Covered | Johnson Controls International, Smardt Chiller Group, Carrier Global Corporation, Drake Refrigeration, LG Electronics, Daikin Industries, Mitsubishi Electric Corporation, Polyscience, Trane Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chiller Market Emerging Trajectories
Refrigerant chemistry transitions are compressing product lifecycles while digitalization of chiller plant operations is shifting value capture toward software-enabled service models.
Magnetic bearing centrifugal compressors are eliminating oil lubrication systems and reducing mechanical losses in large-tonnage applications. Data center operators in hyperscale facilities are specifying these configurations for part-load efficiency advantages. The technology is integrating with variable-speed drives and advanced refrigerant circuits to enable sub-0.5 kW/ton performance at design conditions.
The EU F-Gas Regulation mandates an 80% phasedown of HFC consumption by 2030 against baseline levels. OEMs must redesign compressor architectures for lower-GWP alternatives while securing safety certifications across member state notification bodies. Commercial HVAC contractors in Germany and France face compressed retrofit timelines as reclaimed refrigerant availability tightens.
Performance-based cooling service contracts are displacing equipment ownership models in North American commercial real estate portfolios. Landlords in Class A office buildings transfer capital risk to chiller-as-a-service providers who retain equipment title and efficiency guarantees. This restructuring concentrates in California and New York markets where carbon disclosure mandates elevate operational visibility requirements.
Global Chiller Market Segmentation
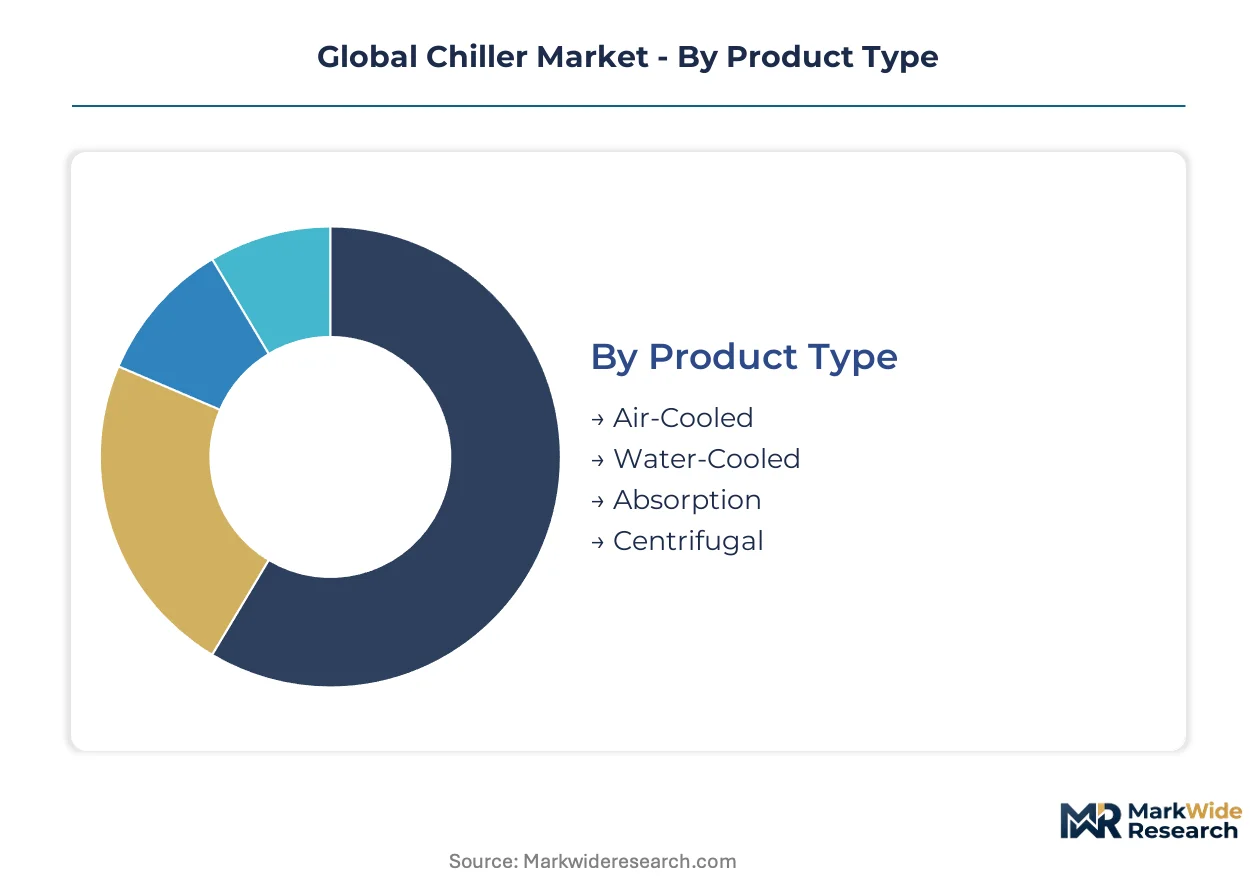
Chiller procurement decisions hinge on thermal load profiles, infrastructure constraints, and regulatory compliance timelines. Segmentation reveals how upgrade cycles concentrate in water-cooled replacements and smart control retrofits while greenfield deployment favors air-cooled configurations.
Product Type:
Replacement cycles dominate purchasing patterns as facility managers phase out refrigerants restricted under the EU F-Gas Regulation and EPA SNAP program.
- Water-Cooled:These systems leverage cooling tower infrastructure to achieve superior thermodynamic efficiency through lower condensing temperatures. Data center operators in Singapore and Northern Virginia specify water-cooled centrifugal configurations for AI server cluster thermal management, though cooling tower water treatment adds operational complexity.
- Air-Cooled:Eliminating cooling tower dependency reduces capital expenditure and permits installation in space-constrained urban environments. Distributed commercial deployments across Germany and France favor these units where infrastructure retrofits prove cost-prohibitive.
- Absorption:Waste heat recovery integration in European chemical processing facilities sustains niche demand despite higher capital intensity.
- Centrifugal:Magnetic bearing variants are displacing oil-lubricated designs in large-tonnage applications where part-load efficiency governs lifecycle economics.
Water-Cooled sits at the top of the volume ranking, with Air-Cooled climbing the fastest.
Application:
Cost tier differentiation separates mission-critical process cooling from comfort conditioning, with premium specifications concentrated in regulated industries.
- HVAC:Commercial building thermal management accounts for substantial installed base value, with district cooling networks in Middle Eastern cities accelerating centralized chiller plant construction over distributed rooftop alternatives.
- Industrial Manufacturing:China's eastern manufacturing corridor drives cooling system upgrades as MEE enforcement of GB energy-efficiency standards compels retrofit cycles outpacing greenfield additions.
- Food & Beverage:Cold chain integrity requirements in India's pharmaceutical distribution network create demand for precision temperature control.
- Chemical Processing:Hazardous area classifications and corrosive environments necessitate specialized materials and safety system integration.
HVAC commands the largest revenue pool, with Industrial Manufacturing gaining share fastest.
End User:
Customer type determines specification stringency, with healthcare and hospitality imposing uptime guarantees that reshape maintenance contract structures.
- Commercial:Class A office buildings in California and New York markets are transitioning to chiller-as-a-service models that transfer capital risk to efficiency guarantee providers.
- Healthcare:Operating room and imaging suite cooling demands 24/7 redundancy with N+1 configurations mandated by facility accreditation standards.
- Hospitality:Guest comfort expectations and event space load variability drive specification toward variable-speed configurations with rapid response capability.
- Residential:District cooling subscriber growth in dense urban developments concentrates demand at central plant level rather than individual unit deployment.
Commercial dominates current installations, with Healthcare expanding most quickly.
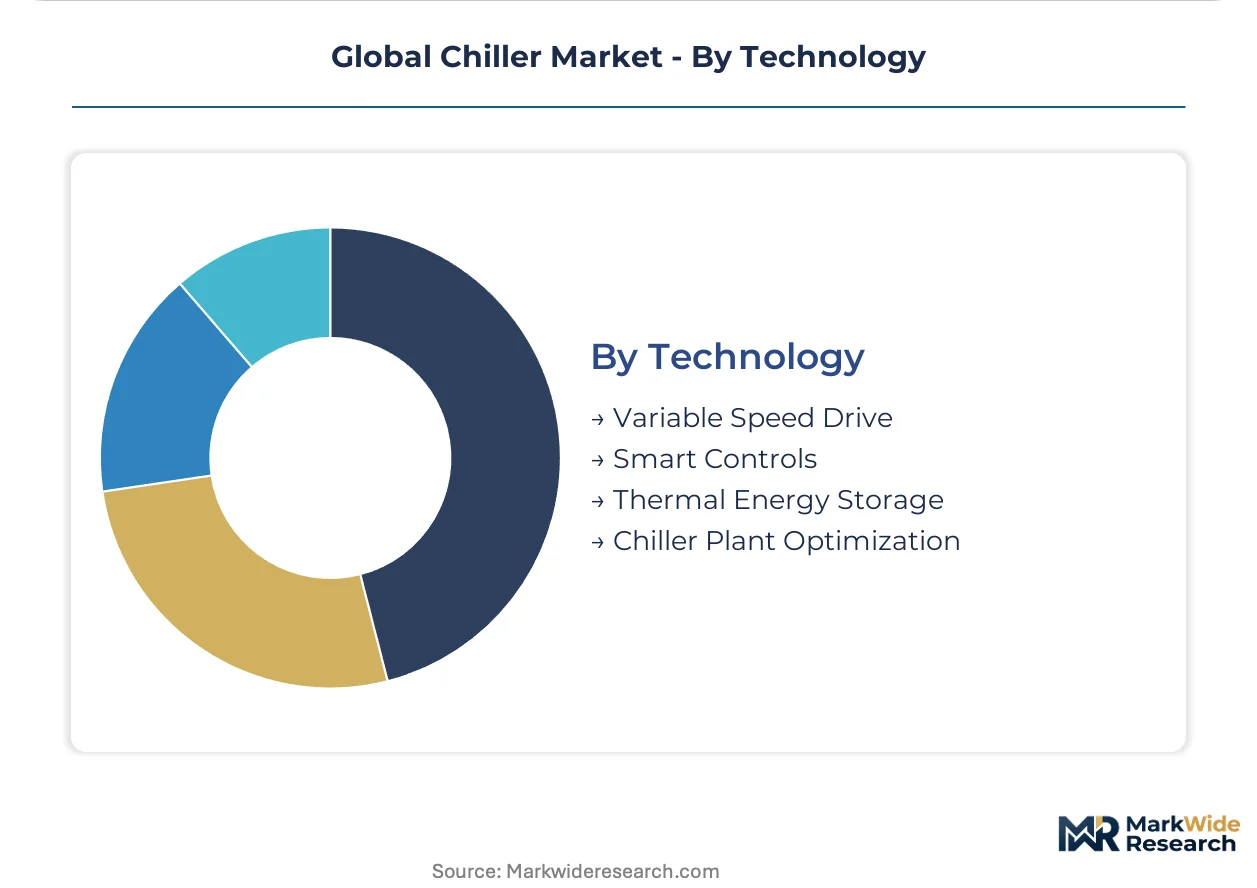
Technology:
Margin capture is shifting from hardware sales toward software-enabled service models as digitalization penetrates chiller plant operations.
- Smart Controls:BACnet and Modbus protocol integration enables building management system connectivity, though legacy system mismatches extend commissioning timelines.
- Variable Speed Drive:Part-load efficiency optimization reduces energy consumption across fluctuating thermal demand profiles in commercial portfolios.
- Chiller Plant Optimization:Predictive maintenance software subscriptions are penetrating North American commercial real estate previously served by break-fix contracts.
- Thermal Energy Storage:Ice and chilled water storage systems shift electrical demand away from peak pricing periods in utility territories with time-of-use rate structures.
Smart Controls leads technology adoption, with Chiller Plant Optimization showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor commands the dominant share of industrial cooling demand, with province-level energy-efficiency enforcement driving retrofit cycles that outpace new construction. Regulatory fragmentation across major economies is compressing product development timelines as OEMs navigate simultaneous refrigerant transitions.
United States
Data center operators in Northern Virginia are expanding chiller deployments to manage thermal loads from AI server clusters. The EPA SNAP program restricts high-GWP refrigerant availability, compelling compressor redesigns. California and New York markets concentrate chiller-as-a-service adoption where carbon disclosure mandates elevate operational visibility requirements.
Germany
Commercial HVAC contractors face compressed retrofit timelines as reclaimed refrigerant availability tightens under EU F-Gas Regulation mandates. The country's national energy regulator enforces building efficiency standards that accelerate district cooling network investments. Industrial facilities in the Rhine-Ruhr corridor pair absorption chillers with cogeneration systems for waste heat recovery.
China
MEE enforcement of GB energy-efficiency standards compels cooling system upgrades across the Yangtze River Delta manufacturing belt. Province-by-province implementation schedules ratchet minimum performance coefficients upward. Shanghai and Jiangsu industrial parks dominate retrofit demand as facility managers phase out legacy equipment ahead of regulatory deadlines.
Singapore
Hyperscale data center operators specify water-cooled centrifugal configurations for concentrated heat rejection requirements. The country's national environmental agency enforces stringent sustainability criteria for new industrial cooling installations. The Tuas industrial zone anchors expansion of precision temperature control infrastructure serving semiconductor and biopharma processing.
India
Temperature-controlled logistics expansion creates demand for precision scroll chillers in vaccine and biologics distribution networks. The Central Electricity Authority enforces efficiency labeling requirements on commercial cooling equipment. Maharashtra and Gujarat pharmaceutical clusters concentrate cold chain infrastructure investment ahead of export compliance deadlines.
Global Chiller Market Vendor Landscape
Global majors compete with regional champions across refrigerant transition timelines and certification requirements, producing a tiered structure where scale-driven players hold installed-base advantages while specialists capture niche margin pools. The vendor base separates into three strategic archetypes: full-line HVAC conglomerates with captive refrigerant supply, precision chiller specialists serving mission-critical applications, and industrial refrigeration contractors with process cooling expertise. Dominant competitive moves include backward integration into fluorochemical feedstocks and technology licensing partnerships to secure A2L safety certifications.
Within the full-line conglomerate tier, Carrier Global Corporation, Daikin Industries, and Trane Technologies exemplify scale-driven positioning. Carrier leverages scroll compressor expertise to sustain margins through refrigerant transitions. Daikin anchors its position through captive supply of HFC-alternative refrigerants. Trane competes on chiller plant optimization software integration across North American commercial portfolios.
| Leading Market Players |
|---|
| Johnson Controls International |
| Smardt Chiller Group |
| Carrier Global Corporation |
| Drake Refrigeration |
| LG Electronics |
| Daikin Industries |
| Mitsubishi Electric Corporation |
| Polyscience |
| Trane Technologies |
| Others |
Supply Flow & Price Mechanics
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by mandating A2L safety certifications for lower-GWP refrigerant systems. OEMs bearing certification costs pass premiums to data center operators and industrial facility managers seeking compliant equipment, while uncertified manufacturers compete on price in lagging regulatory jurisdictions.
Pricing Analysis
Input-cost pass-through from copper-aluminum heat exchanger materials and fluorochemical feedstocks compresses fabrication margins on fixed-price contracts. Three-tier pricing structure across premium, standard, and economy levels separates magnetic bearing centrifugal configurations from oil-lubricated designs and basic scroll units. Cost compression in the economy tier is intensifying because commodity price volatility outpaces contract renegotiation cycles. Data center operators show least price sensitivity due to uptime guarantees, while distributed commercial buyers in Germany and France prioritize capital expenditure minimization.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and Japanese chemical corridors for HFC-alternative refrigerant feedstocks. Manufacturing draws from fluorochemical precursors, rare-earth magnetic bearing components, and precision-machined compressor castings. Tariff exposure on aluminum coil stock and copper tubing feeds from Chilean and Indonesian smelters amplifies cost unpredictability. Distribution runs through authorized HVAC contractor networks and direct OEM relationships with hyperscale data center developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as AI server cluster thermal loads shift procurement toward premium water-cooled centrifugal specifications with sub-0.5 kW/ton efficiency guarantees.
For Market Incumbents: To counter A2L certification bottlenecks stranding engineered systems, Carrier Global Corporation and Trane Technologies should deepen backward integration into refrigerant supply chains while accelerating scroll compressor redesigns for mildly flammable alternatives. Captive fluorochemical production and multi-jurisdiction safety approvals preserve margin pools as regulatory phase-ins compress product development timelines. For New Entrants and Emerging Players: Direct-to-contractor digital platforms offer white-space access in India's pharmaceutical cold chain and European waste heat recovery integration. Precision scroll chillers for vaccine distribution networks present the most penetrable segment given fragmented incumbent presence. Channel partnerships with temperature-controlled logistics operators bypass capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap specialists with magnetic bearing centrifugal expertise and district cooling project pipelines. Long-term viability hinges on software-enabled service model transition and refrigerant transition readiness. The signal to watch is chiller-as-a-service contract penetration in California and New York carbon disclosure mandate markets.| Strategic Initiative | Industry Significance |
|---|---|
| A2L Safety Certification Investment | Secures market access under EU F-Gas Regulation and EPA SNAP program enforcement timelines. |
| Backward Integration into Fluorochemicals | Daikin Industries demonstrates captive refrigerant supply insulates margin compression during transitions. |
| Chiller-as-a-Service Model Launch | Transfers capital risk to efficiency guarantee providers in California and New York disclosure-mandate markets. |
| Magnetic Bearing Technology Licensing | Eliminates oil lubrication systems for data center operators specifying part-load efficiency advantages. |
| District Cooling Network Partnership | Captures centralized plant construction preference in Middle Eastern urban densification corridors. |
Methodological Framework
Coverage spans the United States, Germany, China, Singapore, and India, with primary inputs from each market's stakeholder base. Plant engineers, HVAC contractor procurement leads, data center facilities managers, and aftermarket service heads contributed structured interviews. Secondary validation drew from EPA SNAP filings, EU F-Gas Regulation notification databases, MEE GB standard province-level schedules, and SEC 10-K equipment disclosure segments. Bottom-up installation data triangulated against top-down energy consumption projections.
Granularity-level modeling addressed product type, application, end user, and technology dimensions across the projection horizon. Water-cooled, air-cooled, absorption, and centrifugal configurations were assessed separately. CAGRs were derived from regression analysis of historical retrofit cycles and regulatory enforcement schedules. Forecast inputs included AI server cluster thermal load density trajectories and province-by-province MEE implementation timelines.
Refrigerant supply disruptions, A2L certification delays, and copper-aluminum commodity spikes are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on regulatory phase-in adherence and technology substitution elasticities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Seawater Condensers Market
Cooling Systems
Plate and Frame Heat Exchangers Market
Cooling Systems
Industrial Water Cooling System Market
Cooling Systems
Evaporative Condensing Unit Market
Cooling Systems
Fluid Coolers Market
Cooling Systems
Europe Cooling Systems Market
Cooling Systems
Solar Air Conditioning Market
Cooling Systems
Turbine Inlet Cooling Systems Market
Cooling Systems
United States Heat Pump Market
Cooling Systems
Aftercoolers Market
Cooling Systems
Adiabatic Cooler Market
Cooling Systems
Air Source Heat Pump Market
Cooling Systems
Saudi Arabia Desert Air Coolers Market
Cooling Systems
Thermosiphon Cooling System Market
Cooling Systems
Adaptive Cooling Fan Market
Cooling Systems
Thawing System Market