
 Energy Storage Temperature Control Equipment Market | 2026-2036
Energy Storage Temperature Control Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Storage Temperature Control Equipment Market Insights
Modular rack-level thermal units bundled with battery management software is repositioning procurement patterns for grid operators. Shenzhen Envicool Technology leverages its cooling system specialization to anchor utility contracts across Asia-Pacific. Stulz competes through precision air conditioning expertise extended from data center applications into containerized battery storage. Guangdong Shenling Environmental Systems differentiates via integrated heating and cooling platforms designed for extreme climate zones.
Energy Storage Temperature Control Equipment encompasses active and passive thermal management systems that maintain electrochemical cell temperatures between 15°C and 35°C through liquid cooling loops, phase change material layers, or forced air convection, thereby preventing thermal runaway and capacity degradation in lithium-ion installations. Cooling Systems dominate product type revenue due to their necessity in high-density battery configurations, while Phase Change Materials represent the fastest-growing technology segment as manufacturers seek passive redundancy for safety-critical applications. Battery Storage applications command the largest share of end-user spending, though Electric Vehicles are reshaping component demand through automotive-grade thermal interface requirements.
China's NMPA and GB standards enforce fire containment and thermal propagation testing for grid-connected storage, compelling manufacturers to redesign enclosure architectures. The EU Green Deal and F-Gas Regulation restrict refrigerant choices in European cooling systems, redirecting R&D toward CO2-based and water-glycol alternatives. Stakeholders must monitor how evolving carbon border adjustments and local content rules in multiple jurisdictions reshape sourcing strategies for compressor units and heat exchangers.
Market Dynamics
Utility-scale battery operators now mandate liquid cooling loops as standard architecture, compressing procurement cycles for thermal management vendors and forcing enclosure redesigns to accommodate integrated heat exchangers.
Growth Catalysts
- Grid-scale storage mandates:China's dual carbon goals and NMPA fire containment standards compel thermal redundancy in every new battery installation.
- Phase change material adoption:Passive safety layers now accompany active cooling in lithium-ion configurations to prevent thermal propagation failures.
- F-Gas Regulation phase-down:The EU's refrigerant restrictions accelerate R&D into CO2-based and water-glycol cooling architectures.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger and piping raw material costs swing with commodity markets, squeezing margin predictability for system integrators.
- Compressor supply concentration:German and Japanese manufacturers dominate high-efficiency refrigeration compressor production, creating single-source vulnerabilities.
- Thermal interface material performance ceilings:Current silicone-based gap fillers hit conductivity limits above 8 W/mK, constraining heat flux in next-generation cell chemistries.
Strategic Opportunities
- India grid storage buildout:CEA mandates and PLI scheme incentives create first-mover openings for cooling system providers in utility-scale tenders.
- Automotive-grade thermal interface crossover:EV battery pack thermal management specifications are migrating into stationary storage designs, elevating performance baselines.
- Integrated heating-cooling platforms:Extreme climate zone deployments in northern China and Canada require bidirectional thermal control, opening modular system sales.
Industry Challenges
- Multiphysics simulation talent scarcity:Battery thermal modeling requires coupled electrochemical-thermal-fluid expertise that crosses traditional engineering silos.
- GB standard certification timelines:China's updated fire propagation testing protocols extend product validation cycles by 4-6 months.
- Legacy HVAC integration friction:Containerized battery systems must interface with existing building management protocols, complicating control software architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Storage Temperature Control Equipment Market |
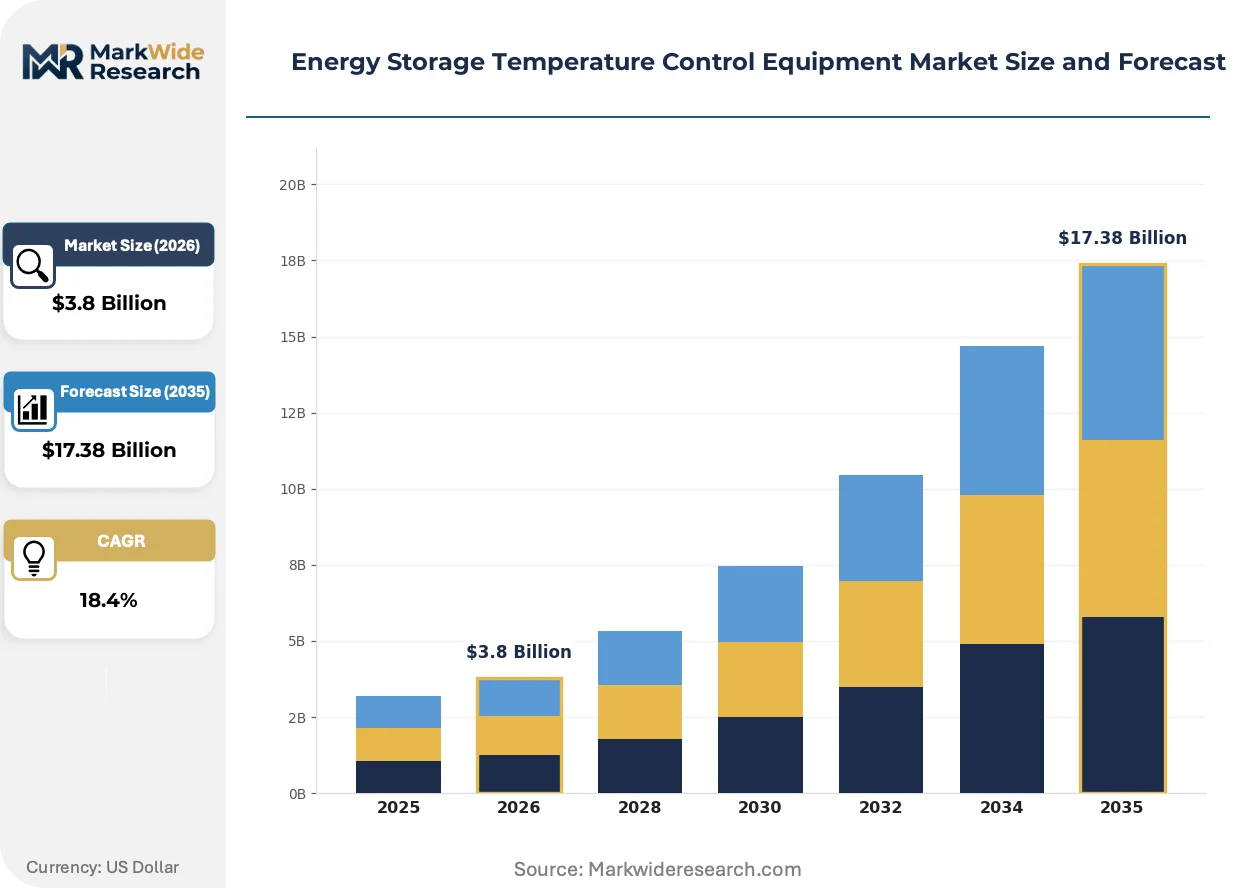
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooling Systems, Heating Systems, Insulation Materials, Temperature Sensors Technology: Thermal Management, Phase Change Materials, Active Control Systems, Passive Control Systems Application: Battery Storage, Electric Vehicles, Renewable Energy Systems, Industrial Applications End User: Utilities, OEMs, Commercial Enterprises, Residential Users |
| Companies Covered | Shenzhen Envicool Technology Co.,Ltd., Stulz, Guangdong Shenling Environmental Systems Co.,Ltd., Bergstrom, Songz Automobile Air Conditioning Co.,Ltd., Sanhe Tongfei Refrigeration Co.,Ltd., Guangzhou Goaland Energy Conservation Tech.Co.,Ltd., Shandong Longertek Technology Co.,Ltd., Aotecar New Energy Technology Co.,Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Storage Temperature Control Equipment Market Trends and Innovations
Liquid cooling architectures are compressing air-cooled system share as battery energy densities climb past 200 Wh/kg and thermal runaway containment becomes non-negotiable in utility contracts.
Immersion dielectric fluids are overtaking cold plate designs in safety-critical deployments. These engineered fluids enable direct cell contact heat removal without electrical conductivity risks. European grid operators now specify immersion for projects above 100 MWh capacity. The technology is overtaking traditional indirect cooling in premium-tier procurements.
The EU F-Gas Regulation's hydrofluorocarbon phase-down is forcing refrigerant substitutions across cooling system portfolios. Manufacturers must redesign compressor architectures for CO2 transcritical cycles or water-glycol loops. German and French utility-scale projects now require refrigerant declarations in tender documentation, shifting competitive advantage toward vendors with alternative cooling expertise.
Buyers now unbundle hardware procurement from long-term service agreements, compressing upfront capital commitments and transferring operational risk to thermal management vendors. This payment restructuring favors suppliers with captive service networks over pure equipment manufacturers. The pattern is most visible in United States utility contracts, where power purchase agreement structures mirror this risk transfer.
Energy Storage Temperature Control Equipment Market Segmentation
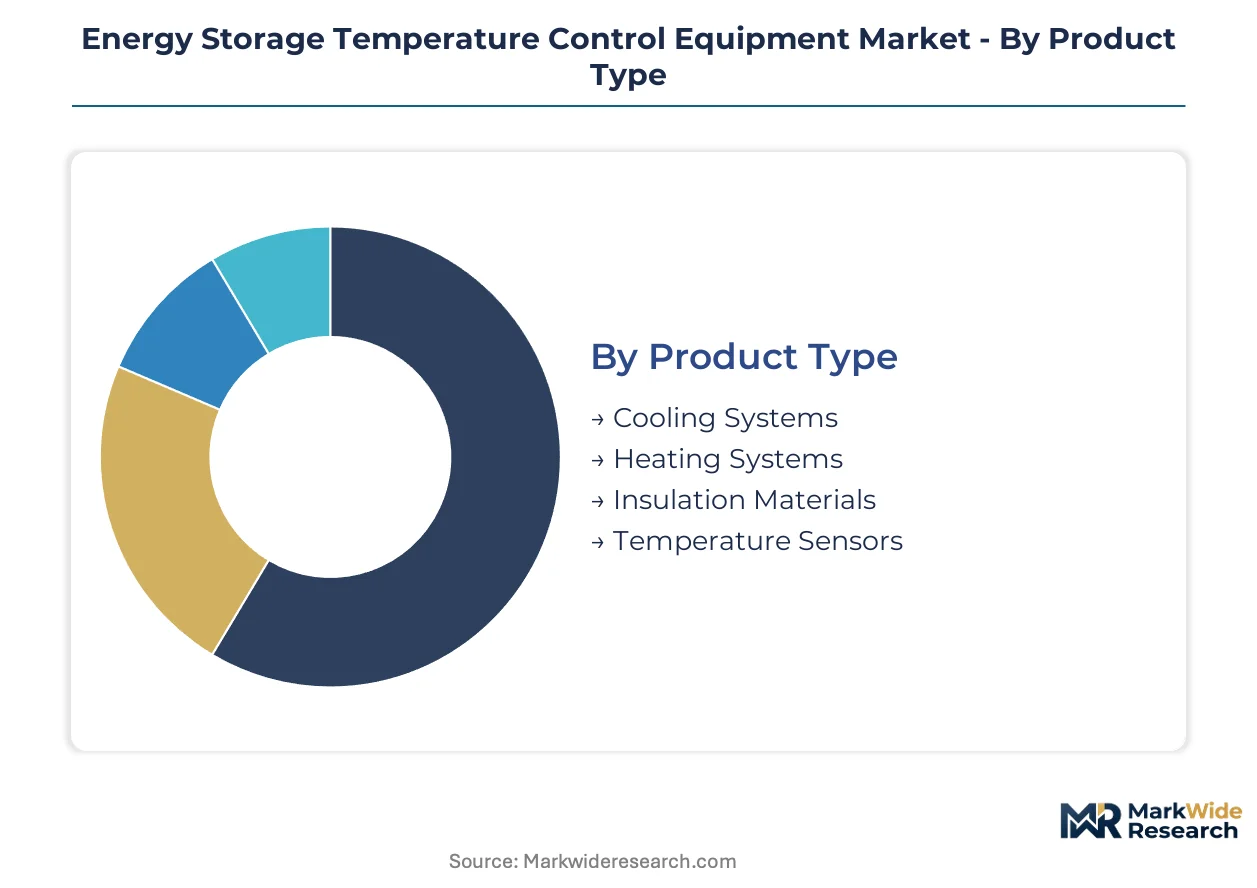
Thermal management architectures vary sharply in capital requirements across product categories and end-use applications. Procurement patterns diverge between utility-scale operators seeking integrated cooling loops and residential buyers prioritizing passive safety layers.
Product Type:
Capital intensity peaks in active mechanical systems requiring compressor arrays and heat exchanger networks, while sensor and insulation categories demand lower upfront outlays.
- Cooling Systems:Liquid cooling loops, forced air convection units, and vapor-compression assemblies maintain electrochemical cells between 15°C and 35°C. Utility-scale battery deployments across China and the United States now specify liquid cooling as mandatory architecture, compressing procurement cycles for vendors.
- Heating Systems:Electric resistance heaters and heat pump assemblies prevent sub-zero capacity loss in northern climate zones. Bidirectional thermal platforms are gaining traction in Canadian and northern Chinese grid storage installations where seasonal temperature swings exceed 40°C.
- Insulation Materials:Aerogel blankets and ceramic fiber boards contain thermal propagation between battery modules.
- Temperature Sensors:Distributed fiber-optic and thermocouple arrays feed real-time data into battery management systems.
Cooling Systems absorb the bulk of installed capacity; Phase Change Materials within insulation categories are expanding most quickly as passive redundancy layers.
Technology:
Technology selection tracks the trade-off between precision control and operational simplicity, with active systems commanding premium pricing against passive alternatives.
- Thermal Management:Integrated hardware-software stacks orchestrate cooling loops, heating elements, and sensor networks through centralized control algorithms. OEMs in Germany and the United States are bundling these platforms with long-term service agreements, transferring operational risk from asset owners.
- Phase Change Materials:Paraffin and salt-hydrate compounds absorb latent heat during thermal excursion events without electrical power. China's NMPA fire containment standards now encourage PCM layers as secondary protection in grid-connected lithium-ion installations.
- Active Control Systems:Microprocessor-driven valve networks and variable-speed compressors optimize energy consumption against thermal load.
- Passive Control Systems:Heat sinks, thermal interface pads, and natural convection channels operate without powered components.
Thermal Management platforms dominate current procurement volumes; Phase Change Materials are climbing the fastest as regulatory pressure elevates passive safety requirements.
Application:
Application segmentation reflects divergent thermal flux densities and safety certification thresholds across mobility and stationary storage.
- Battery Storage:Containerized and rack-level thermal units serving grid-scale electrochemical installations. China's dual carbon goals and utility-scale procurement mandates in the United States are concentrating demand for liquid-cooled architectures above 100 MWh capacity.
- Electric Vehicles:Automotive-grade cold plates, chillers, and refrigerant loops meeting vibration and crash-test specifications. Thermal interface requirements from EV battery packs are migrating into stationary storage designs, elevating performance baselines across both segments.
- Renewable Energy Systems:Solar-plus-storage and wind-coupled installations requiring diurnal thermal cycling resilience.
- Industrial Applications:Forklift fleets, backup power systems, and material handling equipment with intermediate duty cycles.
Battery Storage commands the largest share of end-user spending; Electric Vehicles are reshaping component demand through specification crossover effects.
End User:
End-user categories separate by procurement scale, technical integration depth, and appetite for operational risk transfer.
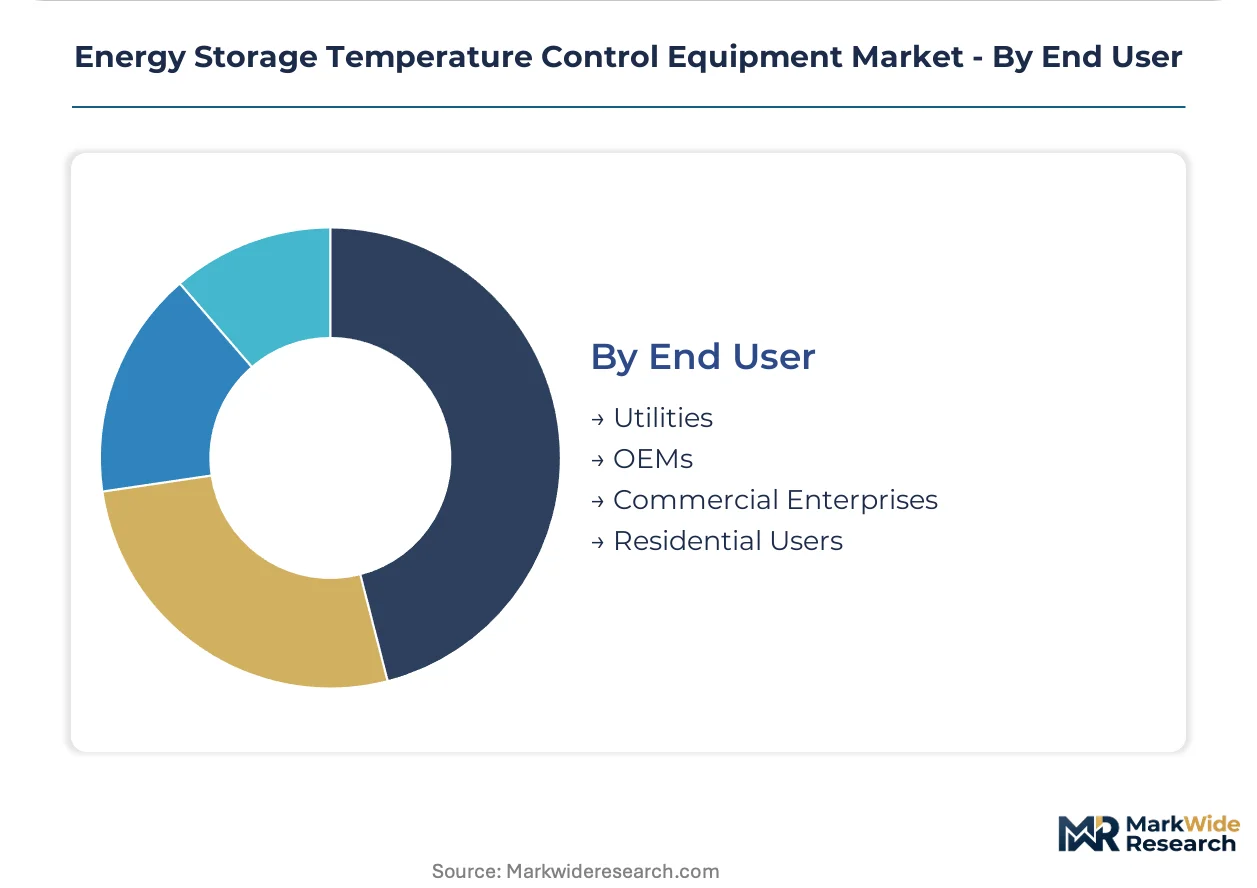
- Utilities:Grid operators and independent power producers contracting thermal management as bundled service packages. United States utility contracts now unbundle hardware from long-term service agreements, favoring vendors with captive maintenance networks.
- OEMs:Battery pack manufacturers and system integrators sourcing thermal components for original equipment production. German and Japanese compressor manufacturers dominate their supplier lists, creating single-source vulnerabilities.
- Commercial Enterprises:C&I solar developers and microgrid operators with intermediate scale requirements.
- Residential Users:Home battery installers selecting simplified air-cooled or passive thermal solutions.
Utilities absorb the bulk of installed capacity; Commercial Enterprises are expanding most quickly behind policy incentives in India and distributed generation growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port and Yangtze River Delta special economic zones concentrate thermal management manufacturing capacity alongside utility-scale battery deployment corridors. These designated zones attract cooling system vendors through tax holidays and streamlined GB standard certification pathways.
China
Grid-scale storage procurement mandates under dual carbon goals drive liquid cooling adoption across 100 MWh-plus installations. NMPA fire containment standards and updated GB testing protocols compel manufacturers to embed phase change materials as secondary thermal barriers. Shenzhen and Dongguan industrial clusters host integrated production of heat exchangers, compressors, and battery enclosure systems.
United States
IRA production tax credits accelerate utility-scale battery deployments in Texas and California ISO markets. FERC Order 2222 enables distributed storage aggregation, expanding addressable demand for containerized thermal units. Arizona and Nevada desert solar-plus-storage projects specify immersion cooling to manage 50°C ambient operating conditions.
Germany
The EU F-Gas Regulation hydrofluorocarbon phase-down forces refrigerant substitutions in cooling system portfolios. Bavaria and Baden-Württemberg host automotive-thermal crossover R&D as EV battery pack specifications migrate into stationary storage designs. Grid operators now require refrigerant declarations in tender documentation above 50 MWh capacity.
India
CEA mandates and PLI scheme incentives create first-mover openings for cooling system providers in utility-scale tenders. Gujarat and Tamil Nadu solar parks specify thermal management in 500 MWh-plus storage tenders. Domestic content requirements under the PLI scheme push foreign vendors toward joint venture structures with Indian fabricators.
Japan
METI subsidies for grid stabilization batteries elevate thermal performance requirements in Hokkaido and Tohoku wind-coupled installations. JIS standards for energy storage safety propagate automotive-grade thermal interface specifications into stationary applications. Osaka-Kobe industrial corridor maintains compressor and precision valve manufacturing for regional supply.
Energy Storage Temperature Control Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across product categories, creating a tiered structure where scale-driven HVAC incumbents face nimble battery-thermal entrants. The vendor base separates into three strategic archetypes: precision cooling specialists extending data center expertise, integrated environmental system manufacturers, and automotive-thermal crossover players repurposing EV battery pack designs. Consolidation pressure mounts through M&A activity targeting phase change material startups and strategic partnerships bundling hardware with long-term service agreements.
Among China-based fabricators, Shenzhen Envicool Technology Co.,Ltd. and Guangdong Shenling Environmental Systems Co.,Ltd. exemplify the precision cooling specialist archetype, while Stulz occupies a position bridging data center heritage with containerized storage applications. These three entities represent divergent geographic and technical positioning within the competitive set, with Chinese manufacturers anchoring Asia-Pacific procurement and European incumbents leveraging refrigerant-transition expertise.
| Leading Market Players |
|---|
| Shenzhen Envicool Technology Co.,Ltd. |
| Stulz |
| Guangdong Shenling Environmental Systems Co.,Ltd. |
| Bergstrom |
| Songz Automobile Air Conditioning Co.,Ltd. |
| Sanhe Tongfei Refrigeration Co.,Ltd. |
| Guangzhou Goaland Energy Conservation Tech.Co.,Ltd. |
| Shandong Longertek Technology Co.,Ltd. |
| Aotecar New Energy Technology Co.,Ltd. |
| Others |
Pricing and Supply Chain Analysis
The EU F-Gas Regulation's hydrofluorocarbon phase-down gates qualified supply for CO2-based and water-glycol cooling architectures, while simultaneously bifurcating pricing access between refrigerant-transition-ready vendors and legacy-dependent competitors. Premium-tier procurement now demands refrigerant declarations in tender documentation above 50 MWh capacity, compressing margin structures for unprepared system integrators.
Pricing Analysis
Cost-down pressure on liquid-cooled architectures accelerates because utility-scale battery operators now mandate integrated heat exchangers as standard, forcing enclosure redesigns and compressing upfront capital commitments. Pricing stratifies across premium, standard, and economy tiers based on certification grade against China's GB fire propagation protocols and volume scale in multi-hundred-megawatt procurement bundles. Chinese and German OEMs absorb the steepest margin compression due to raw material volatility in copper and aluminum heat exchanger components, while United States utilities demonstrate lowest price sensitivity through unbundled hardware-service contract structures that transfer operational risk to vendors.
Supply Chain Analysis
Reverse-logistics flows for compressor refurbishment and heat exchanger remanufacturing are underdeveloped across the thermal management sector, creating stranded asset risks for field-deployed cooling systems. Manufacturing concentrates in China, Germany, and Japan, with Shenzhen and Dongguan industrial clusters anchoring integrated production of heat exchangers, compressors, and battery enclosure systems. Raw material dependencies center on copper tubing, aluminum fin stock, and silicone-based thermal interface compounds. Single-source vulnerability concentrates in German and Japanese high-efficiency refrigeration compressor production. Distribution runs through EPC contractors and battery system integrators serving utility-scale developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Energy Storage Temperature Control Equipment Market is executing a technology-transition phase as immersion dielectric fluid architectures displace traditional cold plate designs in safety-critical deployments above 100 MWh capacity.
For Market Incumbents: Anchor defensive positioning through captive backward integration into compressor manufacturing and heat exchanger fabrication, mitigating single-source vulnerability exposure to German and Japanese suppliers. Accelerate GB standard certification investment to compress China's extended 4-6 month product validation cycles. Deepen service network density in United States ISO markets to capture unbundled hardware-service contract flows. For New Entrants and Emerging Players: Utility-scale solar developers in Gujarat and Tamil Nadu represent the most penetrable channel partner type for first-mover cooling system providers, given CEA mandates and PLI scheme incentives creating tender openings without entrenched incumbent relationships. Target joint venture structures with Indian fabricators to satisfy domestic content requirements. Lead with CO2 transcritical cycle expertise to exploit EU F-Gas Regulation refrigerant substitution demand. For Investors and Strategic Acquirers: Phase change material startup acquisitions are the leading indicator that passive safety layer technology is consolidating toward integrated thermal management platforms. Frame long-term viability around 5-10 year windows where automotive-thermal specification crossover elevates performance baselines across stationary storage. Monitor immersion cooling adoption rates in European grid operator tenders as the primary inflection signal for technology displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CO2 Transcritical Cycle Development | EU F-Gas Regulation compliance secures refrigerant-transition-ready market positioning in German and French utility tenders. |
| Phase Change Material Acquisition | China's NMPA fire containment standards elevate passive safety layers to mandatory secondary protection in grid-connected installations. |
| India Joint Venture Formation | PLI scheme domestic content requirements compel foreign cooling system vendors toward local fabrication partnerships. |
| Immersion Cooling Platform Launch | Arizona and Nevada desert solar-plus-storage projects specify direct cell contact heat removal for 50°C ambient operating conditions. |
| Service Network Expansion | United States utility contracts now unbundle hardware from long-term service agreements, transferring operational risk to vendors with captive maintenance infrastructure. |
Research Methodology
Regulatory filings from China's NMPA, EU F-Gas Regulation implementation documents, and FERC interconnection queue data formed the secondary backbone of this analysis. Primary interviews with utility planning officers, battery EPC contractors, thermal management procurement leads, and grid operator engineering directors were combined with bottom-up and top-down triangulation against customs records, SEC filings from diversified HVAC conglomerates, and project development databases tracking utility-scale storage deployments.
Historical trendline analysis of liquid cooling adoption rates, phase change material integration patterns, and refrigerant substitution timelines informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, technology architecture, application scale tier, end-user procurement structure, and regional regulatory cluster. CAGRs were derived through multivariate regression against battery energy density trajectories and utility-scale deployment pipelines, with specific inputs from compressor supply concentration indices and copper-aluminum commodity price volatility bands.
Caveats apply where raw material price swings, GB standard certification timeline extensions, or automotive-thermal specification migration delays could materially shift the outlook. Practitioners should monitor immersion cooling procurement specifications in European tenders and India's PLI scheme domestic content rule enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Global Air Coolers Market
Cooling Systems
Annular Cooler Market
Cooling Systems
Flue Gas Coolers Market
Cooling Systems
Middle East and Africa Cooling Systems Market
Cooling Systems
Solar Air Conditioning Market
Cooling Systems
Marine Cooling Systems Market
Cooling Systems
Chilled Water System Market
Cooling Systems
Global Secondary Refrigerants Market
Cooling Systems
Adaptive Cooling Fan Market
Cooling Systems
Portable Chiller Market
Cooling Systems
Cold Trap Market
Cooling Systems
Temperature Controlled Container Market
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
Global Condensing Unit Market
Cooling Systems
Industrial Water Cooling System Market
Cooling Systems
Lithium Battery Liquid Cooling Pump Market