
 Solar Fan Market | 2026-2036
Solar Fan Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Fan Market Insights
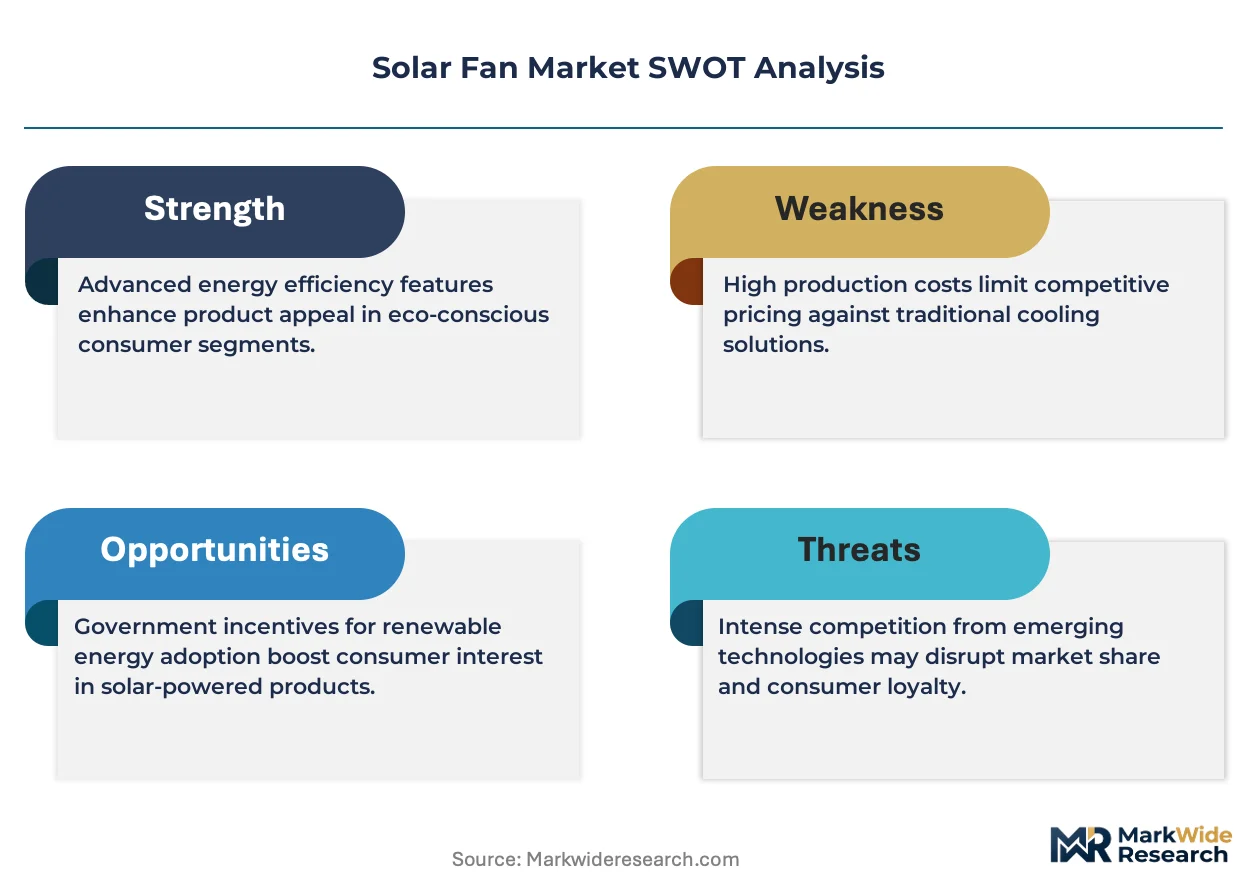
EPA Energy Star certification is recalibrating the cost-of-entry calculus for solar fan manufacturers targeting North American distribution channels. Remington Solar leverages its attic ventilation specialization to sustain premium positioning in residential retrofit segments. Broan-NuTone LLC anchors its competitive stance through channel control across big-box retail and contractor supply networks. QuietCool differentiates via variable-speed DC motor integration that reduces phantom load during low-irradiance conditions.
A solar fan converts photovoltaic energy into mechanical airflow through brushless DC motors, typically achieving 800-1,500 RPM with direct-drive architectures that eliminate belt maintenance and friction losses. The device serves primary commercial and residential purposes where grid connectivity is unreliable or cooling loads coincide with peak solar irradiance. Ceiling fans and exhaust fans occupy distinct margin pools, with roof-mounted exhaust configurations commanding higher installed value due to structural integration requirements while portable table units compete on price in emergency preparedness channels. Photovoltaic systems dominate technology shipments, though battery storage systems are gaining structural share in commercial applications where thermal comfort must persist through evening hours.
FERC interconnection standards and EPA Energy Star specifications shape product design requirements for US-market entrants, while India's BIS certification and CEA rooftop solar mandates create parallel compliance pathways for South Asian suppliers. The EU Green Deal and F-Gas Regulation indirectly expand solar fan addressable markets by restricting conventional refrigerant-based cooling in portable and supplemental applications. Stakeholders must monitor evolving photovoltaic import tariff schedules and battery chemistry safety standards to anticipate cost structure shifts and certification bottlenecks.
Market Dynamics
Monocrystalline photovoltaic cell efficiency gains are compressing unit economics for manufacturers sourcing from Southeast Asian foundries, while rural electrification mandates in sub-Saharan Africa and South Asia create parallel demand channels for off-grid cooling hardware.
Growth Catalysts
- India's CEA rooftop solar mandates:Grid instability across Maharashtra and Tamil Nadu drives residential and agricultural processing adoption of DC-powered ventilation systems.
- Sub-Saharan electrification programs:Off-grid cooling solutions gain structural support from development finance targeting rural household energy access.
- Brushless DC motor architectures:Direct-drive designs eliminate belt maintenance and friction losses, reducing lifetime operating costs for commercial deployments.
Market Restraints
- Photovoltaic import tariff volatility:Schedule uncertainty from US trade authorities disrupts cost planning for North American market entrants.
- Battery chemistry safety standards:Evolving certification requirements for lithium-ion storage systems extend product qualification timelines.
- Conventional refrigerant cooling:Portable compressor-based units retain price advantages in emergency preparedness channels despite F-Gas restrictions.
Strategic Opportunities
- Urban slum electrification:Informal settlement cooling represents underpenetrated demand in Indian megacities with unreliable grid infrastructure.
- EU Green Deal thermal restrictions:F-Gas Regulation phase-down creates addressable market expansion for supplemental non-refrigerant cooling.
- Variable-speed motor integration:Convergence of MPPT charge controllers with smart motor drivers enables phantom load reduction during low-irradiance conditions.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous EPA Energy Star, BIS, and CE marking processes strain product launch bandwidth.
- Photovoltaic supply chain reconfiguration:Southeast Asian foundry concentration creates geographic risk exposure for panel sourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Fan Market |
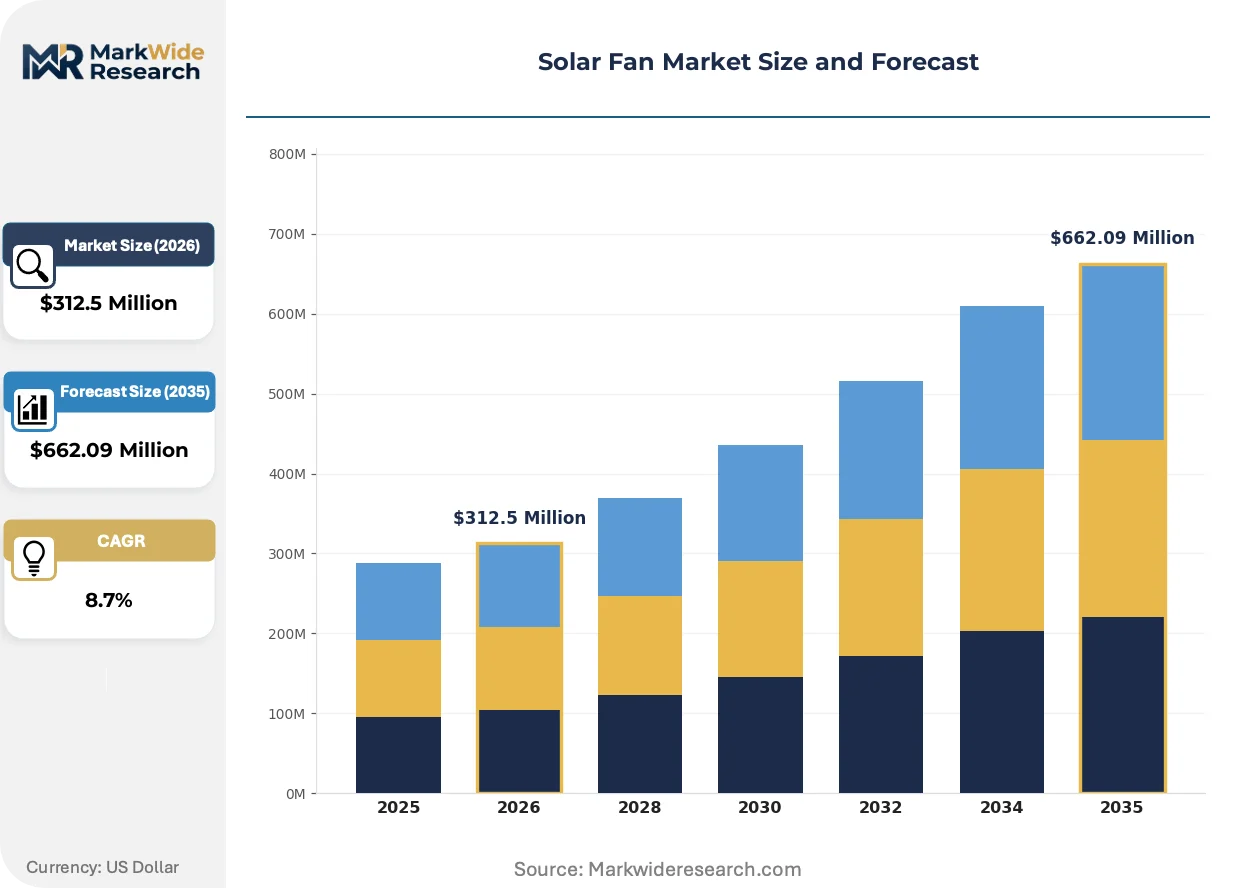
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceiling Fans, Table Fans, Wall-Mounted Fans, Exhaust Fans Technology: Photovoltaic Systems, Battery Storage Systems, Hybrid Systems, Direct Drive Systems End User: Residential, Commercial, Industrial, Outdoor Events Installation: Portable, Fixed, Roof-Mounted, Ground-Mounted |
| Companies Covered | Remington Solar, Broan-NuTone LLC, Natural Light Energy Systems, Attic Breeze LLC, Air Vent Inc., Solar Royal LLC, QuietCool, iLiving USA, Amtrak Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Fan Market Trends and Innovations
Product architecture is bifurcating between premium roof-integrated exhaust systems and commoditized portable units, with motor and controller electronics becoming the primary differentiation layer rather than panel specifications.
Monocrystalline PERC cells with passivated emitter rear contact technology are overtaking polycrystalline alternatives in solar fan applications. Agricultural processing facilities in Gujarat and Rajasthan adopt these higher-efficiency panels to maintain airflow during partial shading conditions. The technology is overtaking legacy configurations in commercial specifications where rooftop space constraints limit array sizing.
The EU F-Gas Regulation progressively restricts hydrofluorocarbon refrigerants in portable cooling equipment through 2030. Solar ventilation systems gain competitive positioning in supplemental cooling applications previously served by small compressor units. German and French distributors are expanding solar fan SKUs in building supply channels to capture this substitution demand.
Indian agricultural cooperatives are consolidating procurement of solar-powered ventilation for grain drying and dairy operations. Bulk purchasing agreements replace individual farmer transactions, shifting volume toward standardized 24V and 48V DC system configurations. This concentration is most visible in Punjab and Haryana, where farmer producer organizations coordinate equipment acquisition.
Solar Fan Market Segmentation
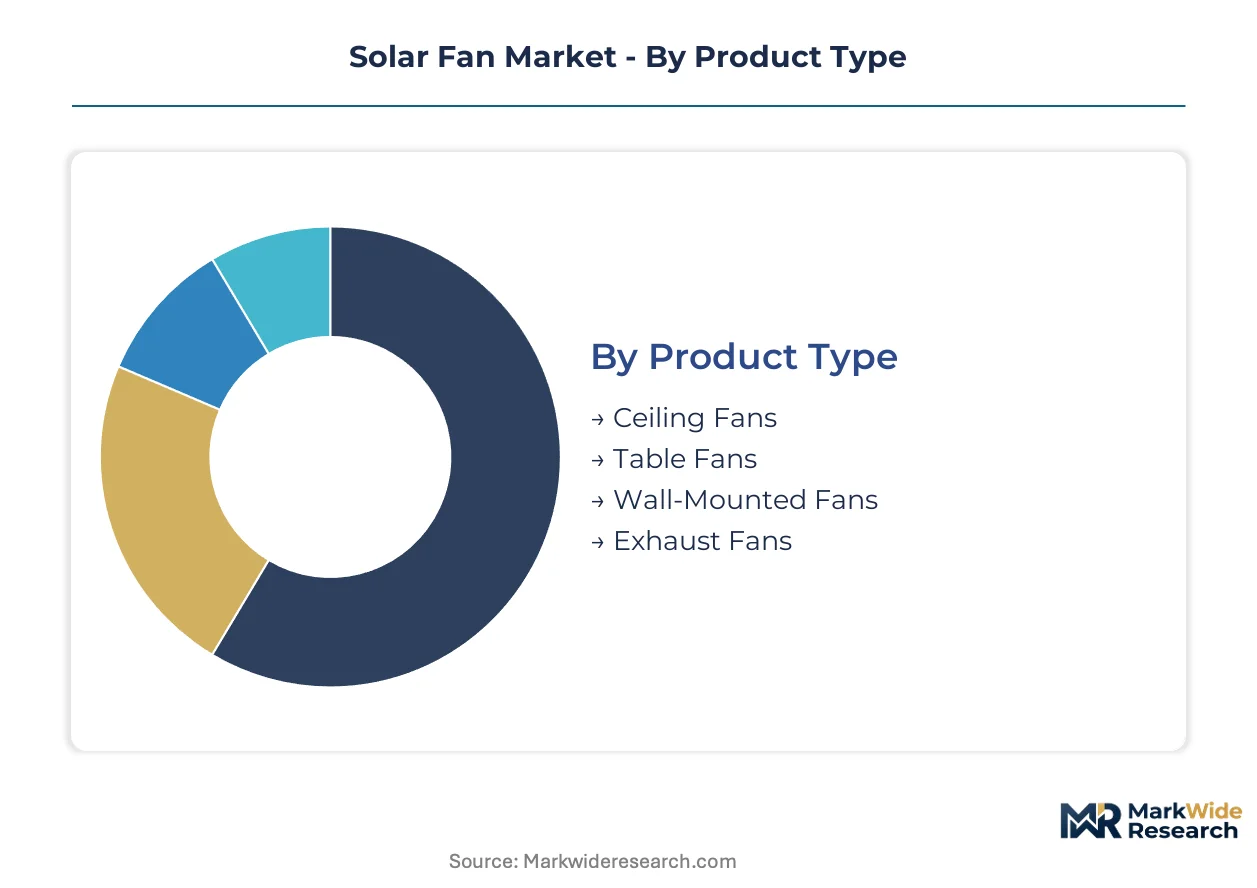
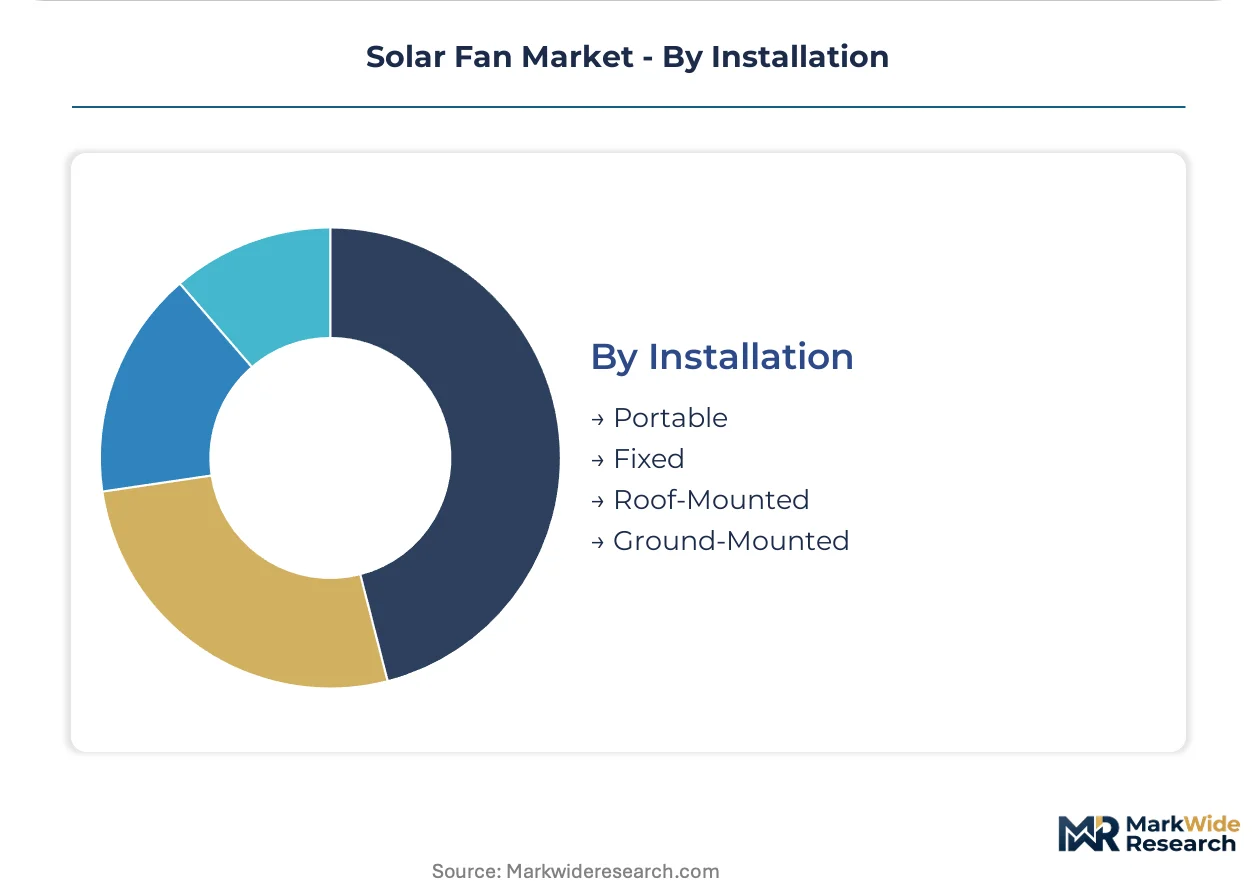
Solar fan manufacturers configure product portfolios around four distinct segmentation axes. Each category reflects divergent margin structures, certification requirements, and customer procurement behaviors that shape go-to-market strategy.
Product Type:
Standardization dominates at the low end while premium configurations demand structural integration expertise.
- Ceiling Fans:Direct-drive brushless DC motors power 48V and 24V configurations designed for continuous operation in tropical climates. Residential uptake concentrates in Indian states with unreliable grid infrastructure, where BIS certification requirements filter out uncertified imports.
- Exhaust Fans:Roof-mounted units incorporate weatherproof housings and variable-speed controllers that synchronize airflow with attic temperature sensors. Higher installed value reflects structural integration requirements and contractor labor, with demand clustering in North American residential retrofit channels seeking EPA Energy Star compliance.
- Table Fans:Portable 12V units with integrated photovoltaic panels serve emergency preparedness and outdoor recreation segments. Price competition intensifies in commoditized channels.
- Wall-Mounted Fans:Fixed-position designs target agricultural processing facilities in Gujarat and Rajasthan where wall mounting optimizes airflow patterns for grain drying operations.
Most installed capacity flows through Ceiling Fans. Expansion is steepest in Exhaust Fans.
Technology:
Cost tier stratification separates basic photovoltaic configurations from battery-augmented systems commanding premium pricing.
- Photovoltaic Systems:Monocrystalline PERC cells with passivated emitter rear contact technology deliver conversion efficiencies exceeding 20%. Southeast Asian foundry supply concentrates manufacturing cost advantages for volume producers.
- Battery Storage Systems:Lithium-ion storage extends operational hours through evening periods when thermal comfort demands persist. Commercial deployments in Indian agricultural processing facilities adopt these configurations to maintain ventilation during post-sunset operations.
- Hybrid Systems:Grid-tie capability with automatic switching between solar and AC power serves urban Indian markets with intermittent electricity supply.
- Direct Drive Systems:Elimination of belt transmissions reduces friction losses and maintenance requirements, penetrating commercial specifications where lifetime operating cost dominates procurement criteria.
Volume concentrates in Photovoltaic Systems. Battery Storage Systems are gaining structural share fastest.
End User:
Application maturity varies sharply across customer types, with industrial procurement consolidating through cooperatives while residential remains fragmented.
- Residential:Individual household purchases dominate sub-Saharan African electrification programs and Indian urban slum cooling initiatives. Development finance subsidies distort price sensitivity in rural channels.
- Commercial:Agricultural cooperatives in Punjab and Haryana consolidate procurement through farmer producer organizations, shifting volume toward standardized 24V and 48V DC configurations. Bulk purchasing agreements replace individual farmer transactions.
- Industrial:Grain drying and dairy ventilation specifications prioritize reliability and continuous operation, with procurement centralized through facility engineering departments.
- Outdoor Events:Rental and temporary deployment models serve festival and construction site markets with minimal installation requirements.
Commercial applications absorb the largest share of megawatt-scale deployments. Residential channels show the steepest volume trajectory.
Installation:
Customer type determines installation complexity, with portable units serving price-sensitive emergency channels while fixed configurations capture structural retrofit value.
- Portable:Self-contained units with integrated panels and battery packs target emergency preparedness and recreational markets. Low barriers to entry intensify price competition.
- Fixed:Permanent wall and ceiling mounting requires electrical integration and structural assessment, filtering procurement toward licensed contractors and certified installers.
- Roof-Mounted:Exhaust and ventilation configurations demand weatherproofing and load-bearing analysis, with installed value reflecting roofing contractor coordination and permitting timelines.
- Ground-Mounted:Agricultural and industrial deployments utilize dedicated array structures separate from building infrastructure, enabling optimal solar orientation independent of roof constraints.
Fixed installations carry the highest cumulative revenue. Ground-Mounted configurations are expanding most quickly in agricultural processing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The solar fan industry traces its commercial scaling to post-2000 rural electrification pilots in India, where off-grid cooling first demonstrated viable demand. Subsequent efficiency gains in monocrystalline photovoltaics and brushless DC motor architectures transformed localized experiments into exportable manufacturing platforms centered in South and Southeast Asia.
India
Agricultural cooperatives in Punjab and Haryana consolidate procurement of solar-powered ventilation systems for grain drying and dairy operations. The Central Electricity Authority mandates rooftop solar installations that accelerate DC-powered cooling adoption across Maharashtra and Tamil Nadu. Gujarat and Rajasthan processing facilities deploy monocrystalline PERC panels to maintain airflow during partial shading conditions.
United States
Residential retrofit channels drive demand for roof-mounted exhaust configurations with EPA Energy Star compliance. FERC interconnection standards and attic ventilation building codes shape product specifications for North American distribution. California and Texas housing markets concentrate installed value through contractor-coordinated structural integration and permitting workflows.
Germany
The EU F-Gas Regulation phase-down of hydrofluorocarbon refrigerants expands addressable markets for supplemental non-refrigerant cooling. German distributors expand solar fan SKUs in building supply channels to capture substitution demand from restricted portable compressor units. Bavaria and Baden-Württemberg industrial zones pilot solar ventilation for manufacturing facilities seeking Green Deal alignment.
Nigeria
Development finance targeting rural household energy access accelerates off-grid cooling hardware deployment across sub-Saharan electrification programs. Grid instability in Lagos and Kano drives informal settlement adoption of portable DC-powered units. Northern agricultural belts adopt wall-mounted configurations for crop drying operations independent of unreliable grid infrastructure.
Vietnam
Southeast Asian foundries supply monocrystalline photovoltaic cells that compress unit economics for solar fan manufacturers. Ho Chi Minh City and Hanoi industrial zones assemble brushless DC motors for export to Indian and African markets. The country's electronics manufacturing clusters capture value from panel sourcing concentration previously centered in China.
Solar Fan Market Competitive Landscape
The competitive structure tilts toward specialization-driven differentiation rather than scale consolidation. Mid-cap manufacturers dominate volume production while premium positioning accrues to ventilation specialists with certified distribution channels. Three archetypes define the field: attic ventilation specialists commanding residential retrofit premiums, diversified HVAC incumbents leveraging contractor networks, and emerging Asian fabricators optimizing for cost-sensitive agricultural procurement. Geographic expansion and technology licensing represent the dominant competitive moves, with players seeking regulatory arbitrage across EPA Energy Star, BIS, and CE marking jurisdictions.
Among North American ventilation specialists, Remington Solar and Broan-NuTone LLC exemplify divergent positioning strategies. Remington Solar occupies the attic ventilation archetype with premium residential retrofit focus, while Broan-NuTone LLC represents diversified HVAC channel control across big-box retail and contractor supply networks. QuietCool anchors the variable-speed DC motor integration tier, reducing phantom load during low-irradiance conditions. These three companies illustrate how motor and controller electronics have displaced panel specifications as the primary differentiation layer in product architecture.
| Leading Market Players |
|---|
| Remington Solar |
| Broan-NuTone LLC |
| Natural Light Energy Systems |
| Attic Breeze LLC |
| Air Vent Inc. |
| Solar Royal LLC |
| QuietCool |
| iLiving USA |
| Amtrak Solar |
| Others |
Pricing and Supply Chain Analysis
Monocrystalline silicon wafer spot indices cascade through Southeast Asian foundry pricing into three-tier cost structures separating roof-integrated exhaust systems from commoditized portable units. Indian agricultural cooperatives and North American residential retrofit channels absorb divergent margin pools as certification requirements filter procurement toward EPA Energy Star and BIS compliance tiers.
Pricing Analysis
Project-based installed value pricing dominates, with roof-mounted exhaust configurations commanding premiums over portable table units due to structural integration and contractor labor. Price differentiation rests on certification grade and volume scale, with BIS-certified ceiling fans filtering out uncertified imports in Indian channels. Cost compression in the portable tier intensifies as Southeast Asian manufacturers optimize for agricultural procurement. Emergency preparedness buyers exhibit highest price sensitivity, while commercial agricultural cooperatives prioritize lifetime operating cost over upfront expenditure.
Supply Chain Analysis
Refurbishment flows for brushless DC motors and lithium-ion battery packs remain underdeveloped, creating stranded value in early-generation deployments. Manufacturing concentrates in Vietnam, India, and China, with Vietnamese electronics clusters assembling motors for export to African and South Asian markets. Raw material dependencies center on monocrystalline silicon wafers, neodymium rare-earth magnets, and lithium carbonate. Single-source vulnerability in Southeast Asian foundry concentration exposes panel sourcing to tariff schedule disruption. Distribution runs through agricultural cooperatives in Punjab and Haryana, big-box retail in North America, and development finance channels in sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the EU F-Gas Regulation phase-down through 2030 systematically expanding addressable markets for non-refrigerant supplemental cooling.
For Market Incumbents: Deploy channel control levers to lock in contractor networks before emerging Asian fabricators achieve BIS certification. Deepen backward integration into brushless DC motor production to defend margin position against Vietnamese cost optimization. QuietCool's variable-speed architecture illustrates how controller electronics displace panel specifications as the primary differentiation layer. For New Entrants and Emerging Players: Agricultural cooperatives represent the most penetrable channel, with farmer producer organizations in Gujarat and Rajasthan consolidating procurement through standardized 24V and 48V configurations. Urban slum electrification in Indian megacities offers parallel white-space opportunity. A direct-to-cooperative go-to-market model bypasses fragmented individual farmer transactions. For Investors and Strategic Acquirers: Asymmetric upside sits with ventilation specialists possessing certified distribution across multiple regulatory jurisdictions. Long-term viability hinges on navigating simultaneous EPA Energy Star, BIS, and CE marking processes without launch bandwidth strain. The inflection signal to watch is lithium-ion battery chemistry standardization timelines extending product qualification cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | Simultaneous EPA Energy Star, BIS, and CE marking unlocks multi-jurisdiction revenue streams. |
| Backward Integration into Motor Production | In-house brushless DC manufacturing captures margin from Vietnamese assembly clusters. |
| Agricultural Cooperative Direct Sales | Bulk procurement agreements in Punjab and Haryana replace fragmented farmer transactions. |
| Variable-Speed Controller Development | MPPT-motor driver convergence reduces phantom load during low-irradiance conditions. |
| Battery Storage System Integration | Lithium-ion augmentation extends operational hours for Indian dairy and grain drying operations. |
Research Methodology
Multiple input streams — regulatory filing analysis, customs trade databases, and primary field engagement — were reconciled to construct segment-level demand estimates. Interviews with solar fan product managers, agricultural cooperative procurement heads, North American HVAC contractors, and Southeast Asian foundry operations specialists were cross-validated against Central Electricity Authority rooftop solar deployment records, EPA Energy Star certification listings, and EU F-Gas Regulation implementation timelines. Bottom-up unit shipment estimates and top-down addressable market sizing were triangulated to resolve variance.
Historical installation trajectories were cross-referenced against panelist input from distribution channel partners to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, technology configuration, end-user category, and installation method, with regional regulatory clusters treated as orthogonal demand shapers. CAGRs were derived from slope analysis of technology adoption curves and policy mandate implementation schedules, with monocrystalline efficiency improvement trajectories and battery cost decline curves incorporated as industry-specific inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to photovoltaic import tariff volatility and lithium-ion safety standard evolution. Forecasts reflect documented assumptions about rural electrification program funding continuity and F-Gas Regulation enforcement intensity. Practitioners should monitor CEA mandate expansion timelines and development finance disbursement patterns for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Global Air Cooled Condenser Market
Cooling Systems
Heat Pipe Market
Cooling Systems
Solar Refrigerators Market
Cooling Systems
Air to Air Heat Pumps Sales Market
Cooling Systems
Heat Pump Dryer Market
Cooling Systems
Aftercoolers Market
Cooling Systems
Solar Air Conditioning Market
Cooling Systems
Offshore Air Handling Units Market
Cooling Systems
Energy Storage Temperature Control Equipment Market
Cooling Systems
Cold Trap Market
Cooling Systems
Air Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Industrial Water Cooling System Market
Cooling Systems
Seawater Cooling System Market
Cooling Systems
Fluid Coolers Market
Cooling Systems
Process Chillers Market
Cooling Systems
Middle East and Africa Cooling Systems Market