
 Africa Natural Gas Market | 2026-2036
Africa Natural Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Natural Gas Market Outlook
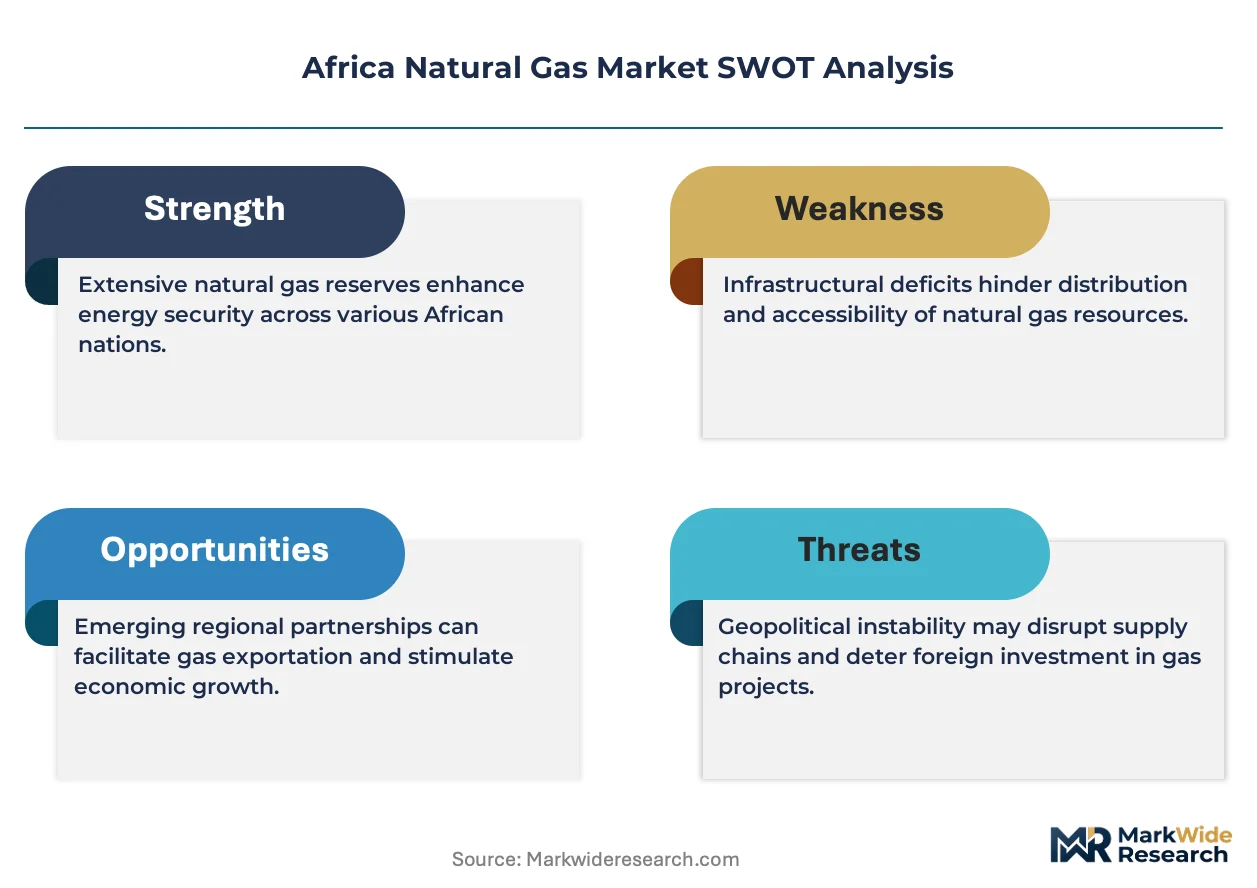
CE marking requirements for gas infrastructure equipment is consolidating procurement standards across North and West African import markets. Shell PLC leverages integrated LNG trading desks to sustain offtake flexibility across Egyptian and Nigerian terminals. Sonatrach anchors Maghreb supply through its pipeline network into Spain and Italy, while TotalEnergies SE competes for deepwater exploration blocks off Mozambique and South Africa.
Africa natural gas comprises hydrocarbon mixtures dominated by methane, often containing ethane, propane, and condensates extracted through conventional drilling, hydraulic fracturing, or associated recovery from oil fields; the resource serves power generation, industrial feedstock, and residential heating across a continent where grid electrification remains incomplete. Associated gas streams from oil operations in Nigeria and Angola still account for substantial flared volumes, yet monetization projects are redirecting this gas toward power generation and LNG export. Non-associated dry gas deposits in Algeria and Egypt dominate pipeline exports to Europe, while liquefaction technology investments in Mozambique and Tanzania target Asian spot markets. Pipelines remain the lowest-cost transmission mode for intra-African trade, though regasification terminals in Ghana and Senegal are expanding import options for nations without domestic reserves.
Nigeria's Petroleum Industry Act, Egypt's EGAS licensing framework, and South Africa's Petroleum Agency SA shape exploration incentives, local content mandates, and environmental compliance obligations across the continent's producing jurisdictions. Algeria's Sonatrach operates under MEE-equivalent environmental standards that govern flaring reduction and carbon intensity benchmarks for export eligibility. Stakeholders must weigh portfolio exposure across conventional pipeline plays, emerging LNG export hubs, and stranded gas monetization projects before committing capital to African upstream or midstream positions.
Market Dynamics
The Africa Natural Gas Market is being fundamentally restructured by the Petroleum Industry Act in Nigeria, which is redrawing fiscal terms and licensing frameworks to redirect upstream capital toward undeveloped reserves and away from mature basin decline.
Growth Catalysts
- Power generation displacement:East African utilities are expanding gas-fired capacity to replace diesel imports, creating anchored demand for pipeline-delivered supply.
- Associated gas monetization:Nigeria's flared gas capture regulations are redirecting previously wasted streams toward LNG export and domestic power generation.
- Rovuma Basin liquefaction:Mozambique's offshore development corridor is attracting midstream investment through long-term offtake structures tied to Asian spot market access.
Market Restraints
- Input cost volatility:Steel and specialized alloy prices for subsea infrastructure fluctuate with commodity cycles, compressing project returns during construction phases.
- Supply concentration risk:Algeria's Sonatrach dominates Maghreb pipeline exports into Europe, creating single-source dependency for Mediterranean buyers.
- Technical limitation:Deepwater pre-salt formations off South Africa require subsea processing technology with limited local service capacity.
Strategic Opportunities
- Underpenetrated geography:Tanzania's onshore Ruvuma Basin holds stranded gas reserves awaiting pipeline linkage to coastal liquefaction terminals.
- Regulatory tailwind:Egypt's EGAS licensing framework offers production-sharing terms that improve contractor economics for deepwater exploration blocks.
- Distribution innovation:Ghana and Senegal are deploying floating regasification units to create import options for nations without domestic reserves or pipeline interconnections.
Industry Challenges
- Specialized skill scarcity:Subsea engineering and LNG process operation expertise concentrates in Algeria and Nigeria, constraining project staffing in emerging basins.
- Capex intensity:Liquefaction trains and subsea production systems require multi-billion dollar commitments with decade-long payback horizons.
- Certification timelines:CE marking compliance for European-bound equipment adds procurement lead times that compress construction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Natural Gas Market |
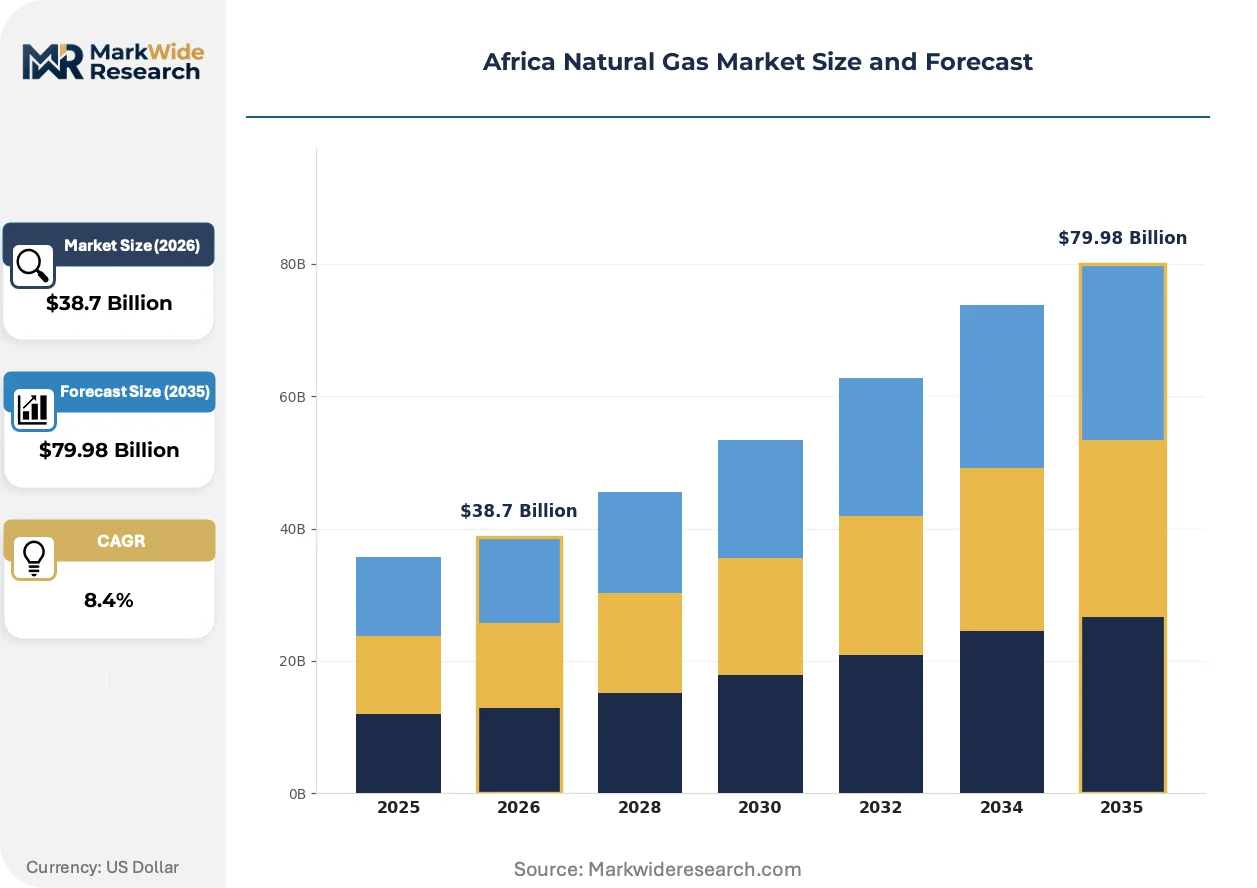
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Dry Gas, Wet Gas, Associated Gas, Non-Associated Gas End User: Power Generation, Industrial, Residential, Transportation Technology: Liquefaction, Regasification, Pipelines, Compression Application: Heating, Electricity Generation, Fuel Supply, Chemical Production |
| Companies Covered | NIPCO PLC, Egyptian Natural Gas Holding Company, Shell PLC, Nigerian National Petroleum Corporation, Eni SpA, Sonatrach, TotalEnergies SE, Chevron Corporation, PetroSA, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Natural Gas Market Strategic Shifts
Digital reservoir characterization and modular liquefaction designs are compressing development timelines across Africa's frontier basins, while carbon intensity benchmarks are reshaping export eligibility criteria for European-bound supply.
Floating LNG technology is converging with subsea production systems to unlock stranded offshore reserves without shore-based infrastructure. Supermajors operating Mozambique's Rovuma developments are deploying this pairing to accelerate first gas. The convergence is compressing capital deployment cycles from sanction to production.
Nigeria's Petroleum Industry Act is restructuring host government take and local content mandates for offshore licensing rounds. International operators must now navigate revised fiscal terms that alter project economics for deepwater exploration. Nigerian deepwater blocks are seeing renewed bidding activity as investors recalibrate under the new framework.
Industrial offtakers in Egypt and South Africa are consolidating procurement through long-term supply agreements rather than spot market exposure. This aggregation is displacing merchant trading structures that previously dominated African gas sales. Cement and fertilizer producers in the Suez Canal Economic Zone are pioneering this shift toward volume-commitment contracting.
Africa Natural Gas Market Segmentation
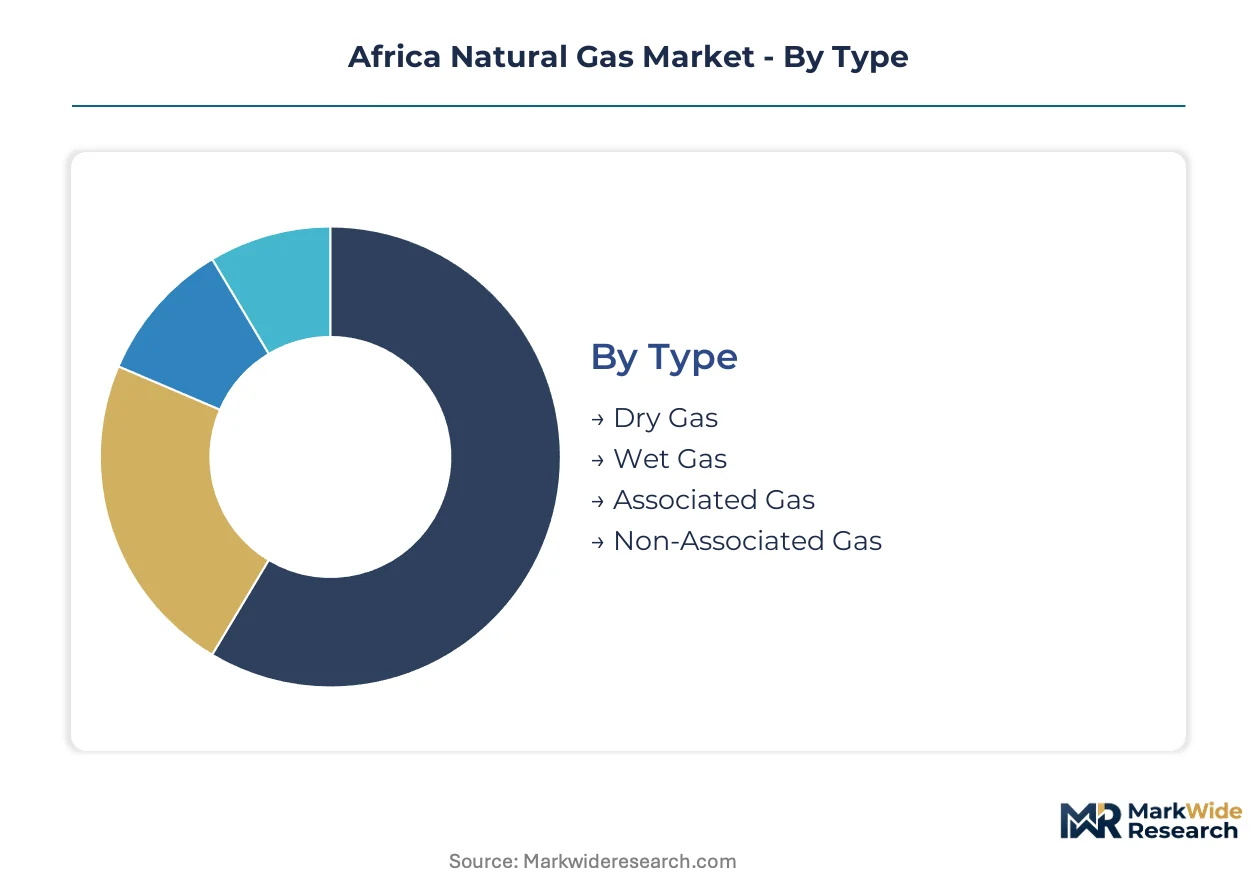
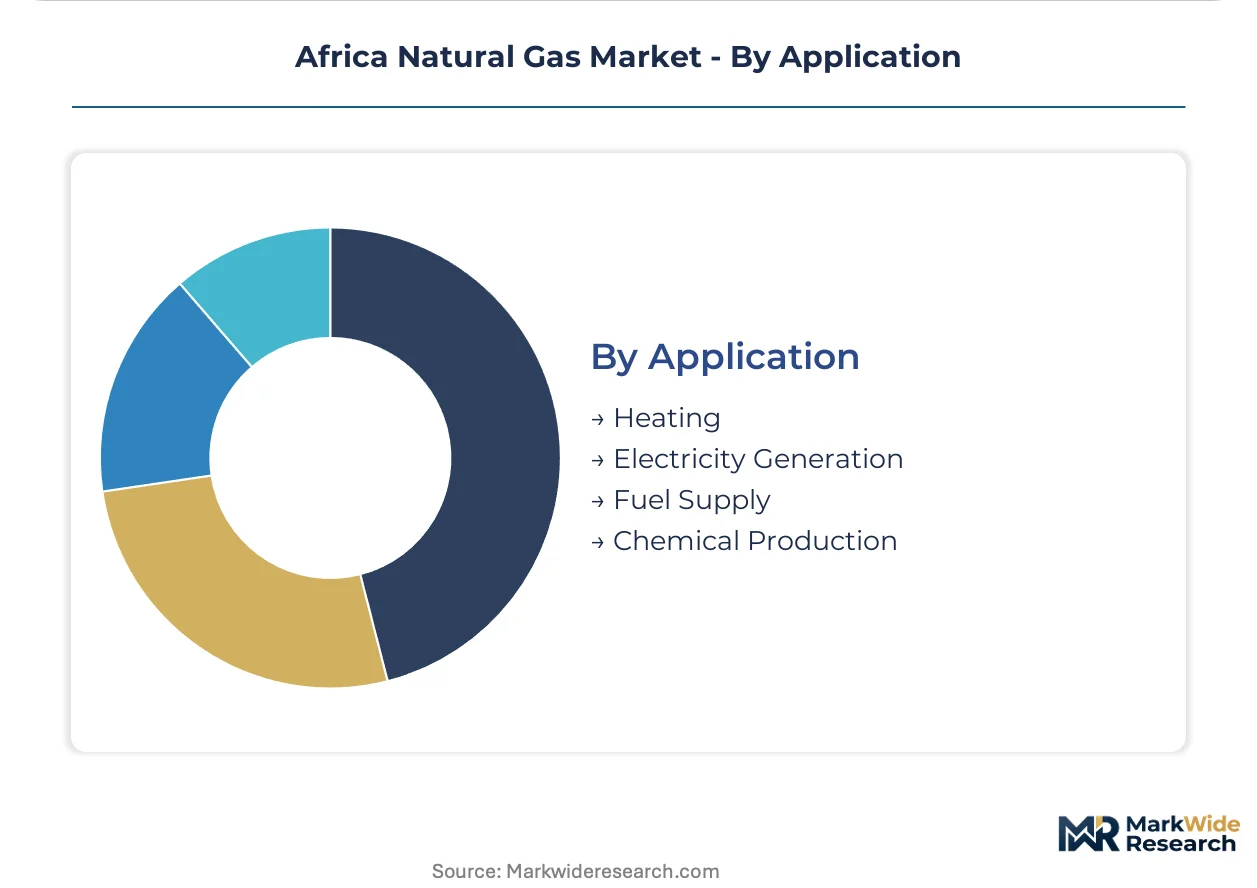
Gas type determines extraction economics and processing requirements across Africa's heterogeneous basins. End-use concentration shapes infrastructure investment priorities from Rovuma liquefaction to West African pipeline networks. Technology and application segments reveal where capital deployment faces the steepest constraints.
Type:
Reservoir chemistry dictates separation complexity and commercial pathway for each stream.
- Dry Gas:Methane-dominated composition requires minimal processing before pipeline injection or liquefaction. Algeria's Hassi R'Mel fields and Egypt's Zohr development anchor supply into European pipeline networks, with carbon intensity benchmarks now conditioning export eligibility under EU regulations.
- Wet Gas:Higher-order hydrocarbons necessitate fractionation facilities and NGL recovery systems. Nigeria's Niger Delta wet gas streams feed domestic petrochemical feedstock demand while residual methane enters LNG export trains, though liquids extraction economics fluctuate with global NGL pricing.
- Associated Gas:Co-produced with crude oil operations and historically flared in Nigeria and Angola. Flare gas capture regulations are redirecting these volumes toward power generation and small-scale LNG, compressing waste volumes while extending field economic life.
- Non-Associated Gas:Pure gas reservoirs requiring dedicated development without oil revenue cross-subsidy. Mozambique's Rovuma Basin non-associated deposits underpin major liquefaction investments targeting Asian spot market offtake.
Dry gas leads volumes today; wet gas is gaining share fastest as NGL recovery economics improve.
End User:
Customer scale and delivery reliability requirements split procurement patterns across the value chain.
- Power Generation:Baseload electricity producers anchor demand through long-term take-or-pay contracts. East African utilities expanding gas-fired capacity displace diesel imports while Nigerian independent power producers absorb domestic gas allocations under Petroleum Industry Act local content mandates.
- Industrial:Cement, fertilizer, and steel producers require uninterrupted supply for continuous process operations. Egyptian industrial offtakers in the Suez Canal Economic Zone are consolidating procurement through volume-commitment contracts rather than spot exposure.
- Residential:Grid-connected households and LPG cylinder distribution networks serve cooking and heating demand. Urbanization in West African coastal cities is expanding piped natural gas distribution where infrastructure permits.
- Transportation:Compressed natural gas for heavy-duty trucking and marine bunkering remains nascent. Senegal and Ghana pilot CNG conversion programs for public transit fleets to reduce diesel import dependency.
Power generation commands the largest volume share; industrial offtake is climbing the fastest as manufacturing capacity expands.
Technology:
Capital intensity and operational flexibility tradeoffs differentiate midstream investment profiles.
- Liquefaction:Cryogenic cooling to -162°C enables intercontinental trade through specialized carriers. Modular train designs are compressing development timelines for Mozambique's offshore developments while floating LNG unlocks stranded reserves without shore infrastructure.
- Regasification:Floating storage and regasification units provide import capability for nations lacking domestic reserves. Ghana and Senegal deploy FSRUs to access global LNG supply without pipeline interconnection to producing basins.
- Pipelines:Lowest-cost transmission mode for continental trade when geography permits. Sonatrach's Maghreb-Europe pipeline dominates North African export capacity while West African backbone networks remain fragmented across national boundaries.
- Compression:Essential for maintaining flow rates across long-distance transmission and for CNG vehicle fueling. Subsea compression technology for deepwater pre-salt formations off South Africa requires specialized service capacity with limited local availability.
Pipelines handle the greatest throughput today; regasification is expanding most quickly as import-dependent nations diversify supply.
Application:
Final use case determines burner specification, emissions profile, and substitution economics.
- Heating:Direct combustion for residential, commercial, and industrial thermal demand. Seasonal load variation in North African markets creates storage and swing supply requirements distinct from baseload power applications.
- Electricity Generation:Combined-cycle gas turbines deliver the dominant share of gas-fired kilowatt-hours. Grid reliability constraints in Sub-Saharan markets favor gas turbine ramping capability over coal baseload alternatives.
- Fuel Supply:Process heat and mechanical drive for extraction, refining, and manufacturing operations. Mining sector demand in South Africa's platinum belt and Zambia's copperbelt anchors regional pipeline proposals.
- Chemical Production:Feedstock for ammonia, methanol, and hydrogen manufacturing. Egyptian fertilizer producers leverage Suez Canal proximity for export-oriented petrochemical integration.
Electricity generation dominates current offtake; chemical production shows the steepest expansion trajectory as feedstock integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Algeria's Hassi R'Mel field established the continent's first major gas export infrastructure in 1961, creating a template later replicated across Nigeria, Egypt, and Mozambique. Pipeline networks and liquefaction terminals now concentrate investment around proven basins with European and Asian market access.
Algeria
Europe-bound pipeline exports through the Trans-Mediterranean and Maghreb-Europe lines anchor national revenue. Sonatrach operates under MEE-equivalent environmental standards governing flaring reduction and carbon intensity benchmarks. Hassi R'Mel and associated fields in the Sahara maintain throughput into Italy and Spain despite infrastructure aging.
Nigeria
Associated gas capture from Niger Delta oil operations feeds domestic power generation and Bonny Island LNG exports. The Petroleum Industry Act restructures fiscal terms and local content mandates for offshore licensing rounds. Lagos-anchored independent power producers absorb domestic gas allocations under revised local content requirements.
Egypt
Zohr field development and Mediterranean deepwater exploration sustain pipeline and LNG export capacity. EGAS licensing framework offers production-sharing terms improving contractor economics for deepwater blocks. Suez Canal Economic Zone industrial clusters consolidate procurement through long-term supply agreements.
Mozambique
Rovuma Basin non-associated deposits underpin major liquefaction investments targeting Asian spot markets. Floating LNG paired with subsea production systems accelerates first gas without shore-based infrastructure. Cabo Delgado province development corridors attract midstream investment through long-term offtake structures.
South Africa
Deepwater pre-salt formations require subsea processing technology with limited local service capacity. Petroleum Agency SA shapes exploration incentives and environmental compliance obligations for frontier blocks. KwaZulu-Natal and Eastern Cape coastal zones host import terminal proposals for LNG regasification.
Africa Natural Gas Market Competitive Environment
The competitive structure tilts toward integrated national oil companies with pipeline and liquefaction asset control. International oil majors compete for exploration access through production-sharing contracts, while specialized midstream operators concentrate on regasification and distribution infrastructure. Two strategic archetypes dominate: state-backed incumbents with legacy infrastructure and supermajors deploying capital-intensive liquefaction technology. Competitive moves center on portfolio diversification into low-carbon gas solutions and strategic partnerships for frontier basin access.
Within the state-backed tier, Sonatrach and Nigerian National Petroleum Corporation anchor Maghreb and West African supply respectively. Shell PLC represents the integrated supermajor archetype competing for deepwater exploration blocks, while TotalEnergies SE occupies a comparable position in Rovuma Basin developments. Egyptian Natural Gas Holding Company exemplifies the national gas monopoly model with integrated upstream and midstream control.
| Leading Market Players |
|---|
| NIPCO PLC |
| Egyptian Natural Gas Holding Company |
| Shell PLC |
| Nigerian National Petroleum Corporation |
| Eni SpA |
| Sonatrach |
| TotalEnergies SE |
| Chevron Corporation |
| PetroSA |
| Others |
Value Chain & Pricing Dynamics
Steel price indices for subsea pipeline alloys and liquefaction-grade nickel cascade through procurement tiers, compressing project returns during construction phases while elevating long-term offtake contract premiums for buyers seeking supply certainty.
Pricing Analysis
Long-term take-or-pay contracting dominates African gas transactions, with price differentiation anchored in volume commitment scale and carbon intensity certification grade. Premium tiers command higher rates for supply with verified low-methane leakage and EU-compliant carbon benchmarks, while economy tiers serve domestic power utilities with less stringent environmental riders. Pricing pressure stems from steel and specialized alloy cost volatility in subsea infrastructure, squeezing developer margins. Industrial offtakers in Egypt's Suez Canal Economic Zone exhibit lowest price sensitivity due to process continuity requirements, whereas West African independent power producers face acute budget constraints.
Supply Chain Analysis
Dual-sourcing mandates from European offtakers and Asian LNG buyers require developers to qualify multiple subsea engineering contractors and liquefaction module fabricators, fragmenting procurement across South Korea, Japan, and Italy. Critical inputs include cryogenic heat exchangers, subsea Christmas trees, and specialized pipeline coatings. Supply chain risk concentrates in single-source dependency for deepwater pre-salt subsea processing technology, where limited local service capacity in South Africa and Mozambique extends mobilization timelines. Distribution runs through Sonatrach's Maghreb-Europe pipeline network for North African dry gas, while floating regasification units serve import-dependent West African markets without domestic reserves.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in African natural gas rests on modular liquefaction designs compressing capital deployment cycles and carbon-intensity premiums opening price arbitrage for certified low-leakage supply into European markets.
For Market Incumbents: Deploy flare gas capture infrastructure to monetize previously wasted associated gas streams from mature Niger Delta fields, while securing long-term offtake positions in Tanzania's stranded Ruvuma reserves before pipeline linkage matures. Shell PLC and TotalEnergies SE face displacement risk from Sonatrach's pipeline dominance in European supply, requiring carbon certification investment to defend premium tier positioning. For New Entrants and Emerging Players: The 40-60% price-point gap between Asian spot-indexed LNG and domestic African power utility tariffs creates entry space for small-scale LNG developers targeting captive industrial demand in Ghana and Senegal. Floating regasification unit deployment offers the most penetrable infrastructure segment, with go-to-market leverage through direct supply agreements with cement and fertilizer producers bypassing national utility intermediaries. For Investors and Strategic Acquirers: Asymmetric upside sits with midstream operators controlling floating LNG and subsea production system technology applicable across multiple frontier basins. Long-term viability favors positions in Mozambique's Rovuma corridor and Tanzania's onshore Ruvuma linkage projects, with inflection signaled by final investment decision timelines for Train 3 expansions and pipeline interconnect agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Associated Gas Monetization Infrastructure | Flare capture regulations in Nigeria redirect waste streams toward LNG export and domestic power generation. |
| Floating LNG Technology Deployment | Offshore liquefaction paired with subsea systems accelerates first gas without shore-based infrastructure in Mozambique. |
| Carbon Intensity Certification Program | EU methane performance standards condition export eligibility for Algerian and Egyptian pipeline supply. |
| Long-term Industrial Offtake Agreements | Suez Canal Economic Zone cement and fertilizer producers consolidate procurement through volume-commitment contracts. |
| Regional Pipeline Interconnection | West African backbone network fragmentation constrains intra-continental trade despite lowest-cost transmission economics. |
Study Parameters
Bottom-up power generation and industrial offtake modeling reconciled against top-down liquefaction capacity and pipeline throughput tracking forms the analytical core. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists combine with secondary validation from EIA data, IEA reports, FERC filings, and African project development databases. Triangulation across stakeholder inputs and documented infrastructure commitments ensures volume and value estimates reflect ground-level contracting activity.
Historical trendline analysis of capacity additions, offtake contract signings, and regulatory milestone achievements informs the projection framework. Segmentation dimensions span gas type chemistry, end-user scale, technology capital intensity, and regional regulatory framework variations across the modeling period. CAGRs derive from fitted growth curves adjusted for project sanction-to-production timelines and carbon intensity benchmark implementation trajectories.
Caveats apply where Petroleum Industry Act implementation delays, Cabo Delgado security conditions, or EU carbon border adjustment mechanisms could materially shift the outlook. Deviation in Asian spot LNG price volatility or European pipeline import policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
APAC Oil and Gas Automation Market
Oil & Gas
Microbial Enhanced Oil Recovery Market
Oil & Gas
Argentina Oil and Gas Upstream Market
Oil & Gas
United States Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Drilling Fluids Market
Oil & Gas
Asia-Pacific LNG Bunkering Market
Oil & Gas
Russian Federation Oil and Gas Downstream Market
Oil & Gas
Asia- Pacific Drilling Market
Oil & Gas
Iran Oil and Gas Market
Oil & Gas
Whipstocks Market
Oil & Gas
Digital Twin in Oil and Gas Market
Oil & Gas
Saudi Arabia Oil and Gas Midstream Market
Oil & Gas
Sidetracking Market
Oil & Gas
Small Scale LNG Terminal Market
Oil & Gas
Oil and Gas Fittings Market