
 Denmark Solar Energy Market | 2026-2036
Denmark Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Solar Energy Market Outlook
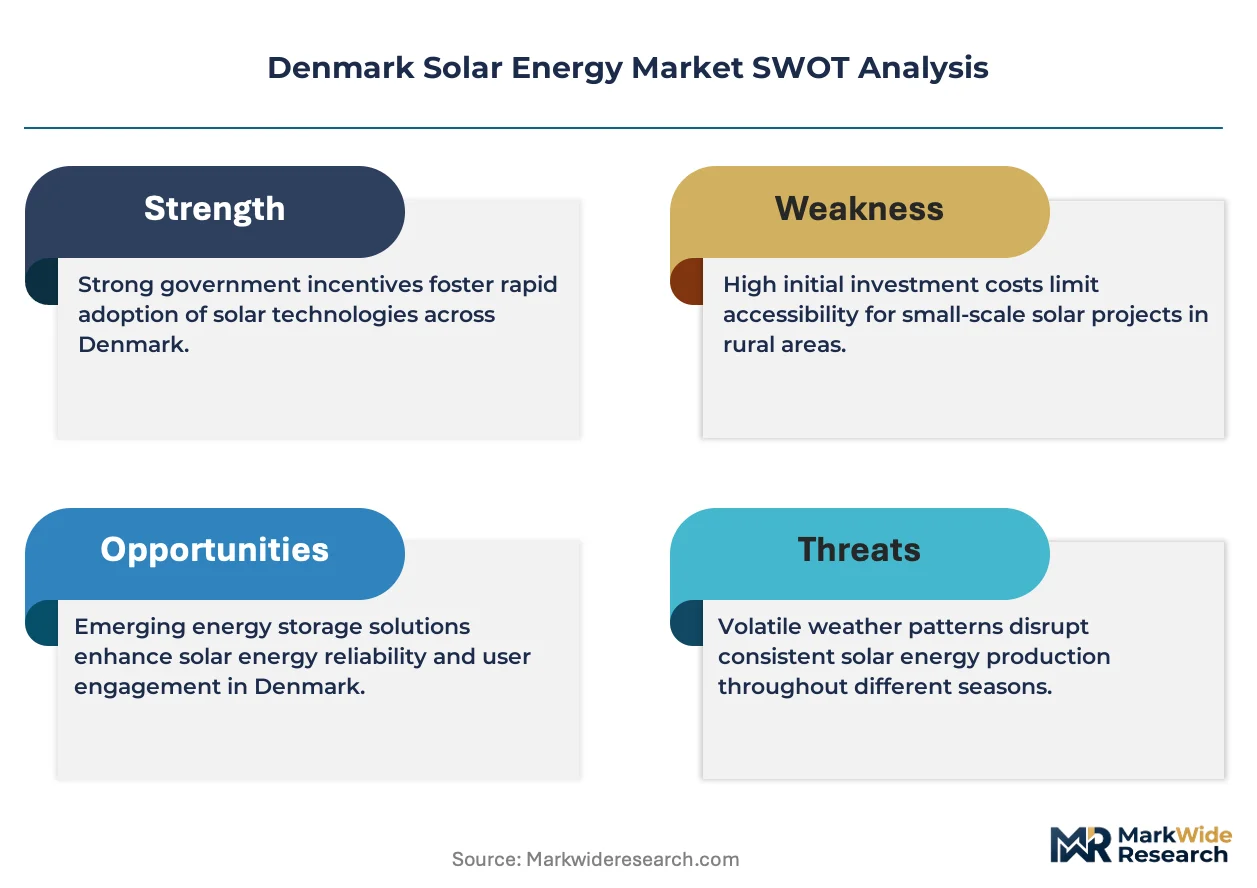
Aftermarket service revenue is narrowing as Danish developers internalize operations and maintenance capabilities. Ørsted A/S leverages its offshore engineering heritage to dominate utility-scale project development. Better Energy A/S sustains a pure-play solar model focused on merchant and contracted capacity across Denmark. European Energy A/S anchors its growth through integrated development, construction, and asset management functions.
Denmark solar energy encompasses photovoltaic systems that convert sunlight into direct current electricity through silicon-based semiconductor junctions, typically operating at 15-22% module efficiency under standard test conditions, then feeding into Denmark's high-voltage alternating current grid or local district heating networks. Photovoltaic systems lead installed capacity as crystalline silicon modules achieve cost parity with onshore wind in Danish auctions. Solar thermal collectors retain niche relevance for district heating integration where seasonal storage projects in Silkeborg and Marstal demonstrate multi-megawatt thermal scale. Power purchase agreements represent the fastest-growing financing model as corporate offtakers from pharmaceutical and logistics sectors seek fixed-price renewable supply.
Danish Energy Agency permitting frameworks shape project timelines through streamlined one-stop approval processes for installations below specific capacity thresholds. The country's building codes administered by the Danish Transport, Construction and Housing Authority mandate solar readiness standards for new commercial structures. EU Green Deal alignment pressures through CSRD disclosure requirements force developers to document supply chain emissions and circularity protocols. Stakeholders must monitor forthcoming offshore solar pilot allocations in the Kattegat and North Sea zones where seabed leasing terms will reshape competitive dynamics.
Market Dynamics
Denmark's 2023 climate agreement has compressed utility-scale solar deployment timelines, forcing developers to accelerate grid connection studies while Danish Energy Agency permitting reforms eliminate redundant municipal approvals for ground-mounted arrays above 1 MW capacity.
Growth Catalysts
- Agri-PV land leasing:Jutland agricultural cooperatives lease marginal acreage to developers, converting low-yield farmland into dual-use solar parks with grazing integration.
- EU Green Deal CSRD alignment:Corporate sustainability reporting mandates drive pharmaceutical and logistics offtakers into power purchase agreements for emissions disclosure compliance.
- Crystalline silicon cost parity:Module efficiency gains at 20-22% under Danish irradiance conditions now match onshore wind levelized costs in Energinet auction rounds.
Market Restraints
- Grid connection queuing:Energinet's high-voltage substation capacity constraints in western Jutland delay commercial operation dates by 18-24 months for projects exceeding 50 MW.
- Polysilicon supply concentration:Danish developers remain exposed to Xinjiang-sourced wafer supply chains despite EU forced labor due diligence proposals.
- Seasonal generation mismatch:December irradiance at 0.5 kWh/m²/day forces thermal storage or import dependency during heating demand peaks.
Strategic Opportunities
- Kattegat offshore solar pilots:Danish Energy Agency seabed leasing terms for floating photovoltaic arrays will unlock capacity multipliers beyond land-constrained eastern Denmark.
- District heating integration:Silkeborg and Marstal seasonal thermal storage projects demonstrate multi-megawatt scale for agricultural process heat offtake.
- Building-integrated photovoltaics:Danish Transport, Construction and Housing Authority solar readiness codes for new commercial structures mandate rooftop pre-wiring standards.
Industry Challenges
- Skilled electrician scarcity:Installation crews for high-voltage DC-to-AC conversion and transformer commissioning face recruitment gaps as project pipelines expand.
- Circular module recycling:EU Waste Electrical and Electronic Equipment directive compliance requires developers to document end-of-life material recovery pathways for crystalline silicon panels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Solar Energy Market |
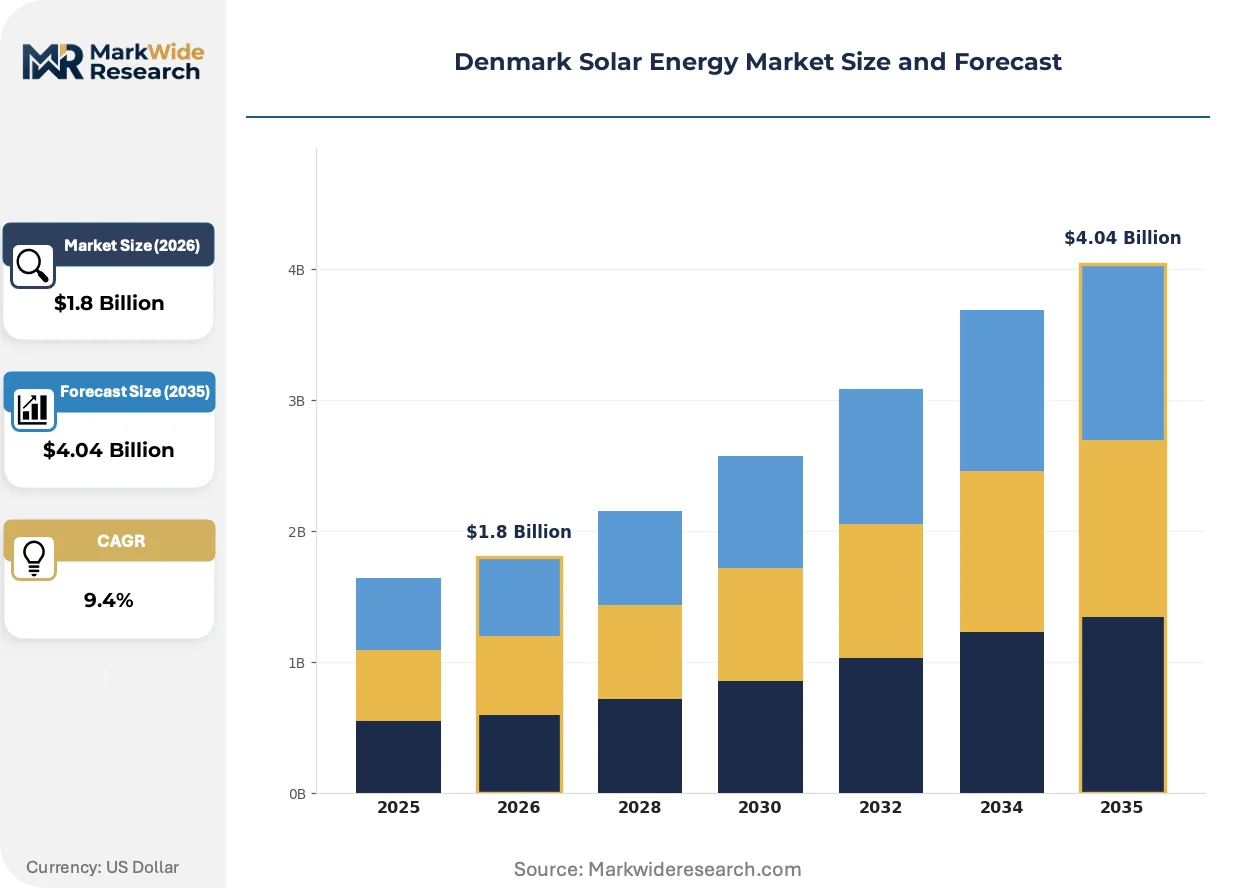
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Systems, Solar Thermal Collectors, Concentrated Solar Power, Hybrid Systems Installation Type: Residential, Commercial, Utility-Scale, Off-Grid End User: Households, Businesses, Government Institutions, Non-Profits Financing Model: Energy-as-a-Service, Power Purchase Agreements, Direct Purchase, Leasing |
| Companies Covered | Arcon-Sunmark A/S, RWE Renewables Denmark, Vestas Wind Systems A/S, Vattenfall A/S, Copenhagen Infrastructure Partners, Ørsted A/S, European Energy A/S, Ennogie Solar Group A/S, Better Energy A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Solar Energy Market Strategic Shifts
Technology convergence and procurement model evolution are restructuring how Danish solar capacity reaches financial close, with hybrid system architectures and corporate offtaker preferences displacing traditional utility ownership structures.
Bifacial photovoltaic modules with tracking systems is hybridizing project economics in Denmark's agricultural zones. Danish developers deploy east-west single-axis trackers on Jutland dairy farms to flatten midday generation peaks and extend morning-evening output. This architecture is hybridizing merchant revenue exposure with contracted floor pricing in corporate power purchase agreements.
Danish Energy Agency one-stop permitting reforms eliminate municipal veto rights for ground-mounted installations below 150 MW, collapsing approval timelines from 24 months to 8 months. Industrial consequence includes accelerated financial close velocity for utility-scale pipelines. Western Jutland municipalities with pre-approved zoning maps capture disproportionate project origination volumes.
Corporate offtakers from Novo Nordisk and Maersk logistics subsidiaries now mandate 15-20 year fixed-price contracts with escalation clauses rather than merchant exposure. Danish renewable energy auctions see developer bids compressing equity returns to secure contracted revenue visibility. This behavioral pivot concentrates origination capability with integrated developers possessing balance sheet capacity for long-dated power purchase agreement warehousing.
Denmark Solar Energy Market Segmentation
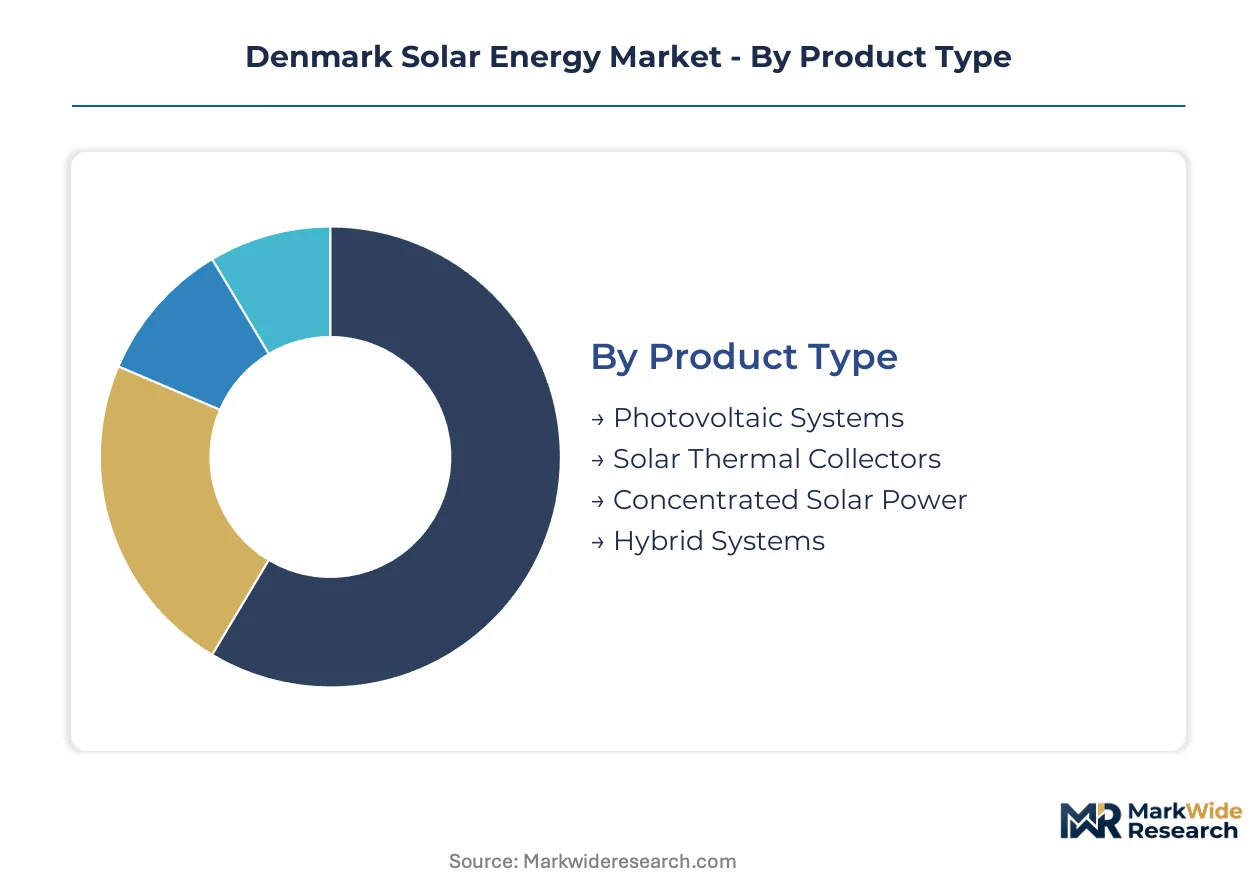
Segmentation of Denmark's solar energy market reveals how crystalline silicon photovoltaic systems dominate procurement while emerging thermal and hybrid architectures carve distinct operational niches. Understanding these partitions clarifies where Energinet grid capacity constraints bite hardest and which financing structures accelerate project velocity.
Product Type:
Mature crystalline technologies anchor Danish deployment volumes while emerging thermal and concentrated architectures occupy specialized integration roles.
- Photovoltaic Systems:Crystalline silicon modules operating at 20-22% efficiency under Danish irradiance conditions constitute the primary installed capacity base. Danish utilities and district heating cooperatives concentrate procurement in Jutland's agricultural regions where landowners lease acreage for utility-scale parks.
- Solar Thermal Collectors:Flat-plate and evacuated tube systems convert sunlight directly to thermal energy for district heating integration. Silkeborg and Marstal seasonal storage projects demonstrate multi-megawatt thermal scale where agricultural process heat offtake drives niche demand.
- Concentrated Solar Power:Parabolic trough and power tower configurations using molten salt storage remain experimental in Denmark's low-direct-normal-irradiance climate. Pilot installations test feasibility for industrial process heat applications.
- Hybrid Systems:Photovoltaic-thermal combinations and battery-coupled solar generation pair generation assets with flexibility services. Bifacial modules with east-west tracking on Jutland dairy farms flatten midday peaks and extend morning-evening output.
Photovoltaic Systems handles the majority of throughput; Hybrid Systems is the fastest mover on share.
Installation Type:
Cost tier differentiation separates subsidized residential rooftops from merchant-exposed utility-scale developments competing at Energinet auction price floors.
- Utility-Scale:Ground-mounted arrays exceeding 1 MW capacity deploy across western Jutland's pre-approved municipal zoning maps. Danish Energy Agency permitting reforms collapsed approval timelines from 24 months to 8 months for these installations.
- Commercial:Rooftop and carport installations on logistics centers, pharmaceutical manufacturing facilities, and retail distribution hubs. Danish Transport, Construction and Housing Authority solar readiness codes mandate pre-wiring standards for new commercial structures.
- Residential:Distributed rooftop systems on single-family homes and multi-unit dwellings. Net metering frameworks and building-integrated photovoltaics integration drive household adoption in Copenhagen and Aarhus metropolitan zones.
- Off-Grid:Standalone systems for remote agricultural operations, island communities, and backup power applications. Bornholm and other Danish islands deploy islanded microgrids with battery storage.
Utility-Scale captures the dominant share of new capacity additions; Commercial installations are expanding most quickly as corporate offtakers from Novo Nordisk and Maersk subsidiaries mandate fixed-price contracts.
End User:
Customer type determines contract structure complexity, with institutional procurement favoring long-dated power purchase agreements and household segments relying on simpler leasing arrangements.
- Businesses:Pharmaceutical manufacturers, logistics operators, and food processing facilities procure renewable supply for EU CSRD emissions disclosure compliance. Corporate offtakers now mandate 15-20 year fixed-price contracts with escalation clauses rather than merchant exposure.
- Households:Residential consumers in suburban Copenhagen, Aarhus, and Odense municipalities adopt rooftop systems through net metering and tax incentive structures. Installation crews for high-voltage DC-to-AC conversion face recruitment gaps as residential pipelines expand.
- Government Institutions:Municipal buildings, schools, and administrative facilities procure solar through public tender frameworks. Danish Energy Agency streamlined one-stop approval processes accelerate public sector deployment timelines.
- Non-Profits:Agricultural cooperatives, housing associations, and community energy groups develop collective ownership models. Jutland agricultural cooperatives lease marginal acreage to developers, converting low-yield farmland into dual-use solar parks with grazing integration.
Businesses command the largest aggregate demand volume; Non-Profits are gaining share fastest through cooperative ownership structures.
Financing Model:
Margin structures diverge sharply between capital-intensive direct ownership and service-based arrangements where developers retain operational risk.
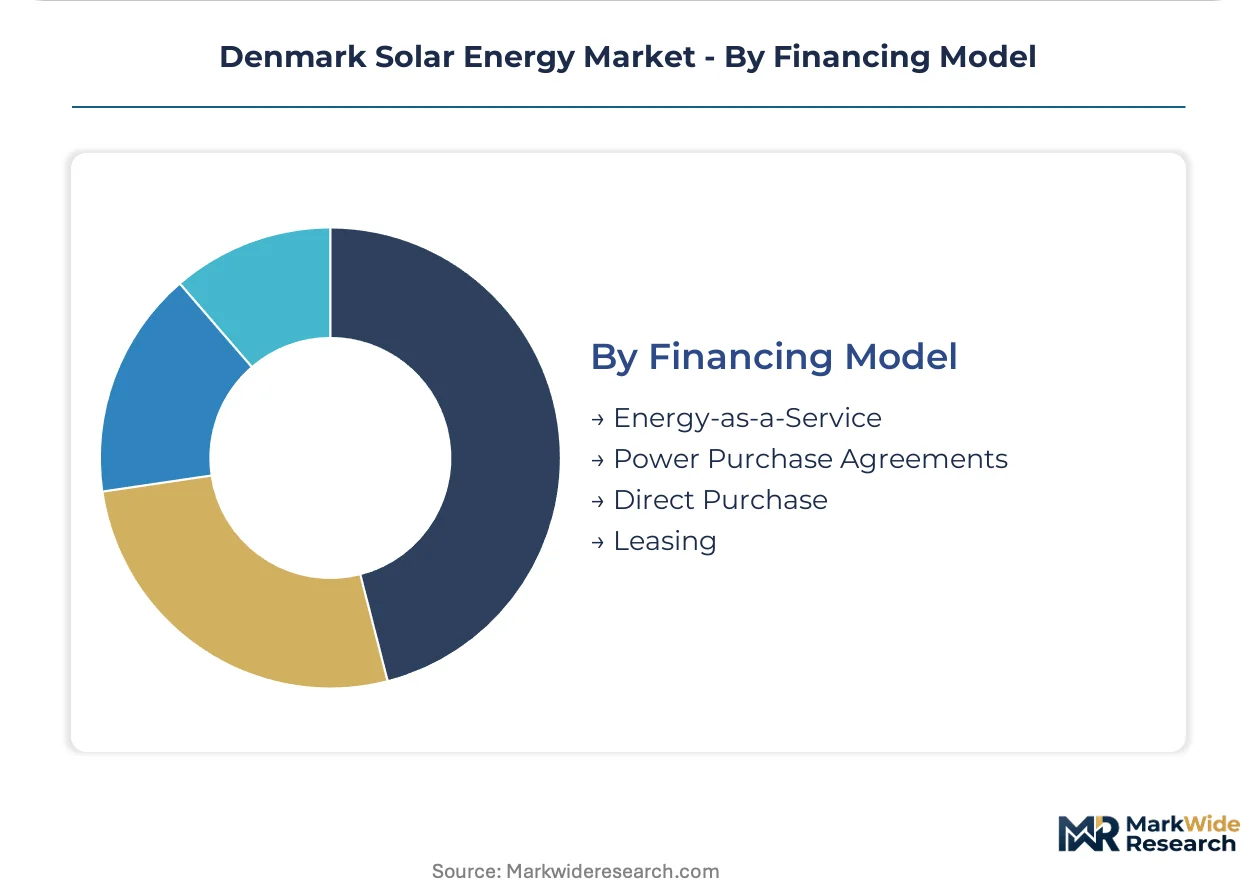
- Power Purchase Agreements:Long-term fixed-price contracts between developers and corporate offtakers transfer price risk while providing revenue visibility. Danish renewable energy auctions see developer bids compressing equity returns to secure contracted revenue visibility.
- Energy-as-a-Service:Developers retain asset ownership and operational responsibility while customers pay for delivered energy. Ørsted A/S and Better Energy A/S deploy this model to warehouse long-dated contract portfolios on their balance sheets.
- Direct Purchase:Asset ownership by end-users through upfront capital expenditure or debt financing. Large industrial offtakers with investment-grade credit ratings favor this structure for maximum lifetime cost control.
- Leasing:Third-party ownership arrangements where households or small businesses pay monthly fees without capital outlay. Simplified customer acquisition and standardized system designs characterize this mass-market segment.
Power Purchase Agreements handle the majority of new project finance volume; Energy-as-a-Service is climbing the fastest as integrated developers deepen balance sheet deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Jutland landowners exhibit the lowest price elasticity for solar leasing, accepting below-market rates for dual-use grazing integration, while Copenhagen metropolitan commercial offtakers demand steep contract discounts to offset grid connection premiums.
North Jutland
Pre-approved municipal zoning maps in Hjørring and Frederikshavn compress permitting timelines to eight months under Danish Energy Agency reforms. EU Green Deal CSRD disclosure requirements drive pharmaceutical logistics operators toward power purchase agreements. Hirtshals port cluster hosts merchant solar development targeting industrial process heat offtake.
Mid Jutland
Silkeborg seasonal thermal storage projects demonstrate multi-megawatt scale for agricultural process heat integration. Danish Transport, Construction and Housing Authority solar readiness codes accelerate commercial rooftop deployment. Aarhus metropolitan construction permits mandate pre-wiring standards for new logistics facilities.
South Jutland
Esbjerg offshore engineering heritage attracts floating photovoltaic pilot allocations in adjacent North Sea zones. Energinet substation capacity constraints delay 50 MW-plus projects by 18-24 months. Ribe agricultural cooperatives convert marginal dairy pasture to bifacial tracker installations with east-west generation flattening.
Zealand
Copenhagen corporate headquarters procurement from Novo Nordisk and Maersk subsidiaries mandates 15-20 year fixed-price contracts with escalation clauses. Danish Energy Agency one-stop permitting eliminates redundant municipal approvals for ground-mounted arrays above 1 MW. Roskilde logistics hubs deploy carport solar to satisfy CSRD emissions disclosure compliance.
Funen
Odense manufacturing facilities integrate building-photovoltaics under 2023 climate agreement capacity targets. District heating cooperatives test hybrid photovoltaic-thermal combinations for seasonal storage. Svendborg port industrial zone captures disproportionate project origination through streamlined grid connection studies.
Denmark Solar Energy Market Competitive Environment
Capability concentration sits with integrated developers possessing balance sheet capacity for long-dated power purchase agreement warehousing; scale advantage sits with offshore engineering heritage firms leveraging marine construction expertise for utility-scale project execution. The market structures around three archetypes: pure-play solar developers, diversified renewable majors with cross-technology portfolios, and district heating cooperatives with captive thermal demand. Competitive moves concentrate on M&A for project pipeline consolidation and strategic partnerships for grid connection queue positioning.
Among Danish pure-play specialists, Better Energy A/S and European Energy A/S occupy positions as merchant and contracted capacity developers with integrated construction and asset management functions. Ørsted A/S anchors the diversified renewable major tier, translating offshore wind engineering capabilities into utility-scale solar origination. Copenhagen Infrastructure Partners represents the infrastructure fund archetype, deploying capital through development-stage equity positions.
| Leading Market Players |
|---|
| Arcon-Sunmark A/S |
| RWE Renewables Denmark |
| Vestas Wind Systems A/S |
| Vattenfall A/S |
| Copenhagen Infrastructure Partners |
| Ørsted A/S |
| European Energy A/S |
| Ennogie Solar Group A/S |
| Better Energy A/S |
| Others |
Value Chain & Pricing Dynamics
Xinjiang-sourced polysilicon wafer supply chains concentrate upstream margin capture with Chinese metallurgical-grade silicon refiners, forcing Danish developers to absorb cost volatility or pivot to European-sourced alternatives at 15-20% premiums. This upstream concentration compresses downstream developer margins while amplifying price differentiation between merchant-exposed and contracted capacity tiers.
Pricing Analysis
Aftermarket service revenue from operations and maintenance contracts drives lifetime value for integrated developers warehousing long-dated power purchase agreements. Danish solar pricing stratifies across premium, standard, and economy tiers based on module efficiency certification and grid connection queue priority. Cost compression in utility-scale EPC contracts is intensifying because Ørsted A/S and Better Energy A/S internalize installation crews. Corporate offtakers from pharmaceutical and logistics sectors exhibit lowest price sensitivity due to EU CSRD compliance mandates, while agricultural cooperatives in Jutland show highest sensitivity to lease rate fluctuations.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for Danish crystalline silicon procurement. Module assembly draws from China, Vietnam, and Malaysia while polysilicon refining rests on Xinjiang and Inner Mongolia capacity. Inverter and tracking hardware sources from Germany, China, and Denmark itself. Single-source vulnerability in metallurgical-grade silicon feedstock threatens project cost predictability. Distribution runs through Baltic Sea container terminals at Aarhus and Copenhagen, then overland to western Jutland construction sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Denmark's solar market presents a defensive-moat story anchored in regulatory entrenchment: Danish Energy Agency permitting reforms and Energinet grid connection queue positioning create structural barriers that compound with each approved project.
For Market Incumbents: Entrench through accelerated origination in western Jutland municipalities with pre-approved zoning maps before queue congestion worsens. Deepen backward integration into high-voltage installation crews to offset skilled electrician scarcity threatening project timelines. Lock in long-dated power purchase agreement warehousing capacity to defend against infrastructure fund capital deployment.
For New Entrants and Emerging Players: District heating cooperative partnerships in Silkeborg and Marstal represent the most penetrable entry point for thermal storage integration expertise. Kattegat offshore solar pilot allocations offer unconstrained capacity access absent land-lease competition. Pursue technology licensing arrangements with Danish Energy Agency for floating photovoltaic seabed leasing rather than competing head-to-head on terrestrial utility-scale origination.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with Copenhagen Infrastructure Partners and similar infrastructure funds holding development-stage equity positions. Five-to-ten year viability hinges on contracted revenue visibility rather than merchant exposure. Watch Energinet substation capacity expansion announcements in western Jutland as the signal for grid connection queue clearing velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Warehousing | Long-dated contracts with Novo Nordisk and Maersk subsidiaries lock in revenue visibility for balance sheet deployment. |
| Backward Integration into Installation Crews | In-house high-voltage DC-to-AC conversion teams mitigate skilled electrician scarcity threatening project timelines. |
| Agri-PV Dual-Use Development | Jutland dairy farm grazing integration unlocks below-market land lease rates while satisfying agricultural cooperative stakeholders. |
| Kattegat Offshore Solar Pilots | Floating photovoltaic seabed leasing terms bypass land constraints in eastern Denmark for capacity multipliers. |
| District Heating Thermal Storage Integration | Silkeborg and Marstal seasonal storage projects anchor agricultural process heat offtake for niche revenue streams. |
Study Parameters
Cross-validation between Energinet auction result databases and Danish Energy Agency permitting records anchors the qualitative findings. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators combined with secondary validation from EIA data, IEA renewable energy reports, and EU Green Deal CSRD implementation documents. Bottom-up project pipeline aggregation and top-down regulatory capacity target triangulation ensure segmentation coherence across photovoltaic systems, solar thermal collectors, and hybrid architectures.
Calibration against historical Energinet auction clearing prices and realized grid connection timelines refines the analytical framework. Segmentation dimensions span product type, installation scale, end-user category, and financing model structure across the projection horizon. Capacity-weighted average cost of capital assumptions and module efficiency degradation curves inform levelized cost trajectories. Danish irradiance data and seasonal generation profiles feed directly into capacity factor modeling.
Stress conditions across polysilicon supply disruption, Energinet substation queue delays, and EU forced labor due diligence enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology cost curves and regulatory implementation timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Poland Solar Energy Market
Solar Power Systems
Residential Solar Panels Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Single Axis Solar PV Tracker Market
Solar Power Systems
Asia-Pacific Solar Tracker Market
Solar Power Systems
Global Solar Module for Electric Vehicle Market
Solar Power Systems
Solar Charger Market
Solar Power Systems
Chile Solar Photovoltaic (PV) Market
Solar Power Systems
South America Solar Tracker Market
Solar Power Systems
Solar Microgrid Market
Solar Power Systems
US Solar Market
Solar Power Systems
India Solar Photovoltaic (PV) Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
Global Ultra Efficient Solar Power Market
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
Solar Tracker for Power Generation Market