
 Hungary Geothermal Energy Market | 2026-2036
Hungary Geothermal Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Hungary Geothermal Energy Market Foresight
Market Context with Strategic Players
The Hungary geothermal energy sector is consolidating around two distinct tiers: premium binary-cycle installations serving industrial offtakers and commodity-grade direct-use systems feeding district heating networks. PannErgy PLC leverages its established drilling portfolio across the Pannonian Basin to anchor utility-scale heat supply contracts. MVM Group sustains integrated project development from exploration through grid connection, while Climeon AB differentiates through compact low-temperature module designs suited for distributed industrial applications.
Technical Definition and Structural Segments
Geothermal energy harnesses heat from subsurface geological formations, typically accessed through wells drilled to depths exceeding two kilometers where reservoir temperatures surpass 100°C, then converted via thermodynamic cycles into electricity or direct thermal output. Binary cycle technology dominates new capacity additions in Hungary due to its operational flexibility at lower reservoir temperatures characteristic of the Pannonian Basin's sedimentary geology. District heating represents the most mature service type with established infrastructure in Szeged, Debrecen, and Győr, while enhanced geothermal systems constitute the fastest-growing segment as developers target deeper, hotter formations previously considered uneconomic.
Regulatory Framework and Forward Outlook
Hungary's geothermal project approvals operate under the dual oversight of the Hungarian Energy and Public Utility Regulatory Authority and EU REACH compliance requirements for drilling fluids and subsurface chemicals. The EU F-Gas Regulation and Hungary's National Energy Strategy constrain equipment choices and mandate emissions monitoring for closed-loop systems. Stakeholders must monitor how upcoming EU taxonomy classifications for sustainable geothermal activities reshape capital access and offtake pricing structures.
Market Dynamics
The Hungary geothermal energy sector is experiencing accelerated permitting velocity under the National Energy Strategy, compressing project development timelines from exploration to operational status while EU Green Deal alignment unlocks capital flows for deep geothermal infrastructure.
Growth Catalysts
- EU Green Deal alignment:Hungary's regulatory harmonization with EU decarbonization mandates streamlines environmental approvals for deep geothermal projects, reducing permitting friction for reservoir temperatures exceeding 100°C.
- District heating network expansion:Municipal utilities in Szeged, Debrecen, and Győr are retrofitting existing infrastructure to accept baseload geothermal thermal input, displacing natural gas dependency in residential heating.
- Binary cycle technology maturation:Operational flexibility at lower reservoir temperatures characteristic of the Pannonian Basin's sedimentary geology expands economically viable resource zones.
Market Restraints
- Drilling cost concentration:Specialized deep drilling rig availability concentrates among Central European contractors, exposing project budgets to equipment mobilization premiums and queue delays.
- EU F-Gas Regulation constraints:Working fluid restrictions for closed-loop binary systems limit equipment vendor selection and increase compliance monitoring overhead for developers.
- Reservoir temperature variability:Pannonian Basin geology produces uneven thermal gradients, requiring expensive exploratory drilling to confirm commercial viability before financing closes.
Strategic Opportunities
- Enhanced geothermal systems:Hydraulic stimulation techniques targeting deeper, hotter formations previously considered uneconomic represent untapped capacity expansion in southeastern Hungary's sedimentary basins.
- Industrial thermal offtake contracts:Food processing and chemical manufacturing facilities near existing district heating infrastructure seek dedicated baseload heat supply agreements at fixed pricing.
- National Energy Strategy incentives:Feed-in tariff mechanisms and accelerated depreciation schedules for renewable thermal assets improve project IRR thresholds for private capital deployment.
Industry Challenges
- Geothermal reservoir engineering talent scarcity:Specialized subsurface modeling and well completion expertise concentrates among aging specialists, constraining project execution capacity as drilling activity intensifies.
- REACH compliance complexity:Drilling fluid formulation disclosure requirements and subsurface chemical registration timelines delay well completion schedules and increase administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hungary Geothermal Energy Market |
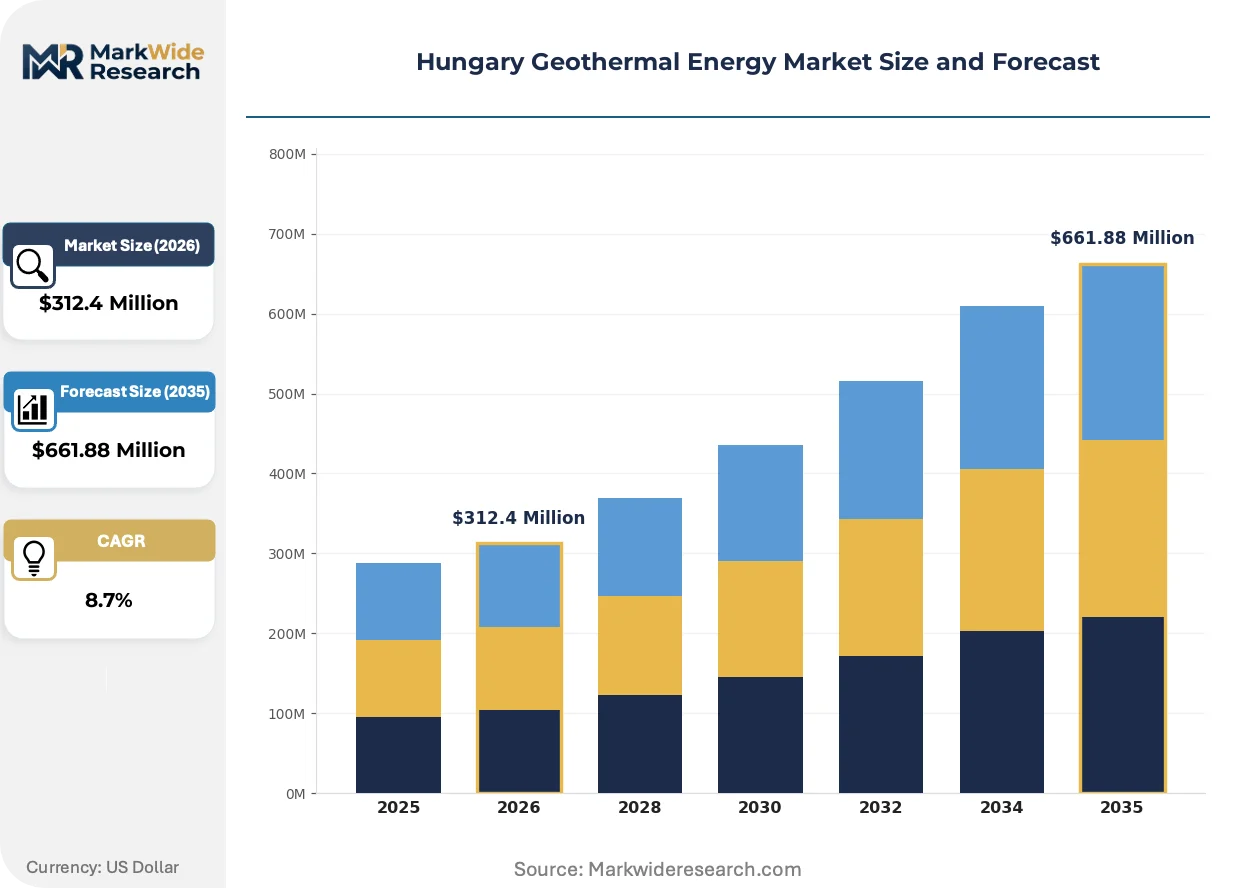
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Electricity Generation, Direct Use, District Heating, Enhanced Geothermal Systems Technology: Binary Cycle, Flash Steam, Dry Steam, Hot Dry Rock End User: Residential, Commercial, Industrial, Agricultural Installation: Onshore, Offshore, Hybrid Systems, Remote Areas |
| Companies Covered | KS Orka Renewables Pte Ltd, Enel SpA, Mannvit, Geoinform Ltd, Engie SA, PannErgy PLC, Porcio Co. Ltd, MVM Group, Climeon AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hungary Geothermal Energy Market Shifts & Advancements
Technology convergence and regulatory compression are restructuring how geothermal resources are accessed, financed, and integrated into Hungary's thermal energy mix. Three developments dominate this transformation.
Binary cycle power generation equipment is modularizing rapidly. Compact low-temperature modules now enable distributed deployment across industrial campuses without centralized plant construction. Manufacturing facilities in western Hungary are adopting these units for captive thermal-electric cogeneration. This modularity is compressing project capital requirements and shortening commissioning cycles from years to months.
Hungary's National Energy Strategy implementation rules are tightening emissions monitoring mandates for closed-loop geothermal systems. The Hungarian Energy and Public Utility Regulatory Authority now requires continuous working fluid leak detection and quarterly reporting submissions. District heating operators are responding by upgrading SCADA infrastructure and contracting third-party verification services to maintain license compliance.
Long-term thermal supply contracting is displacing spot-market fuel purchasing among municipal utilities. Szeged's district heating operator pioneered twenty-year fixed-price geothermal agreements, and Debrecen and Győr utilities are replicating this structure. This contractual innovation is most visible in Transdanubian cities where geothermal resource proximity reduces transmission infrastructure requirements.
Hungary Geothermal Energy Market Segmentation
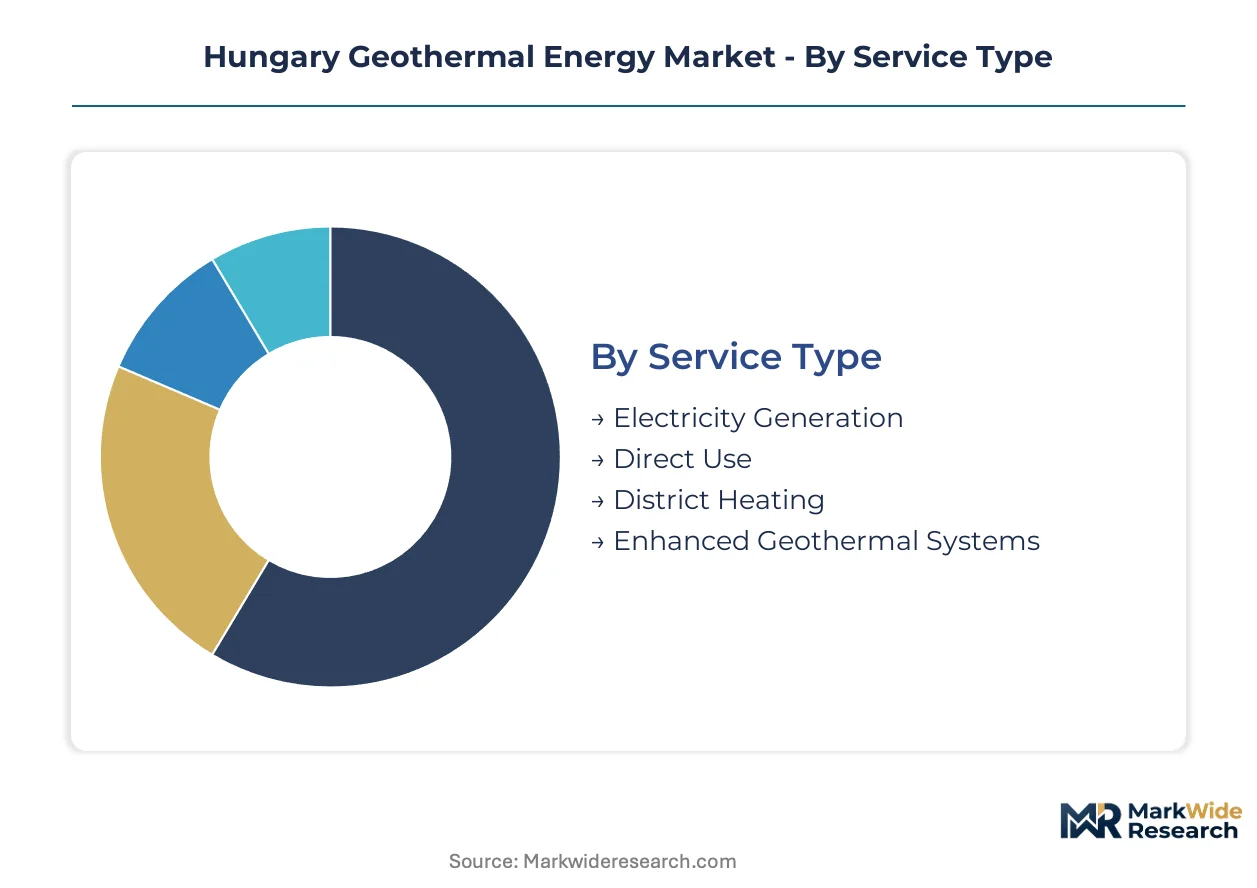
Geothermal market segmentation in Hungary reveals how subsurface resource characteristics dictate viable commercial pathways. Each dimension—service delivery, conversion technology, customer profile, and siting strategy—carries distinct capital intensity and regulatory exposure that shapes developer prioritization.
Service Type:
Supply concentration in Hungary's geothermal sector clusters around thermal service delivery rather than power generation, reflecting the Pannonian Basin's moderate reservoir temperatures and established district heating infrastructure.
- District Heating:Networked thermal distribution systems deliver baseload heat to municipal buildings and residential clusters. Szeged's geothermal district heating network anchors national capacity, with Debrecen and Győr replicating its fixed-price contracting model. The Hungarian Energy and Public Utility Regulatory Authority favors this segment with streamlined permitting for sub-100°C reservoir applications.
- Direct Use:Standalone thermal extraction serves individual facilities without grid integration. Greenhouse operators in southeastern Hungary and thermal spa complexes near Lake Hévíz drive demand for this lower-complexity deployment model. Binary cycle compatibility at reservoir temperatures below 120°C expands addressable resource zones.
- Electricity Generation:Power production via organic Rankine cycle or flash systems remains nascent due to temperature limitations. MVM Group's integrated development model targets this segment for future scaling as enhanced geothermal techniques mature.
- Enhanced Geothermal Systems:Hydraulic stimulation and directional drilling unlock deeper, hotter formations previously uneconomic. Southeastern Hungary's sedimentary basins host pilot projects testing reservoir engineering techniques for temperature augmentation.
Today's leader: District Heating. Tomorrow's challenger: Enhanced Geothermal Systems.
Technology:
Cost tier differentiation separates proven conversion equipment from experimental systems, with binary cycle deployments commanding premium pricing for operational flexibility at lower reservoir temperatures.
- Binary Cycle:Closed-loop systems using organic working fluids transfer heat from moderate-temperature reservoirs to drive turbines. Climeon AB's compact module designs enable distributed industrial deployment without centralized plant construction. The EU F-Gas Regulation constrains working fluid selection, limiting vendor pools and increasing compliance overhead.
- Flash Steam:Direct vapor extraction from high-temperature reservoirs above 180°C suits volcanic geology absent from Hungary's sedimentary basin. This technology holds marginal relevance for Hungarian developers targeting Pannonian Basin resources.
- Dry Steam:Natural steam reservoirs require minimal surface processing. Hungary lacks the tectonic activity necessary for this technology's commercial viability.
- Hot Dry Rock:Engineered reservoirs created through hydraulic fracturing of impermeable formations. Experimental status in Hungary reflects technical uncertainty around stimulation effectiveness in layered sedimentary geology.
Binary cycle systems dominate current deployment. Hot dry rock techniques are climbing the fastest as research funding targets reservoir engineering breakthroughs.
End User:
Customer type determines contract structure and price sensitivity, with industrial offtakers accepting longer-term commitments than residential segments.
- Industrial:Food processing facilities, chemical manufacturers, and pharmaceutical plants near existing district heating infrastructure seek dedicated baseload thermal supply. Fixed-price twenty-year agreements reduce exposure to natural gas volatility. PannErgy PLC anchors utility-scale contracts in this segment.
- Residential:Municipal heating networks aggregate individual household demand. Szeged's retrofit program demonstrates geothermal displacement of gas-fired district heating at scale.
- Commercial:Hotels, hospitals, and office complexes require moderate thermal loads with seasonal variation. Smaller binary cycle modules suit this fragmented demand profile.
- Agricultural:Greenhouse heating and aquaculture operations in the Great Hungarian Plain leverage geothermal for temperature-controlled environments. Lower temperature requirements match available reservoir conditions.
Industrial contracts anchor project financeability. Agricultural applications are expanding most quickly as greenhouse operators seek carbon-neutral thermal alternatives.
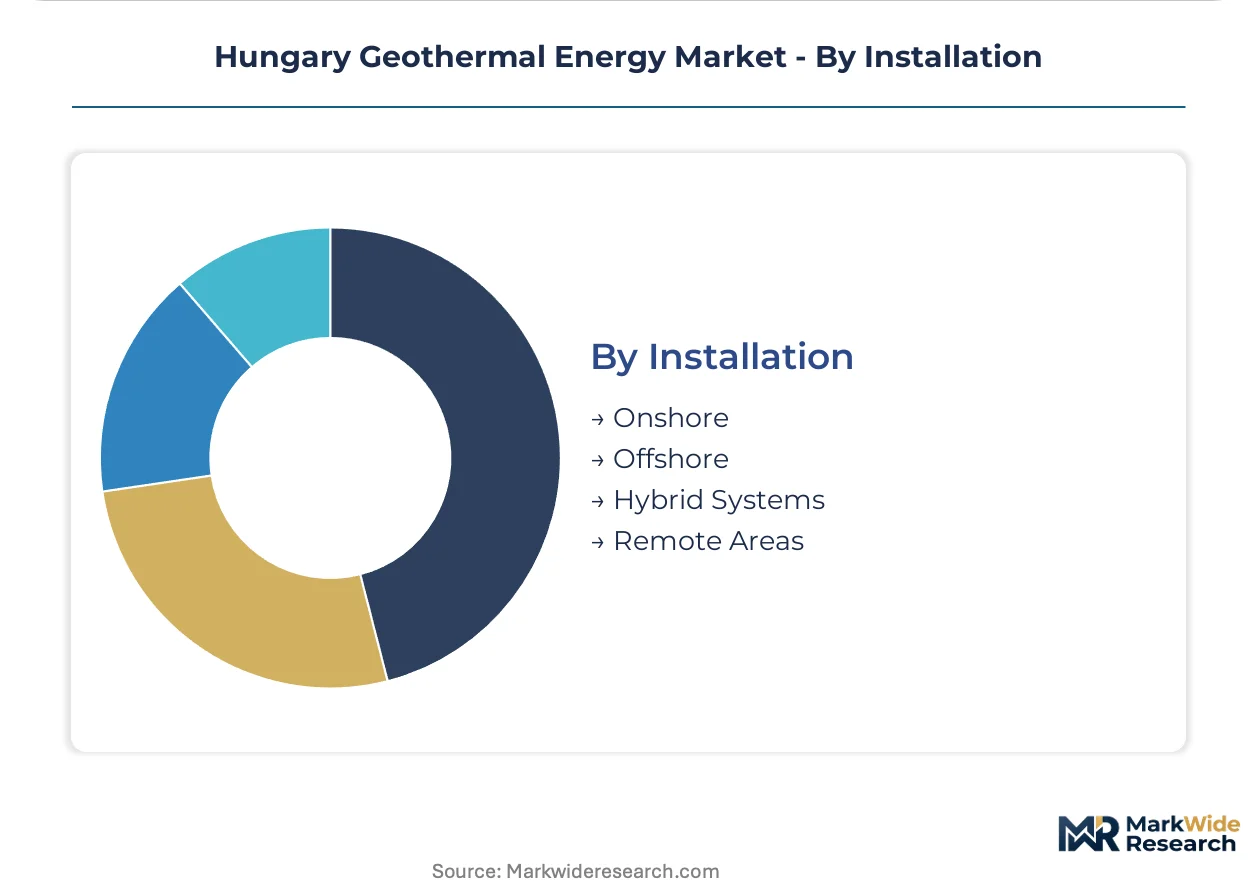
Installation:
Geographic siting constraints reflect Hungary's landlocked position and the concentration of viable resources in specific geological provinces.
- Onshore:Continental drilling targets sedimentary basins across the Great Hungarian Plain and Transdanubia. All operational capacity resides in this category.
- Remote Areas:Distributed generation serves industrial facilities distant from centralized district heating networks. Western Hungarian manufacturing campuses adopt compact binary modules for captive thermal-electric cogeneration.
- Hybrid Systems:Geothermal-solar thermal integration buffers seasonal demand fluctuations. Experimental deployments pair binary cycle baseload with solar peak shaving.
- Offshore:Lake Balaton and other water bodies present theoretical drilling platforms. No commercial activity exists in this category due to technical complexity and regulatory uncertainty.
Onshore development maintains absolute dominance. Remote area installations represent the steepest expansion trajectory as industrial distributed generation gains regulatory support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's geothermal installed capacity exceeds Hungary's by a factor of three, yet Budapest's permitting velocity under the National Energy Strategy now outpaces Berlin's federal approval timelines for comparable deep drilling projects.
Great Hungarian Plain
Thermal spa complexes and greenhouse agriculture drive subsurface heat demand across the Pannonian Basin's sedimentary formations. The Hungarian Energy and Public Utility Regulatory Authority streamlines environmental impact assessments for sub-100°C reservoir applications. Szeged's district heating operator anchors national capacity with twenty-year fixed-price geothermal supply contracts displacing natural gas.
Transdanubia
Industrial food processing and chemical manufacturing facilities seek baseload thermal alternatives to volatile natural gas pricing. EU F-Gas Regulation compliance requirements constrain working fluid selection for binary cycle installations. Győr's municipal utility replicates Szeged's contracting model while western manufacturing campuses adopt compact modular units for captive cogeneration.
Debrecen Metropolitan Area
Pharmaceutical production and hospital thermal loads require uninterrupted heat supply with minimal seasonal variation. Hungary's National Energy Strategy feed-in tariff mechanisms improve project IRR thresholds for private capital deployment. The city's district heating network retrofit program demonstrates geothermal displacement of gas-fired infrastructure at municipal scale.
Southeastern Sedimentary Basins
Enhanced geothermal pilot projects target deeper, hotter formations previously considered uneconomic through hydraulic stimulation techniques. REACH compliance requirements for drilling fluid disclosure delay well completion schedules. Békés County hosts experimental reservoir engineering programs testing temperature augmentation in layered geology.
Lake Hévíz Thermal Region
Medical tourism and wellness hospitality operators require consistent thermal water supply for therapeutic applications. The Hungarian Energy and Public Utility Regulatory Authority mandates continuous working fluid leak detection for closed-loop systems. Local spa complexes upgrade SCADA infrastructure to maintain license compliance under tightening emissions monitoring rules.
Hungary Geothermal Energy Market Competitive Landscape
Top-tier vendors anchor utility-scale integrated development, while specialized technology suppliers occupy modular distributed generation niches. The vendor base clusters around three strategic archetypes: basin-established drillers with established well portfolios, European energy majors leveraging cross-border project finance capacity, and Nordic equipment specialists commercializing compact low-temperature conversion modules. Competitive maneuvering concentrates on long-term thermal offtake contracting and permitting velocity optimization under National Energy Strategy implementation rules.
Within the integrated development tier, MVM Group and PannErgy PLC represent Hungarian market anchors with established Pannonian Basin drilling portfolios and utility-scale heat supply relationships. Climeon AB exemplifies the equipment specialization archetype through its Swedish corporate structure and modular system designs. These three entities occupy positions spanning project origination, subsurface execution, and surface conversion technology without overlapping functional claims.
| Leading Market Players |
|---|
| KS Orka Renewables Pte Ltd |
| Enel SpA |
| Mannvit |
| Geoinform Ltd |
| Engie SA |
| PannErgy PLC |
| Porcio Co. Ltd |
| MVM Group |
| Climeon AB |
| Others |
Supply & Pricing Matrix
Steel price indices and drilling rig day-rate benchmarks cascade through Hungary's geothermal supply chain, compressing project economics for developers while concentrating pricing power among Central European equipment lessors serving the Pannonian Basin.
Pricing Analysis
Capacity additions in southeastern Hungary are reshaping price floors for thermal offtake contracts as enhanced geothermal pilot projects expand supply availability. Fixed-price twenty-year agreements dominate contract structures, with price differentiation driven by reservoir temperature grade and proximity to existing district heating infrastructure. Pricing pressure stems from exploratory drilling cost overruns in layered sedimentary geology. Municipal utilities exhibit highest price sensitivity due to budget constraints, while pharmaceutical manufacturers accept premium tiers for uninterrupted baseload supply.
Supply Chain Analysis
Regional distribution centers in Austria and Germany anchor hub-and-spoke patterns for binary cycle equipment and specialized drilling components. Germany, Austria, and Poland concentrate manufacturing of organic Rankine cycle turbines and high-pressure wellhead assemblies. Raw material dependencies include corrosion-resistant alloys, specialized drilling mud formulations, and fluorinated working fluids constrained by EU F-Gas Regulation. Single-source vulnerability concentrates in deep drilling rig availability among Central European contractors. Distribution runs through EPC contractor networks with direct-to-site logistics for modular binary units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hungary's geothermal sector offers margin expansion through binary cycle technology maturation reducing unit capital costs and industrial offtakers accepting premium-tier fixed-price contracts for carbon-neutral thermal supply.
For Market Incumbents: Extend well portfolio utilization through enhanced geothermal retrofits of existing Pannonian Basin assets rather than greenfield exploration. Anchor utility-scale heat supply contracts with food processing clusters near Győr and Debrecen to defend against modular equipment vendors capturing distributed industrial demand. Pursue backward integration into drilling services to mitigate rig availability bottlenecks. For New Entrants and Emerging Players: Compact low-temperature module designs offer technology-first wedge into western Hungarian manufacturing campuses seeking captive thermal-electric cogeneration without district heating connection. Target agricultural greenhouse operators in the Great Hungarian Plain for direct-use thermal contracts with shorter development cycles than municipal utilities. Deploy equipment-leasing models to bypass upfront capital barriers for mid-size industrial offtakers. For Investors and Strategic Acquirers: Asymmetric upside sits with reservoir engineering specialists possessing hydraulic stimulation expertise for enhanced geothermal scaling in southeastern sedimentary basins. Long-term viability hinges on National Energy Strategy incentive continuity and EU taxonomy classification for sustainable geothermal activities. Monitor permitting velocity at the Hungarian Energy and Public Utility Regulatory Authority as inflection indicator for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced Geothermal Capacity Buildout | Hydraulic stimulation unlocks deeper formations in Békés County previously considered uneconomic. |
| Long-Term Thermal Supply Agreement | Szeged's twenty-year fixed-price contracts reduce municipal exposure to natural gas volatility. |
| Binary Cycle Technology Licensing | Climeon AB's compact module designs enable distributed deployment without centralized plant construction. |
| Backward Integration into Drilling Services | PannErgy PLC's captive rig access mitigates queue delays from Central European contractor concentration. |
| EU Green Deal Certification Program | Alignment with EU taxonomy classifications improves project finance access and offtake pricing structures. |
Research Methodology
Multiple input streams — structured interviews with utility planning officers and IPP project developers, EPC contractor project databases, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged geothermal reservoir engineers, district heating network operators, and binary cycle equipment procurement leads across Budapest, Szeged, and Debrecen. Secondary validation drew from Hungarian Energy and Public Utility Regulatory Authority permitting disclosures, EU F-Gas Regulation implementation guidance, National Energy Strategy policy documents, and IEA geothermal technology roadmaps.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include service delivery type, conversion technology tier, end-user industry vertical, and geographic siting strategy. CAGRs were derived through regression analysis of historical capacity additions against regulatory incentive trajectories and drilling cost inflation patterns. Forecast inputs incorporated reservoir temperature gradient variability across the Pannonian Basin and EU REACH compliance timeline assumptions for drilling fluid registration.
The model holds under sustained National Energy Strategy incentive continuity and EU Green Deal regulatory alignment; deviation in permitting velocity or F-Gas Regulation stringency would shift deployment trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geothermal Energy
Geothermal Power Generation Market
Geothermal Energy
Geothermal Power Market
Geothermal Energy
Geothermal Power Infrastructure and Components Market
Geothermal Energy
Philippines Geothermal Energy Market
Geothermal Energy
Netherlands Geothermal Energy Market
Geothermal Energy
Geothermal Energy Market
Geothermal Energy
Indonesia Geothermal Energy Market
Geothermal Energy
US Geothermal Heat Pump Market
Geothermal Energy
Enhanced Geothermal System Market
Geothermal Energy
Sweden Geothermal Energy Market
Geothermal Energy
United Kingdom Geothermal Energy Market
Geothermal Energy
Asia-Pacific Geothermal Energy Market
Geothermal Energy
Global Geothermal Heat Pumps Market
Geothermal Energy
Denmark Geothermal Energy Market
Geothermal Energy
Geothermal Power Infrastructure Market