
 Industrial Cooling System Market | 2026-2036
Industrial Cooling System Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Cooling System Market Intelligence
Direct procurement channels between original equipment makers and large industrial end users is reshaping how cooling systems reach factory floors. Johnson Controls leverages its building automation heritage to bundle controls with mechanical cooling packages. SPX Corporation anchors its position through specialized heat transfer engineering for power and heavy process industries. Baltimore Aircoil Company Inc. dominates evaporative cooling tower shipments to North American utilities and petrochemical sites.
An industrial cooling system manages thermal loads in manufacturing, power, and commercial facilities through engineered heat rejection equipment typically rated between 10 kW and 50 MW of cooling capacity, using refrigerant cycles, water evaporation, or forced air convection to maintain process temperatures within specified tolerances. Chillers command the largest installed base across process cooling applications, though thermoelectric cooling segments attract premium pricing in semiconductor fabrication where precision thermal stability justifies higher capital outlay. Food processing end users sustain replacement cycles driven by FDA and USDA sanitation mandates that require corrosion-resistant materials and cleanable heat exchanger designs.
EPA SNAP program restrictions on high-GWP refrigerants and EU F-Gas Regulation phase-down timelines are compressing product development cycles and disqualifying legacy equipment from new installations. OSHA process safety management standards and ISO 5149 mechanical refrigeration safety codes further constrain system design choices and certification requirements. Stakeholders must track refrigerant chemistry transitions and regional efficiency tier upgrades to avoid stranded asset risk in installed equipment portfolios.
Market Dynamics
Refrigerant chemistry transitions are compressing product lifecycles across the Industrial Cooling System Market as EPA SNAP restrictions and EU F-Gas phase-downs disqualify legacy equipment from new installations. Equipment makers must redesign thermal packages around lower-GWP alternatives while maintaining performance thresholds for process-critical applications.
Growth Catalysts
- Data center thermal loads:Hyperscale operators in the United States and Germany are expanding compute capacity faster than legacy cooling infrastructure can support, forcing immediate equipment procurement cycles.
- EU F-Gas Regulation:Tightening refrigerant phase-down schedules mandate equipment upgrades across European industrial facilities, accelerating replacement demand for compliant systems.
- Process cooling concentration:China's eastern manufacturing provinces host industrial clusters requiring massive centralized cooling capacity, sustaining heavy chiller and cooling tower shipments.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger fabrication depends on base metal prices that swing with commodity markets, compressing margin predictability for equipment fabricators.
- Refrigerant supply concentration:Lower-GWP alternative chemistries source from limited production facilities, creating bottleneck risk for compliant system rollout timelines.
- Legacy asset stranding:Installed equipment portfolios face accelerated obsolescence as regional efficiency tiers upgrade and refrigerant availability contracts.
Strategic Opportunities
- Semiconductor fabrication thermal stability:Thermoelectric cooling segments command premium positioning where precision temperature control justifies higher capital outlay in advanced node production.
- Direct OEM-to-end-user channels:Large industrial buyers are bypassing traditional distribution layers, creating margin capture potential for original equipment makers with field engineering depth.
- Food sanitation mandates:FDA and USDA corrosion-resistant material requirements sustain replacement cycles with specified cleanable heat exchanger designs.
Industry Challenges
- Refrigerant technician certification gaps:EPA Section 608 and evolving state-level credentialing requirements outpace training program throughput, constraining installation and service capacity.
- ISO 5149 compliance timeline compression:Mechanical refrigeration safety code updates force recertification of existing product lines while development cycles accelerate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Cooling System Market |
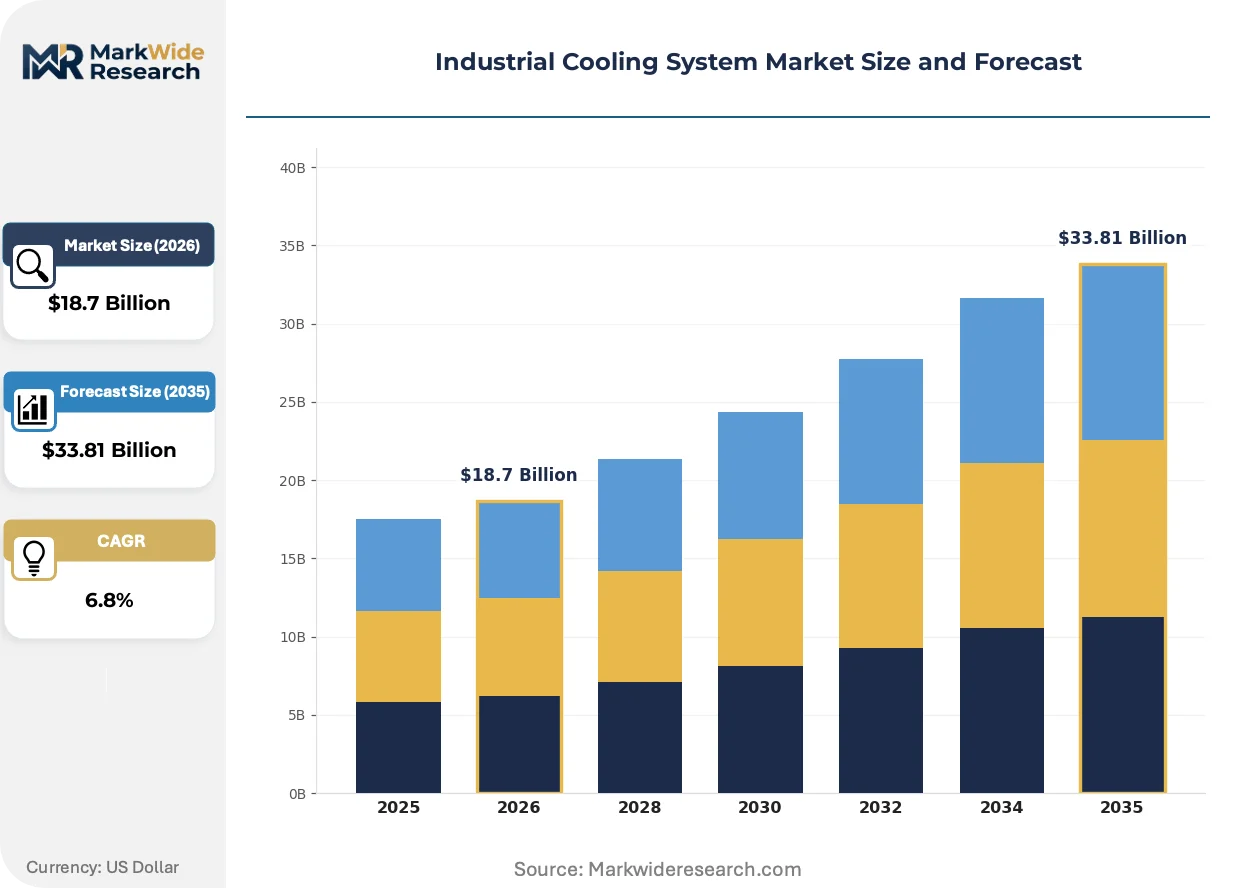
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Heat Exchangers, Cooling Towers, Refrigeration Units Technology: Vapor Compression, Absorption Cooling, Evaporative Cooling, Thermoelectric Cooling End User: Manufacturing, Power Generation, Data Centers, Food Processing Application: Process Cooling, Space Cooling, Equipment Cooling, Hybrid Cooling |
| Companies Covered | SPX Corporation, Johnson Controls, EVAPCO Inc., Baltimore Aircoil Company Inc., Schneider Electric, Emerson Electric Co., Rittal GmbH & Co. KG, Trane Technologies plc, Carrier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Cooling System Market Strategic Shifts & Innovations
Digital twin architectures are virtualizing how cooling system performance is specified, commissioned, and maintained across industrial facilities. This shift compresses design validation cycles and enables predictive thermal management before physical installation.
Digital twin software is virtualizing chiller and cooling tower performance modeling through physics-based simulation layers. Power plant and petrochemical operators are adopting these tools for upfront capacity validation and ongoing optimization. The technology is virtualizing traditional commissioning workflows, reducing field startup time and enabling scenario testing without physical hardware deployment.
The EU F-Gas Regulation is tightening refrigerant phase-down schedules and forcing equipment upgrades across member states. Industrial cooling system manufacturers must redesign thermal packages around lower-GWP alternatives while maintaining performance thresholds. Process cooling applications in Germany and France face the most compressed compliance timelines as national transpositions enforce stricter quotas.
After-sales service unbundling is fragmenting traditional maintenance contracts into discrete performance-based modules. Large industrial end users in the United States are procuring monitoring, parts, and labor separately, pressuring OEM service margins. Food processing facilities show the strongest preference for unbundled structures where sanitation downtime costs dominate total cost of ownership calculations.
Industrial Cooling System Market Segmentation
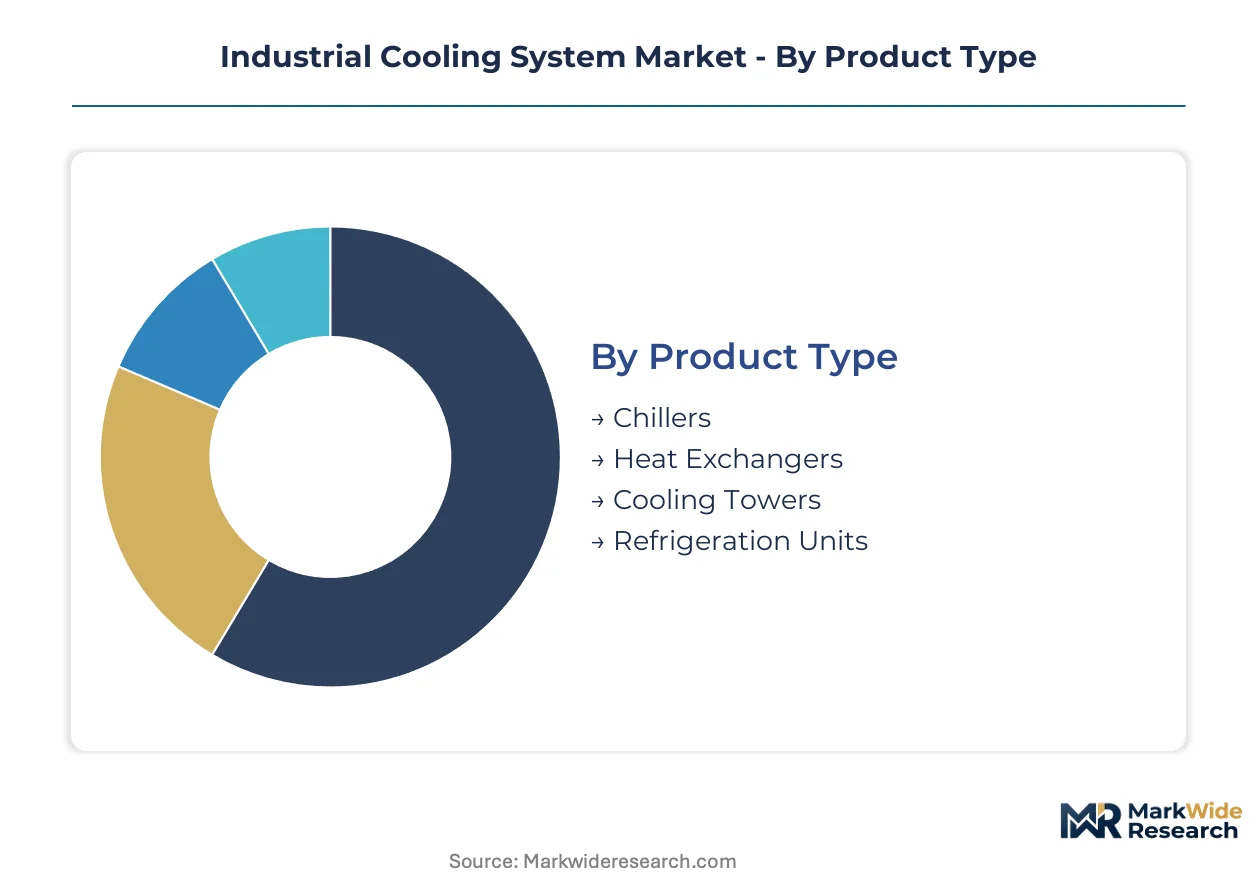
Industrial cooling system procurement patterns diverge sharply across product categories and end-use contexts. Replacement cycles stretch from 15-year chiller installations to 3-year data center thermal upgrades, creating distinct revenue timing profiles for equipment suppliers.
Product Type:
Chillers turn over slowest with decade-plus lifecycles, while refrigeration units face the most compressed replacement schedules driven by refrigerant phase-down mandates.
- Chillers:Centralized vapor compression systems rated 100 kW to 50 MW dominate heavy process cooling loads. Demand concentrates in China's eastern manufacturing provinces where industrial clusters require massive centralized capacity, though EPA SNAP refrigerant restrictions now force premature obsolescence in US installations.
- Cooling Towers:Evaporative heat rejection equipment handles the largest thermal loads in power generation and petrochemical facilities. North American utilities and Gulf Coast petrochemical sites sustain replacement demand as legacy wooden structures face corrosion failures and OSHA process safety upgrades.
- Heat Exchangers:Compact plate-and-frame and shell-and-tube designs enable fluid-to-fluid thermal transfer in constrained footprints.
- Refrigeration Units:Distributed systems below 100 kW serve discrete process zones with faster upgrade cycles tied to refrigerant chemistry transitions.
Chillers dominate installed base. Refrigeration units are where expansion concentrates.
Technology:
Cost tiers separate mature vapor compression from emerging thermoelectric alternatives commanding 3-5x capital premiums.
- Vapor Compression:Mechanical refrigeration cycles using electric compressors deliver the highest coefficient of performance across standard industrial temperature ranges. Food processing facilities in the United States and Germany sustain the largest installed base, though EU F-Gas Regulation phase-downs now force refrigerant transitions.
- Thermoelectric Cooling:Solid-state Peltier devices enable precision temperature control without moving parts. Semiconductor fabrication facilities in Taiwan and South Korea absorb premium pricing where thermal stability within 0.1°C tolerances justifies capital outlay for advanced node production.
- Absorption Cooling:Thermal-activated systems using waste heat or natural gas suit cogeneration environments with available low-grade energy sources.
- Evaporative Cooling:Water-based heat rejection achieves lowest operating costs where water availability and water treatment infrastructure permit open-loop operation.
Vapor compression commands volume leadership. Thermoelectric cooling is climbing the fastest on semiconductor capital expansion.
End User:
Application maturity ranges from century-old power generation practice to decade-old hyperscale data center thermal engineering.
- Data Centers:Hyperscale compute facilities generate thermal densities exceeding 50 kW per rack, exceeding legacy air-cooled infrastructure limits. Operators in Germany and the United States are expanding capacity faster than installed cooling can support, forcing immediate procurement of liquid-cooled and evaporative systems.
- Food Processing:FDA and USDA sanitation mandates require corrosion-resistant materials and cleanable heat exchanger designs that sustain replacement cycles independent of mechanical failure. Poultry and dairy facilities face the most stringent washdown protocols.
- Manufacturing:Discrete and process industries deploy cooling for machine tool thermal stability, plastic injection molding, and chemical reaction control.
- Power Generation:Thermal power plants rely on massive cooling water systems for condenser heat rejection, with nuclear facilities imposing the most stringent safety-grade requirements.
Manufacturing holds the deepest installed base. Data centers are gaining share fastest on compute capacity expansion.
Application:
Volume concentration favors process cooling while margin capture concentrates in precision equipment thermal management.
- Process Cooling:Direct thermal management of manufacturing reactions, extrusions, and forming operations constitutes the largest addressable volume. China's chemical and steel sectors in Jiangsu and Shandong provinces absorb massive chiller and cooling tower shipments for continuous production lines.
- Equipment Cooling:Dedicated thermal protection for electrical switchgear, variable frequency drives, and precision machine tools commands premium pricing where uptime guarantees override energy efficiency considerations. Semiconductor lithography and metrology equipment require the tightest temperature tolerances.
- Space Cooling:Environmental conditioning for occupied or storage areas operates at less stringent tolerances with longer equipment lifecycles.
- Hybrid Cooling:Combined process and space thermal loads in integrated facilities complicate system sizing and control architecture.
Process cooling dominates installed base. Equipment cooling is where expansion concentrates on precision manufacturing growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk terminals and Rhine barge connectivity position the Netherlands as Europe's industrial cooling logistics hub. German data center clusters along the Frankfurt-Mannheim corridor draw cooling equipment through Dutch distribution channels. China's Yangtze River Delta ports handle the densest concentration of chiller and cooling tower imports worldwide.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth are expanding compute capacity beyond legacy air-cooled infrastructure limits. EPA SNAP program restrictions on high-GWP refrigerants are compressing product development cycles and disqualifying legacy equipment from new installations. The Permian Basin petrochemical corridor sustains evaporative cooling tower demand as OSHA process safety management standards force infrastructure upgrades.
Germany
Frankfurt's banking and cloud computing hub generates thermal densities exceeding 50 kW per rack, forcing immediate procurement of liquid-cooled systems. EU F-Gas Regulation phase-down timelines mandate equipment upgrades across industrial facilities, with Germany facing the most compressed compliance schedules. The Rhine-Ruhr industrial belt hosts chemical and steel clusters requiring massive centralized chiller capacity for continuous production lines.
China
Jiangsu and Shandong provinces absorb massive chiller and cooling tower shipments for steel and chemical manufacturing clusters. The country's dual carbon goals under MEE oversight are accelerating efficiency tier upgrades for industrial cooling equipment. Shanghai's Yangshan deep-water port handles the highest volume of imported cooling system components for eastern manufacturing provinces.
Japan
Semiconductor fabrication facilities in the Kyushu region command premium pricing for thermoelectric cooling where thermal stability within 0.1°C tolerances justifies capital outlay. METI energy efficiency standards are forcing refrigerant transitions in food processing and manufacturing facilities. The Kansai industrial corridor around Osaka sustains replacement demand for corrosion-resistant heat exchangers in coastal chemical plants.
Industrial Cooling System Market Key Industry Players
On the supply side, the industry is moderately consolidated around diversified industrial conglomerates with specialized thermal engineering divisions. Tiered competition separates scale-driven full-line suppliers from niche specialists in heat transfer engineering and precision cooling. Three strategic archetypes dominate: building automation integrators bundling controls with mechanical packages, specialized heat transfer engineers serving power and petrochemical verticals, and precision thermal specialists capturing premium positioning in semiconductor fabrication. M&A activity concentrates on controls integration capabilities, while capacity expansion targets lower-GWP refrigerant-compliant manufacturing lines.
Among North American-based fabricators, Baltimore Aircoil Company Inc. and EVAPCO Inc. occupy positions within the evaporative cooling tower specialization tier, exemplifying engineering depth in utility and petrochemical heat rejection applications. Johnson Controls anchors the building automation integrator archetype, representing the bundled controls-plus-mechanical packaging strategy that large industrial end users increasingly favor for direct procurement relationships. These three companies illustrate how geographic proximity to major data center and petrochemical clusters shapes competitive positioning without determining specific market share outcomes.
| Leading Market Players |
|---|
| SPX Corporation |
| Johnson Controls |
| EVAPCO Inc. |
| Baltimore Aircoil Company Inc. |
| Schneider Electric |
| Emerson Electric Co. |
| Rittal GmbH & Co. KG |
| Trane Technologies plc |
| Carrier |
| Others |
Cost & Logistics Intelligence
Jiangsu province's chiller fabrication clusters anchor global capacity for vapor compression systems, concentrating upstream supply power among equipment makers serving downstream data center and petrochemical buyers. This geographic concentration enables tier-one OEMs to enforce volume-discount structures while smaller fabricators absorb margin compression from copper and aluminum commodity volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEMs with ISO 5149 certification and field engineering depth from commodity assemblers. Price differentiation hinges on refrigerant compliance tier and after-sales service bundling, with EU F-Gas Regulation mandates compressing margins for legacy equipment lines. Hyperscale data center operators show lowest price sensitivity where thermal density guarantees override capital constraints, while food processing facilities in secondary markets drive hardest bargain terms.
Supply Chain Analysis
Export-control regimes on semiconductor-grade cooling technologies limit thermoelectric component flows from Taiwan and South Korea to mainland China facilities. Heat exchanger fabrication draws from copper smelters in Chile and aluminum rolling mills in Russia, creating tariff exposure through multiple trade corridors. Distribution runs through Rotterdam's liquid bulk terminals for European inland delivery and Yangshan port for eastern China manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where predictive maintenance contracts and refrigerant transition consulting expand faster than hardware shipments. Digital twin commissioning services and ISO 5149 recertification support represent recurring revenue layers decoupled from equipment replacement cycles.
For Market Incumbents: Entrench position through backward integration into lower-GWP refrigerant captive supply and field engineering capacity in Germany's Rhine-Ruhr corridor. Compress development cycles to outpace EU F-Gas phase-down timelines while acquiring controls integration specialists to defend against building automation bundlers. Threat substitution from thermoelectric cooling in semiconductor nodes demands R&D allocation to precision thermal stability portfolios. For New Entrants and Emerging Players: Establish a beachhead in unbundled aftermarket service modules where large industrial end users procure monitoring, parts, and labor separately. Food processing facilities in secondary US markets show penetrable price sensitivity and compressed replacement cycles driven by FDA sanitation mandates. Go-to-market leverage rests on technician certification programs outpacing EPA Section 608 pipeline constraints. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because refrigerant chemistry transitions and efficiency tier upgrades guarantee replacement demand regardless of macro cycles. Acquisition targets cluster around specialized heat transfer engineering firms with petrochemical vertical relationships and digital twin software capabilities. Signal to watch is EU F-Gas quota auction prices as inflection indicator for equipment upgrade acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lower-GWP Refrigerants | Captive supply secures compliance positioning against EU F-Gas phase-down bottlenecks. |
| Digital Twin Platform Integration | Virtual commissioning tools compress field startup time for hyperscale data center deployments. |
| Technician Certification Program Expansion | EPA Section 608 credentialing capacity constrains installation throughput nationwide. |
| Long-term Service Agreement Unbundling | Performance-based modules capture margin from food processing downtime cost sensitivity. |
| Joint Venture in China's Eastern Provinces | Jiangsu and Shandong industrial clusters require localized fabrication for massive chiller demand. |
Research Approach
Initial hypotheses were tested against primary input from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads, then refined through secondary validation. Stakeholder interviews combined with SEC 10-K filings, customs and trade data, EPA SNAP program documentation, and EU F-Gas Regulation transposition texts enabled bottom-up and top-down triangulation across equipment shipment records and end-user replacement cycle surveys.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling vapor compression, thermoelectric, absorption, and evaporative technology segments alongside chiller, cooling tower, heat exchanger, and refrigeration unit product categories. CAGRs were derived from installed base turnover rates and regulatory compliance deadlines rather than macroeconomic extrapolation, with specific weighting applied to data center thermal density curves and semiconductor capital expenditure patterns.
Stress conditions across copper and aluminum commodity bands, refrigerant supply concentration scenarios, and EU F-Gas quota enforcement timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about replacement cycle compression and efficiency tier adoption curves. Material shifts in EPA SNAP program scope or EU F-Gas phase-down acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Europe Air Source Heat Pump Market
Cooling Systems
Portable Chiller Market
Cooling Systems
Thawing System Market
Cooling Systems
Lithium Battery Liquid Cooling Pump Market
Cooling Systems
Cryosystem Market
Cooling Systems
Air-Cooled Gas Coolers Market
Cooling Systems
Temporary Power and Cooling Solutions Market
Cooling Systems
Cryogenic Systems Market
Cooling Systems
Energy Storage Temperature Control Equipment Market
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
Heat Pump (>100°C) Market
Cooling Systems
Adiabatic Cooler Market
Cooling Systems
Marine Cooling Systems Market
Cooling Systems
Seawater Cooling System Market
Cooling Systems
Chilled Water System Market
Cooling Systems
Industrial Water Cooling System Market