
 Saudi Arabia Desert Air Coolers Market | 2026-2036
Saudi Arabia Desert Air Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Desert Air Coolers Market Insights
Multi-source component procurement is broadening across Saudi Arabia's desert air cooler supply chain as manufacturers reduce dependence on single-country imports. Gree leverages vertical integration to control compressor and fan motor costs. SuperGeneral anchors its position through deep distribution partnerships with Saudi retailers. Daikin competes on inverter technology adapted for evaporative hybrid systems.
Desert air coolers are evaporative cooling devices that use water-saturated pads and high-volume airflow to reduce ambient temperatures by 15–25°F in dry climates, operating at roughly one-eighth the energy consumption of vapor-compression air conditioners. Portable evaporative coolers dominate residential sales due to low entry cost and minimal installation requirements, while industrial coolers command the strongest margin pools through customized ducting and high-capacity blower configurations. Smart controller integration represents the fastest-growing technology segment as IoT-enabled humidity sensing and variable-speed pumps optimize water consumption.
SASO mandates minimum energy performance standards and water efficiency ratings for all cooling appliances sold in the Kingdom, while SFDA oversees material safety in water-contact components. Municipal building codes in Riyadh and Jeddah increasingly prescribe evaporative pre-cooling for commercial structures over 5,000 square meters. Stakeholders must monitor SASO's anticipated expansion of seasonal efficiency metrics and prepare for stricter pad material biodegradability requirements.
Market Dynamics
SASO's tightening energy-efficiency thresholds are compressing margins for low-tier manufacturers while rewarding inverter-ready evaporative systems. This regulatory pressure is restructuring procurement priorities across Riyadh's commercial construction sector and Jeddah's residential retrofit market.
Growth Catalysts
- SASO Seasonal Efficiency Metrics:The Saudi Standards, Metrology and Quality Organization mandates are accelerating replacement cycles in commercial buildings over 5,000 square meters, forcing upgrades to compliant pad materials and variable-speed pumps.
- Grid Infrastructure Strain:Peak summer loads exceeding 45°C temperatures in Riyadh and Jeddah are driving municipal planners toward evaporative pre-cooling mandates as a demand-side management tool.
- IoT-Enabled Humidity Sensing:Smart controller integration allows real-time water consumption optimization, appealing to cost-conscious homeowners seeking alternatives to vapor-compression cooling.
Market Restraints
- Pad Material Import Concentration:Biodegradable cellulose pad supply concentrates in Southeast Asian manufacturing clusters, exposing Saudi distributors to shipping cost volatility and extended lead times.
- Water Scarcity Constraints:Evaporative cooling's water intensity faces mounting scrutiny from the Ministry of Environment, Water and Agriculture in drought-prone northern provinces.
- Air-Conditioning Substitution Threat:Inverter-driven vapor-compression units with solar compatibility are capturing premium residential segments previously accessible to hybrid evaporative systems.
Strategic Opportunities
- Asir and Tabuk Regional Expansion:Highland provinces with lower humidity profiles remain underpenetrated by organized retail distribution, favoring direct-to-contractor sales models.
- SFDA Material Safety Certification:Water-contact component testing requirements create first-mover advantages for manufacturers pre-certifying antimicrobial pad treatments and food-grade reservoir coatings.
- Industrial Process Cooling Convergence:Integration of evaporative pre-cooling with data center thermal management and warehouse cold-chain infrastructure opens project-scale contract opportunities.
Industry Challenges
- Variable-Speed Drive Calibration:Technicians skilled in inverter-pump synchronization for evaporative hybrids remain scarce in Jeddah's service networks, extending commissioning timelines.
- SASO Compliance Documentation:Seasonal efficiency testing protocols require third-party laboratory certification cycles that delay product launches by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Desert Air Coolers Market |
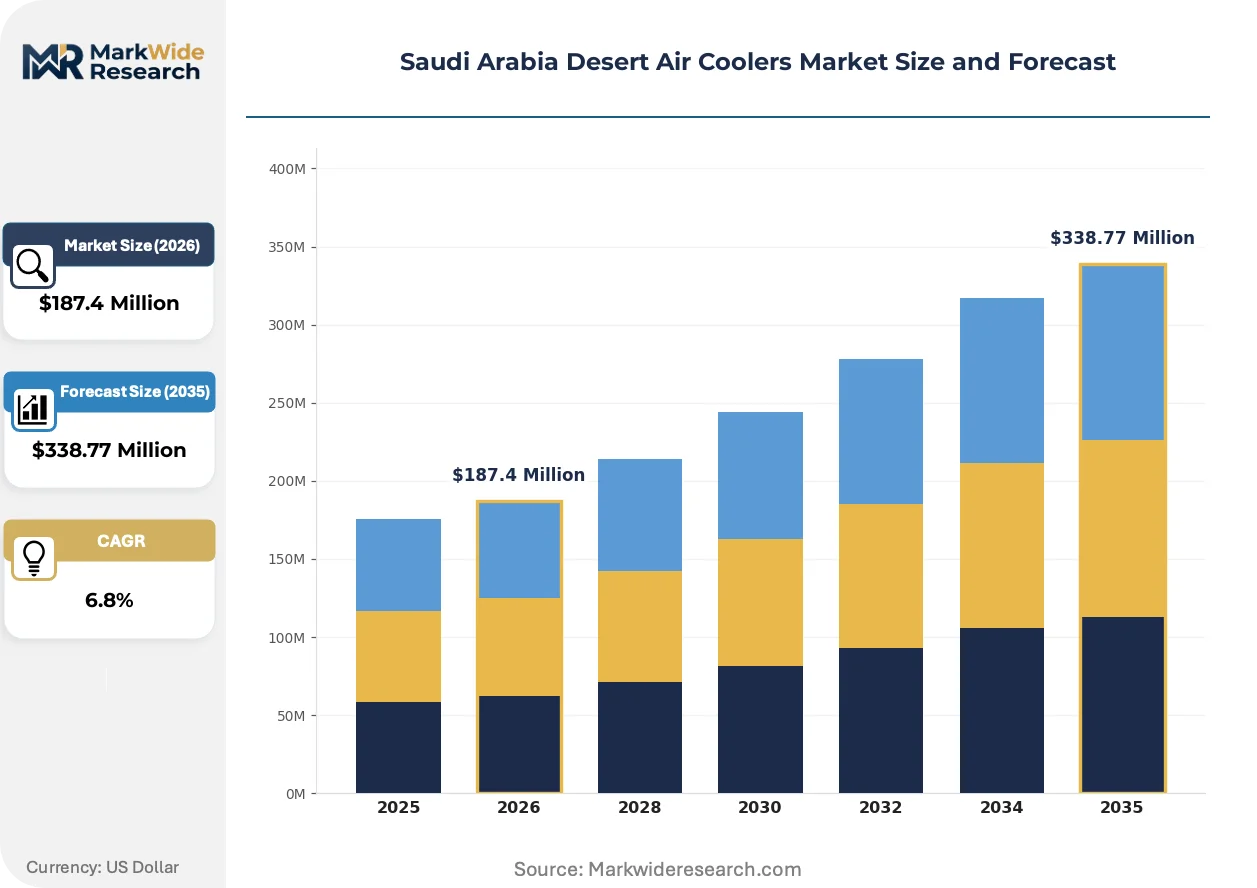
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Evaporative Coolers, Window Evaporative Coolers, Industrial Coolers, Residential Coolers Application: Commercial Spaces, Residential Buildings, Industrial Facilities, Outdoor Events End User: Homeowners, Business Owners, Event Organizers, Facility Managers Technology: Direct Evaporation, Indirect Evaporation, Hybrid Systems, Smart Controllers |
| Companies Covered | Gree, SuperGeneral, Evvoli, Aux, Crownline, Midea, Daikin, Emerson, Carrier, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Desert Air Coolers Market Trends and Innovations
Smart controller ecosystems are reconfiguring how Saudi buyers evaluate total cost of ownership. Manufacturers now compete on predictive maintenance algorithms and remote diagnostics rather than raw cooling capacity alone.
Variable-speed inverter pumps are consolidating control over water distribution precision in residential desert coolers. Middle-income homeowners in Riyadh's eastern districts are adopting these systems at accelerating rates. The technology is consolidating market share from fixed-speed diaphragm pumps by enabling humidity-responsive flow modulation that cuts water waste.
SASO's anticipated expansion of biodegradability requirements for water-contact pad materials is forcing reformulation investments across supply chains. Manufacturers serving the Kingdom must now qualify alternative cellulose sourcing or synthetic fiber blends. Commercial building contractors in Jeddah are front-loading procurement to lock in grandfathered inventory before enforcement windows tighten.
Direct-to-contractor digital platforms are fragmenting traditional distributor control over project specifications. Engineering procurement offices in Riyadh's King Abdullah Financial District are bypassing retail channels for bulk cooler configurations. This pattern is most visible in commercial developments where specification authority has shifted from general contractors to MEP consultants with platform-based vendor access.
Saudi Arabia Desert Air Coolers Market Segmentation
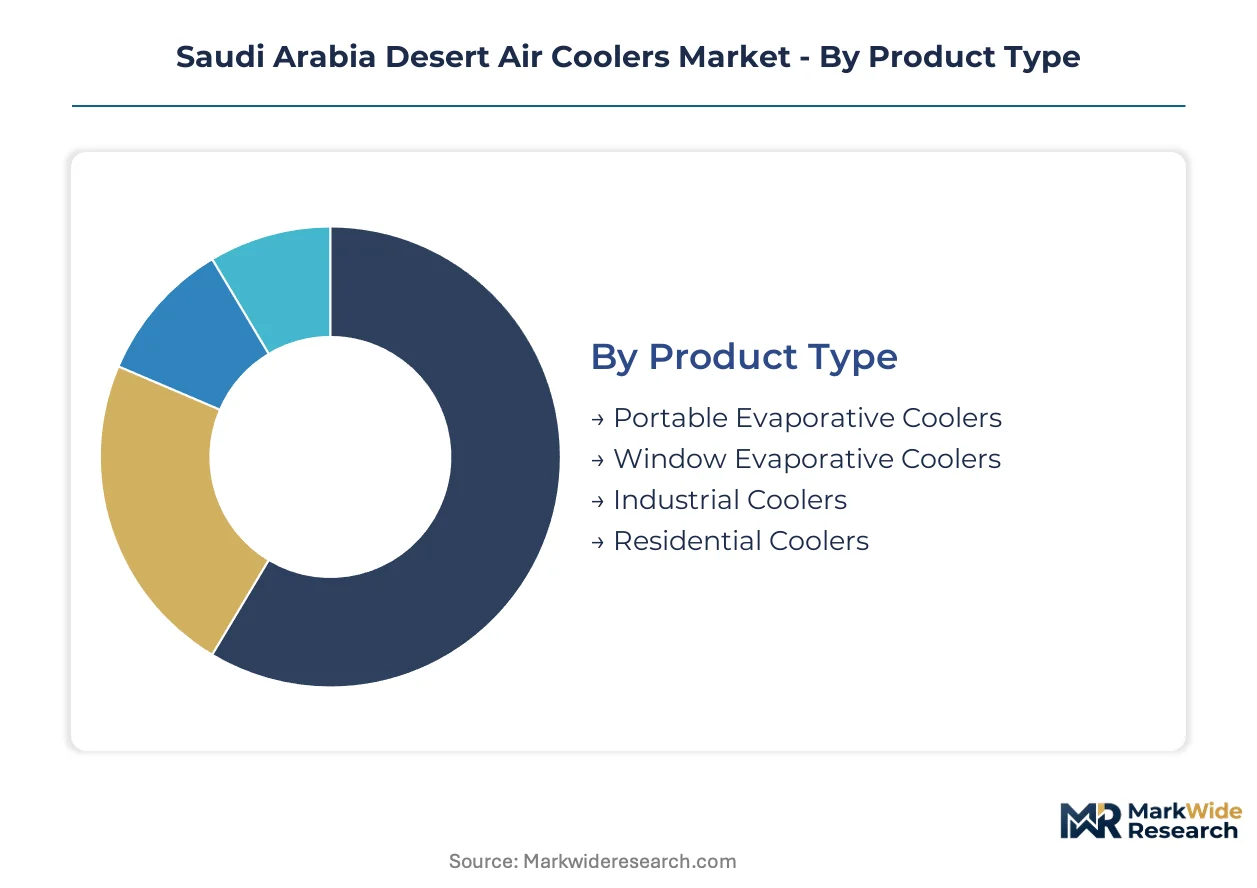
Desert air cooler segmentation in Saudi Arabia reflects divergent technical requirements across Riyadh's commercial towers and Jeddah's residential compounds. Specification authority now rests with MEP consultants who configure systems around SASO efficiency tiers rather than raw cooling capacity.
Product Type:
Physical form factor dictates installation complexity and procurement channel in Saudi Arabia's evaporative cooling market.
- Industrial Coolers:High-capacity blower configurations with customized ducting and corrosion-resistant housings serve warehouse and manufacturing facilities. Demand concentrates in Jeddah's industrial zones where facility managers prioritize uptime over capital cost. SASO seasonal efficiency mandates are accelerating replacement of fixed-speed units with variable-drive configurations.
- Portable Evaporative Coolers:Self-contained units with casters and minimal installation requirements dominate residential sales through hypermarket and e-commerce channels. Riyadh's eastern districts show strongest uptake among middle-income homeowners seeking alternatives to vapor-compression cooling. Low entry cost and plug-and-play deployment drive volume.
- Window Evaporative Coolers:Through-wall units with permanent water connections serve retrofit applications where central ducting is impractical.
- Residential Coolers:Fixed-installation units with integrated reservoirs target villa compounds and apartment buildings with dedicated mechanical rooms.
Mature deployment sits with industrial coolers in Jeddah's logistics corridors. Newer deployment is concentrated in portable units for Riyadh's rental housing market.
Application:
Building code enforcement intensity varies sharply across Saudi Arabia's evaporative cooling applications.
- Commercial Spaces:Structures exceeding 5,000 square meters face mandatory evaporative pre-cooling under Riyadh and Jeddah municipal codes. Variable-speed pumps and biodegradable pad materials are becoming specification requirements for new construction permits. Commissioning delays from SASO compliance documentation extend project timelines.
- Residential Buildings:Villa compounds and apartment towers drive replacement demand as homeowners respond to electricity tariff restructuring. Smart controller integration is climbing fastest in this segment as IoT-enabled humidity sensing reduces water waste. Jeddah's coastal humidity challenges limit effectiveness compared to Riyadh's arid interior.
- Industrial Facilities:Process cooling and worker comfort applications in manufacturing plants require customized blower configurations.
- Outdoor Events:Temporary cooling for festivals and construction sites favors rapid-deployment portable units with high-capacity tanks.
Established regulatory pressure centers on commercial spaces. Emerging compliance requirements are reshaping residential building procurement.
End User:
Purchasing authority fragmentation distinguishes Saudi Arabia's evaporative cooling demand.
- Facility Managers:Technical buyers with lifecycle cost accountability specify industrial-grade systems for corporate and government portfolios. Riyadh's King Abdullah Financial District developments show preference for predictive maintenance platforms and remote diagnostics. Procurement runs through engineering procurement offices with direct-to-contractor platform access.
- Homeowners:Price-sensitive retail buyers prioritize low upfront cost and minimal installation disruption. Seasonal humidity variation between Riyadh and Jeddah creates divergent product expectations. Smart controller adoption is expanding most quickly among this group as water conservation awareness rises.
- Business Owners:Small commercial operators balance capital constraints against SASO compliance requirements.
- Event Organizers:Rental market participants prioritize rapid deployment and damage-resistant construction for temporary installations.
Procurement sophistication clusters with facility managers. Volume expansion is concentrated among homeowners responding to energy tariff signals.
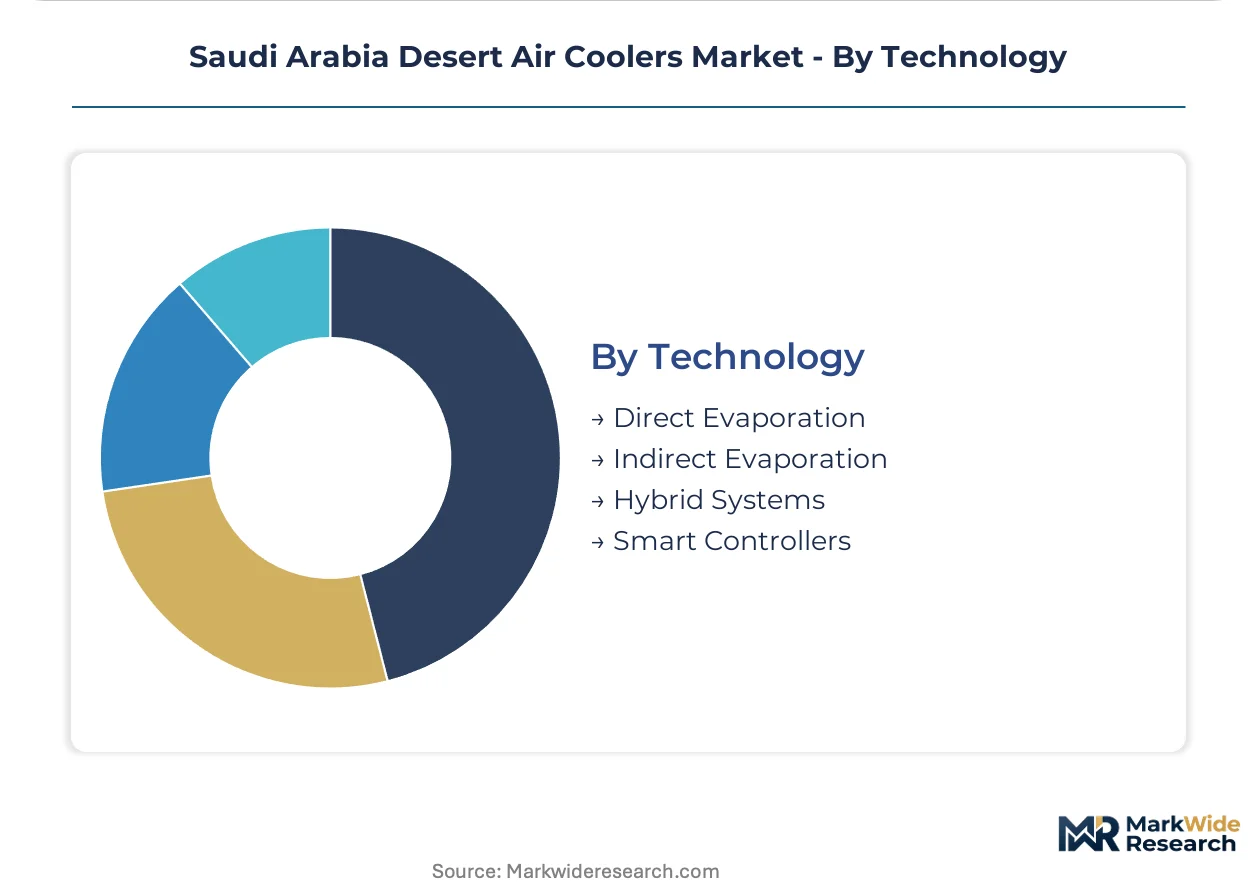
Technology:
Control architecture differentiation now outweighs raw cooling capacity in Saudi specification decisions.
- Smart Controllers:IoT-enabled systems with humidity sensing, variable-speed pump modulation, and predictive maintenance algorithms are expanding most quickly. Riyadh's tech-forward residential districts and Jeddah's commercial developments show parallel adoption. Manufacturers compete on remote diagnostics capability rather than nominal airflow ratings.
- Hybrid Systems:Combined direct-indirect evaporation with inverter integration addresses humidity variability in coastal provinces. Higher capital cost is offset by operational flexibility across Saudi Arabia's climatic zones.
- Direct Evaporation:Conventional pad-and-fan configurations dominate entry-price segments with minimal control sophistication.
- Indirect Evaporation:Separated airflow designs reduce humidity addition but require larger heat exchanger surfaces.
Technology maturity rests with direct evaporation in rural and northern provinces. Steepest expansion trajectory belongs to smart controllers in metropolitan construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silica sand deposits in the Eastern Province anchor Saudi Arabia's desert air cooler manufacturing base. Regional demand patterns diverge sharply between Riyadh's arid interior and Jeddah's humid coastal corridor.
Riyadh
Residential villa compounds and commercial towers drive specification demand for SASO-compliant variable-speed systems. The municipal building code mandates evaporative pre-cooling for structures exceeding 5,000 square meters. King Abdullah Financial District developments concentrate procurement through engineering procurement offices with direct-to-contractor platform access.
Eastern Province
Industrial facilities in Jubail and Dammam prioritize high-capacity blower configurations for worker comfort and process cooling. SFDA material safety requirements shape water-contact component sourcing for petrochemical-adjacent installations. Manufacturing clusters around Dammam absorb bulk cooler shipments for warehouse and logistics infrastructure.
Western Region
Jeddah's coastal humidity challenges conventional evaporative effectiveness, accelerating hybrid system adoption. Electricity tariff restructuring drives residential retrofit demand in middle-income districts. Municipal codes here mirror Riyadh's commercial mandates but face enforcement gaps in older districts.
Asir
Highland provinces with lower humidity profiles remain underpenetrated by organized retail distribution. Direct-to-contractor sales models bypass traditional distributor networks. Abha's cooler summer temperatures limit peak-season demand intensity compared to interior markets.
Tabuk
Northern province water scarcity constraints from the Ministry of Environment, Water and Agriculture scrutinize evaporative cooling intensity. Grid infrastructure strain in summer months favors demand-side management through pre-cooling mandates. Local procurement runs through facility managers with lifecycle cost accountability rather than retail channels.
Saudi Arabia Desert Air Coolers Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers secure distribution depth and technology access. The vendor base stratifies across three tiers: multinational HVAC conglomerates with captive component supply, regional specialists leveraging local assembly partnerships, and price-focused importers serving entry-level residential segments. Two archetypes define competitive positioning: inverter-technology leaders and distribution-anchored assemblers. M&A activity and SASO pre-certification investments constitute the dominant competitive moves reshaping market structure.
Among multinational HVAC conglomerates, Gree exemplifies backward integration into compressor and fan motor production, while Daikin occupies a position emphasizing inverter technology adaptation. SuperGeneral anchors the regional specialist archetype through distribution partnerships with Saudi retailers. These three companies represent divergent strategic postures: captive supply control, technology differentiation, and channel depth respectively.
| Leading Market Players |
|---|
| Gree |
| SuperGeneral |
| Evvoli |
| Aux |
| Crownline |
| Midea |
| Daikin |
| Emerson |
| Carrier |
| Others |
Pricing and Supply Chain Analysis
Technician scarcity in Jeddah's service networks widens pricing spreads between premium inverter-pump installations and economy fixed-speed units, as labor-cost differentials compound with SASO compliance documentation delays to stratify procurement budgets across residential and commercial buyer archetypes.
Pricing Analysis
Warranty bundling separates premium-tier manufacturers from unbundled economy imports, with multi-year service contracts and predictive maintenance platforms commanding margin premiums in Riyadh's King Abdullah Financial District developments. Price differentiation rests on SASO certification grade and smart controller integration depth, with inverter-ready systems widening their premium over fixed-speed alternatives as electricity tariff restructuring accelerates. Cost compression in the portable residential segment intensifies due to hypermarket price competition, while facility managers show lowest price sensitivity given lifecycle cost accountability frameworks.
Supply Chain Analysis
Reverse-logistics infrastructure for pad material refurbishment remains underdeveloped across Saudi Arabia's evaporative cooling sector, limiting circular economy participation and extending replacement part lead times. Manufacturing feedstocks draw from China for electronic controllers, Southeast Asia for biodegradable cellulose pads, and domestic Eastern Province facilities for corrosion-resistant housings. Single-source vulnerability concentrates in cellulose pad supply from Indonesian and Thai manufacturing clusters, exposing distributors to shipping cost volatility. Distribution runs through engineering procurement offices for commercial projects and hypermarket retail channels for residential portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
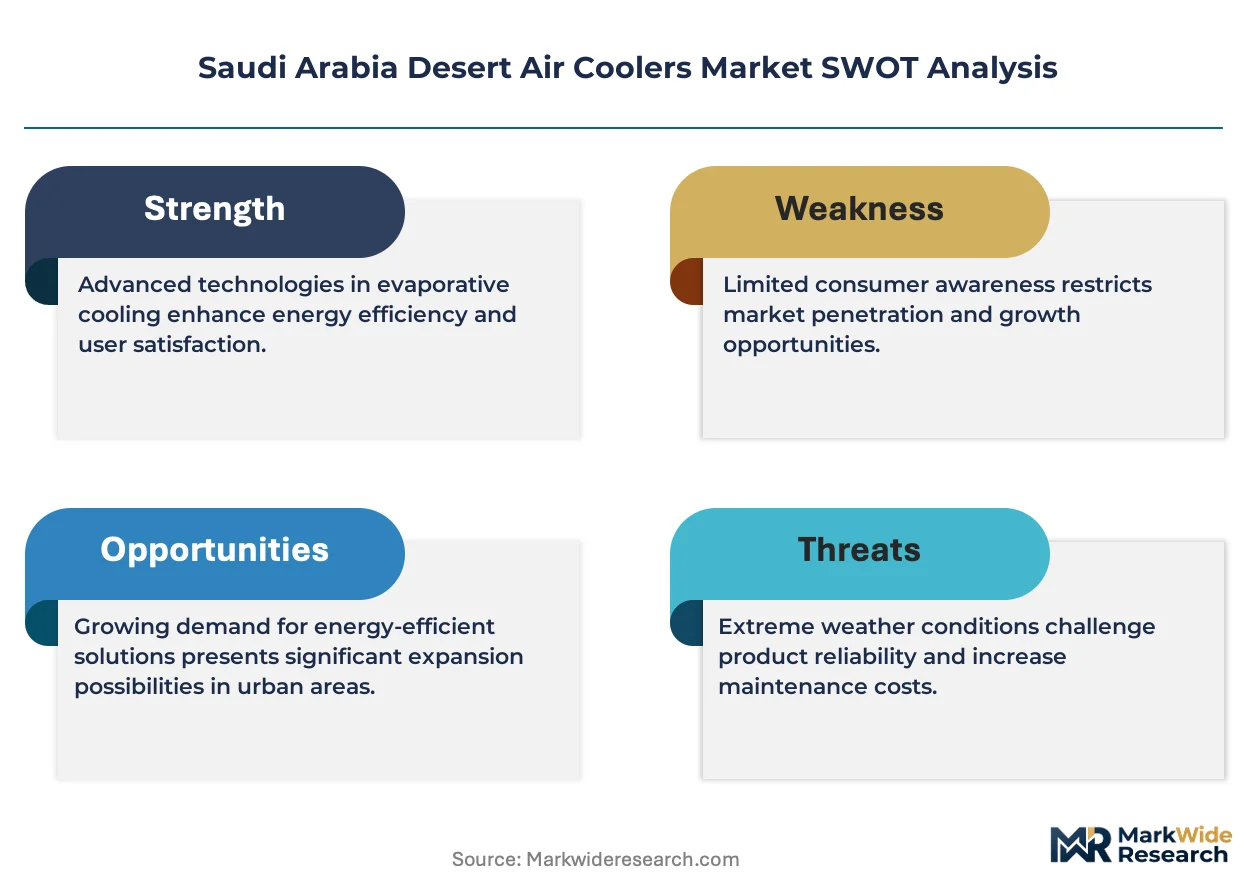
SASO's expanding seasonal efficiency metrics and biodegradability requirements erect compliance moats that favor pre-certified incumbents while raising capital barriers for speculative entrants, transforming market structure around cost-of-compliance capabilities.
For Market Incumbents: Extend predictive maintenance platform deployment to capture facility manager loyalty in Riyadh's commercial tower segment before inverter-driven vapor-compression units with solar compatibility erode the hybrid evaporative value proposition. Deepen backward integration into antimicrobial pad treatment certification to lock in SFDA first-mover advantages as material safety requirements tighten. Prioritize variable-speed pump inventory positioning ahead of anticipated SASO enforcement windows. For New Entrants and Emerging Players: Direct-to-contractor digital platforms offer the lowest-friction route to bypass established distributor control in Asir and Tabuk provinces, where organized retail penetration remains thin and MEP consultants specification authority is rising. Target highland residential compounds with humidity-optimized hybrid systems priced below premium inverter-vapor alternatives. Anchor go-to-market strategy through bulk procurement relationships with King Abdullah Financial District engineering procurement offices. For Investors and Strategic Acquirers: Re-rating potential sits with regional assemblers possessing captive SASO pre-certification pipelines given anticipated margin expansion as enforcement eliminates low-tier import competition. Long-term viability favors manufacturers with demonstrated compliance documentation capabilities and established pad material biodegradability reformulation partnerships. Monitor SFDA antimicrobial treatment approval timelines as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| SASO Pre-Certification Investment | Accelerates product launch timelines and eliminates four-to-six-month third-party laboratory delays. |
| Antimicrobial Pad Treatment Qualification | Secures SFDA material safety approval for water-contact components ahead of competitor submissions. |
| Direct-to-Contractor Platform Development | Bypasses traditional distributor margins in Riyadh's King Abdullah Financial District commercial specifications. |
| Variable-Speed Pump Capacity Expansion | Captures residential replacement demand as electricity tariff restructuring favors efficiency upgrades. |
| Hybrid System Portfolio Extension | Addresses Jeddah coastal humidity limitations that constrain conventional evaporative effectiveness. |
Research Methodology
Multi-period observation of SASO compliance documentation timelines, pad material import lead times, and municipal code enforcement intensity anchored the trend analysis, supplemented by interviews with MEP consultants, facility managers in Riyadh's commercial developments, hypermarket category buyers, and aftermarket service technicians. Secondary validation drew from SASO regulatory filings, SFDA material safety directives, Eastern Province customs records, and municipal building permit databases. Bottom-up shipment data from distribution channels triangulated against top-down energy consumption modeling for evaporative cooling load estimates.
Segment-weighting across product type, application, end user, and technology dimensions structured the analytical framework, with residential portable units, commercial pre-cooling mandates, and smart controller adoption patterns receiving distinct growth trajectory assumptions. CAGRs derived from regression analysis of historical efficiency upgrade cycles and regulatory phase-in schedules. Forecast inputs incorporated electricity tariff restructuring announcements, Ministry of Environment water scarcity advisories, and inverter technology cost curves.
The model holds under stable SASO enforcement timelines and continued grid infrastructure strain; deviation in biodegradability requirement acceleration or vapor-compression solar hybrid cost breakthroughs would shift replacement demand projections. Practitioners should monitor SFDA pad material approval batches and inverter-pump technician training program graduation rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Marine Cooling Systems Market
Cooling Systems
Global Chiller Market
Cooling Systems
Radiant Cooling Systems Market
Cooling Systems
Evaporative Cooling Tower Market
Cooling Systems
Absorption Chillers Market
Cooling Systems
Lithium Battery Liquid Cooling Pump Market
Cooling Systems
North America Evaporative Cooling Market
Cooling Systems
Europe Cooling Systems Market
Cooling Systems
Cryosystem Market
Cooling Systems
Transformer Oil Coolers Market
Cooling Systems
Battery Cooling Plate Market
Cooling Systems
Chilled Water Storage System Market
Cooling Systems
Solar Air Conditioning Market
Cooling Systems
Global Transcritical Co2 Systems Market
Cooling Systems
Adaptive Cooling Fan Market
Cooling Systems
Solar Powered Cold Storage Market