
 Air Source Heat Pump Market | 2026-2036
Air Source Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Air Source Heat Pump Market Analysis
Installer networks and HVAC contractor channels is reconfiguring as manufacturers bypass traditional wholesale distributors to build direct training and certification programs. Daikin Industries Ltd. leverages its captive dealer academy model to lock in specification authority at the contractor level. Mitsubishi Electric Corporation sustains premium positioning through dedicated cold-climate engineering centers in Scandinavia. Carrier Global Corp. competes on bundled service contracts that tie equipment sales to decade-long maintenance agreements.
An air source heat pump extracts ambient thermal energy from outdoor air and transfers it indoors via refrigerant compression cycles, typically achieving coefficient of performance ratings between two and four depending on operating temperature. Split systems dominate retrofit installations where existing ductwork cannot accommodate packaged units, while mini-split systems capture the fastest growth in multifamily buildings lacking central mechanical infrastructure. Smart thermostat integration is concentrating margin pools in control technology, with programmable controls losing ground to connected systems that enable utility demand-response participation.
The EU Green Deal and F-Gas Regulation shape refrigerant transitions and minimum efficiency mandates across European markets, while the EPA in the United States enforces hydrofluorocarbon phase-down schedules that force compressor redesigns. Stakeholders must monitor how building electrification mandates in multiple jurisdictions redefine the competitive boundary between heat pumps and direct electric resistance heating.
Market Dynamics
Refrigerant chemistry transitions under the EU F-Gas Regulation and EPA hydrofluorocarbon phase-downs are forcing compressor redesigns across the entire supply base, compressing development cycles while elevating cold-climate performance certification to a primary procurement filter.
Growth Catalysts
- Building electrification mandates:Multiple jurisdictions now prohibit fossil fuel heating in new construction, creating specification pull for split and mini-split systems in residential retrofits.
- EU Green Deal efficiency thresholds:Minimum performance standards for heating installations in Germany, France, and the Netherlands accelerate replacement cycles for aging boiler stock.
- Cold-climate engineering advances:Expanded operating range compressors maintain coefficient of performance ratings below -15°C, unlocking Nordic housing association procurement.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger materials face commodity price swings that compress equipment margins and destabilize installer quoting.
- Qualified technician scarcity:Refrigerant handling certification requirements in the EU and US limit field workforce expansion, elongating installation backlogs.
- Direct electric resistance substitution:Resistance heating retains capital cost advantage in mild-climate retrofits where operating cost sensitivity remains low.
Strategic Opportunities
- Multifamily building infrastructure gaps:Mini-split systems capture share in apartment blocks lacking central mechanical rooms, particularly in dense Northern European urban cores.
- Utility demand-response integration:Smart thermostat connectivity enables grid-balancing revenue streams that offset equipment premiums for housing associations.
- Service contract bundling:Decade-long maintenance agreements tied to equipment sales generate recurring revenue and lock out competitor replacement cycles.
Industry Challenges
- Refrigerant transition timelines:R-32 and R-290 adoption requires retooling manufacturing lines while managing inventory obsolescence risk for legacy R-410A stock.
- Contractor certification complexity:Manufacturer-direct training programs must scale rapidly to bypass traditional wholesale distributors without fragmenting service quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Source Heat Pump Market |
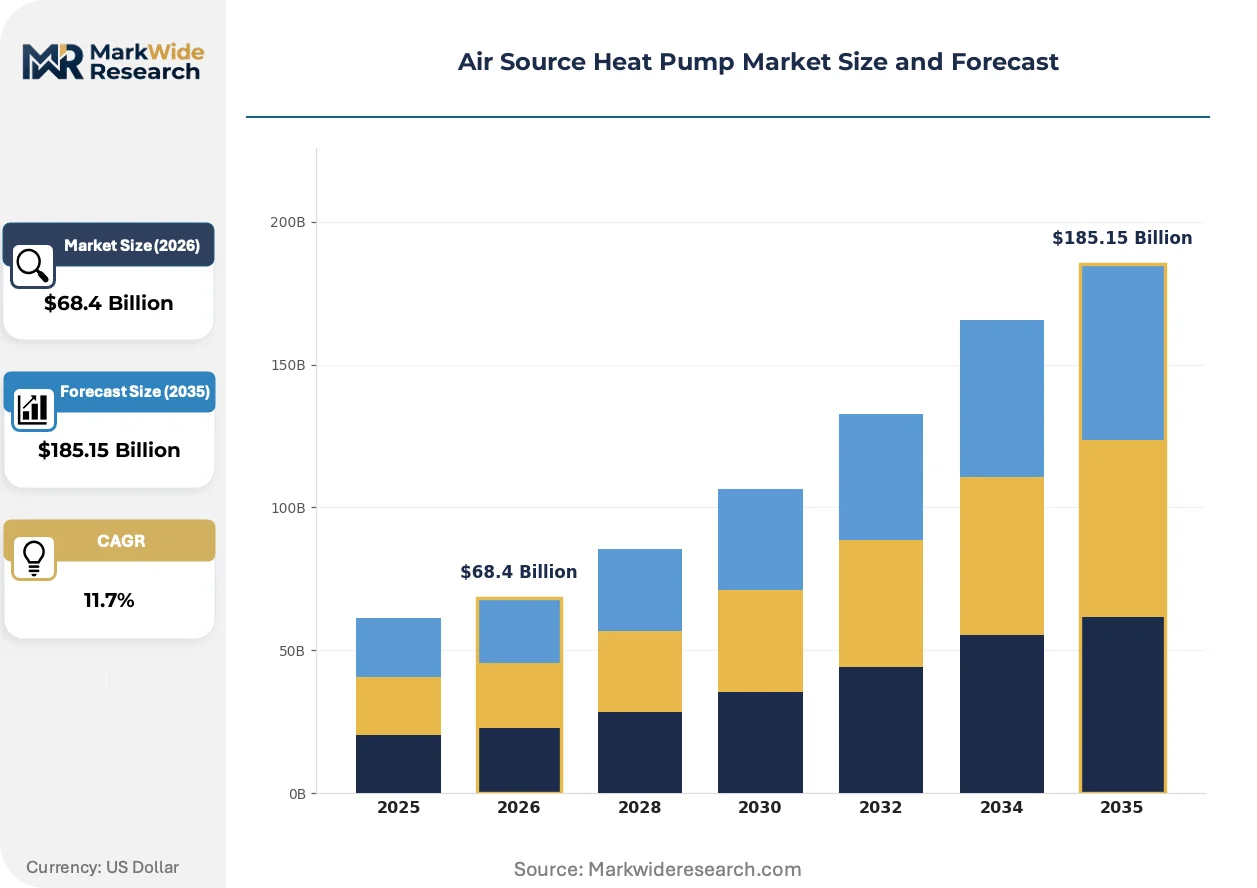
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $185.15 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Split Systems, Mini-Split Systems, Packaged Systems, Ductless Systems Installation Type: Residential, Commercial, Industrial, New Construction Control Technology: Smart Thermostats, Manual Controls, Programmable Controls, Remote Monitoring End User: Homeowners, Contractors, Builders, Facility Managers |
| Companies Covered | Daikin Industries Ltd., Mitsubishi Electric Corporation, Carrier Global Corp., Panasonic Corporation, LG Electronics, Bosch Thermotechnology, A. O. Smith Corporation, NIBE Industrier AB, Fujitsu General Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Source Heat Pump Market Emerging Trajectories
Refrigerant chemistry, control intelligence, and channel configuration are simultaneously transforming how thermal energy is extracted, managed, and monetized across residential and commercial building stock.
Variable-speed inverter compressors with enhanced vapor injection are collapsing the performance penalty historically associated with low-ambient operation. Housing associations in Scandinavia now specify these systems as standard for district heating displacement projects. The technology is collapsing the historical geographic boundary between heat pump viability and resistance heating dominance.
The EPA's hydrofluorocarbon phase-down schedule under the AIM Act forces refrigerant transitions with mandatory GWP reduction targets. Equipment manufacturers must redesign compressor architectures and safety systems for mildly flammable A2L alternatives. Cold-climate product lines face the steepest compliance curves given their reliance on higher charge volumes.
Specification authority is migrating from wholesale distributors to manufacturer-captive dealer networks with direct certification programs. HVAC contractors in Germany and the Netherlands increasingly source through factory academies that bundle training with equipment allocation. This channel compression is most visible in residential retrofit segments where installation quality directly determines warranty exposure and brand reputation.
Air Source Heat Pump Market Segmentation
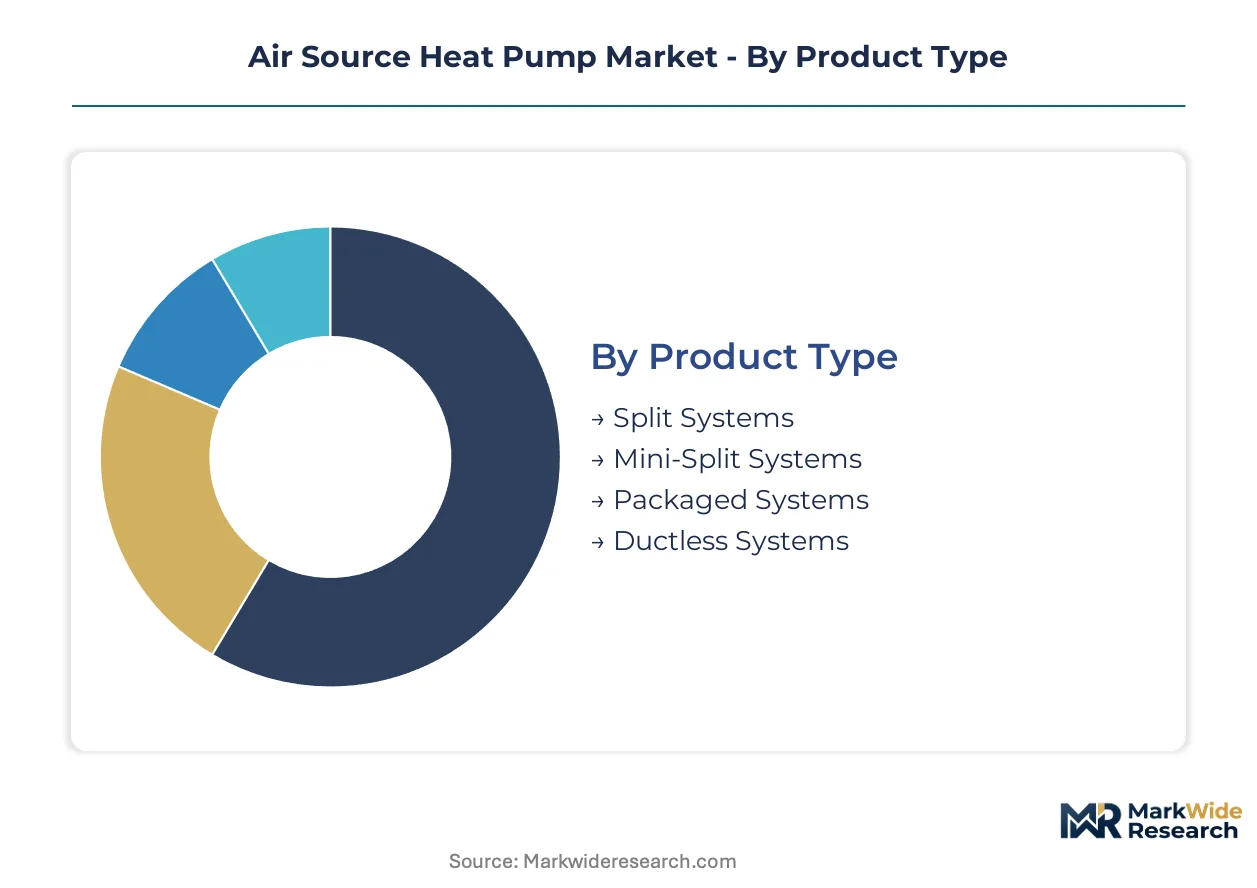
Segmentation in the air source heat pump market determines specification authority, margin capture, and channel strategy. Product architecture dictates installation complexity, while control technology separates premium positioning from commodity competition. Understanding these divides reveals where manufacturers invest in captive training programs versus wholesale distribution.
Product Type:
After-sales service intensity varies sharply across product architectures, with field repair frequency and refrigerant handling complexity driving manufacturer investment in direct technician certification.
- Split Systems:Outdoor compressor units pair with indoor air handlers through refrigerant lines, enabling retrofit installation where existing ductwork remains serviceable. Demand concentrates in German and Dutch residential retrofits where homeowners replace aging natural gas boilers under EU Green Deal efficiency mandates. Cold-climate performance certification from Scandinavian housing associations increasingly filters procurement specifications.
- Mini-Split Systems:Compact refrigerant circuits serve individual zones without duct infrastructure, achieving coefficient of performance ratings above three at ambient temperatures below -15°C. Multifamily buildings in dense Northern European urban cores drive adoption where central mechanical rooms are absent and building electrification mandates prohibit fossil fuel heating.
- Packaged Systems:Self-contained units integrate all components in single outdoor cabinets, requiring minimal indoor footprint.
- Ductless Systems:Wall-mounted or ceiling cassette configurations deliver zoned conditioning without forced-air distribution infrastructure.
By volume, Split Systems lead. By growth pace, Mini-Split Systems is expanding most quickly.
Installation Type:
Cost tier stratification separates capital-light residential replacements from engineered commercial projects with extended performance guarantees.
- Residential:Single-family and multifamily retrofits dominate equipment volume, with homeowners in Germany, France, and the Netherlands replacing fossil fuel boilers under national building code efficiency thresholds. EU F-Gas Regulation refrigerant handling certification limits qualified installer supply, elongating project backlogs.
- Commercial:Office buildings, retail spaces, and hospitality properties specify higher-capacity systems with utility demand-response integration. Facility managers in Nordic markets prioritize cold-climate performance certification for district heating displacement projects.
- Industrial:Process heating and warehouse applications require specialized high-temperature lift configurations.
- New Construction:Building electrification mandates in multiple jurisdictions now prohibit fossil fuel heating, creating specification pull for heat pumps in ground-up development.
Residential captures the largest equipment volume. New Construction is climbing the fastest as electrification mandates expand geographically.
Control Technology:
Margin concentration follows intelligence tier, with connected systems commanding premium positioning over basic programmable alternatives.
- Smart Thermostats:Wi-Fi-enabled controls with machine learning occupancy prediction and utility demand-response participation. Housing associations in Northern Europe specify these for grid-balancing revenue streams that offset equipment premiums.
- Manual Controls:Basic temperature setpoint interfaces without connectivity or scheduling capability.
- Programmable Controls:Time-based scheduling without network connectivity, losing ground to smart alternatives.
- Remote Monitoring:Cloud-based diagnostics enabling predictive maintenance and warranty exposure reduction for manufacturer-captive service networks.
Manual Controls still leads by installed base. Smart Thermostats is gaining share fastest as utility integration requirements harden.
End User:
Customer type determines channel configuration, with specification authority migrating from wholesale distributors to manufacturer-direct training programs.
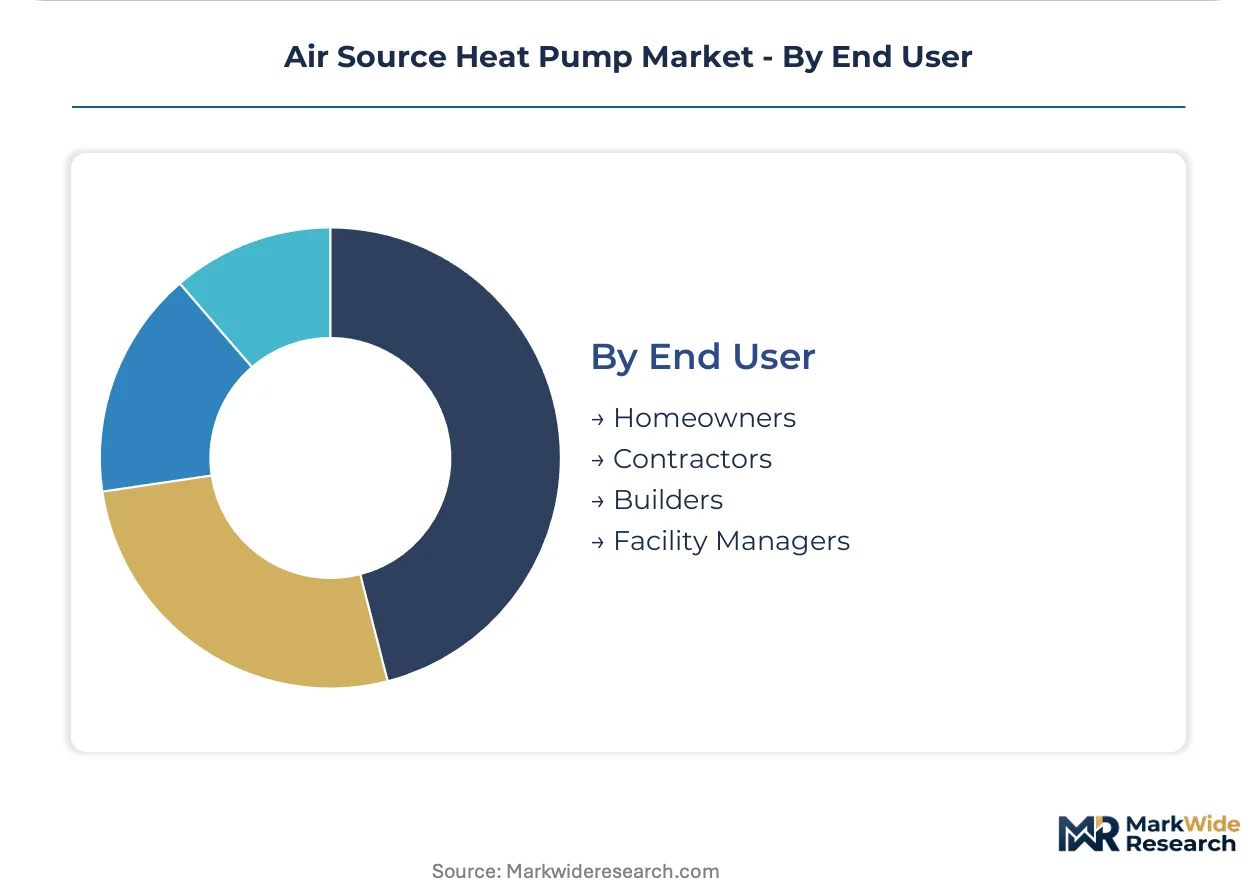
- Homeowners:Individual purchasers rely on contractor recommendations and cold-climate performance certification for Nordic climate zones. Financing through utility-sponsored programs accelerates replacement cycles.
- Contractors:HVAC installation firms increasingly source through factory academies that bundle training with equipment allocation, particularly in Germany and the Netherlands.
- Builders:New construction developers specify systems to meet building electrification mandates and efficiency thresholds.
- Facility Managers:Commercial and institutional operators prioritize decade-long service contracts tied to equipment sales.
Contractors drive the highest transaction volume. Facility Managers is expanding most quickly through bundled service contract adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's building electrification mandates and national efficiency thresholds in Germany, France, and the Netherlands accelerate replacement cycles for fossil fuel heating systems. Cold-climate performance certification from Scandinavian housing associations increasingly filters procurement specifications across Northern Europe.
Germany
Residential retrofits dominate equipment volume as homeowners replace aging natural gas boilers under national building code efficiency thresholds. The Federal Ministry for Economic Affairs and Climate Action enforces minimum performance standards through the Building Energy Act. Installers in the Rhine-Ruhr metropolitan region source increasingly through manufacturer-direct training academies that bundle certification with equipment allocation.
France
Multifamily buildings in dense urban cores drive mini-split adoption where central mechanical rooms are absent and electrification mandates prohibit fossil fuel heating. The French Agency for Ecological Transition administers subsidy programs through MaPrimeRénov that accelerate replacement cycles. Housing associations in the Paris metropolitan area specify cold-climate certified systems for district heating displacement projects.
Netherlands
Contractor networks reconfigure as manufacturers bypass traditional wholesale distributors to build direct certification programs for refrigerant handling under EU F-Gas Regulation. The national government enforces building electrification mandates that prohibit fossil fuel heating in new construction. Installers in the Randstad conurbation concentrate specification authority through factory academy relationships.
Sweden
Scandinavian housing associations prioritize expanded operating range compressors that maintain coefficient of performance ratings below -15°C. The Swedish Energy Agency certifies cold-climate performance standards that filter procurement for district heating displacement. Manufacturers operate dedicated engineering centers in Stockholm and Gothenburg to lock in specification authority at the contractor level.
United States
Utility demand-response integration concentrates margin pools in control technology as smart thermostats enable grid-balancing revenue streams. The EPA enforces hydrofluorocarbon phase-down schedules under the AIM Act that force compressor redesigns for A2L refrigerant alternatives. HVAC contractors in the Northeast corridor face elongated installation backlogs due to refrigerant handling certification requirements limiting qualified technician supply.
Air Source Heat Pump Market Vendor Landscape
On the supply side, the industry is consolidating around manufacturer-captive dealer networks that compress traditional wholesale distribution channels. Japanese and European industrial conglomerates anchor premium positioning through dedicated cold-climate engineering centers. Three strategic archetypes dominate: integrated HVAC conglomerates with captive training academies, specialized heat pump engineering firms with Nordic market focus, and diversified electronics manufacturers leveraging smart control integration. Competitive moves concentrate on direct technician certification programs and decade-long service contract bundling.
Within the integrated HVAC tier, Daikin Industries Ltd. and Mitsubishi Electric Corporation exemplify manufacturer-direct channel strategies. Carrier Global Corp. occupies a position emphasizing bundled service relationships. These three anchors represent divergent approaches to contractor-level specification authority.
| Leading Market Players |
|---|
| Daikin Industries Ltd. |
| Mitsubishi Electric Corporation |
| Carrier Global Corp. |
| Panasonic Corporation |
| LG Electronics |
| Bosch Thermotechnology |
| A. O. Smith Corporation |
| NIBE Industrier AB |
| Fujitsu General Ltd. |
| Others |
Supply Flow & Price Mechanics
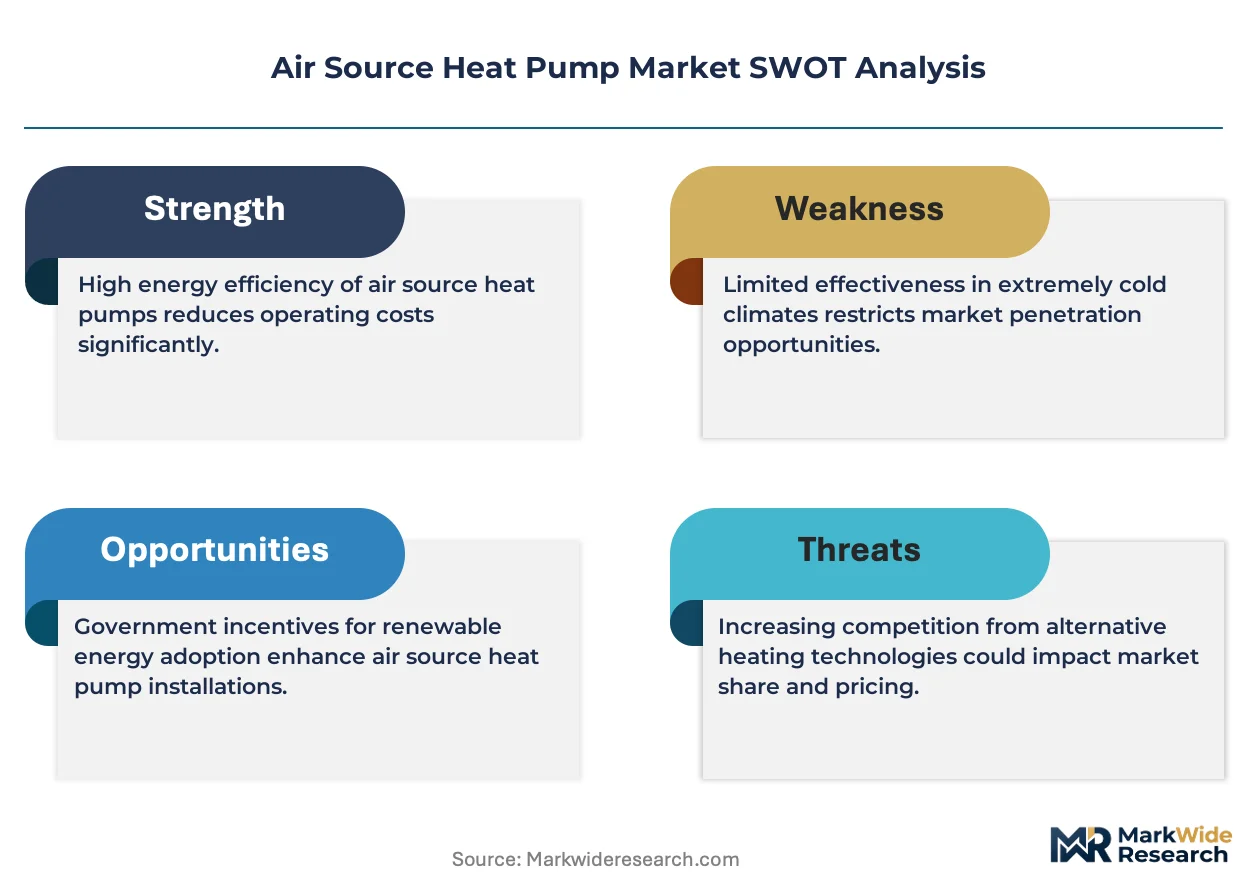
Copper and aluminum commodity volatility compresses equipment margins while simultaneously dictating supply chain geography toward countries with integrated metal processing. This input-cost instability widens pricing spreads between cold-climate certified premium tiers and standard efficiency economy offerings, forcing manufacturers to anchor production in jurisdictions with tariff-advantaged raw material access.
Pricing Analysis
Cold-climate performance certification creates the primary spread between premium and standard equipment tiers, with Scandinavian housing association procurement standards filtering contractor specifications. Pricing stratifies across premium, standard, and economy tiers based on coefficient of performance ratings below -15°C and smart thermostat integration depth. Cost compression in economy segments intensifies because direct electric resistance heating retains capital cost advantage in mild-climate retrofits. Homeowners in Germany and the Netherlands exhibit highest price sensitivity, while facility managers prioritizing decade-long service contracts show lowest.
Supply Chain Analysis
Contract manufacturing for compressor assemblies concentrates among Japanese and South Korean industrial conglomerates with captive foundry capacity. Component sourcing draws from China for heat exchanger aluminum, Germany for precision valve assemblies, and Japan for variable-speed inverter drives. Single-source vulnerability sits with rare earth magnet suppliers for high-efficiency compressor motors. Distribution runs through manufacturer-direct training academies that bypass traditional wholesale channels in Northern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart thermostat interoperability protocols are collapsing equipment-control boundaries into unified home energy platforms, redefining competitive moats around data integration rather than hardware performance alone.
For Market Incumbents: Build certification authority moats through expanded cold-climate engineering centers in Scandinavia that lock contractor specification loyalty. Deepen backward integration into refrigerant handling training programs to capture installer channel control before EU F-Gas Regulation enforcement tightens. Compressor redesign cycles for A2L refrigerant transitions represent the critical threat window requiring preemptive R&D allocation. For New Entrants and Emerging Players: Pursue multifamily building infrastructure gaps in dense Northern European urban cores where central mechanical rooms are absent and electrification mandates create specification pull. Target mini-split system penetration in French apartment blocks lacking duct infrastructure, leveraging utility demand-response integration as the primary go-to-market angle against established split-system incumbents. For Investors and Strategic Acquirers: EPA hydrofluorocarbon phase-down schedules under the AIM Act reshape the acquisition landscape toward compressor engineering specialists with A2L refrigerant safety system expertise. Long-term viability centers on manufacturers with demonstrated cold-climate certification traction and captive dealer academy scale. Monitor refrigerant transition timeline adherence as the critical inflection signal for inventory obsolescence risk versus compliance premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturer-Direct Training Academy Expansion | Captures contractor specification authority in Germany and Netherlands by bundling EU F-Gas certification with equipment allocation. |
| Cold-Climate Engineering Center Establishment | Locks Scandinavian housing association procurement through demonstrated coefficient of performance maintenance below -15°C. |
| Smart Thermostat Platform Integration | Enables utility demand-response revenue streams that offset equipment premiums for Northern European housing associations. |
| Decade-Long Service Contract Bundling | Generates recurring revenue while blocking competitor replacement cycles in commercial facility manager segments. |
| A2L Refrigerant Compressor Redesign | Ensures EPA AIM Act compliance while managing safety system complexity for higher-charge cold-climate product lines. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with HVAC contractors, housing association procurement directors, refrigerant handling technicians, and utility demand-response program managers. Secondary validation drew from EPA AIM Act filings, EU F-Gas Regulation implementation guidance, EIA building electrification trend data, and national building code efficiency threshold documentation. Bottom-up equipment shipment analysis triangulated against top-down energy consumption modeling across the projection horizon.
Calibration anchored volume and value outputs to segmented adoption curves across product architecture, installation type, control technology tier, and end-user category. Coefficient of performance degradation curves at low ambient temperatures and refrigerant charge volume constraints for A2L alternatives served as industry-specific forecast inputs. CAGRs were derived through logistic diffusion modeling of replacement cycle acceleration under electrification mandate expansion.
Sensitivities concentrate around copper and aluminum commodity price trajectories, qualified technician certification bottleneck resolution timelines, and cold-climate performance standard harmonization across Scandinavian housing associations. Quarterly review of installer backlog duration, refrigerant transition inventory ratios, and utility demand-response enrollment rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Solar Powered Cold Storage Market
Cooling Systems
Cold Climate Air Source Heat Pump Market
Cooling Systems
Solar Cooling Market
Cooling Systems
Thermosiphon Cooling System Market
Cooling Systems
Europe Air Source Heat Pump Market
Cooling Systems
Offshore Air Handling Units Market
Cooling Systems
District Heating and Cooling Market
Cooling Systems
Solar Air Conditioning Market
Cooling Systems
Adaptive Cooling Fan Market
Cooling Systems
Thawing System Market
Cooling Systems
Chilled Water Storage System Market
Cooling Systems
Annular Cooler Market
Cooling Systems
Global Evaporative Cooler Market
Cooling Systems
Heat Pump Dryer Market
Cooling Systems
North America Evaporative Cooling Market
Cooling Systems
Solar Ventilation Systems Market