
 Air to Air Heat Pumps Sales Market | 2026-2036
Air to Air Heat Pumps Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Air to Air Heat Pumps Sales Market Insights
Utility-led residential electrification programs is consolidating procurement authority across North American and European municipal housing authorities. Daikin Industries leverages its captive compressor manufacturing to control cost curves across inverter-driven ductless lines. Carrier Global anchors its position through deep contractor-channel relationships in commercial replacement cycles. Mitsubishi Electric specializes in cold-climate performance engineering, sustaining premium positioning in sub-zero operational zones.
Air to air heat pumps transfer thermal energy between indoor and outdoor ambient air via vapor-compression refrigeration cycles, typically achieving coefficient of performance ratings between three and five under moderate conditions. The equipment serves primary space conditioning loads in residential, commercial, and light-industrial envelopes where combustion-based heating faces carbon-cost or regulatory displacement. Split systems dominate installed base volumes across temperate zones, while ductless mini-split configurations capture fastest-growing share in retrofit-intensive European and Northeast US housing stock where central ductwork is absent. Inverter technology leads technology segment value pools by enabling variable-speed modulation that reduces cycling losses and extends seasonal performance factors.
EPA regulations in the United States restrict high-global-warming-potential refrigerants in new equipment, while the EU F-Gas Regulation mandates stepped HFC phase-downs that reshape product roadmaps for export-oriented manufacturers. CE marking under the Ecodesign Directive and evolving MEPS tiers in multiple jurisdictions compress market access for sub-threshold efficiency performers. Stakeholders must monitor refrigerant-transition timelines and cold-climate certification protocols as these dual technical gates determine competitive viability across the next replacement supercycle.
Market Dynamics
The refrigerant transition mandated by the EU F-Gas Regulation and comparable EPA phase-down rules is compressing product development cycles and forcing manufacturers to retool compressor architectures around lower-GWP alternatives ahead of equipment replacement supercycles.
Growth Catalysts
- Residential electrification mandates:Municipal housing authorities in Germany and the United States are consolidating procurement authority through utility-led retrofit programs that specify heat pump-first replacement protocols for aging oil and gas heating systems.
- Cold-climate performance certification:The Northeast Energy Efficiency Partnerships' Cold Climate Heat Pump specification is unlocking rebate eligibility across Massachusetts, Vermont, and New York, accelerating sub-zero-rated equipment deployment.
- Inverter modulation advances:Variable-speed compressor controls are extending seasonal performance factors beyond legacy fixed-speed baselines, reducing cycling losses in part-load conditions common to European housing stock.
Market Restraints
- Copper and rare-earth price volatility:Compressor winding materials and permanent-magnet motors face input cost pressure from concentrated Chinese processing capacity, squeezing margin structures on mid-tier product lines.
- Refrigerant supply fragmentation:The R-32 and R-290 transition requires dedicated handling protocols and separate distribution infrastructure, creating working capital intensity for distributors managing dual-inventory positions.
- Installer capacity constraints:Qualified refrigeration technicians represent a bottleneck in Nordic markets where oil-to-heat-pump substitution programs have compressed project timelines below training pipeline output.
Strategic Opportunities
- Polish and Romanian housing retrofits:EU Recovery and Resilience Facility allocations for building efficiency are concentrating procurement in Eastern European markets with underpenetrated heat pump installed bases and legacy coal-dependent heating.
- Hybrid heat pump-gas configurations:Bivalent systems pairing air-source units with existing condensing boilers are capturing retrofit demand in UK housing stock where full electrification faces distribution panel upgrade barriers.
- Utility demand-response integration:Grid-interactive water heaters and space conditioning loads are qualifying for capacity market payments in PJM and ISO-NE territories, creating hardware-plus-software service bundles.
Industry Challenges
- Cold-climate certification lag:Third-party testing capacity for sub-zero performance validation is concentrated in limited laboratory facilities, extending product launch timelines by 8-14 months for new refrigerant architectures.
- Legacy control system incompatibility:Integration with existing building management protocols in commercial replacement cycles requires protocol translation hardware that adds cost and commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air to Air Heat Pumps Sales Market |
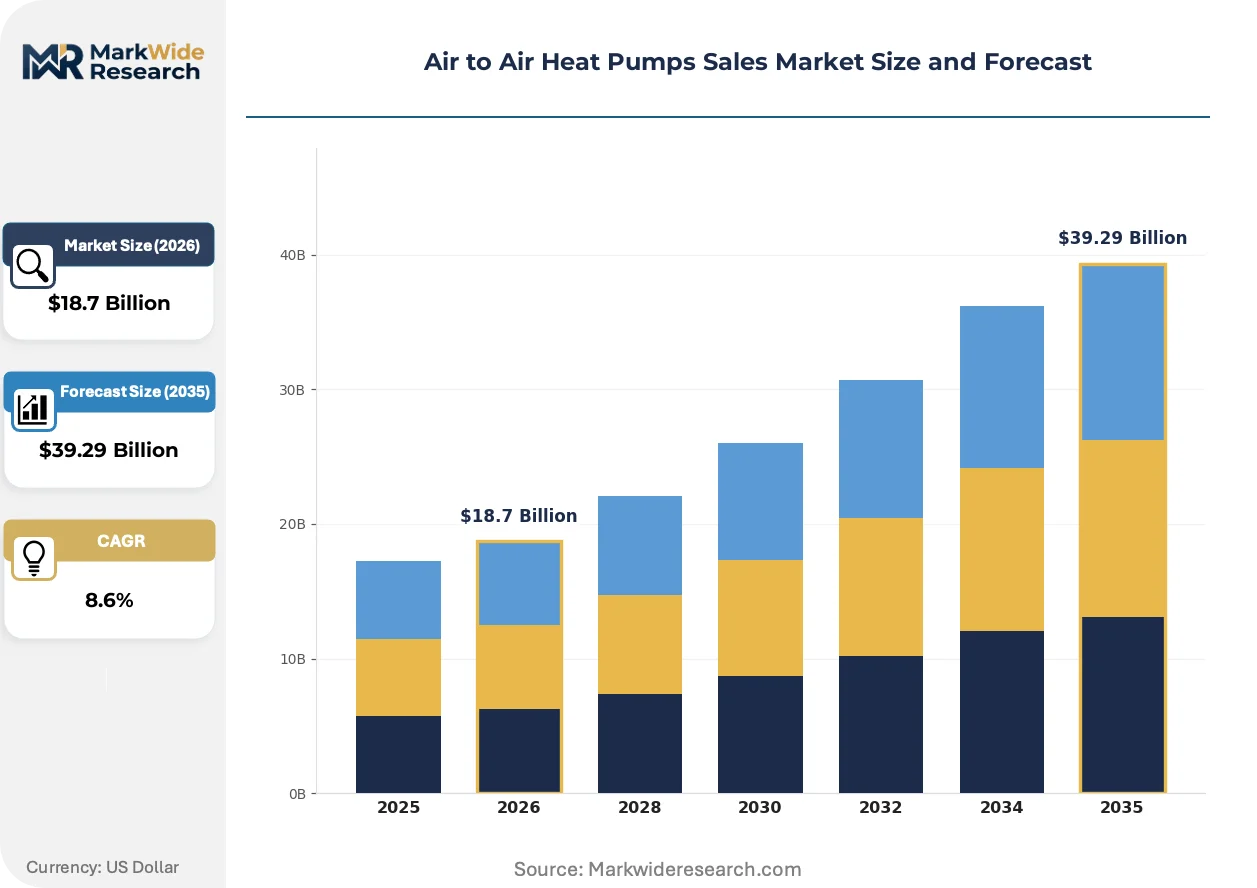
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Split System, Packaged System, Multi-Split System, Ductless Mini-Split End User: Residential, Commercial, Industrial, Institutional Distribution Channel: Direct Sales, Retail, Online, Distributors Technology: Inverter Technology, Traditional Compression, Hybrid Systems, Smart Thermostats |
| Companies Covered | Daikin Industries, Carrier Global, Trane Technologies, LG Electronics, Panasonic Corporation, Fujitsu General, Mitsubishi Electric, Lennox International, Rheem Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air to Air Heat Pumps Sales Market Trends and Innovations
Refrigerant chemistry transitions and connected-system architectures are compressing traditional equipment replacement cycles while opening new service-revenue pools around predictive maintenance and grid-interactive load management.
R-290 propane refrigerant is decentralizing product architecture decisions across European manufacturers. Daikin and Panasonic have retooled their Czech and Malaysian compressor lines for flammable-refrigerant handling. The technology is decentralizing supply chain geography by enabling smaller charge sizes that reduce shipping weight constraints and open regional assembly options previously uneconomical for high-GWP alternatives.
The EPA's Technology Transitions Program under the AIM Act mandates phased HFC restrictions for residential and commercial air conditioning. Equipment manufacturers must certify new products to UL 60335-2-40 fire safety standards for A2L mildly flammable refrigerants. The segment most affected—ducted split systems for new US residential construction—is responding with accelerated R-454B qualification timelines and dealer training investments ahead of 2025 effective dates.
Aggregated procurement through housing authority frameworks is displacing traditional distributor-led specification in multifamily retrofit segments. Massachusetts and New York energy agencies now contract directly with manufacturers for volume pricing on cold-climate-certified equipment, bypassing wholesale channels. This pattern is most visible in Northeast US public housing authorities where federal weatherization funding streams require documented cost-per-ton efficiency thresholds.
Air to Air Heat Pumps Sales Market Segmentation
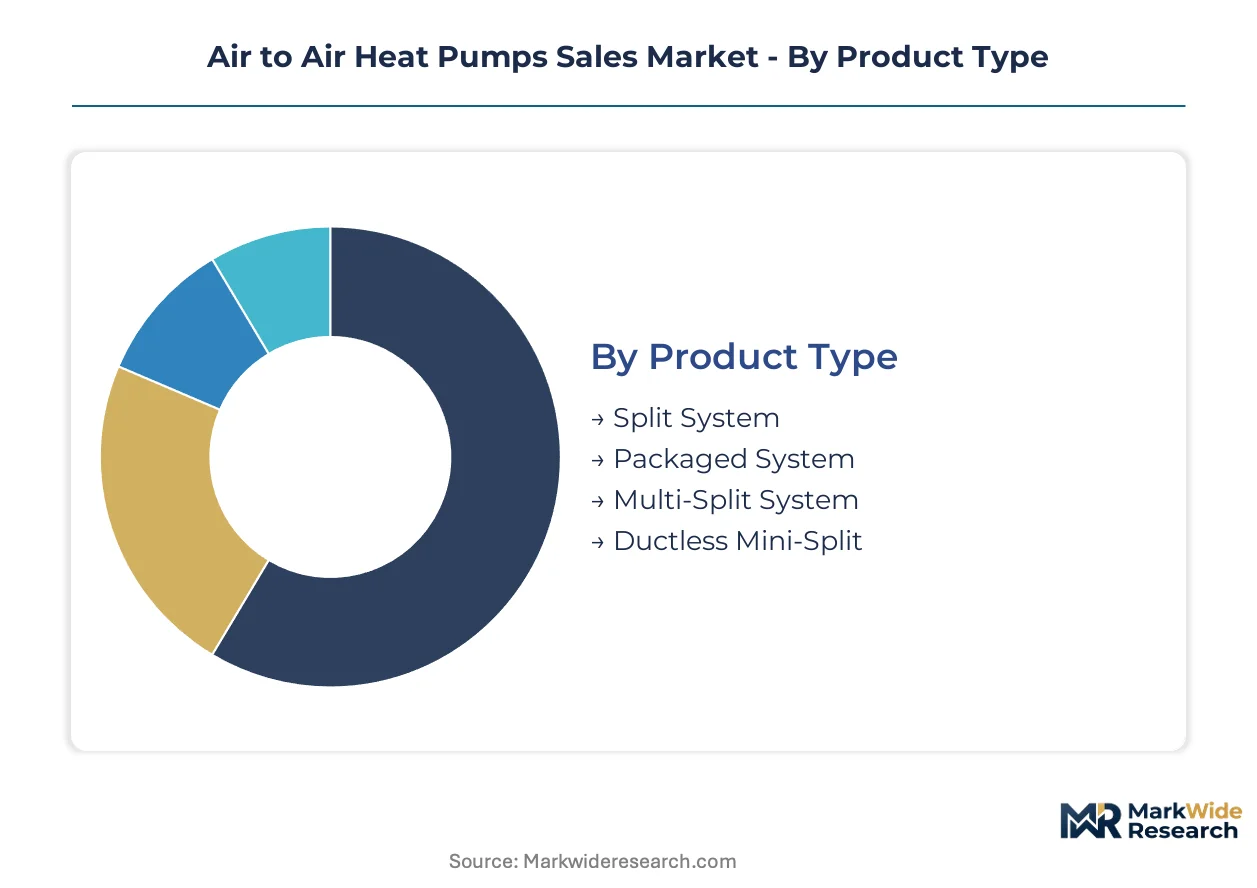
Segmentation reveals how electrification mandates and refrigerant transitions concentrate value across distinct equipment configurations. Procurement patterns diverge sharply between utility-led bulk programs and contractor-driven replacement cycles, reshaping channel economics.
Product Type:
Volume concentrates in legacy split configurations, while premium capture shifts toward refrigerant-flexible architectures with smaller charge sizes.
- Split System:Dominates installed base across temperate climate zones with separate indoor and outdoor coil assemblies. Demand clusters in Germany and the United States where utility retrofit programs specify standard-efficiency replacements for aging oil furnaces.
- Ductless Mini-Split:Variable-speed inverter modulation eliminates distribution losses in buildings lacking central ductwork. Northeast US public housing authorities and Nordic residential retrofits drive fastest expansion as cold-climate certification unlocks rebate eligibility.
- Packaged System:Self-contained rooftop units serve light commercial envelopes with limited mechanical space.
- Multi-Split System:Single outdoor compressor feeds multiple indoor zones, reducing refrigerant charge per conditioned area.
Today's leader: Split System. Tomorrow's challenger: Ductless Mini-Split.
End User:
Residential procurement authority is consolidating through municipal housing frameworks, while commercial replacement cycles remain contractor-mediated.
- Residential:Single-family and multifamily dwellings account for dominant volume as electrification mandates displace combustion heating. Massachusetts and New York energy agencies contract directly with manufacturers for cold-climate-certified equipment, bypassing wholesale channels.
- Commercial:Office, retail, and hospitality envelopes drive replacement demand through deep contractor relationships. The segment faces legacy control system incompatibility requiring protocol translation hardware that adds commissioning complexity.
- Industrial:Light manufacturing and warehouse applications specify high-capacity packaged units with minimal downtime tolerance.
- Institutional:Schools, hospitals, and government facilities prioritize redundancy and extended warranty coverage.
Residential commands current volume. Commercial offers higher margin capture per project.
Distribution Channel:
Channel structure fragments between consolidated procurement frameworks and traditional wholesale relationships.
- Distributors:Maintain inventory depth and installer training networks across fragmented contractor bases. The R-32 and R-290 transition creates working capital intensity as distributors manage dual-inventory positions with separate handling protocols.
- Direct Sales:Manufacturers bypass wholesale tiers for volume contracts with housing authorities and utility programs. This pattern concentrates in Northeast US public housing authorities where federal weatherization funding requires documented efficiency thresholds.
- Retail:Big-box and specialty HVAC retailers serve homeowner self-directed replacement and emergency repair demand.
- Online:E-commerce platforms capture specification research and price transparency, though final purchase often converts through installer referral.
Distributors retain installer relationships. Direct sales gain share fastest in consolidated procurement markets.
Technology:
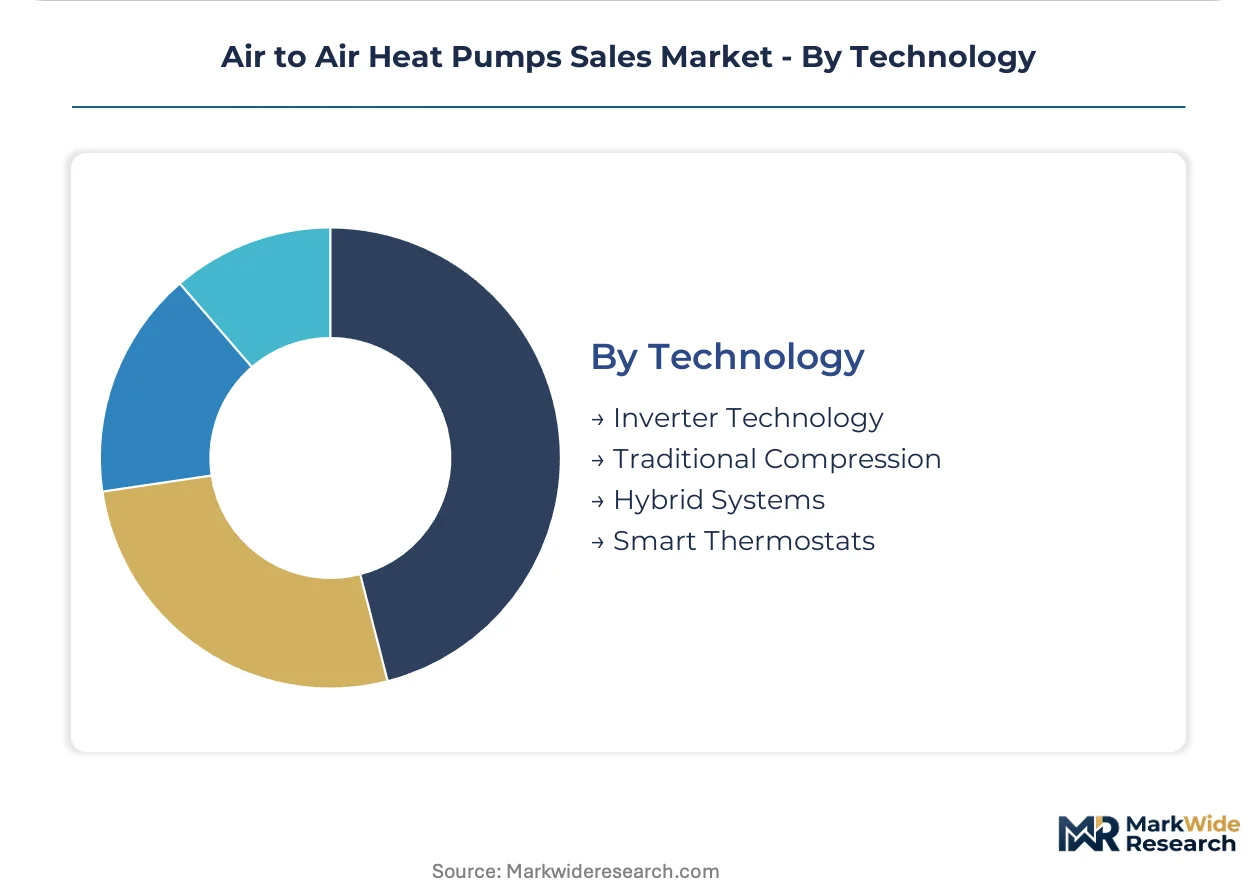
Performance differentiation centers on modulation capability and grid-interactive control architecture.
- Inverter Technology:Variable-speed compressor controls reduce cycling losses and extend seasonal performance factors beyond fixed-speed baselines. Cold-climate performance engineering enables sub-zero operational zones where Mitsubishi Electric and comparable specialists sustain premium positioning.
- Smart Thermostats:Grid-interactive load management qualifies for capacity market payments in PJM and ISO-NE territories, creating hardware-plus-software service bundles around predictive maintenance and demand-response integration.
- Traditional Compression:Fixed-speed systems retain cost advantage in price-sensitive replacement markets with moderate climate loads.
- Hybrid Systems:Bivalent configurations pair air-source units with existing condensing boilers, capturing UK retrofit demand where full electrification faces distribution panel upgrade barriers.
Inverter Technology leads value pools. Smart Thermostats define emerging service revenue architecture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified refrigeration technicians cluster in Germany's Ruhr industrial corridor, Japan's Chubu manufacturing belt, and the Northeast US mechanical trades apprenticeship networks, anchoring installation capacity for electrification retrofit programs.
United States
Massachusetts and New York public housing authorities consolidate procurement through direct manufacturer contracts for cold-climate-certified equipment. The EPA's Technology Transitions Program under the AIM Act mandates HFC phase-downs with 2025 effective dates for residential ducted systems. Installer training pipelines in Greater Boston lag behind compressed project timelines from federal weatherization funding streams.
Germany
Utility-led retrofit programs specify heat pump-first replacement protocols for aging oil heating systems in single-family housing stock. The EU F-Gas Regulation drives R-32 and R-290 transitions across domestic product roadmaps. Bavaria's industrial machinery corridor hosts compressor retooling investments for flammable-refrigerant handling protocols.
China
Concentrated rare-earth processing capacity in Jiangxi and Inner Mongolia supplies permanent-magnet motors for inverter compressors. The country's dual carbon goals accelerate building electrification mandates in northern heating zones. Yangtze River Delta manufacturing clusters dominate export-oriented production for European and North American markets.
Japan
METI efficiency standards and cold-climate performance engineering sustain premium positioning for sub-zero operational zones. Chubu region compressor manufacturing anchors captive production for variable-speed modulation systems. Tokyo's metropolitan housing stock drives ductless mini-split demand in high-density retrofit applications.
Poland
EU Recovery and Resilience Facility allocations concentrate procurement in Eastern European markets with underpenetrated installed bases. The country's national building efficiency regulator channels funding away from legacy coal-dependent heating. Warsaw and Krakow municipal housing authorities pilot aggregated procurement frameworks bypassing traditional wholesale channels.
Air to Air Heat Pumps Sales Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidated procurement authority in utility-led programs favors scale-driven manufacturers with captive compressor production and direct sales capabilities. Three archetypes dominate: integrated refrigerant-to-system conglomerates with backward control over compressor architectures; regional specialists in cold-climate performance engineering; and contract manufacturers serving private-label distributors. Competitive moves center on refrigerant-transition certification racing and direct procurement framework penetration.
Within the integrated conglomerate tier, Daikin Industries and Carrier Global occupy positions defined by captive manufacturing depth and channel control. Daikin exemplifies backward integration into compressor production, enabling cost curve management across inverter-driven lines. Carrier anchors its position through contractor-channel relationships in commercial replacement cycles. Mitsubishi Electric sits within the cold-climate specialist archetype, representing premium positioning in sub-zero operational zones through performance engineering differentiation.
| Leading Market Players |
|---|
| Daikin Industries |
| Carrier Global |
| Trane Technologies |
| LG Electronics |
| Panasonic Corporation |
| Fujitsu General |
| Mitsubishi Electric |
| Lennox International |
| Rheem Manufacturing |
| Others |
Pricing and Supply Chain Analysis
R-290 propane refrigerant transitions are compressing compressor architectures toward smaller charge sizes that simultaneously reduce material costs and enable regional assembly decentralization. This dual effect fragments traditional pricing power held by high-volume manufacturers while opening margin capture for mid-tier players with flexible production footprints.
Pricing Analysis
Bundled hardware-plus-installation contracts dominate residential retrofit segments while unbundled equipment-only transactions persist in commercial replacement cycles. Three-tier pricing structure across premium cold-climate-certified, standard inverter-modulated, and economy fixed-speed levels reflects certification grade and seasonal performance factor differentiation. Cost compression in mid-tier inverter lines is intensifying because Chinese rare-earth processing concentration feeds permanent-magnet motor price volatility. Public housing authorities demonstrate lowest price sensitivity through consolidated procurement frameworks, while independent residential contractors face acute margin pressure from refrigerant inventory carrying costs.
Supply Chain Analysis
Reverse-logistics flows for compressor core returns and refrigerant recovery equipment are creating secondary value pools around remanufactured components and certified reclaimed gas. Manufacturing gravity centers on China's Yangtze River Delta for export-oriented production, Germany's Bavarian industrial corridor for European market serving, and Japan's Chubu region for captive compressor technology. Permanent-magnet motors draw from concentrated Jiangxi rare-earth processing, copper windings hinge on Chilean concentrate flows, and aluminum heat exchangers rest on Chinese smelter output. Single-source vulnerability in rare-earth magnet supply creates structural exposure to export restriction risk. Distribution runs through fragmented wholesale networks with dedicated refrigerant handling protocols alongside direct manufacturer contracts with utility-led procurement programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air-to-air heat pumps sales market represents a late-cycle quality story where electrification mandates and refrigerant transitions concentrate procurement authority toward premium cold-climate-certified specifications. Demand is shifting from standard-efficiency replacements toward sub-zero-rated equipment with documented seasonal performance factors.
For Market Incumbents: Anticipate margin compression from R-32 and R-290 handling infrastructure investments by securing captive compressor production capacity in flammable-refrigerant-certified facilities. Defensive consolidation through direct procurement framework penetration with Massachusetts and New York housing authorities offsets distributor channel displacement. Cold-climate certification racing against Mitsubishi Electric's performance engineering specialization represents the priority defensive lever. For New Entrants and Emerging Players: The premium-to-economy price gap in Nordic oil-to-heat-pump substitution programs creates white-space entry around mid-tier inverter systems with simplified installation protocols. Polish and Romanian municipal housing retrofits offer the most penetrable geography given EU Recovery and Resilience Facility funding concentration and underpenetrated installed bases. A contractor-training-centric go-to-market angle addresses installer capacity constraints that bottleneck incumbent fulfillment timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among regional cold-climate specialists with proprietary compressor modulation technology and limited brand recognition outside Nordic markets. Long-term viability framing centers on refrigerant-transition completion and grid-interactive control architecture integration as equipment becomes energy system infrastructure. The signal to watch is Northeast Energy Efficiency Partnerships specification expansion into additional US states as inflection indicator for premium tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Architecture Retooling | R-290 compressor line investments in Czech and Malaysian facilities enable EU F-Gas Regulation compliance ahead of competitor timelines. |
| Cold-Climate Certification Expansion | Third-party laboratory capacity expansion reduces product launch timelines for sub-zero-rated equipment in Northeast US markets. |
| Direct Procurement Framework Penetration | Bypassing wholesale channels with Massachusetts and New York housing authorities captures volume pricing and displaces distributor relationships. |
| Installer Training Pipeline Development | Refrigeration technician certification programs in Greater Boston and Nordic markets address bottleneck constraints on project fulfillment. |
| Grid-Interactive Control Integration | Hardware-plus-software bundles qualifying for PJM and ISO-NE capacity market payments create recurring revenue streams beyond equipment sales. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary field engagement with HVAC equipment manufacturers, refrigeration technician training program administrators, utility demand-side management officers, and municipal housing authority procurement directors alongside secondary validation through EPA Technology Transitions Program filings, EU F-Gas Regulation implementation reports, Northeast Energy Efficiency Partnerships specification documents, and customs trade data for compressor and heat exchanger imports. Bottom-up equipment shipment analysis and top-down electrification mandate spending trajectories were triangulated against regional installation permit data.
Segment-weighting approaches applied product type, end user category, distribution channel structure, and technology tier dimensions across the modeling period. CAGRs were derived from replacement cycle timing analysis and refrigerant-transition compliance deadlines rather than extrapolation. Forecast inputs incorporated housing stock age profiles, fossil fuel heating system retirement timelines, and cold-climate performance certification penetration curves specific to Nordic and Northeast US markets.
Caveats apply where refrigerant supply fragmentation, rare-earth export restrictions, or installer training pipeline output shortfalls could materially shift the outlook. Practitioners should monitor EPA enforcement timelines for A2L refrigerant handling standards and EU F-Gas Regulation phase-down acceleration proposals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Heat Pump (>100°C) Market
Cooling Systems
District Heating and Cooling Market
Cooling Systems
Saudi Arabia Desert Air Coolers Market
Cooling Systems
Global Air Coolers Market
Cooling Systems
Solar Powered Cold Storage Market
Cooling Systems
Cold Climate Air Source Heat Pump Market
Cooling Systems
Process Chillers Market
Cooling Systems
Evaporative Condensing Unit Market
Cooling Systems
Global Evaporative Cooler Market
Cooling Systems
Critical Power and Cooling Market
Cooling Systems
Cryogenic Systems Market
Cooling Systems
Absorption Chillers Market
Cooling Systems
Solar Refrigerators Market
Cooling Systems
Annular Cooler Market
Cooling Systems
Solar Cooling Market
Cooling Systems
Radiant Cooling Systems Market