
 Water Scooter Market | 2026-2036
Water Scooter Market Size, Share, and Industry Trends Forecast 2026-2036
Water Scooter Market Analysis
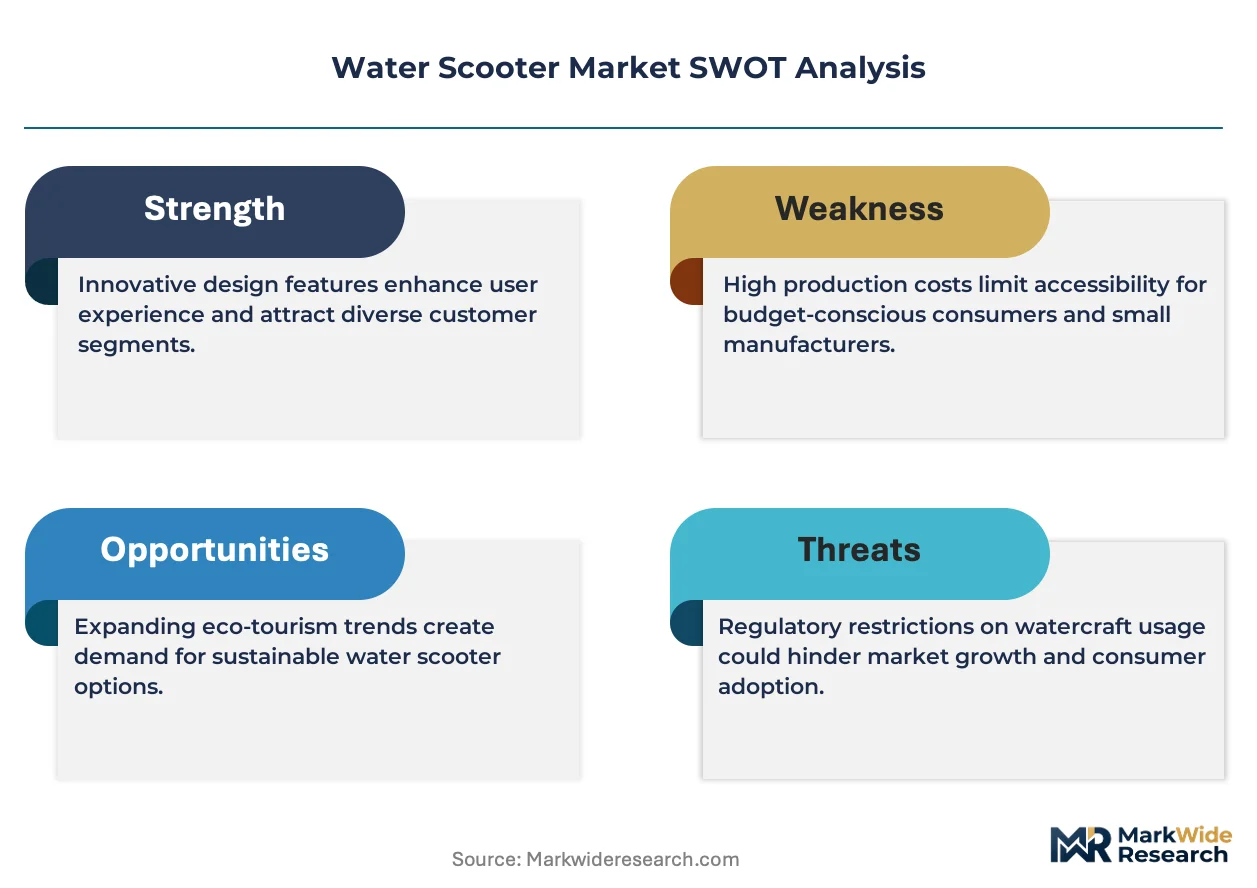
A shift from outsourced engine sourcing to in-house electric powertrain development is repositioning competitive dynamics among water scooter manufacturers. Yamaha Motor Co. Ltd leverages its marine engineering heritage to sustain dominance in gasoline-powered performance segments. Sea-Doo specializes in recreational sit-down platforms with integrated intelligent brake and reverse systems. Bombardier Recreational Products Inc. controls North American distribution networks while navigating the transition toward electrified product lines.
Water scooters are self-propelled personal watercraft designed for surface and limited subsurface operation, typically powered by gasoline internal combustion engines or electric brushless motors generating thrust through axial-flow jet pumps. These vessels serve recreational consumers, commercial rental fleets, and competitive athletes requiring maneuverable, high-power-density marine mobility. Sit-down configurations anchor volume sales across rental services and tourism applications due to passenger stability and lower operator training thresholds. Electric power sources represent the fastest-expanding segment as harbor authorities in coastal municipalities impose emissions restrictions on gasoline-powered craft. Gasoline variants retain margin concentration in competitive racing and high-performance recreational channels where energy density requirements exceed current battery capabilities.
The US Coast Guard enforces flotation and stability standards under 33 CFR while the EPA regulates marine engine emissions through Tier 3 certification requirements, compelling manufacturers to redesign combustion architectures or accelerate electric alternatives. The EU Green Deal and F-Gas Regulation pressure European operators to eliminate fluorinated greenhouse gas refrigerants in cooling systems and adopt zero-emission propulsion in designated marine protected areas. Stakeholders must monitor evolving port authority electrification mandates and battery recycling compliance obligations as regulatory frameworks tighten across major recreational boating jurisdictions.
Market Dynamics
Electric powertrain migration is absorbing capital allocation and engineering talent across water scooter manufacturers, compressing development cycles for gasoline platforms while expanding battery integration capabilities.
Growth Catalysts
- Marine Protected Area Mandates:The EU Green Deal and F-Gas Regulation are compelling fleet operators in Greece, Spain, and Italy to phase out gasoline-powered craft in coastal zones.
- Lithium-Ion Density Gains:Energy storage improvements are extending operational range for electric platforms, enabling rental operators to serve full-day tourism itineraries without mid-trip charging.
- Coastal Tourism Recovery:Mediterranean destination visitation is accelerating fleet procurement by commercial rental services seeking capacity expansion.
Market Restraints
- Battery Pack Cost Structure:Lithium carbonate price volatility and cathode material sourcing constraints inflate electric platform manufacturing costs relative to gasoline equivalents.
- Charging Infrastructure Gaps:Harbor electrification remains uneven across coastal municipalities, limiting electric fleet deployment to ports with installed shore power systems.
- EPA Tier 3 Compliance Burden:Gasoline engine certification requirements are extending development timelines and raising fixed costs for combustion powertrain programs.
Strategic Opportunities
- Subsurface Capability Convergence:Integration of closed-circuit rebreather systems with electric propulsion is opening technical diving and underwater photography applications.
- Subscription Fleet Models:Seasonal rental operators are piloting battery-as-a-service arrangements to eliminate upfront capital requirements and transfer degradation risk.
- Harbor Authority Electrification Incentives:Port infrastructure grants in Italy and Spain are subsidizing shore power installation for commercial water scooter docking.
Industry Challenges
- Marine Electrician Skill Scarcity:Fleet maintenance operations lack technicians trained in high-voltage battery diagnostics and thermal runaway containment protocols.
- Dual Certification Complexity:Manufacturers pursuing both EPA Tier 3 and EU F-Gas compliance face divergent testing protocols and documentation requirements.
- Jet Pump Cavitation Engineering:Electric motor torque curves demand redesigned impeller geometries to prevent efficiency losses at low-speed maneuvering RPMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Scooter Market |
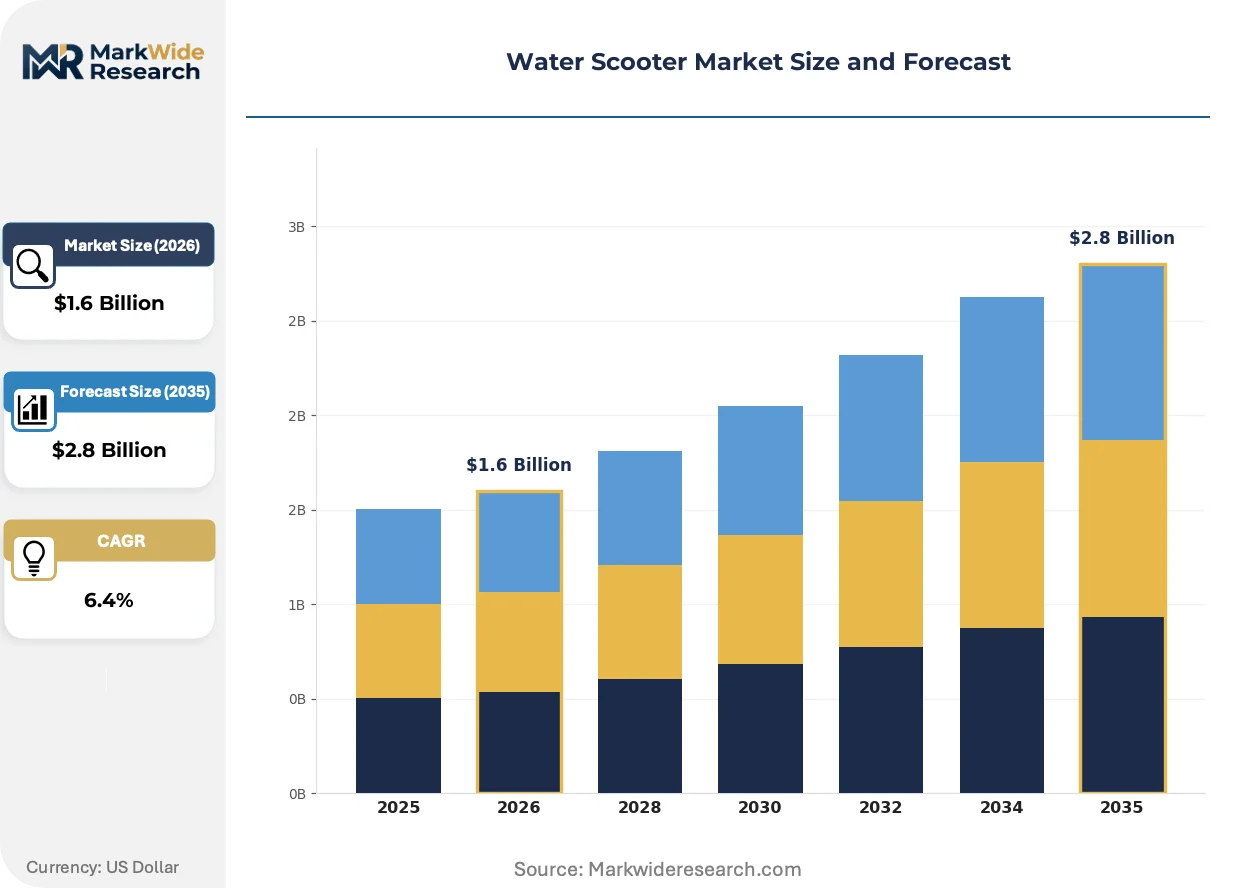
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $2.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up, Sit-Down, Inflatable, Racing Application: Recreational Use, Competitive Sports, Rental Services, Tourism End User: Individuals, Tour Operators, Sports Clubs, Rental Companies Power Source: Electric, Gasoline, Hybrid, Others |
| Companies Covered | Sea-Doo, DiverTug, Yamaha Motor Co. Ltd, SUEX S.r.l., Torpedo Inc., Bombardier Recreational Products Inc., Dive Xtras Inc., SubGravity, Kawasaki Heavy Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Scooter Market Emerging Trajectories
Product development priorities are pivoting toward integrated digital control systems and modular battery architectures that enable rapid swapping and fleet uptime optimization.
Solid-state battery chemistry is absorbing research investment from marine powertrain divisions seeking to eliminate thermal management complexity and extend cycle life. Rental fleet operators in the Mediterranean are piloting early prototypes for evaluation against lithium-ion benchmarks. This transition is compressing the performance gap between electric and gasoline platforms in high-thrust applications.
The EU F-Gas Regulation is phasing out fluorinated refrigerants in cooling systems, forcing manufacturers to redesign thermal management architectures for battery packs and motor controllers. Component suppliers are accelerating development of dielectric fluid cooling alternatives to maintain power density. European commercial operators face accelerated replacement schedules for existing fleet inventory in regulated marine zones.
Commercial buyers are consolidating procurement decisions through centralized fleet management platforms that integrate vehicle telematics, predictive maintenance scheduling, and usage-based insurance pricing. Independent rental operators in Greece and Croatia are adopting these systems to compete with vertically integrated tourism conglomerates. This behavioral shift is elevating software capability and data interoperability to primary vendor selection criteria.
Water Scooter Market Segmentation
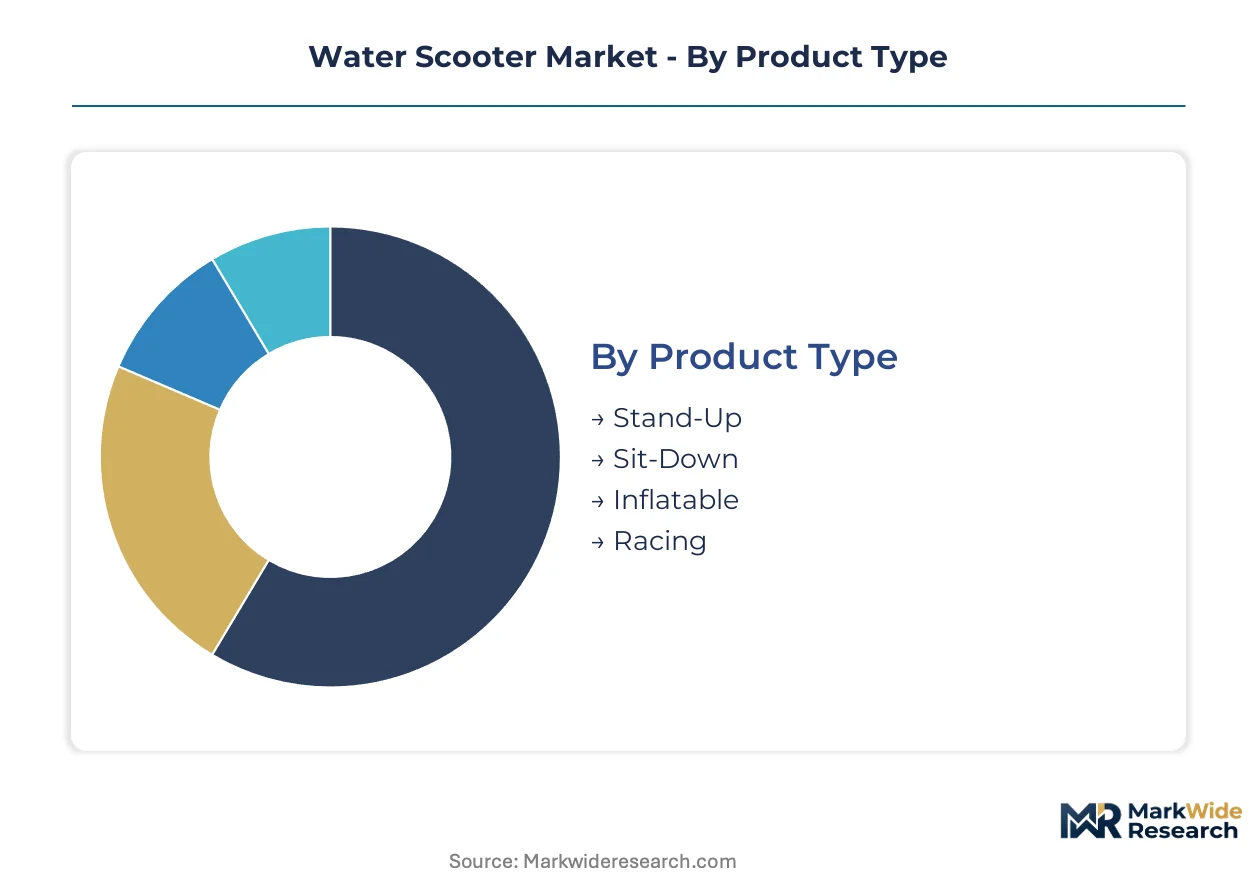
Water scooter segmentation reveals distinct procurement patterns across standalone recreational purchases versus integrated fleet deployments. Rental operators and tourism conglomerates prioritize sit-down platforms with telematics compatibility, while individual consumers fragment across performance tiers and powertrain preferences.
Product Type:
Stand-up configurations function as independent operator-controlled vessels requiring direct physical engagement, whereas sit-down and inflatable variants embed into supervised rental ecosystems with reduced training overhead.
- Sit-Down:Enclosed hull designs with integrated intelligent brake and reverse systems dominate commercial fleet procurement. Mediterranean rental operators in Greece, Spain, and Italy concentrate demand here for passenger stability and lower insurance liability.
- Stand-Up:Open-deck platforms demand higher operator skill and physical engagement. Competitive athletes and enthusiast individuals drive demand where maneuverability outweighs comfort requirements.
- Inflatable:Collapsible hulls serve seasonal operators with storage constraints. Port authorities with limited winter docking capacity favor these for deployment flexibility.
- Racing:Streamlined hull geometries with reinforced pump tunnels address organized competition circuits. Energy density requirements currently constrain electric penetration in this segment.
Sit-Down leads volumes today; Electric-compatible Inflatable variants are gaining share fastest.
Application:
Cost tier stratification separates capital-intensive commercial deployments from discretionary consumer spending, with rental services occupying the mid-tier procurement band.
- Rental Services:Fleet-scale procurement with centralized maintenance protocols and telematics integration. Harbor electrification subsidies in Italy and Spain are redirecting capital toward electric platform procurement.
- Tourism:Coastal destination operators bundle water scooter access with hospitality packages. Mediterranean visitation recovery is accelerating equipment refresh cycles.
- Recreational Use:Individual ownership for private waterfront access. EPA Tier 3 compliance costs are compressing gasoline model affordability at entry price points.
- Competitive Sports:Organized racing leagues and training programs. F-Gas Regulation thermal management requirements are complicating high-output electric motor controller designs.
Rental Services anchor commercial revenue; Tourism applications are expanding most quickly.
End User:
Customer type determines procurement volume thresholds and service attachment rates, with institutional buyers consolidating vendor relationships.
- Rental Companies:Multi-unit fleet operators with seasonal utilization patterns. Battery-as-a-service pilots are transferring degradation risk from balance sheets to suppliers.
- Tour Operators:Integrated hospitality providers bundling marine activities. Predictive maintenance platforms are elevating software capability in vendor selection.
- Individuals:Discretionary purchasers with single-unit acquisition patterns. Lithium carbonate price volatility is widening electric-gasoline upfront cost gaps.
- Sports Clubs:Organized training and competition programs. Specialized high-thrust requirements sustain gasoline platform relevance.
Rental Companies dominate unit procurement; Tour Operators are climbing the fastest.
Power Source:
Technology maturity curves separate commercially deployable electric platforms from established gasoline architectures, with hybrid configurations occupying transitional positioning.
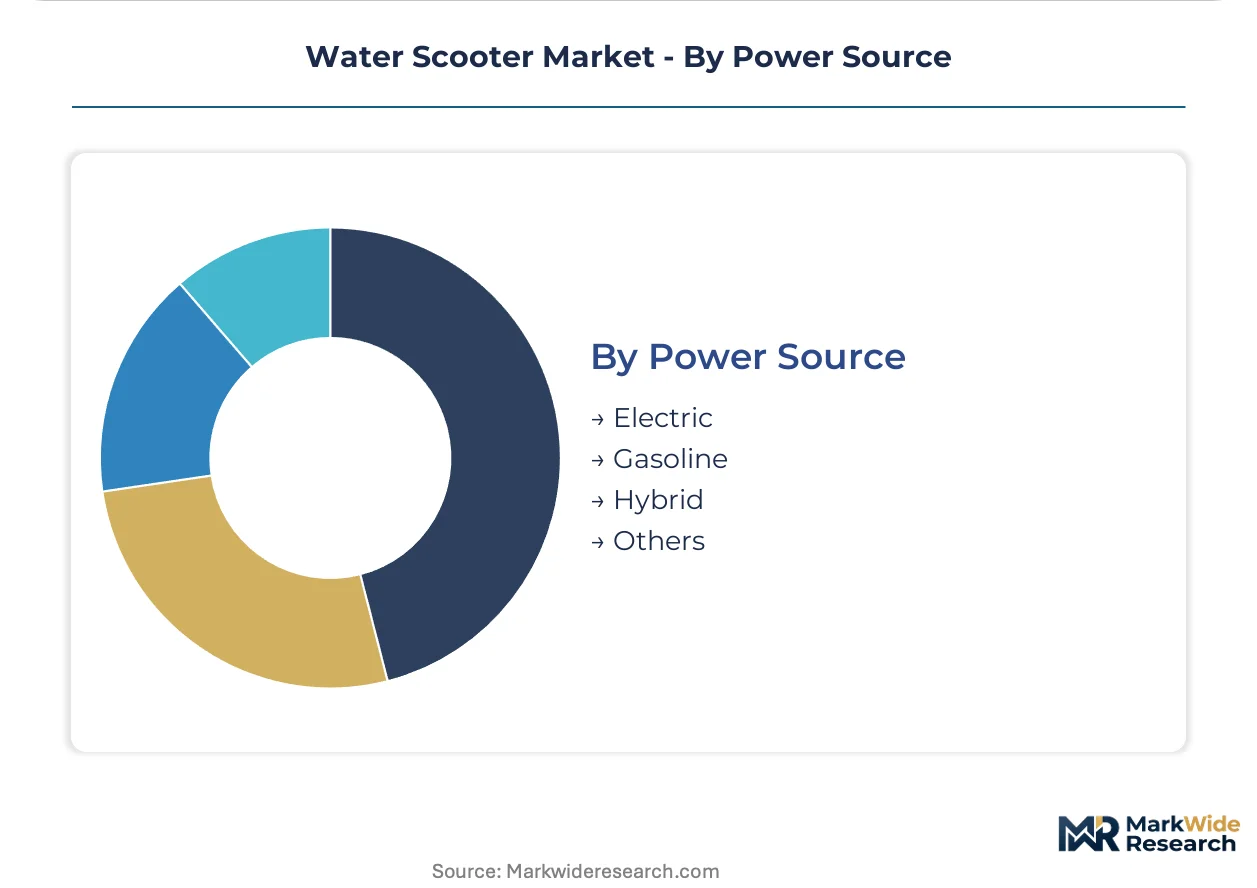
- Electric:Brushless motor systems with lithium-ion battery packs and axial-flow jet pumps. EU Green Deal marine protected area mandates in Greece, Spain, and Italy are accelerating fleet conversion timelines.
- Gasoline:Internal combustion engines with established refueling infrastructure. EPA Tier 3 certification requirements are extending development timelines and raising fixed costs.
- Hybrid:Dual-mode architectures combining electric maneuvering with gasoline range extension. Engineering complexity has limited commercial deployment to prototype evaluation.
- Others:Experimental propulsion including hydrogen fuel cells and compressed air systems. Harbor safety protocols for gaseous fuels remain underdeveloped.
Gasoline leads installed base; Electric powertrains are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mediterranean coastal economies anchor procurement volume for commercial water scooter fleets, with harbor electrification subsidies and marine protected area mandates redirecting capital toward zero-emission platforms.
United States
Recreational boaters in Florida and California drive individual ownership demand while rental operators in Lake Tahoe and Miami-Dade consolidate fleet procurement. EPA Tier 3 certification requirements extend gasoline engine development timelines. The Pacific Northwest cluster around Seattle hosts emerging electric powertrain testing programs for harbor-compliant craft.
Italy
Tourism operators in Sardinia and the Amalfi Coast are accelerating equipment refresh cycles as coastal visitation rebounds. EU Green Deal marine protected area mandates in the Tyrrhenian Sea compel fleet conversion to electric platforms. Port infrastructure grants in Liguria subsidize shore power installation for commercial docking.
Spain
Balearic Islands rental services are piloting battery-as-a-service arrangements to eliminate upfront capital requirements. F-Gas Regulation pressures operators to eliminate fluorinated refrigerants in cooling systems. Barcelona and Valencia harbor authorities are deploying electrification incentives for seasonal fleet operators.
Greece
Cyclades and Ionian island tour operators bundle water scooter access with hospitality packages as destination visitation climbs. EU marine protected area designations in the Aegean accelerate gasoline fleet phase-out timelines. Athens-based commercial buyers are consolidating procurement through centralized fleet management platforms.
France
Corsican rental operators face compressed seasonal windows that favor rapid-charge electric platforms with modular battery swapping. ANSM and CNIL oversight extends to connected fleet telematics data handling. The Provence-Alpes-Côte d'Azur corridor concentrates Mediterranean-facing procurement decisions for hybrid tourism-marine activity bundles.
Water Scooter Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue electrification specialization and subsurface capability convergence. The vendor base stratifies across marine engineering conglomerates with gasoline heritage, recreational vehicle specialists with intelligent control integration, and dedicated diving equipment fabricators with closed-circuit system expertise. Strategic archetypes include powertrain technology licensors, fleet management platform integrators, and harbor electrification solution bundlers. Dominant competitive moves encompass in-house electric powertrain development and predictive maintenance software capability acquisition.
Among Japanese marine engineering conglomerates, Yamaha Motor Co. Ltd and Kawasaki Heavy Industries Ltd occupy positions reflecting gasoline powertrain heritage and axial-flow jet pump engineering depth. Sea-Doo and Bombardier Recreational Products Inc. exemplify North American recreational vehicle specialists with intelligent brake and reverse system integration. SUEX S.r.l. represents Italian diving equipment fabricators with subsurface propulsion specialization.
| Leading Market Players |
|---|
| Sea-Doo |
| DiverTug |
| Yamaha Motor Co. Ltd |
| SUEX S.r.l. |
| Torpedo Inc. |
| Bombardier Recreational Products Inc. |
| Dive Xtras Inc. |
| SubGravity |
| Kawasaki Heavy Industries Ltd |
| Others |
Supply Flow & Price Mechanics
Rental fleet operators in the Mediterranean basin command pricing leverage through centralized procurement consortia that negotiate volume-based contracts with manufacturers. This buyer concentration compresses margins on gasoline platforms while subsidizing electric platform adoption through harbor authority incentive programs.
Pricing Analysis
Lithium carbonate and cathode material volatility feeds through to electric platform manufacturing costs, widening upfront price gaps against gasoline equivalents. Three-tier pricing structure across premium racing, standard recreational, and economy rental levels reflects certification grade and after-sales service bundling. Pricing pressure stems from EPA Tier 3 compliance costs extending gasoline engine development timelines. Individual consumers exhibit highest price sensitivity, while tourism conglomerates absorb premiums for telematics-integrated fleet solutions.
Supply Chain Analysis
Regional distribution centers in Italy, Spain, and Greece operate hub-and-spoke patterns serving seasonal Mediterranean rental operators. Battery cell production concentrates in South Korea, Japan, and China, while axial-flow jet pump machining anchors in Japan and the United States. Lithium-ion sourcing draws from concentrated cathode material suppliers, creating single-source vulnerability for European assemblers. Distribution runs through authorized marine dealerships and direct fleet procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The water scooter market functions as a stable compounder anchored by coastal tourism recovery and regulatory-mandated fleet electrification timelines. Mediterranean harbor authority subsidies and marine protected area designations create predictable demand visibility for commercial operators.
For Market Incumbents: Hedge gasoline powertrain exposure by accelerating in-house electric motor controller development and securing long-term lithium supply agreements. Yamaha Motor and Sea-Doo must defend against emerging entrants specializing in subsurface capability convergence by acquiring predictive maintenance software capabilities. Battery-as-a-service pilots threaten traditional hardware margin capture.
For New Entrants and Emerging Players: Capture white-space in closed-circuit rebreather integration for technical diving applications where SUEX S.r.l. currently dominates. Inflatable electric variants for seasonal operators with storage constraints represent the most penetrable segment. Harbor electrification subsidy qualification should anchor initial go-to-market positioning in Italy and Spain.
For Investors and Strategic Acquirers: Marine tourism conglomerates are the most active acquirer in this space, consolidating fragmented rental operators to achieve fleet-scale procurement leverage. Long-term viability rests on electric platform transition execution and software-defined fleet management capability. Monitor EU F-Gas Regulation enforcement acceleration in Greek and Italian marine protected areas as inflection signal for gasoline fleet obsolescence timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| In-House Electric Powertrain Development | Yamaha Motor and Bombardier Recreational Products reduce outsourced engine dependency while capturing EU Green Deal compliance premiums. |
| Battery-as-a-Service Pilot Expansion | Spanish and Italian rental operators transfer degradation risk from balance sheets to suppliers, improving fleet utilization economics. |
| Predictive Maintenance Platform Integration | Greek tour operators compete with vertically integrated hospitality conglomerates through telematics-enabled uptime optimization. |
| Subsurface Capability Convergence | Dive Xtras and SUEX S.r.l. address technical diving and underwater photography through closed-circuit rebreather integration. |
| Harbor Electrification Partnership | Port infrastructure grants in Liguria and Barcelona subsidize shore power installation for commercial water scooter docking. |
Methodological Framework
Multiple input streams — primary interviews with rental fleet managers, marine tourism operators, and powertrain engineers, alongside secondary validation through EU regulatory filings and harbor authority procurement records — were reconciled to construct segment-level demand estimates. Bottom-up unit economics from Mediterranean rental operators were triangulated against top-down coastal tourism expenditure data. Primary fieldwork encompassed procurement directors at commercial fleet operators, harbor electrification program administrators, and lithium-ion battery supply specialists. Secondary sources included EPA Tier 3 certification databases, EU F-Gas Regulation implementation reports, and port infrastructure grant disclosures.
Data-stream reconciliation across product type, application, end user, and power source dimensions informed the analytical framework over the projection horizon. CAGRs were derived from segment-specific adoption curves weighted by regulatory mandate timelines and battery energy density improvement trajectories. Forecast inputs incorporated harbor electrification subsidy allocation patterns and marine protected area designation schedules across Greek, Spanish, and Italian coastal zones.
Underlying measurement precision varies by segment; electric powertrain forecasts carry tighter precision than hybrid configurations given regulatory visibility. Forecasts reflect documented assumptions regarding lithium carbonate price stabilization and EU Green Deal enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Europe Personal Watercraft Market
Recreational Vehicles
Recreational Vehicle Rental Market
Recreational Vehicles
Saudi Arabia Yacht Charter Market
Recreational Vehicles
Superyacht Market
Recreational Vehicles
Watercraft Accessories Market
Recreational Vehicles
Recreational Boating Market
Recreational Vehicles
Europe Recreational Vehicle Market
Recreational Vehicles
Australia Recreational Vehicle Market
Recreational Vehicles
Asia Pacific Luxury Yacht Market
Recreational Vehicles
Inflatable Boat Market
Recreational Vehicles
Global Recreational Vehicle (RV) Market
Recreational Vehicles
Recreational Vehicle Parks and Campgrounds Market
Recreational Vehicles
Middle East and Africa Personal Watercraft Market
Recreational Vehicles
Kick Scooter Market
Recreational Vehicles
Camping Trailer Market
Recreational Vehicles
Fifth Wheel Trailer Market