
 Scooter Market | 2026-2036
Scooter Market Size, Share, and Industry Trends Forecast 2026-2036
Scooter Market Intelligence
China is tilting its manufacturing capacity toward high-volume electric scooter exports, with Shenzhen-based production corridors now supplying motor controllers and lithium-ion packs at scale. Segway Ninebot leverages its integrated hardware-software ecosystem to dominate shared fleet deployments across European and North American cities. Apollo sustains a premium positioning through in-house suspension tuning and proprietary frame geometries. Kaabo specializes in dual-motor performance configurations that occupy the enthusiast segment with torque outputs exceeding conventional commuter benchmarks.
A scooter is a two-wheeled personal mobility device with a platform deck, steering column, and either human-propelled or electric motor-driven propulsion, where electric variants typically incorporate brushless hub motors rated between 250W and 5000W, lithium-ion battery packs with 36V to 72V architectures, and regenerative braking systems for energy recovery. The primary commercial purpose spans individual last-mile transportation, recreational riding, and accessibility mobility for users with limited ambulatory capacity. Electric scooters lead volume expansion as municipal bike-lane investments and congestion pricing schemes redirect commuter flows away from automobiles. Folding scooters concentrate margin pools in the premium tier where titanium alloy frames and quick-release mechanisms command price premiums over fixed-frame commuter alternatives. Rental services represent the fastest-growing distribution channel as dockless operators deploy GPS-tracked fleets with swappable battery architectures.
The US Consumer Product Safety Commission and the European Union's Machinery Directive impose distinct safety testing protocols on braking performance, electrical system integrity, and maximum speed thresholds, creating compliance cost differentials between export destinations. China's GB standards for electric vehicles and the EU's CE marking requirements for personal light electric vehicles together shape product design decisions around motor wattage limits and lighting configurations. Stakeholders must monitor evolving municipal permitting regimes for shared fleet operations, as city-level caps on vendor counts and fleet sizes directly constrain revenue scalability regardless of underlying hardware demand.
Market Dynamics
Battery chemistry advancement is compressing charge cycles while extending range thresholds, fundamentally altering how OEMs configure motor-battery architectures and where fleets deploy swappable versus fixed-cell systems.
Growth Catalysts
- EU Green Deal transport decarbonization mandates:Municipal congestion pricing schemes in Paris, Milan, and Stockholm redirect commuter flows toward micro-mobility corridors, expanding addressable ridership pools for fleet operators.
- Solid-state cell development:Higher energy density configurations reduce battery pack weight while maintaining voltage stability, enabling dual-motor performance scooters to achieve commuter-grade efficiency without thermal management penalties.
- Dockless rental channel expansion:GPS-tracked fleet deployments with smartphone-unlock interfaces capture trip volumes previously served by fixed-station bike-share systems.
Market Restraints
- Lithium carbonate price volatility:Cathode material cost swings compress margin pools for mid-tier OEMs lacking long-term offtake agreements with Chinese refiners.
- Controller chipset supply concentration:Shenzhen-based semiconductor packaging facilities supply 70-plus percent of brushless motor drivers, creating single-geography vulnerability for European and North American assemblers.
- Maximum speed threshold divergence:The US Consumer Product Safety Commission's 20 mph ceiling conflicts with EU Machinery Directive interpretations above 25 km/h, forcing dual-SKU production runs.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cell manufacturing:Domestic battery production incentives reduce import duty exposure for OEMs establishing local assembly operations.
- Last-mile logistics fleet electrification:Courier and food-delivery operators replace gasoline mopeds with 72V cargo-rated scooters capable of 150 kg payload configurations.
- Accessibility mobility certification pathways:Medical device regulatory frameworks in Germany and Japan create premium pricing tiers for stability-enhanced scooters with seated configurations.
Industry Challenges
- Embedded software validation timelines:Functional safety certification under ISO 26262 for regenerative braking algorithms extends product launch cycles by 8-14 months.
- Swappable battery standardization delays:Competing connector geometries and communication protocols between Ninebot, Okai, and Tier Mobility fleets prevent interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scooter Market |
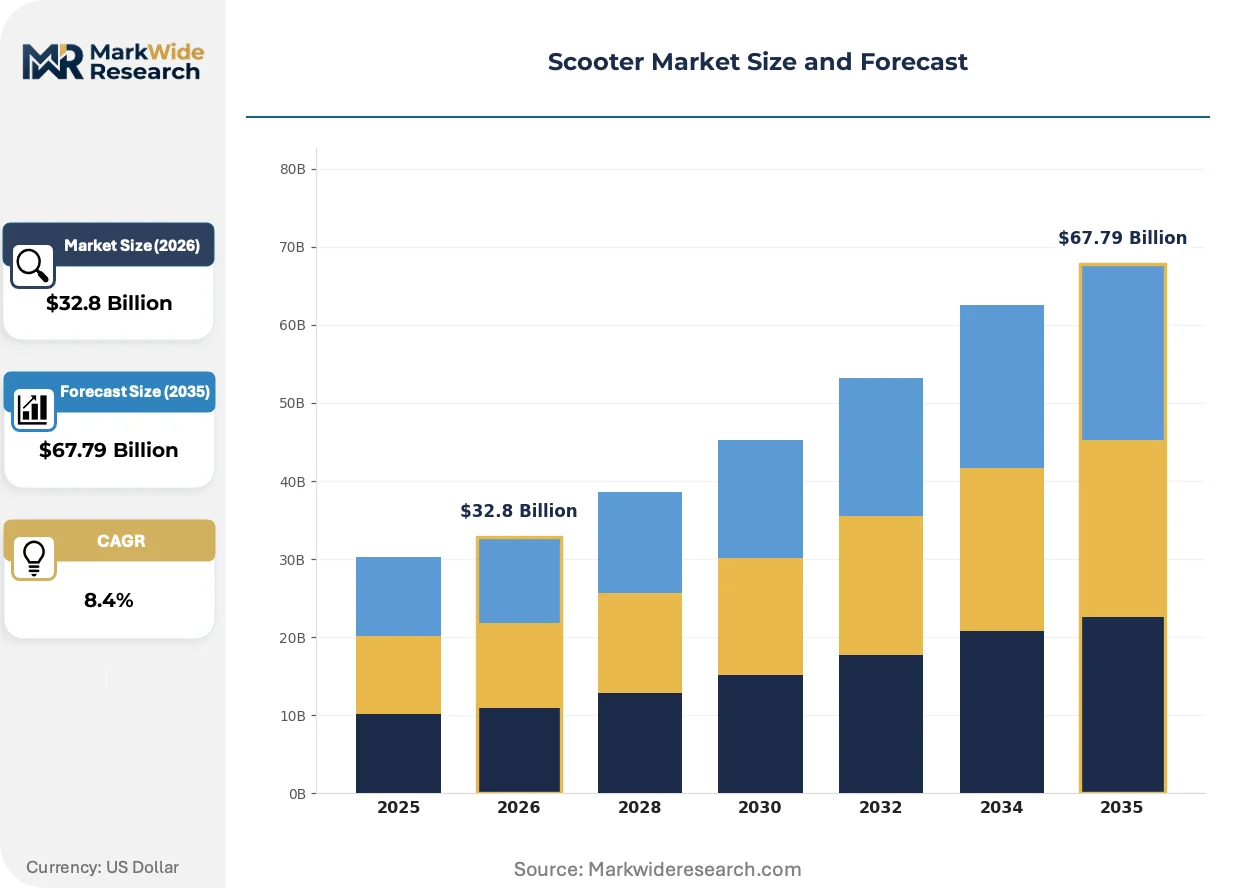
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Scooter, Kick Scooter, Mobility Scooter, Folding Scooter End User: Urban Commuters, Students, Elderly, Tourists Distribution Channel: Online Retail, Specialty Stores, Department Stores, Rental Services Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | EMOVE, iSinwheel, Segway Ninebot, Dualtron, Kaabo, Apollo, Unagi, Nami, Gotrax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scooter Market Strategic Shifts & Innovations
Active material innovations in cathode chemistry and thermal interface materials are reconfiguring powertrain architectures, while regulatory pressure on end-of-life battery handling creates new compliance service layers.
Silicon-carbon composite anodes are hybridizing conventional graphite electrodes by replacing 10-15 percent of active material with silicon-doped structures. Premium commuter OEMs in the Netherlands and Denmark have adopted these configurations since 2023. This hybridization is compressing charge-time benchmarks from 6 hours to under 4 hours for 72V systems without expanding physical pack volume.
The EU's Machinery Directive 2006/42/EC amendment process is incorporating specific braking-distance requirements for personal light electric vehicles above 25 km/h. Manufacturers must now submit dual-mode test data under both dry and wet surface conditions. The shared fleet segment faces the steepest compliance burden, as retrofitting existing GPS-tracked units with upgraded hydraulic calipers exceeds residual book value.
Fleet procurement through mobility-as-a-service subscriptions is displacing direct hardware ownership among urban logistics operators. Last-mile delivery contractors in Barcelona and Berlin now source scooters through per-kilometer contracts bundling maintenance, insurance, and battery swapping. This model concentrates purchasing authority with three to five platform aggregators rather than fragmented individual buyers.
Scooter Market Segmentation
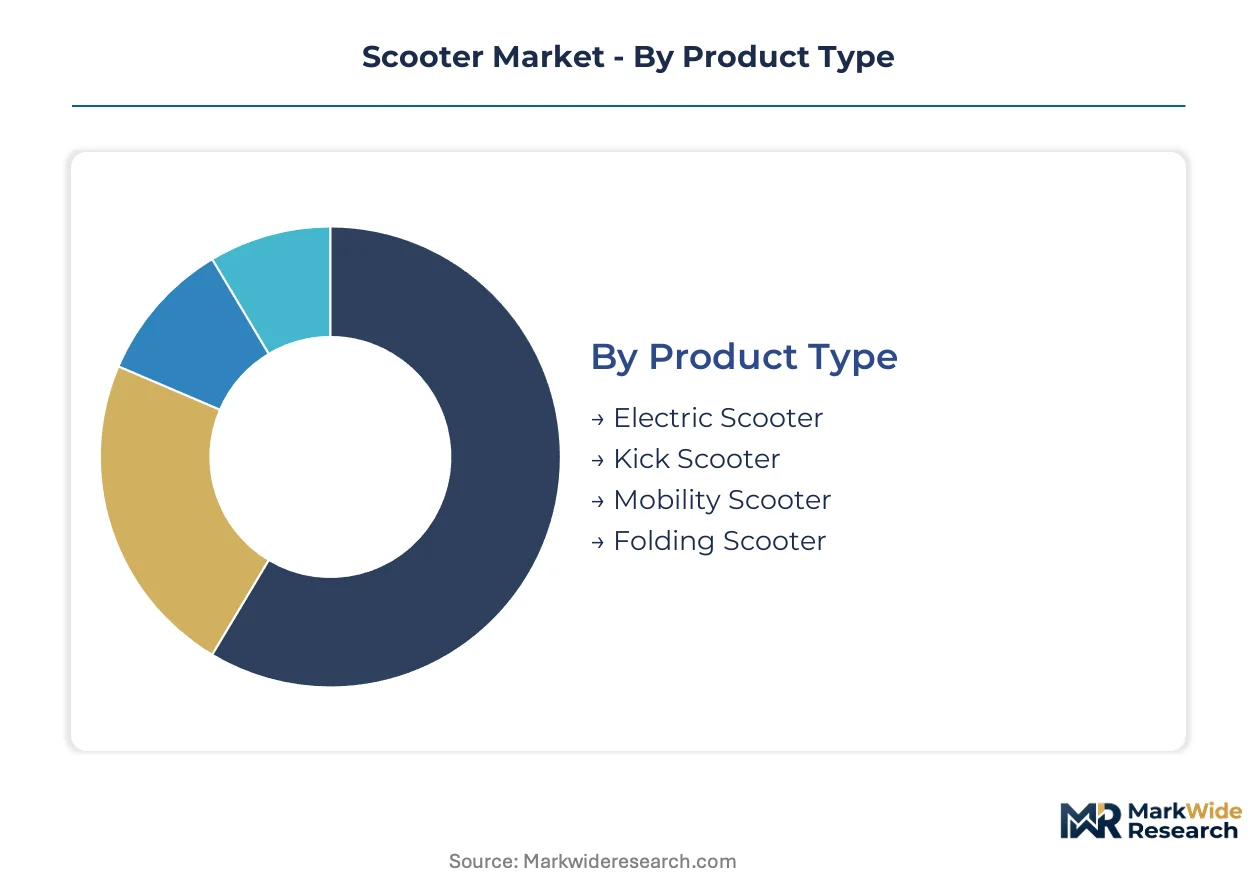
Segmentation in the scooter market reflects divergent engineering priorities between recreational convenience and commercial durability. Each category maps distinct margin pools to specific procurement behaviors and regulatory exposure profiles.
Product Type:
Mature commuter configurations dominate volume, while emerging performance variants reshape motor-battery architectures for enthusiast demand.
- Electric Scooter:Brushless hub motors rated 250W to 5000W pair with 36V-72V lithium-ion architectures and regenerative braking systems. Demand concentrates among urban commuters in Paris, Milan, and Stockholm where municipal congestion pricing redirects ridership from automobiles toward micro-mobility corridors.
- Kick Scooter:Human-propelled aluminum or carbon fiber decks with polyurethane wheel compounds prioritize sub-5kg portability for multimodal transit integration. Students in university towns across Germany and the Netherlands represent the concentrated end-use pool, driven by campus parking restrictions and inter-building transit needs.
- Mobility Scooter:Seated configurations with stability-enhanced wheelbases and medical-grade seating accommodate users with limited ambulatory capacity.
- Folding Scooter:Titanium alloy frames with quick-release mechanisms command price premiums over fixed-frame alternatives in premium commuter segments.
Electric scooters retain volume leadership; folding scooters hold the steepest expansion curve.
End User:
Customer type determines durability specifications and warranty exposure, with commercial operators demanding reinforced frame geometries absent in consumer-grade hardware.
- Urban Commuters:Daily-use configurations prioritize IP54 weather sealing and 500+ charge cycle battery warranties. Fleet procurement through mobility-as-a-service subscriptions is displacing direct ownership among Barcelona and Berlin logistics contractors.
- Students:Price-sensitive demand centers on sub-15kg portability and smartphone-integrated locking mechanisms for campus security protocols.
- Elderly:Stability-enhanced scooters with seated configurations and medical device certification pathways in Germany and Japan access premium pricing tiers.
- Tourists:Dockless rental channel expansion with GPS-tracked fleets captures trip volumes previously served by fixed-station bike-share systems.
Urban commuters anchor procurement volume; tourists are expanding most quickly through shared fleet deployments.
Distribution Channel:
Channel selection determines margin capture and post-sale service obligations, with direct-to-consumer models avoiding retail markup but absorbing return logistics costs.
- Online Retail:Direct-to-consumer platforms bypass specialty store markups but require robust packaging for last-mile delivery integrity. Budget and mid-range tiers concentrate here due to price transparency and comparison shopping behavior.
- Specialty Stores:In-person suspension tuning and test-ride facilities support premium tier conversion. Physical presence enables hands-on motor controller diagnostics and firmware update services that online channels cannot replicate.
- Department Stores:Seasonal promotional cycles and impulse purchase environments favor entry-level kick scooters and children's variants.
- Rental Services:GPS-tracked fleet deployments with swappable battery architectures represent the fastest-growing channel as dockless operators expand municipal permits.
Online retail maintains volume leadership; rental services are gaining share fastest through fleet scaling.
Price Tier:
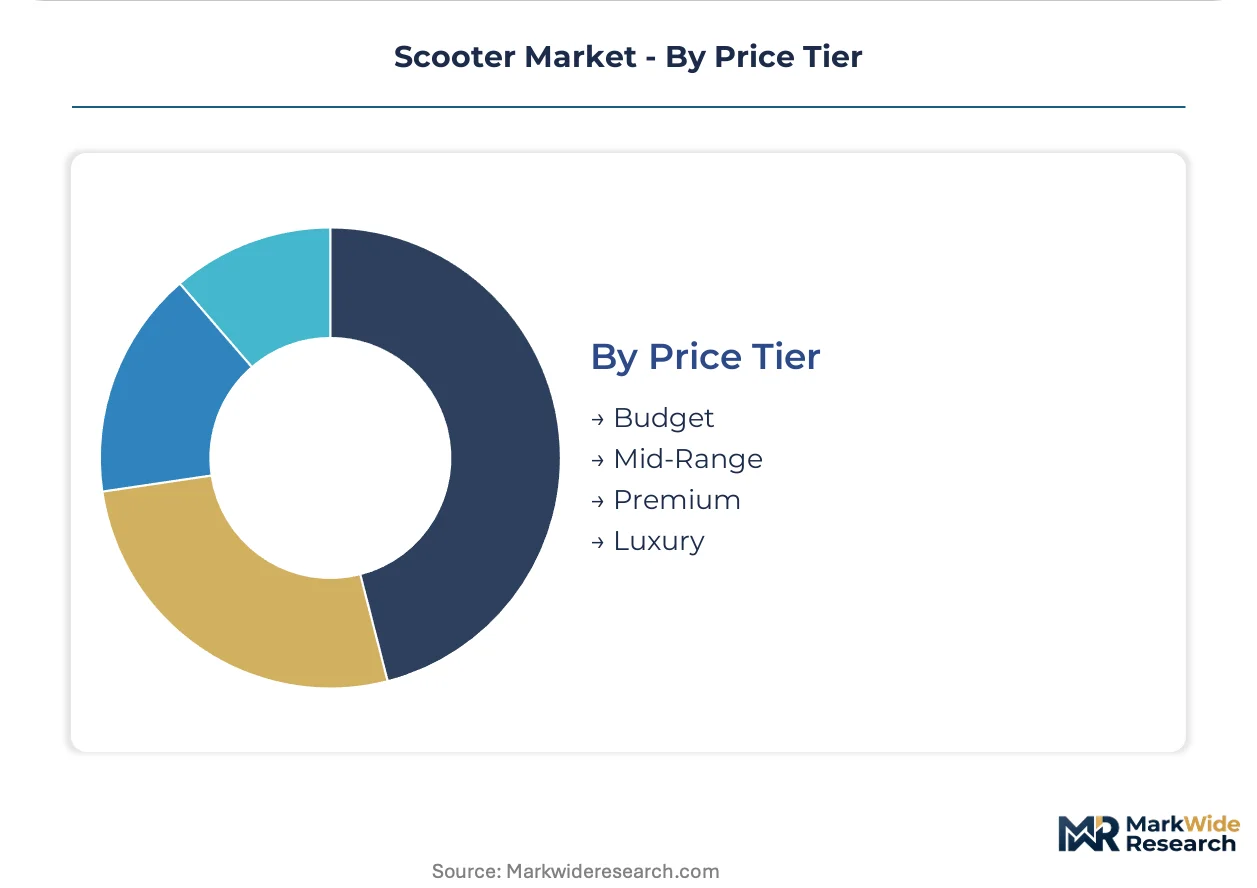
Cost stratification aligns with component grade and certification burden, with premium tiers absorbing ISO 26262 functional safety validation costs that budget tiers bypass.
- Budget:Steel-frame constructions with 250W motors and lead-acid or entry-level lithium-ion cells target price-sensitive students and occasional recreational users. Margin compression from lithium carbonate volatility hits this tier hardest due to absent long-term offtake agreements.
- Mid-Range:500W-1000W brushless motors with 36V-48V lithium-ion packs balance range and portability for daily commuters. This tier captures the largest absolute volume as municipal bike-lane investments expand addressable ridership pools.
- Premium:In-house suspension tuning, proprietary frame geometries, and silicon-carbon composite anodes enabling sub-4-hour charge cycles for 72V systems.
- Luxury:Titanium alloy frames, dual-motor configurations exceeding 2000W combined output, and bespoke finishing for enthusiast segments with torque demands above commuter benchmarks.
Mid-range tiers dominate absolute volume; luxury configurations show the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing corridors around Shenzhen and Shanghai supply motor controllers and lithium-ion packs at scale, creating supply-side density that shapes competitive positioning across export markets. Demand localization varies sharply by regulatory environment and municipal infrastructure investment cycles.
China
Domestic OEMs and component suppliers cluster around Shenzhen and Shanghai manufacturing corridors, feeding high-volume electric scooter exports. GB standards for electric vehicles shape product design decisions around motor wattage limits and lighting configurations. Shenzhen-based semiconductor packaging facilities supply the majority of brushless motor drivers, creating single-geography vulnerability for European and North American assemblers.
Germany
Municipal congestion pricing schemes in Berlin redirect commuter flows toward micro-mobility corridors, expanding addressable ridership pools. The EU Machinery Directive and specific braking-distance requirements for personal light electric vehicles above 25 km/h impose compliance burdens on fleet operators. Medical device regulatory frameworks create premium pricing tiers for stability-enhanced scooters with seated configurations.
United States
Urban commuters in dense metropolitan zones drive fleet procurement through mobility-as-a-service subscriptions. The Consumer Product Safety Commission's 20 mph ceiling conflicts with EU Machinery Directive interpretations, forcing dual-SKU production runs for cross-Atlantic suppliers. California and New York metro areas concentrate dockless rental deployments with GPS-tracked fleets.
India
The PLI scheme for advanced chemistry cell manufacturing reduces import duty exposure for OEMs establishing local assembly operations. Last-mile delivery contractors in Bangalore and Mumbai replace gasoline mopeds with cargo-rated scooters capable of elevated payload configurations. Domestic battery production incentives are reshaping procurement patterns for logistics fleet electrification.
Netherlands
Premium commuter OEMs in Amsterdam and Rotterdam have adopted silicon-carbon composite anodes since 2023, compressing charge-time benchmarks. Campus parking restrictions in university towns drive concentrated end-use pools for sub-5kg portable configurations. The country's bike-lane infrastructure investments expand addressable ridership pools for daily-use configurations.
Scooter Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying motor controllers and battery management systems. The vendor base organizes around three strategic archetypes: vertically integrated hardware-software ecosystems, in-house suspension and frame geometry specialists, and dual-motor performance configurators. Competitive moves concentrate on capacity expansion in Shenzhen-adjacent corridors and strategic partnerships for swappable battery standardization.
Within the integrated ecosystem tier, Segway Ninebot represents the dominant fleet deployment archetype across European and North American cities. Apollo and Kaabo occupy differentiated positions—Apollo exemplifies premium-tier in-house engineering, while Kaabo anchors the enthusiast segment with high-torque dual-motor configurations. These three companies illustrate how competitive positioning stratifies across hardware-software integration depth, suspension tuning specialization, and performance output thresholds.
| Leading Market Players |
|---|
| EMOVE |
| iSinwheel |
| Segway Ninebot |
| Dualtron |
| Kaabo |
| Apollo |
| Unagi |
| Nami |
| Gotrax |
| Others |
Cost & Logistics Intelligence
Shenzhen-based semiconductor packaging facilities supplying brushless motor drivers concentrate upstream margin capture, forcing downstream assemblers in Europe and North America to absorb controller chipset premiums or surrender pricing power to integrated OEMs with captive sourcing.
Pricing Analysis
The EU Machinery Directive dictates the pricing tier structure through divergent certification burdens, separating premium configurations with ISO 26262 functional safety validation from budget tiers that bypass regenerative braking algorithm certification. Price differentiation hinges on motor wattage grade and CE marking tier, with dual-SKU production for cross-Atlantic markets amplifying cost complexity. Pricing pressure intensifies in the budget tier as lithium carbonate volatility compresses margin pools for OEMs lacking long-term offtake agreements with Chinese refiners. Students and occasional recreational users exhibit the highest price sensitivity, while fleet operators and accessibility mobility purchasers absorb premium tiers for durability and medical device certification.
Supply Chain Analysis
Lithium carbonate feedstock draws from Chinese, Australian, and Chilean extraction corridors, with cathode material processing concentrating in Shenzhen and Shanghai manufacturing belts. Component dependencies center on brushless hub motors, silicon-carbon composite anodes, and battery management system chipsets. Single-source vulnerability in Shenzhen-based semiconductor packaging creates chokepoint exposure for European and North American assemblers sourcing seventy-plus percent of motor controllers from one geography. Distribution runs through direct-to-consumer platforms, specialty retail with test-ride facilities, and mobility-as-a-service fleet procurement channels bundling maintenance and battery swapping.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as dockless e-bike fleets and micromobility-as-a-service platforms capture overlapping last-mile trip volumes, eroding the addressable ridership pool for hardware ownership models.
For Market Incumbents: Harden supply chain resilience through backward integration into battery cell production or strategic offtake agreements with Indian PLI scheme beneficiaries, insulating margin pools from lithium carbonate volatility. Deepen hardware-software ecosystem lock-in by embedding proprietary battery management protocols that resist interoperability with competing swappable fleet architectures. Prioritize certification investment in ISO 26262 functional safety validation to capture premium pricing tiers inaccessible to unvalidated competitors.
For New Entrants and Emerging Players: Pursue white-space opportunities in India's logistics fleet electrification corridor, where last-mile delivery contractors in Bangalore and Mumbai replace gasoline mopeds with cargo-rated configurations. Target accessibility mobility certification pathways in Germany and Japan, where medical device regulatory frameworks create premium pricing tiers for stability-enhanced seated configurations. Anchor go-to-market strategy through mobility-as-a-service subscription models that displace direct hardware ownership among urban logistics operators.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated hardware-software ecosystems with captive battery sourcing and fleet deployment scale, positioning for consolidation as swappable battery standardization delays force interoperability investments. Long-term viability favors OEMs with Shenzhen-adjacent manufacturing corridors and municipal permit relationships across European and North American cities. Monitor municipal fleet size caps and vendor count restrictions as inflection indicators for revenue scalability constraints regardless of underlying hardware demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Swappable Battery Standardization Partnership | Resolves connector geometry conflicts between Ninebot, Okai, and Tier Mobility fleets enabling interoperability. |
| Silicon-Carbon Anode Adoption | Compresses charge cycles for 72V systems without expanding physical pack volume in premium commuter tiers. |
| India PLI Scheme Manufacturing Localization | Reduces import duty exposure for OEMs establishing assembly operations in Bangalore and Mumbai corridors. |
| ISO 26262 Functional Safety Certification | Extends product launch timelines but unlocks premium pricing tiers inaccessible to unvalidated competitors. |
| Mobility-as-a-Service Fleet Procurement | Concentrates purchasing authority with platform aggregators displacing fragmented individual buyer relationships. |
Research Approach
The analysis maps electric scooter, kick scooter, mobility scooter, and folding scooter sub-sectors, each validated through procurement directors at fleet operators, regulatory affairs leads at OEMs, battery management system engineers, and municipal permitting officers. Primary interviews with these stakeholders combined with secondary validation against EU Machinery Directive filings, GB standards documentation, PLI scheme announcements, and SEC disclosures from listed micromobility operators. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across price tiers and distribution channels.
Forecast assumptions held fixed the current regulatory divergence between the US Consumer Product Safety Commission's speed thresholds and EU Machinery Directive interpretations, while varying battery chemistry advancement trajectories and municipal fleet permit expansion rates across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, distribution channel, and price tier stratification. CAGRs derived from logistic curve fitting to adoption saturation patterns in comparable micromobility markets, with inputs from lithium-ion cell cost curves and congestion pricing scheme rollout schedules in Paris, Milan, and Stockholm.
Sensitivities concentrate around lithium carbonate price volatility, controller chipset supply disruptions from Shenzhen-based facilities, and municipal fleet size cap revisions that directly constrain revenue scalability. Forecasts reflect these assumptions without claiming predictive certainty. Cross-checking against IEA micromobility deployment databases and FHWA alternative fuel corridor reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Global Electric Light Commercial Vehicles Market
Electric Vehicles
Worldwide EV Range Extender Market
Electric Vehicles
India Electric Car Market
Electric Vehicles
NGO Steel in Electric Vehicle Market
Electric Vehicles
South America E-Bike Market
Electric Vehicles
E-Bike Battery Pack Market
Electric Vehicles
Middle-East and Africa Electric Vehicle (EV) Fluids Market
Electric Vehicles
Europe Automotive Battery Thermal Management System Market
Electric Vehicles
Train Battery Market
Electric Vehicles
Electric Vehicle Battery Enclosure Market
Electric Vehicles
Electric Tricycle Market
Electric Vehicles
Canada E-Bike Market
Electric Vehicles
Battery Electric Vehicle (BEV) Market
Electric Vehicles
France Electric Bus Battery Pack Market
Electric Vehicles
Asia-Pacific Solar E-Bike Market
Electric Vehicles
Foldable Electric Car Market