
 Asia Pacific Luxury Yacht Market | 2026-2036
Asia Pacific Luxury Yacht Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Luxury Yacht Market Insights
Project finance and yacht leasing structures is rewriting competitive access across the Asia Pacific basin. Ferretti S.p.A. leverages its Italian design heritage while anchoring distribution through Singapore hub operations. Horizon Yacht specializes in semi-custom fiberglass builds that dominate Taiwan-to-Thailand delivery routes. Gulf Craft Inc. extends its UAE manufacturing footprint into Southeast Asian charter markets through direct sales offices.
Asia Pacific luxury yachts are vessels exceeding 24 meters in length, constructed from fiberglass, aluminum, steel, or wood composites, designed for private recreation, corporate hospitality, or commercial charter with crew accommodations and extended cruising range. Motor yachts occupy the largest volume share due to their operational simplicity for owner-operators across Indonesia's archipelagic waters. Superyachts command the steepest margin pools as bespoke steel and aluminum hulls require dedicated project management and multi-year build cycles. Catamarans are gaining traction among charter companies serving Thailand's Phang Nga Bay and Australia's Whitsunday routes where shallow draft and beam stability matter.
Australia's Australian Maritime Safety Authority enforces strict commercial vessel standards that filter entry for imported builds. Singapore's Maritime and Port Authority coordinates berthing allocation and environmental compliance that shapes fleet composition in the region's densest marina network. China's MEE implements marine emissions controls that push builders toward hybrid-electric propulsion architectures. Stakeholders must weigh carbon regulation trajectories against the capital intensity of retooling shipyards for alternative powertrains.
Market Dynamics
China's dual carbon goals and MEE marine emissions standards are compressing build cycles as shipyards retool for hybrid-electric propulsion architectures across Taiwan, Thailand, and Australian yards.
Growth Catalysts
- Hybrid-Electric Propulsion Mandates:China's MEE emissions controls push builders toward lithium-ion battery systems and diesel-electric hybrids. Taiwan's Horizon Yacht integrates these powertrains into semi-custom fiberglass hulls for Southeast Asian charter operators.
- Ultra-High-Net-Worth Expansion:Technology and finance sector principals in Singapore and Hong Kong are expanding private fleets. Australia's Gold Coast marina clusters absorb newbuild demand with dedicated superyacht berthing infrastructure.
- Archipelagic Cruising Routes:Indonesia's 17,000-island geography favors shallow-draft catamarans. Thailand's Phang Nga Bay charter corridors drive multi-hull orders with beam stability specifications for overnight anchoring.
Market Restraints
- Aluminum and Steel Input Volatility:Superyacht hull fabrication depends on aerospace-grade aluminum plate and marine steel. Price swings compress margin pools on bespoke builds with fixed-price contracts.
- Supply Concentration in Italian Design Houses:Styling and naval architecture for vessels exceeding 40 meters concentrates in Lombardy and Liguria. Asian builders face royalty burdens and extended design-review cycles.
- Substitution by Fractional Ownership Platforms:Charter management companies in Singapore offer 1/8th equity slices with guaranteed utilization. This displaces whole-vessel purchases among first-time buyers in the 24-30 meter segment.
Strategic Opportunities
- Vietnam's Underpenetrated Marina Infrastructure:Da Nang and Nha Trang lack deep-water berthing for vessels exceeding 35 meters. Greenfield marina development with foreign operator partnerships unlocks cruising route expansion.
- Green Finance Incentives:Singapore's Maritime and Port Authority coordinates preferential berthing tariffs for hybrid-electric vessels. Builders embedding battery systems capture charter fleet replacement cycles.
- Convergence of Solar Photovoltaics and Hull Design:Integrated deck-mounted PV arrays supplement hotel loads. Australian builders test this on catamaran superstructures for Whitsunday bareboat charters.
Industry Challenges
- Naval Architect and Marine Engineer Talent Scarcity:Hybrid propulsion integration requires electrical systems specialists. Australian and Taiwanese yards compete for graduates with automotive battery experience.
- Commercial Certification Timeline Compression:Australia's Australian Maritime Safety Authority enforces extended sea trials for imported builds. Delays strand capital in work-in-progress inventory.
- Legacy Marina Electrical Infrastructure:Australia's Gold Coast and Sydney marinas require shore-power upgrades to 400-amp three-phase service. Retrofit costs pass through to berth holders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Luxury Yacht Market |
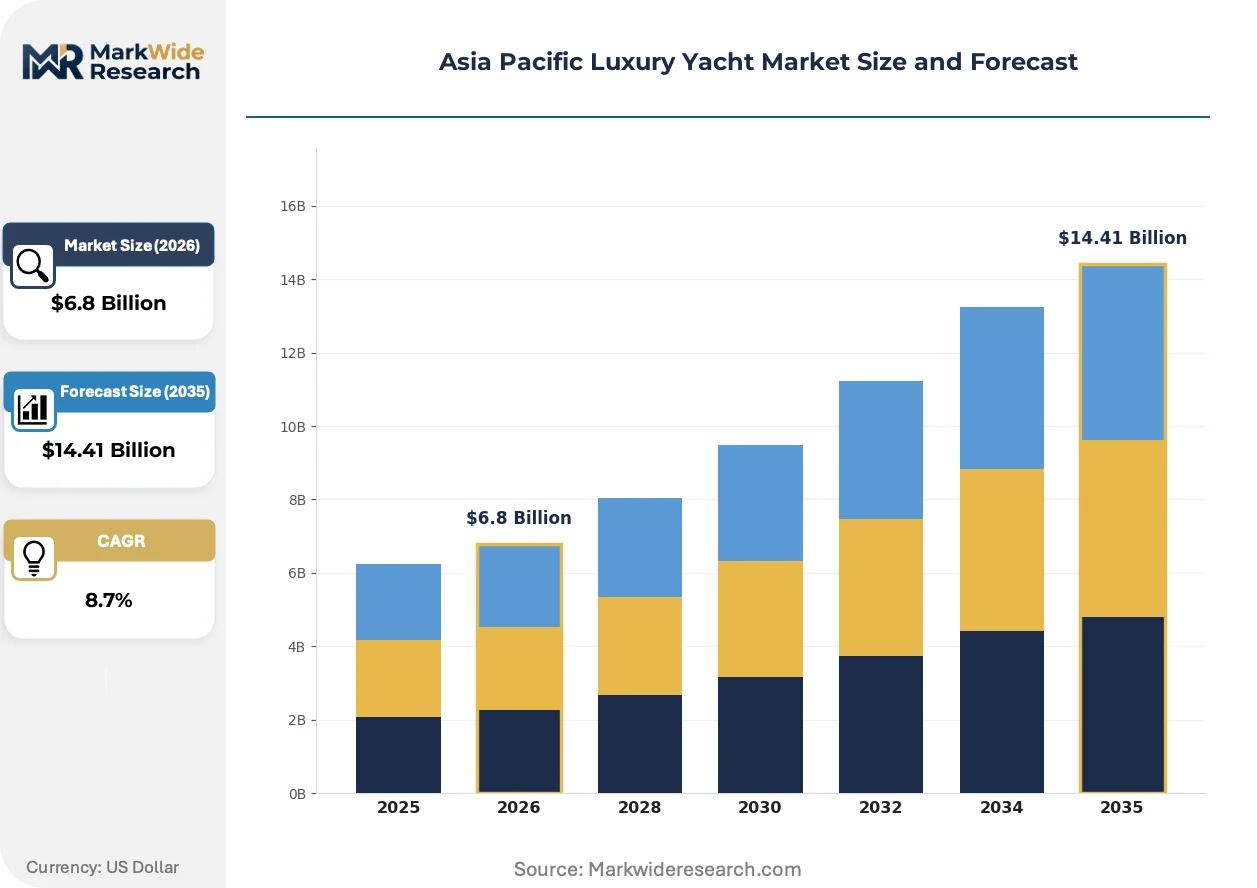
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Yacht Type: Sailing Yachts, Motor Yachts, Catamarans, Superyachts Client Type: Private Owners, Charter Companies, Corporate Clients, Dealers Size Category: Small Yachts, Medium Yachts, Large Yachts, Mega Yachts Material Type: Fiberglass, Aluminum, Steel, Wood |
| Companies Covered | Ferretti S.p.A., Ocean Alexander, Gulf Craft Inc., Heysea Yachts Company Limited, Riviera Australia Pty. Ltd., Sunseeker, Sanlorenzo Asia, Horizon Yacht, Azimut Benetti, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Luxury Yacht Market Trends and Innovations
Propulsion electrification and digital hull monitoring are compressing operational cost structures while regulatory compliance timelines reshape shipyard capital allocation across the region.
Hybrid-electric propulsion architectures combining diesel generators with lithium-ion battery banks are rendering obsolete conventional twin-screw mechanical drivelines in the 24-40 meter charter segment. Australian and Thai fleet operators specify these systems to meet MEE emissions standards in Chinese waters. The technology compresses fuel consumption by thirty to forty percent on typical Indonesia-to-Singapore passages.
China's dual carbon goals and MEE marine emissions controls are forcing builders to certify hulls under stricter NOx and particulate standards. Taiwan's fiberglass specialists and Australian aluminum yards must document supply chain carbon intensity for steel and composite inputs. Superyacht segments above 50 meters face the steepest compliance cost escalation.
Charter procurement is fragmenting from whole-vessel weekly rates toward day-use corporate hospitality blocks. Singapore-based brokers unbundle crew, catering, and fuel into line-item invoices. This pattern concentrates in Thailand's Phang Nga Bay routes where tech sector principals book four-hour sunset circuits rather than extended cruising itineraries.
Asia Pacific Luxury Yacht Market Segmentation
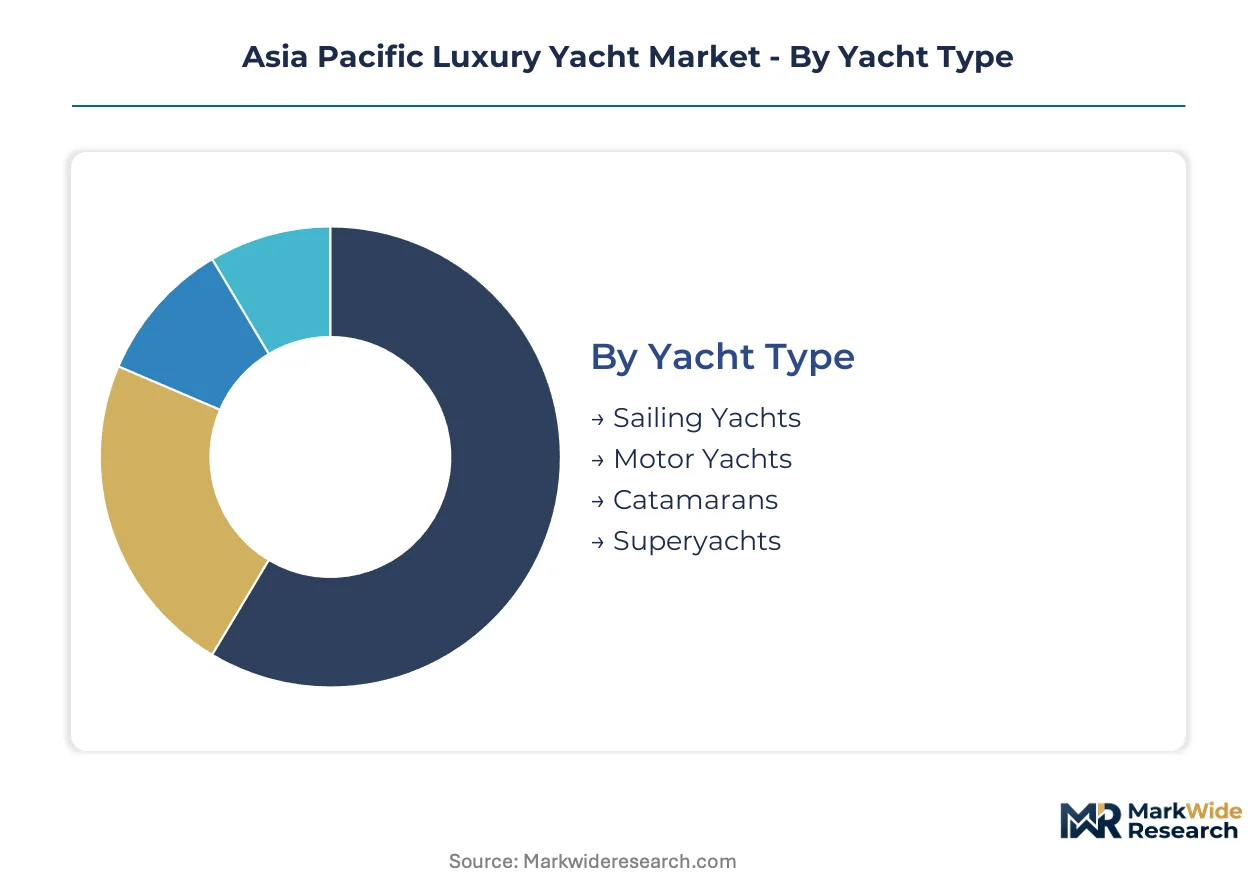
Segmentation in the Asia Pacific luxury yacht market reveals distinct procurement patterns across hull architectures, ownership structures, and material specifications. Each dimension carries unique regulatory, operational, and capital intensity profiles that shape builder specialization and buyer decision frameworks.
Yacht Type:
Mature propulsion formats dominate charter fleet rotations while emerging multi-hull designs capture archipelagic cruising demand.
- Motor Yachts:Twin-screw diesel configurations with enclosed flybridge layouts serve owner-operators across Indonesia's archipelagic waters. Australia's Gold Coast marina clusters absorb the highest concentration of newbuild demand in this category due to operational simplicity for short-handed crews.
- Superyachts:Steel and aluminum hulls exceeding 50 meters require dedicated project management with multi-year build cycles. Singapore-based ultra-high-net-worth individuals from technology and finance sectors drive bespoke commissioning through Italian design houses.
- Catamarans:Shallow-draft multi-hull platforms with beam stability specifications serve Thailand's Phang Nga Bay charter corridors where overnight anchoring demands reduced roll motion.
- Sailing Yachts:Performance-oriented carbon-fiber rigs retain niche positioning among Australian private owners prioritizing regatta participation over charter revenue.
Motor yachts retain volume leadership; catamarans hold the steepest expansion curve.
Client Type:
Procurement scale separates individual capital deployment from fleet-level asset management strategies.
- Charter Companies:Fleet operators in Thailand and Australia's Whitsunday routes specify hybrid-electric propulsion to meet China's MEE emissions standards for cross-regional itineraries. These buyers prioritize shallow-draft hulls with high passenger density for day-use corporate hospitality blocks.
- Private Owners:Ultra-high-net-worth individuals in Singapore and Hong Kong commission semi-custom fiberglass builds with extended cruising range for Southeast Asian waters. Personal use patterns favor enclosed skylounges and crew accommodations for owner-operated passages.
- Corporate Clients:Tech sector principals book unbundled four-hour sunset circuits rather than extended weekly charters, fragmenting traditional procurement toward line-item invoicing.
- Dealers:Distribution intermediaries concentrate in Singapore's yacht charter corridors, managing inventory risk for Taiwan-to-Thailand delivery routes.
Charter companies dominate unit procurement volume; private owners command the highest per-vessel specification spend.
Size Category:
Hull length thresholds determine regulatory jurisdiction, crew requirements, and marina infrastructure compatibility.
- Large Yachts:Vessels spanning 40-60 meters face Australia's Australian Maritime Safety Authority commercial certification timelines with extended sea trials for imported builds. This segment concentrates margin pools for aluminum hull fabricators serving Indonesian archipelagic routes.
- Mega Yachts:Steel-hulled platforms exceeding 60 meters require dedicated superyacht berthing infrastructure available only at Australia's Gold Coast and select Singapore facilities. Build cycles stretch across three to four years with fixed-price contracts exposing builders to aluminum and steel input volatility.
- Medium Yachts:The 24-40 meter bracket captures hybrid-electric propulsion adoption fastest as charter operators replace mechanical drivelines with diesel-electric hybrids.
- Small Yachts:Sub-24 meter vessels fall below the luxury yacht threshold for crew accommodation standards, serving bareboat charter demand in Australia's Whitsunday routes.
Large yachts anchor builder revenue stability; mega yachts generate the steepest margin expansion.
Material Type:
Supply concentration and carbon intensity documentation requirements differentiate fabrication economics across hull substrates.
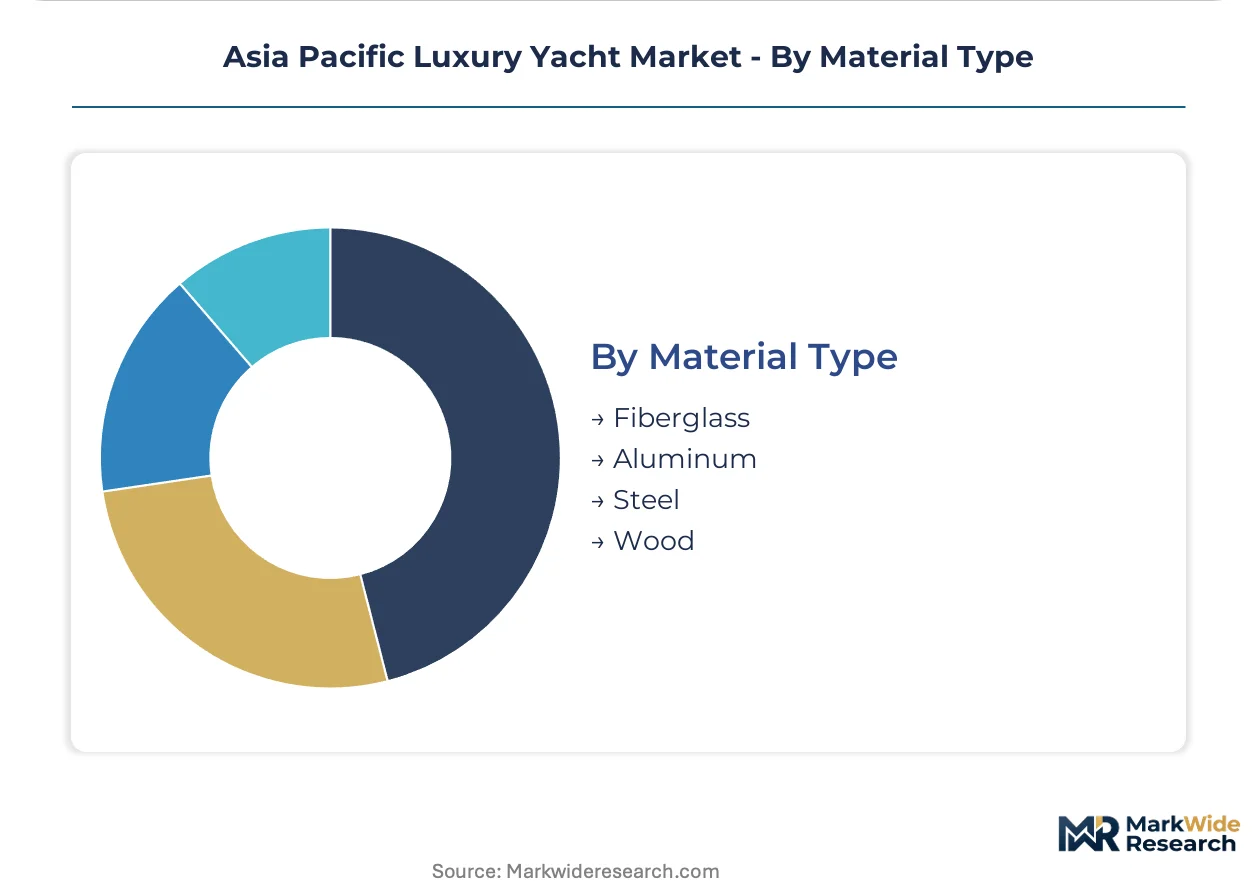
- Fiberglass:Taiwan's Horizon Yacht specializes in semi-custom GRP builds dominating Southeast Asian charter fleet replacement cycles. The material permits rapid mold-based production with lower capital intensity than metal hulls.
- Aluminum:Aerospace-grade plate fabrication for superyacht segments above 50 meters concentrates in Australian yards facing China's MEE supply chain carbon intensity documentation requirements. Price swings compress margin pools on fixed-price contracts.
- Steel:Marine-grade steel hulls serve extended-range cruising specifications with dedicated project management for bespoke architectures exceeding 50 meters.
- Wood:Traditional composite construction retains ceremonial and heritage vessel niches with negligible commercial volume in the region.
Fiberglass commands volume leadership; aluminum faces the steepest compliance cost escalation trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and MEE marine emissions standards are reshaping fleet procurement patterns across Southeast Asian cruising grounds. Singapore's Maritime and Port Authority coordinates preferential berthing tariffs that concentrate hybrid-electric vessel deployment. Australia's Gold Coast marina infrastructure absorbs the region's densest superyacht berthing demand.
Australia
Ultra-high-net-worth individuals from technology and finance sectors are expanding private fleets along Queensland's coastline. The Australian Maritime Safety Authority enforces strict commercial vessel standards that filter entry for imported builds. Gold Coast marina clusters absorb newbuild demand with dedicated superyacht berthing infrastructure and extended sea trial protocols.
Singapore
Charter management companies offer fractional ownership slices with guaranteed utilization, displacing whole-vessel purchases among first-time buyers. The Maritime and Port Authority coordinates berthing allocation and environmental compliance that shapes fleet composition. Yacht charter corridors concentrate broker activity and unbundled corporate hospitality procurement.
China
MEE marine emissions controls push builders toward lithium-ion battery systems and diesel-electric hybrids for cross-regional itineraries. The dual carbon goals compress build cycles as shipyards retool for alternative powertrains. Taiwan-to-Thailand delivery routes channel semi-custom fiberglass builds through distribution networks serving Chinese principals.
Thailand
Phang Nga Bay charter corridors drive multi-hull orders with beam stability specifications for overnight anchoring. Shallow-draft catamarans capture archipelagic cruising demand where reduced roll motion matters. Fleet operators specify hybrid-electric propulsion to meet emissions standards for Indonesia-to-Singapore passages.
Indonesia
The 17,000-island geography favors shallow-draft vessels with operational simplicity for short-handed crews. Archipelagic cruising routes concentrate demand for beam-stable platforms with extended range. Charter companies prioritize passenger density for day-use corporate hospitality blocks across dispersed island chains.
Asia Pacific Luxury Yacht Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distribution and fabrication tiers. Italian design heritage anchors premium positioning through Singapore hub operations while Taiwanese and Australian yards specialize in semi-custom and aluminum fabrication. Three archetypes dominate: heritage European marques with Asia-Pacific distribution networks, regional fiberglass specialists serving charter fleet replacement cycles, and aluminum superyacht fabricators facing carbon intensity documentation requirements. Competitive moves concentrate on hybrid propulsion certification and marina infrastructure partnerships.
Among heritage European marques, Ferretti S.p.A. and Azimut Benetti exemplify design-led positioning through Singapore hub operations. Gulf Craft Inc. represents UAE-based fabrication extending into Southeast Asian charter markets. Horizon Yacht anchors Taiwanese semi-custom production dominating regional delivery routes. These three occupy distinct competitive spaces without direct product overlap.
| Leading Market Players |
|---|
| Ferretti S.p.A. |
| Ocean Alexander |
| Gulf Craft Inc. |
| Heysea Yachts Company Limited |
| Riviera Australia Pty. Ltd. |
| Sunseeker |
| Sanlorenzo Asia |
| Horizon Yacht |
| Azimut Benetti |
| Others |
Pricing and Supply Chain Analysis
Commodity volatility in aerospace-grade aluminum plate and marine-grade steel determines both margin compression on fixed-price superyacht contracts and the geographic clustering of hull fabrication capacity. China's MEE supply chain carbon intensity documentation requirements add compliance cost layers that widen pricing spreads between documented and undocumented material tiers.
Pricing Analysis
Hull material certification grade creates the primary spread between premium aerospace-aluminum superyachts and standard fiberglass charter builds. Three-tier pricing structure across bespoke steel-aluminum hybrids, semi-custom GRP production, and economy bareboat catamarans reflects build complexity and crew accommodation standards. Cost compression in the 24-40 meter segment intensifies as Taiwan's fiberglass specialists compete on delivery speed for Southeast Asian fleet operators. Charter companies exhibit highest price sensitivity due to utilization-dependent revenue models, while Singapore-based ultra-high-net-worth individuals prioritize specification over unit cost.
Supply Chain Analysis
Italian design houses in Lombardy and Liguria hold concentrated styling and naval architecture capacity for vessels exceeding 40 meters. Raw material sourcing draws from Chinese steel mills, Australian aluminum smelters, and Taiwanese composite resin suppliers. Single-source vulnerability concentrates in Italian exterior design royalties that Asian builders cannot easily replicate. Distribution runs through Singapore hub operations coordinating Taiwan-to-Thailand delivery routes with charter fleet deployment schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
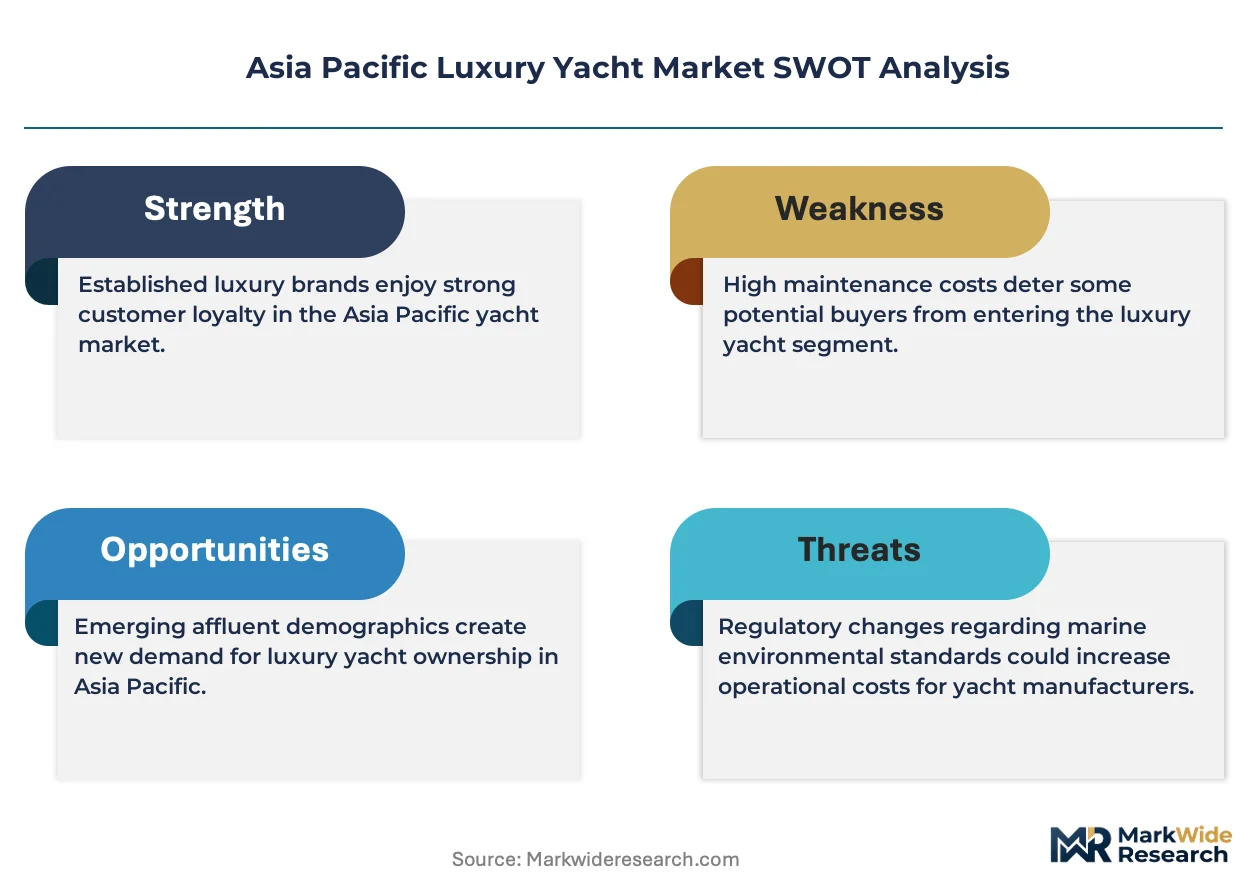
Fractional ownership platforms and unbundled charter procurement threaten traditional whole-vessel sales, forcing incumbents to defend against asset-light substitution models.
For Market Incumbents: Entrench hybrid-electric certification leadership through MEE compliance documentation that locks in charter fleet replacement cycles. Secure captive supply of aerospace-grade aluminum plate via Australian smelter partnerships to insulate margin pools from commodity volatility. Defend against fractional ownership displacement by embedding guaranteed utilization clauses in direct sales contracts. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's marina infrastructure gap by partnering with foreign operators on Da Nang deep-water berthing development. Target Thailand's Phang Nga Bay charter corridor with shallow-draft catamarans specified for beam-stable overnight anchoring. Penetrate through solar-photovoltaic hull integration that Australian builders are testing for Whitsunday bareboat routes. For Investors and Strategic Acquirers: Regional aluminum superyacht fabricators with documented carbon intensity compliance represent the most defensible acquisition archetype as MEE standards tighten. Long-term viability hinges on shipyard retooling completion for hybrid-electric architectures across the projection horizon. Monitor lithium-ion battery system integration rates in Taiwanese semi-custom builds as inflection indicator for technology adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Certification Program | MEE compliance documentation unlocks preferential Singapore berthing tariffs for charter fleet operators. |
| Marina Infrastructure Partnership | Da Nang deep-water berthing development expands cruising routes into Vietnam's underpenetrated coastline. |
| Aluminum Supply Integration | Australian smelter partnerships reduce exposure to aerospace-grade plate price volatility on fixed contracts. |
| Solar Photovoltaic Hull Integration | Deck-mounted PV arrays supplement hotel loads for Whitsunday bareboat charter operators. |
| Fractional Ownership Platform Launch | 1/8th equity slices with guaranteed utilization defend against charter management company displacement. |
Research Methodology
A spread of perspectives from yacht builders, charter fleet operators, marina infrastructure developers, and naval architecture consultants converged on the working assumptions driving this analysis. Primary fieldwork with shipyard project managers and Singapore-based brokers combined with secondary validation from Australian Maritime Safety Authority certification records, China's MEE emissions filings, and customs data on hull material imports. Bottom-up build cycle analysis and top-down regional fleet composition estimates were triangulated to anchor volume and value outputs.
Demand-supply balance modeling across the projection horizon captured charter fleet replacement cycles, private owner expansion patterns, and corporate hospitality procurement fragmentation. Segmentation dimensions included hull architecture, ownership structure, material specification, and size category thresholds that determine regulatory jurisdiction. CAGRs were derived from build pipeline visibility and berthing infrastructure expansion schedules, with hybrid-electric propulsion adoption curves and aluminum input cost trajectories serving as key forecast inputs.
Sensitivities concentrate around MEE regulatory enforcement timing, lithium-ion battery supply constraints, and Italian design house capacity allocation. Forecasts reflect documented assumptions on shipyard retooling completion and marina electrical infrastructure upgrade cadence. Quarterly review of hybrid propulsion certification timelines and aluminum spot price movements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Saudi Arabia Yacht Charter Market
Recreational Vehicles
Asia-Pacific Personal Watercraft Market
Recreational Vehicles
North America Recreational Vehicle Market
Recreational Vehicles
Malaysia Trailer Market
Recreational Vehicles
North America ATV and UTV Market
Recreational Vehicles
Europe Recreational Vehicle Market
Recreational Vehicles
US Electric UTV and ATV Powertrain Market
Recreational Vehicles
Low-Speed Electric Vehicle Market
Recreational Vehicles
Asia-Pacific Motor Home Market
Recreational Vehicles
RV Solar Panels Market
Recreational Vehicles
United States Luxury Yacht Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Low Speed Vehicle (LSV) Market
Recreational Vehicles
Light Car Trailer Market
Recreational Vehicles
Australia Recreational Vehicle Rental Market
Recreational Vehicles
Online Powersports Market