
 Inflatable Boat Market | 2026-2036
Inflatable Boat Market Size, Share, and Industry Trends Forecast 2026-2036
Inflatable Boat Market Foresight
Software-defined hull monitoring is decoupling vessel performance data from physical ownership, creating recurring revenue streams alongside hardware sales. Zodiac Nautic leverages its military heritage to sustain premium positioning in professional-grade tenders. BRIG Boats anchors European production capacity with Bulgarian manufacturing facilities. Highfield Boats dominates aluminum-hulled RIB innovation, extending its technical lead in hybrid rigid-inflatable architectures.
An inflatable boat consists of a flexible, pressurized tube structure—typically fabricated from PVC, Hypalon, neoprene, or coated nylon—bonded to a rigid or soft floor system, with operational pressures between 2.5 and 4.0 PSI enabling displacement hull characteristics without permanent form. These craft serve commercial fishing, military insertion, search-and-rescue, and recreational yacht tender roles where stowability and shallow draft outweigh conventional hull limitations. Rigid inflatable boats command the widest margin pool due to composite hull complexity and institutional buyer specifications. PVC materials lead volume shipments for recreational kayaks and dinghies, while Hypalon concentrates in military and rescue services where UV resistance and chemical tolerance justify premium procurement. Distribution through specialty stores retains the highest conversion rates for fitted accessories and service bundling, though online retail captures entry-level kayak and canoe volumes.
The International Organization for Standardization (ISO) 6185 series governs buoyancy, stability, and material endurance benchmarks, while the EU's REACH framework restricts phthalate plasticizers in PVC formulations, compelling material reformulation across European supply chains. The US Coast Guard enforces flotation and labeling standards that differentiate commercial from recreational certification tiers, directly influencing manufacturer product line architecture. Stakeholders must weigh regulatory compliance investments against the service-revenue potential of connected hull diagnostics as buyer expectations shift from transactional ownership to operational reliability contracts.
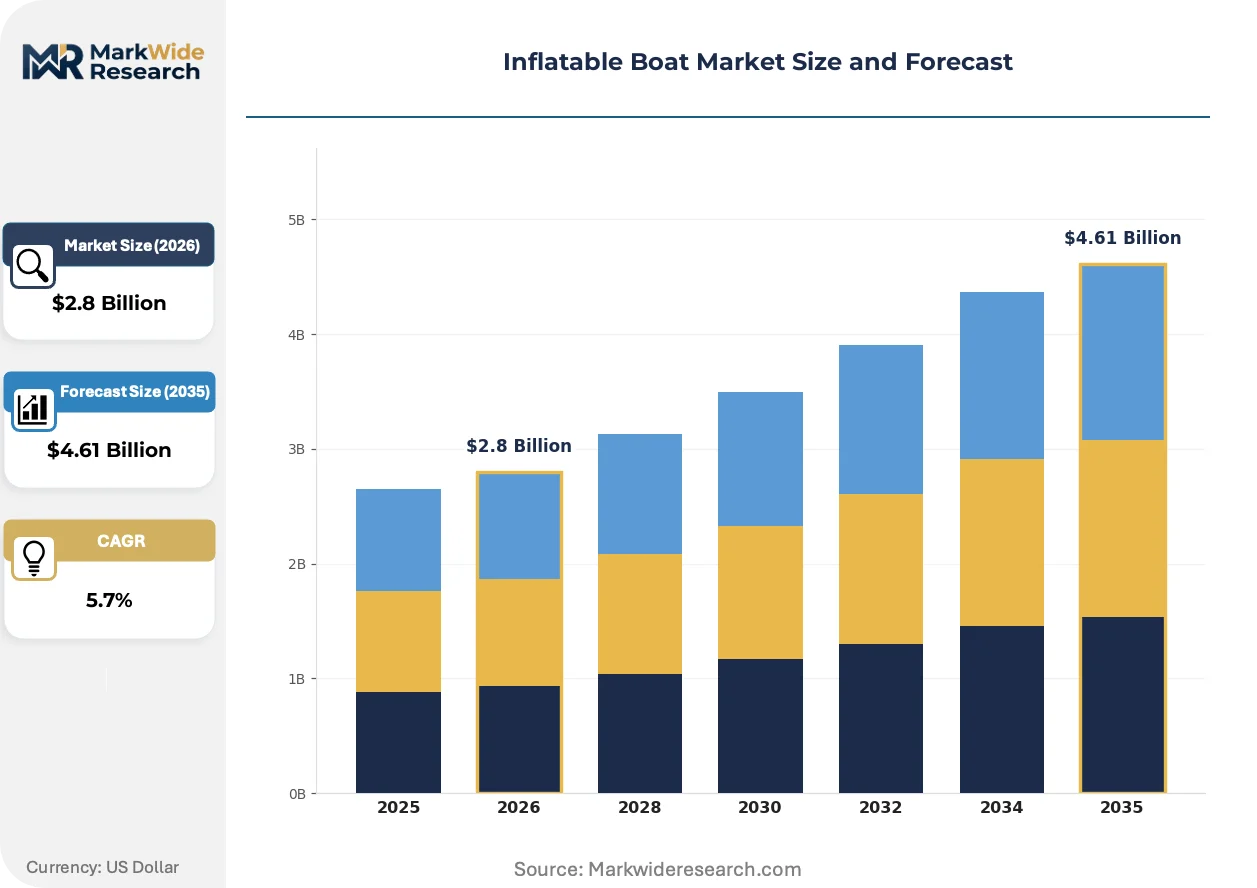
Market Dynamics
EU REACH compliance mandates are forcing material reformulation across PVC and Hypalon supply chains, while NATO military procurement specifications are accelerating adoption of advanced hull architectures. These dual pressures are compressing margins for commodity producers while rewarding specialized fabricators with certified production lines.
Growth Catalysts
- NATO Naval Modernization:Alliance member states are expanding rigid inflatable boat orders for littoral operations and special forces insertion, creating sustained institutional demand for vessels meeting STANAG interoperability standards.
- REACH-Driven Material Innovation:ECHA restrictions on phthalate plasticizers are compelling European manufacturers to develop alternative PVC formulations with comparable UV resistance and weldability.
- Coastal Mediterranean Clustering:Overlapping commercial fishing fleet renewal and superyacht tender operations in ports from Barcelona to Athens generate concentrated demand for professional-grade inflatables.
Market Restraints
- Hypalon Feedstock Concentration:Chlorosulfonated polyethylene production concentrates among a limited set of chemical suppliers, exposing fabricators to input cost volatility and allocation risk.
- REACH Compliance Burden:ECHA registration, evaluation, and authorization requirements impose fixed costs that disproportionately burden small-batch European manufacturers.
- Rigid Hull Substitution:Aluminum and fiberglass skiffs with improved trailering systems compete for recreational buyers prioritizing durability over stowability.
Strategic Opportunities
- Software-Defined Hull Monitoring:Integration of pressure sensors, GPS tracking, and predictive maintenance algorithms enables recurring service revenue alongside hardware sales.
- Search-and-Rescue Fleet Electrification:European municipalities are mandating low-emission vessels for harbor patrol and emergency response, opening procurement channels for electric RIB platforms.
- Direct-to-Operator Digital Channels:Professional fishing cooperatives and yacht management companies are consolidating purchasing through specialized B2B platforms, bypassing traditional marine retail.
Industry Challenges
- Composite Fabrication Skill Gap:Rigid inflatable boat production requires technicians proficient in both thermoplastic welding and fiberglass lamination, a dual competency scarce in European labor markets.
- ISO 6185 Certification Timelines:Third-party buoyancy and stability testing creates 4-6 month product launch delays, compressing competitive response windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inflatable Boat Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canoes, Kayaks, Dinghies, Rigid Inflatable Boats End User: Recreational Users, Commercial Users, Military Organizations, Rescue Services Material: PVC, Hypalon, Neoprene, Coated Nylon Distribution Channel: Online Retail, Specialty Stores, Sports Equipment Shops, Direct Sales |
| Companies Covered | Zodiac Nautic, AB Inflatables, BRIG Boats, Highfield Boats, Walker Bay Boats, Ribcraft USA, Achilles Inflatable Crafts, Damen Shipyard, Novurania, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inflatable Boat Market Shifts & Advancements
Propulsion electrification is restructuring product architecture across all vessel categories, while regulatory chemistry mandates and procurement centralization are reshaping competitive access. These forces favor integrated manufacturers with in-house electronics and materials science capabilities.
Electric outboard systems are electrifying small-craft propulsion, replacing 15-40 horsepower gasoline engines with lithium-ion battery packs and submerged motor pods. Harbor patrol fleets in Scandinavian ports are adopting these platforms for noise-sensitive operations. This shift is electrifying the aftermarket service model, as battery lifecycle management and charging infrastructure replace traditional engine maintenance revenue streams.
ECHA's expanded SVHC candidate list is restricting additional plasticizers and flame retardants in marine fabrics, compelling reformulation of PVC coatings and adhesive systems. German and French manufacturers are accelerating testing of bio-based polyurethane alternatives. Military and rescue service procurement specifications are tightening chemical compliance requirements, disqualifying uncertified suppliers from institutional tenders.
Professional fleet operators are consolidating vendor relationships through multi-year operational reliability contracts rather than transactional vessel purchases. Mediterranean fishing cooperatives and Middle Eastern superyacht management firms are bundling hull monitoring, preventive maintenance, and rapid replacement guarantees. This restructuring concentrates purchasing power among integrated service providers with regional logistics networks.
Inflatable Boat Market Segmentation
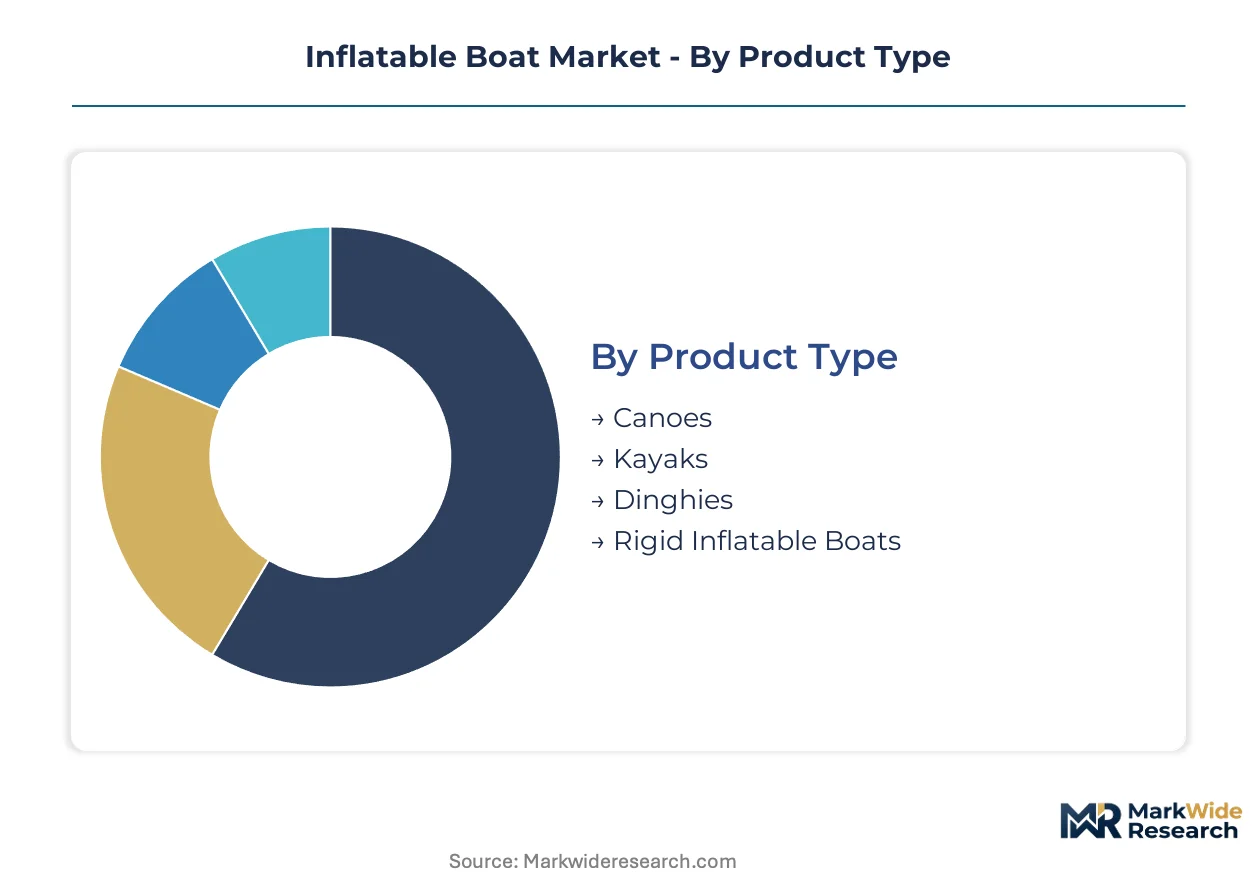
Inflatable boat procurement patterns diverge sharply across user profiles and material specifications. Product architecture and distribution channel choices reflect fundamentally different performance priorities between recreational buyers and institutional operators.
Product Type:
Supply concentration tilts toward composite hull fabrication, where thermoplastic welding and fiberglass lamination skills overlap in scarce labor pools.
- Rigid Inflatable Boats:Composite hulls bonded to pressurized tube collars deliver planing performance in military and professional tender roles. NATO littoral operations and Mediterranean superyacht services sustain premium procurement volumes despite complex manufacturing.
- Kayaks:PVC drop-stitch floors and recreational pricing dominate mass-market shipments. Coastal tourism operators in Spain and Greece rotate fleets frequently, compressing replacement cycles.
- Canoes:Open-tube designs serve flatwater recreation and expedition touring. German and Austrian alpine outfitters favor packable models for multi-day river trips.
- Dinghies:Soft-floor tenders stow aboard cruising sailboats with minimal deck footprint. French and Italian yacht builders specify custom tube diameters for davits.
Today's leader: Rigid Inflatable Boats. Tomorrow's challenger: Kayaks.
End User:
Cost tier stratification separates specification-heavy institutional buyers from price-sensitive recreational entrants.
- Military Organizations:STANAG interoperability mandates and STANAG 4155 hull specifications govern NATO procurement. Rigid inflatable platforms with ballistic tube protection and integrated electronics bays command extended tender cycles.
- Rescue Services:Hypalon construction and self-righting architectures withstand UV exposure and petroleum contact. Scandinavian harbor patrol fleets are electrifying RIB platforms for noise-sensitive operations.
- Commercial Users:Fishing cooperatives and dive operators prioritize payload capacity and engine compatibility. Croatian and Greek fleets favor aluminum-hulled RIBs for durability in salt-heavy environments.
- Recreational Users:Entry-level PVC kayaks and dinghies dominate volume through online retail. Weekend boaters in Florida and California prioritize trailering convenience over hull longevity.
Institutional buyers concentrate margin capture. Recreational channels expand volume fastest.
Material:
Volume distribution favors PVC formulations, though regulatory chemistry is accelerating substitution timelines.
- PVC:Thermoplastic formulations weld efficiently and price competitively for recreational craft. ECHA phthalate restrictions are forcing European manufacturers toward bio-based plasticizer alternatives.
- Hypalon:Chlorosulfonated polyethylene resists UV degradation and chemical attack in military and rescue applications. Feedstock concentration among limited chemical suppliers creates allocation risk during demand spikes.
- Neoprene:Synthetic rubber laminates provide abrasion resistance in whitewater and expedition roles. Czech and Slovak manufacturers specialize in neoprene-dinghy production for Central European river markets.
- Coated Nylon:Lightweight packable fabrics enable high-pressure floor systems in expedition kayaks. Japanese textile suppliers dominate technical nylon weaving for performance segments.
REACH compliance is compressing PVC's cost advantage. Hypalon's technical moat widens.
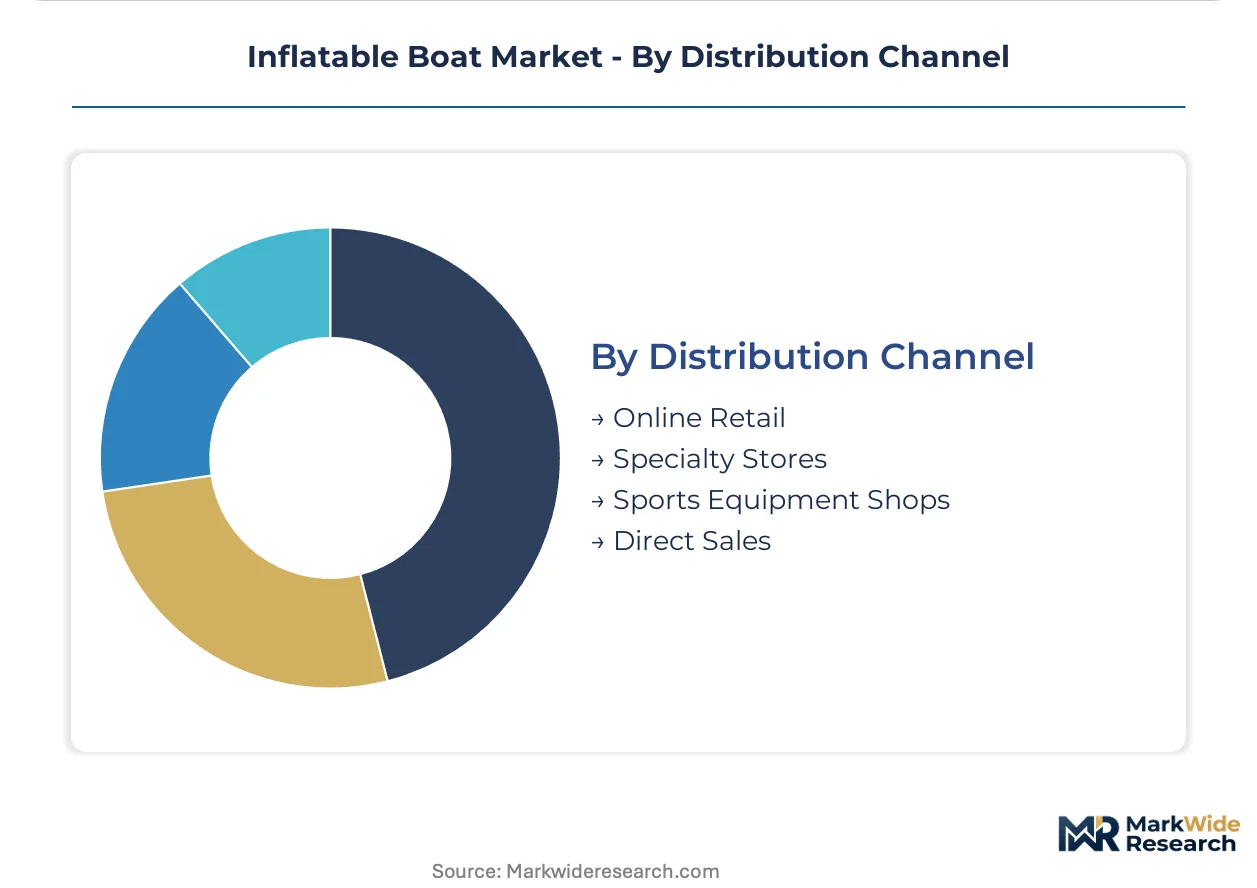
Distribution Channel:
Customer type fragmentation splits procurement between transactional online convenience and relationship-driven specialty service.
- Specialty Stores:Fitted accessory bundling and seasonal service contracts sustain conversion rates. Mediterranean chandleries in Barcelona and Athens coordinate fleet maintenance for commercial operators.
- Direct Sales:Yacht builders and military procurement offices negotiate multi-year operational reliability contracts. BRIG Boats and Highfield Boats cultivate direct relationships with superyacht management firms.
- Online Retail:Amazon and marine-specific platforms capture entry-level kayak and canoe volumes. Price transparency compresses margins for PVC recreational products.
- Sports Equipment Shops:Seasonal stocking and impulse purchases drive recreational dinghy sales. French Decathlon hypermarkets dominate European mass-market distribution.
Specialty retail defends margin through service attachment. Digital channels commoditize entry tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates military-grade RIB procurement while Greece dominates Mediterranean commercial fishing fleet renewal, revealing how procurement purpose—not geography alone—shapes national market character.
United States
Coast Guard procurement and recreational yacht tender demand sustain institutional and premium consumer volumes. US Coast Guard flotation standards differentiate commercial from recreational certification tiers, forcing manufacturers to maintain dual product architectures. Florida's Miami-Dade County hosts concentrated superyacht management firms that bundle tender specifications with hull monitoring service contracts.
France
Zodiac Nautic's heritage anchors domestic production of professional-grade inflatables for NATO-aligned military operators. ECHA REACH restrictions on phthalate plasticizers compel reformulation of PVC coatings in Brittany and Loire-Atlantique manufacturing zones. Decathlon's hypermarket network dominates mass-market recreational distribution through seasonal stocking and impulse purchase placement.
Italy
Superyacht builder integration and commercial fishing cooperative procurement generate overlapping demand for aluminum-hulled RIB platforms. EU Green Deal harbor electrification mandates accelerate adoption of electric propulsion systems in Ligurian and Adriatic port authorities. Genoa's chandleries coordinate fleet maintenance contracts that bundle hull monitoring with preventive service schedules.
Spain
Coastal tourism operators in Catalonia and the Balearics rotate PVC kayak fleets frequently, compressing replacement cycles for entry-level recreational products. ECHA SVHC candidate list expansions restrict additional flame retardants in marine fabrics, disqualifying uncertified suppliers from institutional tenders. Barcelona's specialty marine retailers defend margin through fitted accessory bundling and seasonal service attachment.
Greece
Mediterranean fishing cooperative consolidation and island ferry tender operations concentrate demand for durable aluminum-hulled RIBs in salt-heavy environments. National harbor patrol electrification programs open procurement channels for low-emission emergency response vessels. Piraeus and Thessaloniki anchor commercial fleet renewal cycles that prioritize payload capacity and engine compatibility specifications.
Inflatable Boat Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with military and professional tender markets rewarding heritage positioning while recreational channels favor scale-driven cost efficiency. The vendor base concentrates among European fabricators with certified REACH-compliant production lines and NATO STANAG interoperability credentials. Three archetypes dominate: heritage military suppliers leveraging institutional relationships, aluminum-hull innovators extending technical differentiation, and mass-market assemblers capturing online retail volumes. Competitive moves center on multi-year operational reliability contracts and direct-to-operator digital channel development.
Within the heritage-tier segment, Zodiac Nautic and BRIG Boats exemplify institutional procurement positioning, while Highfield Boats anchors aluminum-hulled RIB innovation. These European-limited entities occupy differentiated competitive spaces without overlapping segment claims, representing how geographic production concentration and materials specialization fragment strategic options.
| Leading Market Players |
|---|
| Zodiac Nautic |
| AB Inflatables |
| BRIG Boats |
| Highfield Boats |
| Walker Bay Boats |
| Ribcraft USA |
| Achilles Inflatable Crafts |
| Damen Shipyard |
| Novurania |
| Others |
Supply & Pricing Matrix
NATO STANAG interoperability mandates for rigid inflatable boats are compressing supplier qualification timelines and forcing fabricators to absorb certification costs into quoted vessel prices. ECHA REACH compliance investments in alternative PVC plasticizers and Hypalon feedstock security premiums are reshaping how European manufacturers structure long-term procurement contracts.
Pricing Analysis
Capacity additions in Bulgaria and Turkey are reshaping price floors for aluminum-hulled RIB platforms across Mediterranean markets. Three-tier pricing structure across NATO-certified, commercial-grade, and recreational tiers separates institutional buyers from fleet operators from weekend entrants. Price differentiation rests on ISO 6185 certification level and after-sales service bundling. Cost compression in PVC recreational kayaks is intensifying because online retail price transparency erodes specialty store premiums. Recreational users through Amazon and Decathlon channels exhibit highest price sensitivity; military procurement offices demonstrate lowest sensitivity due to operational reliability contract structures.
Supply Chain Analysis
ISO 6185 certification and ECHA REACH registration act as gating mechanisms that filter uncertified Asian assemblers from European institutional tenders. Manufacturing concentrates in France, Bulgaria, and Italy for RIB fabrication, with Japanese textile suppliers dominating coated nylon inputs for expedition kayaks. Raw material dependencies include chlorosulfonated polyethylene for Hypalon tubes, lithium-ion battery packs for electric propulsion systems, and marine-grade aluminum extrusions for hull structures. Single-source vulnerability in Hypalon feedstock from limited chemical suppliers exposes fabricators to allocation risk during NATO procurement spikes. Distribution runs through specialty chandleries in Barcelona and Athens for commercial fleet service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The inflatable boat market reads as a late-cycle quality story where professional fleet operators now prioritize operational reliability contracts over transactional vessel purchases. NATO military specifications and EU harbor electrification mandates are concentrating procurement power among certified fabricators with integrated service capabilities.
For Market Incumbents: Extend certification moats by accelerating ECHA REACH-compliant material reformulation ahead of SVHC list expansions. Secure captive supply arrangements for Hypalon feedstock to insulate against chemical supplier allocation risk. Deepen direct relationships with Mediterranean fishing cooperatives and superyacht management firms through multi-year operational reliability contracts that bundle hull monitoring with preventive maintenance.
For New Entrants and Emerging Players: Direct-to-operator digital platforms targeting Croatian and Greek commercial fishing fleets offer the most penetrable white-space entry. Electric RIB platforms for Scandinavian harbor patrol electrification programs represent a specification-driven segment with limited incumbent specialization. Pursue white-label manufacturing partnerships with established Bulgarian fabricators to bypass ISO 6185 certification timeline barriers.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier aluminum-hull specialists possessing ECHA-registered production lines and nascent software-defined hull monitoring capabilities. Five-to-ten year viability hinges on regulatory chemistry compliance rather than commodity volume scale. Watch for NATO procurement office shifts toward STANAG 4155 ballistic tube protection specifications as inflection indicator for premium RIB demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Reformulation | ECHA registration secures access to EU institutional tenders and NATO-aligned procurement channels. |
| Software-Defined Hull Monitoring Integration | Pressure sensors and predictive maintenance algorithms transform transactional sales into recurring service revenue streams. |
| Electric Propulsion Platform Development | EU Green Deal harbor electrification mandates in Italy and Greece open municipal procurement channels. |
| Direct-to-Operator Digital Channel Buildout | B2B platforms bypass traditional marine retail and capture professional fleet consolidation purchasing. |
| Hypalon Feedstock Security Arrangements | Long-term chemical supplier contracts insulate margins against chlorosulfonated polyethylene allocation volatility. |
Research Methodology
Multiple input streams — structured interviews with RIB fabrication plant managers, procurement leads at Mediterranean fishing cooperatives, and superyacht management firms — were reconciled against customs trade data, ECHA registration databases, and NATO procurement disclosures. Secondary validation drew from ISO 6185 certification records, EU tender documentation, and marine electronics supplier filings. Bottom-up vessel shipment estimates and top-down addressable market sizing were triangulated to constrain forecast variance.
Historical procurement patterns were cross-referenced against expert panel input from technical directors at heritage military suppliers and aluminum-hull innovators. Segmentation modeling spanned hull architecture, end-user mission profile, material chemistry compliance tier, and regional regulatory framework. CAGRs were derived from fitted trend extrapolation moderated by procurement cycle visibility and fleet replacement schedule disclosures. Electric propulsion adoption curves and ECHA SVHC list expansion timelines served as industry-specific forecast inputs.
REACH regulatory enforcement intensity, NATO procurement budget allocation shifts, and battery supply chain disruption are the dominant revision risks to modeled outcomes. Forecasts embed assumptions regarding certification timeline stability and chemical supplier capacity expansion. A model refresh is warranted upon material change in ECHA candidate list composition or STANAG specification amendment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Kick Scooter Market
Recreational Vehicles
Middle East and Africa Personal Watercraft Market
Recreational Vehicles
North America Youth ATV and UTV Market
Recreational Vehicles
Europe Personal Watercraft Market
Recreational Vehicles
Luxury Van Market
Recreational Vehicles
Global Truck Camper Market
Recreational Vehicles
RV Solar Panels Market
Recreational Vehicles
Low Speed Vehicle (LSV) Market
Recreational Vehicles
Leisure Boat Market
Recreational Vehicles
North America ATV and UTV Market
Recreational Vehicles
Specialty Vehicle Market
Recreational Vehicles
North America Recreational Vehicle Market
Recreational Vehicles
Europe Recreational Vehicle Market
Recreational Vehicles
Global Houseboats Market
Recreational Vehicles
ATV-UTV Tire Market
Recreational Vehicles
Asia-Pacific Motor Home Market