
 Europe Recreational Vehicle Market | 2026-2036
Europe Recreational Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Recreational Vehicle Market Analysis
Retiree buyers is redrawing demand patterns across Europe as younger family segments plateau in key markets. Thor Industries leverages its transatlantic manufacturing footprint to sustain volume leadership in motorhome categories. Knaus Tabbert anchors its position through specialized compact vehicle production aimed at German and Austrian channels. Trigano competes across multiple price tiers through its portfolio of French and Italian brands.
A recreational vehicle constitutes a motorized or towable dwelling unit engineered for temporary habitation during travel, typically incorporating integrated sleeping quarters, kitchen facilities, and onboard power systems rated between 12V DC and 230V AC configurations. These units serve the commercial purpose of enabling extended mobile tourism and outdoor hospitality consumption across European campground networks and rural tourism corridors. Motorhomes currently dominate value generation due to higher unit economics and integrated chassis manufacturing, while electric fuel type configurations represent the fastest-expanding segment as battery-electric drivetrains penetrate compact and mid-size categories. Trailer segments maintain mature demand profiles in Southern Europe where tow vehicle ownership remains elevated and storage infrastructure is well developed.
The EU Green Deal and F-Gas Regulation are reshaping vehicle efficiency mandates and refrigerant standards across European RV manufacturing, compelling producers to redesign thermal management systems and chassis electrification architectures. EMA and national type-approval authorities in Germany through KBA and France through ANSM coordinate safety and environmental compliance for cross-border sales. Stakeholders must monitor battery supply chain localization requirements and evolving campground charging infrastructure standards as electrification commitments deepen across member states.
Market Dynamics
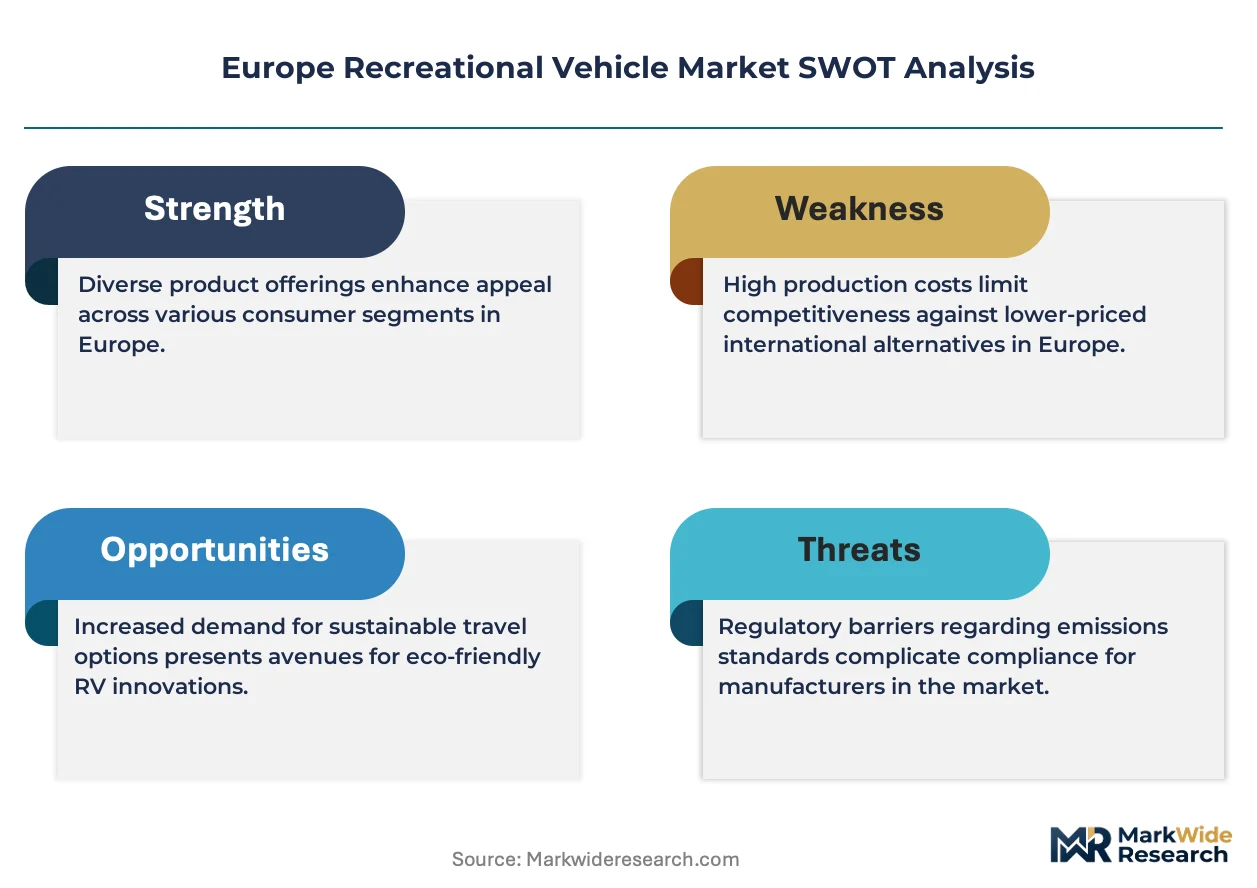
Electrification mandates under the EU Green Deal are restructuring chassis sourcing and thermal system design across European RV manufacturing, forcing producers to retool supply relationships and energy architectures simultaneously.
Growth Catalysts
- EU Green Deal decarbonization targets:Member state fleet emission standards are accelerating battery-electric drivetrain adoption in compact motorhome categories, creating compliant product pipelines for German and French channels.
- Retiree demographic expansion:Aging populations in Italy and Spain are extending purchase cycles for premium motorhome configurations with integrated accessibility features and extended-season thermal packages.
- Campground charging infrastructure:National tourism boards in France and Germany are deploying high-amperage shore power standards that enable overnight battery replenishment for electric RVs.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack assembly depends on cathode material flows from a narrow supplier base in Poland and Hungary, exposing production schedules to raw material allocation constraints.
- F-Gas refrigerant phase-down:The EU F-Gas Regulation is compressing availability of high-GWP blowing agents for insulated wall panels, forcing thermal envelope redesigns and certification delays.
- Compact urban storage scarcity:Municipal parking restrictions in Dutch and Belgian city centers are limiting motorhome ownership feasibility for buyers without rural property access.
Strategic Opportunities
- Portuguese and Croatian coastal corridors:Underdeveloped RV service infrastructure along Algarve and Dalmatian routes presents first-mover positioning for rental fleet operators and seasonal dealership networks.
- Vehicle-to-grid integration:Bidirectional charging hardware convergence with home energy management systems creates ancillary revenue streams for owners and grid stabilization contracts with utilities.
- CSRD-aligned circular design:The EU Corporate Sustainability Reporting Directive is creating procurement preference for manufacturers with verified end-of-life material recovery programs and remanufactured component streams.
Industry Challenges
- High-voltage technician certification gaps:Service networks across Austria and Switzerland face shortages of mechanics qualified for 400V battery system diagnostics and thermal runaway containment protocols.
- Cross-border type-approval harmonization:Divergent interpretations of EMA safety standards between Germany's KBA and France's ANSM are extending homologation timelines for multi-country product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Recreational Vehicle Market |
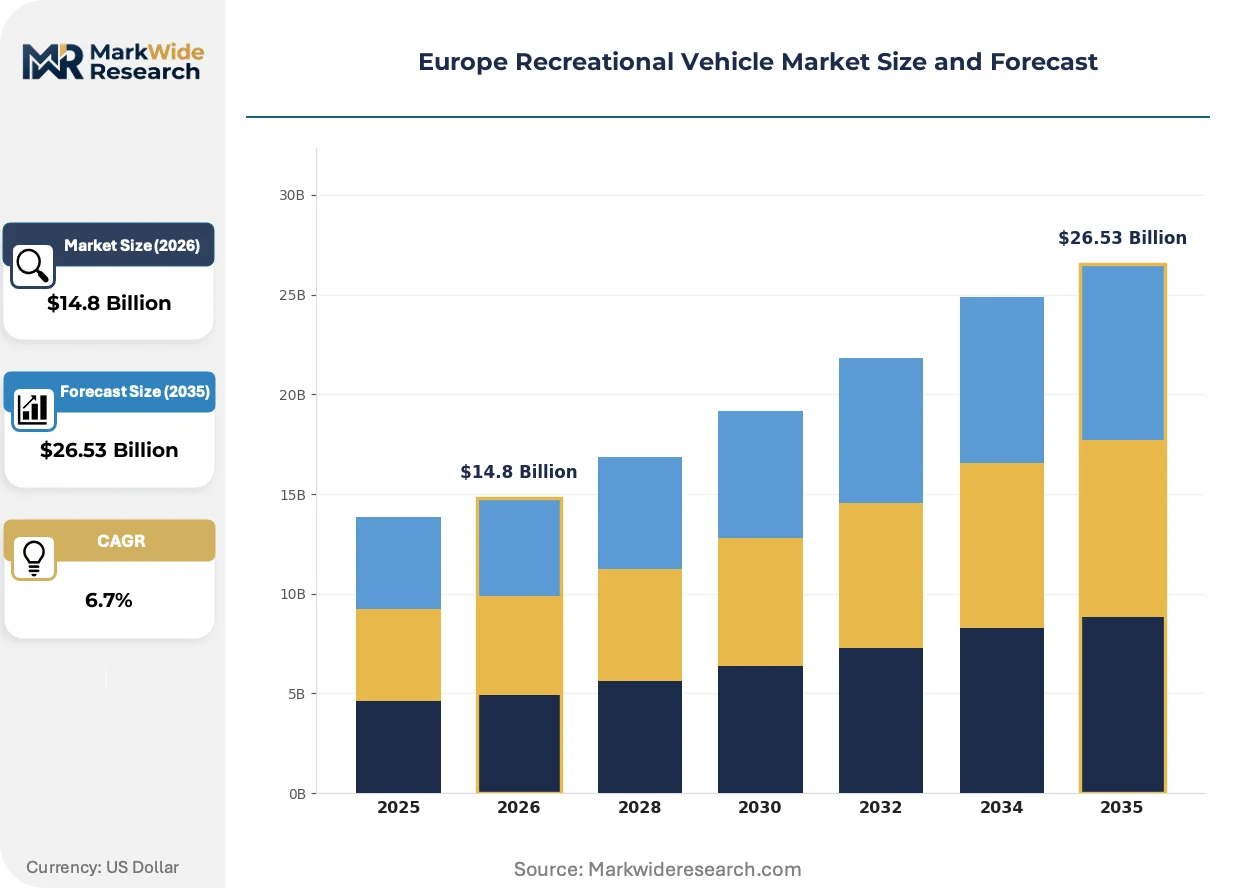
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Motorhomes, Campervans, Trailers, Fifth Wheels End User: Families, Retirees, Adventure Seekers, Tourists Size: Compact, Mid-size, Full-size, Luxury Fuel Type: Diesel, Gasoline, Electric, Hybrid |
| Companies Covered | Thor Industries Inc., Dethleffs GmbH & Co. KG, Swift Group Ltd., Knaus Tabbert AG, Auto Trail VR LTD, Trigano SA, Hymer AG, Adria Mobil d.o.o., Eura Mobil GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Recreational Vehicle Market Emerging Trajectories
Digitalization of energy management and lightweight material substitution are compressing vehicle mass and extending electric range, while regulatory pressure on refrigerants and chassis emissions is forcing concurrent thermal and drivetrain redesigns.
Composite sandwich panels with vacuum-infused resin transfer molding are displacing traditional fiberglass-reinforced polyester construction in motorhome body shells. German manufacturers including Knaus Tabbert are adopting these structures to reduce kerb weight by 12-15 percent in mid-size categories. This mass reduction is displacing the historical trade-off between battery capacity and usable payload, enabling larger energy storage without GVW penalties.
The EU F-Gas Regulation's stepped reduction in hydrofluorocarbon quotas is compelling insulation foam suppliers to transition toward hydro-olefin formulations with lower global warming potential. French converter networks are requalifying thermal envelope assemblies under revised ANSM safety protocols. This regulatory compression is most acute in premium alpine motorhomes where polyurethane thickness directly determines four-season occupancy ratings.
Direct-to-consumer digital configuration platforms are fragmenting traditional dealer intermediation in Northern European markets. Buyers in Denmark and Sweden now specify chassis, floorplan, and energy packages through manufacturer portals before factory slot allocation. This channel shift is most visible in compact van conversions where standardized module interfaces reduce the need for physical pre-purchase inspection.
Europe Recreational Vehicle Market Segmentation
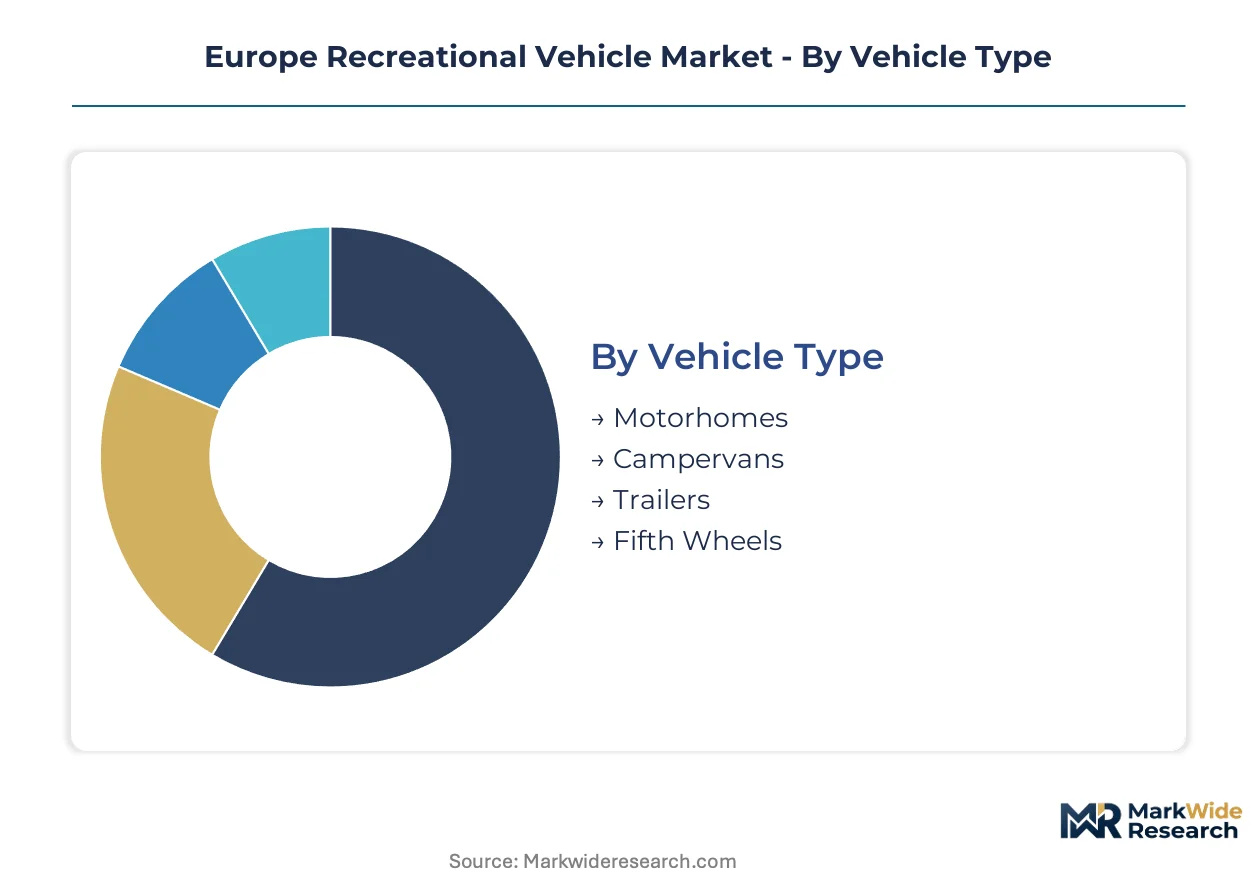
Segmentation in the Europe Recreational Vehicle Market reveals divergent supply chain configurations and regulatory exposure profiles across vehicle architectures and buyer cohorts. Manufacturers align production footprints to distinct margin structures and type-approval pathways that vary sharply by chassis integration level and energy architecture.
Vehicle Type:
German and French manufacturing clusters dominate integrated chassis production, while Eastern European suppliers anchor towable assembly for export into Southern European channels.
- Motorhomes:Self-propelled dwelling units built on dedicated commercial vehicle chassis with integrated 230V AC power distribution and fixed sanitation systems. Demand concentrates in German and Austrian markets where KBA type-approval standards favor integrated safety architectures and extended-season thermal packages.
- Campervans:Compact van conversions utilizing standard commercial vehicle platforms with modular interior fit-outs. French converter networks in the Lyon corridor specialize in these configurations, exploiting ANSM certification pathways and proximity to alpine tourism corridors.
- Trailers:Towable units requiring separate motive vehicles, prevalent in Italy and Spain where tow vehicle ownership remains elevated and rural storage infrastructure is well developed.
- Fifth Wheels:Articulated towable units with over-bed hitch configurations, occupying a niche position in premium segments across Benelux markets where heavy-duty pickup registrations support deployment.
Motorhomes command the established base. The steepest expansion runs through Campervans.
End User:
Purchasing cycles and specification intensity diverge sharply between demographic cohorts, with accessibility requirements and digital connectivity demands reshaping R&D allocation.
- Families:Multi-berth configurations with integrated child safety anchors and entertainment systems. Italian buyers in this cohort prioritize compact footprints for Mediterranean coastal mobility.
- Retirees:Extended-season occupants requiring enhanced thermal envelopes, single-level floorplans, and accessibility features. Spanish and Portuguese retirement migration corridors drive specification for these units.
- Adventure Seekers:Off-grid capable configurations with elevated ground clearance and lithium battery architectures. Scandinavian buyers emphasize four-season insulation and all-terrain chassis modifications.
- Tourists:Rental fleet demand for standardized, damage-resistant interiors with telematics integration. Croatian and Greek island operators specify these for seasonal deployment.
Retirees anchor value generation. Adventure Seekers are climbing the fastest.
Size:
Kerb weight thresholds determine battery-electric feasibility under EU Green Deal fleet standards, compressing viable configurations in urban-accessible categories.
- Compact:Sub-3.5 tonne GVW configurations eligible for standard driving licenses across all member states. Dutch municipal parking restrictions make these the only viable ownership option for buyers without rural property.
- Mid-size:3.5-7.5 tonne GVW range requiring C1 license entitlement in most jurisdictions. German manufacturers concentrate electrification efforts here, exploiting battery density improvements without commercial vehicle operator mandates.
- Full-size:Integrated coach-built architectures with slide-out expansion modules. French alpine operators deploy these for seasonal leasing in ski resort corridors.
- Luxury:Bespoke configurations with premium material specifications and extended water/power autonomy. Swiss and Austrian buyers in this segment prioritize craftsmanship credentials and residual value retention.
Mid-size configurations dominate volume. Compact segments are gaining share fastest.
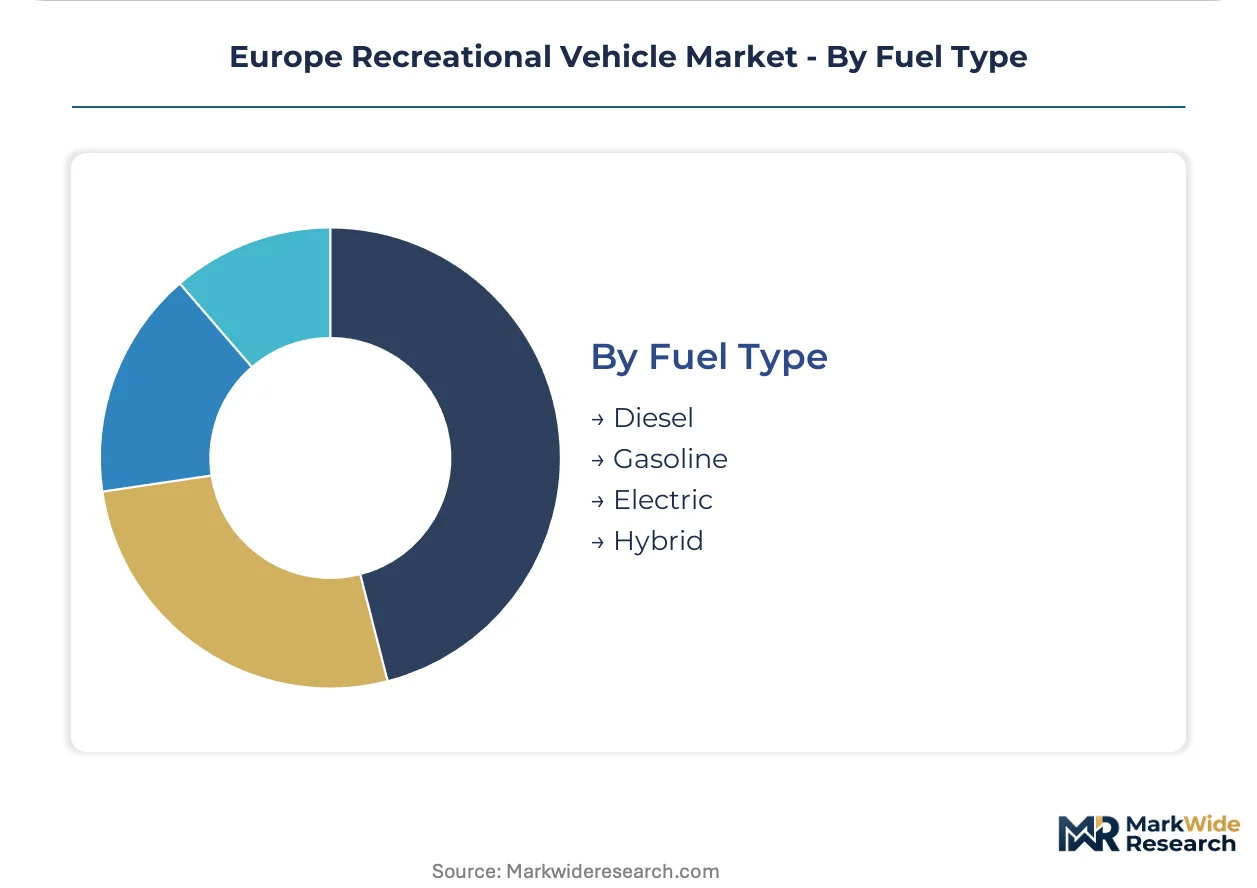
Fuel Type:
EMA coordination with KBA and ANSM is fragmenting approval timelines for alternative drivetrains, advantaging producers with established electric platform relationships.
- Diesel:Established compression-ignition architectures with extensive service network coverage. Italian and Spanish markets retain preference for these configurations in full-size categories where range anxiety persists.
- Gasoline:Spark-ignition alternatives in compact campervan conversions where payload constraints limit battery accommodation. French urban buyers specify these for weekend mobility within low-emission zones.
- Electric:Battery-electric drivetrains with 400V architectures and regenerative braking. German manufacturers lead deployment, leveraging industrial partnerships with domestic commercial vehicle producers.
- Hybrid:Range-extender configurations combining electric traction with auxiliary power units. Belgian and Dutch early adopters favor these for transitional compliance with evolving urban access regulations.
Diesel retains the installed base. Electric drivetrains are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor freight rail link underwrites Central Europe's dominance in RV manufacturing logistics, connecting component suppliers across the Benelux-German-Swiss manufacturing triangle.
Germany
KBA type-approval standards and retiree demand for extended-season thermal packages drive specification intensity. The EU Green Deal fleet standards accelerate battery-electric drivetrain adoption in Baden-Württemberg chassis assembly plants. Stuttgart's industrial cluster concentrates mid-size motorhome electrification programs leveraging domestic commercial vehicle partnerships.
France
ANSM certification pathways and alpine tourism corridor proximity shape Lyon-based converter specialization in compact campervans. The F-Gas Regulation refrigerant phase-down forces thermal envelope redesigns in Auvergne-Rhône-Alpes manufacturing facilities. French national tourism board shore power deployment enables overnight battery replenishment along Mediterranean coastal routes.
Italy
Mediterranean coastal mobility preferences and elevated tow vehicle ownership sustain trailer segment maturity. Retiree demographic expansion in Lombardy and Veneto extends purchase cycles for premium configurations. The Emilia-Romagna industrial district anchors towable assembly for Southern European export channels.
Spain
Retirement migration corridors and rural storage infrastructure availability support full-size motorhome demand. Municipal parking restrictions in Barcelona and Madrid compress viable ownership to compact segments. Catalan manufacturing networks specialize in rental fleet specifications for seasonal island deployment.
Netherlands
Randstad urban density and municipal motorhome parking prohibitions make sub-3.5 tonne configurations the sole viable ownership option. Dutch early adopters favor hybrid range-extender configurations for transitional urban access compliance. Eindhoven Region battery pack assembly plants supply cathode-dependent production schedules across neighboring member states.
Europe Recreational Vehicle Market Vendor Landscape
Concentration sits with integrated chassis manufacturers and specialized compact vehicle producers competing across distinct margin structures. German and French manufacturing clusters anchor volume leadership through KBA and ANSM certification advantages. Three archetypes dominate: transatlantic diversified conglomerates, regional specialist converters, and premium alpine craftsmen. Competitive moves center on electrification platform partnerships and thermal system requalification under F-Gas mandates.
Among Germany-based fabricators, Knaus Tabbert AG and Hymer AG occupy positions within the integrated chassis specialist tier, while Thor Industries Inc. represents the transatlantic diversified archetype. Trigano SA anchors French converter network coordination across multiple price tiers. These entities exemplify how geographic proximity to KBA and ANSM regulators shapes homologation timeline advantages.
| Leading Market Players |
|---|
| Thor Industries Inc. |
| Dethleffs GmbH & Co. KG |
| Swift Group Ltd. |
| Knaus Tabbert AG |
| Auto Trail VR LTD |
| Trigano SA |
| Hymer AG |
| Adria Mobil d.o.o. |
| Eura Mobil GmbH |
| Others |
Supply Flow & Price Mechanics
KBA and ANSM type-approval regimes gate both supplier qualification and price tiering across European RV manufacturing, compressing margins for uncertified converters while rewarding homologated producers with premium positioning in German and French channels.
Pricing Analysis
Volume-discount tiering structures separate motorhome configurations across premium alpine craftsmen, mid-size integrated chassis specialists, and compact van conversion economy tiers. Price differentiation rests on KBA certification grade and thermal envelope performance ratings under F-Gas mandates. Cost compression in compact segments is intensifying because lithium-ion cell allocation constraints are squeezing battery pack suppliers. Rental fleet operators exhibit highest price sensitivity, while Swiss and Austrian luxury buyers prioritize craftsmanship credentials over unit economics.
Supply Chain Analysis
Strategic stockpiling of cathode materials prevails over just-in-time preferences as Polish and Hungarian battery cell suppliers face raw material allocation constraints. Component sourcing draws from German chassis assembly plants, French thermal system converters, and Italian trailer fabricators. Single-source vulnerability concentrates in high-voltage battery management systems from a narrow supplier base. Distribution runs through dealership networks in Northern Europe and direct-to-consumer digital platforms in Scandinavian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward retiree demographic consolidation as aging populations in Italy and Spain extend purchase cycles for premium configurations, fragmenting price negotiation leverage across family segment plateau.
For Market Incumbents: Compound certification advantages under KBA and ANSM protocols to lock out unqualified competitors from cross-border sales channels. Deepen chassis electrification partnerships with Baden-Württemberg commercial vehicle producers before battery supply allocation tightens further. Prioritize thermal system requalification investments to capture F-Gas Regulation compliance premiums in alpine motorhome categories. For New Entrants and Emerging Players: Anchor in Portuguese and Croatian coastal corridors where RV service infrastructure remains underdeveloped and seasonal rental demand outpaces supply. Target adventure seeker segments in Scandinavian markets where four-season insulation specifications command pricing power. Deploy direct-to-consumer digital configuration platforms to bypass established dealer intermediation in Dutch and Belgian urban markets. For Investors and Strategic Acquirers: The EU Green Deal fleet standards reshape the acquisition landscape by advantaging producers with validated electric drivetrain platforms and KBA type-approval pipelines. Long-term viability centers on manufacturers with backward integration into battery pack assembly and thermal envelope design capabilities. Monitor campground charging infrastructure deployment rates across French and German national tourism corridors as electrification adoption inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Drivetrain Platform Partnership | Secures battery supply allocation from Stuttgart industrial cluster producers. |
| Thermal System Requalification | Enables F-Gas Regulation compliance for Auvergne-Rhône-Alpes manufacturing facilities. |
| Direct-to-Consumer Digital Launch | Bypasses dealer intermediation in Denmark and Sweden configuration markets. |
| Campground Charging Infrastructure Partnership | Locks in shore power standards with French national tourism board deployment. |
| CSRD-Aligned Circular Design Program | Captures procurement preference through verified end-of-life material recovery. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with RV manufacturing executives, KBA homologation specialists, campground infrastructure planners, and thermal system R&D directors; and secondary validation against EMA regulatory filings, KBA type-approval databases, national tourism board infrastructure disclosures, and EU Green Deal implementation trackers. Bottom-up unit economics triangulated against top-down regional demand modeling.
Across the projection horizon, the analytical framework segmented volume and value outputs by vehicle architecture, fuel type transition pathway, end-user demographic cohort, and national regulatory cluster. CAGRs derived from battery-electric adoption curves, retiree demographic expansion rates, and campground charging deployment schedules.
Material uncertainties — lithium-ion cell supply disruptions, F-Gas refrigerant quota compressions, and cross-border type-approval interpretation divergences — sit outside the modeled envelope. Forecasts reflect documented assumptions about electrification cost parity timelines and infrastructure buildout cadence. Revision becomes warranted when battery pack localization requirements or campground charging standards cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Australia Trailer Market
Recreational Vehicles
Motorhome Market
Recreational Vehicles
Recreational Boats Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Low Speed Vehicle (LSV) Market
Recreational Vehicles
Self Balancing Scooter Market
Recreational Vehicles
Kick Scooter Market
Recreational Vehicles
Material Buggy Market
Recreational Vehicles
Australia Recreational Vehicle Market
Recreational Vehicles
Asia-Pacific Personal Watercraft Market
Recreational Vehicles
Australia Recreational Vehicle Rental Market
Recreational Vehicles
Global Recreational Vehicle (RV) Market
Recreational Vehicles
Asia Pacific Luxury Yacht Market
Recreational Vehicles
Inflatable Boat Market
Recreational Vehicles
North America ATV and UTV Market
Recreational Vehicles
Global Segway Consumption Market