
 Saudi Arabia Yacht Charter Market | 2026-2036
Saudi Arabia Yacht Charter Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Yacht Charter Market Insights
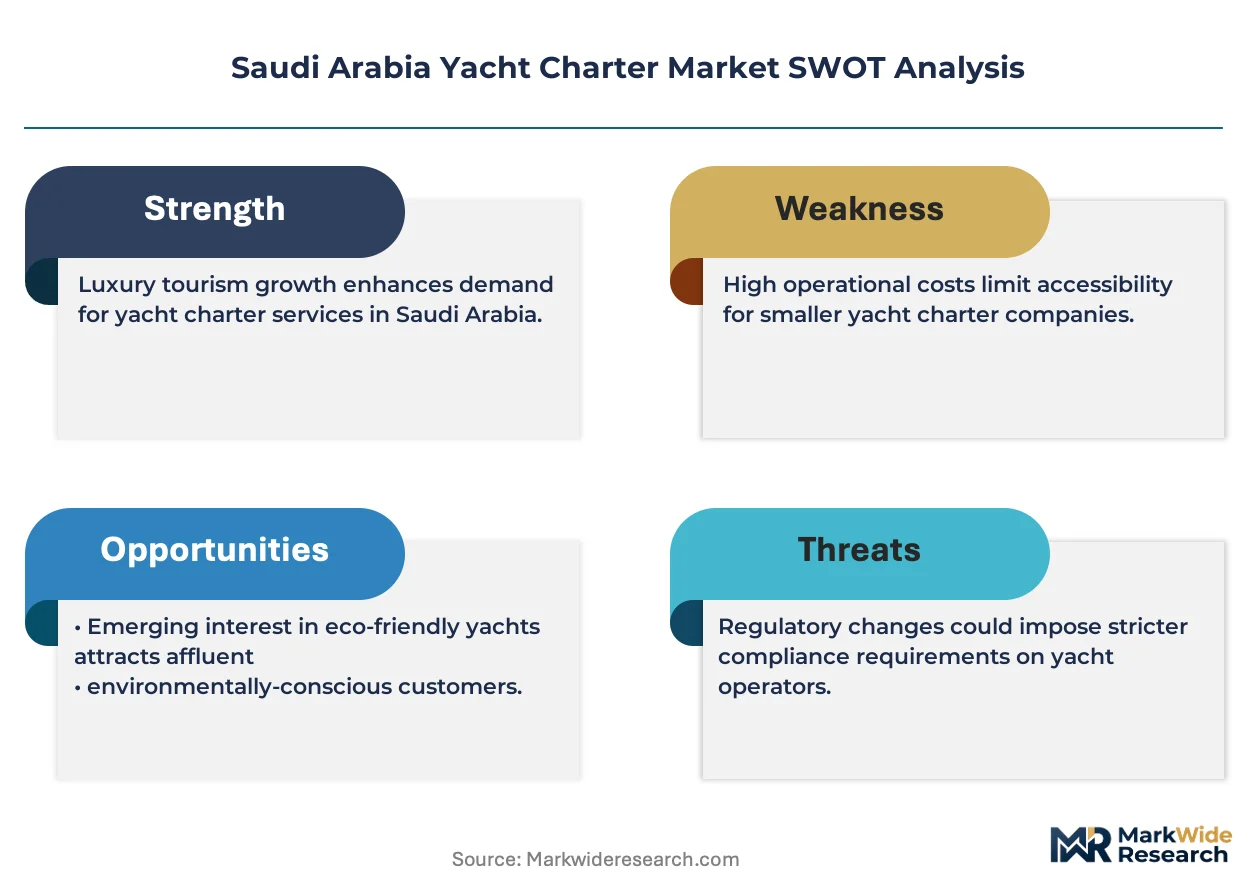
Concierge-driven itinerary customization is pivoting the core charter proposition from vessel access to experiential packaging. Yachting Partners International leverages its Red Sea operational base to anchor multi-destination circuits linking AlUla and the Farasan Islands. Gulf Craft competes through in-house manufacturing scale that sustains rapid fleet refresh cycles for regional operators. Fraser Yachts differentiates with crew-training protocols that control service consistency across its managed Saudi fleet.
A yacht charter denotes the short-term lease of a crewed or bareboat vessel, typically spanning 12 to 60 meters in length, for recreational cruising within designated maritime zones. The arrangement transfers operational command to the charterer while the owner retains hull insurance and registration obligations, serving luxury tourism and corporate hospitality applications. Crewed charters command premium positioning due to the embedded cost of licensed captains, deckhands, and culinary staff, whereas bareboat arrangements attract licensed skippers seeking autonomous routing flexibility. Weekly and monthly duration tiers concentrate margin pools, as extended bookings reduce per-day turnaround logistics and marina berthing fees.
The General Authority of Civil Aviation coordinates seaplane transfer integrations that expand yacht access beyond conventional port infrastructure, while the Saudi Red Sea Authority issues coastal cruising permits that shape seasonal itinerary legality. MOHAP maritime health standards govern crew medical certification requirements, directly affecting operator staffing costs and compliance timelines. Stakeholders must monitor how NEOM regulatory exemptions evolve relative to national maritime law, as zone-specific licensing could fragment operational standards across Saudi waters.
Market Dynamics
The Saudi Arabia Yacht Charter Market pivots on the Red Sea Project licensing framework, which is converting restricted coastal zones into accessible cruising corridors and forcing operators to rebuild fleet positioning around new marina nodes.
Growth Catalysts
- Ultra-high-net-worth leisure travelers:This end-user segment is expanding fastest, pulling demand toward multi-day experiential itineraries rather than single-day vessel rentals.
- Seaplane transfer integration:The General Authority of Civil Aviation coordinates aerial connectivity that extends yacht access beyond conventional port infrastructure, opening remote anchorage points.
- Jeddah-to-Neom corridor infrastructure:New marina construction along this coastal axis is compressing seasonal booking windows and extending viable charter months.
Market Restraints
- MOHAP maritime health standards:Crew medical certification requirements inflate operator staffing costs and extend compliance timelines for new vessel deployments.
- NEOM regulatory exemption uncertainty:Zone-specific licensing that diverges from national maritime law threatens to fragment operational standards across Saudi waters.
- Licensed skipper scarcity:Bareboat charter demand outstrips the supply of certified captains holding Saudi coastal cruising permits, constraining fleet utilization rates.
Strategic Opportunities
- Farasan Islands circuit development:This underpenetrated archipelago offers multi-destination itinerary potential linking Red Sea biodiversity zones with AlUla heritage sites.
- Corporate hospitality applications:Extended weekly and monthly charter tiers attract enterprise clients seeking differentiated event venues, reducing per-day logistics overhead.
- Concierge-driven experiential packaging:Operators can capture margin by bundling vessel access with curated land excursions, culinary programming, and cultural immersion.
Industry Challenges
- Crew-training standardization:Service consistency across managed fleets requires protocols that align licensed captains, deckhands, and culinary staff to unified hospitality benchmarks.
- Marina berthing fee volatility:Turnaround logistics for shorter-duration bookings face cost compression as new infrastructure operators test dynamic pricing models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Yacht Charter Market |
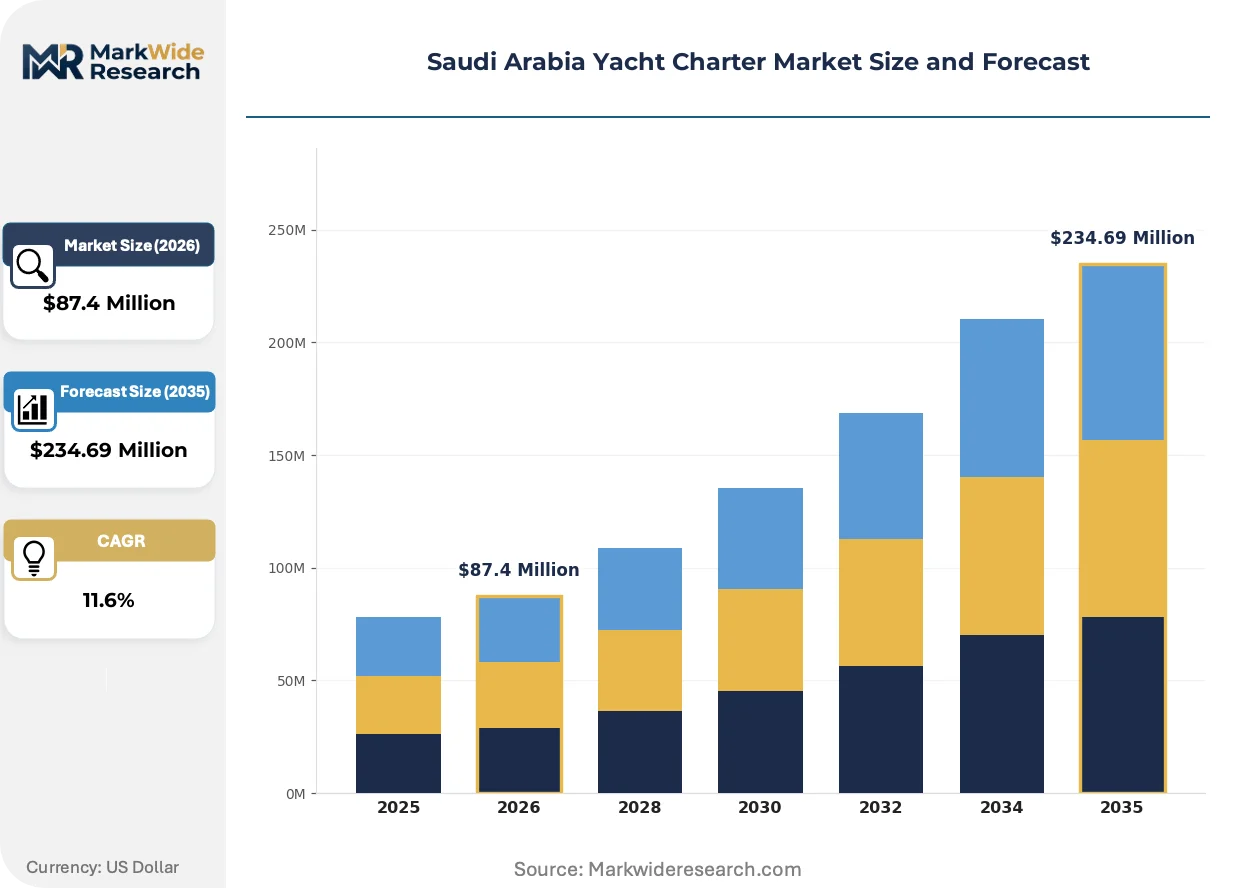
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $234.69 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Luxury Yachts, Catamarans, Motor Yachts, Sailing Yachts Service Type: Bareboat Charters, Crewed Charters, Corporate Events, Private Rentals Duration: Daily, Weekend, Weekly, Monthly End User: Tourists, Corporates, Event Planners, Private Clients |
| Companies Covered | Yachting Partners International, Phoenix Yachts, Burgess Yachts, TWW Yachts, FGI Yacht Group, Fraser Yachts, Gulf Craft, Experiences by ROAM, Northrop & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Yacht Charter Market Trends and Innovations
Hybrid propulsion systems and digital itinerary platforms are actively reshaping how Saudi operators configure fleet offerings and how charterers discover and book vessel access.
Hybrid-electric propulsion architecture is electrifying the technical specifications of newbuild vessels entering Red Sea service. Ultra-high-net-worth charterers now specify reduced-emission cruising profiles as a booking prerequisite, compressing demand toward vessels with shore-power compatibility and battery-assisted anchoring systems. This shift is electrifying competitive positioning for operators able to source lower-carbon fleet additions ahead of regulatory mandates.
The Saudi Red Sea Authority's coastal cruising permit framework is tightening itinerary legality requirements for foreign-flagged vessels. Operators must now pre-file route plans with designated anchorage coordinates, creating administrative friction that favors established players with regulatory liaison capacity. Domestic charter firms holding pre-authorized permits are consolidating market access while new entrants face extended compliance timelines.
Charter procurement is migrating from broker-mediated transactions toward direct digital platforms with transparent vessel availability and crew credentialing. Ultra-high-net-worth travelers now expect real-time itinerary customization through concierge interfaces rather than static catalog browsing. This behavioral pivot concentrates booking volume with operators investing in proprietary reservation technology and direct customer relationship infrastructure.
Saudi Arabia Yacht Charter Market Segmentation
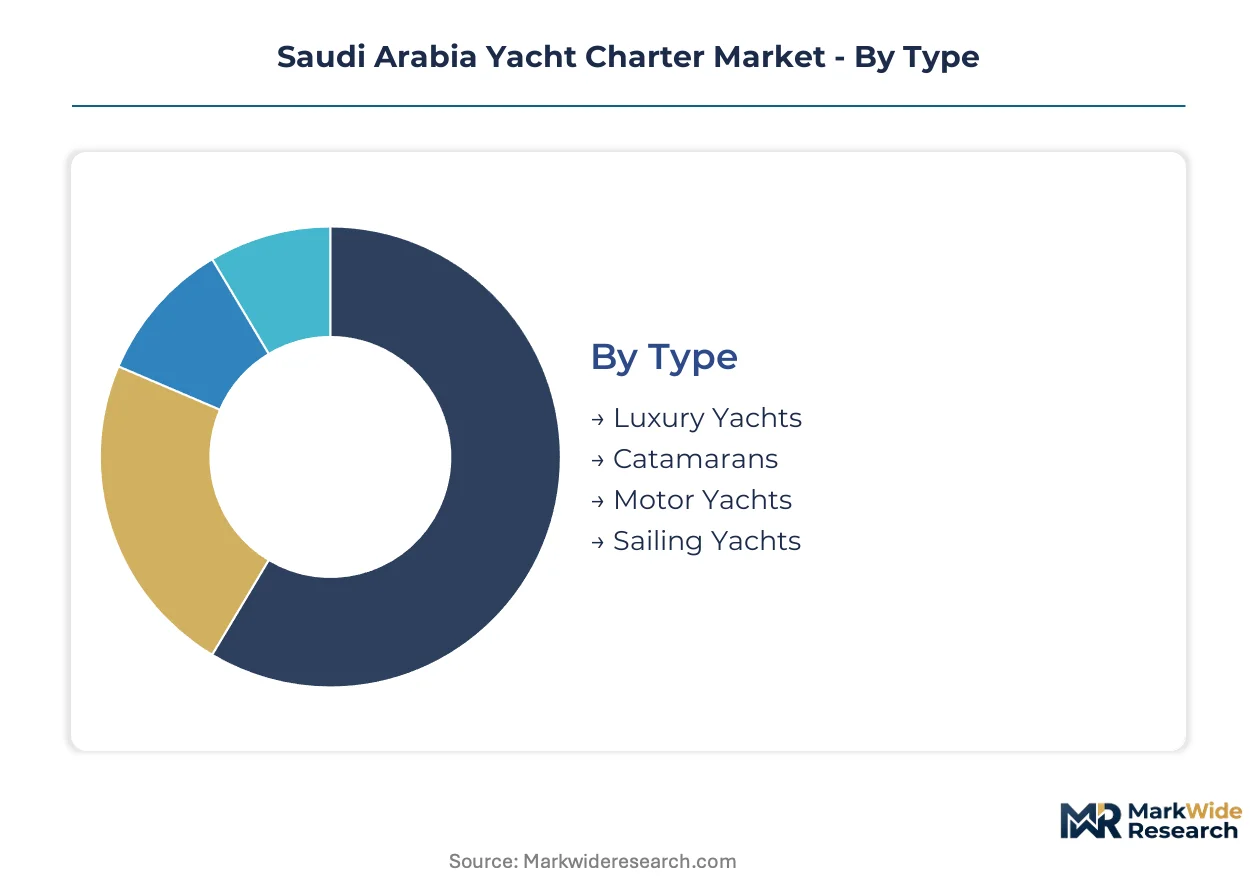
Vessel type and service configuration determine margin architecture for Saudi operators navigating the Red Sea Project's new cruising corridors. Charter duration tiers compress logistics costs while end-user segmentation reveals where experiential packaging commands premium positioning.
Type:
Supply concentration among luxury yacht operators is reshaping fleet investment priorities as ultra-high-net-worth travelers specify vessel dimensions above 40 meters.
- Luxury Yachts:These vessels exceed 40 meters with full-service crews, stabilizers, and extended-range fuel capacity. Demand concentrates along the Jeddah-to-Neom corridor where new marina infrastructure accommodates superyacht drafts, though MOHAP medical certification requirements inflate operational staffing costs.
- Motor Yachts:Powered hulls ranging 15-40 meters prioritize speed and shallow-water anchorage access. Corporate hospitality applications in the Red Sea pull demand toward vessels with conference facilities and overnight guest capacity, compressing booking windows during peak winter months.
- Catamarans:Twin-hull stability and reduced draft suit Farasan Islands exploration circuits.
- Sailing Yachts:Wind-dependent propulsion attracts licensed skippers seeking autonomous routing flexibility in designated coastal zones.
Today's leader: Luxury Yachts. Tomorrow's challenger: Motor Yachts.
Service Type:
Cost tier differentiation separates bareboat economics from crewed charter premium structures across Saudi coastal permit zones.
- Crewed Charters:Full-service arrangements embed captain, deckhands, and culinary staff within the base rate. Ultra-high-net-worth leisure travelers specify these configurations for multi-day itineraries linking AlUla heritage sites with Red Sea biodiversity zones, extending average booking duration.
- Corporate Events:Customized hospitality programming for enterprise clients leverages yacht venues for product launches and executive retreats. The Saudi Red Sea Authority's pre-filed route requirements create administrative friction that favors established operators with regulatory liaison capacity.
- Bareboat Charters:Licensed skippers retain operational command while owners retain hull insurance obligations.
- Private Rentals:Direct owner-to-charterer arrangements bypass broker intermediaries for repeat clientele.
Crewed configurations dominate current revenue pools. Corporate events are climbing the fastest as enterprise clients seek differentiated venue options.
Duration:
Volume concentration in weekly tiers reduces per-day turnaround logistics and marina berthing fee exposure for Saudi operators.
- Weekly:Seven-day bookings represent the operational sweet spot, compressing vessel repositioning costs and crew rotation schedules. Extended itineraries along the Jeddah-to-Neom corridor align with seaplane transfer integrations coordinated by the General Authority of Civil Aviation.
- Monthly:Extended deployments attract ultra-high-net-worth travelers and corporate hospitality clients seeking exclusive vessel access. Reduced per-day logistics overhead and stabilized crew scheduling improve operator margin capture during shoulder seasons.
- Weekend:Two-to-three-day windows concentrate demand from regional Gulf clientele.
- Daily:Single-day rentals face cost compression from marina berthing fee volatility and high turnaround overhead.
Weekly tiers anchor current utilization rates. Monthly contracts are gaining share fastest as experiential packaging extends beyond vessel access.
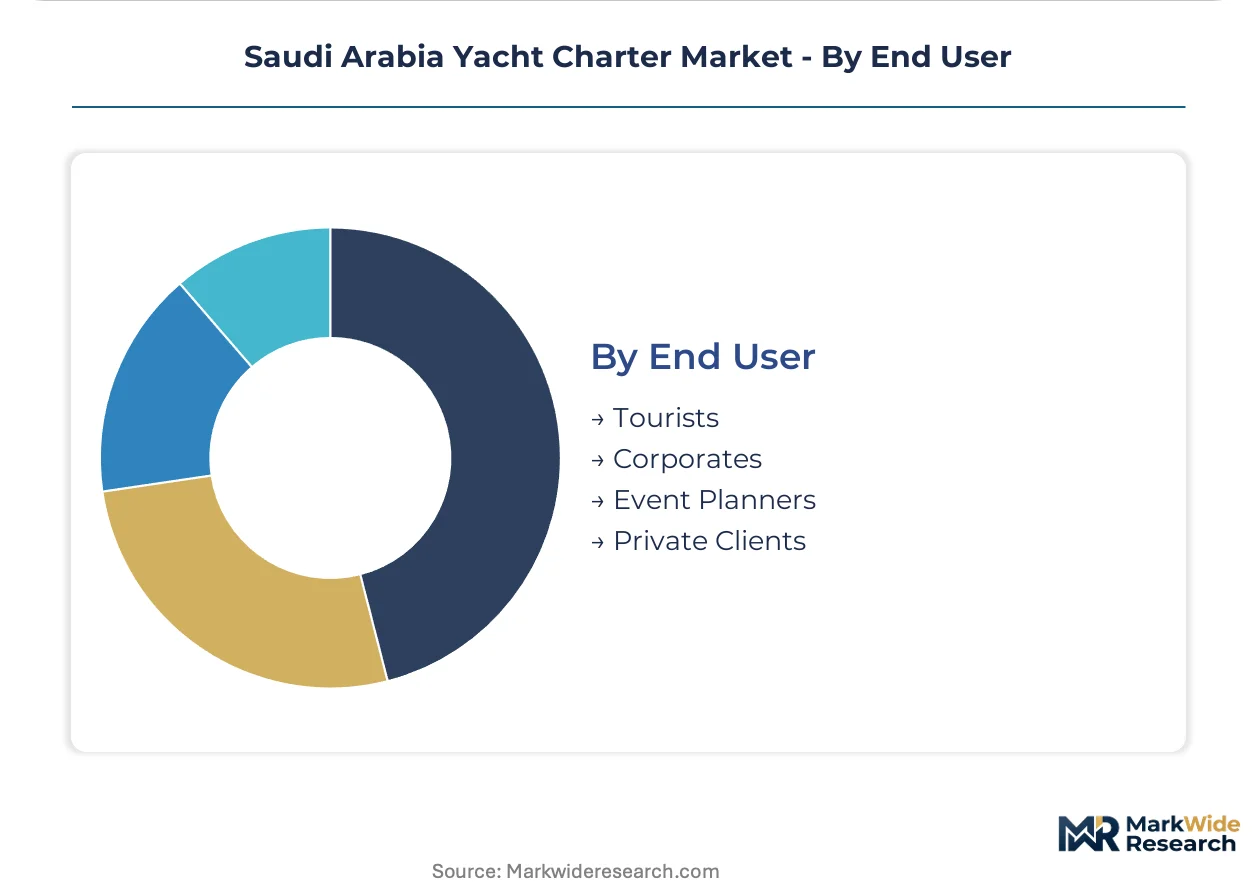
End User:
Customer type segmentation reveals where concierge-driven itinerary customization commands margin expansion versus commoditized vessel rental.
- Private Clients:Individual ultra-high-net-worth travelers specify hybrid-electric propulsion and real-time itinerary customization through direct digital platforms. This segment drives fleet refresh cycles as operators source lower-carbon vessels ahead of regulatory mandates.
- Tourists:International leisure travelers booking through hospitality channels concentrate demand along established Red Sea circuits with pre-authorized coastal cruising permits.
- Corporates:Enterprise clients seek differentiated event venues with embedded AV infrastructure and catering scalability.
- Event Planners:Third-party coordinators aggregate multi-vessel logistics for weddings and milestone celebrations.
Private clients dominate premium tier bookings. Tourists represent the steepest expansion trajectory as the Red Sea Project licensing framework opens previously restricted coastal zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UAE commands larger fleet volumes than Saudi Arabia, yet the Kingdom's regulatory opening is compressing the gap faster than regional peers anticipated.
Western Region
Jeddah's King Abdullah Economic City anchors Red Sea charter demand through its integrated marina complex. The Saudi Red Sea Authority's coastal cruising permit framework governs vessel movements from this hub. Yachting Partners International maintains operational staging here for multi-destination circuits linking AlUla heritage sites.
NEOM Northwest
The zone-specific licensing regime attracts ultra-high-net-worth travelers seeking extended itineraries beyond conventional port infrastructure. Regulatory exemptions from national maritime law create administrative friction that favors established operators with pre-authorized permits. Sindalah Island marina infrastructure is reshaping seasonal booking patterns through year-round superyacht accommodation.
Eastern Province
Dammam and Al-Khobar concentrate corporate hospitality applications for Aramco-affiliated executives and regional enterprise clients. The General Authority of Civil Aviation coordinates seaplane transfer integrations that extend yacht access to remote Arabian Gulf anchorage points. Local operators face crew medical certification requirements under MOHAP standards that inflate staffing costs.
Riyadh
The capital's absence of coastal access drives fly-in charter procurement through King Khalid International Airport connectivity to Red Sea marinas. Private aviation brokers coordinate same-day transfers to Jeddah embarkation points. Domestic ultra-high-net-worth households here generate disproportionate demand for monthly-duration exclusive vessel contracts.
Saudi Arabia Yacht Charter Market Competitive Landscape
Top-tier vendors anchor crewed luxury charter operations, while mid-scale operators compete on bareboat flexibility and regional circuit familiarity. The vendor base clusters around three strategic archetypes: international brokerage houses with regulatory liaison capacity, Gulf-based manufacturers controlling in-house fleet supply, and concierge platforms bundling experiential land programming. Dominant competitive moves include marina infrastructure partnerships and proprietary reservation technology deployment.
Within the international brokerage tier, Burgess Yachts and Fraser Yachts represent established players with coastal permit pre-authorization advantages. Gulf Craft exemplifies the manufacturing-integrated archetype through regional production scale. Yachting Partners International occupies a specialist position linking Red Sea maritime access with AlUla terrestrial programming.
| Leading Market Players |
|---|
| Yachting Partners International |
| Phoenix Yachts |
| Burgess Yachts |
| TWW Yachts |
| FGI Yacht Group |
| Fraser Yachts |
| Gulf Craft |
| Experiences by ROAM |
| Northrop & Johnson |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed marina infrastructure developers are consolidating berthing capacity along the Jeddah-to-Neom corridor, compressing price-setting power toward operators with pre-authorized coastal permits while fragmenting supply access for unaffiliated charter firms.
Pricing Analysis
Capacity additions in the Red Sea Project zone are reshaping price floors for weekly and monthly charter tiers. Three-tier pricing structure across luxury, motor, and bareboat levels separates crewed superyacht configurations from autonomous skippered vessels. Price differentiation rests on Saudi Red Sea Authority permit pre-authorization and hybrid-electric propulsion certification. Margins are tightening due to MOHAP medical certification inflation for crew staffing. Corporate hospitality clients show lowest price sensitivity, while regional Gulf weekend charterers concentrate demand in the most price-elastic daily tier.
Supply Chain Analysis
The Saudi Red Sea Authority's local-content mandates for crew training and vessel maintenance are reshaping sourcing patterns toward domestic maritime academies and Jeddah-based technical service providers. Fleet supply draws from UAE shipyards, Italian superyacht builders, and Gulf Craft's in-house manufacturing in Ajman. Critical inputs include marine-grade aluminum hulls, hybrid-electric propulsion systems, and MOHAP-certified medical equipment. Single-source vulnerability concentrates in foreign-flagged vessel registrations facing extended coastal permit timelines. Distribution runs through marina-based operators with direct digital booking platforms rather than traditional broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi Arabia Yacht Charter Market functions as a stable compounder, with the Red Sea Project's regulatory opening converting restricted coastal zones into accessible cruising corridors and sustaining multi-year demand expansion.
For Market Incumbents: Deepen regulatory liaison capacity with the Saudi Red Sea Authority to secure pre-authorized coastal cruising permits before zone-specific licensing fragments operational standards. Anchor fleet positioning at Sindalah Island and King Abdullah Economic City marina nodes. Defend against bareboat charter entrants by embedding proprietary concierge programming that bundles AlUla heritage access with vessel rental. For New Entrants and Emerging Players: Begin with Farasan Islands circuit development, the most penetrable geography given underdeveloped multi-destination itinerary competition. Target licensed skipper certification programs to address bareboat charter supply constraints. Establish go-to-market presence through seaplane transfer partnerships coordinated with the General Authority of Civil Aviation rather than conventional port-based brokerage. For Investors and Strategic Acquirers: Sovereign wealth vehicles and hospitality conglomerates are the most active acquirer in this space, consolidating marina infrastructure with experiential land programming. Long-term viability rests on regulatory exclusivity duration within NEOM exemption zones. Monitor Saudi Red Sea Authority permit issuance velocity as the inflection indicator for competitive access tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Marina Infrastructure Partnership | Sindalah Island berthing capacity anchors year-round superyacht accommodation outside seasonal Jeddah compression. |
| Hybrid Fleet Refresh Program | Shore-power compatibility addresses ultra-high-net-worth emission specifications ahead of Saudi regulatory mandates. |
| Concierge Technology Platform | Direct digital booking with real-time itinerary customization displaces traditional broker-mediated transactions. |
| Crew Training Academy Investment | MOHAP-certified maritime health standards reduce compliance timelines and staffing cost inflation for managed fleets. |
| Seaplane Transfer Integration | General Authority of Civil Aviation coordination extends yacht access to remote Farasan Islands anchorage points. |
Research Methodology
Multiple input streams — operator financial disclosures, regulatory filing analysis, and fleet utilization databases — were reconciled across primary interviews with yacht charter executives, marina infrastructure developers, and Saudi Red Sea Authority licensing officers. Secondary validation drew from General Authority of Civil Aviation coordination records, MOHAP maritime health standard publications, and Red Sea Project development timelines. Bottom-up vessel inventory counts and top-down tourism expenditure estimates were triangulated to anchor market sizing.
Historical charter booking patterns were cross-referenced against panel input from fleet managers and hospitality procurement officers across the projection horizon. Segmentation dimensions modeled include vessel type, service configuration, duration tier, and end-user category, with regional regulatory cluster differentiation across Western Region, NEOM Northwest, Eastern Province, and Riyadh fly-in demand. CAGRs were derived from iterative reconciliation of infrastructure deployment schedules and permit issuance trajectories, incorporating seaplane transfer integration velocity and hybrid propulsion fleet refresh cycles as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including potential NEOM regulatory exemption reversals, MOHAP certification requirement escalations, and sovereign tourism policy shifts. Forecasts reflect documented assumptions regarding Red Sea Project phase completion and coastal zone accessibility expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Superyacht Market
Recreational Vehicles
Towable Tubes Market
Recreational Vehicles
Automotive Trailer Market
Recreational Vehicles
Electric Baby Car Market
Recreational Vehicles
Recreational Vehicle Rental Market
Recreational Vehicles
Luxury Van Market
Recreational Vehicles
Asia-Pacific Personal Watercraft Market
Recreational Vehicles
Recreational Boats Market
Recreational Vehicles
United States RV Rental Market
Recreational Vehicles
Deck Boat Market
Recreational Vehicles
Luxury Yacht Market
Recreational Vehicles
ATV-UTV Tire Market
Recreational Vehicles
RV Leisure Battery Market
Recreational Vehicles
Europe Personal Watercraft Market
Recreational Vehicles
Online Powersports Market
Recreational Vehicles
Light Car Trailer Market